
 NOR-Based Multi-Chip Packages Market | 2026-2036
NOR-Based Multi-Chip Packages Market Size, Share, and Industry Trends Forecast 2026-2036
NOR-Based Multi-Chip Packages Market Analysis
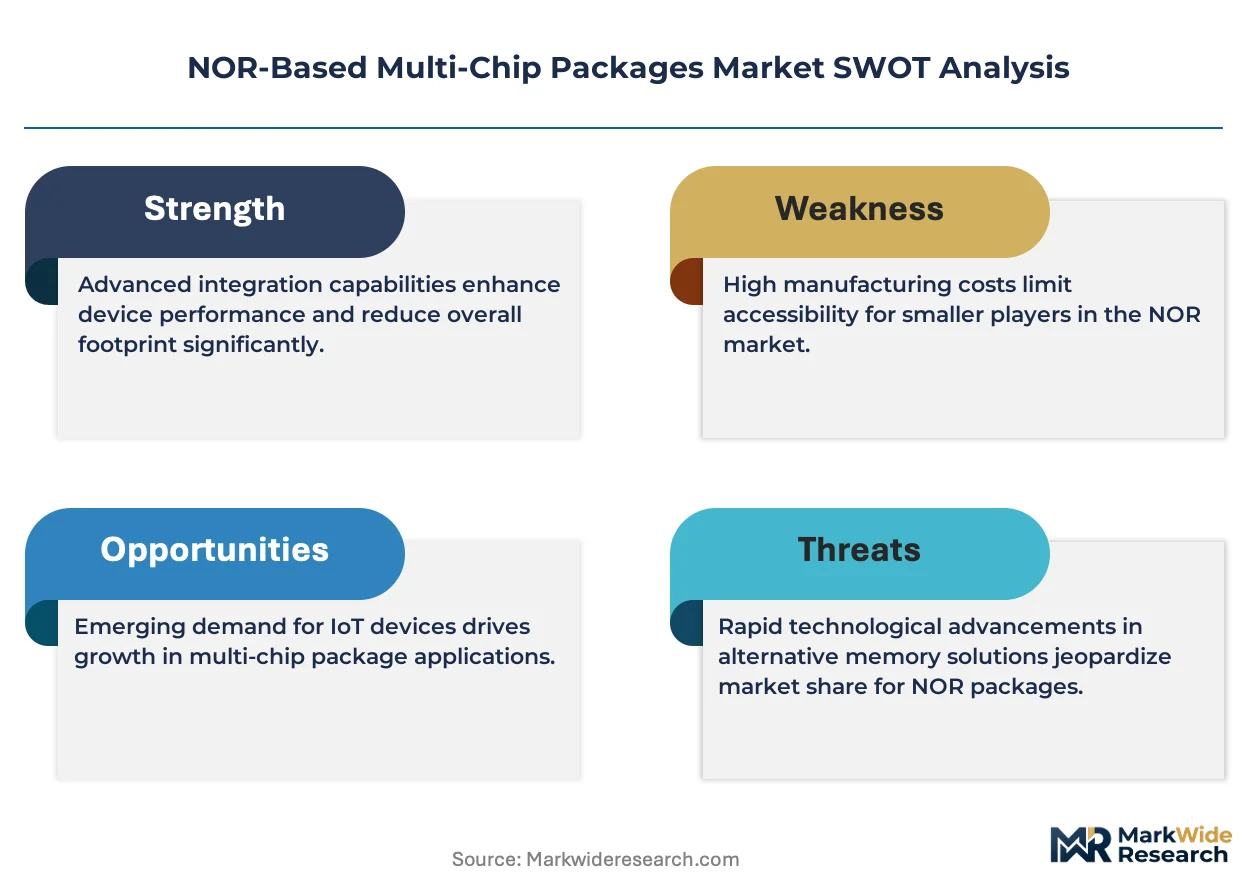
Foundry capacity expansion in Taiwan is realigning supply dynamics for NOR-based multi-chip packages. Winbond Electronics leverages captive wafer processing to sustain cost leadership in stacked flash solutions. Infineon Technologies anchors European automotive demand through specialized AEC-Q100 qualified packages. Micron Technology competes on advanced 3D packaging density for industrial-grade applications.
NOR-based multi-chip packages integrate discrete flash memory dies with controller logic within a single molded substrate, typically employing wire-bond or flip-chip interconnection with package heights below 1.4 mm to satisfy space-constrained board designs. These assemblies serve primarily as code-storage subsystems in devices requiring fast random read access and execute-in-place capability. Stacked packages occupy the largest volume share due to mature cost structures, while SiP configurations capture expanding margin pools in automotive telematics modules. Wafer-level packaging exhibits the fastest trajectory among technology categories as OSATs transition from traditional leadframe assembly to reconstituted wafer formats for thinner profiles.
REACH compliance and RoHS substance restrictions govern material selection across European-bound shipments, compelling substrate suppliers to eliminate lead-based finishes and halogenated flame retardants. The EU AI Act and emerging product safety frameworks for autonomous systems impose traceability requirements on memory components in safety-critical automotive chains. China's SAMR enforces GB standards for domestic automotive electronics certification, creating divergent testing protocols for multi-chip packages serving local OEMs versus export markets. Stakeholders must monitor evolving F-Gas Regulation impacts on die-attach thermal interface materials and assess dual carbon policy timelines in China for foundry energy sourcing decisions.
Market Dynamics
Wafer-level packaging migration is compressing traditional leadframe assembly margins while automotive ECU consolidation accelerates demand for stacked flash configurations with sub-1.4 mm height profiles.
Growth Catalysts
- Automotive ECU consolidation:Advanced driver-assistance systems require execute-in-place code storage with fast random read access, pulling NOR flash MCPs into safety-critical domains.
- REACH substance restrictions:European-bound shipments must eliminate lead-based finishes and halogenated flame retardants, compelling substrate suppliers to develop compliant material stacks.
- Foundry-to-OSAT integration:Taiwan and South Korea fabrication clusters enable high-volume stacked package output through captive wafer processing and reconstituted wafer format transitions.
Market Restraints
- Gold wire bond volatility:Precious metal cost swings in wire-bond interconnection directly impact stacked package economics, squeezing margin pools in standard-grade products.
- Taiwan concentration risk:Over 70% of advanced MCP wafer processing sits within a single seismic zone and geopolitical flashpoint, exposing supply chains to disruption.
- Die-attach thermal interface constraints:F-Gas Regulation phase-downs limit fluorinated compound availability for high-temperature automotive applications, forcing material substitutions.
Strategic Opportunities
- Industrial edge computing:Factory automation controllers and robotics systems require deterministic boot code storage with extended temperature ranges, opening non-automotive volume.
- China dual carbon alignment:Foundry energy sourcing certification under MEE timelines creates preference for low-carbon wafer processing in domestic automotive electronics procurement.
- Wafer-level fan-out expansion:OSATs adopting reconstituted wafer formats enable thinner profiles than traditional leadframe assembly, capturing premium positioning in telematics modules.
Industry Challenges
- AEC-Q100 qualification timelines:Extended test cycles for automotive-grade packages delay revenue recognition and tie up engineering resources across multiple temperature grade validations.
- Legacy system integration friction:Board designers migrating from discrete flash to MCPs face footprint compatibility constraints and firmware porting complexity in established industrial controllers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | NOR-Based Multi-Chip Packages Market |
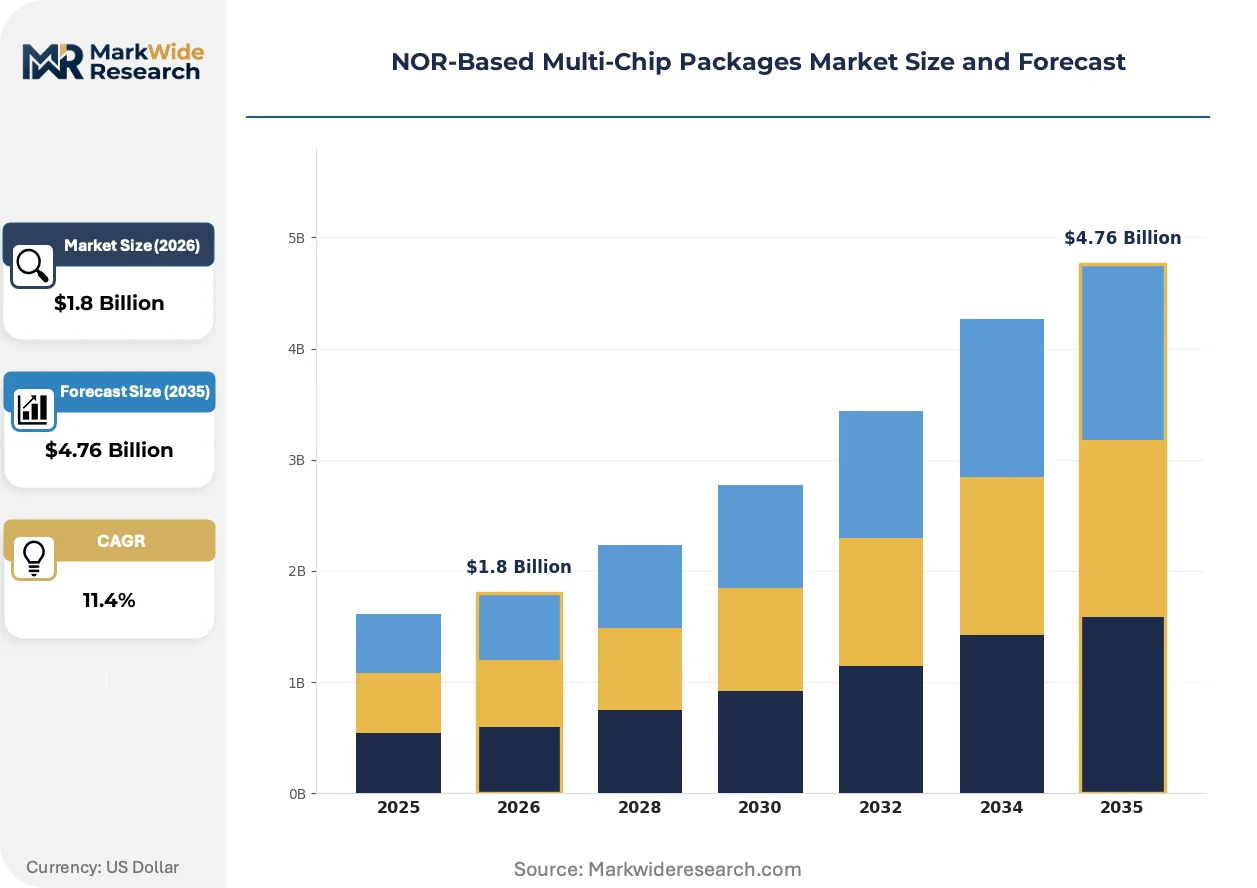
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stacked Packages, SiP, 2-in-1 Packages, Multi-Die Packages Application: Consumer Electronics, Automotive, Telecommunications, Industrial Devices Technology: 3D Packaging, Wafer-Level Packaging, Flip Chip Technology, TSV Technology End User: OEMs, Tier-1 Suppliers, Contract Manufacturers, Aftermarket Providers |
| Companies Covered | Macronix International, Infineon Technologies, Integrated Silicon Solution, Winbond Electronics, Micron Technology, Samsung Electronics, ISS Integrated Silicon Solution, Microchip Technology, Cypress Semiconductor, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
NOR-Based Multi-Chip Packages Market Emerging Trajectories
Packaging technology convergence with automotive functional safety requirements is redefining qualification protocols and procurement criteria across code-storage subsystems.
System-in-package configurations are integrating NOR flash dies with baseband processors and power management units within single molded substrates. Tier-1 automotive suppliers are adopting these consolidated modules for telematics control units to reduce board area and assembly steps. This integration is compressing the addressable market for standalone flash packages while expanding margin capture for qualified SiP providers.
EU AI Act traceability mandates are imposing documentation requirements on memory components in autonomous driving chains. Component suppliers must maintain batch-level provenance records through multi-tier supply networks. Automotive OEMs serving European markets are responding by narrowing approved vendor lists to suppliers with established quality management system certifications.
Direct foundry relationships are displacing traditional distribution channels for high-volume automotive procurement. ECU manufacturers in Germany and Japan are negotiating long-term supply agreements that bypass semiconductor distributors, securing wafer allocation through binding volume commitments. This channel compression is most pronounced in safety-critical applications where qualification transfer costs between suppliers are prohibitive.
NOR-Based Multi-Chip Packages Market Segmentation
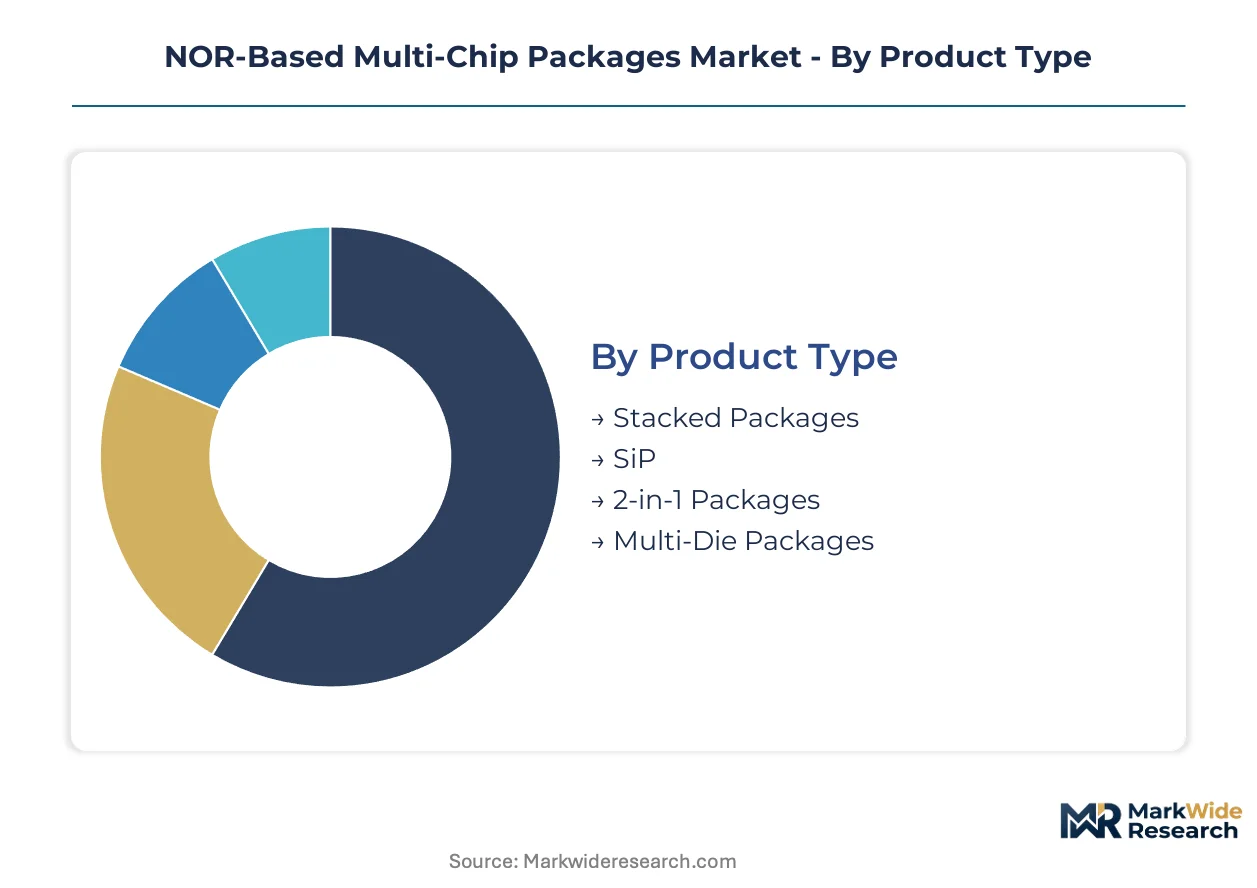
NOR-based multi-chip packages serve heterogeneous performance requirements across automotive safety systems, industrial controllers, and consumer devices. Segment differentiation reflects trade-offs between vertical integration depth, thermal operating ranges, and qualification burden.
Product Type:
Package architecture determines z-height profiles, thermal dissipation paths, and assembly cost structures for code-storage subsystems.
- Stacked Packages:Vertical die stacking with wire-bond interconnection achieves sub-1.4 mm profiles for space-constrained board designs. Automotive ECU consolidation in Germany and Japan pulls these configurations into safety-critical domains where execute-in-place capability is mandatory.
- SiP:System-in-package integrates NOR flash dies with baseband processors and power management units within single molded substrates. Tier-1 automotive suppliers in Europe adopt these consolidated modules for telematics control units to compress board area and assembly steps.
- 2-in-1 Packages:Dual-die configurations pair discrete flash with controller logic for mid-tier industrial applications requiring deterministic boot sequences without full SiP complexity.
- Multi-Die Packages:Three or more die assemblies address high-density code storage in network infrastructure equipment, though thermal management constraints limit automotive adoption.
Stacked packages lead on scale; SiP leads on momentum.
Application:
End-use environments impose divergent reliability specifications, temperature grade requirements, and procurement volume patterns.
- Automotive:Advanced driver-assistance systems require AEC-Q100 qualified packages with extended temperature ranges and traceability documentation under EU AI Act mandates. OEMs in Germany and Japan negotiate direct foundry relationships, bypassing traditional distribution channels for high-volume procurement.
- Industrial Devices:Factory automation controllers and robotics systems demand deterministic boot code storage with -40°C to +105°C operational windows. This segment expands volume outside automotive as edge computing architectures proliferate.
- Consumer Electronics:Wearables and portable devices prioritize minimal z-height over extended temperature performance, accepting commercial-grade specifications.
- Telecommunications:Base station controllers and network infrastructure equipment require high-reliability code storage with long field-life guarantees, though volume concentrates in fewer equipment manufacturers.
Automotive commands premium positioning; industrial devices expand most quickly.
Technology:
Interconnection and substrate approaches define manufacturing cost structures, die yield economics, and profile thinness limits.
- Wafer-Level Packaging:Reconstituted wafer formats enable thinner profiles than traditional leadframe assembly, capturing premium positioning in telematics modules. OSATs in Taiwan and South Korea are transitioning capacity from leadframe to wafer-level formats.
- 3D Packaging:Through-silicon-via and micro-bump stacking achieve highest vertical density for industrial-grade applications where board area is severely constrained.
- Flip Chip Technology:Direct die-to-substrate interconnection improves thermal performance and electrical parasitics compared to wire-bond alternatives.
- TSV Technology:Through-silicon-via vertical interconnects enable shortest signal paths for highest-performance code storage, though cost structures limit deployment to premium automotive and aerospace applications.
Wafer-level packaging leads on momentum; 3D packaging leads on density premiums.
End User:
Procurement channel structure and qualification transfer costs shape supplier relationships and contract terms.
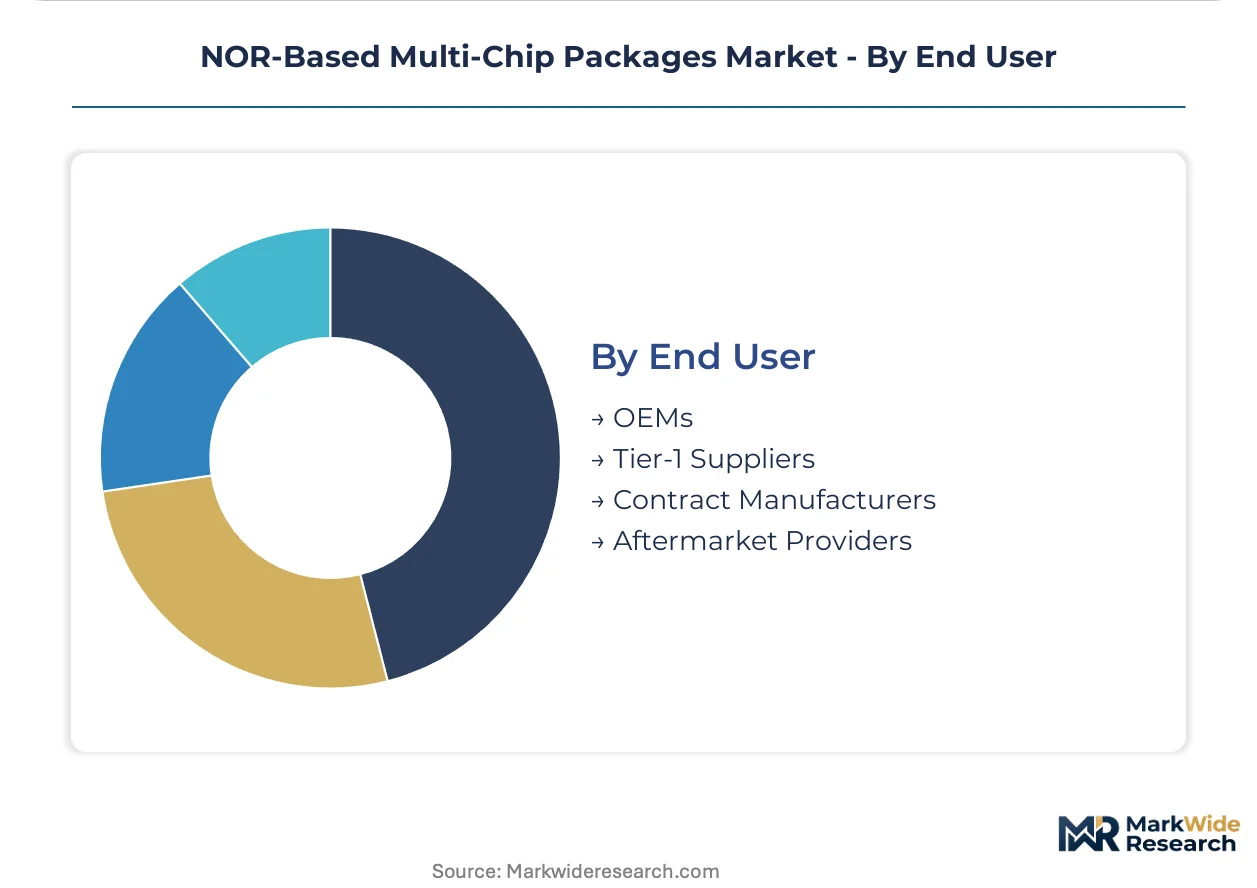
- Tier-1 Suppliers:Continental, Bosch, and Denso anchor European and Japanese automotive demand through specialized AEC-Q100 qualified packages, maintaining narrow approved vendor lists to satisfy traceability mandates.
- OEMs:Vehicle manufacturers and industrial equipment builders are consolidating direct foundry negotiations, securing wafer allocation through binding volume commitments that displace distributor relationships.
- Contract Manufacturers:Flex, Jabil, and Foxconn handle assembly for consumer electronics and mid-tier industrial applications where qualification transfer costs between suppliers remain manageable.
- Aftermarket Providers:Replacement module suppliers serve legacy vehicle fleets and industrial equipment refresh cycles, accepting longer lead times and broader supplier qualification.
Tier-1 suppliers lead on qualification rigor; OEMs lead on channel compression.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redrawing fabrication footprints as REACH compliance costs in Europe and dual carbon mandates in China create divergent cost-of-compliance environments for substrate suppliers and OSATs.
China
Domestic automotive electronics procurement under GB standards is accelerating foundry energy sourcing certification timelines. SAMR enforces divergent testing protocols for multi-chip packages serving local OEMs versus export markets. Yangtze River Delta fabrication clusters in Shanghai and Suzhou are scaling wafer-level packaging capacity to capture telematics module demand.
Taiwan
Over 70% of advanced MCP wafer processing concentrates within this seismic zone, exposing supply chains to geopolitical flashpoint risk. Foundry-to-OSAT integration enables high-volume stacked package output through captive wafer processing. Hsinchu Science Park and Tainan Technology Industrial Park are transitioning capacity from leadframe assembly to reconstituted wafer formats.
South Korea
Memory semiconductor specialists are expanding 3D packaging density for industrial-grade applications requiring severe board area constraints. The country's national semiconductor regulator aligns with international REACH substance restrictions for European-bound shipments. Pyeongtaek and Yongin fabrication corridors are integrating controller logic with flash dies for automotive telematics modules.
Germany
ECU manufacturers are negotiating direct foundry relationships that bypass traditional semiconductor distributors for high-volume procurement. ECHA REACH restrictions compel substrate suppliers to eliminate lead-based finishes and halogenated flame retardants. Bavaria's automotive electronics corridor around Munich and Ingolstadt anchors European demand for AEC-Q100 qualified packages.
Japan
Vehicle manufacturers are consolidating safety-critical code storage procurement through binding volume commitments with captive wafer allocation. METI industrial standards intersect with EU AI Act traceability mandates for autonomous driving chains. Nagoya's Chubu region and Tokyo's Kanto cluster are specializing in deterministic boot code storage for advanced driver-assistance systems.
NOR-Based Multi-Chip Packages Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue wafer-level fan-out capabilities and automotive SiP integration. The market structure consolidates around memory specialists with captive fabrication and diversified OSATs with packaging scale. Three archetypes dominate: integrated memory fabricators with backward wafer control, automotive-qualified packaging specialists, and industrial-grade density leaders. Competitive moves concentrate on foundry-to-OSAT integration partnerships and AEC-Q100 qualification portfolio expansion.
Among integrated memory fabricators, Winbond Electronics and Macronix International exemplify the captive processing archetype, while Infineon Technologies occupies a position within the automotive-qualified tier. These companies represent divergent strategic postures: Taiwan-based limited companies leveraging vertical wafer ownership versus European technology corporations anchoring safety-critical supply chains through specialized qualification protocols. Micron Technology sits within the density-driven segment, illustrating the industrial-grade positioning that competes on advanced 3D packaging architectures.
| Leading Market Players |
|---|
| Macronix International |
| Infineon Technologies |
| Integrated Silicon Solution |
| Winbond Electronics |
| Micron Technology |
| Samsung Electronics |
| ISS Integrated Silicon Solution |
| Microchip Technology |
| Cypress Semiconductor |
| Others |
Supply Flow & Price Mechanics
Gold wire bond costs cascade through three distinct pricing tiers for NOR-based multi-chip packages, with automotive AEC-Q100 qualified products commanding premium positioning over commercial-grade alternatives due to precious metal content and extended qualification timelines.
Pricing Analysis
Distributor margins compress as direct foundry relationships displace traditional semiconductor distribution channels for high-volume automotive procurement. Three-tier pricing structure across premium, standard, and economy levels separates AEC-Q100 automotive grades from industrial extended-temperature specifications and consumer commercial-grade products. Cost compression in standard-grade stacked packages intensifies because gold wire bond volatility squeezes margin pools. Tier-1 automotive suppliers exhibit lowest price sensitivity due to qualification transfer costs, while contract manufacturers serving consumer electronics remain most responsive to unit pricing.
Supply Chain Analysis
Photoresist supply rests on Japanese specialty chemical producers, while silicon wafer feedstock draws from German and Japanese polysilicon refiners. Advanced MCP wafer processing concentrates in Taiwan and South Korea, with leadframe substrates sourcing from Chinese and Malaysian metal stamping operations. Single-source vulnerability in Taiwan's Hsinchu Science Park exposes automotive ECU supply chains to seismic and geopolitical disruption. Distribution runs through direct foundry contracts for Tier-1 automotive suppliers, supplemented by semiconductor distributors for mid-tier industrial and consumer applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
NOR-based multi-chip package procurement arbitrages REACH compliance costs in Europe against dual carbon certification requirements in China, creating divergent landed cost structures for substrate suppliers serving both markets.
For Market Incumbents: Lock in captive wafer processing capacity through foundry-to-OSAT integration partnerships in Taiwan and South Korea. Defend margin pools by accelerating AEC-Q100 qualification portfolio expansion before emerging SiP specialists capture automotive telematics module demand. Channel control through direct OEM relationships insulates against distributor margin compression.
For New Entrants and Emerging Players: Aftermarket providers serving legacy vehicle fleet refresh cycles represent the most penetrable buyer archetype with manageable qualification burdens. Industrial edge computing controllers for factory automation offer white-space expansion outside automotive concentration. Pursue wafer-level fan-out capabilities to capture premium positioning in telematics modules through thinner profile differentiation.
For Investors and Strategic Acquirers: Consolidation pressure builds where AEC-Q100 qualification timelines create switching costs that trap automotive OEMs with incumbent suppliers. Long-term viability favors packaging specialists with backward integration into captive wafer supply and established European regulatory compliance infrastructure. Watch F-Gas Regulation phase-down impacts on die-attach thermal interface material availability as inflection indicator for automotive-qualified package economics.
| Strategic Initiative | Industry Significance |
|---|---|
| Foundry-to-OSAT Integration Partnership | Captive wafer processing in Taiwan secures cost leadership for stacked flash output. |
| AEC-Q100 Qualification Expansion | Extended temperature grade validation opens safety-critical automotive ECU procurement channels. |
| Wafer-Level Fan-Out Transition | Reconstituted wafer formats enable sub-1.4 mm profiles for telematics module premium capture. |
| REACH-Compliant Material Stack Development | ECHA substance restrictions compel lead-free finishes for European-bound shipment eligibility. |
| Direct OEM Supply Agreement | Bypassing semiconductor distributors compresses channel margins for high-volume procurement. |
Methodological Framework
Bottom-up automotive ECU and industrial controller modeling reconciled against top-down wafer processing capacity tracking forms the analytical core. Primary interviews with Tier-1 supplier procurement directors, OSAT operations managers, foundry planning officers, and automotive platform engineers combined with secondary validation against SEC filings, customs trade data, AEC-Q100 certification registries, and SAMR GB standard documentation. Triangulation across supply-side fabrication metrics and demand-side bill-of-materials analysis ensures segment-level precision.
Input-output matrices map die yield economics, wire-bond interconnection costs, and substrate material stacks across package architecture segments. Modeled dimensions span product type, application environment, interconnection technology, and end-user procurement channel structure. CAGRs derive from regression against historical wafer starts, MCP unit shipments, and automotive ECU production volumes. Forecast inputs incorporate REACH compliance cost trajectories, F-Gas Regulation phase-down schedules, and foundry energy sourcing certification timelines under China's MEE dual carbon policy.
Underlying measurement precision varies by segment; automotive AEC-Q100 qualified products carry tighter precision than consumer commercial-grade alternatives due to documented certification registries. Forecasts reflect assumptions regarding Taiwan geopolitical stability, precious metal price volatility, and automotive ECU consolidation rates. Supply chain disruption from seismic events, export control expansion, or die-attach material substitution failures warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Packaging
Advanced Semiconductor Packaging Market
Semiconductor Packaging
Outsourced Semiconductor Assembly and Test Services (OSAT) Market
Semiconductor Packaging
Semiconductor Wafer Tape Market
Semiconductor Packaging
Global Interposer and Fan-Out WLP Market
Semiconductor Packaging
Asia-Pacific Quad-Flat-No-Lead Packaging Market
Semiconductor Packaging
Bonding Wire Packaging Market
Semiconductor Packaging
Quad-Flat-No-Lead Packaging (QFN) Market
Semiconductor Packaging
Embedded Die Packaging Technology Market
Semiconductor Packaging
System in Package (SIP) Die Market
Semiconductor Packaging
Semiconductor and IC Packaging Materials Market
Semiconductor Packaging
Semiconductor Solder Flux Market
Semiconductor Packaging
3D IC and 2.5D IC Packaging Market
Semiconductor Packaging
Global Semiconductor Packaging and Assembly Equipment Market
Semiconductor Packaging
System in Package (Sip) Technology Market
Semiconductor Packaging
2.5D and 3D Semiconductor Packaging Market
Semiconductor Packaging
Multichip Package Market