
 Wafer Carrier Boxes Market | 2026-2036
Wafer Carrier Boxes Market Size, Share, and Industry Trends Forecast 2026-2036
Wafer Carrier Boxes Market Insights
The wafer carrier boxes market is pivoting around a widening split between ultra-clean premium carriers for EUV lithography zones and commodity-grade boxes for legacy 200mm lines. Entegris leverages its vertical integration in polymer purification to sustain margins at the top tier. Gudeng Precision anchors its position through geographic dominance in Taiwan's foundry cluster. Shin-Etsu Polymer competes via material science leadership in conductive and static-dissipative compounds.
Wafer carrier boxes are precision-engineered enclosures designed to transport, store, and protect silicon wafers through semiconductor fabrication, typically molded from high-purity PEEK, PBT, or carbon-filled polymers with particle counts below Class 1 cleanliness thresholds and surface resistivity controlled between 10^4 and 10^11 ohms per square. Their primary purpose is to eliminate electrostatic discharge, outgassing, and particulate contamination during repeated automated handling. Multi-wafer carriers lead volume shipments due to throughput economics in high-volume memory fabs, while customized carriers command the strongest margin pools as EUV process nodes impose wafer-specific dimensional tolerances. Plastic materials dominate the material split, though ceramic composites are gaining traction for extreme-temperature anneal steps where polymer creep limits performance.
The EPA regulates perfluorinated compound emissions from semiconductor manufacturing, indirectly shaping carrier material selection by restricting fluoropolymer processing aids. Japan's METI enforces JIS standards for electrostatic control in electronics handling equipment, creating a technical barrier for non-domestic suppliers. Taiwan's Industrial Development Bureau coordinates local content requirements that favor regional molders. Stakeholders must monitor how evolving EUV pellicle and reticle box standards propagate backward into carrier specifications, as lithography tool OEMs tighten upstream cleanliness protocols.
Market Dynamics
The wafer carrier boxes market is bifurcating around EUV lithography cleanliness requirements, which demand sub-Class 1 particle counts and atomic-level surface control that legacy 200mm carriers cannot achieve. This technical chasm is forcing carriers into two irreconcilable supply chains serving different fab generations.
Growth Catalysts
- 300mm Wafer Migration:Logic and memory fabs in Taiwan, South Korea, and Japan are replacing 200mm infrastructure, requiring new carrier fleets with tighter dimensional tolerances.
- REACH Chemical Compliance:The EU's tightening material specifications are accelerating replacement cycles as older polymer formulations face authorization sunset clauses.
- EUV Zone Contamination Protocols:Lithography tool OEMs are mandating upstream cleanliness standards that propagate into carrier specifications, creating upgrade demand across existing installed base.
Market Restraints
- High-Purity Polymer Supply Concentration:Purified PEEK and PBT resin production concentrates among a handful of Japanese and European chemical suppliers, creating input bottlenecks.
- Fluoropolymer Processing Restrictions:EPA regulations on perfluorinated compound emissions limit domestic US manufacturing of certain carrier grades, forcing import dependence.
- Ceramic Composite Cost Barrier:Extreme-temperature anneal applications favor ceramic carriers, but their 3-5x cost premium versus polymers restricts penetration beyond leading-edge logic nodes.
Strategic Opportunities
- India Semiconductor Mission:The country's PLI scheme and upcoming fab investments create virgin demand for carrier supply chains without incumbent vendor lock-in.
- Reticle-to-Wafer Standard Convergence:EUV pellicle box cleanliness protocols are migrating downward into wafer carrier specifications, opening premium positioning for vendors with cross-product certification.
- Static-Dissipative Compound Innovation:Carbon nanotube-filled polymers are enabling surface resistivity control below 10^6 ohms per square without particulate shedding, unlocking new process tool integrations.
Industry Challenges
- Cleanroom Molding Talent Scarcity:The specialized skill set for Class 1 injection molding in semiconductor-grade environments concentrates in Japan and Taiwan, limiting geographic expansion.
- Dual Certification Timeline Compression:Simultaneous JIS and ISO 14644-1 qualification requirements stretch validation cycles to 18-24 months, delaying revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wafer Carrier Boxes Market |
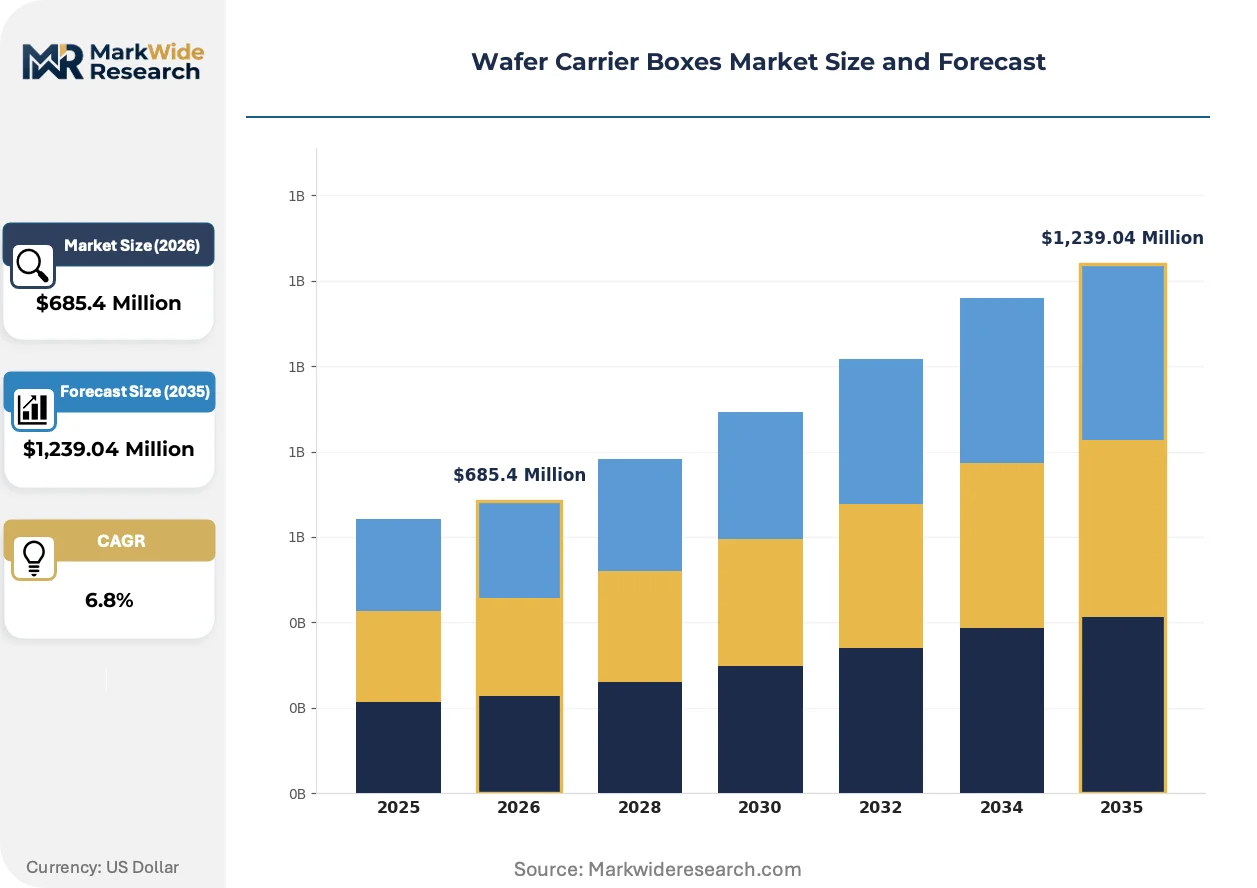
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,239.04 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Wafer Carrier, Multi-Wafer Carrier, Customized Carrier, Standard Carrier Material: Plastic, Metal, Ceramic, Composite End User: Semiconductor Manufacturers, Electronics Manufacturers, Research Institutions, Fabrication Facilities Size: Standard Size, Large Size, Small Size, Custom Size |
| Companies Covered | Entegris, Gudeng Precision, Shin-Etsu Polymer, Miraial, 3S Korea, Chuang King Enterprise, Pozzetta, ePAK, E-SUN, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wafer Carrier Boxes Market Trends and Innovations
Wafer carrier engineering is converging on material platforms that simultaneously satisfy electrostatic control, thermal stability, and outgassing suppression. Three vectors dominate competitive positioning.
Carbon nanotube-doped polymer compounds are overtaking traditional carbon-black formulations in EUV lithography zones. Memory fabs in South Korea are adopting these materials at pilot scale this quarter. The technology is overtaking legacy conductive compounds by eliminating particle generation during automated handling cycles.
Japan's METI has tightened JIS C 61340-5-1 electrostatic control standards for electronics handling equipment. The revision mandates surface resistivity documentation traceable to national metrology institutes. Taiwan's Industrial Development Bureau is responding with local content incentives that favor domestic molders achieving equivalent certification.
Consolidated procurement through lithography tool OEMs is replacing direct fab purchasing for EUV-zone carriers. Applied Materials and ASML are bundling carrier specifications into equipment service contracts. South Korean memory houses are the first to adopt this model, compressing vendor count from twelve to three qualified suppliers per fab.
Wafer Carrier Boxes Market Segmentation
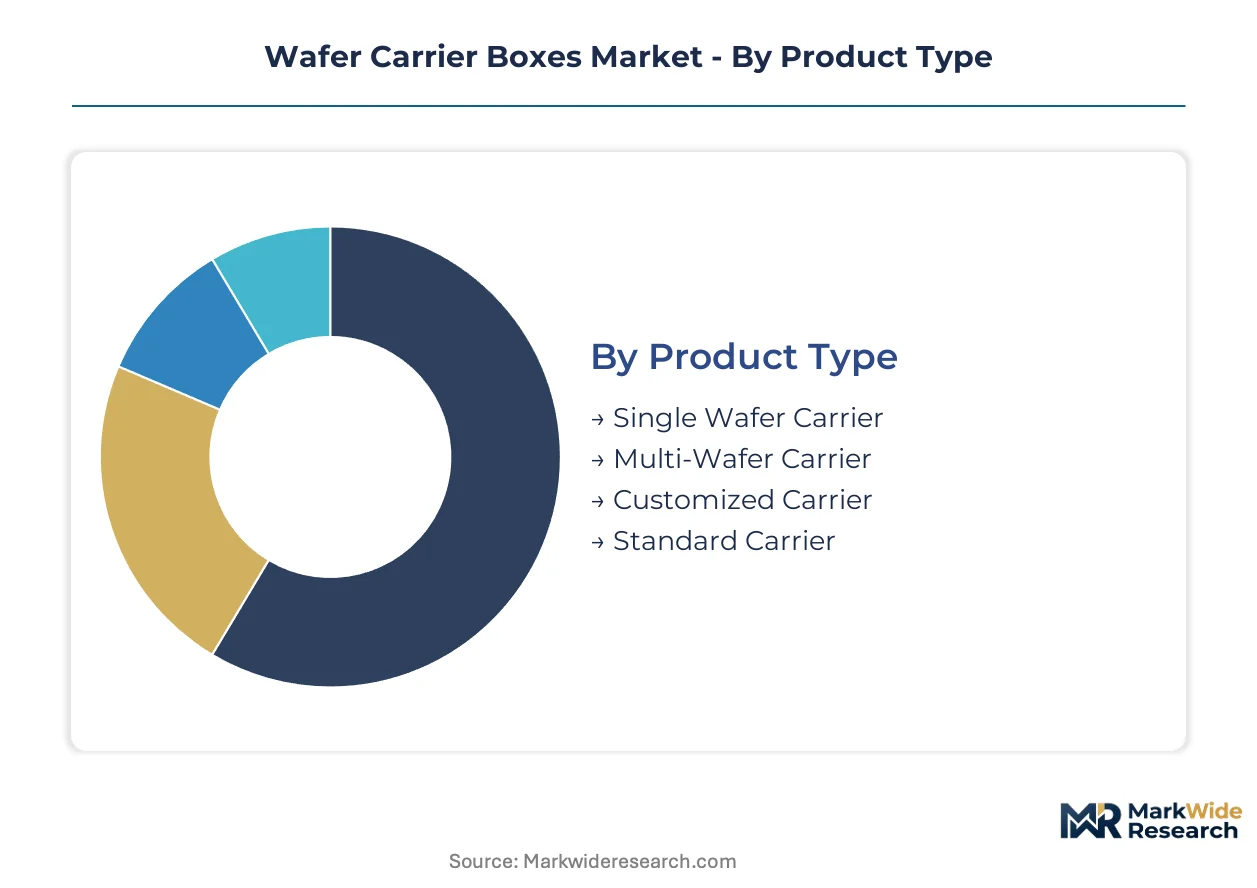
Carrier selection in semiconductor fabrication hinges on cleanliness grade, thermal tolerance, and automated handling compatibility. Segmentation reveals how process node requirements split demand across incompatible technical tiers.
Product Type:
Throughput economics and EUV lithography protocols drive carrier selection more than unit cost.
- Multi-Wafer Carrier:Engineered for batch transport of 25 wafers with automated load port compatibility. Memory fabs in South Korea deploy these carriers at highest volumes where throughput per square meter of cleanroom floor dominates capital efficiency calculations.
- Customized Carrier:Built to wafer-specific dimensional tolerances for EUV process nodes below 7nm. Taiwan's leading foundries are expanding procurement as lithography tool OEMs tighten upstream cleanliness protocols beyond Class 1 thresholds.
- Single Wafer Carrier:Designed for individual wafer protection during tool-to-tool transport in mixed-node fabs.
- Standard Carrier:Generic specification carriers serving legacy 200mm lines and non-critical process steps.
Volume sits with Multi-Wafer Carrier; growth tilts toward Customized Carrier.
Material:
Material selection traces directly to maximum process temperature and outgassing limits imposed by tool OEMs.
- Plastic:High-purity PEEK and PBT compounds dominate through 300°C operating ranges with surface resistivity controlled between 10^4 and 10^11 ohms per square. EPA restrictions on perfluorinated compound emissions constrain domestic US manufacturing of certain fluoropolymer grades.
- Ceramic:Aluminum nitride and alumina composites withstand extreme-temperature anneal steps where polymer creep limits performance. Leading-edge logic nodes in Japan are piloting these carriers despite 3-5x cost premiums over polymer alternatives.
- Metal:Anodized aluminum carriers retain niche applications in non-cleanroom logistics and external transport.
- Composite:Hybrid ceramic-polymer constructions target thermal management in rapid thermal processing tools.
Plastic commands installed base volume; Ceramic is climbing the fastest as advanced nodes proliferate.
End User:
Procurement concentration follows foundry and memory fab capital expenditure cycles.
- Semiconductor Manufacturers:Logic and memory fabs in Taiwan, South Korea, and Japan generate carrier demand tied directly to 300mm wafer migration timelines. EUV zone contamination protocols are mandating upstream cleanliness standards that propagate into carrier specifications.
- Fabrication Facilities:Specialty foundries and analog/mixed-signal producers operate mixed 200mm/300mm fleets requiring differentiated carrier inventories.
- Electronics Manufacturers:OSATs and test houses utilize carriers for back-end handling with less stringent cleanliness requirements.
- Research Institutions:Universities and national laboratories pilot novel carrier materials and handling protocols.
Semiconductor Manufacturers absorb majority volume; Fabrication Facilities show steepest expansion trajectory as specialty analog capacity expands.
Size:
Wafer diameter standardization has collapsed size variation to 300mm dominance with residual 200mm demand.
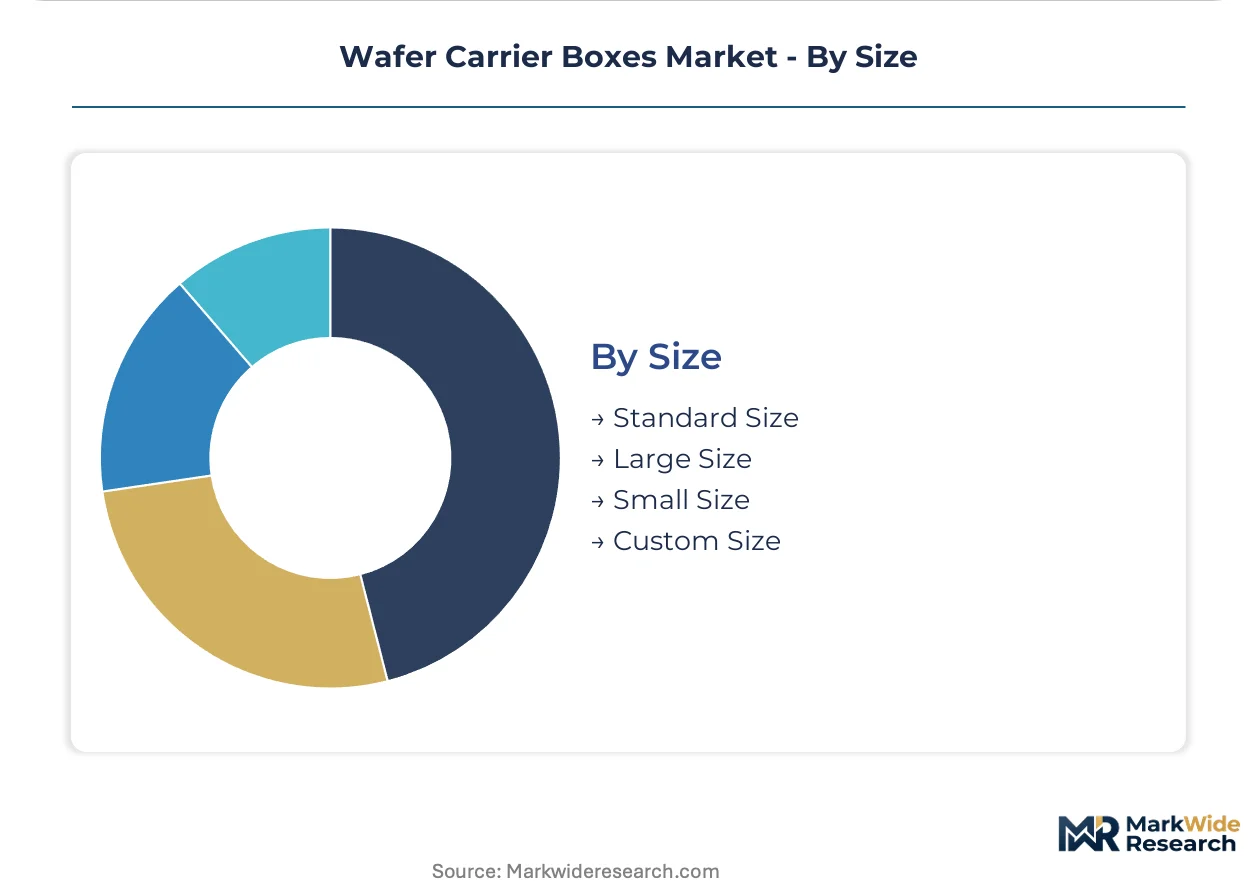
- Standard Size:300mm carriers align with SEMI mechanical interface specifications for FOUP load ports. Taiwan's Industrial Development Bureau coordinates local content requirements favoring regional molders of these carriers.
- Custom Size:Non-standard dimensions serve experimental wafer formats and specialized annealing tools. Japan's METI enforces JIS standards that create technical barriers for non-domestic suppliers of these variants.
- Large Size:Retained for 450mm pilot line equipment and specialized display substrate handling.
- Small Size:Limited to 200mm legacy lines and compound semiconductor wafer formats.
Standard Size anchors procurement volume; Custom Size is gaining share fastest as EUV-specific dimensional tolerances proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Taipei anchors wafer carrier procurement through its concentration of 300mm foundry capacity, with the Hsinchu Science Park generating carrier demand tied directly to EUV lithography tool installations.
Taiwan
Hsinchu and Tainan foundry clusters drive multi-wafer carrier volumes as TSMC expands 3nm and 2nm production lines. The Industrial Development Bureau coordinates local content requirements favoring domestic molders. Kaohsiung suppliers are scaling cleanroom molding capacity to capture EUV-zone certification contracts.
South Korea
Samsung and SK Hynix memory fabs in Pyeongtaek and Icheon are consolidating carrier procurement through lithography tool OEM service contracts. The MFDS maintains electrostatic control standards for electronics handling equipment. Yongin-based compounders are qualifying carbon nanotube-doped polymers for pilot production.
Japan
Tokyo and Osaka polymer suppliers dominate high-purity PEEK and PBT resin production for carrier substrates. METI enforces JIS C 61340-5-1 electrostatic control standards creating technical barriers for non-domestic entrants. Nagoya molders are advancing ceramic composite carriers for extreme-temperature anneal applications.
United States
Intel's Arizona and Oregon fabs are replacing 200mm carrier fleets during 300mm wafer migration. The EPA restricts perfluorinated compound emissions from semiconductor manufacturing, limiting domestic fluoropolymer carrier production. Boise suppliers face import dependence for certain high-purity grades.
China
Yangtze Memory Technologies and SMIC are expanding domestic carrier procurement as part of semiconductor self-sufficiency targets. The MIIT oversees GB standards for electrostatic control in electronics manufacturing. Shanghai molders are qualifying Class 1 injection molding lines for 300mm FOUP production.
Wafer Carrier Boxes Market Competitive Landscape
Capital-heavy polymer compounders compete with asset-light carrier designers in a tiered structure where material purification capabilities determine premium positioning. The market consolidates around three strategic archetypes: vertically integrated material-to-carrier producers, specialized cleanroom molders, and lithography tool OEM bundlers. Capacity expansion in Taiwan and South Korea dominates competitive moves, while strategic partnerships between resin suppliers and molders secure high-purity feedstock access.
Among integrated material specialists, Entegris exemplifies the vertical-control archetype through captive polymer purification, while Gudeng Precision occupies the geographic-anchor position within Taiwan's foundry cluster. Shin-Etsu Polymer represents the compound-innovation tier with conductive polymer leadership.
| Leading Market Players |
|---|
| Entegris |
| Gudeng Precision |
| Shin-Etsu Polymer |
| Miraial |
| 3S Korea |
| Chuang King Enterprise |
| Pozzetta |
| ePAK |
| E-SUN |
| Others |
Pricing and Supply Chain Analysis
EUV lithography tool OEMs bundling carrier specifications into equipment service contracts are compressing vendor counts and forcing supply chains to absorb qualification costs, which in turn stratifies pricing across certification tiers rather than material grades alone.
Pricing Analysis
Yield protection guarantees anchor value-based pricing for EUV-zone carriers, with foundries paying premiums for documented sub-Class 1 particle performance. Three-tier pricing structure across premium, standard, and economy levels separates EUV-certified custom carriers from multi-wafer memory fab units and legacy 200mm generic boxes. Cost compression in the standard tier is intensifying because South Korean memory houses are consolidating procurement through ASML and Applied Materials service contracts. Specialty analog fabs show highest price sensitivity due to mixed-node carrier inventory requirements, while leading-edge logic houses prioritize cleanliness certification over unit cost.
Supply Chain Analysis
Air freight premiums for Class 1 cleanroom-molded carriers from Taiwan and Japan to US and European fabs add 15-25% to landed costs, incentivizing regional molding investments. High-purity PEEK and PBT resin production concentrates in Japan and Germany, while precision molding capacity clusters in Taiwan and South Korea. Single-source vulnerability pervades the purified polymer feedstock tier, where three Japanese chemical suppliers control semiconductor-grade resin output. Distribution runs through lithography tool OEM service contracts for EUV carriers and direct fab procurement for legacy lines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The wafer carrier market sits in a technology-transition phase as carbon nanotube-doped polymers displace carbon-black conductive compounds in EUV lithography zones, rendering legacy formulations obsolete for leading-edge nodes.
For Market Incumbents: Deepen captive control over high-purity PEEK and PBT resin supply to defend margins against Japanese chemical supplier pricing power. Entrench JIS C 61340-5-1 and ISO 14644-1 dual certification capabilities to extend qualification timelines that block fast-follower entry. Carbon nanotube compound patents represent the critical defensive moat as memory fabs scale pilot adoption. For New Entrants and Emerging Players: Capture India's Semiconductor Mission carrier demand before incumbent vendor lock-in solidifies around TSMC's planned fab investments. The country's PLI scheme creates virgin procurement channels without established supplier relationships. Target specialty analog and mixed-signal fabs in Europe with REACH-compliant carrier formulations that incumbent Asian suppliers are slow to certify. For Investors and Strategic Acquirers: The window for entry favors compound-innovation specialists with carbon nanotube polymer expertise over commodity molders. Long-term viability hinges on EUV lithography penetration rates across logic and memory fabs. Watch for ASML and Applied Materials expanding carrier bundling into equipment service contracts as the inflection signal for vendor consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Carbon Nanotube Compound Scale-Up | Shin-Etsu Polymer and Entegris are qualifying next-generation static-dissipative materials for EUV zones. |
| Cleanroom Molding Capacity Expansion | Kaohsiung suppliers are adding Class 1 injection lines to capture TSMC 2nm carrier contracts. |
| Dual Certification Investment | Simultaneous JIS and ISO qualification stretches timelines to 18-24 months, entrenching incumbents. |
| India Market Entry Partnership | Joint ventures with domestic molders bypass PLI local content requirements for virgin fab demand. |
| Ceramic Composite Pilot Production | Nagoya molders advance aluminum nitride carriers for extreme-temperature anneal steps at 3-5x polymer cost. |
Research Methodology
Semiconductor equipment trade associations, customs shipment records, and lithography tool OEM service contract disclosures formed the secondary backbone, supplemented by SEC filings from publicly traded material suppliers. Primary interviews with fab procurement directors, cleanroom molding engineers, polymer compound R&D leads, and lithography tool OEM supply chain managers provided operational validation. Bottom-up wafer carrier unit demand was triangulated against top-down fab capital expenditure forecasts across the analysis window.
Historical trendline analysis of 300mm wafer migration rates and EUV lithography tool installation patterns informed the projection framework. Segmentation dimensions modeled include carrier type, material grade, cleanliness certification tier, end-use fab node, and regional regulatory cluster. CAGRs were derived from equipment intensity ratios per wafer start and replacement cycle assumptions tied to REACH authorization sunsets. Forecast inputs incorporated foundry and memory house capital expenditure guidance and EUV pellicle box standard propagation timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EUV lithography adoption velocity, ceramic composite cost reduction curves, and India fab construction delays. Forecasts reflect documented assumptions around polymer purification capacity expansion and JIS standard revision schedules. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Packaging
Embedded Die Packaging Technology Market
Semiconductor Packaging
Fan Out Packaging Market
Semiconductor Packaging
Microtube Box Market
Semiconductor Packaging
3D IC and 2.5D IC Packaging Market
Semiconductor Packaging
Semiconductor Chip Handler Market
Semiconductor Packaging
Embedded Die Packaging Market
Semiconductor Packaging
Advanced Semiconductor Packaging Market
Semiconductor Packaging
3D Semiconductor Packaging Market
Semiconductor Packaging
Global High-End Semiconductor Packaging Market
Semiconductor Packaging
Outsourced Semiconductor Assembly and Testing Market
Semiconductor Packaging
Wafer Level Packaging (WPL) Market
Semiconductor Packaging
Outsourced Semiconductor Assembly and Test Services (OSAT) Market
Semiconductor Packaging
Quad-Flat-No-Lead Packaging (QFN) Market
Semiconductor Packaging
Through-Silicon via (TSV) IC Packaging Market
Semiconductor Packaging
Antenna-In-Package Technology Market
Semiconductor Packaging
Ceramic IC Packages Market