
 Asia Pacific LED Packaging Market | 2026-2036
Asia Pacific LED Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific LED Packaging Market Outlook
Flip-chip and chip-scale packaging architectures is rewriting how high-brightness LED modules achieve thermal performance and lumen density. Nichia Corporation leverages its phosphor-converted white LED portfolio to sustain premium positioning in general illumination. Seoul Semiconductor Co. Ltd anchors its competitive stance through WICOP technology leadership in automotive forward-lighting segments. Samsung Electronics Co. Ltd dominates the backlighting supply chain for premium display panels shipped to television OEMs.
Asia Pacific LED packaging encompasses the encapsulation, interconnection, and thermal management of semiconductor dies emitting visible or near-visible radiation, typically employing epoxy or silicone encapsulants with junction temperatures managed below 150°C to ensure lumen maintenance and color stability over operational life. The process transforms bare gallium nitride or indium gallium nitride dies into deployable light sources for illumination, signaling, and display applications. Surface Mount Device configurations lead volume shipments due to compatibility with automated PCB assembly lines serving consumer electronics and retail signage end users. Chip-on-Board technology captures expanding share in high-power general lighting as thermal path optimization becomes critical for lumen-per-watt targets. Flip-chip architectures represent the fastest-growing technology segment as display manufacturers demand finer pixel pitches with improved wall-plug efficiency.
China's MEE enforces escalating energy-efficiency tiers under national standards GB 30255 and GB 24906, compelling packagers to redesign optical and thermal subsystems. South Korea's MFDS and KATS frameworks govern photobiological safety classification and electromagnetic compatibility for LED products distributed domestically. Japan's METI Top Runner program continuously ratchets performance benchmarks for packaged light sources sold into commercial and residential channels. Stakeholders must monitor how divergence between Chinese GB standards and Korean KS certification requirements fragments testing protocols and compliance costs across Northeast Asian supply chains.
Market Dynamics
China's dual carbon goals from MEE are compressing thermal and optical subsystem redesign cycles across the Asia Pacific LED packaging value chain. Packagers must now validate lumen maintenance protocols under stricter GB 30255 tiers while display manufacturers demand finer pixel pitches.
Growth Catalysts
- Automotive forward-lighting specifications:South Korea's KATS framework mandates photobiological safety compliance for headlamp modules, pulling WICOP-class thermal architectures into mass production.
- GB 24906 energy-efficiency tiers:China's MEE ratchets efficacy benchmarks annually, forcing packagers to adopt flip-chip interconnects that reduce junction temperatures below 125°C.
- Chip-on-Board thermal path optimization:High-power street lighting projects across Vietnam and Thailand require direct die attachment to aluminum substrates, eliminating intermediate package layers.
Market Restraints
- Silicone encapsulant cost volatility:Organosilicon feedstock prices fluctuate with petrochemical cracking capacity concentrated in Zhejiang province, compressing gross margins on mid-power SMD lines.
- Gallium nitride substrate supply concentration:Two Japanese suppliers control 80% of high-quality GaN boule output, exposing packagers to allocation risk during display panel demand surges.
- Phosphor-converted white efficacy ceiling:Quantum dot alternatives threaten premium general illumination sockets as color rendering indices above 95 become standard specification.
Strategic Opportunities
- Indonesia's underpenetrated commercial retrofit channel:Jakarta's building energy codes now mandate LED conversion for structures above 10,000 square meters, creating first-mover advantage for COB module suppliers.
- Micro-LED transfer equipment convergence:Laser lift-off bonding aligns with mass transfer pick-and-place systems, enabling packagers to service both consumer displays and automotive HUD projections.
- Australia's NABERS rating integration:Commercial landlords now bundle lighting efficacy scores with lease agreements, opening specification channels for premium lumen-maintenance products.
Industry Challenges
- Thermal simulation talent scarcity:Finite element analysis for junction temperature prediction requires semiconductor physics expertise that packaging houses struggle to recruit in Penang and Suzhou clusters.
- GB-KS certification divergence:China's GB standards and Korea's KS requirements employ incompatible lumen depreciation test protocols, doubling validation timelines for cross-border shipments.
- Flip-chip bumping capex intensity:Copper pillar electroplating lines demand cleanroom infrastructure that mid-tier packagers cannot finance without foundry partnerships.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific LED Packaging Market |
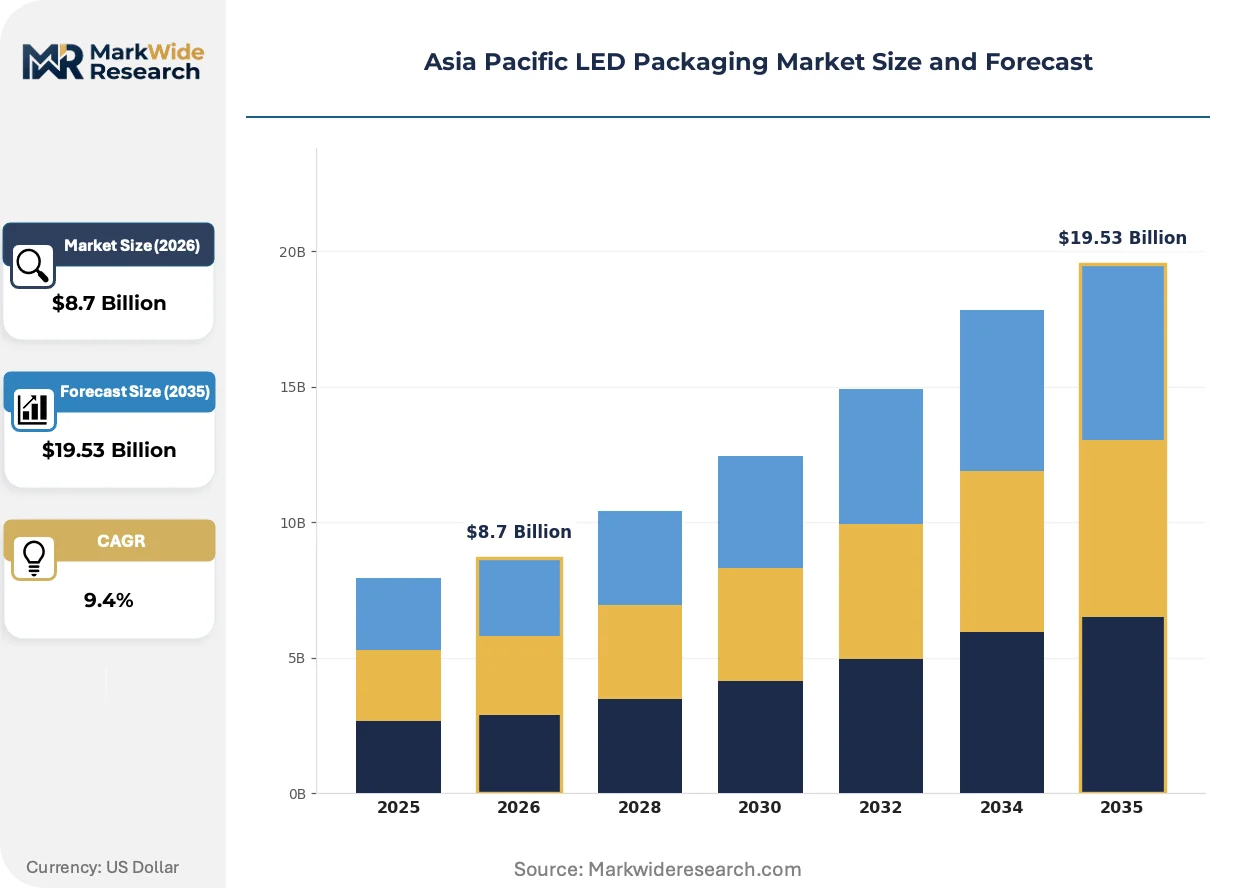
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Chip-on-Board, Surface Mount Device, Flip Chip, InGaN Application: General Lighting, Automotive Lighting, Backlighting, Displays End User: Telecommunications, Consumer Electronics, Automotive, Retail Form Factor: Standard Packages, Customized Packages, 3D Packages, Others |
| Companies Covered | Nichia Corporation, OSRAM Licht AG, Seoul Semiconductor Co. Ltd, Samsung Electronics Co. Ltd, Cree Inc., Everlight Electronics Co. Ltd, Stanley Electric Co. Ltd, Citizen Electronics Co. Ltd, Toyoda Gosei Co., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific LED Packaging Market Strategic Shifts
Digital process control is penetrating phosphor deposition and die bonding stages across Asia Pacific packaging floors. Thermal management architectures are fragmenting by end-use thermal budget. Procurement patterns are compressing supplier qualification cycles as OEMs consolidate vendor lists.
Flip-chip gallium nitride architectures are digitizing how display manufacturers achieve sub-100 micron pixel pitches without sacrificing wall-plug efficiency. Television OEMs in South Korea's manufacturing corridor now specify copper-pillar interconnects for 8K backlighting modules. This shift is digitizing legacy wire-bonding equipment valuations and redirecting capex toward laser-assisted bonding platforms.
Japan's METI Top Runner program continuously ratchets commercial lighting efficacy benchmarks above 150 lumens per watt. Packagers must redesign optical extraction layers and thermal interface materials to maintain product eligibility. Residential channel products face the steepest redesign frequency as METI resets thresholds biennially.
Consolidated vendor lists are compressing qualification timelines from 18 months to 9 months among premium display panel OEMs. Single-source agreements now dominate high-volume backlighting contracts, displacing dual-source risk-mitigation strategies. This concentration is most visible in South Korea's display manufacturing corridor where Samsung and LG Display have reduced qualified packaging suppliers by 40% since 2022.
Asia Pacific LED Packaging Market Segmentation
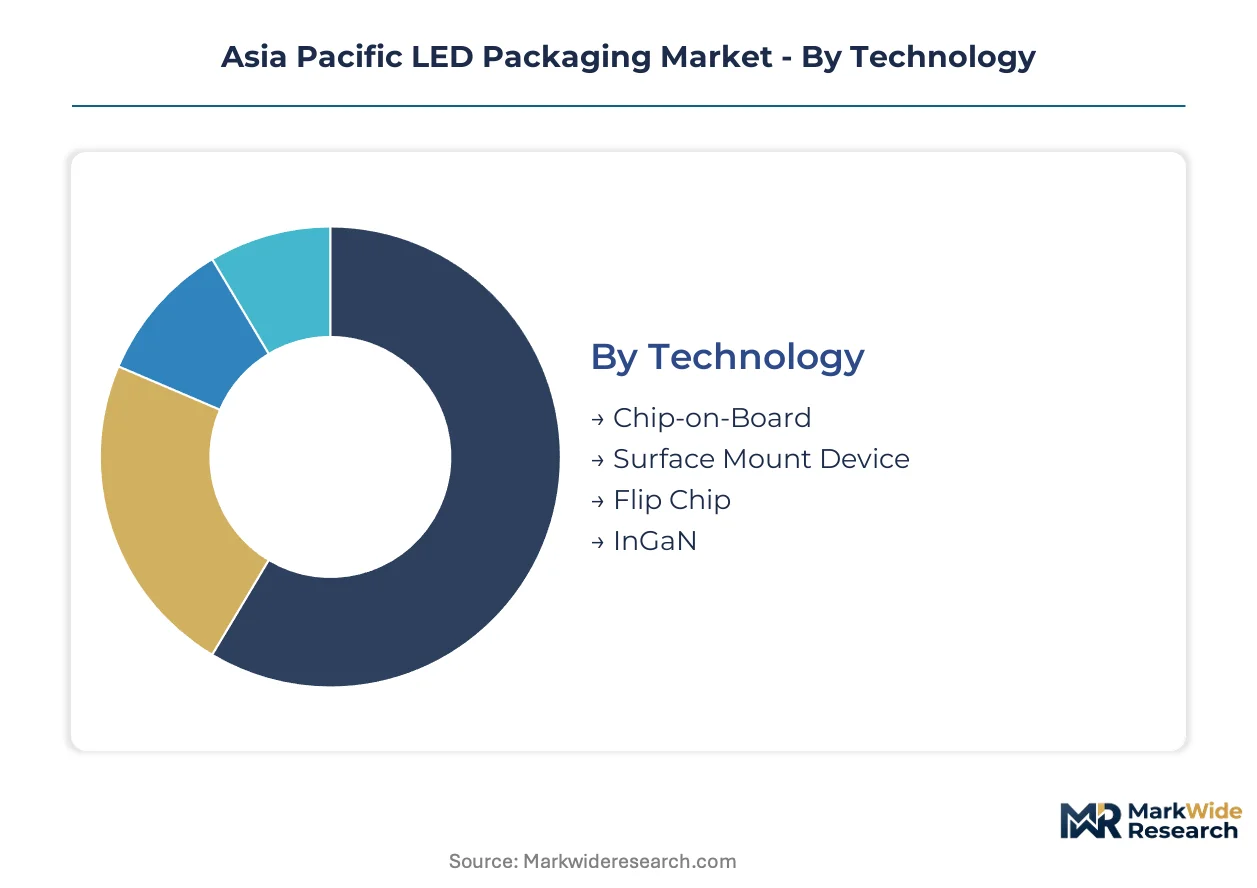
LED packaging segmentation in Asia Pacific reflects divergent thermal budgets and pixel density requirements across automotive, display, and illumination end uses. Technology choices determine capital intensity and redesign frequency, while application mix shapes regional supply chain configuration.
Technology:
Flip-chip architectures turn over fastest as display OEMs demand finer pitches, while Surface Mount Device platforms sustain longest production runs due to standardized PCB assembly compatibility.
- Flip Chip:Copper-pillar interconnects eliminate wire bonds to enable sub-100 micron pixel pitches for 8K backlighting modules. South Korean display manufacturers specify this architecture for premium television panels, though electroplating cleanroom requirements limit supplier participation.
- Surface Mount Device:Epoxy-molded packages with gull-wing or J-lead terminations dominate high-volume consumer electronics assembly. Chinese contract manufacturers favor SMD configurations for retail signage and portable lighting products due to pick-and-place equipment ubiquity in Shenzhen and Suzhou clusters.
- Chip-on-Board:Direct die attachment to aluminum or ceramic substrates optimizes thermal paths for high-power street lighting. Vietnamese and Thai infrastructure projects specify COB modules for lumen-per-watt targets above 150.
- InGaN:Indium gallium nitride epitaxy enables blue and green emission wavelengths for white-light conversion. Japanese substrate suppliers control boule quality specifications that constrain regional packager yield rates.
Surface Mount Device dominates installed base. Flip Chip is where expansion concentrates.
Application:
Cost tier differentiation separates premium automotive forward-lighting from commoditized general illumination, with backlighting occupying a mid-tier position tied to display panel pricing cycles.
- General Lighting:Phosphor-converted white LED modules serve commercial and residential retrofit channels. China's GB 30255 efficacy tiers force annual thermal subsystem redesigns for products sold into domestic distribution.
- Automotive Lighting:Headlamp and taillight modules require WICOP-class thermal architectures to manage junction temperatures below 125°C under KATS photobiological safety mandates. South Korean OEMs specify these packages for export vehicle programs.
- Backlighting:Edge-lit and direct-lit configurations for LCD panels demand tight color uniformity across production lots. Samsung and LG Display procurement concentrates qualified suppliers in Gyeonggi province manufacturing corridors.
- Displays:Micro-LED and mini-LED transfer applications require laser lift-off bonding compatibility. Mass transfer equipment convergence enables packagers to service both consumer displays and automotive HUD projections.
General Lighting commands volume share. Automotive Lighting is climbing the fastest.
End User:
Customer type determines qualification timeline compression, with telecommunications infrastructure requiring longest validation cycles and retail signage permitting shortest supplier onboarding.
- Telecommunications:Base station and data center optical transceivers demand hermetic packaging for 25-year operational life. NEBS compliance testing extends qualification timelines to 18 months for products deployed in Australian and Japanese networks.
- Consumer Electronics:Smartphone and tablet backlighting contracts consolidate around single-source agreements. South Korean panel OEMs reduced qualified packaging suppliers by 40% since 2022, compressing vendor lists to capture scale pricing.
- Automotive:Tier-1 lighting module suppliers enforce AEC-Q101 stress test protocols. KATS electromagnetic compatibility requirements add certification layers for products distributed domestically versus export programs.
- Retail:Digital signage and shelf illumination prioritize lumen-per-dollar over longevity specifications. Indonesian commercial retrofit channels show underpenetrated demand as Jakarta building energy codes mandate LED conversion above 10,000 square meters.
Consumer Electronics concentrates procurement leverage. Retail is gaining share fastest.
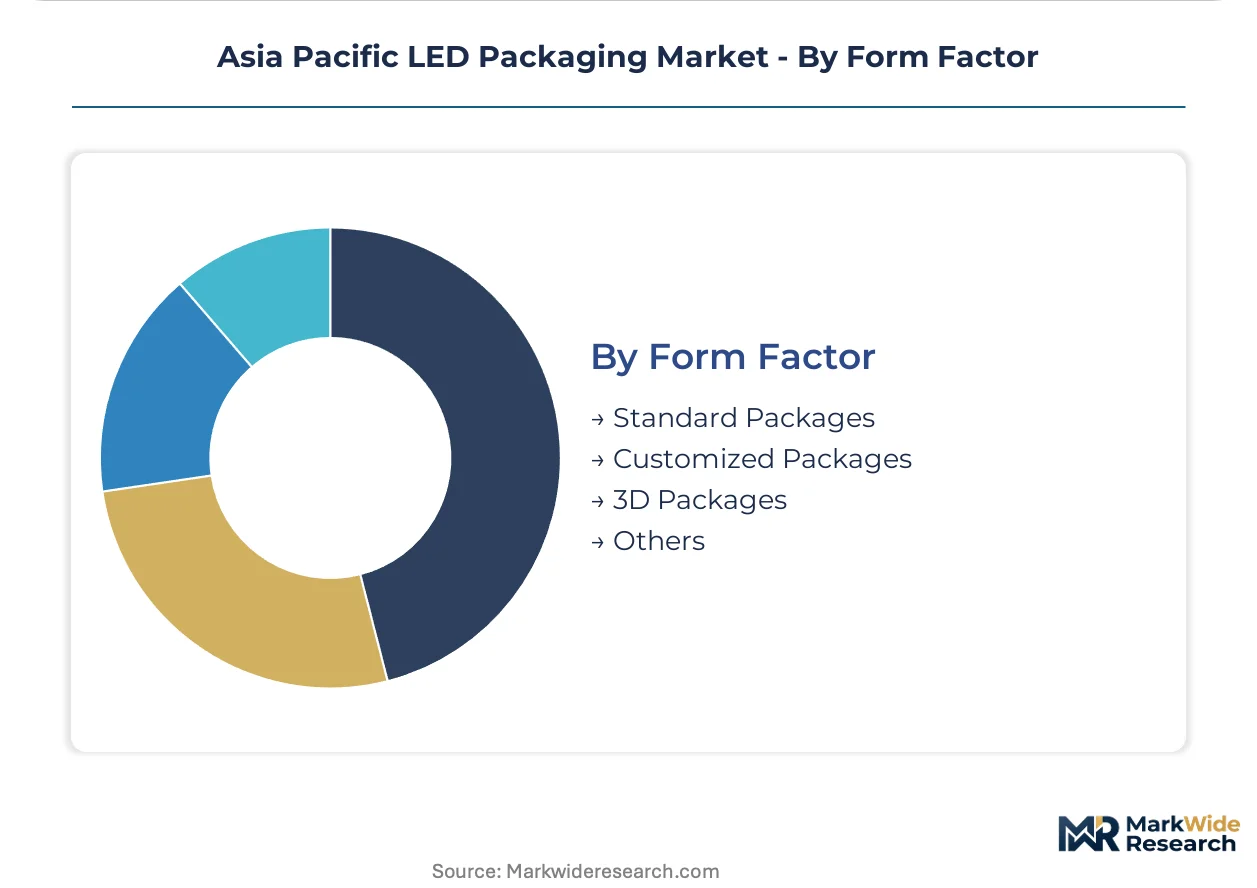
Form Factor:
Package customization intensity correlates with end-use thermal budget specificity, with standard platforms serving cost-sensitive volume applications and 3D architectures addressing emerging optical integration requirements.
- Standard Packages:Pre-defined epoxy or silicone encapsulant dimensions with JEDEC mechanical outlines. Chinese packagers dominate this segment through automated molding line scale in Guangdong province.
- Customized Packages:Application-specific optical lens geometries and thermal interface configurations. Automotive forward-lighting modules require bespoke secondary optic integration for beam pattern compliance.
- 3D Packages:Stacked die and through-silicon via architectures for emerging micro-LED display applications. Laser-assisted bonding platforms enable vertical integration of driver electronics with emitter arrays.
- Others:Experimental and niche configurations including chip-scale and wafer-level packages. These architectures serve R&D programs at Japanese and South Korean display manufacturers.
Standard Packages dominate installed base. Customized Packages is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Korea's display manufacturers export copper-pillar flip-chip modules to television OEMs across Japan and North America, creating a specialized trade corridor that concentrates advanced packaging capacity in Gyeonggi province.
China
Domestic retrofit demand for commercial lighting and street infrastructure drives volume procurement of Chip-on-Board modules. MEE enforces escalating GB 30255 efficacy tiers that compress thermal subsystem redesign cycles to annual intervals. Suzhou and Shenzhen clusters host automated Surface Mount Device lines serving retail signage exporters.
South Korea
8K backlighting contracts from Samsung and LG Display pull WICOP-class thermal architectures into mass production for automotive forward-lighting. KATS mandates photobiological safety compliance for headlamp modules distributed domestically. Gyeonggi province manufacturing corridors concentrate qualified packaging suppliers under single-source procurement agreements.
Japan
METI Top Runner program ratchets commercial lighting efficacy benchmarks above 150 lumens per watt, forcing biennial optical extraction layer redesigns. Phosphor-converted white LED modules face quantum dot substitution threats in premium general illumination. Kanto region substrate suppliers control gallium nitride boule quality specifications that constrain regional packager yields.
Vietnam
Infrastructure projects across Hanoi and Ho Chi Minh City specify high-power street lighting with lumen-per-watt targets above 150. Direct die attachment to aluminum substrates eliminates intermediate package layers for thermal path optimization. Local distributors import Chip-on-Board modules from Guangdong province packagers to meet municipal procurement timelines.
Indonesia
Jakarta building energy codes mandate LED conversion for commercial structures above 10,000 square meters, creating first-mover advantage for retrofit channel suppliers. Underpenetrated demand concentrates in retail and hospitality verticals. Surabaya and Bandung emerging as secondary distribution nodes for imported Surface Mount Device inventories.
Asia Pacific LED Packaging Market Competitive Environment
On the supply side, the industry is consolidating around three distinct capability tiers. Premium positioning depends on phosphor-converted white LED portfolios and flip-chip thermal architectures. Mid-tier competitors compete on automated molding line scale in standardized Surface Mount Device configurations. Capacity expansion and strategic licensing agreements represent the dominant competitive moves as packagers seek foundry partnerships for copper pillar electroplating infrastructure.
Within the premium phosphor and thermal architecture tier, Nichia Corporation and Seoul Semiconductor Co. Ltd exemplify specialized positioning, while Samsung Electronics Co. Ltd anchors the scale-driven display integration segment. These three entities represent divergent strategic archetypes: materials science leadership, automotive forward-lighting specialization, and vertical control over backlighting supply chains.
| Leading Market Players |
|---|
| Nichia Corporation |
| OSRAM Licht AG |
| Seoul Semiconductor Co. Ltd |
| Samsung Electronics Co. Ltd |
| Cree Inc. |
| Everlight Electronics Co. Ltd |
| Stanley Electric Co. Ltd |
| Citizen Electronics Co. Ltd |
| Toyoda Gosei Co. |
| Others |
Value Chain & Pricing Dynamics
The Shanghai-Busan maritime corridor's freight cost volatility compresses margin buffers for mid-tier Surface Mount Device packagers while amplifying price differentiation between premium flip-chip modules and commodity Chip-on-Board lines. Chinese molding houses absorb container rate spikes through volume scale, forcing Korean and Japanese competitors to reposition toward thermal architecture specialization or exit volume segments entirely.
Pricing Analysis
Flip-chip copper-pillar interconnects command three to four times the per-unit pricing of wire-bond Surface Mount Device alternatives, with next-generation micro-LED transfer architectures targeting further premiums. Three-tier pricing structure across premium, standard, and economy levels separates AEC-Q101 automotive-qualified modules from commercial retrofit products and unbranded signage components. Cost compression in mid-power SMD lines is intensifying because Zhejiang province organosilicon feedstock volatility transmits directly to encapsulant costs. Retail signage buyers exhibit highest price sensitivity, while automotive Tier-1 suppliers prioritize thermal performance over unit economics.
Supply Chain Analysis
Tariff exposure between China and South Korea dominates supply chain risk calculus for display backlighting contracts, with Japanese gallium nitride substrate suppliers controlling boule quality specifications that constrain regional packager yields. Manufacturing gravity centers on Guangdong province for automated molding lines, Gyeonggi province for flip-chip cleanroom infrastructure, and Kanto region for phosphor and substrate materials. Raw material dependencies span indium gallium nitride epitaxy wafers, silicone encapsulants, and rare-earth phosphor formulations. Single-source vulnerability pervades high-quality GaN boule allocation from Japanese suppliers. Distribution runs through Shenzhen component markets for retail signage, Gyeonggi corridor direct contracts for display OEMs, and Jakarta distributor networks for Indonesian retrofit channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
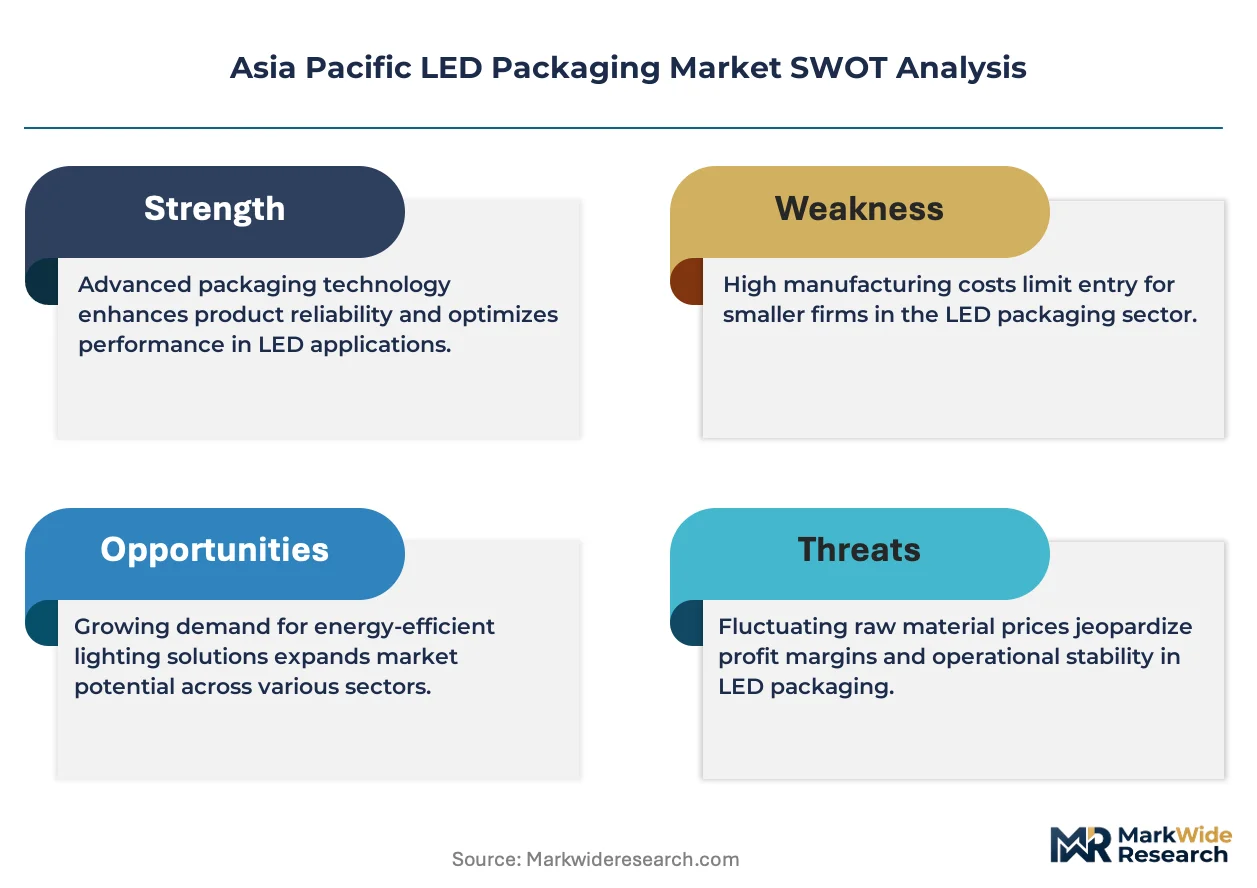
Fragmentation opportunity pervades this market as China's MEE efficacy tiers force annual thermal subsystem redesigns, creating specialist niches for packagers with finite element analysis capabilities and foundry partnerships. Demand-side regulatory divergence between GB and KS certification protocols prevents scale players from dominating all segments simultaneously.
For Market Incumbents: Harden WICOP-class thermal architecture portfolios against quantum dot substitution threats in premium automotive forward-lighting by deepening phosphor-converted white efficacy research. Secure captive supply of high-quality GaN substrates through long-term offtake agreements with Japanese boule suppliers. Expand copper-pillar electroplating partnerships to lock out mid-tier competitors from flip-chip qualification.
For New Entrants and Emerging Players: Indonesia's underpenetrated commercial retrofit channel offers lowest competitive density among major Asia Pacific economies, with Jakarta building energy codes mandating LED conversion above 10,000 square meters creating immediate specification opportunities. Target Vietnamese high-power street lighting projects requiring direct die attachment to aluminum substrates. Pursue foundry partnerships with Guangdong molding houses to bypass cleanroom capex requirements.
For Investors and Strategic Acquirers: Mid-scale packagers with thermal simulation talent scarcity and existing GB-KS dual certification capabilities represent priority acquisition targets for platform consolidation plays. Long-term viability hinges on positioning for micro-LED transfer equipment convergence across consumer displays and automotive HUD projections. Monitor laser-assisted bonding platform adoption rates among South Korean display manufacturers as inflection indicator for next-generation packaging technology transition timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Foundry Partnership for Copper Pillar Infrastructure | Cleanroom electroplating access enables flip-chip qualification without capital intensity burden. |
| Dual GB-KS Certification Investment | Simultaneous compliance with Chinese and Korean protocols captures cross-border display contracts. |
| Phosphor-Converted White R&D Expansion | Efficacy advancement defends against quantum dot substitution in premium illumination sockets. |
| Thermal Simulation Talent Acquisition | Finite element analysis capabilities differentiate high-power COB module suppliers. |
| Indonesian Distribution Channel Buildout | First-mover positioning in Jakarta retrofit market leverages mandatory conversion regulations. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of customs trade databases, SEC filings from listed packaging houses, and METI efficacy benchmark publications. Primary interviews engaged packaging engineering directors, automotive Tier-1 procurement managers, display panel OEM supply chain leads, and thermal materials R&D specialists. Secondary validation drew from GB standards documentation, KATS certification protocols, and Vietnam infrastructure procurement disclosures. Bottom-up unit shipment estimates triangulate against top-down value projections across technology and application segments.
Forecast inputs include technology adoption curves for flip-chip versus wire-bond architectures, efficacy tier progression under Chinese MEE regulations, and display panel production schedules from Gyeonggi province manufacturers. Segmentation dimensions span packaging technology, application end-use, and regional regulatory cluster. CAGRs derive from regression analysis of historical shipment data against projected efficacy requirement tightening and pixel pitch evolution in backlighting specifications. Industry-specific inputs incorporate phosphor efficacy ceilings and GaN substrate allocation constraints.
Practitioners should monitor MEE efficacy tier acceleration, Japanese GaN boule supplier capacity announcements, and South Korean display OEM vendor list consolidation for early signals of forecast deviation. Forecasts reflect assumptions about regulatory enforcement continuity and thermal architecture substitution elasticities. Material shifts in Chinese dual carbon policy implementation pace or breakthrough quantum dot cost reduction would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Packaging
Outsourced Semiconductor Assembly and Test Services (OSAT) Market
Semiconductor Packaging
Through-Silicon via (TSV) IC Packaging Market
Semiconductor Packaging
Chip Carrier Socket Market
Semiconductor Packaging
Global Semiconductor Equipment Packaging and Test Market
Semiconductor Packaging
Through Silicon via (TSV) Packaging Market
Semiconductor Packaging
NOR-Based Multi-Chip Packages Market
Semiconductor Packaging
Outsourced Semiconductor Assembly and Testing Market
Semiconductor Packaging
System in Package (Sip) Technology Market
Semiconductor Packaging
2.5D IC Packaging Market
Semiconductor Packaging
Microtube Box Market
Semiconductor Packaging
Multichip Package Market
Semiconductor Packaging
Epoxy Potting Market
Semiconductor Packaging
Global High-End Semiconductor Packaging Market
Semiconductor Packaging
Ball Grid Array (BGA) Packaging Market
Semiconductor Packaging
Global Semiconductor Seals Market
Semiconductor Packaging
3D TSV Packages Market