
 Semiconductor Chip Handler Market | 2026-2036
Semiconductor Chip Handler Market Size, Share, and Industry Trends Forecast 2026-2036
Semiconductor Chip Handler Market Analytics
Aftermarket service revenue is narrowing as original equipment margins compress across the handler installed base. Cohu, Inc. leverages its global refurbishment network to capture recurring revenue from legacy test cell upgrades. Advantest Corporation anchors its position through deep integration with its own tester platforms, creating captive demand for handler pairings. ASM Pacific Technology competes by extending its semiconductor assembly expertise into precision handling modules for advanced packaging lines.
Semiconductor chip handlers are electromechanical systems that transport, orient, and present bare die or packaged devices to test contactors with placement accuracy typically measured in microns; vacuum pick-and-place end effectors, vision alignment subsystems, and thermal conditioning chambers constitute their core functional modules. Their primary purpose is to maximize test throughput while minimizing mechanical damage to delicate devices during high-speed cycling. Automatic handlers dominate volume shipments for commodity memory test floors where uptime and throughput metrics govern procurement decisions. Integrated handlers represent the fastest-growing configuration as heterogeneous integration and chiplet architectures demand sequential test and burn-in operations within unified cells. Hybrid technology platforms that combine vacuum and mechanical gripping mechanisms command premium positioning for thin-die and warped-wafer applications where single-mode handlers risk yield loss.
FDA oversight applies to handlers deployed in medical device semiconductor manufacturing, while EPA regulations govern solvent-based cleaning processes and volatile organic compound emissions from handler maintenance operations in the United States. FCC electromagnetic compatibility standards constrain servo motor drive electronics and wireless diagnostic modules integrated into handler control architectures. OSHA workplace safety rules directly influence handler guarding, interlock design, and robotic zone access protocols for fab and test floor installations. Stakeholders must monitor how converging export control classifications and semiconductor subsidy compliance requirements reshape equipment vendor qualification pathways and customer procurement eligibility across jurisdictions.
Market Dynamics
Handler architectures are bifurcating between high-throughput memory test floors and precision-oriented advanced packaging cells, with heterogeneous integration forcing equipment vendors to reconcile conflicting throughput and accuracy specifications within unified product lines.
Growth Catalysts
- CHIPS Act capital allocation:US-based foundry construction is triggering localized procurement of test floor equipment, with handler vendors establishing domestic service networks to capture subsidy-linked purchasing.
- High-bandwidth memory packaging:AI accelerator demand is expanding burn-in and final test capacity for stacked memory devices, requiring thermal conditioning handlers capable of managing complex thermal profiles.
- Taiwan cluster expansion:Foundry service providers in Hsinchu and Tainan are adding test floor square footage dedicated to chiplet-based designs, sustaining equipment orders for integrated handler configurations.
Market Restraints
- Precise motion component scarcity:Linear motor stages and high-resolution encoders face concentrated supply from Japanese and German precision mechanics suppliers, creating lead time vulnerability.
- Export control friction:US Bureau of Industry and Security licensing requirements for advanced packaging equipment are complicating qualification pathways for handlers targeting sub-7nm test applications.
- Legacy installed base entrenchment:Mature packaging facilities in Malaysia and Thailand retain functional pick-and-place handlers beyond typical depreciation cycles, compressing replacement demand.
Strategic Opportunities
- India semiconductor ecosystem:Gujarat and Karnataka fab projects under the PLI scheme will require greenfield test floor builds, creating first-mover positioning for handler vendors establishing local technical support.
- Medical device semiconductor qualification:FDA 21 CFR Part 820 quality system requirements for diagnostic chip manufacturing are opening specialized handler configurations with enhanced traceability and contamination control.
- Edge AI inference module testing:System-in-package devices integrating logic, memory, and analog functions are demanding sequential test protocols that integrated handler-tester cells can monetize at premium positioning.
Industry Challenges
- Multi-physics simulation expertise:Handler design now requires simultaneous optimization of thermal, mechanical, and electromagnetic behavior, but talent pools combining these disciplines remain shallow in most manufacturing geographies.
- Retrofit integration complexity:Upgrading legacy test cells with vision alignment and thermal conditioning modules demands firmware harmonization across equipment generations that vendors struggle to scope predictably.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Semiconductor Chip Handler Market |
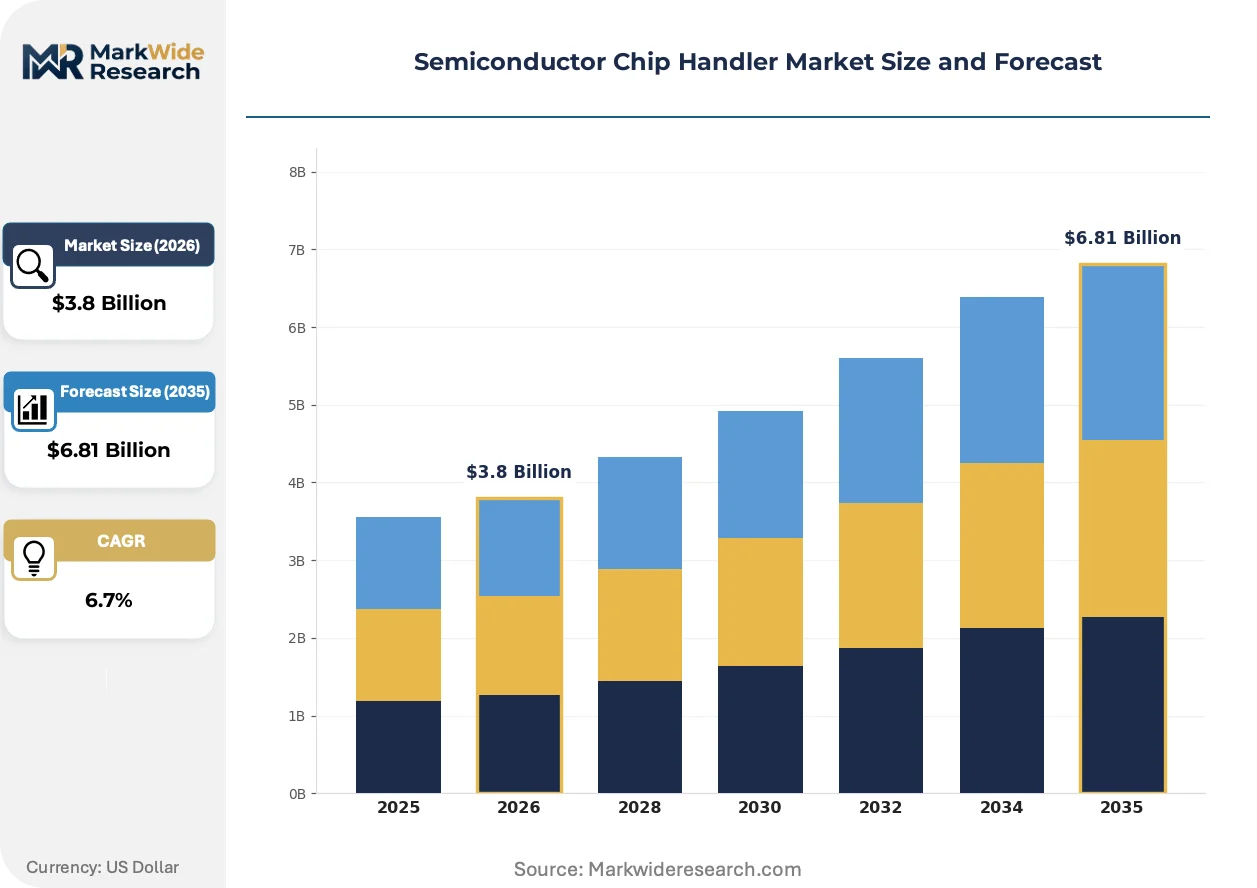
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Handler, Automatic Handler, Integrated Handler, Multi-Function Handler End User: Contract Manufacturers, OEMs, Electronic Assemblers, Research Laboratories Technology: Vacuum Technology, Mechanical Technology, Hybrid Technology, Laser Technology Application: Memory Chips, Microprocessors, ASICs, Integrated Circuits |
| Companies Covered | Cohu, Inc., Advantest Corporation, ASM Pacific Technology, ChangChuan Technology, TESEC Corporation, Boston Semi Equipment, Hon Precision, SRM Integration, Exis Tech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Semiconductor Chip Handler Market Evolving Landscape
Digital thread architectures are penetrating handler control systems, enabling predictive maintenance and remote diagnostics that reshape service revenue models and equipment uptime guarantees.
Machine vision subsystems incorporating sub-pixel edge detection algorithms are digitizing die placement verification, with advanced packaging lines in South Korea and Taiwan adopting these modules to manage warped substrates and thin-die handling. Memory test floors lag this transition, prioritizing cycle time over inspection depth. The capability gap is digitizing competitive differentiation between commodity and precision handler tiers.
REACH substance restrictions on perfluorinated compounds are forcing solvent cleaning process redesigns for handler maintenance operations across European manufacturing facilities. Equipment vendors are qualifying aqueous and plasma-based alternatives that comply with ECHA authorization requirements. Medical device semiconductor handlers face parallel EPA VOC emission constraints in US installations, creating dual-jurisdiction compliance engineering burdens.
Service contract unbundling is separating hardware procurement from maintenance and software upgrade commitments, with large foundry buyers negotiating à la carte support terms. This fragmentation pressures vendor recurring revenue predictability and forces explicit pricing of firmware feature releases. The pattern is most pronounced in Singapore and Arizona fab projects where capital discipline accompanies subsidy compliance reporting.
Semiconductor Chip Handler Market Segmentation
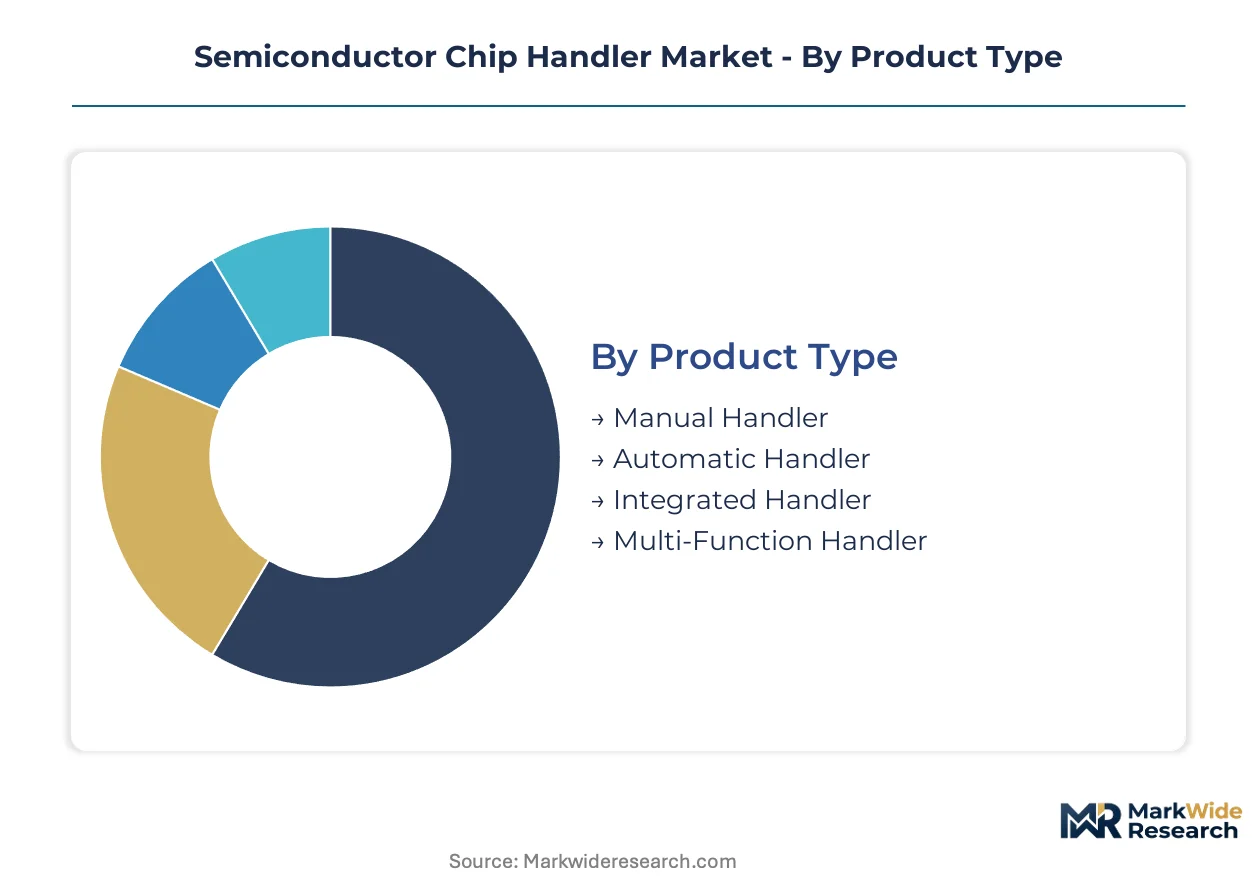
Segmentation in semiconductor chip handlers reveals how equipment specifications diverge across test floor architectures. Procurement patterns differ sharply between high-volume memory operations and precision advanced packaging cells, with service intensity varying by configuration complexity.
Product Type:
After-sales service intensity escalates with handler automation level, as integrated configurations demand firmware synchronization and multi-module calibration protocols.
- Automatic Handler:Vacuum pick-and-place architectures dominate commodity memory test floors with cycle-time-optimized kinematics. Demand concentrates in Taiwan and South Korea foundry expansions where uptime guarantees drive procurement decisions.
- Integrated Handler:Unified cells combine sequential test, burn-in, and inspection operations for chiplet-based heterogeneous integration. South Korean packaging houses are expanding capacity for high-bandwidth memory stacks, requiring thermal conditioning modules with complex profile management.
- Manual Handler:Operator-directed systems persist in low-volume qualification and prototype environments.
- Multi-Function Handler:Reconfigurable platforms serve mixed-product test floors with rapid changeover capabilities.
Automatic handler configurations hold the largest share; momentum sits with integrated handler architectures.
End User:
Procurement authority shapes equipment specifications, with foundry buyers demanding unbundled service contracts and explicit firmware feature pricing.
- Contract Manufacturers:OSAT facilities in Malaysia and Thailand operate mature installed bases with extended depreciation cycles, compressing replacement demand.
- OEMs:Captive test floor operators in the United States are expanding capacity under CHIPS Act capital allocation, requiring domestic service network qualification.
- Electronic Assemblers:System-in-package integrators demand sequential test protocols for edge AI inference modules.
- Research Laboratories:University and national lab facilities prioritize flexibility over throughput metrics.
Contract manufacturers represent the largest installed base; OEM direct procurement is climbing the fastest.
Technology:
Precision mechanics supply concentration in Japan and Germany constrains technology adoption timelines for advanced gripping architectures.
- Hybrid Technology:Combined vacuum and mechanical gripping mechanisms command premium positioning for thin-die and warped-wafer applications where single-mode handlers risk yield loss. Taiwan advanced packaging lines are adopting these modules to manage substrate warpage from heterogeneous integration thermal cycles.
- Vacuum Technology:Pick-and-place systems with sub-micron placement accuracy serve standard packaged device test floors.
- Mechanical Technology:Jaw-based gripping persists in legacy configurations for robust packaged devices.
- Laser Technology:Non-contact die handling emerges for extreme thin-die applications requiring zero mechanical contact.
Vacuum technology holds the largest share; hybrid configurations are gaining share fastest.
Application:
AI accelerator demand is bifurcating test floor investment between high-bandwidth memory burn-in capacity and logic device precision handling.
- Memory Chips:DRAM and NAND test floors prioritize throughput metrics with automatic handler configurations. Taiwan foundry expansions in Hsinchu and Tainan are adding square footage dedicated to stacked memory device final test.
- ASICs:Application-specific integrated circuits for AI inference demand integrated handler-tester cells with sequential test protocols.
- Microprocessors:High-pin-count devices require precision contactor alignment with vision subsystem verification.
- Integrated Circuits:General-purpose analog and mixed-signal devices span commodity to precision handler tiers.
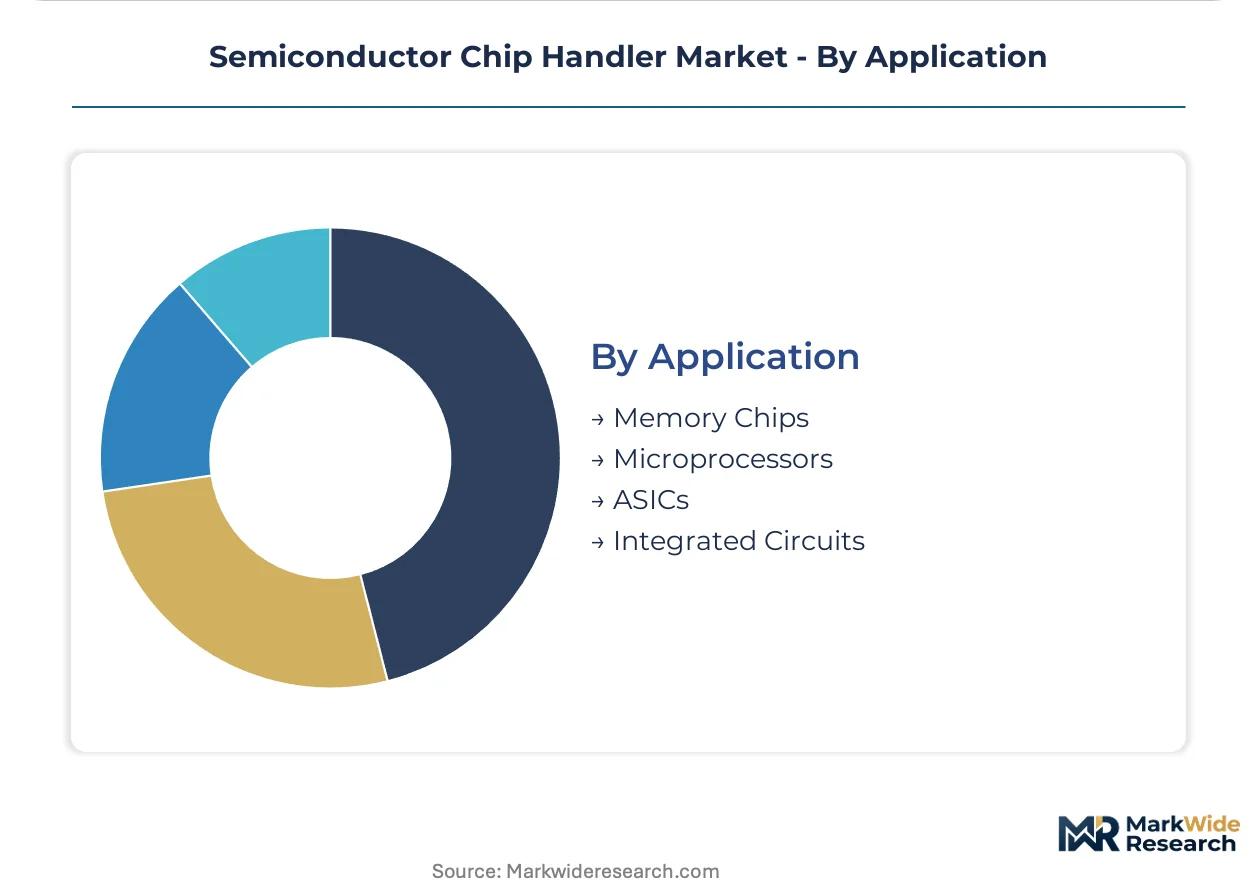
Memory chip applications hold the largest share; ASIC test capacity expansion shows the steepest trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Handler manufacturing clusters concentrate in East Asian electronics corridors, with precision mechanics suppliers in Japan and Germany anchoring upstream component flows. Subsidy programs in the United States and India are redrawing procurement geography for test floor equipment.
United States
CHIPS Act capital allocation is expanding foundry test floor capacity in Arizona and Texas. OSHA workplace safety rules govern robotic zone access protocols for fab installations. Greater Phoenix hosts emerging domestic service network builds by handler vendors seeking subsidy-linked procurement eligibility.
Taiwan
Foundry service providers in Hsinchu and Tainan are adding square footage for chiplet-based designs and high-bandwidth memory stacks. The island's precision trade controls align with US Bureau of Industry and Security licensing frameworks for sub-7nm equipment. Advanced packaging lines in Taichung are adopting hybrid gripping modules for warped-wafer applications.
South Korea
AI accelerator demand is expanding burn-in capacity for stacked memory devices requiring complex thermal profile management. MFDS oversight applies to handlers deployed in medical device semiconductor manufacturing. Packaging houses in Suwon and Pyeongtaek are scaling integrated handler-tester cells for heterogeneous integration.
Japan
Linear motor stages and high-resolution encoders from Japanese precision mechanics suppliers create lead time vulnerability for handler manufacturers worldwide. METI industrial policy supports domestic equipment vendor qualification pathways. Nagoya and Osaka industrial corridors concentrate motion component fabrication for semiconductor capital equipment.
India
Gujarat and Karnataka fab projects under the PLI scheme will require greenfield test floor builds with domestic technical support networks. BIS certification requirements shape equipment import and localization timelines. Dholera and Bengaluru manufacturing corridors are emerging as handler vendor service hub priorities.
Semiconductor Chip Handler Market Competitive Landscape
Integrated equipment conglomerates and precision automation specialists split the market between captive tester-handler pairings and modular open-architecture configurations. Vendor tiers stratify by service network density and firmware integration depth. Dominant competitive moves include geographic service expansion to capture subsidy-linked procurement and portfolio diversification into thermal conditioning modules for advanced packaging.
Among US-based equipment vendors, Cohu, Inc. and Boston Semi Equipment occupy positions within the refurbishment and legacy upgrade service archetype. Japanese conglomerates represented by Advantest Corporation exemplify the integrated tester-handler pairing model. ASM Pacific Technology anchors the precision automation specialist tier extending assembly expertise into handling modules.
| Leading Market Players |
|---|
| Cohu, Inc. |
| Advantest Corporation |
| ASM Pacific Technology |
| ChangChuan Technology |
| TESEC Corporation |
| Boston Semi Equipment |
| Hon Precision |
| SRM Integration |
| Exis Tech |
| Others |
Value Network & Pricing Analysis
Nagoya and Osaka industrial corridors concentrate linear motor stage and high-resolution encoder fabrication, creating upstream pricing power that handler manufacturers pass downstream through equipment cost structures. Japanese precision mechanics suppliers anchor component availability timelines, while foundry buyers in Taiwan and South Korea negotiate volume discounts that compress margins for commodity automatic handler configurations.
Pricing Analysis
OSHA workplace safety rules dictate the pricing tier structure for handler installations in US fab projects, with compliance-engineered guarding and interlock systems commanding premium positioning over standard configurations. Three-tier pricing structure across premium, standard, and economy levels separates integrated handler-tester cells with firmware synchronization from basic vacuum pick-and-place units. Cost compression in automatic handler segments is intensifying because legacy installed base entrenchment in Malaysia and Thailand extends replacement cycles. Contract manufacturers in OSAT facilities demonstrate highest price sensitivity, while OEM captive test floors under CHIPS Act capital allocation prioritize uptime guarantees over unit cost.
Supply Chain Analysis
US Bureau of Industry and Security licensing requirements for advanced packaging equipment constrain component flows for sub-7nm test applications, forcing handler vendors to qualify alternative sourcing pathways. Taiwan, South Korea, and Japan anchor geographic supply concentration for precision motion components and thermal conditioning modules. Raw material dependencies center on rare-earth magnets for linear motors, ceramic substrates for thermal chambers, and high-purity aluminum for vacuum end effectors. Single-source vulnerability from Japanese encoder suppliers creates lead time risk for integrated handler production. Distribution runs through direct sales teams for large foundry accounts and regional distributors for mid-tier OSAT facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Handler control architectures are shifting toward digital thread platforms that enable predictive maintenance monetization, with firmware integration depth becoming the primary interoperability battleground for equipment vendor ecosystems.
For Market Incumbents: Pre-empt service contract unbundling by establishing explicit à la carte pricing for firmware feature releases before large foundry buyers in Singapore and Arizona force terms. Defend against emerging precision automation specialists by deepening backward integration into thermal conditioning module production. Capture recurring revenue predictability through captive refurbishment networks for legacy test cell upgrades. For New Entrants and Emerging Players: Establish a beachhead in India's Gujarat and Karnataka fab corridors before domestic technical support networks solidify around incumbent vendors. Target medical device semiconductor qualification segments where FDA 21 CFR Part 820 requirements create specialized handler demand with enhanced traceability. Pursue go-to-market partnerships with precision mechanics suppliers in Japan to bypass linear motor stage scarcity. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrated handler-tester cell vendors with firmware synchronization capabilities over modular open-architecture specialists. Long-term viability hinges on exposure to high-bandwidth memory burn-in capacity expansion and chiplet-based heterogeneous integration trends. Watch for inflection signals in CHIPS Act subsidy compliance requirements that reshape equipment vendor qualification pathways.| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Service Network Expansion | Captures CHIPS Act subsidy-linked procurement in Arizona and Texas fab corridors. |
| Thermal Conditioning Module Integration | Addresses AI accelerator demand for complex burn-in profile management in South Korea. |
| Firmware Feature Unbundling | Responds to Singapore foundry buyer pressure for explicit software upgrade pricing. |
| Hybrid Gripping Technology Development | Enables thin-die handling for warped substrates from heterogeneous integration thermal cycles. |
| India Technical Support Hub Establishment | Positions for PLI scheme greenfield test floor builds in Dholera and Bengaluru corridors. |
Research Methodology
Initial hypotheses were tested against primary input from test floor operations managers, semiconductor capital equipment procurement directors, precision mechanics component suppliers, and aftermarket service heads, then refined through secondary validation. Primary fieldwork drew from handler vendor engineering teams, foundry reliability engineers, and OSAT facility maintenance directors across Taiwan, South Korea, Japan, and the United States. Secondary sources included SEC 10-K filings from listed equipment vendors, customs trade data for precision motion component flows, OSHA regulatory guidance documents, and Bureau of Industry and Security export control classifications. Bottom-up equipment shipment tallies and top-down foundry capex allocation models were triangulated to reconcile volume estimates.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, with handler procurement modeled against foundry test floor square footage expansion and burn-in capacity buildout timelines. Segmentation dimensions included automation level, end-user procurement authority, gripping technology architecture, and application-specific thermal profile requirements. CAGRs were derived from equipment vendor order backlog analysis and foundry customer pipeline confirmation. Industry-specific forecast inputs incorporated CHIPS Act capital allocation schedules and EU Chips Act subsidy compliance timelines.
Stress conditions across export control licensing delays, precision component lead time extensions, and subsidy program eligibility revisions were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding foundry construction completion rates and handler replacement cycle normalization. Material shifts in US-Taiwan trade control alignment or Japanese precision mechanics supplier capacity allocation would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Packaging
Global Semiconductor Packaging and Assembly Equipment Market
Semiconductor Packaging
Global Interposer and Fan-Out WLP Market
Semiconductor Packaging
Ceramic IC Packages Market
Semiconductor Packaging
2.5D and 3D Semiconductor Packaging Market
Semiconductor Packaging
2.5D IC Packaging Market
Semiconductor Packaging
Global High-End Semiconductor Packaging Market
Semiconductor Packaging
3D Semiconductor Packaging Market
Semiconductor Packaging
Electronic Board Level Underfill and Encapsulation Material Market
Semiconductor Packaging
Fan Out Packaging Market
Semiconductor Packaging
Wafer Carrier Boxes Market
Semiconductor Packaging
Embedded Die Packaging Market
Semiconductor Packaging
3D TSV Packages Market
Semiconductor Packaging
Advanced Semiconductor Packaging Market
Semiconductor Packaging
Global Semiconductor Seals Market
Semiconductor Packaging
IC Packaging and Testing Market
Semiconductor Packaging
3D IC Packaging Market