
 Advanced Semiconductor Packaging Market | 2026-2036
Advanced Semiconductor Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Advanced Semiconductor Packaging Market Analysis
The gap between premium interposer-based 2.5D/3D packaging and commodity leadframe/organic substrate solutions is recalibrating competitive investment thresholds across the industry. Samsung Electronics leverages its captive memory and logic foundry positions to integrate advanced packaging in-house from wafer to module. Taiwan Semiconductor Manufacturing Company dominates the bleeding-edge CoWoS and InFO platforms that supply NVIDIA and AMD AI accelerators. Amkor Technology competes aggressively in the OSAT tier, extending its geographic footprint to serve fabless customers seeking supply chain diversification.
Advanced semiconductor packaging encompasses the set of interconnect, substrate, and encapsulation technologies that enable multiple dies to function as a unified system with electrical, thermal, and mechanical integrity, typically employing copper pillar bumps, through-silicon vias with aspect ratios exceeding 10:1, and redistribution layers at sub-2 micrometer line widths to achieve bandwidth densities beyond 1 Tbps per millimeter. The primary industrial purpose is to overcome the slowing of transistor scaling by replacing monolithic system-on-chip architectures with disaggregated chiplets that optimize yield, cost, and performance across process nodes. System in Package configurations now anchor the highest-volume segment as smartphone and wearable OEMs prioritize footprint reduction over raw compute density. Through Silicon Via technology leads the premium tier where HBM stack integration demands vertical interconnect pitches below 40 micrometers. Fan Out wafer-level packaging is displacing traditional flip chip in mid-range mobile applications as panel-level processing matures.
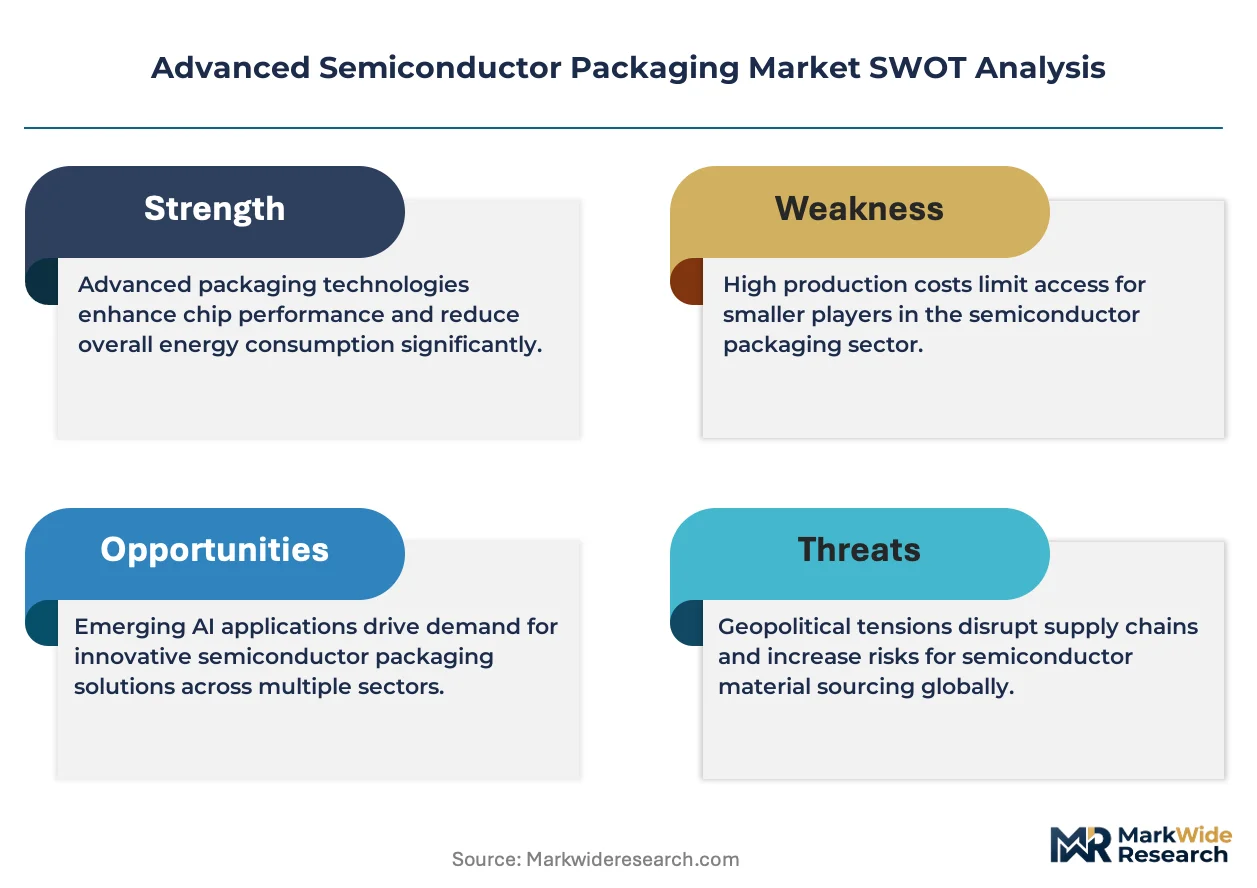
REACH and RoHS frameworks in Europe restrict lead-based solders and halogenated flame retardants in substrate materials, forcing reformulation of underfill and molding compounds across the supply chain. The US CHIPS and Science Act and Japan's METI semiconductor subsidies are reshaping where new packaging capacity receives public capital, with strings attached to domestic content thresholds. China's GB standards and dual carbon goals impose energy-efficiency benchmarks on fabs and OSATs operating within its borders. Stakeholders must monitor which regulatory jurisdictions capture the next wave of advanced packaging investment, as subsidy eligibility and environmental compliance costs will determine long-term cost structures more than process technology alone.
Market Dynamics
The AI accelerator buildout is compressing advanced packaging capacity timelines, forcing OSATs and foundries to choose between CoWoS expansion and legacy node commitments as interposer supply tightens.
Growth Catalysts
- EU Chips Act capital deployment:Subsidy frameworks redirect public funds toward domestic substrate and interposer fabrication, reducing import dependency for European automotive semiconductor sourcing.
- HBM3E stack integration:Through-silicon via pitch scaling below 35 micrometers enables 12-high memory configurations that AI training clusters require for bandwidth density.
- Panel-level fan-out maturation:600mm x 600mm processing formats cut unit costs for mid-range mobile system-in-package modules, drawing smartphone OEMs away from traditional flip-chip.
Market Restraints
- EMC and underfill feedstock volatility:Epoxy molding compound formulations depend on specialized silica fillers and resin systems subject to petrochemical price swings and Japan-centric supplier concentration.
- Interposer wafer bottleneck:Silicon interposer manufacturing requires 65nm-class lithography capacity that memory foundries and logic nodes compete for, creating allocation conflicts during demand surges.
- REACH substance restrictions:ECHA candidate list expansions threaten brominated flame retardants in substrate laminates, forcing reformulation cycles that extend qualification timelines by 12-18 months.
Strategic Opportunities
- India OSAT greenfield development:PLI scheme incentives for semiconductor assembly and testing attract packaging investment to Gujarat and Tamil Nadu, targeting export markets with cost-competitive fan-out capacity.
- Automotive chiplets for zonal architectures:Disaggregated sensor fusion and domain controller modules create demand for heterogeneous integration formats that legacy wirebond cannot satisfy.
- Glass core substrate piloting:Corning and suppliers in Japan are advancing glass interposers that eliminate CTE mismatch with organic alternatives, opening paths for 2.5D scaling beyond silicon limits.
Industry Challenges
- Advanced packaging process engineering talent scarcity:RDL lithography, TSV etch, and thermocompression bonding require specialized technicians that university programs and incumbent workforce pipelines fail to replenish.
- Multi-die thermal co-design complexity:Heterogeneous integration forces simultaneous optimization of logic, memory, and interposer thermal profiles, straining EDA tool capabilities and design-service capacity.
- OSAT-customer IP firewalling:Foundry-proprietary CoWoS and InFO process parameters create information asymmetries that complicate yield debugging and liability allocation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Advanced Semiconductor Packaging Market |
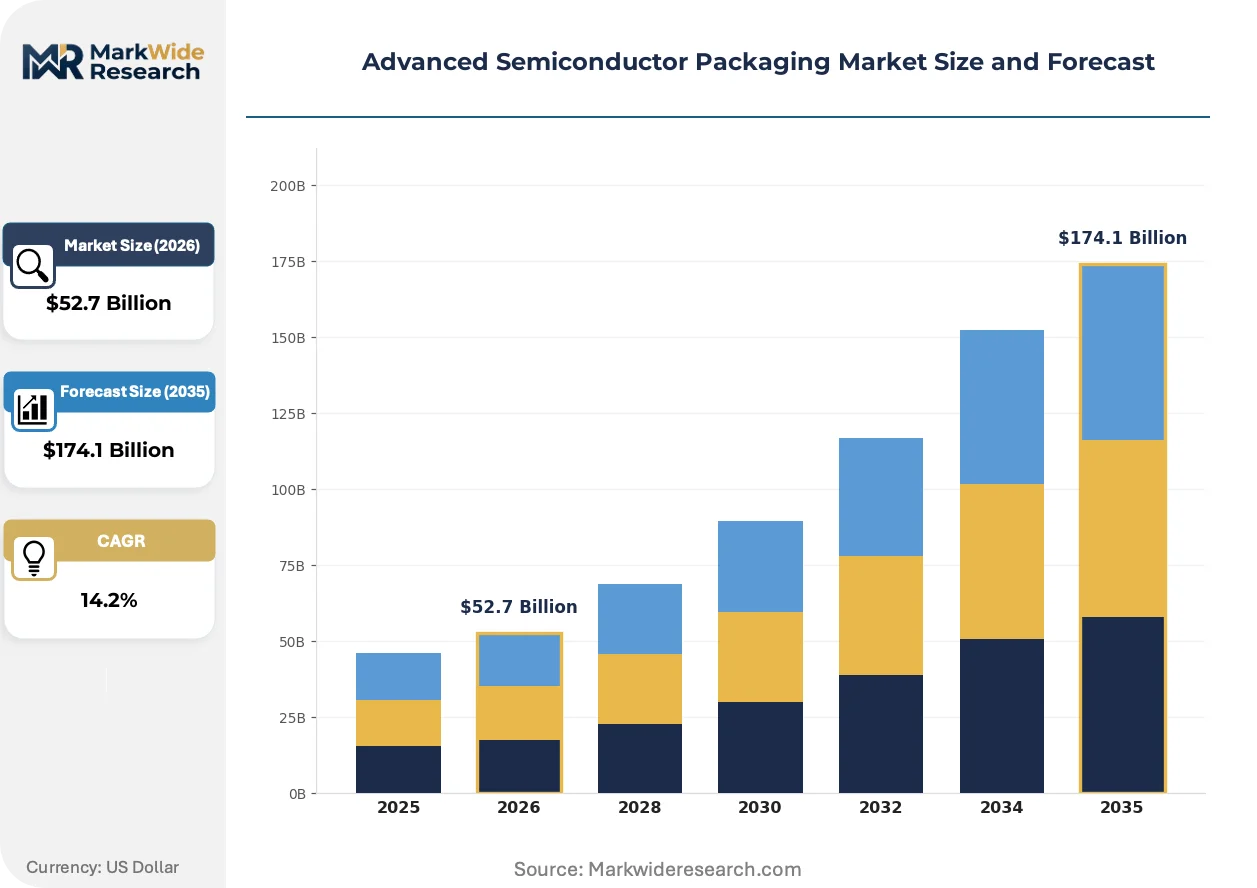
| Market Size in 2026 | $52.7 Billion |
| Market Size in 2035 | $174.1 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
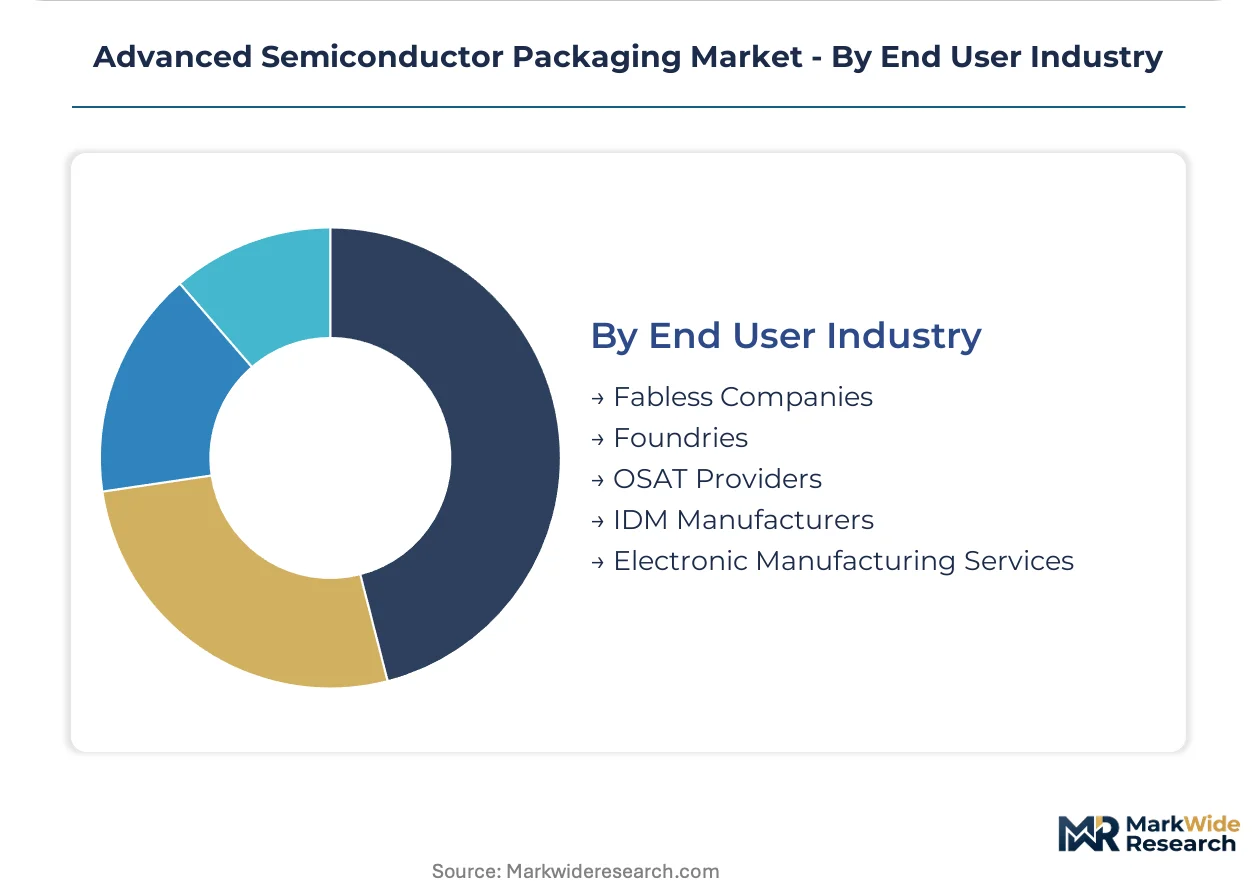
| Segmentation | Package Type: System in Package, Wafer Level Package, Flip Chip, Chip Scale Package, Multi-Chip Module Technology: Through Silicon Via, 3D IC, Fan Out, Embedded Die, Micro Bump Application: Consumer Electronics, Telecommunications Equipment, Aerospace Systems, Industrial Automation, Military Defense End User Industry: Fabless Companies, Foundries, OSAT Providers, IDM Manufacturers, Electronic Manufacturing Services |
| Companies Covered | Samsung Electronics Co., Ltd., JCET Group Corporation, Amkor Technology Inc., NXP Semiconductors NV, SK Hynix Inc., Advanced Semiconductor Engineering, Inc., Intel Corporation, Micron Technology Inc., Taiwan Semiconductor Manufacturing Company Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Advanced Semiconductor Packaging Market Emerging Trajectories
Process convergence between front-end wafer fabrication and back-end assembly is dissolving traditional foundry-OSAT boundaries, creating new competitive arenas around substrate, interposer, and module integration.
Hybrid bonding is expanding into high-bandwidth memory stacking and logic-on-logic configurations, replacing microbump interconnects for pitches below 10 micrometers. Apple and NVIDIA have qualified copper-to-copper direct bond technologies for flagship processors. This shift is compressing the effective market for solder-based flip-chip and forcing equipment suppliers to retool for plasma activation and room-temperature bonding platforms.
CSRD disclosure mandates from ECHA are compelling packaging houses to document Scope 3 emissions across substrate laminates, molding compounds, and interposer silicon. Supply chain audit requirements now extend to Korean and Taiwanese material suppliers serving European automotive module customers. Mid-tier OSATs without embedded carbon accounting systems face procurement disqualification from EU-based OEMs.
Consolidated procurement through hyperscaler direct sourcing is displacing traditional distributor and contract manufacturer channels for AI accelerator modules. Microsoft, Amazon, and Google now negotiate packaging capacity directly with TSMC and ASE, bypassing fabless semiconductor vendors. Taiwan anchors this concentration, though Arizona and Japan greenfield sites are capturing qualification volumes for geographic risk mitigation.
Advanced Semiconductor Packaging Market Segmentation
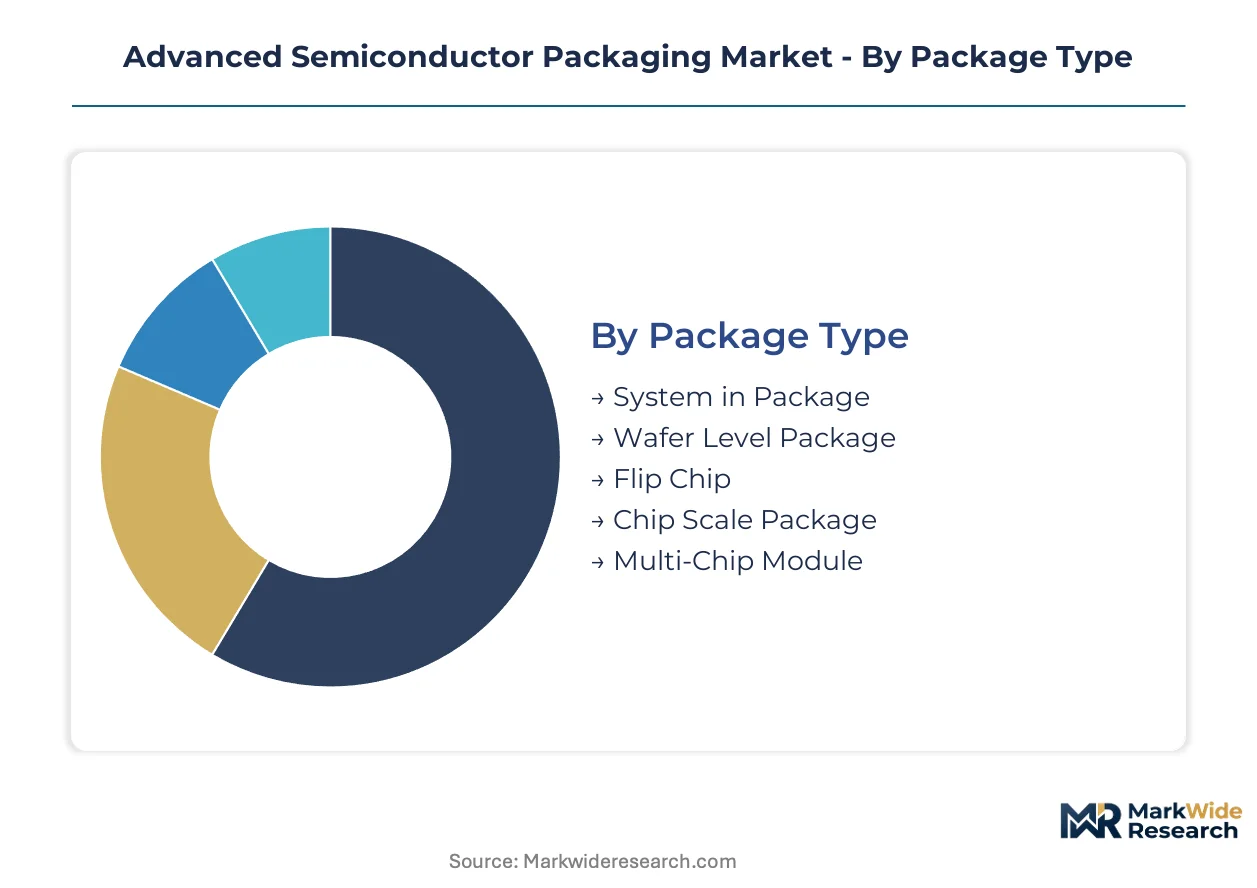
Advanced semiconductor packaging segmentation reveals how capital allocation, technical complexity, and customer concentration create divergent margin structures across the value chain. Package type and technology choices determine which players capture premium returns versus commodity exposure.
Package Type:
Capital intensity escalates sharply from wirebond legacy formats toward interposer-based 2.5D solutions, with equipment depreciation and cleanroom requirements defining competitive moats.
- System in Package:Heterogeneous integration of logic, memory, and passive components within a single molded body achieves footprint reductions exceeding 40% versus discrete mounting. Smartphone OEMs in Taiwan and South Korea drive volume absorption, though substrate supply constraints from Japan limit expansion timelines.
- Wafer Level Package:Redistribution layers formed directly on intact wafers before singulation enable line widths below 2 micrometers for high-I/O mobile processors. Foundry captive capacity in Taiwan dominates supply, while OSATs in Malaysia and Vietnam compete on cost for legacy sensor applications.
- Flip Chip:Controlled collapse chip connection with copper pillar bumps remains the workhorse for mainstream compute and networking silicon.
- Chip Scale Package:Package area within 1.2x of die size targets cost-sensitive consumer and automotive microcontroller segments.
- Multi-Chip Module:Ceramic and organic laminate substrates integrate multiple bare die for aerospace and defense applications requiring radiation tolerance.
System in Package absorbs the bulk of installed capacity; Wafer Level Package is expanding most quickly.
Technology:
Process maturity separates technologies already qualified at scale from those requiring years of yield engineering before commercial viability.
- Through Silicon Via:Vertical interconnects etched through full wafer thickness with aspect ratios exceeding 10:1 enable HBM stack integration at pitches below 40 micrometers. Memory foundries in South Korea anchor supply, though substrate-to-wafer bonding yield losses constrain effective output during demand surges.
- 3D IC:Die-to-wafer and wafer-to-wafer stacking with hybrid bonding achieves pitch scaling below 10 micrometers for logic-on-logic configurations. High-performance computing customers in the United States and China absorb pilot volumes, with thermocompression equipment bottlenecks limiting 2024-2025 ramp slopes.
- Fan Out:Reconstituted wafer and emerging panel-level formats displace flip chip in mid-range mobile and automotive radar modules.
- Embedded Die:Active components laminated within multilayer PCBs serves power management and RF front-end integration.
- Micro Bump:Solder-based interconnects at 40-50 micrometer pitch bridge the gap between conventional flip chip and copper-to-copper hybrid bonding.
Through Silicon Via commands the steepest expansion trajectory as AI training clusters multiply; Fan Out scales fastest in unit terms as panel-level processing matures.
Application:
End-use requirements for thermal cycling reliability, electromagnetic shielding, and signal integrity dictate substrate material selection and encapsulation chemistry.
- Consumer Electronics:Wearables and smartphones prioritize thickness reduction below 0.4mm and electromagnetic interference shielding integration. Assembly houses in Vietnam and India capture migration from Chinese OSATs as tariff and logistics risks reshape sourcing decisions.
- Telecommunications Equipment:Baseband processors and optical transceivers demand organic substrate formats with low-loss dielectric materials for 112Gbps signaling. North American and European network equipment vendors qualify second-source OSATs in Mexico and Portugal to dilute Taiwan concentration.
- Aerospace Systems:Hermetic ceramic packaging and known-good-die screening protocols address radiation hardness requirements.
- Industrial Automation:Wide-temperature-range molding compounds and enhanced solder joint reliability target factory floor operating conditions.
- Military Defense:Trusted foundry and packaging accreditation limits qualified supplier pools to domestic sources in the United States and select NATO allies.
Consumer Electronics absorbs the bulk of installed capacity; Telecommunications Equipment is expanding most quickly.
End User Industry:
Business model distinctions between captive integration and merchant outsourcing determine pricing power and capacity allocation priorities.
- Fabless Companies:NVIDIA, AMD, and Qualcomm rely on foundry-proprietary CoWoS and InFO platforms, creating direct capacity negotiations with TSMC rather than OSAT intermediaries. Design-service partnerships with packaging houses in Taiwan and the United States accelerate time-to-market for complex multi-die products.
- Foundries:TSMC, Samsung, and Intel integrate advanced packaging as a service extension, capturing margin that OSATs cannot access at the bleeding edge. Arizona and Japan greenfield sites qualify initial volumes for geographic risk mitigation.
- OSAT Providers:ASE, Amkor, and JCET compete on cost and geographic diversification for mainstream flip chip and wirebond volumes.
- IDM Manufacturers:Integrated device maintainers with captive packaging lines optimize for automotive and industrial reliability requirements.
- Electronic Manufacturing Services:Foxconn and Jabil perform final module assembly and test, sourcing packaged die from upstream suppliers.
Fabless Companies absorb the bulk of installed capacity; Foundries are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Taipei anchors the world's densest concentration of high-end interposer and fan-out capacity, with TSMC and ASE operating facilities that supply NVIDIA and AMD AI accelerators. Foundry-proprietary CoWoS and InFO platforms dominate bleeding-edge output from this cluster. Subsidy frameworks in Asia, Europe, and North America are redirecting capital toward domestic packaging ecosystems.
Taiwan
AI accelerator cards from NVIDIA and AMD absorb advanced packaging capacity at unprecedented rates from TSMC's CoWoS lines. The National Development Council's semiconductor initiatives channel public funds toward substrate and interposer fabrication autonomy. Hsinchu Science Park hosts the densest cluster of 2.5D/3D packaging infrastructure globally.
United States
Hyperscalers Microsoft, Amazon, and Google negotiate packaging capacity directly with foundries, bypassing traditional fabless vendor channels. The CHIPS and Science Act attaches domestic content thresholds to subsidy eligibility for new packaging facilities. Arizona greenfield sites capture initial qualification volumes for geographic risk mitigation.
South Korea
Memory foundries anchor supply for HBM3E stack integration requiring through-silicon via pitches below 35 micrometers. METI semiconductor subsidies in neighboring Japan create competitive pressure for Korean packaging investment decisions. Samsung Electronics leverages captive memory and logic positions to integrate advanced packaging from wafer to module.
Japan
Specialized silica fillers and resin systems for epoxy molding compounds concentrate among Japan-centric suppliers, creating feedstock volatility risks. METI subsidy frameworks reshape where new packaging capacity receives public capital with domestic content requirements. Kyushu and Tohoku regions host material supplier clusters serving global OSAT networks.
China
GB standards and dual carbon goals impose energy-efficiency benchmarks on fabs and OSATs operating within Chinese borders. Domestic packaging ecosystems receive state-directed capital toward substrate and interposer fabrication import substitution. Yangtze River Delta clusters compete for mid-range mobile system-in-package volumes.
Advanced Semiconductor Packaging Market Vendor Landscape
Premium-margin players sit above commodity-margin players across technology complexity, with interposer-based 2.5D solutions commanding depreciation and cleanroom requirements that commodity leadframe formats cannot match. The vendor base organizes into captive foundry integrators, merchant OSATs, and IDM-maintained packaging lines. Three archetypes dominate: foundry-proprietary platform operators, geographic-diversified merchant assemblers, and memory-logic captive integrators. Capacity expansion and strategic partnerships constitute the dominant competitive moves as interposer supply tightens.
Among Taiwan-based operators, Taiwan Semiconductor Manufacturing Company Ltd. and Advanced Semiconductor Engineering, Inc. occupy positions at the premium and merchant tiers respectively. Samsung Electronics Co., Ltd. exemplifies the captive integrator archetype through its combined memory and logic manufacturing positions. Amkor Technology Inc. represents geographic diversification strategies among merchant OSATs serving fabless customers.
| Leading Market Players |
|---|
| Samsung Electronics Co., Ltd. |
| JCET Group Corporation |
| Amkor Technology Inc. |
| NXP Semiconductors NV |
| SK Hynix Inc. |
| Advanced Semiconductor Engineering, Inc. |
| Intel Corporation |
| Micron Technology Inc. |
| Taiwan Semiconductor Manufacturing Company Ltd. |
| Others |
Supply Flow & Price Mechanics
Hyperscaler direct procurement of AI accelerator modules concentrates buyer power among Microsoft, Amazon, and Google, forcing value-based pricing tied to interposer yield throughput rather than per-unit wafer costs.
Pricing Analysis
Yield-guaranteed throughput contracts anchor pricing for CoWoS and InFO platforms, with TSMC and ASE capturing premiums tied to bandwidth density outcomes rather than input silicon area. Price differentiation separates qualified automotive-grade modules from consumer mobile formats through AEC-Q100 certification tiers and thermal cycling reliability guarantees. Cost compression in mid-range fan-out segments is intensifying as panel-level processing matures and Vietnamese OSATs absorb legacy smartphone volumes. Fabless AI chip vendors exhibit the sharpest price sensitivity, while captive foundry integrators at Samsung and Intel maintain internal transfer pricing insulation.
Supply Chain Analysis
Silica filler and specialized resin formulations for epoxy molding compounds rest on Japan-centric suppliers including Shin-Etsu and Sumitomo Bakelite, creating feedstock vulnerability. Raw material dependencies span photoresist from JSR and Tokyo Ohka Kogyo, bismaleimide-triazine laminates from Mitsubishi Gas Chemical, and silicon interposer wafers from Shin-Etsu. Single-source vulnerability concentrates in 65nm-class lithography capacity for interposer fabrication, where memory foundries and logic nodes compete for allocation. Distribution runs through direct foundry channels for premium 2.5D/3D formats, while merchant OSATs serve mid-tier flip-chip and wirebond demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Interposer wafer bottlenecks constrain effective CoWoS output below AI accelerator demand curves, propping pricing power for qualified suppliers through at least the near-term capacity expansion cycle.
For Market Incumbents: Cement captive interposer supply through backward integration into substrate fabrication or long-term offtake agreements with silicon wafer suppliers. Defend yield premiums by restricting process parameter disclosure to fabless customers, preserving information asymmetry that complicates second-source qualification. Prioritize thermocompression bonding equipment acquisition ahead of hybrid bonding ramp slopes. For New Entrants and Emerging Players: Begin with automotive zonal architecture modules in Gujarat and Tamil Nadu, where PLI scheme incentives offset capital intensity for greenfield fan-out capacity. Target heterogeneous integration formats for sensor fusion and domain controllers that legacy wirebond cannot satisfy. Pursue design-service partnerships with European automotive OEMs seeking REACH-compliant substrate formulations. For Investors and Strategic Acquirers: The window for entry favors mid-tier OSATs with embedded carbon accounting systems and EU automotive module qualifications. Long-term viability hinges on geographic diversification beyond Taiwan concentration and panel-level processing readiness. Watch for ECHA candidate list expansions threatening brominated flame retardants as the inflection signal for substrate laminate reformulation cycles.| Strategic Initiative | Industry Significance |
|---|---|
| CoWoS Capacity Expansion | TSMC and ASE additions in Arizona and Japan dilute Taiwan geographic risk for NVIDIA and AMD supply. |
| Glass Core Substrate Piloting | Corning and Japanese suppliers advance interposers eliminating CTE mismatch with organic alternatives. |
| Hybrid Bonding Equipment Retooling | Plasma activation and room-temperature bonding platforms displace microbump interconnects below 10 micrometer pitch. |
| Carbon Accounting System Implementation | Mid-tier OSATs face procurement disqualification from EU automotive OEMs without Scope 3 documentation. |
| India OSAT Greenfield Development | PLI scheme incentives attract ASE and Amkor packaging investment to Gujarat for export-market fan-out capacity. |
Methodological Framework
Multi-period observation of hyperscaler capex disclosures, foundry capacity utilization rates, and interposer wafer pricing anchored the trend analysis, supplemented by interviews with packaging process engineers, OSAT procurement directors, fabless semiconductor supply chain managers, and automotive module qualification leads. Secondary validation drew from SEC 10-K filings, ECHA substance restriction updates, METI and EU Chips Act subsidy documentation, and customs trade data for epoxy molding compound feedstocks. Bottom-up unit demand modeling and top-down value chain margin analysis were triangulated against capacity expansion announcements.
Input-output matrices mapped die-to-wafer bonding yield curves, lithography capacity allocation conflicts, and panel-level processing cost trajectories across the analysis window. Segmentation dimensions included package type, technology maturity, application thermal requirements, and end-user industry business model. CAGRs were derived from supply-constrained demand absorption curves and public capital deployment timelines. Forecast inputs incorporated AI training cluster buildout schedules and automotive zonal architecture transition roadmaps.
Interposer supply shocks, ECHA regulatory acceleration, and geopolitical export restriction expansion are the dominant revision risks to modeled outputs. Forecasts reflect assumptions about yield engineering timelines and subsidy disbursement pacing. A small set of triggers—silica filler supply disruptions, hybrid bonding equipment delivery delays, and EU domestic content threshold adjustments—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Packaging
Bonding Wire Packaging Market
Semiconductor Packaging
2.5D IC Packaging Market
Semiconductor Packaging
Epoxy Potting Market
Semiconductor Packaging
System in Package (Sip) Technology Market
Semiconductor Packaging
IC Packaging and Testing Market
Semiconductor Packaging
Semiconductor and IC Packaging Materials Market
Semiconductor Packaging
Asia-Pacific Quad-Flat-No-Lead Packaging Market
Semiconductor Packaging
Electronic Board Level Underfill and Encapsulation Material Market
Semiconductor Packaging
Antenna-In-Package Technology Market
Semiconductor Packaging
System in Package (SIP) Die Market
Semiconductor Packaging
Outsourced Semiconductor Assembly and Testing Market
Semiconductor Packaging
Memory Packaging Market
Semiconductor Packaging
3D IC and 2.5D IC Packaging Market
Semiconductor Packaging
Global MEMS Packaging Market
Semiconductor Packaging
Wafer Level Packaging (WPL) Market
Semiconductor Packaging
Microtube Box Market