
 Global Interposer and Fan-Out WLP Market | 2026-2036
Global Interposer and Fan-Out WLP Market Size, Share, and Industry Trends Forecast 2026-2036
Global Interposer and Fan-Out WLP Market Outlook
Buyer concentration among hyperscale cloud operators and AI accelerator designers is pivoting procurement toward custom interposer designs with dedicated capacity agreements. Taiwan Semiconductor Manufacturing Company leverages captive CoWoS capacity to dominate advanced interposer supply for NVIDIA and AMD AI chips. Samsung Electronics anchors its fan-out panel-level packaging roadmap to compete for mobile AP and automotive radar module share. ASE Technology Holding sustains broadest end-user diversification across wire bonding and flip chip backends.
Interposer and fan-out wafer-level packaging refers to redistribution-layer-based interconnect schemes that enable fine-pitch die-to-die communication on silicon or organic substrates, typically employing through-silicon vias at sub-10-micron pitch or molded reconstituted wafer approaches to achieve high I/O density in compact footprints. The primary purpose is to replace traditional wire bonding and organic substrates in high-bandwidth, low-power applications where signal integrity and form factor constraints dominate. Fan-out variants lead volume shipment growth due to smartphone system-in-package adoption and automotive radar module miniaturization, while interposer architectures command premium positioning in AI training clusters where HBM-to-GPU bandwidth requirements strain conventional substrates. Embedded wafer-level packaging occupies a developing niche in wearable biomedical sensors where hermeticity and thickness constraints converge.
ISO 9001 quality management and IEC semiconductor packaging standards govern substrate reliability testing across jurisdictions, while REACH chemical restrictions in Europe and EPA hazardous substance rules in the United States constrain molding compound and underfill material selection. Japan's METI circular economy directives for electronics are pressuring packagers to document material recovery pathways for reconstituted wafers and temporary bonding adhesives. Stakeholders must monitor sovereign packaging subsidy qualification criteria as these determine where captive versus merchant capacity investments flow.
Market Dynamics
Captive capacity agreements between hyperscale cloud operators and advanced packaging foundries are compressing merchant substrate availability and redrawing procurement hierarchies across high-performance computing supply chains.
Growth Catalysts
- EU Chips Act subsidies:Sovereign silicon initiatives in Europe are redirecting capital expenditure toward localized fan-out panel-level packaging lines, reducing import dependency for automotive radar substrates.
- AI accelerator bandwidth requirements:HBM-to-GPU interconnect demands are straining conventional organic substrates and pulling volume toward silicon interposer architectures with sub-10-micron through-silicon via pitch.
- Smartphone system-in-package adoption:Mobile AP miniaturization in East Asian manufacturing clusters is accelerating molded reconstituted wafer approaches for antenna-in-package modules.
Market Restraints
- Silicon wafer supply concentration:Polished wafer and epitaxial substrate production clusters in Taiwan and South Korea create single-point vulnerability for interposer blank sourcing.
- REACH chemical restrictions:European ECHA constraints on molding compound constituents and underfill material selection are narrowing qualified supplier pools and extending qualification timelines.
- Die-to-wafer bonding yield limits:Thermal compression and laser-assisted bonding processes for fine-pitch interposers face throughput ceilings that inflate unit economics at current technology nodes.
Strategic Opportunities
- India PLI scheme for semiconductors:Production-linked incentive structures are attracting OSAT investment for fan-out wafer-level packaging serving domestic mobile and automotive electronics demand.
- Biomedical wearable hermeticity requirements:Embedded wafer-level packaging for continuous glucose monitors and neural interfaces opens thickness-constrained applications outside traditional computing verticals.
- Japan METI circular economy directives:Electronics material recovery mandates are creating first-mover advantage for packagers documenting reconstituted wafer and temporary bonding adhesive recycling pathways.
Industry Challenges
- Process integration engineer scarcity:Deep expertise in hybrid bonding, chemical-mechanical planarization, and temporary debonding processes concentrates at a handful of captive facilities.
- ISO/IEC qualification timeline compression:Accelerated product ramps for AI accelerators are colliding with extended substrate reliability testing protocols under joint ISO 9001 and IEC semiconductor packaging standards.
- CoWoS-equivalent process IP complexity:Patent thickets around silicon interposer architectures and die-stacking methodologies are fragmenting technology licensing and raising royalty burdens for merchant competitors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Interposer and Fan-Out WLP Market |
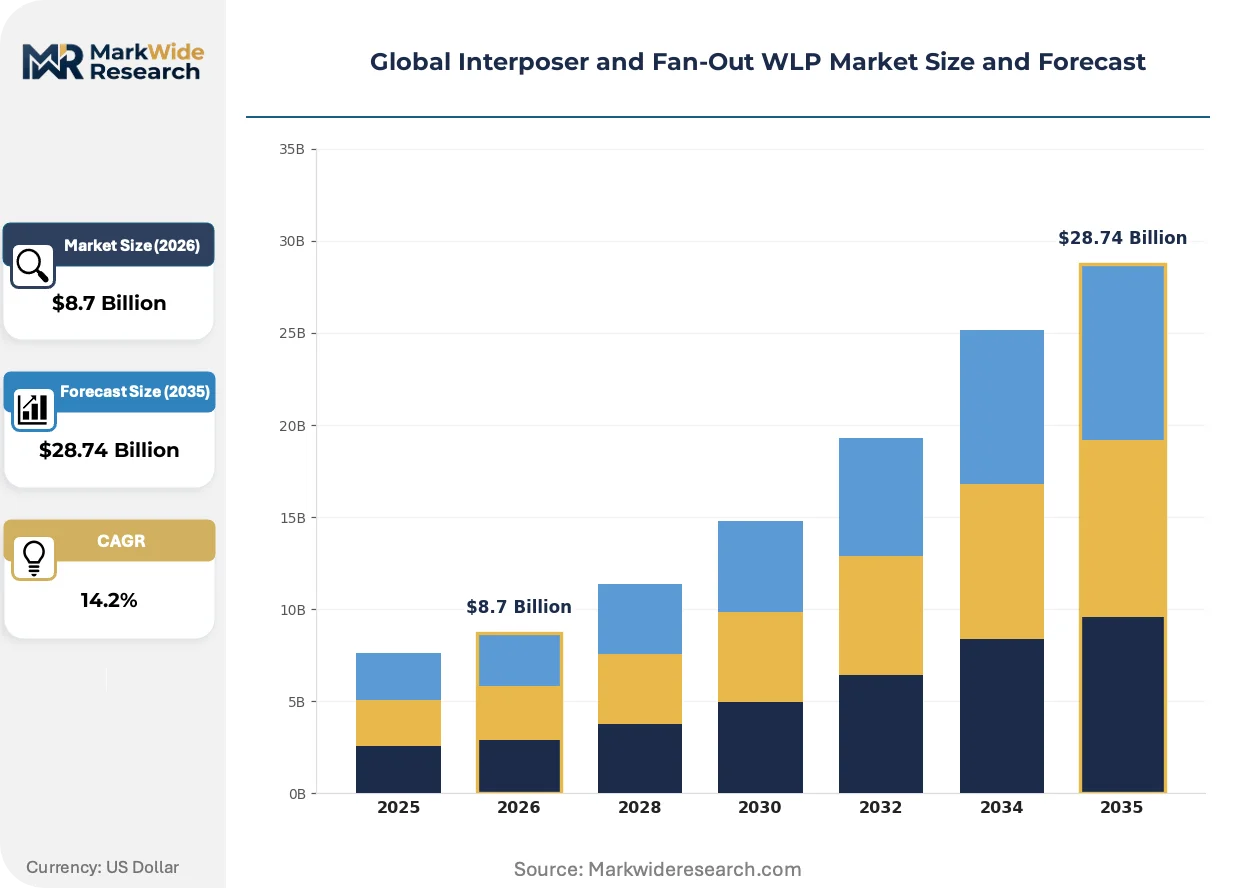
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Interposer, Fan-Out, Embedded Wafer Level, Standard Wafer Level End User: Semiconductor, Consumer Electronics, Automotive, Telecommunications Technology: Flip Chip, Wire Bonding, Tape-Automated Bonding, Die Attach Application: High-Performance Computing, Mobile Devices, Internet of Things, Wearable Devices |
| Companies Covered | Taiwan Semiconductor Manufacturing Company, ASE Technology Holding, Amkor Technology, Samsung Electronics, Toshiba Corporation, SK Hynix, Intel Corporation, United Microelectronics Corporation, JCET Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Interposer and Fan-Out WLP Market Strategic Shifts
Advanced packaging roadmaps are converging on panel-level fan-out formats and hybrid bonding interfaces that compress interconnect pitch while expanding substrate area economics beyond 300mm wafer constraints.
Hybrid bonding is unifying copper-to-copper and oxide-to-oxide interfaces at sub-5-micron pitch, eliminating underfill and solder microbump layers entirely. Memory manufacturers and logic foundries are piloting this for next-generation HBM stacks and 3D system-on-chip integration. The structural consequence is unifying previously separate front-end and back-end process flows into single manufacturing sequences.
REACH chemical restrictions are tightening scrutiny on epoxy molding compound formulations and temporary bonding adhesive chemistries used in reconstituted wafer processing. European packagers are reformulating material sets to maintain market access, with automotive radar module suppliers facing the steepest compliance cost gradients. Germany and France are seeing accelerated substitution toward halogen-free and bisphenol-A-free compound alternatives.
Hyperscale operators are consolidating advanced packaging procurement through dedicated capacity reservations rather than spot-market substrate purchasing. This channel compression is displacing traditional merchant OSAT relationships for AI training and inference chip supply. Taiwan and South Korea manufacturing clusters exhibit the most pronounced buyer concentration effects.
Global Interposer and Fan-Out WLP Market Segmentation
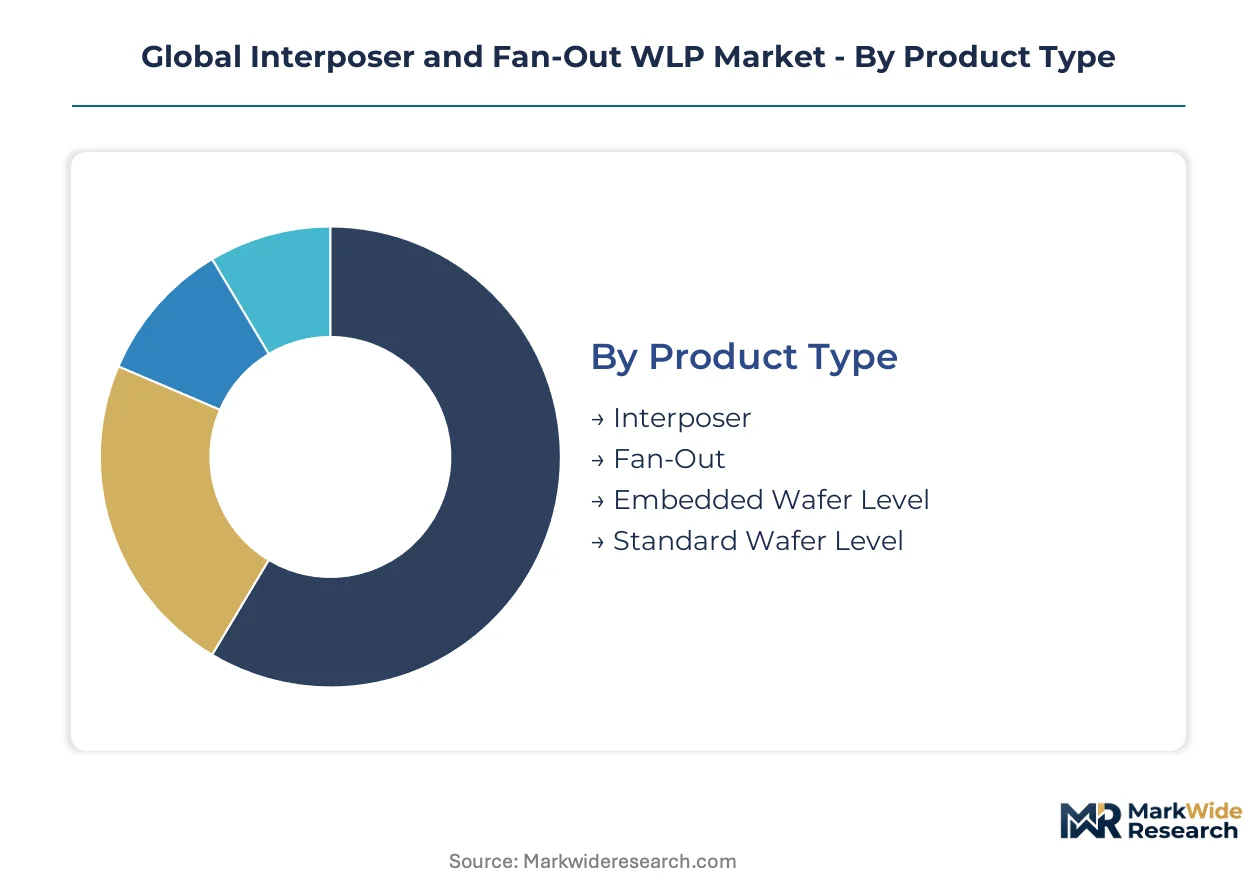
Interposer and fan-out wafer-level packaging technologies serve divergent certification and performance requirements across computing, mobility, and automotive verticals. Segment boundaries reflect substrate complexity tiers, bonding methodology constraints, and end-use reliability standards rather than simple form-factor distinctions.
Product Type:
ISO 9001 quality management and IEC semiconductor packaging standards impose tiered testing protocols, with silicon interposers facing the most stringent reliability documentation and embedded wafer-level variants navigating biomedical-specific hermeticity certifications.
- Interposer:Silicon or organic substrates with through-silicon vias at sub-10-micron pitch enabling HBM-to-GPU bandwidth aggregation. Taiwan Semiconductor Manufacturing Company captive CoWoS capacity dominates supply for NVIDIA and AMD AI accelerators, though die-to-wafer bonding yield limits constrain merchant competitor entry.
- Fan-Out:Molded reconstituted wafer approaches redistributing I/O across expanded footprints without substrate size constraints. Smartphone system-in-package adoption in East Asian manufacturing clusters and automotive radar module miniaturization drive volume shipment leadership.
- Embedded Wafer Level:Wafer-level processing integrating passive components and interconnect within molded compound. Japan METI circular economy directives pressure material recovery pathway documentation for temporary bonding adhesives.
- Standard Wafer Level:Conventional redistribution layer builds on unmodified wafer substrates. REACH chemical restrictions on epoxy molding compound formulations narrow qualified supplier pools for European market access.
Fan-Out sits at the top of the volume ranking, with Embedded Wafer Level climbing the fastest.
End User:
Cost tier stratification separates captive foundry arrangements from merchant OSAT relationships, with hyperscale cloud operators compressing procurement hierarchies through dedicated capacity reservations.
- Semiconductor:Logic foundries and memory manufacturers deploying advanced packaging for internal product roadmaps. AI accelerator bandwidth requirements pull substrate selection toward silicon interposer architectures with hybrid bonding interfaces at sub-5-micron pitch.
- Consumer Electronics:Smartphone original equipment manufacturers specifying antenna-in-package and mobile AP miniaturization. EU Chips Act subsidies redirecting capex toward localized fan-out panel-level packaging lines reduce import dependency for European device assembly.
- Automotive:Radar module suppliers and power electronics packagers facing AEC-Q100 reliability grades plus ECHA REACH constraints on halogen-free molding compounds. Germany and France exhibit accelerated substitution toward bisphenol-A-free compound alternatives.
- Telecommunications:Baseband processor and RF front-end module integration for 5G infrastructure. Base station equipment margins favor fan-out over interposer cost structures at current technology nodes.
Semiconductor end-use commands the highest absolute spending, with Automotive expanding most quickly.
Technology:
Application requirements dictate bonding methodology selection, with thermal and electrical performance specifications filtering available process flows.
- Flip Chip:Solder microbump or copper pillar interconnect with active face-down die orientation. High-performance computing substrates in Taiwan and South Korea manufacturing clusters anchor capacity expansion for this methodology.
- Wire Bonding:Thermosonic gold or copper ball-and-stitch interconnects on face-up die configurations. ASE Technology Holding sustains broadest end-user diversification across legacy and advanced backend applications.
- Tape-Automated Bonding:Gang bonding of inner lead patterns to bumped die for display driver and memory card applications. Samsung Electronics anchors fan-out panel-level packaging roadmap competition partly through TAB-to-fan-out process transitions.
- Die Attach:Adhesive and eutectic attach processes for thermal and electrical interface formation. EPA hazardous substance rules in the United States constrain conductive adhesive material selection for defense and aerospace-qualified supply chains.
Flip Chip dominates the technology mix, with Die Attach gaining share fastest in biomedical wearable applications.
Application:
Customer type concentration varies sharply, with hyperscale operators consolidating procurement for AI training clusters while mobile device manufacturers fragment demand across multiple OSAT sources.
- High-Performance Computing:AI training and inference chip packaging with HBM integration and silicon interposer mediation. Captive capacity agreements between hyperscale cloud operators and advanced packaging foundries compress merchant substrate availability.
- Mobile Devices:Smartphone system-in-package and antenna-in-module integration. India PLI scheme for semiconductors attracts OSAT investment serving domestic mobile electronics demand with fan-out wafer-level packaging capacity.
- Internet of Things:Sensor hub and connectivity module miniaturization for industrial and smart home endpoints. Cost structures favor standard wafer-level and early fan-out generations over interposer architectures.
- Wearable Devices:Continuous glucose monitors and neural interfaces requiring hermeticity and thickness constraints. Embedded wafer-level packaging occupies this developing niche outside traditional computing verticals.
High-Performance Computing leads absolute value contribution, with Wearable Devices showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Taiwan commands captive CoWoS capacity for AI accelerator substrates while South Korea anchors HBM-to-logic integration, yet both face mounting pressure from sovereign packaging initiatives redirecting capital toward localized production lines.
United States
Hyperscale cloud operators consolidate procurement through dedicated capacity reservations for AI training clusters. EPA hazardous substance rules constrain conductive adhesive selection for defense-qualified supply chains. Arizona and Texas manufacturing corridors attract advanced packaging investments serving domestic high-performance computing demand.
Taiwan
Semiconductor fabs anchor global capacity expansion for silicon interposer substrates with sub-10-micron through-silicon via pitch. METI circular economy directives from Japan pressure cross-strait material recovery documentation for temporary bonding adhesives. Hsinchu Science Park concentrates die-to-wafer bonding expertise for NVIDIA and AMD AI chip supply.
South Korea
Memory manufacturers pilot hybrid bonding interfaces at sub-5-micron pitch for next-generation HBM stacks. MFDS regulatory alignment with REACH chemical restrictions narrows qualified molding compound supplier pools. Seoul Capital Area and Busan-Ulsan corridors integrate logic foundry and advanced packaging capacity for mobile AP miniaturization.
Germany
Automotive radar module suppliers face AEC-Q100 reliability grades plus ECHA constraints on halogen-free molding compounds. KBA vehicle-type approval processes extend qualification timelines for fan-out panel-level packaging in power electronics. Bavaria and Baden-Württemberg clusters accelerate substitution toward bisphenol-A-free compound alternatives.
India
Production-linked incentive structures attract OSAT investment for fan-out wafer-level packaging serving domestic mobile electronics demand. BIS quality management standards govern substrate reliability testing for telecommunications infrastructure. Gujarat and Karnataka manufacturing zones concentrate emerging capacity for antenna-in-package modules.
Global Interposer and Fan-Out WLP Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across captive foundry and merchant OSAT segments. The vendor base stratifies into three tiers: integrated device manufacturers with captive packaging lines, dedicated advanced packaging foundries, and diversified assembly-and-test houses serving fragmented end-user demand. Two dominant competitive moves reshape positioning: sovereign subsidy qualification drives geographic capacity relocation, and hybrid bonding technology licensing fragments patent-controlled process flows.
Within the captive foundry tier, Taiwan Semiconductor Manufacturing Company exemplifies vertical integration into AI accelerator substrate supply. Among merchant OSAT specialists, ASE Technology Holding and Amkor Technology occupy positions spanning wire bonding through advanced fan-out implementations. Samsung Electronics anchors a diversified electronics conglomerate archetype competing across memory, logic, and packaging domains.
| Leading Market Players |
|---|
| Taiwan Semiconductor Manufacturing Company |
| ASE Technology Holding |
| Amkor Technology |
| Samsung Electronics |
| Toshiba Corporation |
| SK Hynix |
| Intel Corporation |
| United Microelectronics Corporation |
| JCET Group |
| Others |
Value Chain & Pricing Dynamics
Epoxy molding compound formulations flow from Japanese and German chemical suppliers through three distinct pricing tiers downstream, with REACH-compliant halogen-free variants commanding substantial premiums over legacy bisphenol-A-containing alternatives in European automotive radar module procurement.
Pricing Analysis
Capacity additions in South Korea and Taiwan are reshaping price floors for silicon interposer substrates, compressing margins for merchant competitors unable to match captive foundry scale economies. Three-tier pricing structure across premium, standard, and economy levels separates CoWoS-equivalent AI accelerator substrates from automotive-qualified fan-out panels and commodity wire-bonded packages. Cost compression in standard-tier fan-out runs through panel-level format adoption, which expands substrate area economics beyond 300mm wafer constraints. Hyperscale cloud operators exhibit lowest price sensitivity due to dedicated capacity reservation structures, while domestic automotive electronics assemblers in India and Southeast Asia face acute cost pressure from import dependency.
Supply Chain Analysis
Single-source vulnerability sits with polished wafer and epitaxial substrate production clusters in Taiwan and South Korea, where interposer blank sourcing concentrates for sub-10-micron through-silicon via architectures. Raw material dependencies draw from high-purity silicon feedstock, specialty epoxy molding compounds, and temporary bonding adhesives with documented recovery pathways. Supply chain risk centers on die-to-wafer bonding yield limits that constrain throughput ceilings at current technology nodes. Distribution runs through direct foundry relationships for AI accelerator substrates and fragmented merchant OSAT channels for mobile and automotive applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story justified by hyperscale operator procurement consolidation toward custom interposer designs with dedicated capacity agreements and hybrid bonding interfaces at sub-5-micron pitch.
For Market Incumbents: Anchor defensive positioning through backward integration into temporary bonding adhesive and molding compound formulation supply, securing qualified material pools ahead of REACH restriction tightening. Deepen captive capacity reservation structures with hyperscale cloud operators to displace merchant substrate availability. Prioritize hybrid bonding IP licensing revenue streams as patent thickets fragment technology access for competitors. For New Entrants and Emerging Players: Begin with biomedical wearable applications where embedded wafer-level packaging hermeticity requirements create protected demand outside computing verticals dominated by incumbent foundries. Target India PLI scheme qualification for fan-out wafer-level packaging capacity serving domestic mobile electronics demand, where sovereign subsidy structures offset scale disadvantages. Pursue automotive radar module miniaturization as the most penetrable volume segment given EU Chips Act localization mandates. For Investors and Strategic Acquirers: Consolidation pressure builds where process integration engineer scarcity concentrates hybrid bonding expertise at a handful of captive facilities, creating acquisition premiums for specialist talent pools. Long-term viability favors vertically integrated packaging foundries with demonstrated sovereign subsidy qualification across multiple jurisdictions. Watch hybrid bonding pilot-to-production yield trajectories at memory manufacturers as the inflection signal for next-generation HBM stack technology transitions.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Bonding Technology Licensing | Patent-controlled process flows generate royalty revenue streams as sub-5-micron pitch interfaces unify front-end and back-end manufacturing sequences. |
| Panel-Level Fan-Out Capacity Buildout | Substrate area economics expansion beyond 300mm wafer constraints reduces unit costs for smartphone antenna-in-package modules. |
| Sovereign Subsidy Qualification | EU Chips Act and India PLI scheme eligibility determines geographic flow of captive versus merchant packaging investments. |
| REACH-Compliant Material Reformulation | Halogen-free and bisphenol-A-free compound alternatives maintain European market access for automotive radar substrate suppliers. |
| Circular Economy Documentation | Japan METI material recovery pathway compliance creates first-mover positioning for reconstituted wafer and adhesive recycling capabilities. |
Study Parameters
Direct dialogue with advanced packaging process engineers, substrate procurement managers at hyperscale cloud operators, automotive radar module suppliers, and semiconductor fab planning officers grounded qualitative findings in operational reality. Secondary validation drew from SEC 10-K filings, EU Chips Act subsidy disclosure documents, ECHA REACH restriction updates, and Japan METI circular economy directive implementation guidance. Bottom-up capacity buildout tracking across Taiwan, South Korea, and emerging India manufacturing zones triangulated against top-down AI accelerator shipment forecasts.
Segment-level value outputs across the projection horizon reflect discrete modeling of interposer, fan-out, embedded wafer-level, and standard wafer-level product categories by end-use vertical, bonding technology, and application requirements. CAGRs were derived from installed capacity expansion schedules, die-to-wafer bonding yield improvement trajectories, and sovereign subsidy disbursement timelines. Forecast inputs incorporated HBM-to-GPU bandwidth requirement scaling, smartphone system-in-package adoption curves, and automotive radar module miniaturization roadmaps.
Several conditions sit outside the modeled scope, including unannounced hybrid bonding technology breakthroughs, abrupt REACH chemical restriction scope expansions, and geopolitical disruptions to Taiwan Strait manufacturing operations. Forecasts reflect documented assumptions regarding sovereign subsidy continuation and foundry yield improvement rates. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Packaging
Ball Grid Array (BGA) Packaging Market
Semiconductor Packaging
Electronic Board Level Underfill and Encapsulation Material Market
Semiconductor Packaging
IC Packaging and Testing Market
Semiconductor Packaging
Multichip Package Market
Semiconductor Packaging
Through-Silicon via (TSV) IC Packaging Market
Semiconductor Packaging
Through Silicon via (TSV) Packaging Market
Semiconductor Packaging
Antenna-In-Package Technology Market
Semiconductor Packaging
NOR-Based Multi-Chip Packages Market
Semiconductor Packaging
Global MEMS Packaging Market
Semiconductor Packaging
3D IC Packaging Market
Semiconductor Packaging
Semiconductor Wafer Tape Market
Semiconductor Packaging
Global Semiconductor Packaging and Assembly Equipment Market
Semiconductor Packaging
Asia-Pacific Quad-Flat-No-Lead Packaging Market
Semiconductor Packaging
Semiconductor and IC Packaging Materials Market
Semiconductor Packaging
Semiconductor Solder Flux Market
Semiconductor Packaging
Semiconductor Packaging Market