
 Laser Annealing System Market | 2026-2036
Laser Annealing System Market Size, Share, and Industry Trends Forecast 2026-2036
Laser Annealing System Market Foresight
Japan is tilting toward domestic laser annealing capacity as semiconductor self-sufficiency becomes a strategic priority. Tokyo Electron Limited leverages its etch and deposition heritage to extend into thermal processing tools. Applied Materials anchors North American supply through its broad materials engineering portfolio. SCREEN Semiconductor Solutions competes in display and wafer-level annealing with specialized excimer platforms.
A laser annealing system employs high-energy coherent light to induce rapid thermal cycling in thin-film materials without bulk substrate heating, typically operating at wavelengths from 157 nm to 1064 nm with pulse durations spanning nanoseconds to milliseconds. The primary purpose is to activate dopants, crystallize amorphous films, or repair lattice damage in temperature-sensitive device architectures. Excimer laser annealing dominates semiconductor manufacturing for flat-panel display backplanes and advanced logic nodes where uniform grain structure determines carrier mobility. Pulsed laser technology leads in silicon photovoltaic processing where selective emitter formation improves cell efficiency. Fiber laser systems are gaining fastest in metal fabrication for localized hardness tuning without distortion.
EPA emissions rules and EU REACH chemical restrictions shape equipment material choices and process gas handling in laser annealing installations. Japan's METI semiconductor revitalization framework and South Korea's K-Semiconductor Belt incentives direct capital toward domestic laser thermal processing capacity. China's MIIT dual carbon goals and GB energy efficiency standards constrain power consumption profiles for imported and locally built systems. Stakeholders must weigh regional subsidy eligibility against technology transfer requirements when siting new laser annealing deployment.
Market Dynamics
Advanced node semiconductor manufacturing is concentrating laser annealing demand among a handful of leading-edge foundries, compressing procurement timelines and elevating technical specifications for thermal processing uniformity.
Growth Catalysts
- Sub-3nm logic ramp:Taiwan Semiconductor Manufacturing and Samsung Foundry are expanding excimer laser annealing capacity for gate-all-around transistor architectures. Dopant activation requirements at these geometries mandate sub-millisecond thermal cycling.
- EU Green Deal industrial heat mandates:Solar cell manufacturers across Germany, France, and Italy are replacing furnace diffusion with selective emitter laser processing to cut thermal energy consumption per wafer by over sixty percent.
- South Korea K-Semiconductor Belt:Memory producers in Pyeongtaek and Yongin are procuring solid-state laser annealing systems for 3D NAND string stacking, where vertical channel crystallization determines yield.
Market Restraints
- Optics supply concentration:German and Japanese suppliers dominate deep-ultraviolet lens and mirror fabrication, creating single-source vulnerability for 193nm excimer beam delivery systems.
- Technical limitation at high-aspect ratios:Laser annealing suffers from shadowing effects in 3D NAND vertical channels exceeding 200:1 aspect ratios, forcing hybrid thermal approaches.
- Substitution threat from flash lamp annealing:Applied Materials and Veeco offer millisecond-scale arc lamp systems at lower capital cost for mature node applications above 7nm.
Strategic Opportunities
- India PLI scheme for solar:Domestic cell and module manufacturing incentives are attracting laser tool vendors to establish local service infrastructure for selective emitter and passivated contact processing.
- Technology convergence with atomic layer deposition:Integrated laser-ALD cluster tools enable sequential crystallization and dielectric encapsulation for oxide semiconductor backplanes in augmented reality microdisplays.
- Power device silicon carbide annealing:Emerging demand for activating aluminum implants in SiC MOSFETs at temperatures exceeding 1700°C presents a greenfield application beyond silicon processing.
Industry Challenges
- Process engineer scarcity:Laser-materials interaction modeling and beam homogenization design require rare combinations of optical physics and semiconductor device expertise concentrated in Taiwan, Japan, and the Netherlands.
- Qualification timeline compression:Leading foundries demand six-month tool qualification cycles for new annealing platforms, compressing validation of process stability across temperature and pulse-to-pulse energy variation.
- Legacy furnace integration:Hybrid manufacturing lines must synchronize laser thermal budgets with conventional rapid thermal processing sequences, complicating factory automation and wafer tracking systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Laser Annealing System Market |
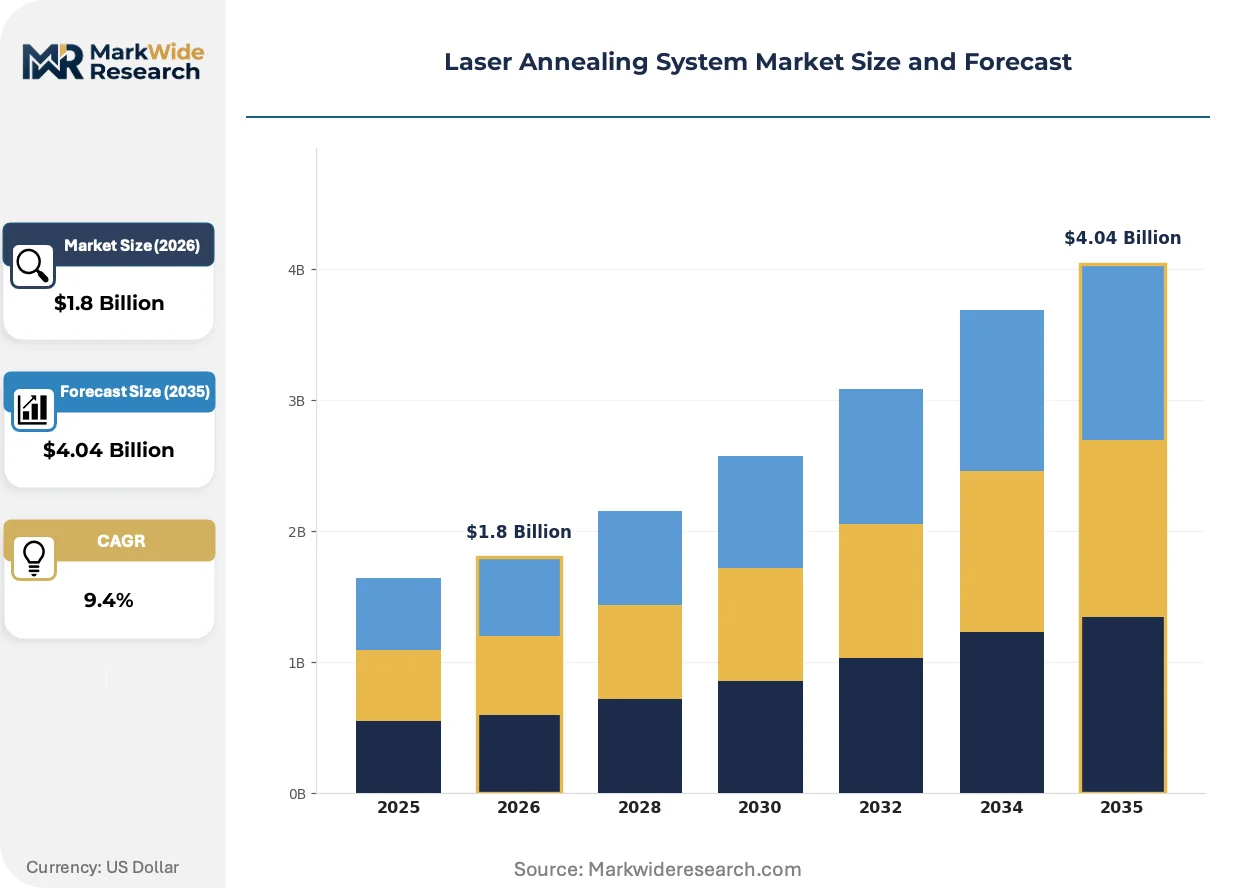
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.04 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Excimer Laser, Solid State Laser, Fiber Laser, Others Technology: Continuous Wave, Pulsed Laser, Hybrid Laser, Others Application: Semiconductor Manufacturing, Solar Cell Production, Metal Fabrication, Glass Processing End User: Electronics Industry, Automotive Sector, Solar Industry, Aerospace Industry |
| Companies Covered | Veeco Instruments Inc., Tokyo Electron Limited, Mitsui Group (JSW), Beijing U-PRECISION Tech, EO Technics, Sumitomo Heavy Industries, Applied Materials, Chengdu Laipu Technology, SCREEN Semiconductor Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Laser Annealing System Market Shifts & Advancements
Beam delivery architectures and process control methodologies are converging to address uniformity requirements at shrinking thermal budgets. Equipment vendors are embedding in-situ metrology to close real-time feedback loops.
Ultrafast fiber laser systems are hybridizing nanosecond and continuous-wave modes within single process recipes. Display manufacturers in South Korea and Japan are adopting these platforms for low-temperature polysilicon crystallization on flexible polymer substrates. The technology is hybridizing process development cycles, allowing foundries to qualify single platforms for multiple thermal budgets rather than maintaining separate excimer and solid-state toolsets.
EPA emissions standards for semiconductor manufacturing are tightening fluorinated greenhouse gas reporting requirements for laser gas mixtures containing krypton and xenon. Equipment suppliers must now certify closed-loop gas recycling systems to maintain operating permits. Display and logic foundries in the United States are absorbing compliance costs through modified service contracts that transfer regulatory liability to tool vendors.
Consolidation among leading-edge semiconductor buyers is compressing vendor negotiation leverage. Taiwan Semiconductor Manufacturing, Samsung, and Intel now account for the majority of new laser annealing procurement, forcing equipment makers into multi-year framework agreements with fixed pricing escalators. Japanese and European vendors are responding by unbundling software upgrades and consumables from base hardware contracts to preserve margin visibility.
Laser Annealing System Market Segmentation
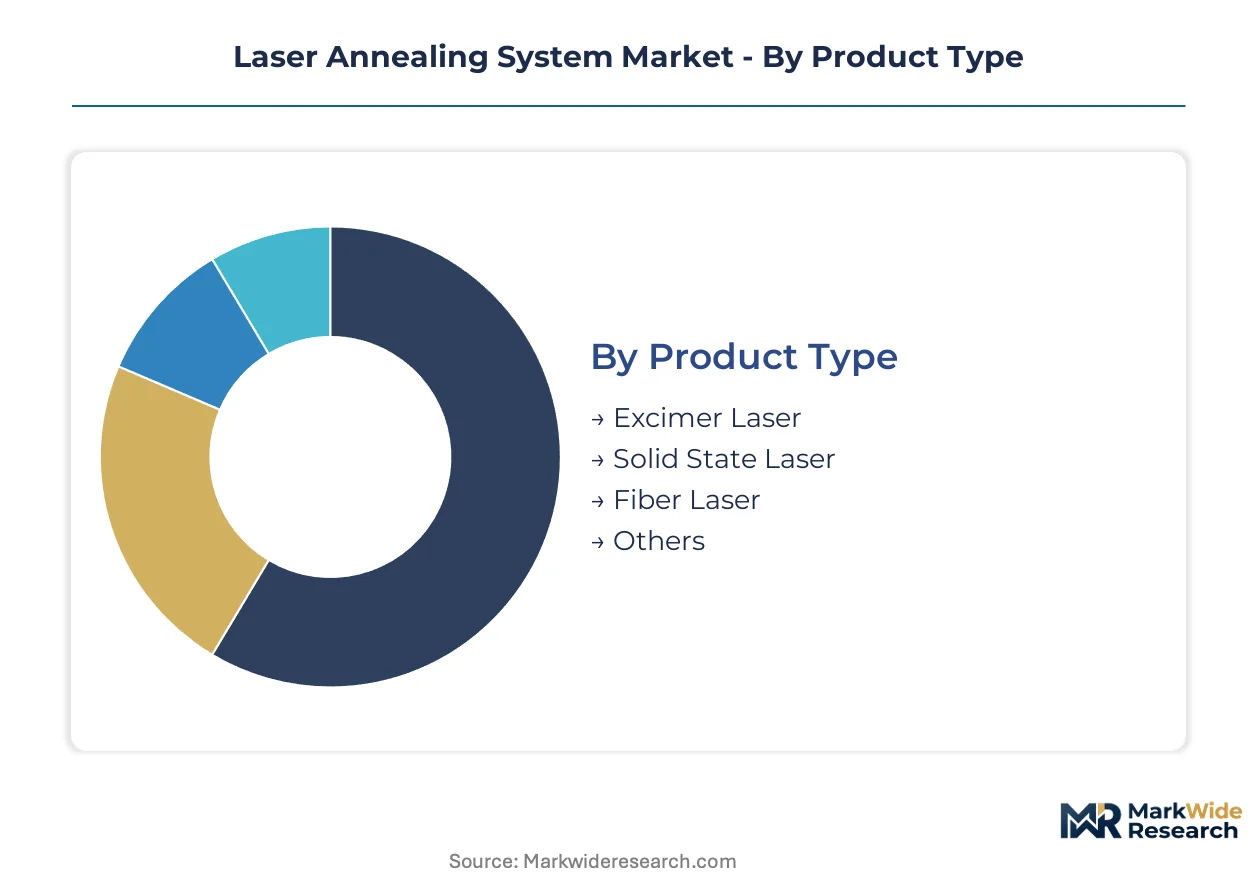
Laser annealing system procurement varies sharply across technology platforms and thermal budgets. Equipment buyers prioritize wavelength precision, pulse control, and substrate compatibility when matching tools to specific material processing requirements.
Product Type:
Mature excimer platforms anchor high-volume manufacturing while fiber configurations emerge fastest in non-semiconductor thermal processing.
- Excimer Laser:Deep-ultraviolet sources operating at 157-351 nm deliver uniform grain crystallization for flat-panel display backplanes and sub-3nm logic nodes. Taiwan Semiconductor Manufacturing and Samsung Foundry dominate procurement for gate-all-around transistor dopant activation where sub-millisecond thermal cycling is mandatory.
- Solid State Laser:Nd:YAG and diode-pumped architectures provide nanosecond pulse trains for 3D NAND vertical channel crystallization in Pyeongtaek and Yongin manufacturing complexes. South Korea's K-Semiconductor Belt incentives accelerate deployment for memory string stacking applications.
- Fiber Laser:Ytterbium-doped fiber systems enable continuous-wave and quasi-continuous modes for localized metal hardness tuning without bulk heating distortion.
- Others:CO2 and direct-diode platforms serve niche polymer and ceramic processing with longer infrared wavelengths.
Excimer systems retain volume leadership; fiber configurations hold the steepest expansion curve.
Technology:
Cost tier stratification separates premium precision platforms from standard thermal processing equipment.
- Pulsed Laser:Nanosecond-to-millisecond energy deposition enables selective emitter formation in silicon photovoltaics, cutting thermal energy consumption per wafer by over sixty percent under EU Green Deal mandates. German and French solar cell manufacturers lead replacement of furnace diffusion with laser-based processing.
- Continuous Wave:Steady-state irradiation provides uniform heating profiles for low-temperature polysilicon crystallization on flexible polymer substrates in South Korean and Japanese display manufacturing.
- Hybrid Laser:Ultrafast platforms combining nanosecond and continuous-wave modes within single process recipes reduce qualification cycles for foundries serving multiple thermal budgets.
- Others:Burst-mode and modulated continuous-wave variants address specialized annealing profiles for compound semiconductors.
Pulsed technology commands the premium tier; hybrid systems are climbing fastest as multi-application platforms.
Application:
Customer type concentration drives specification divergence between leading-edge foundries and industrial processing operations.
- Semiconductor Manufacturing:Advanced logic and memory fabrication demands sub-millisecond thermal budgets for dopant activation and crystallization at nodes below 7nm. Taiwan, South Korea, and the United States concentrate procurement where leading-edge foundries operate at scale.
- Solar Cell Production:Selective emitter and passivated contact processing replaces conventional furnace diffusion, aligning with EPA emissions standards and EU REACH chemical restrictions on process gas handling.
- Metal Fabrication:Localized hardness tuning for automotive and aerospace components without distortion drives fiber laser adoption.
- Glass Processing:Stress relief and surface modification for display cover panels and architectural glazing.
Semiconductor manufacturing retains volume leadership; solar cell production holds the steepest expansion curve.
End User:
Supply concentration in optics and beam delivery components shapes regional procurement patterns across customer segments.
- Electronics Industry:Foundries and IDMs in Taiwan, South Korea, and the United States account for the majority of new laser annealing procurement, compressing vendor negotiation leverage into multi-year framework agreements.
- Solar Industry:Germany, France, and Italy cell manufacturers drive selective emitter adoption under tightening energy efficiency mandates from EU Green Deal industrial heat regulations.
- Automotive Sector:Power device silicon carbide MOSFET processing for electric vehicle inverters creates emerging demand for aluminum implant activation above 1700°C.
- Aerospace Industry:Superalloy and titanium component thermal processing for turbine blade repair and surface enhancement.
Electronics industry retains volume leadership; solar industry holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA emissions standards and the EU Green Deal industrial heat mandates are reshaping laser annealing procurement across leading semiconductor and solar manufacturing economies. Taiwan, South Korea, and the United States concentrate advanced logic and memory fabrication demand, while Germany and Japan drive equipment innovation and domestic capacity expansion.
United States
Intel's Arizona and Oregon fabrication complexes anchor North American demand for sub-7nm dopant activation tools. EPA fluorinated greenhouse gas reporting requirements for krypton and xenon laser gas mixtures now mandate closed-loop recycling certification for operating permits. Display and logic foundries in California's Silicon Valley absorb compliance costs through modified vendor service contracts.
Taiwan
TSMC's Hsinchu and Tainan science parks dominate global excimer laser annealing procurement for gate-all-around transistor architectures. The island's National Development Council semiconductor revitalization framework directs capital subsidies toward thermal processing capacity expansion. Kaohsiung's emerging advanced packaging cluster is integrating laser annealing with hybrid bonding for 3D chip stacking.
South Korea
Samsung Foundry and SK Hynix drive solid-state laser deployment across Pyeongtaek and Yongin memory manufacturing complexes. The K-Semiconductor Belt incentive program accelerates procurement for 3D NAND string stacking where vertical channel crystallization determines yield. Seoul's Gangnam district hosts concentrated process engineering talent for laser-materials interaction modeling.
Germany
Fraunhofer Institute networks and industrial laser specialists in Aachen and Munich anchor European deep-ultraviolet optics supply chains. EU REACH chemical restrictions on process gas handling shape equipment material choices for laser annealing installations. Solar cell manufacturers in Saxony and Thuringia replace furnace diffusion with selective emitter laser processing under Green Deal thermal efficiency mandates.
Japan
Tokyo Electron and SCREEN Semiconductor Solutions leverage etch and deposition heritage to extend into thermal processing tools. METI's semiconductor revitalization framework directs capital toward domestic laser annealing capacity as self-sufficiency becomes strategic priority. Yokohama and Osaka industrial corridors concentrate excimer beam delivery system component fabrication.
Laser Annealing System Market Competitive Landscape
Broad-based materials engineering conglomerates and specialized semiconductor equipment fabricators split the market for laser thermal processing platforms. Vendor negotiation leverage has compressed into multi-year framework agreements as leading-edge foundry procurement concentrates among three dominant buyers. Two strategic archetypes prevail: integrated process equipment portfolios spanning deposition through thermal treatment, and focused annealing specialists with wavelength-specific beam delivery expertise. Competitive dynamics center on technology licensing partnerships and captive optics supply chain development.
Among diversified process equipment conglomerates, Applied Materials and Tokyo Electron Limited exemplify integrated thermal processing strategies. These California- and Tokyo-based entities occupy positions spanning etch, deposition, and annealing modules. Within the specialized tier, SCREEN Semiconductor Solutions represents concentrated expertise in display and wafer-level excimer platforms. Veeco Instruments Inc. anchors North American presence through precision materials engineering heritage. Chinese fabricators including Beijing U-PRECISION Tech and Chengdu Laipu Technology exemplify emerging regional supply capacity.
| Leading Market Players |
|---|
| Veeco Instruments Inc. |
| Tokyo Electron Limited |
| Mitsui Group (JSW) |
| Beijing U-PRECISION Tech |
| EO Technics |
| Sumitomo Heavy Industries |
| Applied Materials |
| Chengdu Laipu Technology |
| SCREEN Semiconductor Solutions |
| Others |
Supply & Pricing Matrix
Single-source dependency on German and Japanese deep-ultraviolet optics suppliers determines both pricing tier spreads and supply chain shape in laser annealing equipment procurement. Equipment vendors absorb margin compression from concentrated lens and mirror fabrication while passing compliance costs through modified service contracts.
Pricing Analysis
Geographic price spreads widen substantially between Taiwan-South Korea procurement clusters and emerging Indian solar manufacturing installations. Three-tier pricing structure across premium excimer platforms, standard solid-state systems, and economy fiber configurations stratifies by thermal budget precision and after-sales service bundling. Pricing pressure stems from flash lamp annealing substitution at mature nodes above 7nm. Solar cell manufacturers in Germany and India exhibit highest price sensitivity; leading-edge foundries in Taiwan prioritize thermal uniformity over capital cost.
Supply Chain Analysis
Extended payment terms from leading-edge foundries now stretch 90-120 days, forcing equipment vendors into supply-chain finance facilities with Japanese and German component suppliers. Deep-ultraviolet lens fabrication concentrates in Germany and Japan; solid-state laser diodes source primarily from South Korea and the United States. Single-source vulnerability in 193nm excimer beam delivery systems creates structural risk for qualification timelines. Distribution runs through direct vendor-foundry framework agreements with multi-year pricing escalators rather than independent distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Laser annealing equipment penetration sits at early-cycle expansion as sub-3nm logic ramp and EU Green Deal thermal efficiency mandates accelerate replacement of conventional furnace diffusion. Foundry consolidation into three dominant buyers compresses vendor negotiation leverage while opening white-space in solar and power device applications.
For Market Incumbents: Pre-empt flash lamp annealing substitution by unbundling software upgrades and consumables from base hardware contracts to preserve margin visibility. Deepen captive optics supply chain development in Yokohama and Aachen corridors to reduce single-source vulnerability in deep-ultraviolet beam delivery systems. For New Entrants and Emerging Players: India's PLI scheme for solar cell manufacturing represents the most penetrable entry point for selective emitter and passivated contact processing tools. Power device silicon carbide annealing above 1700°C offers greenfield application expansion beyond silicon processing. Establish local service infrastructure in Gujarat and Tamil Nadu manufacturing clusters before incumbent vendors lock in multi-year maintenance contracts. For Investors and Strategic Acquirers: EPA fluorinated greenhouse gas reporting tightening reshapes the acquisition landscape toward equipment suppliers with certified closed-loop gas recycling systems. Long-term viability centers on wavelength-agnostic platform developers serving multiple thermal budgets through hybrid laser architectures. Monitor qualification timeline compression at leading foundries as early signal for vendor consolidation pressure.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Optics Supply Development | In-house lens fabrication in Germany and Japan reduces single-source dependency for 193nm excimer beam delivery. |
| Hybrid Laser Platform Launch | Ultrafast systems combining nanosecond and continuous-wave modes reduce foundry qualification cycles across multiple thermal budgets. |
| Closed-Loop Gas Recycling Certification | EPA compliance for krypton and xenon mixtures preserves operating permits in Intel's Arizona and Oregon fabrication complexes. |
| India Local Service Infrastructure | Gujarat and Tamil Nadu facilities capture PLI scheme solar cell manufacturing incentives before incumbent lock-in. |
| SiC Power Device Annealing Entry | Aluminum implant activation above 1700°C opens greenfield application beyond silicon for electric vehicle inverters. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of SEC equipment vendor filings, EPA emissions compliance databases, and EU Green Deal industrial heat mandate documentation. Semiconductor process engineers, foundry procurement directors, and solar cell manufacturing executives provided operational perspective. Equipment vendor service contracts, METI subsidy disclosure records, and Taiwan National Development Council capital allocation reports supplied secondary validation. Bottom-up tool shipment tracking triangulates against top-down foundry capex analysis.
Forecast inputs include laser wavelength configuration, pulse duration technology, application thermal budget requirements, and regional subsidy eligibility across the projection horizon. Segmentation dimensions span product type, technology mode, application vertical, and end-user industry. CAGRs derive from equipment procurement pipeline analysis and foundry capacity expansion announcements. Sub-3nm logic ramp velocity and EU Green Deal implementation pace serve as industry-specific forecast sensitivity inputs.
Practitioners should monitor EPA fluorinated greenhouse gas rulemaking, EU REACH chemical restriction updates, and foundry consolidation patterns for early signals. Forecasts reflect assumptions about subsidy continuity, optics supply chain stability, and qualification timeline compression. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Equipment
Semiconductor Capital Equipment Market
Semiconductor Equipment
Vacuum Coating Equipment Market
Semiconductor Equipment
Europe Chip Mounter Market
Semiconductor Equipment
Tape on Reel Feeder Market
Semiconductor Equipment
Global Photoresist Market
Semiconductor Equipment
Ion Milling System Market
Semiconductor Equipment
Wafer Back-Grinding Machine Market
Semiconductor Equipment
Africa Extreme Ultraviolet Lithography (EUVL) Systems Market
Semiconductor Equipment
Global Semiconductor Coolers Market
Semiconductor Equipment
Multi-Touch Equipment Market
Semiconductor Equipment
APAC Die Attach Equipment Market
Semiconductor Equipment
Global Battery Manufacturing Equipment Market
Semiconductor Equipment
Unscrambling Machine Market
Semiconductor Equipment
Global Resist Processing Equipment Market
Semiconductor Equipment
Wire Bonder Equipment Market
Semiconductor Equipment
Vacuum Ovens Market