
 Microtube Box Market | 2026-2036
Microtube Box Market Size, Share, and Industry Trends Forecast 2026-2036
Microtube Box Market Foresight
ISO 13485 certification for medical device quality management is bifurcating the competitive landscape into qualified suppliers and commodity producers. Thermo Fisher Scientific Inc. leverages its diagnostic infrastructure to anchor distribution across North American clinical networks. VWR International, LLC sustains channel dominance through integrated laboratory supply contracts with research institutions. MTM Molded Products Company specializes in precision-molded polypropylene configurations for cryogenic storage applications.
A microtube box is a rigid container engineered to organize, protect, and thermally stabilize cylindrical microcentrifuge tubes, typically manufactured from autoclavable polypropylene or acetal copolymer with alphanumeric grid indexing for sample traceability. These boxes serve biobanking, diagnostic testing, and pharmaceutical quality-control workflows where thermal cycling resistance and dimensional stability prevent tube deformation. Storage Boxes command the largest volume share due to biorepository capacity expansion, while Cooling Boxes represent the fastest-growing category as cell-and-gene therapy logistics demand active temperature control during transport. Polypropylene dominates material selection for its chemical inertness and minus-eighty-degree Celsius performance, though Acetal gains traction in automated handling systems requiring tighter dimensional tolerances.
FDA 21 CFR Part 820 quality system regulation governs U.S. medical device packaging suppliers, while EU MDR and REACH compliance shape European market access through biocompatibility and substance restriction requirements. ISO 10993 biological evaluation standards further constrain material selection for direct-contact applications. Stakeholders must monitor evolving cold-chain validation protocols as regenerative medicine shipments expand beyond traditional frozen-specimen logistics.
Market Dynamics
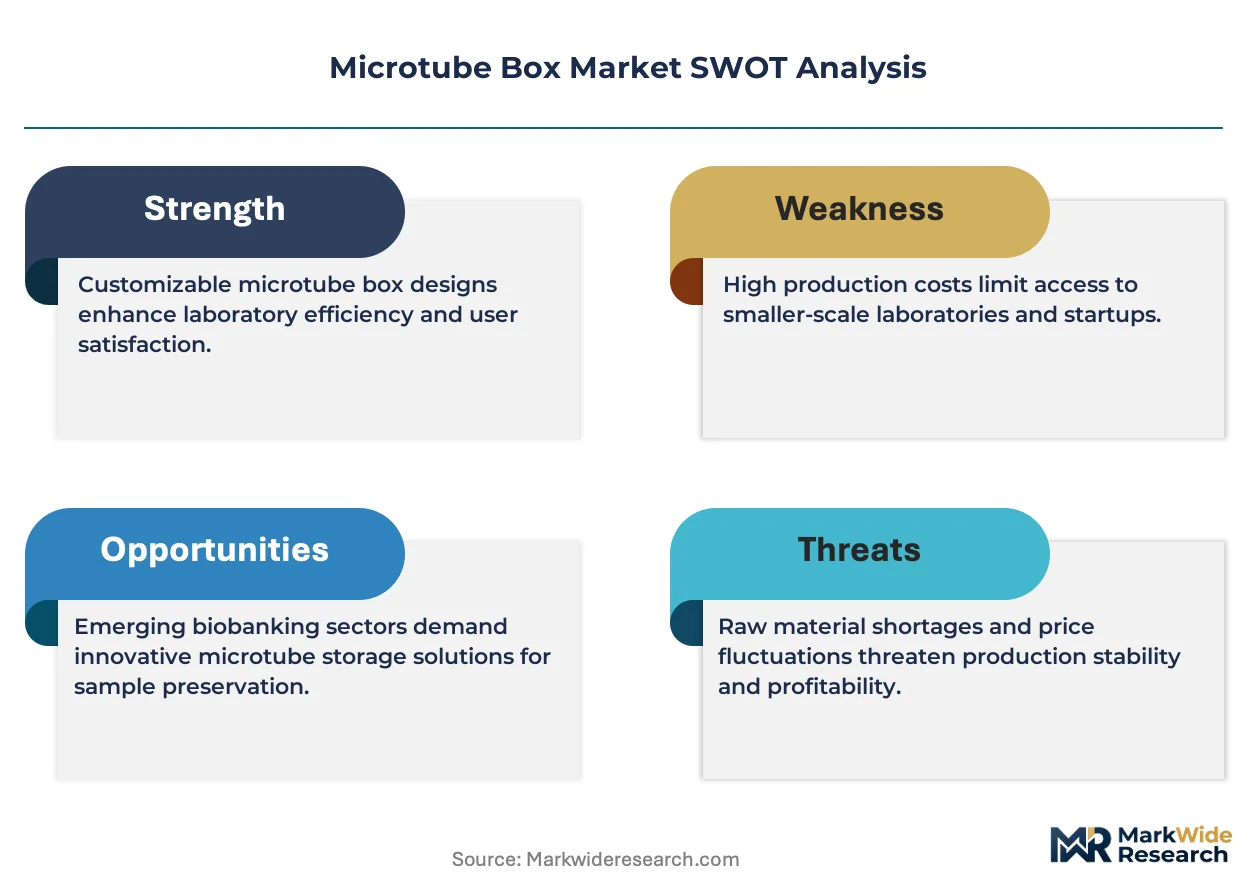
ISO 13485 certification requirements are concentrating supplier qualification around cryogenic-grade polypropylene capabilities, forcing mid-tier molders to exit clinical-grade segments or absorb multi-year compliance costs.
Growth Catalysts
- EU MDR biocompatibility mandates:Device packaging regulations now require documented material traceability, accelerating replacement of uncertified storage containers in European biobanks.
- Cell-and-gene therapy cold-chain expansion:Regenerative medicine logistics demand active temperature control during transport, pulling investment into specialized cooling box configurations.
- Germany's cryogenic infrastructure concentration:Pharmaceutical cold-chain investment outpaces regional peers, creating anchor demand for minus-eighty-degree Celsius validated containers.
Market Restraints
- Polypropylene resin price volatility:Propylene feedstock costs fluctuate with crude oil benchmarks, compressing margins for standardized storage box producers.
- ISO 10993 testing timeline friction:Biological evaluation protocols add months to new product introductions, delaying revenue recognition for material innovations.
- Acetal copolymer substitution threat:Automated handling systems increasingly specify tighter dimensional tolerances than polypropylene achieves, shifting specification authority.
Strategic Opportunities
- India biobanking infrastructure buildout:CDSCO-aligned medical device regulations and government research funding create first-mover advantage for certified suppliers.
- Smart container convergence:Integration of RFID tracking with thermal mass engineering enables real-time chain-of-custody documentation for high-value specimens.
- Direct-to-laboratory distribution channels:E-procurement platforms serving academic medical centers disintermediate traditional distributor markups.
Industry Challenges
- Multi-standard certification complexity:Simultaneous FDA 21 CFR Part 820, EU MDR, and ISO 13485 compliance requires dedicated regulatory affairs functions that strain mid-cap resources.
- Legacy inventory system integration:Alphanumeric grid indexing standards vary across biorepository software platforms, forcing custom mold modifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Microtube Box Market |
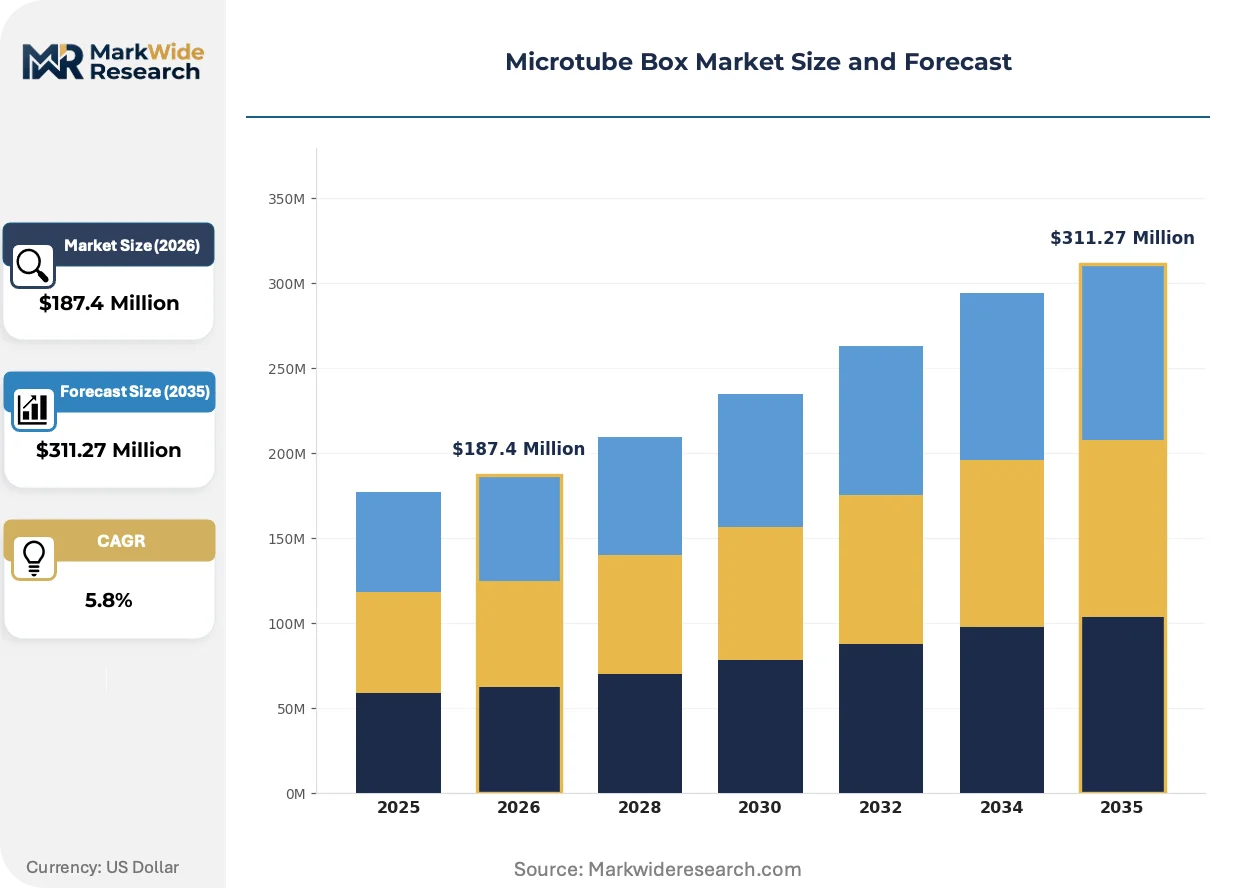
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Storage Boxes, Transport Boxes, Sample Boxes, Cooling Boxes Material: Polypropylene, Polyethylene, Acetal, Aluminum End User: Life Sciences, Pharmaceutical Companies, Research Institutions, Clinical Laboratories Size: Standard Size, Mini Size, Large Capacity, Custom Size |
| Companies Covered | VWR International, LLC, Medax International Inc, Cole-Parmer Instrument Company, LLC, Isolab Laborgeräte GmbH, Ritter GmbH, Thermo Fisher Scientific Inc., Bioline Technologies, MTM Molded Products Company, Axil Scientific Pte Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Microtube Box Market Shifts & Advancements
Material science advances and regulatory digitization are compressing product lifecycles while elevating performance specifications for cryogenic containment.
Acetal copolymer formulations with enhanced dimensional stability are supplanting polypropylene in automated liquid-handling workstations. Pharmaceutical quality-control laboratories specify these tighter-tolerance boxes for high-throughput screening workflows. The shift is compressing addressable volume for commodity polypropylene molders while expanding premium pricing bands.
REACH substance restriction amendments now govern phthalate and bisphenol content in laboratory plastics. European manufacturers reformulate additive packages to maintain minus-eighty-degree Celsius performance without restricted plasticizers. Cryogenic storage applications face the steepest compliance burden due to extended material-stress exposure.
Consolidated procurement through integrated laboratory supply contracts now dominates academic medical center purchasing. Independent distributors lose share to sole-source agreements covering consumables, equipment, and service. Germany and the United States exhibit the most concentrated buyer power, squeezing spot-market suppliers.
Microtube Box Market Segmentation
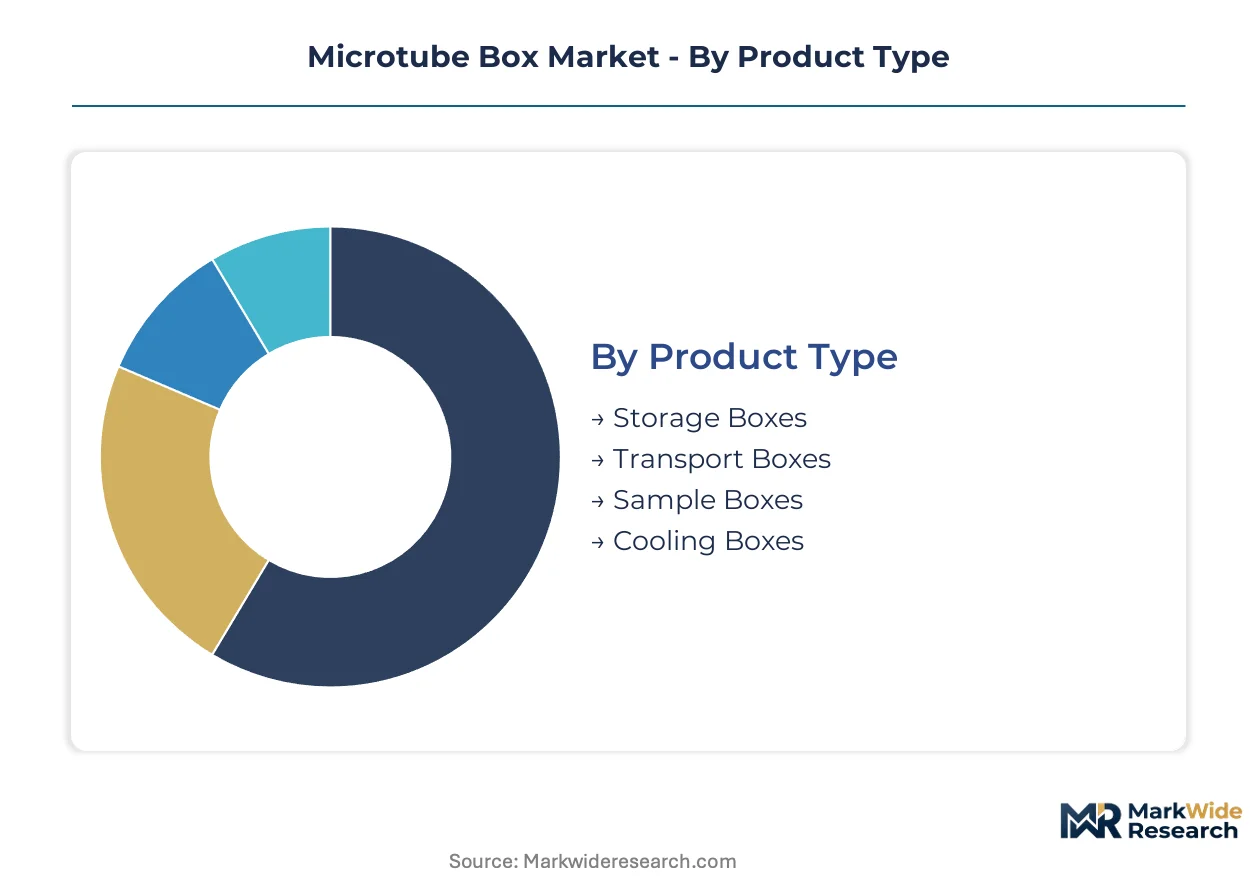
Microtube box segmentation reflects divergent performance requirements across cryogenic storage, automated handling, and point-of-care logistics. Material selection and dimensional specifications directly determine qualification for ISO 13485-certified supply chains versus commodity procurement channels.
Product Type:
Transport Boxes face acute substitution pressure from passive insulated shippers in cell-and-gene therapy logistics, while Cooling Boxes command specification authority through active temperature control integration.
- Storage Boxes:Rigid polypropylene containers with alphanumeric grid indexing support biorepository capacity expansion. Academic medical centers in Germany anchor procurement volume for minus-eighty-degree Celsius validated configurations.
- Cooling Boxes:Engineered thermal mass systems with phase-change materials enable active temperature control during regenerative medicine shipments. Cell-and-gene therapy logistics networks specify these for chain-of-custody compliance.
- Transport Boxes:Lightweight configurations prioritize specimen security during short-duration movement.
- Sample Boxes:Specialized formats for diagnostic testing workflows emphasize traceability features.
Storage Boxes anchor the volume base while Cooling Boxes gain share at the steepest rate.
Material:
Cost tier stratification separates cryogenic-grade certified resins from commodity laboratory plastics, with automated handling systems driving specification migration toward tighter-tolerance polymers.
- Polypropylene:Autoclavable homopolymer dominates biobanking infrastructure for chemical inertness and minus-eighty-degree Celsius performance. REACH substance restriction amendments now govern additive packages in European supply.
- Acetal:Copolymer formulations with enhanced dimensional stability supplant polypropylene in automated liquid-handling workstations. Pharmaceutical quality-control laboratories specify these for high-throughput screening tolerances.
- Polyethylene:Lower-cost alternative for ambient-temperature storage applications.
- Aluminum:Metal configurations serve specialized thermal conductivity requirements.
Polypropylene retains the largest installed base while Acetal climbs the fastest in specification-intensive segments.
End User:
Customer type concentration in consolidated procurement systems favors sole-source agreements covering consumables, equipment, and service.
- Life Sciences:Broad research applications span academic and commercial laboratories.
- Pharmaceutical Companies:Quality-control and manufacturing operations demand validated supply chains with documented material traceability under EU MDR biocompatibility mandates.
- Research Institutions:Academic medical centers drive biobanking expansion with integrated laboratory supply contracts.
- Clinical Laboratories:Diagnostic testing networks require high-volume standardized configurations.
Research Institutions concentrate procurement volume while Pharmaceutical Companies expand specification requirements most aggressively.
Size:
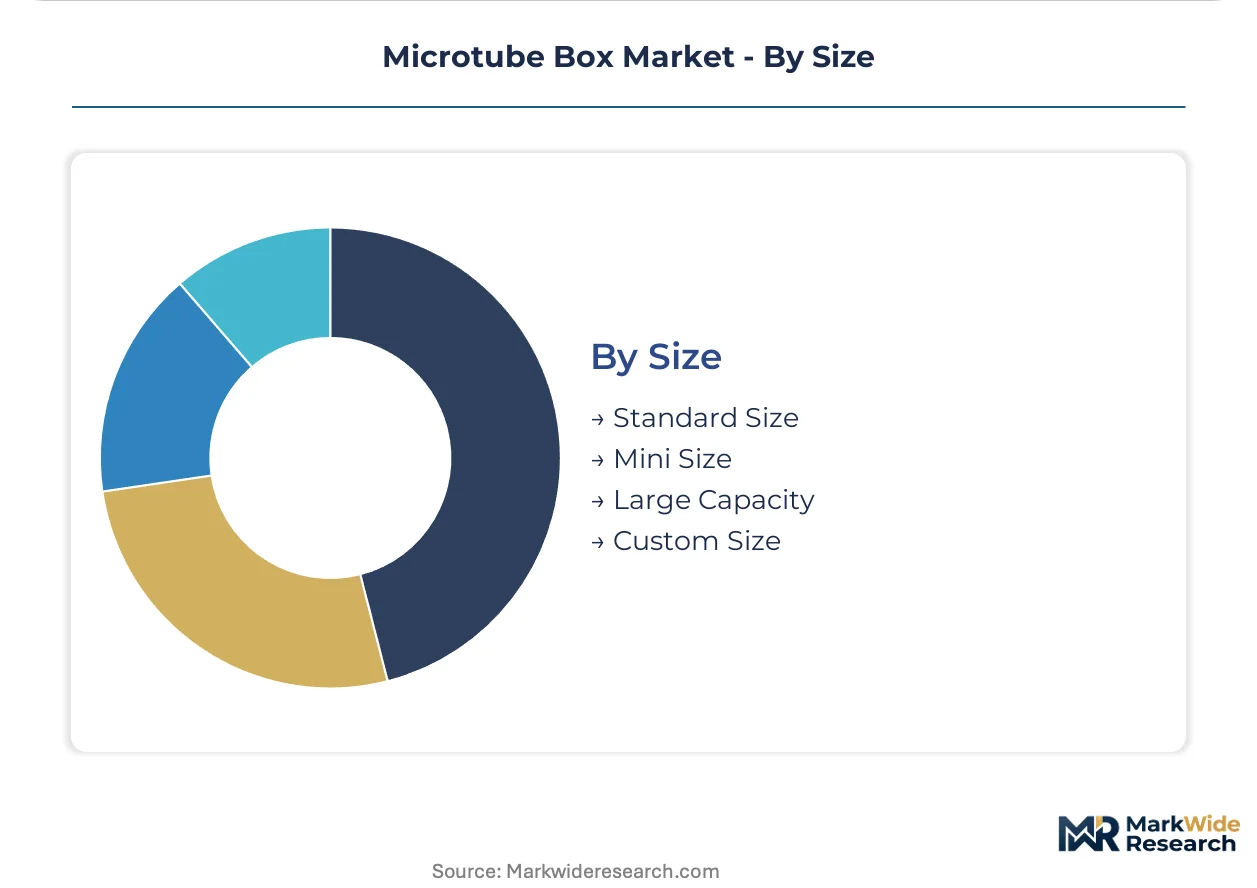
Volume scale economics favor standard configurations, though custom dimensions penetrate automated handling installations.
- Standard Size:96-well and 100-well grid formats dominate biorepository software platform compatibility.
- Large Capacity:High-density configurations reduce per-specimen storage footprint in cryogenic infrastructure.
- Mini Size:Compact formats serve point-of-care and field collection applications.
- Custom Size:Application-specific dimensions integrate with proprietary automated handling systems.
Standard Size captures the highest shipment volumes while Custom Size commands premium pricing in integrated automation deployments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Academic medical centers and pharmaceutical cold-chain operators concentrate procurement authority in Germany, the United States, and select Asian biotech clusters. ISO 13485-certified suppliers command premium positioning where regenerative medicine logistics expand fastest.
Germany
Pharmaceutical cold-chain investment and cryogenic storage infrastructure anchor European demand for minus-eighty-degree Celsius validated containers. EU MDR biocompatibility mandates accelerate replacement of uncertified storage boxes across Bavarian and North Rhine-Westphalian biobanks. The Munich-Leipzig corridor concentrates contract manufacturing for cell-and-gene therapy logistics.
United States
FDA 21 CFR Part 820 quality system regulation governs medical device packaging suppliers serving diagnostic testing networks and biorepository expansion. Academic medical centers in Greater Boston and the Research Triangle drive integrated laboratory supply contract consolidation. California's regenerative medicine cluster pulls specialized cooling box configurations for chain-of-custody compliance.
China
NMPA medical device regulations and government research funding accelerate biobanking infrastructure buildout in Yangtze River Delta biotech parks. CDSCO-aligned quality standards emerge as reference points for export-oriented molders serving clinical-grade segments. Shanghai's Zhangjiang Hi-Tech Park concentrates precision molding capabilities for automated handling systems.
India
Government research funding and CDSCO medical device regulations create first-mover advantage for ISO 13485-certified suppliers entering biobanking infrastructure. Maharashtra and Karnataka anchor demand from academic medical centers and pharmaceutical quality-control operations. Hyderabad's genome valley cluster drives specification migration toward alphanumeric grid indexing compatibility.
Japan
PMDA quality management requirements and METI technology roadmaps shape container specifications for automated liquid-handling workstations. Pharmaceutical quality-control laboratories in Kanto and Kansai regions specify tighter dimensional tolerances for high-throughput screening workflows. Osaka's medical device manufacturing belt concentrates acetal copolymer molding expertise.
Microtube Box Market Competitive Landscape
Player mix skews toward diversified laboratory supply conglomerates and precision-molding specialists. Thermo Fisher Scientific and VWR International anchor North American distribution through diagnostic infrastructure and integrated supply contracts. Three strategic archetypes dominate: cryogenic-grade certified molders, automated handling system integrators, and channel-dominant distributors. Competitive moves concentrate on ISO 13485 certification acquisition and sole-source agreement penetration with academic medical centers.
Within the certified-molder tier, MTM Molded Products Company exemplifies precision-molded polypropylene specialization for cryogenic storage applications. Thermo Fisher Scientific Inc. occupies a position as a diversified conglomerate leveraging diagnostic infrastructure for distribution reach. VWR International, LLC sits within the channel-dominant archetype through integrated laboratory supply contracts with research institutions. These three represent the strategic positioning vectors—material specialization, vertical integration, and procurement consolidation—that separate qualified suppliers from commodity producers.
| Leading Market Players |
|---|
| VWR International, LLC |
| Medax International Inc |
| Cole-Parmer Instrument Company, LLC |
| Isolab Laborgeräte GmbH |
| Ritter GmbH |
| Thermo Fisher Scientific Inc. |
| Bioline Technologies |
| MTM Molded Products Company |
| Axil Scientific Pte Ltd |
| Others |
Supply & Pricing Matrix
Long-term offtake agreements between cryogenic-grade polypropylene molders and German pharmaceutical cold-chain operators lock in supply access while anchoring price visibility against propylene feedstock volatility. These contracts bundle ISO 13485-certified container volumes with indexed resin pass-through clauses, insulating qualified suppliers from spot-market margin compression.
Pricing Analysis
Cost-plus contracts with propylene indexation dominate procurement between certified molders and European biobanking networks. Three-tier pricing structure across premium certified-grade, standard clinical-grade, and economy laboratory-grade levels separates ISO 10993-validated configurations from commodity alternatives. Pricing pressure stems from acetal copolymer substitution in automated handling systems, displacing polypropylene in high-throughput screening workflows. Academic medical centers exhibit the highest price sensitivity through consolidated procurement tenders, while cell-and-gene therapy logistics operators prioritize validated supply over unit cost.
Supply Chain Analysis
Just-in-time inventory strategies prevail among automated liquid-handling workstation OEMs, while biorepository operators maintain strategic stockpiles of minus-eighty-degree Celsius validated containers. Manufacturing concentrates in Germany, the United States, and China, with precision molding capabilities clustering around pharmaceutical cold-chain infrastructure. Polypropylene resin and acetal copolymer pellets constitute the primary raw material dependencies, with REACH substance restriction amendments constraining additive package sourcing. Single-source vulnerability runs through specialized cryogenic-grade resin formulations. Distribution feeds through integrated laboratory supply contracts and direct e-procurement platforms serving academic medical centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent suppliers must defend against acetal copolymer substitution in automated handling segments while navigating consolidated procurement pressure from sole-source agreements.
For Market Incumbents: Consolidate certification authority by accelerating ISO 13485 acquisition for cryogenic-grade polypropylene lines, then deepen backward integration into propylene feedstock hedging to defend margin position against resin volatility. Channel control through integrated laboratory supply contracts with German academic medical centers provides defensive moats against spot-market competitors. For New Entrants and Emerging Players: CDSCO-aligned ISO 13485 fast-track pathways in India offer the most penetrable entry point, targeting government-funded biobanking infrastructure buildout in Maharashtra and Karnataka. Direct-to-laboratory e-procurement platforms disintermediate traditional distributor markups, enabling specification capture without legacy channel investments. For Investors and Strategic Acquirers: Capital is best deployed toward precision-molding specialists with cryogenic-grade resin capabilities and existing EU MDR technical documentation. Long-term viability hinges on regenerative medicine logistics expansion beyond traditional frozen-specimen applications. Watch for inflection when cell-and-gene therapy shipment volumes trigger dedicated cooling box capacity constraints.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 13485 Certification Acquisition | Qualifies suppliers for EU MDR biocompatibility mandates and German pharmaceutical procurement. |
| Cryogenic-Grade Resin Backward Integration | Captures margin from propylene feedstock volatility through captive polypropylene formulation. |
| RFID-Enabled Smart Container Development | Integrates thermal mass engineering with real-time chain-of-custody documentation for cell-and-gene therapy. |
| Direct E-Procurement Platform Launch | Disintermediates distributor markups in academic medical center consolidated purchasing. |
| Acetal Copolymer Precision Molding Capacity | Captures automated liquid-handling workstation specifications with tighter dimensional tolerances. |
Research Methodology
Desk research of FDA 21 CFR Part 820 guidance documents, EU MDR technical documentation requirements, and ISO 10993 biological evaluation standards preceded structured interviews with cryogenic storage infrastructure managers, biomedical procurement officers at academic medical centers, precision-molding operations directors, and regulatory affairs leads at medical device packaging suppliers. Secondary validation drew from SEC filings of laboratory supply conglomerates, customs data on polypropylene resin trade flows, and hospital procurement database extracts. Bottom-up volume modeling triangulated against top-down pharmaceutical cold-chain investment forecasts.
Variance decomposition across product type, material grade, end-user concentration, and regional regulatory cluster shaped the analytical framework. CAGRs were derived from segmented growth rate reconciliation against aggregate market expansion. Cryogenic storage capacity buildout, cell-and-gene therapy logistics network expansion, and automated handling system penetration served as industry-specific forecast inputs throughout the projection horizon.
Decision-makers should treat outputs as directional under assumptions of sustained pharmaceutical cold-chain investment and stable REACH substance restriction enforcement; material deviation would warrant model refresh. Revision becomes warranted when acetal copolymer substitution rates in automated handling systems cross thresholds that compress polypropylene addressable volume.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Packaging
Semiconductor Wafer Tape Market
Semiconductor Packaging
3D TSV Packages Market
Semiconductor Packaging
Multichip Package Market
Semiconductor Packaging
Global Semiconductor Equipment Packaging and Test Market
Semiconductor Packaging
2.5D and 3D Semiconductor Packaging Market
Semiconductor Packaging
Bonding Wire Packaging Market
Semiconductor Packaging
Antenna-In-Package Technology Market
Semiconductor Packaging
Semiconductor Chip Handler Market
Semiconductor Packaging
System in Package (Sip) Technology Market
Semiconductor Packaging
Asia Pacific LED Packaging Market
Semiconductor Packaging
Semiconductor Packaging Market
Semiconductor Packaging
Global Semiconductor Seals Market
Semiconductor Packaging
Outsourced Semiconductor Assembly and Test Services (OSAT) Market
Semiconductor Packaging
Through-Silicon via (TSV) IC Packaging Market
Semiconductor Packaging
Fan Out Packaging Market
Semiconductor Packaging
Advanced Semiconductor Packaging Market