
 ESD Stackable Boxes Market | 2026-2036
ESD Stackable Boxes Market Size, Share, and Industry Trends Forecast 2026-2036
ESD Stackable Boxes Market Foresight
Direct-to-factory supply routes from conductive plastics compounders to box molders is rewriting procurement economics across the ESD packaging tier. RTP leverages captive resin formulation capabilities to sustain margin control from pellet to finished tote. Desco Industries anchors North American distribution through its captive distributor network and in-house static-control testing labs. AUER Packaging competes on European automotive sequencing contracts where VDA-standard totes must also meet IEC 61340-5-1 surface resistivity thresholds.
ESD stackable boxes are injection-molded containers engineered with surface resistivity between 10^4 and 10^11 ohms per square, typically loaded with carbon black or inherently conductive polymers to dissipate electrostatic discharge without generating triboelectric charge. Their primary purpose is to protect static-sensitive components—printed circuit assemblies, bare dies, medical sensors—from field-induced damage during transport, storage, and line-side presentation. Polypropylene grades dominate volume production due to chemical resistance and recycling compatibility, though conductive ABS commands premium positioning in semiconductor front-end applications where outgassing limits apply. Customizable box configurations are capturing the fastest expansion as electronics assemblers adopt modular kanban systems requiring dimension-specific dividers and lid interfaces.
FDA 21 CFR Part 820 quality system regulations shape medical device storage demand by mandating traceable, contamination-controlled packaging environments for finished devices and subassemblies. EPA guidelines on recycled content and state-level extended producer responsibility frameworks in California and New York are pressuring molders to validate post-industrial regrind ratios without degrading conductive performance. IEC 61340-5-1 and ANSI/ESD S20.20 certification requirements create a compliance floor that filters out uncertified regional competitors and locks qualified suppliers into recurring audit cycles. Stakeholders must monitor how automotive electrification programs and medical device reshoring initiatives redistribute volume across application segments before committing to material-specific capacity expansions.
Market Dynamics
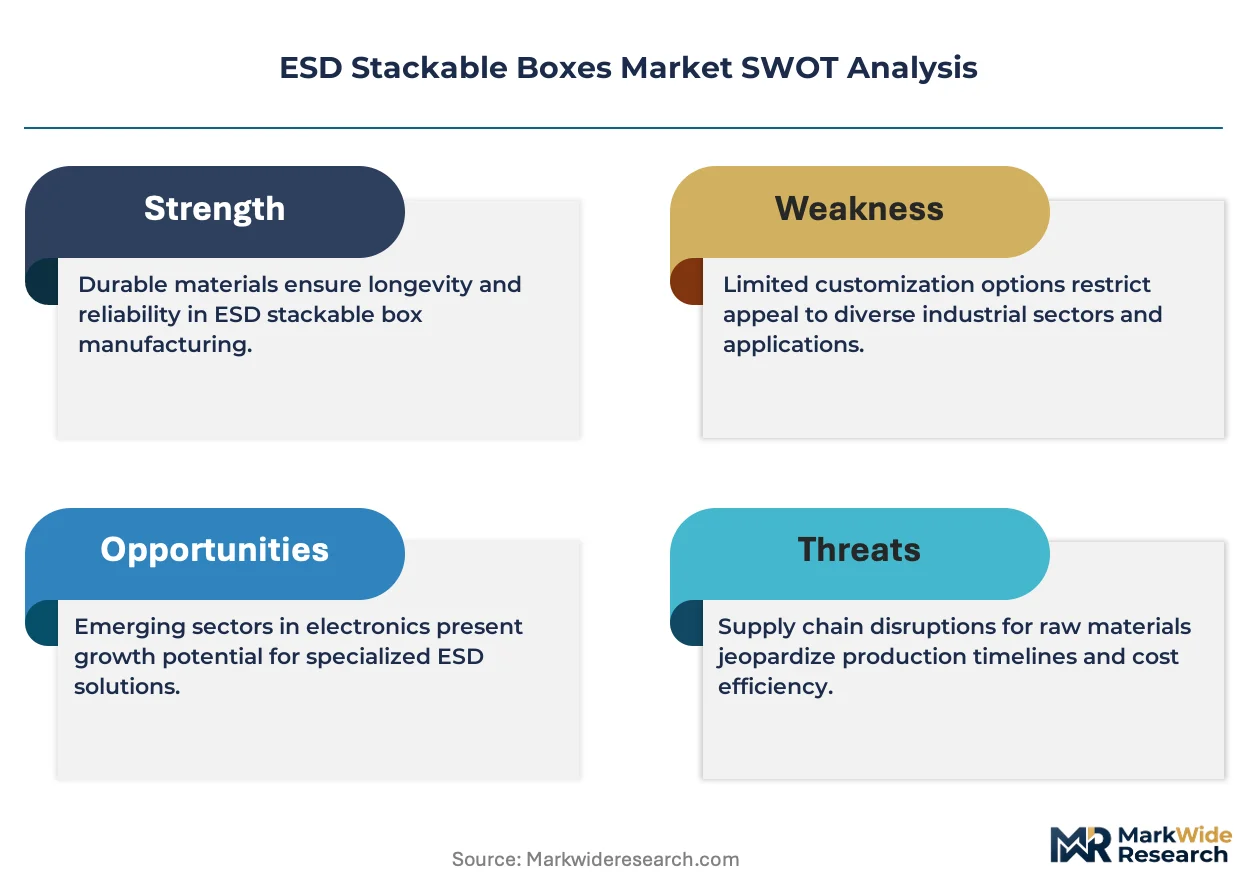
Direct-to-factory supply routes from conductive plastics compounders to box molders are rewriting procurement economics across the ESD packaging tier, compressing traditional distributor margins and rewarding captive resin formulation capabilities.
Growth Catalysts
- Semiconductor packaging expansion:Wafer fabs in Taiwan and South Korea are scaling intra-facility transport systems that demand IEC 61340-5-1 certified conductive containers.
- EU REACH compliance mandates:Electronics assemblers across European supply chains must replace legacy packaging with RoHS-aligned conductive polypropylene to meet hazardous substance thresholds.
- Medical device reshoring:FDA 21 CFR Part 820 quality system regulations are driving domestic U.S. demand for traceable, contamination-controlled storage environments.
Market Restraints
- Carbon black price volatility:Primary conductive filler costs fluctuate with petrochemical feedstock markets, squeezing compounder margins.
- Concentrated resin supply:Conductive polypropylene pellet production clusters in Germany and the U.S. Gulf Coast create geographic vulnerability.
- Outgassing limitations:Semiconductor front-end applications restrict polymer selection, blocking cheaper ABS alternatives from high-value segments.
Strategic Opportunities
- India electronics manufacturing:PLI scheme incentives for semiconductor and mobile device assembly are creating first-mover openings for localized ESD box production.
- Automotive battery sequencing:Electric vehicle assembly lines in Germany require VDA-standard totes that simultaneously meet ESD and dimensional tolerances.
- Closed-loop recycling systems:California and New York extended producer responsibility frameworks reward molders validating post-industrial regrind ratios without conductivity degradation.
Industry Challenges
- ANSI/ESD S20.20 certification timelines:Audit cycles and documentation requirements lock qualified suppliers into recurring compliance investments that regional competitors cannot match.
- Kanban system integration:Electronics assemblers demand modular dividers and lid interfaces that require custom tooling for each dimension specification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | ESD Stackable Boxes Market |
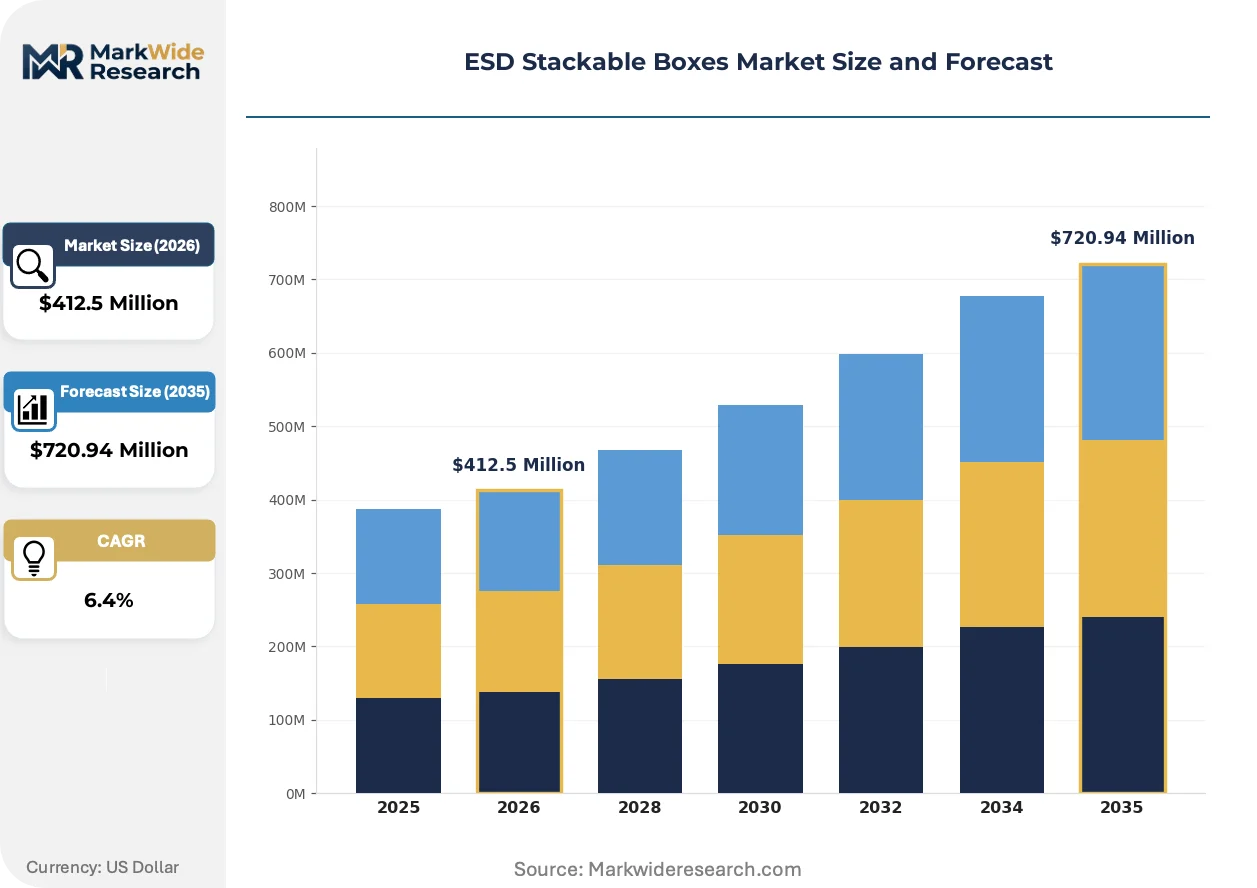
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $720.94 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Boxes, Customizable Boxes, Small Parts Containers, Tote Boxes Material: Polypropylene, Conductive Plastics, Polyethylene, ABS Application: Electronics Manufacturing, Semiconductor Packaging, Automotive Supply, Medical Device Storage End User: Manufacturers, Warehouses, Logistics Providers, Retailers |
| Companies Covered | RTP, Induspac, Molded Fiber Glass Companies, AUER Packaging, Protective Packaging Corporation, Desco Industries, Summit Container, GWP Group, Storopack Hans Reichenecker, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
ESD Stackable Boxes Market Shifts & Advancements
Material science advances and regulatory tightening are converging to reshape how static-sensitive components move through electronics supply chains. Three developments dominate the current transformation.
Embedded RFID tagging is digitizing inventory tracking within ESD containers. Semiconductor front-end facilities in South Korea are deploying these smart totes for real-time wafer location monitoring. The technology is digitizing what was previously manual barcode scanning, compressing cycle times and reducing misplacement errors in cleanroom environments.
EU F-Gas Regulation restrictions on fluorinated compounds are pressuring molders to eliminate perfluorinated anti-static additives from conductive formulations. Compounders in the Netherlands and Belgium are reformulating with carbon nanotube alternatives. Medical device packaging for European export faces the steepest compliance curve, with manufacturers accelerating validation timelines to maintain CE marking eligibility.
Contract manufacturers in China's Yangtze River Delta are consolidating supplier relationships around vertically integrated compounder-molders. This buyer concentration is displacing fragmented distributor networks that previously intermediated between resin suppliers and box producers. Procurement teams now negotiate direct pellet-to-tote pricing, compressing the traditional three-tier supply structure into two-layer transactions.
ESD Stackable Boxes Market Segmentation
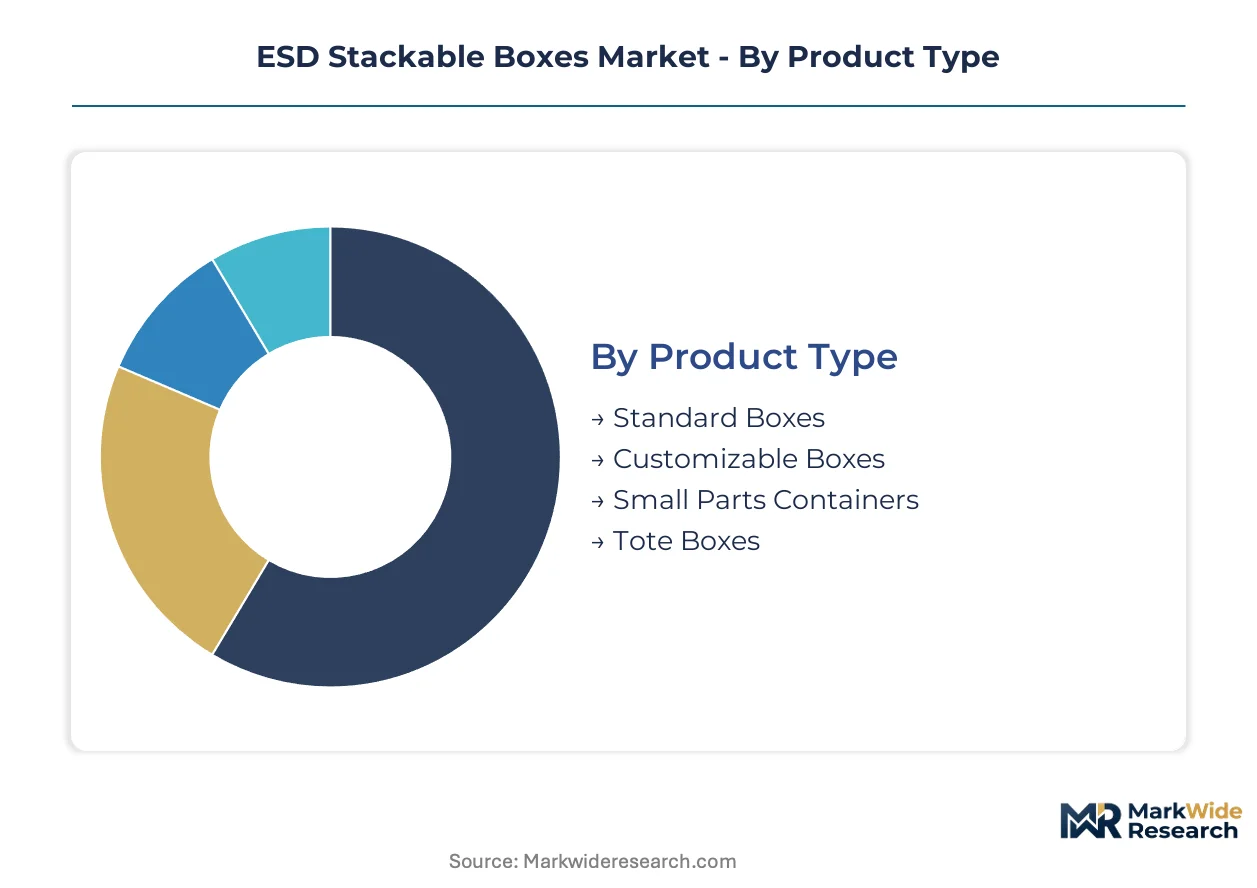
ESD stackable boxes serve distinct operational rhythms across electronics supply chains. Cycle times vary dramatically from semiconductor wafer handling requiring immediate turnover to medical device storage demanding extended contamination control. Understanding these velocity differentials shapes procurement strategy and capacity planning.
Product Type:
Standard boxes turn inventory fastest through catalog distribution, while custom tooled configurations lock capital for 12-18 week production cycles.
- Standard Boxes:Injection-molded containers in fixed dimensions with IEC 61340-5-1 certification. Electronics contract manufacturers in China's Yangtze River Delta pull these through direct mill relationships for kanban replenishment.
- Customizable Boxes:Modular platforms accepting dimension-specific dividers, lid interfaces, and RFID mounting points. Semiconductor packaging facilities in Taiwan specify these for wafer transport compatibility with automated handling equipment.
- Small Parts Containers:Cell-sized bins for component-level storage in surface-mount assembly lines.
- Tote Boxes:VDA-standard footprints serving automotive sequencing operations in Germany.
Standard boxes dominate installed base. Customizable boxes are where expansion concentrates.
Material:
Conductive filler selection determines both unit economics and regulatory compliance across export destinations.
- Polypropylene:Carbon-black loaded grades dominate volume production with chemical resistance and recycling compatibility. European electronics assemblers favor these for REACH-aligned hazardous substance compliance.
- Conductive Plastics:Inherently conductive polymer formulations command premium positioning where outgassing limits apply. Semiconductor front-end cleanrooms in South Korea specify these for bare die protection.
- Polyethylene:Lower-cost alternative for non-critical static dissipation in warehouse buffering applications.
- ABS:Restricted from high-value segments by outgassing constraints despite favorable processing characteristics.
Polypropylene captures the broadest volume footprint. Conductive plastics are climbing the fastest on semiconductor packaging expansion.
Application:
End-use requirements fragment procurement specifications across surface resistivity thresholds and dimensional tolerances.
- Electronics Manufacturing:Printed circuit assembly operations requiring 10^6 to 10^9 ohms per square surface resistivity for component handling.
- Semiconductor Packaging:Wafer-level transport demanding the tightest conductivity windows and lowest particulate generation.
- Automotive Supply:Battery module sequencing in electric vehicle assembly lines requiring simultaneous ESD protection and VDA dimensional compliance.
- Medical Device Storage:FDA 21 CFR Part 820 traceability mandates driving contamination-controlled environments for finished devices.
Electronics manufacturing anchors current volume. Semiconductor packaging is gaining share fastest on Taiwan and South Korea fab expansion.
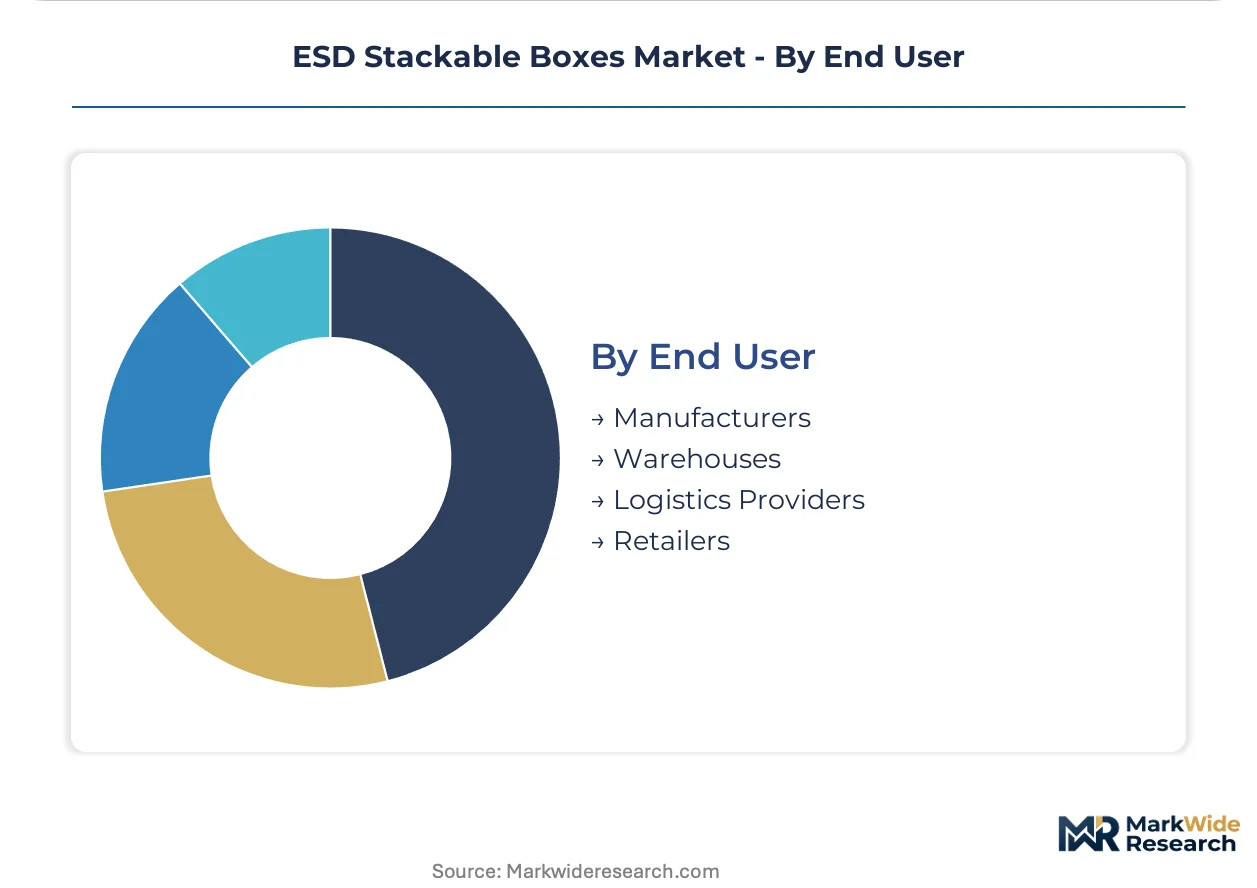
End User:
Procurement authority concentrates differently across direct manufacturing versus third-party logistics channels.
- Manufacturers:OEM and contract electronics assemblers specifying direct-to-factory supply routes from compounders.
- Warehouses:Distribution centers managing buffer inventory with shorter specification cycles.
- Logistics Providers:Third-party handlers consolidating multi-customer requirements into standardized container pools.
- Retailers:Limited direct procurement, primarily serving aftermarket electronics component distribution.
Manufacturers control specification authority. Logistics providers are where procurement consolidation is accelerating.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MIIT semiconductor packaging mandates in China are accelerating conductive container standardization across East Asian supply chains. Electronics assemblers in three countries dominate procurement volume for IEC 61340-5-1 certified transport systems.
China
Yangtze River Delta contract manufacturers are consolidating supplier relationships around vertically integrated compounder-molders. MIIT dual carbon goals pressure molders to validate post-industrial regrind ratios without degrading surface resistivity. Domestic producers in Suzhou and Wuxi are scaling capacity to serve Foxconn and Luxshare Precision assembly lines.
South Korea
Samsung and SK Hynix wafer fabs are expanding intra-facility transport systems demanding 10^6 to 10^9 ohms per square conductivity windows. MFDS medical device export regulations align with FDA traceability requirements for contamination-controlled packaging. Pyeongtaek and Yongin semiconductor clusters are deploying RFID-embedded smart totes for real-time wafer tracking.
Taiwan
TSMC and ASE packaging facilities are scaling automated handling equipment compatible with modular kanban container configurations. The country's national standards bureau enforces GB-aligned IEC certification for electronics packaging exports. Hsinchu Science Park and Tainan Technology Industrial Park are driving demand for customizable box platforms with dimension-specific dividers.
Germany
Automotive battery sequencing operations for BMW and Volkswagen EV lines require simultaneous VDA dimensional compliance and ESD protection. ECHA REACH hazardous substance thresholds are eliminating perfluorinated anti-static additives from conductive formulations. Bavarian and Baden-Württemberg automotive clusters are sourcing totes from compounders reformulating with carbon nanotube alternatives.
United States
Medical device reshoring initiatives are driving FDA 21 CFR Part 820 compliant storage demand for finished devices and subassemblies. EPA guidelines on recycled content pressure California and New York molders under extended producer responsibility frameworks. Austin and Phoenix semiconductor packaging facilities are expanding domestic sourcing of ANSI/ESD S20.20 certified containers.
ESD Stackable Boxes Market Competitive Landscape
Resin compounders and finished goods molders split the market along captive formulation versus distributed manufacturing lines. The vendor base concentrates around three strategic archetypes: vertically integrated compounder-molders controlling pellet-to-tote margins, specialized ESD testing and certification houses anchoring compliance authority, and regional fabricators competing on automotive sequencing contracts. Dominant competitive moves include backward integration into conductive resin formulation and geographic expansion into India PLI scheme electronics corridors.
Among North American specialists, Desco Industries exemplifies the certification-anchored archetype through its captive distributor network and in-house static-control testing infrastructure. RTP represents the vertically integrated model with captive resin formulation capabilities sustaining margin control from conductive pellet to finished container. AUER Packaging occupies a position within the automotive-sequencing tier, competing on European contracts where VDA-standard totes must simultaneously meet IEC 61340-5-1 surface resistivity thresholds and dimensional tolerances.
| Leading Market Players |
|---|
| RTP |
| Induspac |
| Molded Fiber Glass Companies |
| AUER Packaging |
| Protective Packaging Corporation |
| Desco Industries |
| Summit Container |
| GWP Group |
| Storopack Hans Reichenecker |
| Others |
Supply & Pricing Matrix
Conductive polypropylene pellet production clusters in Germany and the U.S. Gulf Coast concentrate upstream supply, anchoring margin pools with compounders who control resin formulation and captive mold-to-tote integration. Carbon black loading ratios and IEC 61340-5-1 certification tiers stratify pricing power across the value chain.
Pricing Analysis
Geographic price spreads between European REACH-compliant formulations and Asian standard-grade containers reflect regulatory compliance premiums alongside carbon black cost differentials. Three-tier pricing structure across premium, standard, and economy levels separates semiconductor front-end conductive plastics from warehouse-grade polypropylene. Pricing pressure stems from carbon black volatility tied to petrochemical feedstock markets, compressing compounder margins. Electronics contract manufacturers in China's Yangtze River Delta exhibit highest price sensitivity, while semiconductor fabs in Taiwan and South Korea prioritize conductivity precision over unit cost.
Supply Chain Analysis
Tariff exposure between Germany and China on carbon black imports dominates supply chain risk planning for European molders. Conductive resin production centers on Germany, the U.S. Gulf Coast, and South Korea, drawing from carbon black feedstocks, polypropylene base resins, and inherently conductive polymer additives. Single-source vulnerability concentrates in specialized carbon nanotube formulations replacing perfluorinated additives under EU F-Gas Regulation. Distribution runs through vertically integrated compounder-molders serving direct-to-factory procurement channels, displacing traditional three-tier distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ESD stackable boxes represent an early-cycle expansion story as semiconductor packaging capacity buildouts in Taiwan and South Korea accelerate adoption of IEC 61340-5-1 certified conductive containers beyond legacy electronics assembly applications.
For Market Incumbents: Harden certification authority through ANSI/ESD S20.20 audit infrastructure investments that regional competitors cannot replicate. Deepen backward integration into conductive resin formulation to defend margin pools against carbon black price volatility. Channel control through captive distributor networks anchors North American positioning against emerging Asian compounder-molders. For New Entrants and Emerging Players: India's PLI scheme electronics manufacturing corridors represent the most penetrable entry point for localized ESD box production serving semiconductor and mobile device assembly lines. Automotive battery sequencing operations in Germany offer second-mover openings where VDA-standard totes must simultaneously meet ESD and dimensional tolerances. Direct mill relationships with contract manufacturers bypass fragmented distributor networks. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated compounder-molders with captive resin formulation and in-house static-control testing infrastructure across the analysis window. Acquisition targets should demonstrate validated post-industrial regrind ratios under California and New York extended producer responsibility frameworks. The signal to watch is consolidation velocity among China's Yangtze River Delta supplier relationships as procurement teams negotiate direct pellet-to-tote pricing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Conductive Resin Formulation | Captive pellet-to-tote margin control defends against carbon black volatility and REACH compliance premiums. |
| RFID-Embedded Smart Tote Development | Real-time wafer tracking in South Korean semiconductor fabs compresses cycle times and reduces misplacement errors. |
| Carbon Nanotube Additive Reformulation | Elimination of perfluorinated compounds under EU F-Gas Regulation maintains CE marking eligibility for medical device exports. |
| India Manufacturing Footprint Establishment | PLI scheme incentives for semiconductor assembly create first-mover positioning in localized ESD box production. |
| Closed-Loop Recycling System Validation | Post-industrial regrind ratio certification satisfies California and New York extended producer responsibility frameworks. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with procurement managers at electronics contract manufacturers, plant managers at conductive resin compounders, quality directors at semiconductor packaging facilities, and logistics coordinators at automotive sequencing operations. Secondary validation drew from MIIT semiconductor packaging mandates, ECHA REACH substance databases, FDA 21 CFR Part 820 quality system guidance, IEC 61340-5-1 certification registries, and customs trade data on conductive plastics imports. Bottom-up container shipment estimates and top-down electronics manufacturing value chain analysis were triangulated to anchor volume assumptions.
Calibration against historical capacity expansion patterns and regulatory implementation timelines shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, material grade, application vertical, end-user procurement authority, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted demand curves incorporating semiconductor fab buildout schedules and automotive electrification program commitments. Carbon black price indices and resin supply concentration metrics fed industry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in electronics capital expenditure cycles, petrochemical feedstock pricing, or trade policy between major manufacturing blocs would shift the trajectory. Forecasts reflect documented assumptions on adoption rates and certification penetration that may revise with regulatory enforcement intensity or technology substitution. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Packaging
Quad-Flat-No-Lead Packaging (QFN) Market
Semiconductor Packaging
Semiconductor Wafer Tape Market
Semiconductor Packaging
Semiconductor Packaging Material Market
Semiconductor Packaging
Bonding Wire Packaging Market
Semiconductor Packaging
Antenna-In-Package Technology Market
Semiconductor Packaging
System in Package (SIP) Die Market
Semiconductor Packaging
Advanced Semiconductor Packaging Market
Semiconductor Packaging
Fan Out Packaging Market
Semiconductor Packaging
IC Packaging and Testing Market
Semiconductor Packaging
Global Semiconductor Packaging and Assembly Equipment Market
Semiconductor Packaging
Global Semiconductor Seals Market
Semiconductor Packaging
Chip Carrier Socket Market
Semiconductor Packaging
Global Interposer and Fan-Out WLP Market
Semiconductor Packaging
Semiconductor Chip Handler Market
Semiconductor Packaging
Through-Silicon via (TSV) IC Packaging Market
Semiconductor Packaging
System in Package (Sip) Technology Market