
 3D IC Packaging Market | 2026-2036
3D IC Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
3D IC Packaging Market Outlook
Multi-source advanced packaging partnerships is restructuring how semiconductor firms secure 3D IC capacity. TSMC sustains foundry-led packaging integration through its CoWoS and SoIC platforms. Samsung Electronics dominates memory-centric 3D stacking with its X-Cube technology roadmap. ASE Technology Holding anchors outsourced semiconductor assembly and test capacity across multiple nodes.
3D IC packaging vertically interconnects multiple semiconductor dies using through-silicon vias, microbumps, and hybrid bonding to achieve higher bandwidth density and reduced power consumption than planar interconnect. Through-Silicon Via technology leads current commercial volume while hybrid bonding is displacing microbump approaches in the highest-performance tiers. Consumer Electronics and Computing end-user segments concentrate near-term demand, though Automotive qualification cycles are extending adoption timelines for 3D configurations in powertrain and sensor fusion applications.
EPA facility permitting in the United States, REACH substance restrictions in Europe, and Taiwan EPA emissions standards collectively shape where new 3D IC packaging capacity can be built and what materials qualify for commercial use. ISO 9001 and IATF 16949 certifications gate automotive market access for packaging suppliers. Stakeholders must monitor which regulatory jurisdictions accelerate environmental permitting for advanced packaging fabs versus those imposing stricter chemical disclosure requirements on interposer and substrate materials.
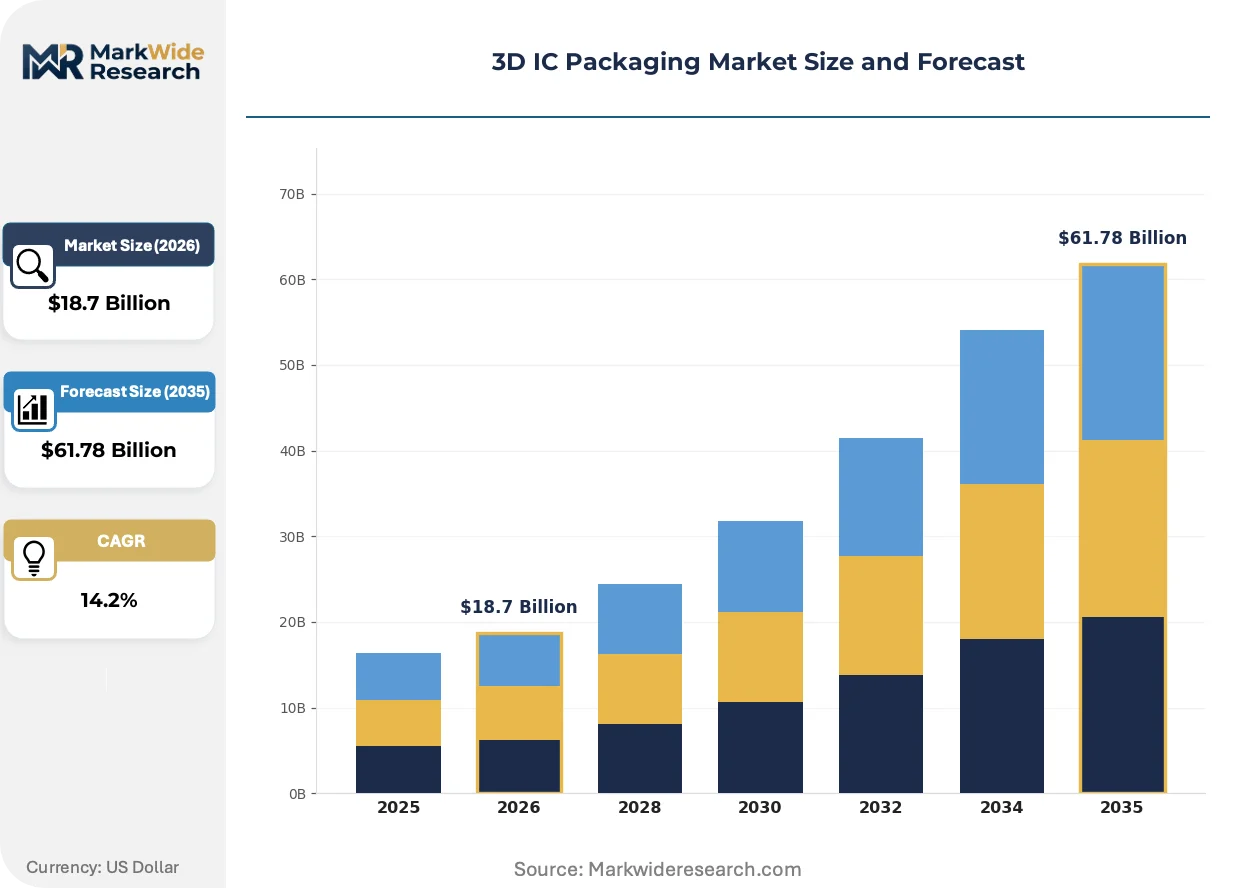
Market Dynamics
Hybrid bonding is rewriting competitive positioning in high-performance tiers as microbump interconnects face bandwidth ceilings, while foundry-led packaging integration concentrates capacity among vertically integrated players controlling both front-end and back-end processes.
Growth Catalysts
- EU Chips Act capital allocation:Subsidy frameworks in Germany, France, and the Netherlands are accelerating cleanroom construction for advanced packaging fabs. Domestic substrate supply chains are receiving priority permitting.
- Data center AI accelerator procurement:Hyperscalers are mandating vertically stacked HBM-logic configurations for training clusters. Memory bandwidth requirements per socket are driving TSV adoption rates upward.
- Automotive sensor fusion architectures:Lidar and camera consolidation onto single packaged substrates is creating new volume for mid-tier 3D configurations. Powertrain electrification is extending qualification timelines but securing long-term supply agreements.
Market Restraints
- Substrate material cost volatility:ABF substrate supply from Japan and Taiwan is experiencing price pressure due to resin and copper foil input constraints. Build-up layer yield rates amplify cost sensitivity.
- Foundry packaging concentration:CoWoS and similar integrated platforms remain captive to TSMC capacity allocation decisions. Fabless designers face extended lead times for high-bandwidth memory integration.
- Hybrid bonding equipment scarcity:Die-to-wafer bonders from Applied Materials and Besi are operating at full utilization. Tool delivery schedules are stretching beyond eighteen months for new entrants.
Strategic Opportunities
- India semiconductor packaging incentives:PLI scheme disbursements and state-level land allocations are attracting OSAT investment for mature-node 3D configurations. Domestic electronics manufacturing is creating captive demand.
- Edge AI inference modules:Low-power 3D stacking for smartphone and IoT endpoints remains underpenetrated relative to data center volumes. Chiplets for vision and voice processing are emerging as a white space.
- Automotive functional safety certification:IATF 16949 and ISO 26262 compliance is creating a two-tier supplier structure. Certified packaging houses are capturing premium positioning in powertrain and ADAS modules.
Industry Challenges
- Thermal management engineering shortage:Stacked die architectures require specialized expertise in heat spreader design and underfill material selection. Universities are not producing sufficient packaging thermal engineers.
- IP licensing fragmentation:TSV and microbump patent pools span multiple non-practicing entities. Royalty stacking is complicating cost modeling for new product introductions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 3D IC Packaging Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $61.78 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Through-Silicon Via, Microbumps, Flip Chip, Stack Die End User: Consumer Electronics, Telecommunications, Automotive, Computing Form Factor: Wafer Level, Chip Scale, Package on Package, System in Package Material: Silicon, Glass, Organic Substrates, Metal |
| Companies Covered | ASE Technology Holding Co., Ltd., JCET Group Co., Ltd., Taiwan Semiconductor Manufacturing Company, Ltd. (TSMC), Powertech Technology Inc., United Microelectronics Corporation (UMC), Samsung Electronics Co., Ltd., Amkor Technology, Broadcom, Intel Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
3D IC Packaging Market Strategic Shifts
Process-material convergence is compressing development cycles as equipment vendors and chemical suppliers co-design solutions for sub-micron pitch interconnect. Standardization efforts are lagging implementation.
Hybrid bonding is rewriting power-performance tradeoffs in the highest-bandwidth tiers. The technology eliminates microbump capacitance and resistance penalties by creating direct copper-to-copper atomic connections. Data center GPU and AI training chip designers are adopting die-to-wafer configurations at the 10-micron pitch node and below. This bonding approach is compressing the performance gap between monolithic and disaggregated silicon.
REACH substance restrictions are forcing material substitutions in European-bound packaging flows. ECHA candidate list updates are targeting specific epoxy mold compounds and underfill chemistries used in consumer electronics modules. Suppliers are reformulating halogen-free alternatives while maintaining JEDEC moisture sensitivity ratings. Automotive and industrial segments in Germany and France are experiencing the longest qualification delays as they await toxicological dossier approvals.
Buyer consolidation among hyperscalers is concentrating negotiating leverage for custom packaging configurations. Amazon Web Services, Microsoft Azure, and Google Cloud are specifying proprietary substrate designs and direct foundry relationships. Traditional OSAT intermediaries are being disintermediated from the highest-value AI accelerator flows. This concentration is most visible in Taiwan and the United States where cloud capital expenditure decisions are finalized.
3D IC Packaging Market Segmentation
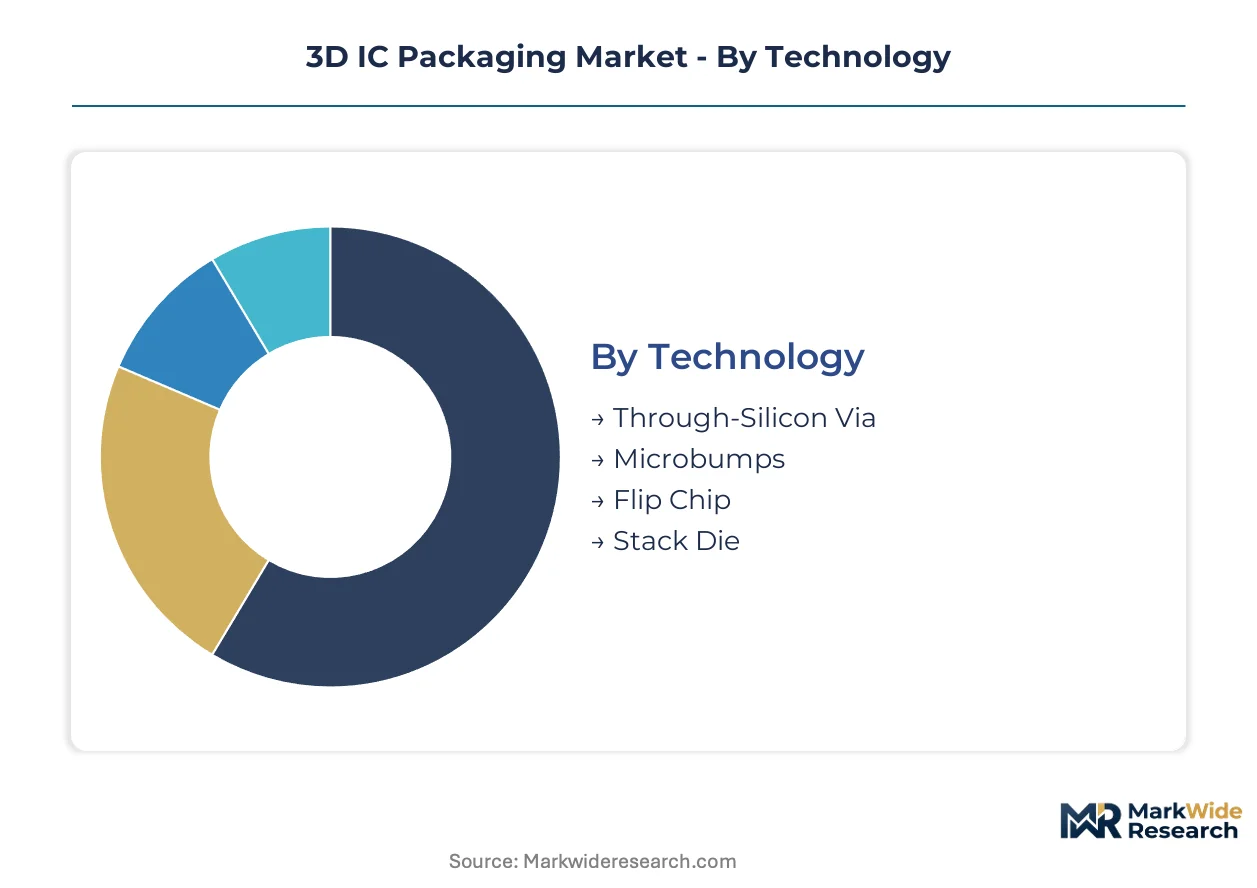
3D IC packaging configurations diverge sharply in certification requirements and thermal performance envelopes. Segment selection determines which foundry partnerships, substrate suppliers, and regulatory pathways become accessible to device architects.
Technology:
Certification burdens vary by interconnect density — automotive-qualified TSV processes demand IATF 16949 traceability, while consumer-grade microbump flows operate under ISO 9001 alone.
- Through-Silicon Via:Vertical copper-filled vias pierce silicon substrates to enable die-to-die stacking at sub-50-micron pitch. Data center AI accelerators in Taiwan and the United States are absorbing the majority of high-bandwidth memory-logic TSV capacity as hyperscalers expand training cluster deployments.
- Microbumps:Solder-based interconnects at 40-micron pitch and above bridge stacked dies through thermocompression bonding. Mid-range smartphone application processors in South Korea and China concentrate procurement, though hybrid bonding is displacing microbumps in flagship tiers.
- Flip Chip:Peripheral array bumps connect dies directly to organic substrates without wirebond loops. Automotive radar modules in Germany require extended thermal cycling validation under AEC-Q100 stress test guidelines.
- Stack Die:Wirebonded memory-on-logic configurations using adhesive die attach films. Cost-sensitive IoT endpoints in India leverage this mature approach where bandwidth requirements stay below 100 GB/s.
Through-Silicon Via sits at the top of the volume ranking, with hybrid bonding displacing microbumps fastest in premium tiers.
End User:
Application-specific qualification timelines stretch from six months for consumer modules to thirty-six months for powertrain electronics, reshaping supplier cash flow profiles.
- Consumer Electronics:Smartphones, tablets, and wearables drive high-volume demand for thin profile memory stacking. Apple and Samsung flagship launches in Q3 cycles create predictable capacity crunches at OSATs.
- Computing:GPU and AI training accelerators command premium pricing for HBM3E integration. NVIDIA and AMD procurement decisions in Taiwan and the United States determine CoWoS capacity allocation across the industry.
- Automotive:ADAS sensor fusion and domain controller modules require ISO 26262 functional safety certification. German OEM qualification cycles for lidar-on-chip packaging extend through 2025 for volume production.
- Telecommunications:5G baseband processors and mmWave antenna-in-package modules. Ericsson and Nokia specifications in Finland and Sweden emphasize hermetic sealing for outdoor deployment.
Computing commands the highest revenue per unit, with Automotive expanding most quickly once qualification gates clear.
Form Factor:
Package footprint constraints dictate substrate layer count and thermal solution mass, creating tradeoffs between z-height and lateral area.
- System in Package:Heterogeneous integration of logic, memory, and passive components within a single molded body. Apple SiP designs for smartwatches in California set miniaturization benchmarks.
- Package on Package:Memory packages stacked atop application processors through BGA interconnect. Low-cost smartphone platforms in India and Vietnam rely on this approach for bill-of-materials control.
- Wafer Level:Redistribution layers and bumps applied before singulation, eliminating substrate costs. Image sensor modules in Japan leverage fan-out wafer-level packaging for camera module thickness reduction.
- Chip Scale:Package area within 1.2x of die dimensions for portable electronics. Hearing aid manufacturers in Denmark specify chip-scale BGA for in-ear device comfort.
System in Package leads in functional density, with Wafer Level gaining share fastest in image sensor applications.
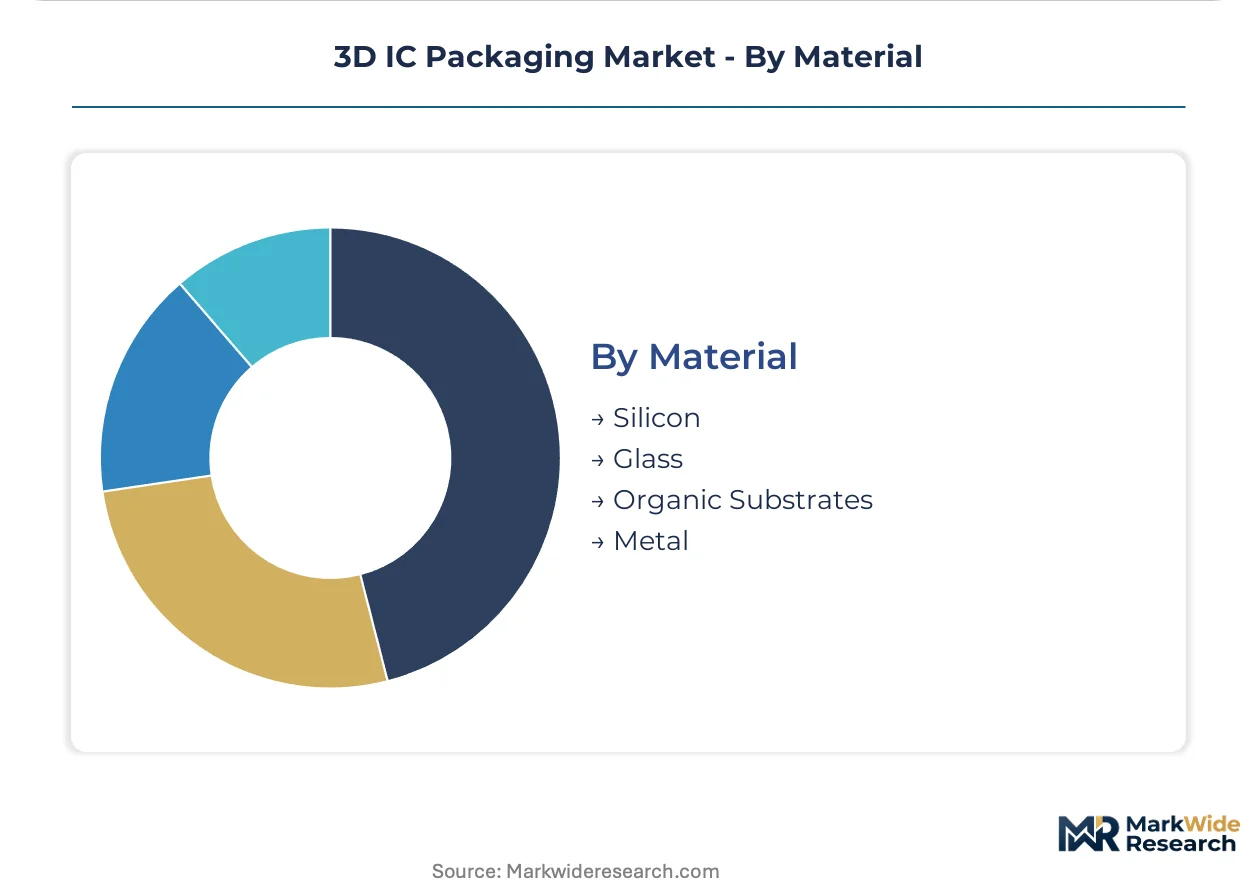
Material:
Coefficient of thermal expansion matching between die and substrate determines underfill crack resistance and long-term reliability.
- Silicon:Monolithic interposers and active base dies provide matched CTE with stacked logic. TSMC CoWoS-S flows in Taiwan use 65nm-node silicon interposers for reticle-size routing.
- Organic Substrates:ABF and BT resin-based build-up layers for cost-sensitive flip-chip and wirebond packages. Supply constraints from Japan and Taiwan resin suppliers are extending lead times.
- Glass:Emerging interposer material with tunable CTE and optical transparency for photonic integration. Intel and Corning development programs in Arizona target 2026 pilot production.
- Metal:Copper heat spreaders and lid assemblies for thermal management in high-power computing. Vapor chamber attachments in South Korean server designs address 500W+ socket power.
Silicon interposers dominate high-performance tiers, with Glass interposers climbing fastest in photonics-coprocessor prototypes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Taiwan's Hsinchu Science Park anchors the densest concentration of 3D IC packaging capacity globally, with foundry-integrated operations and dedicated OSAT complexes operating within a thirty-kilometer radius.
United States
Hyperscaler procurement of AI training accelerators drives demand for HBM-logic integration in Oregon and Arizona fabrication clusters. EPA facility permitting timelines shape cleanroom construction schedules for advanced packaging fabs. Intel's Arizona operations and NVIDIA's supply chain decisions in California concentrate high-bandwidth memory packaging decisions.
South Korea
Samsung Electronics' X-Cube technology roadmap dominates memory-centric 3D stacking for smartphone and server applications. MFDS chemical disclosure requirements govern epoxy mold compound selections for consumer electronics modules. Seoul-Pyeongtaek corridor houses vertically integrated DRAM-logic packaging capacity serving domestic and export demand.
Germany
Automotive OEM qualification cycles for ADAS sensor fusion modules extend through 2025, creating pipeline demand for ISO 26262-certified packaging. EU Chips Act subsidy frameworks prioritize cleanroom construction in Saxony and Bavaria. Infineon supply chain decisions in Munich and Dresden concentrate powertrain module packaging specifications.
Japan
ABF substrate supply from resin and copper foil suppliers experiences price pressure, extending lead times for build-up layer materials. METI semiconductor revitalization programs target advanced packaging capacity in Kyushu and Tohoku regions. Sony image sensor packaging in Nagasaki leverages fan-out wafer-level configurations for camera module miniaturization.
India
PLI scheme disbursements and state-level land allocations attract OSAT investment for mature-node wirebond and flip-chip configurations. BIS certification requirements govern import substitution for domestic electronics manufacturing. Gujarat and Karnataka industrial corridors concentrate emerging packaging capacity serving captive smartphone and IoT demand.
3D IC Packaging Market Competitive Environment
Global majors compete with regional champions across technology integration depth, with foundry-led packaging operations commanding premium positioning while independent OSATs anchor mid-tier volume. Market structure tilts toward consolidation at the high-performance tier where hybrid bonding equipment scarcity creates entry barriers. Three archetypes dominate: vertically integrated foundries controlling front-to-back processes, memory specialists with proprietary stacking roadmaps, and independent assemblers scaling across multiple interconnect nodes. Capacity expansion and strategic partnerships constitute the dominant competitive moves, with equipment co-development agreements and substrate supply alliances reshaping access to constrained inputs.
Within the foundry-integrated tier, Taiwan Semiconductor Manufacturing Company exemplifies captive packaging control through CoWoS and SoIC platforms. Samsung Electronics occupies a position as the dominant memory-centric stacker with its X-Cube technology roadmap. ASE Technology Holding anchors independent OSAT capacity across wirebond, flip-chip, and emerging 3D configurations. These three entities collectively represent the competitive poles around which supplier relationships and capacity allocation decisions revolve.
| Leading Market Players |
|---|
| ASE Technology Holding Co., Ltd. |
| JCET Group Co., Ltd. |
| Taiwan Semiconductor Manufacturing Company, Ltd. (TSMC) |
| Powertech Technology Inc. |
| United Microelectronics Corporation (UMC) |
| Samsung Electronics Co., Ltd. |
| Amkor Technology |
| Broadcom |
| Intel Corporation |
| Others |
Value Chain & Pricing Dynamics
REACH substance restrictions in Europe gate both qualified supply and premium-tier pricing access for 3D IC packaging flows, as ECHA candidate list updates force halogen-free reformulations that extend qualification timelines and concentrate pricing power among certified suppliers.
Pricing Analysis
Input-cost pass-through from ABF substrate resin and copper foil suppliers in Japan and Taiwan is compressing margins across mid-tier flip-chip and wirebond configurations. Three-tier pricing structure across automotive-certified, consumer-grade, and mature-node legacy tiers separates IATF 16949-qualified flows from ISO 9001-only production. Cost compression in consumer electronics modules is intensifying because build-up layer yield rates amplify material sensitivity. Smartphone OEMs in South Korea exhibit highest price sensitivity, while hyperscaler AI accelerator procurement in the United States shows lowest sensitivity due to performance-per-watt mandates.
Supply Chain Analysis
Certification and qualification gating through IATF 16949 and ISO 26262 is fragmenting supplier access for automotive modules, creating tiered supply availability that mirrors certification investment depth. Manufacturing concentrates in Taiwan, South Korea, and the United States, with Hsinchu Science Park and Seoul-Pyeongtaek corridor anchoring front-to-back integration. The supply chain draws from silicon interposers, ABF substrates, and die-to-wafer bonders as critical inputs. Single-source vulnerability around Applied Materials and Besi bonding equipment creates allocation risk for new entrants. Distribution runs through direct foundry relationships for AI accelerators and OSAT intermediaries for consumer volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
3D IC packaging functions as a stable compounder, with data center AI accelerator procurement providing steady demand visibility that supports capacity expansion returns across the analysis window.
For Market Incumbents: Deepen hybrid bonding equipment co-development agreements with Applied Materials and Besi to lock in allocation priority as tool scarcity extends delivery schedules. Expand captive substrate supply through backward integration into ABF resin partnerships in Japan, defending margin position against input cost volatility. Memory-centric stackers face displacement risk from foundry-led integration if CoWoS capacity allocation tightens further. For New Entrants and Emerging Players: Fabless AI chip designers represent the most penetrable channel partner type for independent OSATs seeking to bypass foundry packaging captivity. Target edge AI inference modules for smartphone and IoT endpoints, where low-power 3D stacking remains underpenetrated relative to data center volumes. Pursue automotive functional safety certification as a go-to-market angle, as IATF 16949 compliance creates premium positioning in powertrain and ADAS modules where German OEM qualification cycles are clearing. For Investors and Strategic Acquirers: Valuations sit cheapest among independent OSATs with automotive certification depth but limited hybrid bonding exposure, as the market discounts their terminal value against foundry-led integration trends. Long-term viability hinges on equipment access and substrate supply alliances over a multi-year horizon. Watch CoWoS capacity allocation decisions by TSMC as the inflection signal for OSAT margin compression or expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Bonding Equipment Co-Development | Secures tool allocation priority with Applied Materials and Besi as scarcity intensifies. |
| Automotive Certification Investment | Unlocks IATF 16949-gated supply agreements with Infineon and German OEMs. |
| Substrate Supply Backward Integration | Reduces ABF resin dependency on Japanese suppliers amid price volatility. |
| Edge AI Module Packaging Development | Captures smartphone and IoT volume as data center concentration peaks. |
| Direct Hyperscaler Relationship Formation | Bypasses OSAT intermediation for AWS, Azure, and Google Cloud AI accelerator flows. |
Study Parameters
Multiple input streams — primary interviews with packaging process engineers, substrate procurement leads, and hyperscaler silicon sourcing managers; secondary validation through SEMI equipment shipment data, EPA permitting records, and EU Chips Act disbursement filings — were reconciled through bottom-up capacity modeling and top-down demand triangulation. Foundry capex disclosures, OSAT revenue segmentations, and chemical supplier toxicological dossiers provided cross-reference points for supply-side assumptions.
Historical capacity utilization patterns were cross-referenced against panel input from equipment vendors and substrate suppliers to anchor growth trajectories across the projection horizon. Segmentation dimensions modeled include interconnect technology, end-user application, form factor configuration, and material substrate type. CAGRs were derived from installed capacity expansion schedules weighted against qualification timeline constraints. Industry-specific forecast inputs include die-to-wafer bonder delivery schedules and ABF substrate yield improvement curves.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EPA permitting velocity in the United States and ECHA substance list expansion in Europe. Forecasts reflect assumptions around hybrid bonding adoption rates and automotive qualification clearance timelines. A model refresh is warranted upon material change in EU Chips Act capital allocation disbursement schedules.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Packaging
Semiconductor Solder Flux Market
Semiconductor Packaging
Fan Out Packaging Market
Semiconductor Packaging
Embedded Die Packaging Market
Semiconductor Packaging
Global Semiconductor Equipment Packaging and Test Market
Semiconductor Packaging
Bonding Wire Packaging Market
Semiconductor Packaging
2.5D and 3D Semiconductor Packaging Market
Semiconductor Packaging
Through-Silicon via (TSV) IC Packaging Market
Semiconductor Packaging
Electronic Board Level Underfill and Encapsulation Material Market
Semiconductor Packaging
System in Package (SIP) Die Market
Semiconductor Packaging
Embedded Die Packaging Technology Market
Semiconductor Packaging
Microtube Box Market
Semiconductor Packaging
Semiconductor Packaging Material Market
Semiconductor Packaging
Multichip Package Market
Semiconductor Packaging
Global Semiconductor Packaging and Assembly Equipment Market
Semiconductor Packaging
2.5D IC Packaging Market
Semiconductor Packaging
Global Bare Die Shipping and Handling and Processing and Storage Market