
 System in Package (SIP) Die Market | 2026-2036
System in Package (SIP) Die Market Size, Share, and Industry Trends Forecast 2026-2036
System in Package (SIP) Die Market Insights
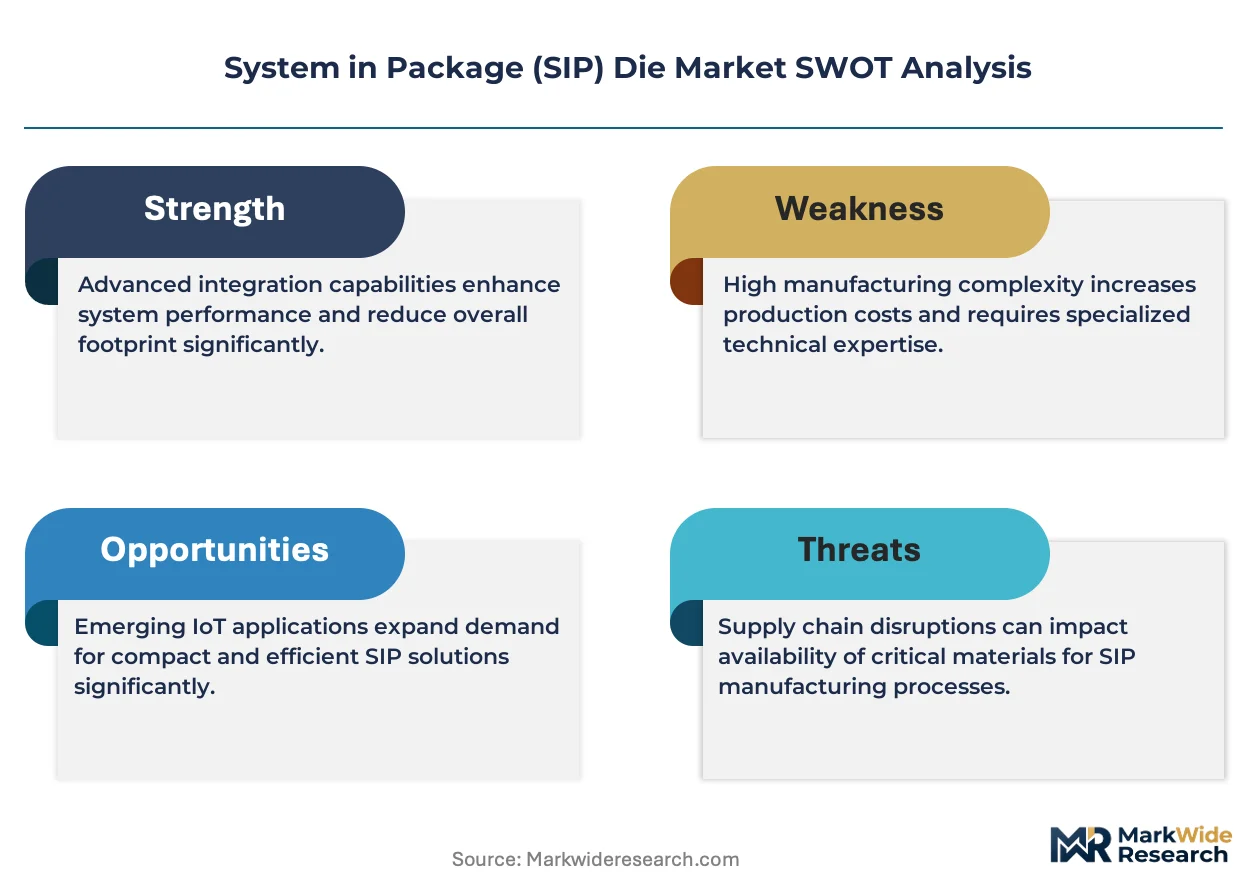
A capital-intensity divergence between foundry-integrated packagers and pure-play OSATs is rotating competitive investment toward 3D stacking and fan-out wafer-level platforms. ASE Group leverages captive bumping and testing infrastructure across Kaohsiung and Chungli to sustain cost leadership in high-volume RFIC SiP. Amkor Technology anchors North American automotive qualification pipelines through its Arizona and Korea facilities. Intel Corporation differentiates via embedded multi-die interconnect bridge technology that competes directly with conventional TSV approaches in AI accelerator packaging.
System in Package die refers to multiple semiconductor dies, passive components, and interconnect substrates integrated into a single compact module typically measuring under 10mm x 10mm, fabricated through processes including flip-chip bonding, wire bonding, and through-silicon via formation to achieve functional density unobtainable at monolithic scaling limits. RFIC and ASIC product types currently occupy the largest value share as 5G front-end modules and AI inference engines drive layer-count expansion. Automotive application demand is accelerating fastest among structural segments as ISO 26262 functional safety requirements push suppliers toward pre-validated SiP subsystems rather than discrete component sourcing.
EPA hazardous substance rules and REACH SVHC restrictions are tightening material compliance burdens for mold compounds and lead-free solder alloys used in SiP assembly. FDA oversight of wireless medical devices incorporating RFIC SiP modules adds secondary validation layers for healthcare-bound suppliers. IEEE 802.11be and 3GPP Release 18 standards evolution will force stakeholders to monitor spectrum allocation decisions that directly dictate RFIC SiP die count and antenna-in-package complexity.
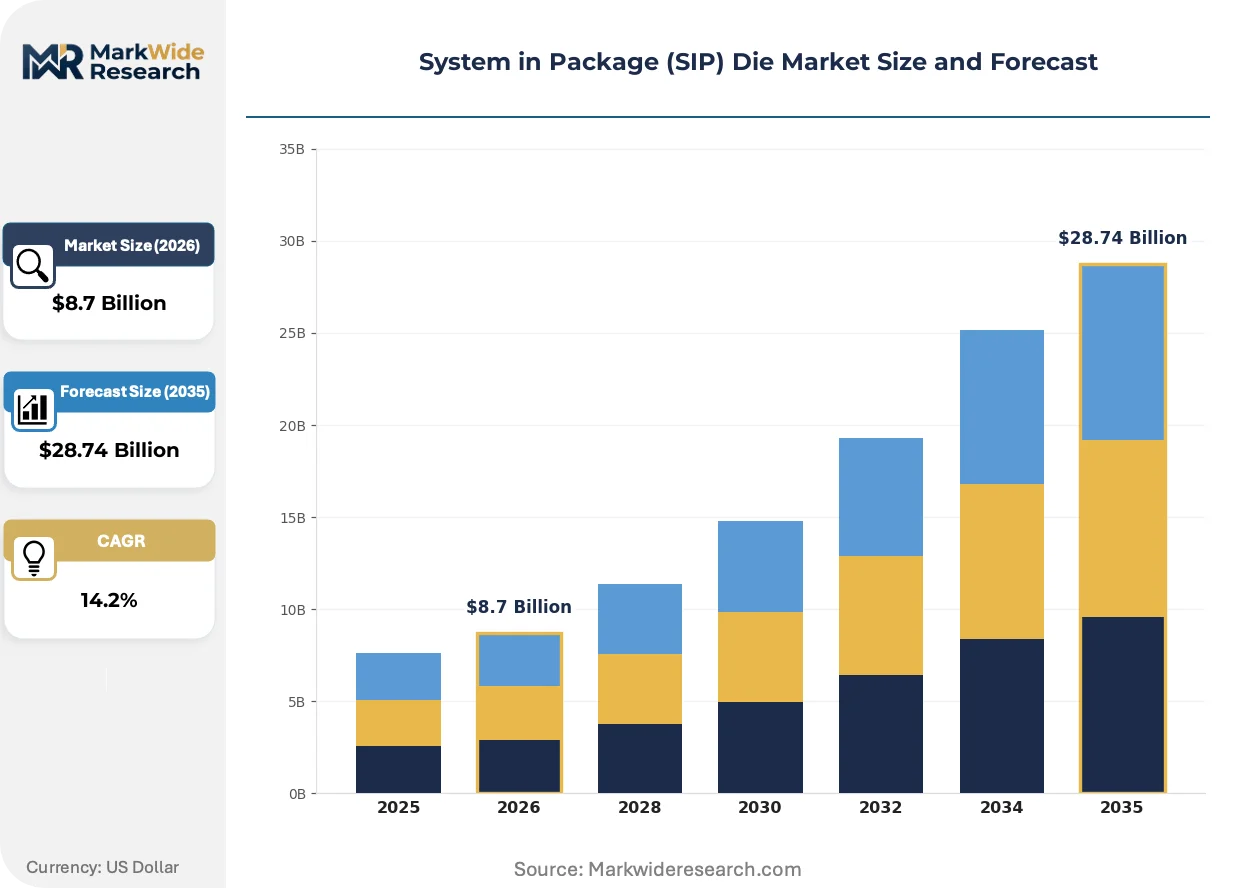
Market Dynamics
5G mmWave antenna-in-package complexity and AI accelerator die-stacking requirements are forcing heterogeneous integration roadmaps to accelerate faster than monolithic scaling economics can sustain.
Growth Catalysts
- 5G Sub-6GHz Module Proliferation:Smartphone OEMs are expanding SiP die procurement for front-end modules as carrier aggregation schemes multiply RF chain component counts beyond discrete assembly feasibility.
- EU Chips Act Investment:European packaging capacity is redirecting toward advanced heterogeneous integration with dedicated funding streams for fan-out wafer-level processing infrastructure.
- Automotive ISO 26262 Pre-Validation:Functional safety mandates are pushing tier-one suppliers toward pre-validated SiP subsystems rather than discrete component sourcing for ADAS compute modules.
Market Restraints
- TSV Cost Structure:Through-silicon via formation consumes disproportionate capital per wafer start compared to wire-bond alternatives, compressing margins at volume tiers below automotive qualification thresholds.
- Taiwan Supply Concentration:Backend dominance by ASE Group and TSMC creates geographic risk concentration that OEMs cannot diversify without multi-year qualification timelines.
- EMI Shielding Material Volatility:Silver-filled epoxy and sputtered copper prices fluctuate with precious metals markets, destabilizing mold compound cost forecasting for RFIC SiP producers.
Strategic Opportunities
- India PLI Scheme Capture:Electronics manufacturing incentives are attracting OSATs to establish packaging facilities serving domestic smartphone assembly and export markets.
- Wireless Medical Device Integration:FDA oversight pathways for RFIC SiP modules in implantable monitors and wearable diagnostics create premium pricing tiers for healthcare-qualified suppliers.
- Fan-Out Wafer-Level Convergence:Embedded bridge die and redistribution layer process integration is enabling sub-2µm line/space routing density previously exclusive to silicon interposers.
Industry Challenges
- Multi-Physics Simulation Talent Scarcity:Electromagnetic-thermal-mechanical co-design for antenna-in-package modules requires skill sets concentrated at a handful of research institutions and incumbent packagers.
- REACH SVHC Compliance Latency:Mold compound reformulation to eliminate restricted substances extends qualification cycles by 12-18 months for automotive and medical grade SiP products.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | System in Package (SIP) Die Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: RFIC, ASIC, MEMS, Power IC Application: Consumer Electronics, IoT Devices, Automotive, Telecommunications End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Distributors Technology: 3D Packaging, TSV, SiP, Embedded Die |
| Companies Covered | ASE Group, Amkor Technology, Intel Corporation, Samsung Electronics, Texas Instruments, STMicroelectronics, Qualcomm Technologies, ChipMOS Technologies, NXP Semiconductors, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
System in Package (SIP) Die Market Trends and Innovations
Advanced packaging architectures are compressing traditional die-shrink timelines while regulatory material restrictions and buyer consolidation are reshaping supplier qualification hierarchies.
Embedded multi-die interconnect bridge technology is supplanting conventional TSV approaches in AI accelerator packaging by eliminating deep silicon etching costs while maintaining sub-100µm die-to-die pitch. Hyperscale data center operators are adopting this architecture for training chiplet arrays. The shift is compressing capital deployment timelines for advanced packaging capacity expansion.
EPA hazardous substance rules and REACH SVHC restrictions are tightening material compliance burdens for mold compounds and lead-free solder alloys used in SiP assembly. Suppliers must maintain dual formulation stocks for medical versus consumer grade products. Healthcare-bound suppliers face secondary FDA validation layers that extend time-to-revenue for new SiP configurations.
Automotive tier-one procurement is consolidating qualified vendor lists to pre-validated SiP subsystem suppliers capable of ISO 26262 traceability. Discrete component sourcing is retreating to non-safety-critical modules. Germany and Japan anchor this consolidation pattern through KBA and METI safety framework alignment.
System in Package (SIP) Die Market Segmentation
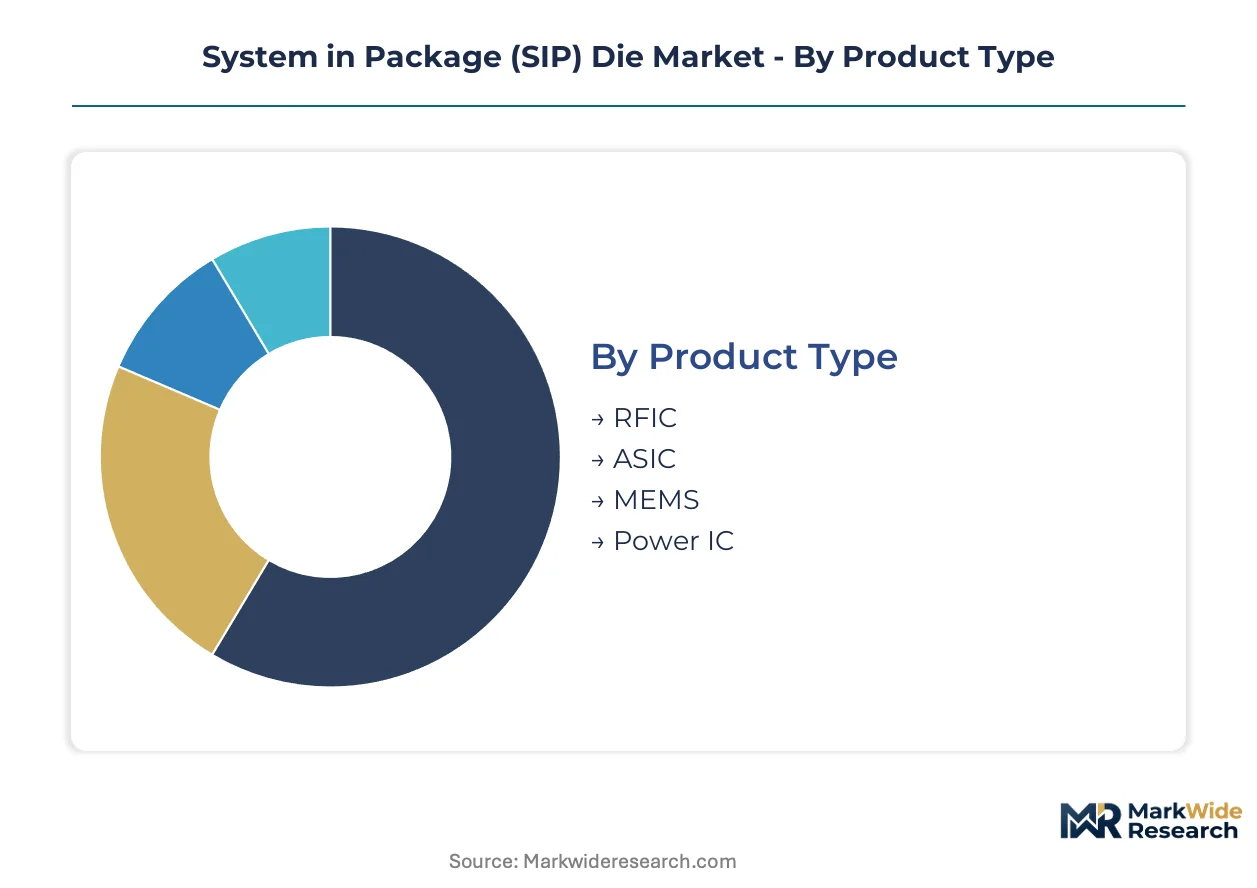
SiP die procurement channels diverge sharply by segment—consumer electronics flows through high-volume OSATs while automotive and medical routes demand pre-qualified subsystem vendors with traceability documentation. Understanding these channel dynamics separates pricing power from commodity margin compression.
Product Type:
Channel mix varies dramatically—RFIC modules move through smartphone OEM direct procurement while ASIC and MEMS segments route through specialized distributors serving industrial and medical accounts.
- RFIC:Front-end modules integrate PA, LNA, switch, and filter dies with antenna-in-package configurations for 5G sub-6GHz and mmWave bands. Smartphone OEMs in Taiwan and South Korea dominate procurement volume as carrier aggregation schemes multiply RF chain complexity beyond discrete assembly feasibility. REACH SVHC compliance for mold compounds extends automotive and medical qualification cycles.
- ASIC:AI inference engines and cryptocurrency mining accelerators drive layer-count expansion with chiplets arranged in 2.5D interposer or embedded bridge configurations. Hyperscale data center operators in the United States and China anchor demand concentration for training chiplet arrays with sub-100µm die-to-die pitch requirements.
- MEMS:Inertial sensors, microphones, and environmental sensors combine with ASIC dies in compact modules for wearable and automotive applications.
- Power IC:Voltage regulators and battery management circuits integrate passives for mobile and IoT power delivery subsystems.
RFIC dominates installed base. ASIC is where expansion concentrates.
Application:
Cost tier stratification separates consumer-grade volume plays from automotive and medical premium pricing tiers requiring ISO 26262 and FDA validation layers.
- Consumer Electronics:Smartphones, tablets, and wearables drive the highest die volumes with shortest product lifecycles and aggressive cost-down trajectories. Taiwan-based OSATs capture the majority of RFIC SiP assembly through captive bumping and testing infrastructure.
- Automotive:ADAS compute modules and battery management systems require pre-validated SiP subsystems with full traceability under ISO 26262 functional safety mandates. Germany's KBA and Japan's METI safety frameworks push tier-one suppliers away from discrete component sourcing toward qualified subsystem vendors.
- IoT Devices:Industrial sensors and smart home equipment combine wireless connectivity with edge processing in ultra-compact form factors.
- Telecommunications:Baseband processing and optical transceivers demand high-reliability packaging for infrastructure deployment cycles.
Consumer electronics commands volume share. Automotive is climbing the fastest on safety-driven specification upgrades.
End User:
Customer type determines margin structure—OEM direct relationships sustain pricing power while distributor channels compress margins through inventory risk transfer.
- OEMs:Apple, Samsung, and automotive tier-ones negotiate multi-year die supply agreements with volume commitments and technology roadmapping clauses. Direct procurement concentrates in Taiwan, South Korea, and the United States for smartphone and data center applications.
- Tier-1 Suppliers:Continental, Bosch, and Denso qualify SiP subsystems for ADAS and powertrain modules under automotive safety frameworks.
- Aftermarket Providers:Repair and refurbishment channels serve extended lifecycle equipment in industrial and automotive segments.
- Distributors:Arrow, Avnet, and regional specialists carry inventory for mid-volume industrial and medical accounts with fragmented demand patterns.
OEMs dominate procurement value. Tier-1 suppliers represent the steepest expansion trajectory as automotive SiP adoption accelerates.
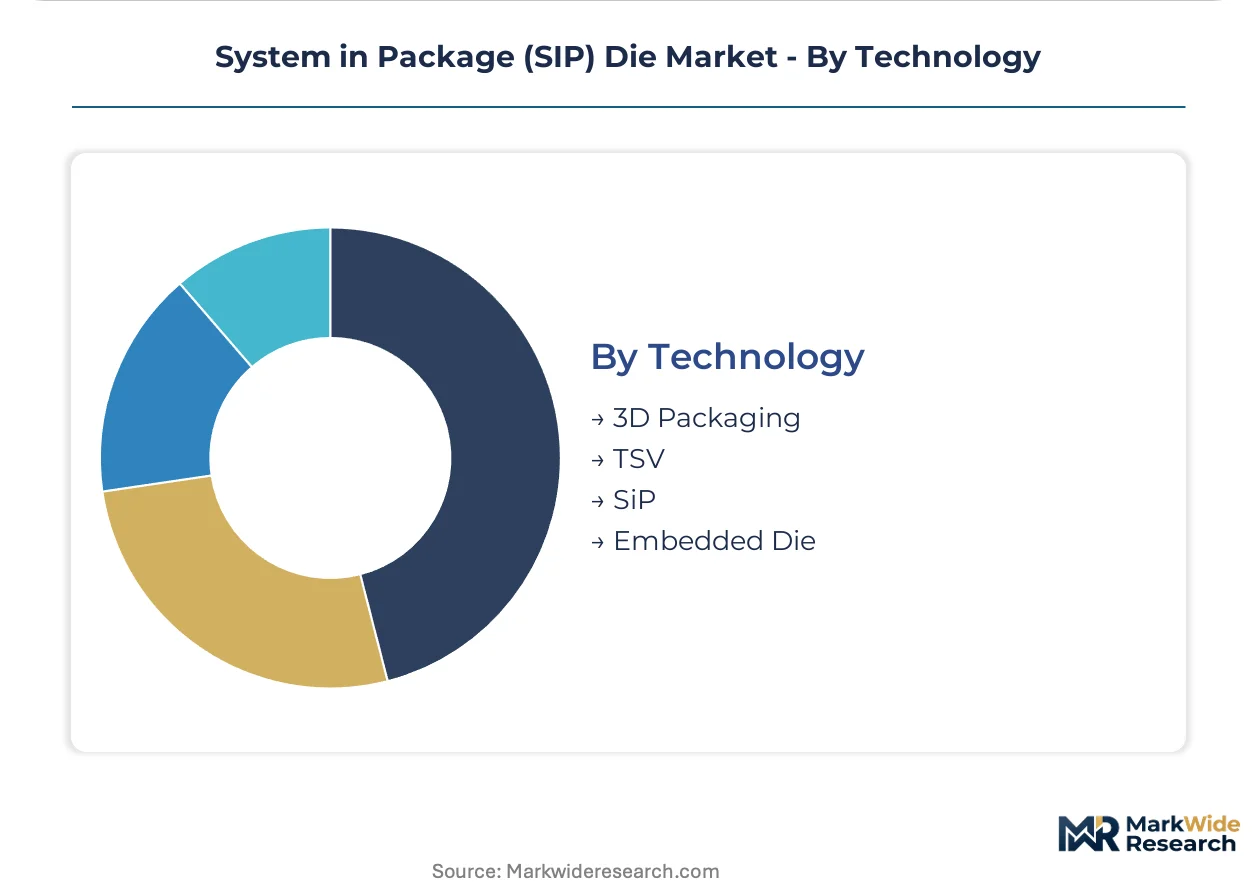
Technology:
Maturity curves separate established wire-bond and laminate platforms from emerging fan-out and embedded die processes requiring fresh capital deployment.
- 3D Packaging:Die stacking with microbumps and hybrid bonding achieves vertical integration density for memory-logic combinations and image sensors. TSMC and Samsung anchor capacity concentration in Taiwan and South Korea.
- TSV:Through-silicon via formation enables true 3D interconnect with shortest electrical paths for high-bandwidth memory and AI accelerators. Capital intensity per wafer start limits adoption to automotive qualification thresholds and above.
- SiP:Conventional laminate-based system-in-package with wire-bond and flip-chip assembly serves cost-optimized consumer and IoT volumes.
- Embedded Die:Fan-out wafer-level processing with die embedded in molded reconstituted wafers enables sub-2µm line/space routing density. EU Chips Act funding targets European capacity expansion for this platform.
Conventional SiP dominates unit shipments. Embedded die is gaining share fastest on fan-out wafer-level convergence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Taiwan while procurement risk accumulates in Germany. Taiwan-based ASE Group and TSMC backend operations command premium margins through captive bumping infrastructure. German automotive tier-ones face qualification bottlenecks that compress their supplier negotiation leverage.
United States
Hyperscale data center operators drive AI accelerator die-stacking demand with sub-100µm pitch requirements. FDA oversight of wireless medical devices adds secondary validation layers for healthcare-bound RFIC SiP modules. Intel Corporation's Arizona facilities anchor North American automotive qualification pipelines for embedded multi-die interconnect bridge technology.
Taiwan
ASE Group leverages captive bumping and testing infrastructure across Kaohsiung and Chungli to sustain cost leadership in high-volume RFIC SiP. The island's backend dominance creates geographic risk concentration that OEMs cannot diversify without multi-year qualification timelines. TSMC's advanced packaging capacity serves smartphone OEMs in South Korea and China with 3D stacking for 5G mmWave antenna-in-package modules.
South Korea
Samsung Electronics integrates memory-logic combinations through hybrid bonding for image sensor and AI training chiplet arrays. The country's smartphone OEMs dominate procurement volume for 5G sub-6GHz front-end modules as carrier aggregation schemes multiply RF chain complexity. Seoul-based packaging operations compete directly with Taiwanese OSATs on fan-out wafer-level processing density.
Germany
Automotive tier-one suppliers consolidate qualified vendor lists toward pre-validated SiP subsystems under KBA safety framework alignment. ISO 26262 functional safety mandates push Continental and Bosch away from discrete component sourcing for ADAS compute modules. Bavaria-based automotive electronics clusters face REACH SVHC compliance latency that extends mold compound qualification cycles by 12-18 months.
Japan
METI safety frameworks align with German KBA standards to drive automotive SiP subsystem pre-validation. Inertial sensor and microphone MEMS modules combine with ASIC dies for wearable applications under domestic OEM procurement. Tokyo and Osaka industrial corridors concentrate packaging R&D for electromagnetic-thermal-mechanical co-design talent scarce across the broader industry.
System in Package (SIP) Die Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the SiP die market. Foundry-integrated packagers concentrate advanced heterogeneous integration capacity while pure-play OSATs dominate high-volume consumer electronics flows. Three archetypes define competitive positioning: captive backend divisions of IDMs, independent packaging specialists with automotive qualification pipelines, and foundry-integrated advanced packaging units serving AI accelerator demand. M&A activity targets fan-out wafer-level capability gaps while capacity expansion concentrates in Taiwan and South Korea.
Among Taiwan-based packaging specialists, ASE Group and ChipMOS Technologies occupy positions within the independent OSAT tier serving smartphone OEM direct procurement. Intel Corporation represents the IDM-integrated archetype with embedded bridge technology competing against conventional TSV approaches. These three companies exemplify the technology-cost divergence: ASE Group anchors cost-optimized high-volume RFIC assembly, Intel Corporation commands premium positioning in AI accelerator packaging, and ChipMOS Technologies sits within the mid-tier specialist segment.
| Leading Market Players |
|---|
| ASE Group |
| Amkor Technology |
| Intel Corporation |
| Samsung Electronics |
| Texas Instruments |
| STMicroelectronics |
| Qualcomm Technologies |
| ChipMOS Technologies |
| NXP Semiconductors |
| Others |
Pricing and Supply Chain Analysis
Twenty-six-week qualification timelines for automotive-grade SiP modules compress buyer negotiation leverage while amplifying pricing power for pre-certified suppliers in Taiwan and South Korea. This lead-time rigidity concentrates margin capture among incumbent packagers with captive bumping infrastructure, forcing OEMs into multi-year offtake commitments that insulate suppliers from spot-market volatility.
Pricing Analysis
Configured-to-order pricing for automotive and medical SiP modules commands a substantial premium over standard consumer-grade catalog pricing, with ISO 26262 and FDA validation layers creating certification-grade tiers. Contract-based long-term offtake agreements dominate high-volume smartphone procurement, while project-based pricing persists in low-volume industrial and medical segments. Price differentiation stems from functional safety certification level and geographic delivery cost, with automotive tier-ones least price-sensitive due to traceability mandates and consumer electronics OEMs most sensitive due to aggressive cost-down trajectories. Cost compression in RFIC SiP for 5G sub-6GHz modules is intensifying as smartphone OEMs consolidate vendor lists and demand annual price reductions.
Supply Chain Analysis
Container availability constraints on Asia-North America trade lanes have elevated inbound logistics costs for mold compound and lead-free solder alloy shipments, compressing margins at pure-play OSATs without captive material stocks. Supply concentrates in Taiwan, South Korea, and the United States, with ASE Group and TSMC backend operations anchoring high-volume RFIC assembly. Raw material dependencies center on silver-filled epoxy mold compounds, sputtered copper EMI shielding materials, and ABF substrate laminates. Single-source vulnerability around Taiwan-based bumping and testing infrastructure creates geographic risk concentration that OEMs cannot diversify without multi-year qualification timelines. Distribution runs through direct OEM procurement for smartphone and data center volumes, while specialized distributors serve fragmented industrial and medical accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
System in Package die adoption sits in early-cycle expansion as 5G mmWave antenna-in-package complexity and AI accelerator die-stacking requirements outpace monolithic scaling economics, with automotive functional safety mandates accelerating pre-validated subsystem procurement.
For Market Incumbents: Fortify automotive qualification pipelines by expanding ISO 26262 traceability documentation and captive bumping capacity in Taiwan and South Korea to defend against emerging fan-out wafer-level specialists. Deepen backward integration into ABF substrate supply and EMI shielding material formulation to offset silver-price volatility and REACH SVHC compliance latency that extends competitor qualification cycles. For New Entrants and Emerging Players: Post-qualification technical support gaps in mid-volume industrial and wireless medical device segments offer service-layer differentiation opportunities against high-volume OSATs with standardized offerings. Target India's PLI scheme electronics manufacturing incentives to establish packaging facilities serving domestic smartphone assembly and export markets, leveraging government subsidy structures to compress capital deployment timelines relative to greenfield investments in established hubs. For Investors and Strategic Acquirers: Carve-out targets emerge from IDM captive packaging divisions seeking to monetize non-core backend assets and automotive-qualified mid-tier OSATs with underutilized fan-out wafer-level capacity. Long-term viability favors suppliers with dual certification in ISO 26262 automotive and FDA medical device pathways, as convergence between ADAS and healthcare monitoring applications accelerates. Monitor EU Chips Act funding disbursement velocity as an inflection indicator for European packaging capacity expansion and competitive intensity in embedded die processing.| Strategic Initiative | Industry Significance |
|---|---|
| Fan-Out Wafer-Level Capacity Expansion | EU Chips Act funding accelerates European packaging infrastructure for heterogeneous integration roadmaps. |
| Automotive Safety Certification Investment | ISO 26262 pre-validation opens ADAS compute module procurement to tier-one suppliers consolidating vendor lists. |
| Hybrid Bonding Technology Licensing | Memory-logic integration for AI training chiplet arrays commands premium positioning in hyperscale data center supply chains. |
| India PLI Scheme Facility Establishment | Domestic smartphone assembly incentives attract OSATs serving export markets with lower labor cost structures. |
| REACH-Compliant Material Formulation | Mold compound reformulation eliminates SVHC substances for automotive and medical grade product qualification. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with packaging engineering directors, automotive tier-one procurement managers, semiconductor equipment specialists, and regulatory compliance officers; and secondary validation against SEC filings, SEMI equipment spending reports, EU Chips Act funding disclosures, and REACH SVHC substance restriction updates. Bottom-up triangulation across OSAT revenue disclosures and top-down cross-checks against smartphone OEM bill-of-materials estimates calibrated market sizing.
Across the analysis window, the forecasting framework modeled volume and value trajectories by product type, application segment, end-user channel, and technology platform, with additional granularity for certification-grade tiers distinguishing automotive ISO 26262 from consumer-grade specifications. CAGRs derived from segment-level growth rate distributions weighted by base-year revenue shares, incorporating inputs from 5G subscriber penetration curves and AI accelerator die-count expansion in hyperscale data center capex plans.
Forecasts assume regulatory continuity in EU REACH substance restrictions and FDA medical device oversight; material policy shifts in SVHC classification or wireless device emission standards would require re-modeling. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Packaging
System in Package (Sip) Technology Market
Semiconductor Packaging
Ceramic IC Packages Market
Semiconductor Packaging
Wafer Level Packaging (WPL) Market
Semiconductor Packaging
Chip Carrier Socket Market
Semiconductor Packaging
Bonding Wire Packaging Market
Semiconductor Packaging
Asia Pacific LED Packaging Market
Semiconductor Packaging
3D IC Packaging Market
Semiconductor Packaging
Flip-Chip COB Technology Market
Semiconductor Packaging
Global MEMS Packaging Market
Semiconductor Packaging
Embedded Die Packaging Technology Market
Semiconductor Packaging
Electronic Board Level Underfill and Encapsulation Material Market
Semiconductor Packaging
3D IC and 2.5D IC Packaging Market
Semiconductor Packaging
Memory Packaging Market
Semiconductor Packaging
Wafer Carrier Boxes Market
Semiconductor Packaging
Microtube Box Market
Semiconductor Packaging
IC Packaging and Testing Market