
 Multichip Package Market | 2026-2036
Multichip Package Market Size, Share, and Industry Trends Forecast 2026-2036
Multichip Package Market Analysis
High-density heterogeneous integration is collapsing the historical cost gap between discrete and packaged solutions. Samsung Electronics leverages its captive foundry-to-OSAT pipeline to dominate advanced 3D packaging for memory-logic combinations. Taiwan Semiconductor Manufacturing Company anchors leading-edge CoWoS capacity, while Amkor Technology competes through geographic diversification across Southeast Asia and North America.
A multichip package combines two or more semiconductor dies within a single substrate or interposer using flip-chip, wire bond, or through-silicon via interconnects, achieving higher bandwidth and lower power than equivalent discrete implementations. System-in-Package configurations lead volume shipments for mobile and IoT applications, whereas 3D packaging and heterogeneous integration capture the fastest expansion as data center AI accelerators demand massive die-to-die bandwidth. Wire bond remains mature and cost-optimized for automotive and industrial reliability requirements, concentrating margin pools in automotive-grade flip-chip and embedded die segments.
REACH and RoHS frameworks in Europe restrict hazardous substances in packaging substrates and mold compounds, while FDA and ISO 13485 standards govern healthcare device qualification timelines. Taiwan's Industrial Development Bureau and South Korea's K-Battery/K-Semiconductor strategies channel subsidies toward advanced packaging R&D, shaping where capacity localizes. Stakeholders must monitor which regulatory jurisdictions certify automotive functional safety standards fastest, as this determines qualification pathways for next-generation driver-assistance compute modules.
Market Dynamics
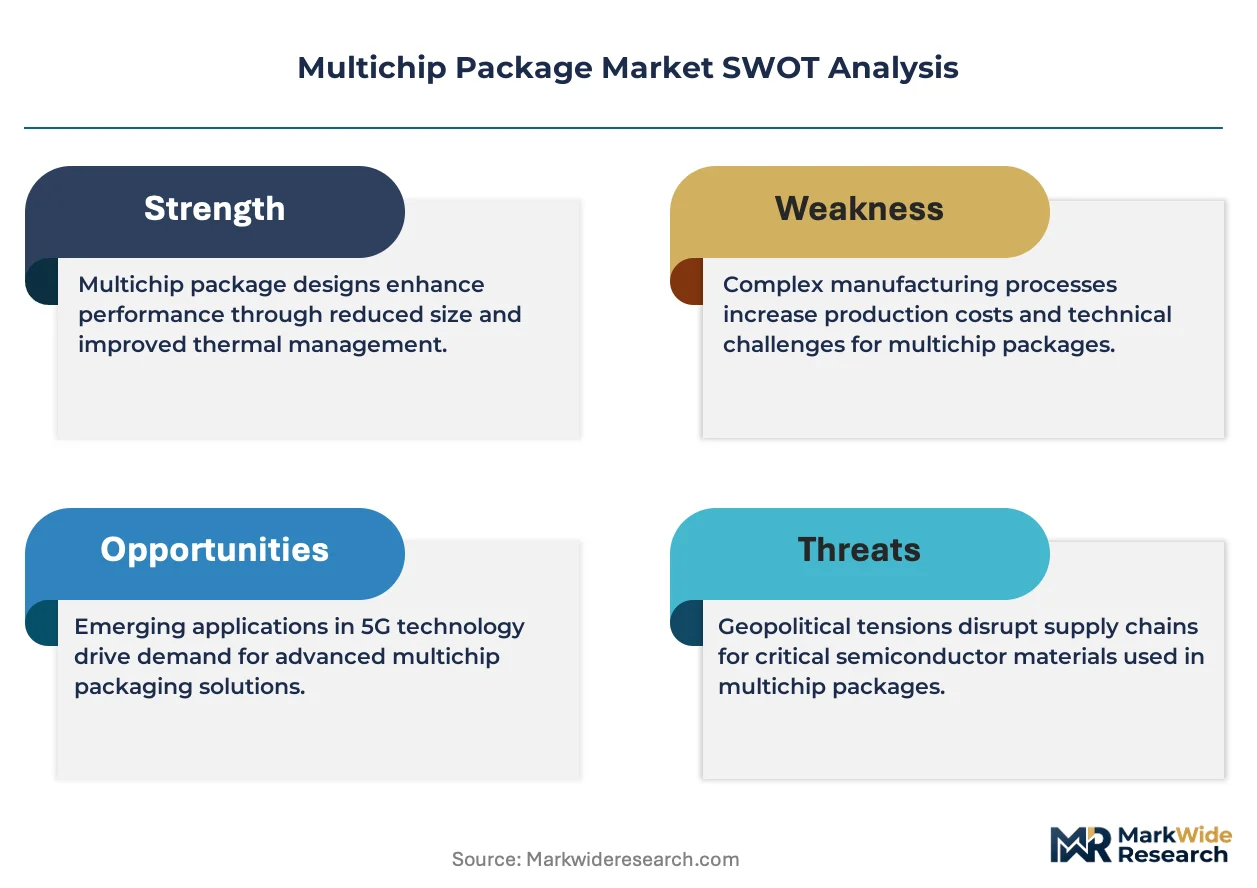
Heterogeneous integration is compressing the traditional boundary between front-end wafer fabrication and back-end packaging, forcing capital reallocation toward interposer capacity and advanced substrate technologies. Foundries now capture margin pools historically reserved for OSATs, while automotive functional-safety requirements extend qualification timelines.
Growth Catalysts
- Advanced Driver-Assistance Systems:Automotive OEMs mandate denser compute integration for LiDAR fusion and neural-network inference, pulling high-bandwidth memory-logic combinations into vehicle architectures. NHTSA functional-safety standards accelerate automotive-grade packaging qualification.
- EU Chips Act capital flows:Industrial policy redirects subsidy streams toward domestic packaging capacity expansion across Germany, France, and Italy, reducing import dependency for critical semiconductor substrates.
- Through-silicon via scaling:Micro-bump pitch reduction below 40 micrometers enables 3D stacking of logic dies with HBM cubes, collapsing interconnect energy-per-bit versus traditional PCB routing.
Market Restraints
- Organic substrate supply concentration:ABF substrate manufacturing concentrates among Japanese suppliers, creating input bottlenecks for large-format interposers exceeding 100mm square.
- REACH substance restrictions:ECHA frameworks limit brominated flame retardants in mold compounds, forcing reformulation cycles that extend material qualification timelines by 12-18 months.
- Silicon interposer cost structure:300mm silicon interposers require leading-edge lithography capacity, pricing mid-volume AI accelerators out of CoWoS-class solutions.
Strategic Opportunities
- India semiconductor packaging:PLI scheme subsidies and Micron Technology's Gujarat assembly facility establish initial advanced packaging footprint for memory modules serving domestic data center demand.
- Glass core substrate convergence:Panel-level processing of glass interposers combines display-industry equipment with semiconductor patterning, enabling cost reduction for high-layer-count substrates.
- Healthcare device miniaturization:ISO 13485 certification pathways for implantable neuromodulators create premium pricing tiers for biocompatible System-in-Package configurations.
Industry Challenges
- Thermal-mechanical simulation expertise:Multi-physics modeling of warpage and solder-joint reliability requires scarce cross-trained engineers fluent in both materials science and finite-element analysis.
- Chiplets interoperability standards:UCIe specification gaps between foundry implementations force custom interface designs that fragment IP reuse across AMD, Intel, and ARM-based ecosystems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Multichip Package Market |
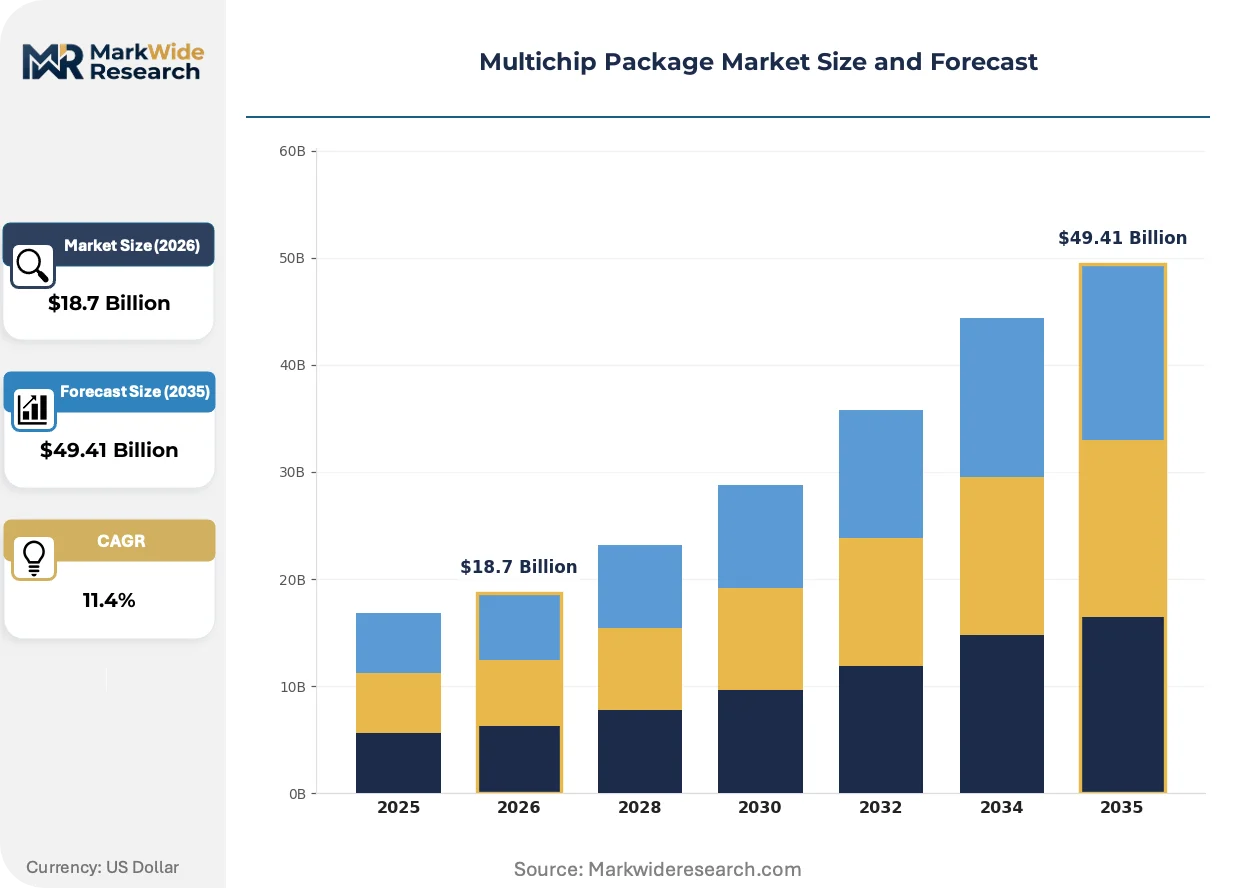
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flip Chip, Chip-on-Board, Wire Bond, System-in-Package Technology: 3D Packaging, Embedded Die, Advanced Interconnect, Heterogeneous Integration End User: Telecommunications, Consumer Electronics, Automotive, Healthcare Application: Data Centers, Mobile Devices, IoT Devices, RF Applications |
| Companies Covered | Infineon Technologies, Integrated Silicon Solution, Inc. (ISSI), Micron Technology, Macronix International, Winbond Electronics, Amkor Technology, Advanced Semiconductor Engineering, Samsung Electronics, Taiwan Semiconductor Manufacturing Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Multichip Package Market Emerging Trajectories
Chiplet-based architectures are fragmenting monolithic die designs into disaggregated functional blocks, redistributing value capture toward interconnect technologies and substrate suppliers. This decomposition shifts competitive advantage from transistor density to packaging integration sophistication.
Hybrid bonding is decomposing the traditional micro-bump interconnect stack by enabling direct copper-to-copper wafer bonding at sub-10 micrometer pitch. AI accelerator designers at cloud hyperscalers are adopting this for logic-to-memory stacking, compressing power consumption and form factor versus solder-based alternatives. The technology is decomposing the historical cost structure of 3D integration, enabling wider market access beyond leading-edge memory manufacturers.
EU AI Act risk-classification frameworks are mandating traceability and reliability documentation for high-risk AI hardware deployments. Packaging suppliers must now maintain die-level provenance records and thermal cycling test data across extended temperature ranges. Medical imaging and autonomous vehicle compute modules face the steepest compliance burdens, with German automotive Tier-1s accelerating supply chain audits ahead of enforcement timelines.
Consolidated procurement of packaging services is displacing fragmented multi-vendor sourcing as cloud hyperscalers negotiate direct capacity reservations with foundry-integrated OSATs. Device OEMs are ceding package design ownership to semiconductor partners in exchange for guaranteed CoWoS and EMIB allocation. This concentration is most visible in Taiwan, where NVIDIA and AMD direct allocation agreements with TSMC reshape traditional fabless-OSAT relationships.
Multichip Package Market Segmentation
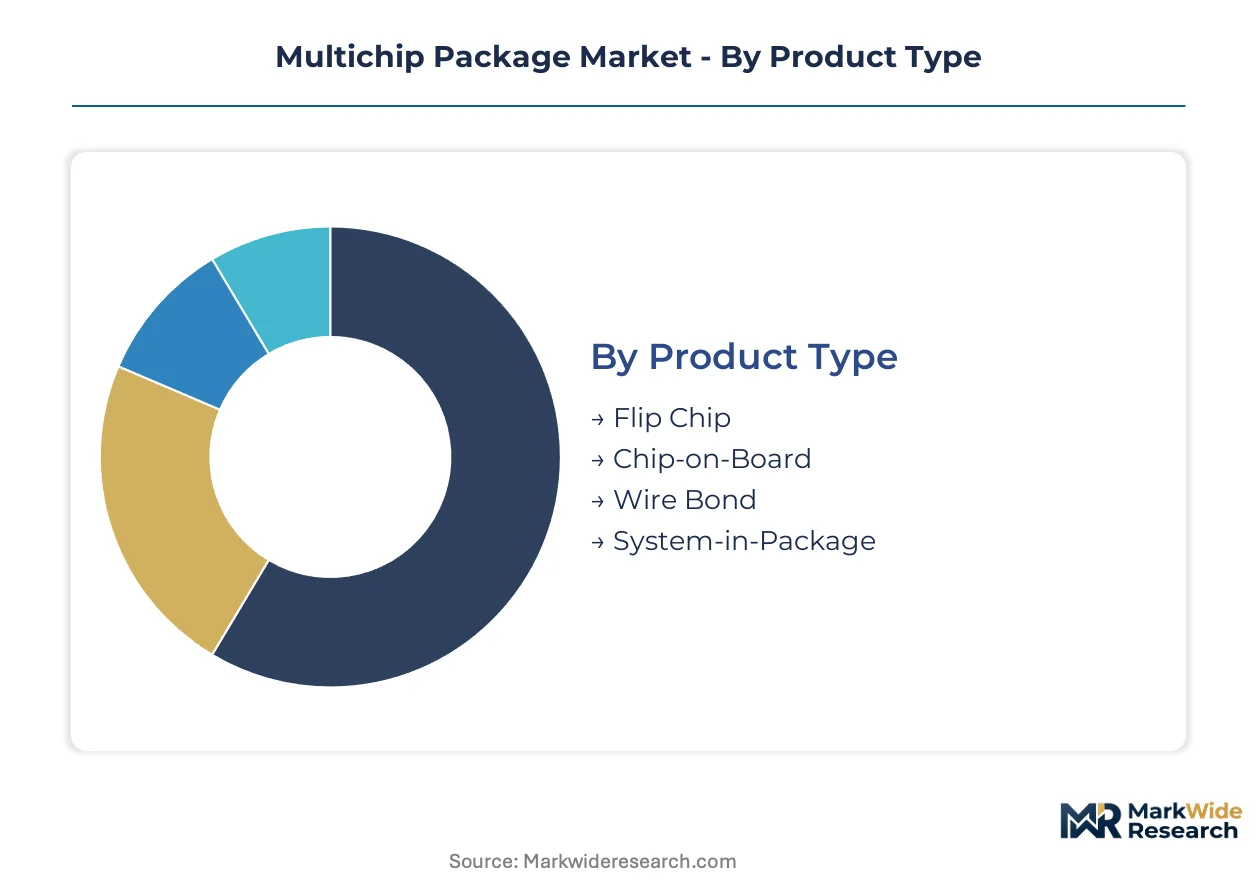
Multichip package architectures fragment across interconnect methods, vertical stacking approaches, and thermal-mechanical requirements. Each segment channels through distinct procurement pathways—foundry-direct for advanced 3D, OSAT-distributed for mature wire bond.
Product Type:
Channel mix varies sharply: flip-chip and SiP flow predominantly through foundry-integrated packaging houses, while wire bond and chip-on-board distribute across independent OSAT networks.
- Flip Chip:Solder micro-bump or copper-pillar interconnects attach dies directly to organic or ceramic substrates, eliminating wire loops. Data center AI accelerators in Taiwan and South Korea pull the majority of leading-edge flip-chip capacity for memory-logic combinations.
- Wire Bond:Gold or aluminum wires stitch die pads to substrate traces, remaining the cost floor for automotive sensor modules and industrial controllers. German automotive Tier-1s specify wire-bonded packages for engine-control units under KBA functional-safety audits.
- Chip-on-Board:Bare die mounts directly onto PCB with epoxy encapsulation, serving cost-constrained LED drivers and power management. Chinese consumer electronics OEMs dominate procurement for white-goods motor controllers.
- System-in-Package:Multiple dies integrate with passives and antennas under molded encapsulation, collapsing board area for smartphones and wearables. Apple and Samsung smartphone divisions account for the largest SiP allocation pools.
Wire bond dominates installed base. Flip chip is where expansion concentrates.
Technology:
Cost tier stratification separates qualification-intensive 3D packaging from mainstream embedded die, with heterogeneous integration commanding premium pricing for AI training clusters.
- 3D Packaging:Through-silicon vias stack logic and memory dies vertically, achieving sub-100 micrometer interconnect pitch. NVIDIA and AMD data center GPUs drive demand concentration for CoWoS-class 3D assembly in Hsinchu packaging corridors.
- Heterogeneous Integration:Chiplets from different process nodes combine on silicon interposers or organic bridges, optimizing cost-performance. Intel's Meteor Lake and AMD's Ryzen processors anchor this segment's volume ramp.
- Embedded Die:Active components bury within PCB or substrate cores, serving automotive radar modules and telecom base stations. European automotive suppliers qualify embedded die under AEC-Q100 stress-test protocols.
- Advanced Interconnect:Hybrid bonding and micro-bump scaling below 40 micrometer pitch enable next-generation bandwidth density. Samsung's X-Cube and TSMC's SoIC roadmaps define this segment's technical frontier.
Embedded die holds the broadest qualification footprint. Heterogeneous integration is climbing the fastest.
End User:
Application-specific reliability requirements segment procurement—automotive mandates 15-year operational life, while consumer electronics prioritize miniaturization over extended temperature cycling.
- Automotive:Advanced driver-assistance systems and electric powertrains require AEC-Q100 Grade 0 packages operating from -40°C to 150°C. LiDAR fusion modules pull high-bandwidth memory-logic combinations into vehicle architectures.
- Telecommunications:5G base stations and optical transceivers demand RF-optimized packaging with controlled impedance and thermal dissipation. Ericsson and Nokia infrastructure divisions specify flip-chip BGA for millimeter-wave beamforming.
- Consumer Electronics:Smartphone APUs, TWS earbuds, and smartwatch SoCs drive SiP miniaturization. Apple procures the majority of leading-edge fan-out wafer-level packaging for iPhone main processors.
- Healthcare:Implantable neuromodulators and diagnostic imaging systems require ISO 13485-certified biocompatible encapsulation. Medtronic and Boston Scientific anchor demand for hermetic ceramic packages in cardiac rhythm management.
Consumer electronics commands volume leadership. Automotive is where qualification complexity steepest.
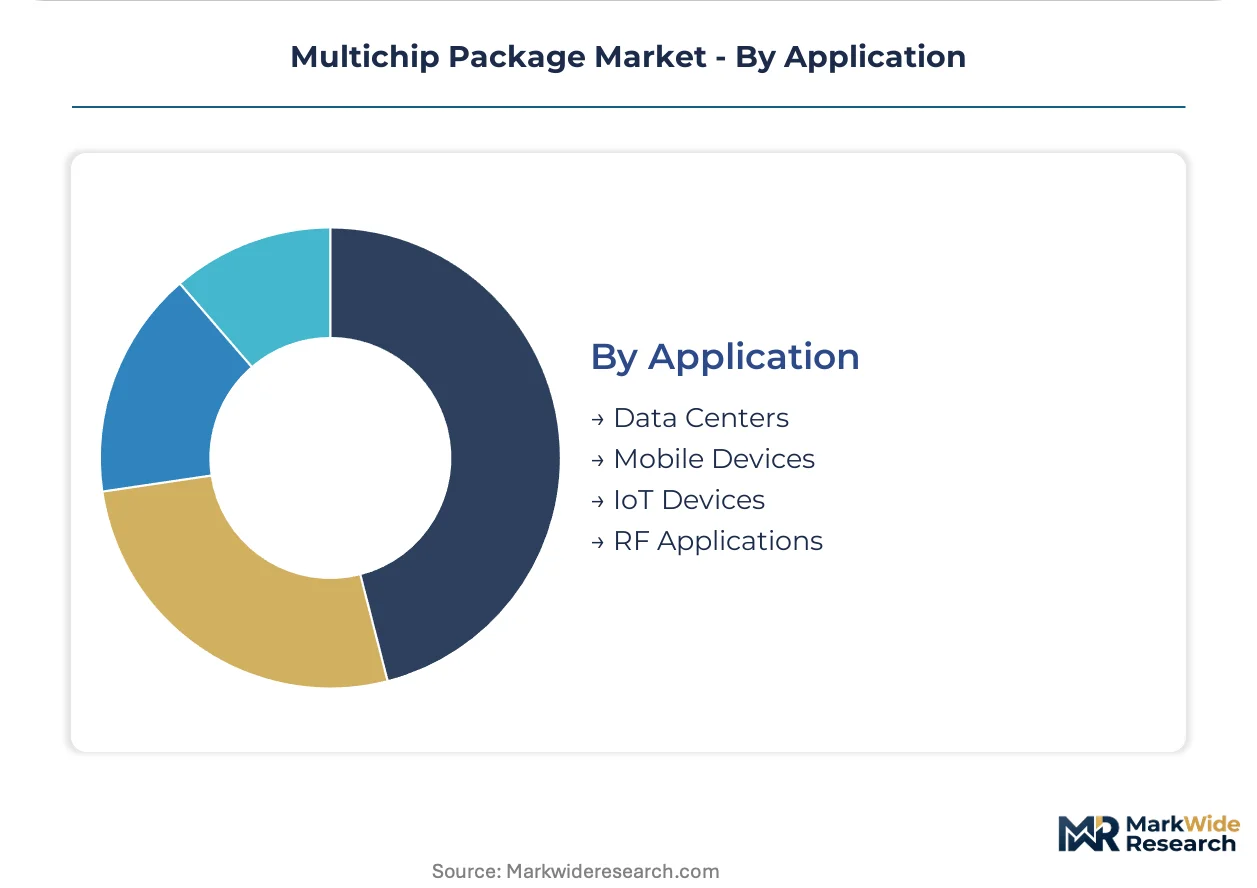
Application:
Volume scale separates mobile device procurement—billions of units annually—from data center deployment measured in millions, with margin structure inversely correlated.
- Data Centers:AI training and inference accelerators require massive die-to-die bandwidth, driving CoWoS and EMIB adoption. Cloud hyperscalers in the US reserve packaging capacity two years forward through direct TSMC and Intel Foundry agreements.
- Mobile Devices:Smartphone and tablet APUs demand the highest I/O density per square millimeter, favoring fan-out panel-level packaging. MediaTek and Qualcomm flagship chipsets anchor this segment's technology roadmap.
- IoT Devices:Sensor hubs and edge AI endpoints combine microcontrollers with RF and memory in ultra-compact SiP configurations. Industrial IoT deployments in Germany specify extended-temperature packages for factory automation.
- RF Applications:5G mmWave and satellite communication modules require low-loss substrates and precision passive integration. Qorvo and Skyworks dominate procurement for smartphone front-end modules.
Mobile devices anchor unit volume. Data centers define the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Taiwan and South Korea show minimal price elasticity for CoWoS-class capacity, while Indian and Southeast Asian procurement remains highly sensitive to wire-bond cost floors. German automotive OEMs occupy a middle tier, accepting premium pricing for AEC-Q100 qualification but resisting silicon interposer premiums below volume thresholds.
Taiwan
TSMC's CoWoS capacity anchors global supply for NVIDIA and AMD AI accelerators, with Hsinchu packaging corridors operating at full utilization. Taiwan's Industrial Development Bureau channels subsidies toward advanced packaging R&D through the K-Semiconductor strategy. Taichung's emerging packaging cluster is absorbing overflow demand as Hsinchu reaches physical capacity constraints.
South Korea
Samsung Electronics leverages captive foundry-to-OSAT pipelines for memory-logic 3D integration, serving domestic AI semiconductor demand. The K-Battery/K-Semiconductor strategy directs state capital toward advanced substrate technologies. Pyeongtaek's packaging complex is expanding hybrid bonding capacity for next-generation HBM4 stacking.
United States
Cloud hyperscalers reserve packaging capacity two years forward through direct foundry agreements, bypassing traditional OSAT relationships. NHTSA functional-safety standards accelerate automotive-grade packaging qualification timelines. Arizona's emerging semiconductor corridor is attracting advanced packaging investments from Taiwan-based suppliers seeking geographic diversification.
Germany
Automotive Tier-1s specify AEC-Q100 Grade 0 packages for LiDAR fusion modules under KBA functional-safety audits. The EU Chips Act redirects subsidy streams toward domestic packaging capacity expansion in Saxony and Bavaria. Dresden's semiconductor cluster is integrating packaging operations with Bosch and Infineon wafer fabrication.
India
Domestic data center demand pulls memory module assembly through Micron Technology's Gujarat facility under PLI scheme subsidies. BIS standards govern electronics manufacturing quality frameworks. Sanand's semiconductor ecosystem is emerging as a testbed for automotive-grade packaging qualification.
Multichip Package Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, with foundry-integrated packaging houses commanding premium pricing for heterogeneous integration while independent OSATs defend wire-bond cost floors. The market structure concentrates advanced 3D capacity among three vertically integrated Asian producers, while mature packaging fragments across geographic networks. Strategic archetypes span foundry-captive packaging divisions, independent OSATs with geographic diversification, and memory-integrated assemblers. Dominant competitive moves include direct capacity reservations by cloud hyperscalers and backward integration into substrate manufacturing.
Within the foundry-captive tier, Taiwan Semiconductor Manufacturing Company and Samsung Electronics exemplify technology leadership through integrated foundry-packaging pipelines. Amkor Technology occupies a position among independent OSATs with geographic diversification across Southeast Asia and North America. Infineon Technologies represents the automotive-specialized archetype with captive packaging capabilities aligned to functional-safety qualification requirements.
| Leading Market Players |
|---|
| Infineon Technologies |
| Integrated Silicon Solution, Inc. (ISSI) |
| Micron Technology |
| Macronix International |
| Winbond Electronics |
| Amkor Technology |
| Advanced Semiconductor Engineering |
| Samsung Electronics |
| Taiwan Semiconductor Manufacturing Company |
| Others |
Supply Flow & Price Mechanics
Twenty-six-week lead times for CoWoS-class silicon interposers signal acute supply scarcity that concentrates pricing power among Taiwan-based foundry-integrated packaging houses while forcing automotive OEMs into long-term offtake commitments.
Pricing Analysis
After-sales service contracts for thermal cycling qualification and field-failure analysis now drive lifetime value capture beyond unit shipments. Pricing stratifies across automotive-grade AEC-Q100, industrial-extended temperature, and consumer-commercial tiers, with certification premiums widening as NHTSA functional-safety audits extend qualification timelines. Cost compression in mature wire-bond segments intensifies because Chinese OSATs expand capacity for white-goods motor controllers. Cloud hyperscalers exhibit minimal price sensitivity for heterogeneous integration, whereas Indian data center operators remain highly elastic to memory module assembly quotes.
Supply Chain Analysis
Inbound logistics costs from Yokohama port congestion and constrained ABF substrate container availability on Asia-Europe trade lanes amplify input pricing volatility for large-format interposer production. Manufacturing concentrates in Taiwan, South Korea, and Japan, with Japanese suppliers controlling ABF substrate feedstock for advanced organic packages. Raw material dependencies span brominated epoxy mold compounds, ultra-low-alpha lead-free solder, and 300mm silicon interposer wafers. Single-source vulnerability around ABF substrate manufacturing creates structural risk. Distribution runs through foundry-direct allocation agreements for advanced 3D packaging and independent OSAT networks for mature wire bond.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Multichip packaging sits in early-cycle expansion as chiplet disaggregation accelerates adoption beyond leading-edge memory manufacturers into mainstream AI inference accelerators.
For Market Incumbents: Compound technology leadership through captive substrate manufacturing investments in Arizona and Dresden, securing ABF supply independence from Japanese suppliers. Deepen backward integration into glass core substrate panel processing to capture cost reduction from display-industry equipment reuse. Defend against emerging captive foundry-OSAT pipelines by accelerating automotive qualification timelines under KBA audits.
For New Entrants and Emerging Players: Differentiate on healthcare device miniaturization by pursuing ISO 13485 certification for implantable neuromodulator SiP configurations, where Medtronic and Boston Scientific procurement tolerates premium pricing. Target India's Sanand semiconductor ecosystem for automotive-grade packaging qualification, leveraging PLI scheme subsidies and Micron's Gujarat facility anchor tenancy. Pursue direct hospital system partnerships for diagnostic imaging compute modules as the go-to-market angle.
For Investors and Strategic Acquirers: Long-term, this sits as a substrate-convergence play because glass interposer panel processing combines display-industry depreciation curves with semiconductor patterning economics, collapsing cost structures for high-layer-count substrates. Acquisition targets should center on hybrid bonding equipment specialists and thermal-mechanical simulation software firms. Watch for Intel Foundry direct allocation agreements with cloud hyperscalers as the inflection signal for foundry-integrated packaging margin capture.
| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Bonding Capacity Expansion | Enables sub-10 micrometer pitch logic-to-memory stacking for NVIDIA and AMD accelerators. |
| Glass Core Substrate Panel Processing | Combines display-industry equipment with semiconductor patterning for cost reduction. |
| Automotive Functional-Safety Certification | Accelerates AEC-Q100 Grade 0 qualification under KBA and NHTSA audit frameworks. |
| Direct Foundry Capacity Reservation | Bypasses traditional OSAT relationships through TSMC and Intel Foundry allocation agreements. |
| Healthcare ISO 13485 Certification Pathway | Unlocks premium pricing tiers for biocompatible implantable neuromodulator packages. |
Methodological Framework
Desk research of SEC semiconductor capex disclosures, ECHA REACH substance restriction filings, and customs trade data preceded structured interviews with packaging technology directors, automotive Tier-1 procurement leads, foundry business development executives, and healthcare device regulatory affairs managers. Primary fieldwork combined with secondary validation across TSMC technology symposium proceedings, Samsung Electronics investor materials, and EU Chips Act implementation documents. Bottom-up die shipment modeling and top-down substrate consumption estimates provided triangulation.
Variance decomposition across interconnect method, vertical stacking approach, and end-use reliability requirements shaped the analytical framework over the projection horizon. Segmentation dimensions spanned product type, technology node, end-user industry, and application workload intensity. CAGRs derived from die attach equipment utilization rates, interposer area expansion curves, and memory-logic combination penetration assumptions. Forecast inputs included CoWoS capacity buildout schedules and EU AI Act risk-classification enforcement timelines.
Material uncertainties — silicon interposer lithography capacity constraints, ECHA brominated flame retardant restriction expansion, and UCIe specification fragmentation — sit outside the modeled envelope. Forecasts reflect assumptions about automotive qualification timeline compression and cloud hyperscaler allocation agreement stickiness. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Packaging
2.5D and 3D Semiconductor Packaging Market
Semiconductor Packaging
ESD Stackable Boxes Market
Semiconductor Packaging
3D TSV Packages Market
Semiconductor Packaging
Electronic Board Level Underfill and Encapsulation Material Market
Semiconductor Packaging
Microtube Box Market
Semiconductor Packaging
Memory Packaging Market
Semiconductor Packaging
Semiconductor Packaging Market
Semiconductor Packaging
Asia-Pacific Quad-Flat-No-Lead Packaging Market
Semiconductor Packaging
Semiconductor Solder Flux Market
Semiconductor Packaging
Asia Pacific LED Packaging Market
Semiconductor Packaging
Fan Out Packaging Market
Semiconductor Packaging
Semiconductor and IC Packaging Materials Market
Semiconductor Packaging
Bonding Wire Packaging Market
Semiconductor Packaging
System in Package (SIP) Die Market
Semiconductor Packaging
Global Semiconductor Packaging and Assembly Equipment Market
Semiconductor Packaging
3D IC and 2.5D IC Packaging Market