
 Memory Packaging Market | 2026-2036
Memory Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Memory Packaging Market Foresight
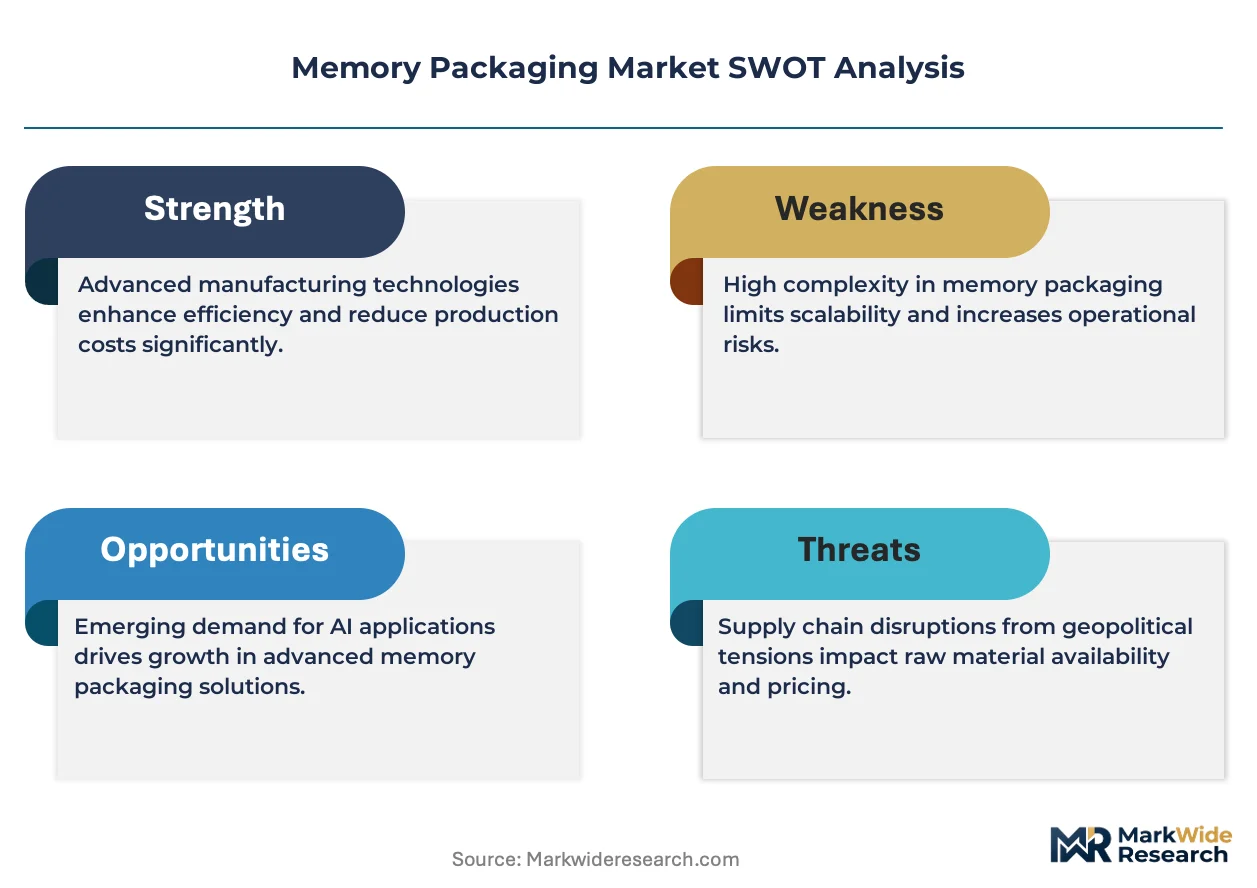
EU F-Gas Regulation is realigning substrate bonding specifications across European automotive supply chains. Amkor Technology Inc. leverages its Philippines-based capacity to serve memory module OEMs with lead-free flip-chip formats. Powertech Technology Inc. anchors high-volume DRAM packaging for Taiwanese foundry customers. Jiangsu Changjiang Electronics Technology Co. Ltd competes on wire-bonding cost structures for consumer NAND applications.
Memory packaging denotes the protective enclosure and electrical interconnection of volatile and non-volatile semiconductor die, typically employing organic substrates with copper redistribution layers, solder ball arrays, and mold compounds rated for thermal cycling between -40°C and 150°C. Its primary purpose is to ensure signal integrity, thermal dissipation, and mechanical reliability during device operation. NAND Flash packaging commands the largest revenue pool due to bit-density scaling in data center SSDs, while 3D Packaging through TSV interposers captures the fastest expansion as HBM stacks penetrate AI accelerator boards. Wire Bonding retains volume dominance in cost-sensitive consumer electronics but yields thinner margin pools than advanced flip-chip formats.
FDA device-grade reliability standards shape memory packaging for implantable medical electronics in the United States. EPA hazardous substance rules restrict lead content and mold compound formulations across North American supply chains. REACH compliance in Europe mandates full material disclosure for substrate laminates and underfill resins, raising entry barriers for non-compliant Asian suppliers. Stakeholders must monitor evolving substance restriction schedules and pre-qualify alternative bonding materials before regulatory deadlines disrupt qualified product lists.
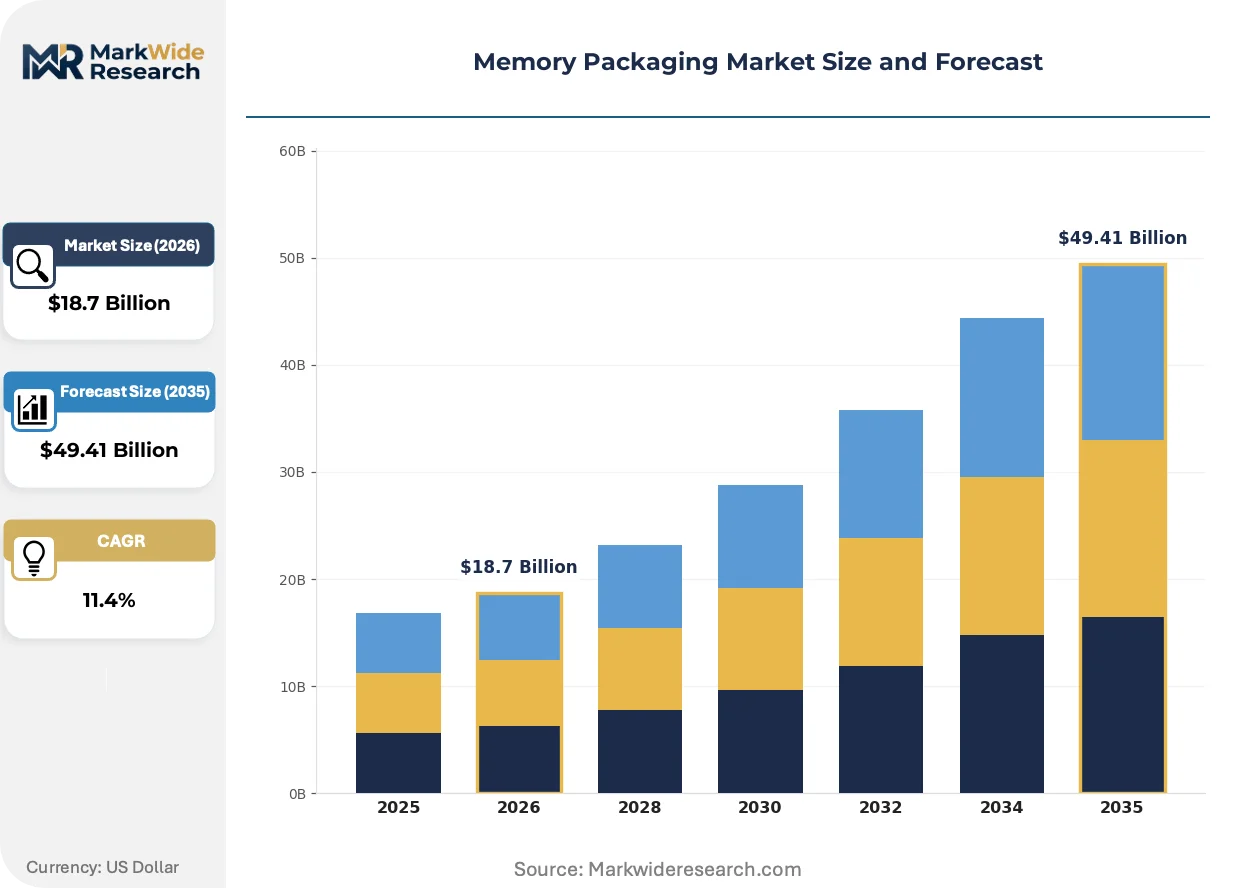
Market Dynamics
High-bandwidth memory stack penetration into AI training clusters is compressing packaging technology cycles while Taiwan and South Korean foundry capacity constraints force buyers into longer qualification pipelines.
Growth Catalysts
- HBM3E TSV integration:Through-silicon via interposers enable 12-high DRAM stacks for NVIDIA and AMD accelerator boards, pulling advanced substrate capacity from traditional flip-chip lines.
- EU F-Gas Regulation:Mandates for low-global-warming-potential bonding agents in automotive ECU modules are accelerating substrate material requalification across German OEM supply chains.
- Data center SSD bit-density scaling:QLC NAND die thinning below 50 micrometers requires thermally enhanced mold compounds for enterprise storage arrays.
Market Restraints
- ABF substrate shortage:Ajinomoto Build-up Film core-layer supply concentrates with three Japanese chemical suppliers, creating 26-week lead times for advanced packaging orders.
- Gold wire cost volatility:Palladium-doped copper bonding wire substitution stalls in automotive grade applications due to reliability qualification delays.
- REACH substance disclosure:Full material declaration requirements for underfill resins block non-compliant Asian substrate laminators from European medical device supply chains.
Strategic Opportunities
- India PLI scheme for semiconductors:Domestic packaging incentives attract OSAT investment for memory module assembly serving Middle East and African data center demand.
- Automotive zone-ECU consolidation:Domain controller architectures fuse ADAS and infotainment memory onto single high-reliability packages requiring AEC-Q100 Grade 0 qualification.
- Hybrid bonding die-to-wafer:Copper-copper direct bonding eliminates microbump pitch limitations for next-generation HBM4 stacks below 36 micrometers.
Industry Challenges
- Process engineer scarcity:TSV etch and CMP module expertise concentrates in Hsinchu and Seoul metro areas, constraining capacity expansion timelines.
- Multi-die warpage control:Coefficient-of-thermal-expansion mismatch between logic die and HBM stacks drives yield loss above 15 percent in 2.5D interposer assemblies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Memory Packaging Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: SDRAM, DRAM, SRAM, NAND Flash Application: Consumer Electronics, Automotive Electronics, Telecommunications, Industrial Automation Technology: 3D Packaging, Flip Chip, Wire Bonding, TSV End User: OEMs, Aftermarket Providers, Tier-1 Suppliers, Distributors |
| Companies Covered | Lingsen Precision Industries Ltd., Tianshui Huatian Technology Co. Ltd, Amkor Technology Inc., TongFu Microelectronics Co., Jiangsu Changjiang Electronics Technology Co. Ltd, Advanced Semiconductor Engineering Inc., Powertech Technology Inc., ChipMOS Technologies Inc., Hana Micron Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Memory Packaging Market Shifts & Advancements
Packaging architecture is bifurcating between cost-optimized wire-bonding for consumer NAND and thermally aggressive 3D stacking for AI accelerators, with substrate material science emerging as the critical differentiator.
Hybrid bonding is converging with microbump elimination in HBM4 roadmaps. Samsung and SK Hynix are accelerating die-to-wafer copper-copper joining for 16-high stacks. This convergence is compressing substrate redistribution layer pitch requirements below two micrometers.
REACH substance restriction schedules are tightening disclosure windows for epoxy mold compounds. ECHA's 2024-2026 SVHC candidate list expansion forces reformulation of brominated flame retardants in server DIMM packages. European automotive memory suppliers are pre-qualifying phosphorus-based alternatives ahead of sunset dates.
Cloud hyperscalers are consolidating memory procurement through direct OSAT contracts rather than module vendor intermediation. AWS, Microsoft Azure, and Google Cloud now specify package thermal profiles and signal integrity requirements in their own datasheets. This disintermediation is most visible in US and Irish data center clusters where custom HBM configurations dominate AI training infrastructure.
Memory Packaging Market Segmentation
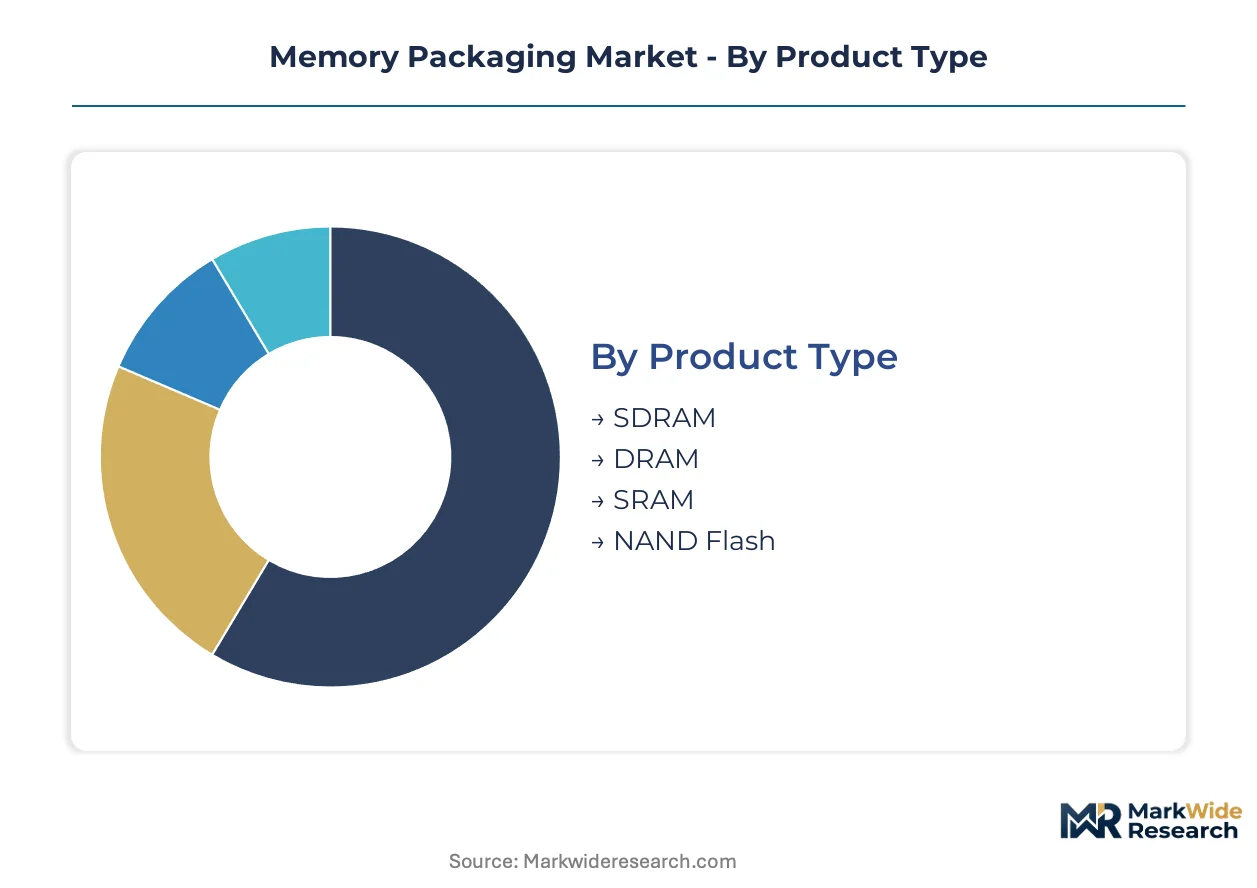
Memory packaging architectures diverge sharply across bit-density requirements, thermal envelopes, and signal integrity thresholds. Each segmentation axis reveals distinct margin structures and qualification barriers that reshape supplier positioning.
Product Type:
Die volatility characteristics and bit-density scaling curves define substrate selection and mold compound specifications.
- NAND Flash:QLC and TLC die architectures dominate enterprise SSD configurations, demanding thermally enhanced mold compounds for data center storage arrays operating above 85°C junction temperatures. Bit-density scaling below 50 micrometers is compressing package warpage tolerances in hyperscale deployments across the United States and Ireland.
- DRAM:DDR5 and LPDDR5X modules require low-profile fine-pitch ball grid arrays for mobile and server DIMM applications. HBM3E TSV integration is pulling advanced ABF substrate capacity from traditional flip-chip lines serving NVIDIA and AMD accelerator boards.
- SDRAM:Legacy synchronous architectures persist in industrial control systems and automotive infotainment modules where qualification longevity outweighs bandwidth requirements.
- SRAM:Six-transistor cell structures serve cache hierarchies in networking ASICs and FPGA companion chips with deterministic latency specifications.
NAND Flash leads on scale; DRAM leads on momentum.
Application:
End-use thermal cycling profiles and reliability grades fragment procurement specifications across customer bases.
- Automotive Electronics:Domain controller architectures fuse ADAS and infotainment memory onto single high-reliability packages requiring AEC-Q100 Grade 0 qualification for ambient temperatures spanning -40°C to 150°C. German OEMs now mandate RoHS-compliant packaging for ECU memory modules under EU F-Gas Regulation alignment.
- Telecommunications:Baseband processing and routing infrastructure demand signal-integrity-optimized flip-chip formats with copper redistribution layers for 56G PAM4 serdes channels. 5G massive MIMO deployments in South Korea and Taiwan are concentrating substrate procurement through direct OSAT contracts.
- Consumer Electronics:Cost-optimized wire-bonding formats dominate smartphone and tablet NAND modules where bill-of-material compression outweighs thermal performance.
- Industrial Automation:Extended temperature range specifications and long product lifecycle commitments favor established package families with frozen process controls.
Automotive Electronics commands premium pricing; Telecommunications is expanding most quickly.
Technology:
Interconnection pitch and thermal dissipation density determine capital intensity and process engineer requirements.
- 3D Packaging:Die-to-wafer hybrid bonding eliminates microbump pitch limitations for next-generation HBM4 stacks below 36 micrometers. Samsung and SK Hynix are accelerating copper-copper joining for 16-high DRAM configurations.
- TSV:Through-silicon via interposers enable 12-high HBM3E stacks with sub-2 micrometer redistribution layer pitch requirements. TSV etch and CMP module expertise concentrates in Hsinchu and Seoul metro areas, constraining capacity expansion timelines.
- Flip Chip:Lead-free solder bump arrays serve high-I/O memory controllers and GPU companion die with organic substrate carriers. Amkor Technology leverages Philippines-based capacity for memory module OEMs.
- Wire Bonding:Gold and palladium-doped copper interconnects retain volume dominance in cost-sensitive consumer NAND applications. Jiangsu Changjiang Electronics Technology competes on wire-bonding cost structures for consumer storage.
Wire Bonding leads on unit volume; 3D Packaging leads on technology trajectory.
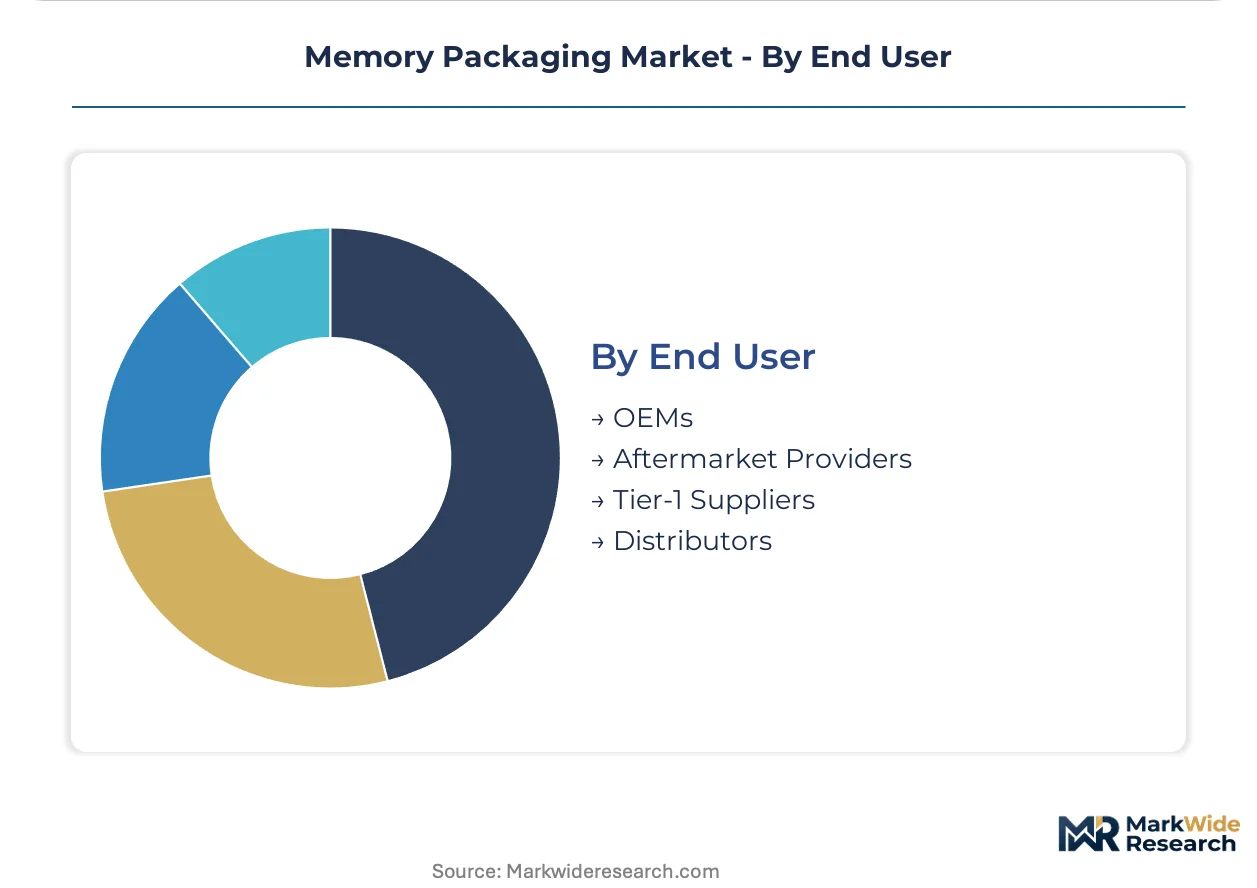
End User:
Procurement authority and technical specification control determine supplier engagement models and contract structures.
- OEMs:Cloud hyperscalers including AWS, Microsoft Azure, and Google Cloud now specify package thermal profiles and signal integrity requirements in proprietary datasheets, disintermediating traditional module vendors in US and Irish data center clusters.
- Tier-1 Suppliers:Automotive electronics OEMs in Germany consolidate memory procurement for domain controller architectures, requiring AEC-Q100 qualification and REACH-compliant material disclosure from substrate laminators.
- Distributors:Channel intermediaries serve fragmented industrial and medical device customers with smaller lot sizes and extended delivery schedules.
- Aftermarket Providers:Repair and upgrade modules for legacy enterprise storage and networking equipment require form-factor compatibility with end-of-life package outlines.
OEMs lead on specification authority; Tier-1 Suppliers lead on qualification rigor.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Process engineers with TSV etch and CMP expertise cluster in Hsinchu and Seoul metro areas, anchoring advanced packaging capacity. Taiwan and South Korean foundries supply the substrate redistribution layers feeding AI accelerator demand. German automotive OEMs drive RoHS-compliant material requalification across European supply chains.
United States
Cloud hyperscalers including AWS, Microsoft Azure, and Google Cloud specify package thermal profiles in proprietary datasheets, disintermediating traditional module vendors. FDA device-grade reliability standards govern implantable medical electronics memory packaging. The Pacific Northwest and Northern Virginia data center clusters concentrate custom HBM procurement for AI training infrastructure.
Germany
Automotive electronics OEMs mandate RoHS-compliant packaging for ECU memory modules under EU F-Gas Regulation alignment. ECHA REACH substance disclosure requirements block non-compliant Asian substrate laminators from medical device supply chains. Bavaria's automotive supplier corridor consolidates memory procurement for domain controller architectures requiring AEC-Q100 Grade 0 qualification.
Taiwan
Semiconductor foundries anchor supply-side capacity for high-volume DRAM packaging serving NVIDIA and AMD accelerator boards. The national industrial regulator enforces chemical substance controls on substrate bonding agents. Hsinchu Science Park concentrates TSV etch and CMP module expertise, constraining capacity expansion timelines for advanced interposer production.
South Korea
Samsung and SK Hynix accelerate die-to-wafer copper-copper joining for 16-high HBM4 stack configurations. MFDS medical device regulations shape packaging reliability standards for implantable electronics exports. Seoul metro area engineering talent pools support 12-high HBM3E TSV integration for AI training clusters.
Philippines
OSAT capacity serves memory module OEMs with lead-free flip-chip formats for consumer and industrial applications. The national investment promotion agency administers fiscal incentives for semiconductor packaging operations. Subic Bay and Clark economic zones host back-end assembly capacity feeding Middle East and African data center demand.
Memory Packaging Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across memory packaging value chains. The supplier base concentrates around three Japanese chemical suppliers controlling Ajinomoto Build-up Film core-layer production, creating 26-week lead times for advanced substrate orders. Strategic archetypes include foundry-captive OSATs, independent merchant packagers, and substrate material specialists. Competitive moves center on geographic capacity expansion and hybrid bonding technology licensing.
Among Asia-Pacific-based fabricators, Amkor Technology Inc., Powertech Technology Inc., and Jiangsu Changjiang Electronics Technology Co. Ltd occupy distinct positioning within the merchant packaging tier. Amkor represents the Philippines-anchored capacity serving lead-free flip-chip demand. Powertech exemplifies foundry-aligned DRAM packaging concentration. Jiangsu Changjiang sits within wire-bonding cost-competitive positioning for consumer NAND applications. These three entities illustrate the geographic and technological stratification shaping supplier selection criteria.
| Leading Market Players |
|---|
| Lingsen Precision Industries Ltd. |
| Tianshui Huatian Technology Co. Ltd |
| Amkor Technology Inc. |
| TongFu Microelectronics Co. |
| Jiangsu Changjiang Electronics Technology Co. Ltd |
| Advanced Semiconductor Engineering Inc. |
| Powertech Technology Inc. |
| ChipMOS Technologies Inc. |
| Hana Micron Inc. |
| Others |
Supply & Pricing Matrix
Die-to-wafer hybrid bonding adoption for HBM4 stack configurations is compressing unit economics while concentrating advanced substrate procurement among three Japanese ABF suppliers. This technology transition simultaneously elevates capital requirements for packaging houses and tightens margin structures across tiered service levels.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates AEC-Q100 automotive-grade packages from consumer wire-bonding formats and commodity NAND modules. Price differentiation hinges on thermal cycling certification depth and volume scale commitments from hyperscale data center operators. Cost compression in consumer wire-bonding tiers is intensifying because Jiangsu Changjiang Electronics Technology and TongFu Microelectronics compete aggressively on gold wire substitution economics. Automotive electronics OEMs exhibit lowest price sensitivity due to qualification longevity requirements, while smartphone NAND module vendors face acute bill-of-material pressure.
Supply Chain Analysis
Freight cost escalation on Ajinomoto Build-up Film substrate shipments from Japan to Philippines-based OSAT facilities is amplifying working capital requirements. Supply concentrates in Taiwan, South Korea, and Japan, with Hsinchu Science Park anchoring TSV etch capacity and Seoul metro areas feeding HBM3E stack integration. Raw material dependencies span ABF core layers, palladium-doped copper bonding wire, and thermally enhanced mold compounds. Single-source vulnerability on Japanese chemical suppliers creates procurement risk. Distribution runs through direct OSAT contracts with cloud hyperscalers disintermediating traditional module vendors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The memory packaging market reads as a late-cycle quality story. HBM3E and HBM4 stack penetration into AI training clusters is forcing buyers toward premium thermal specification tiers with extended qualification pipelines.
For Market Incumbents: Cement ABF substrate allocation agreements with Japanese chemical suppliers before capacity constraints worsen. Defend margin position by accelerating hybrid bonding technology licensing to offset wire-bonding commoditization. Vertical integration into underfill resin formulation mitigates REACH substance disclosure risks blocking Asian laminators from European medical device supply chains. For New Entrants and Emerging Players: Copper-copper direct bonding equipment specialization offers entry into HBM4 substrate redistribution layer production below two micrometer pitch requirements. Target India's PLI scheme incentives for semiconductor packaging to capture Middle East and African data center demand with lower qualification barriers. Pursue automotive zone-ECU consolidation opportunities in Bavaria's supplier corridor where AEC-Q100 Grade 0 qualification scarcity limits incumbent expansion. For Investors and Strategic Acquirers: Valuations sit cheapest among wire-bonding-dependent OSATs facing NAND Flash margin compression. Long-term viability centers on hybrid bonding technology access and ABF substrate supply relationships. The signal to watch is HBM4 stack adoption rates among NVIDIA and AMD accelerator board configurations.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Bonding Technology Licensing | Enables copper-copper direct joining for HBM4 stacks below 36 micrometer pitch requirements. |
| ABF Substrate Capacity Expansion | Addresses 26-week lead time constraints from Japanese chemical supplier concentration. |
| India PLI Scheme Participation | Captures fiscal incentives for semiconductor packaging serving Middle East data center demand. |
| REACH-Compliant Material Reformulation | Pre-qualifies phosphorus-based flame retardants ahead of ECHA SVHC sunset dates. |
| Automotive Grade 0 Qualification Investment | Secures domain controller memory procurement from German OEM supply chain consolidation. |
Research Methodology
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region's packaging engineering centers. The analysis combines primary interviews with OSAT operations directors, substrate procurement managers, automotive electronics OEM supply chain leads, and semiconductor foundry packaging strategists with secondary validation from SEC 10-K filings, ECHA REACH substance databases, and hyperscaler capex disclosures. Bottom-up and top-down triangulation cross-checks unit volume assumptions against foundry wafer start data.
Granularity-level modeling extends to package technology tier, memory type volatility characteristics, end-use thermal cycling requirements, and geographic regulatory cluster. Value outputs across the analysis window derive from segment-specific ASP trajectories informed by ABF substrate cost curves and gold wire price volatility. CAGRs were computed from annualized growth rates applied to base-year market sizing. Industry-specific forecast inputs include HBM stack penetration rates and automotive ECU consolidation timelines.
The model holds under stable Taiwan-South Korea foundry capacity allocation; deviation in geopolitical trade restrictions or ABF supply disruption would shift capacity expansion timelines. Forecasts reflect assumptions on hybrid bonding yield maturation and REACH substance substitution schedules. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Packaging
NOR-Based Multi-Chip Packages Market
Semiconductor Packaging
Ball Grid Array (BGA) Packaging Market
Semiconductor Packaging
Outsourced Semiconductor Assembly and Test Services (OSAT) Market
Semiconductor Packaging
Advanced Semiconductor Packaging Market
Semiconductor Packaging
3D TSV Packages Market
Semiconductor Packaging
System in Package (Sip) Technology Market
Semiconductor Packaging
3D IC Packaging Market
Semiconductor Packaging
Global Semiconductor Seals Market
Semiconductor Packaging
Semiconductor Packaging Material Market
Semiconductor Packaging
System-On-Package Market
Semiconductor Packaging
Wafer Carrier Boxes Market
Semiconductor Packaging
Through-Silicon via (TSV) IC Packaging Market
Semiconductor Packaging
Asia Pacific LED Packaging Market
Semiconductor Packaging
IC Packaging and Testing Market
Semiconductor Packaging
System in Package (SIP) Die Market
Semiconductor Packaging
Global High-End Semiconductor Packaging Market