
 Semiconductor and IC Packaging Materials Market | 2026-2036
Semiconductor and IC Packaging Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Semiconductor and IC Packaging Materials Market Analytics
Direct sales from foundries to OSATs is rewriting procurement pathways for advanced substrates. Taiwan Semiconductor Manufacturing Company anchors captive packaging demand through its CoWoS and InFO platforms. Samsung Electronics extends vertical control from memory wafer fabrication through to 2.5D assembly. JCET Group competes aggressively in fan-out wafer-level packaging for mobile APs and RF modules.
Semiconductor and IC packaging materials encompass die-attach films, leadframe substrates, encapsulant compounds, and interposer metallurgies engineered for thermal cycling between minus 40 and 150 degrees Celsius, moisture sensitivity level compliance, and wire-bond or flip-chip interconnect integrity. These materials protect active silicon from mechanical stress, environmental corrosion, and thermal dissipation failure while enabling electrical signal routing between die and system boards. Ball Grid Array formats dominate high-I/O logic devices, while flip-chip production methods command premium positioning in AI accelerator and data-center processor applications where bump pitch now pushes below 40 micrometers. Copper metallization leads material value pools as power-device substrates shift from traditional alloys to direct-bond-copper architectures.
EPA toxics release rules and REACH substance restrictions are tightening permissible formulations for epoxy resin hardeners and polyimide precursors, forcing reformulation investments across the supply base. China's MEE enforces dual carbon compliance on copper smelters and substrate plating facilities, reshaping regional cost structures for raw material feedstock. Taiwan's national semiconductor regulator coordinates with ISO 9001 and IATF 16949 auditors to harmonize automotive-grade packaging certification across the island's OSAT ecosystem. Stakeholders must monitor how substrate material qualification timelines interact with foundry node migration schedules as heterogeneous integration architectures proliferate.
Market Dynamics
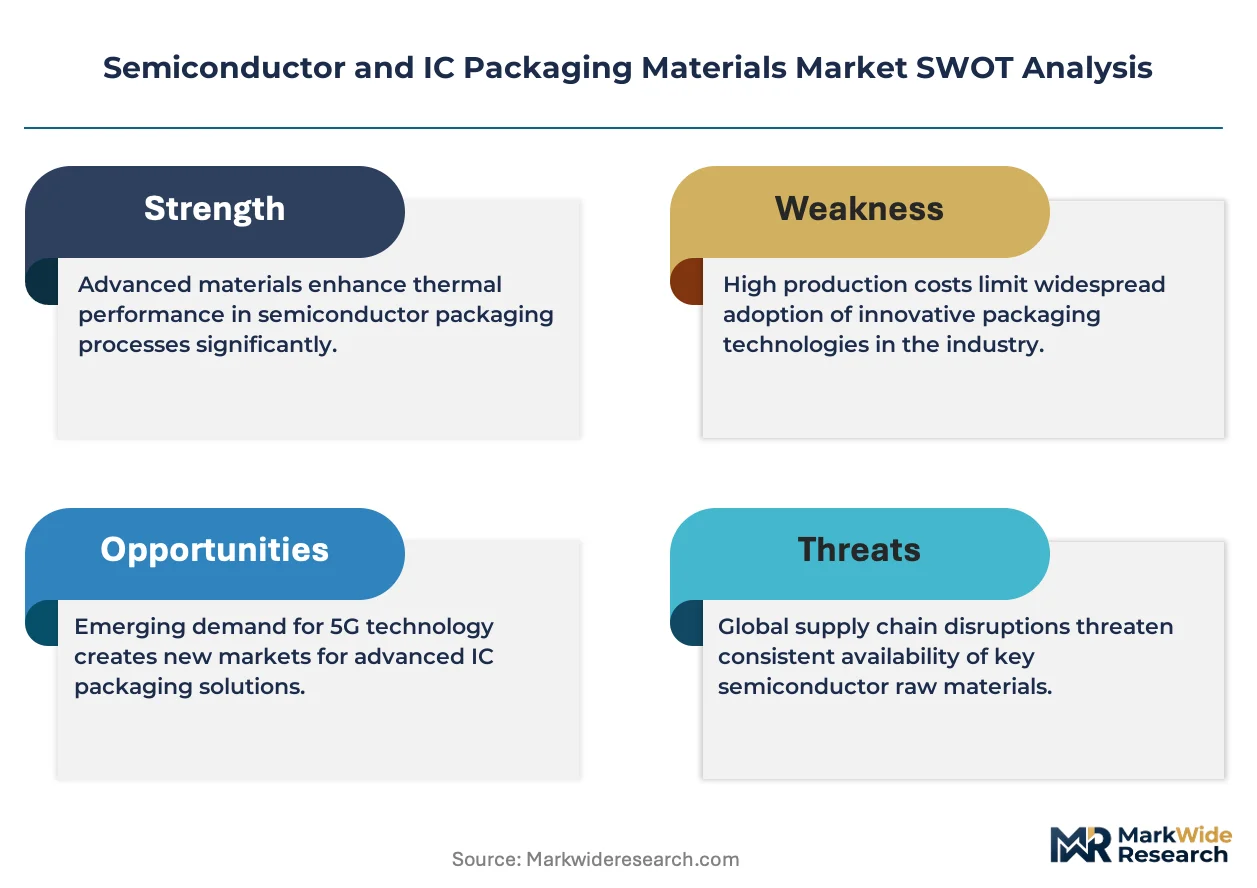
Advanced packaging architectures are compressing qualification timelines for substrate materials as heterogeneous integration forces simultaneous optimization of thermal, electrical, and mechanical properties within single interposer designs.
Growth Catalysts
- Automotive electrification mandates:Power module packaging for EV traction inverters is pulling direct-bond-copper substrates and silver-sintered die-attach pastes into high-volume production. EPA vehicle emission rules and China's dual carbon goals are accelerating this transition.
- AI accelerator packaging:CoWoS and 2.5D interposers for data-center GPUs are expanding demand for ultra-low-loss organic substrates and high-density redistribution layers. Taiwan's Hsinchu cluster anchors this demand concentration.
- REACH substance restrictions:ECHA's tightening controls on halogenated flame retardants and bisphenol-A derivatives are forcing reformulation investments that open market share for compliant epoxy resin suppliers.
Market Restraints
- Raw material concentration:High-purity copper smelting and specialty polyimide precursor synthesis concentrate in China's Yangtze River Delta, exposing substrate costs to MEE environmental enforcement actions and power rationing.
- Technical limitation at fine pitch:Bump pitch scaling below 40 micrometers encounters capillary underfill voiding and electromigration failures that constrain flip-chip reliability in automotive thermal cycling.
- Capital intensity barrier:Fan-out panel-level packaging lines require 300mm-equivalent mold compound handling equipment that exceeds 150 million dollars per installation, freezing out mid-tier OSATs.
Strategic Opportunities
- India semiconductor packaging:PLI scheme subsidies for display and compound semiconductor fabs are creating first-mover substrate qualification windows for epoxy molding compound suppliers before indigenous capacity matures.
- Glass interposer convergence:Panel-level packaging and photonic chiplet integration are hybridizing around through-glass-via architectures that bypass organic substrate warpage limits.
- Automotive-grade certification acceleration:IATF 16949 and AEC-Q100 test protocols are compressing from 18-month to 12-month qualification cycles for materials suppliers who pre-validate with tier-one OSATs.
Industry Challenges
- Materials characterization talent scarcity:Thermomechanical analysis and failure mode simulation for multi-die stacks requires expertise spanning polymer chemistry, metallurgy, and finite element modeling that concentrates in Taiwan and South Korea.
- Cross-foundry qualification fragmentation:Each leading foundry maintains proprietary design rules for CoWoS, InFO, and EMIB variants that force redundant substrate development cycles without industry-wide standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Semiconductor and IC Packaging Materials Market |
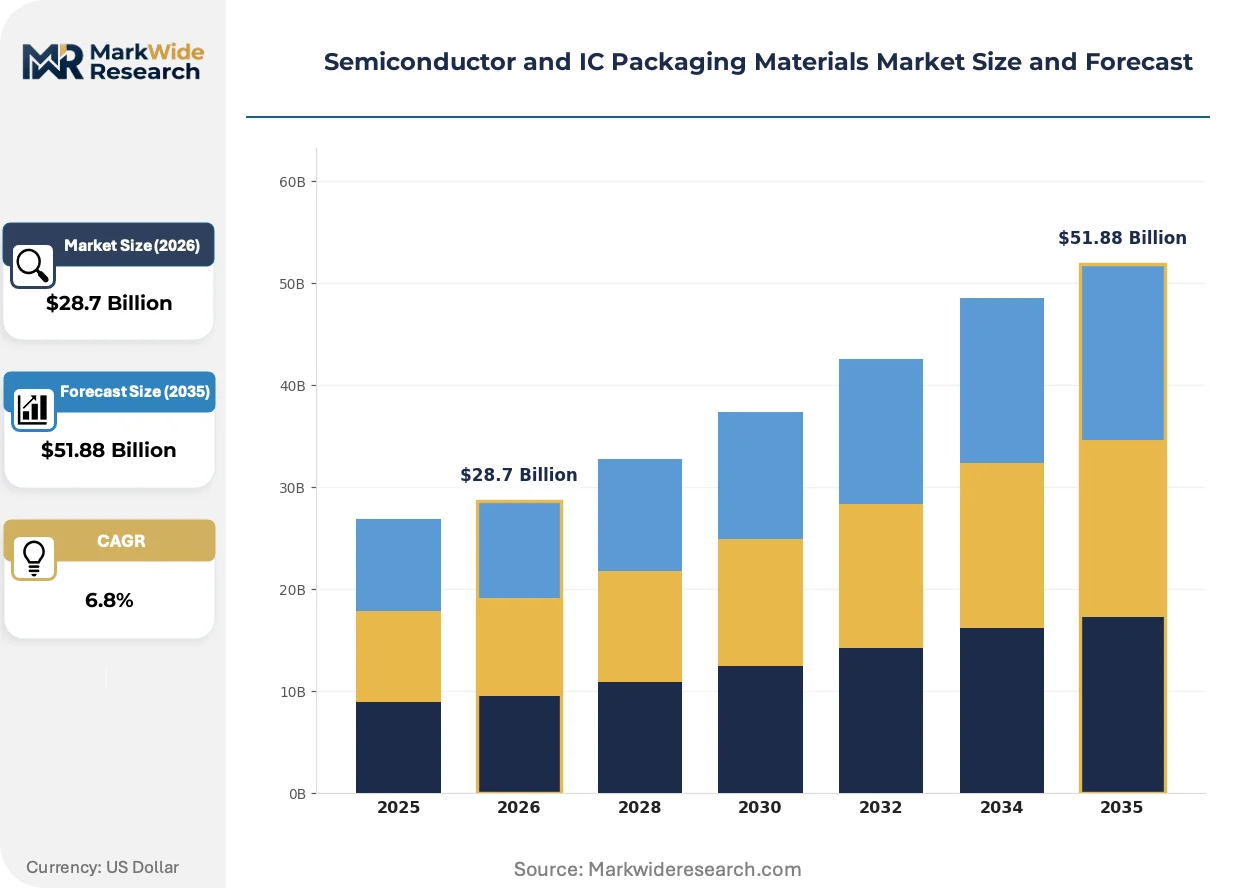
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $51.88 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Packaging Type: Ball Grid Array, Chip-on-Board, Dual In-line Package, Quad Flat Package Material: Epoxy Resin, Polyimide, Copper, Silicon End User: Consumer Electronics, Automotive Electronics, Aerospace, Telecommunications Production Method: Thermal Compression, Wire Bonding, Flip Chip, Molded Packaging |
| Companies Covered | Advanced Semiconductor Engineering, JCET Group, Taiwan Semiconductor Manufacturing Company, Unimicron Technology, Siliconware Precision Industries, Intel Corporation, Amkor Technology, Texas Instruments, Samsung Electronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Semiconductor and IC Packaging Materials Market Evolving Landscape
Packaging material innovation is pivoting from incremental thermal performance gains toward simultaneous optimization of signal integrity, power delivery, and mechanical reliability as chiplet architectures proliferate.
Hybrid bonding is hybridizing copper-to-copper direct bonding with traditional microbump interconnects in high-bandwidth memory stacks. AI training chip designers at leading cloud service providers are adopting this for HBM3E integration despite 25 percent yield premiums. The technology is compressing substrate layer counts by eliminating solder-based interconnects while demanding atomically smooth copper surfaces that reshape plating chemistry requirements.
REACH substance restrictions on per- and polyfluoroalkyl substances are forcing epoxy resin hardener reformulations across European supply chains. ECHA's 2023 PFAS restriction proposal threatens fluorinated mold release agents and low-Dk dielectric additives that underpin high-frequency substrate performance. Material suppliers are responding with silicon-based alternatives that trade 10-15 percent dielectric loss for regulatory compliance, primarily affecting RF module packaging for 5G infrastructure.
Direct procurement contracts between automotive OEMs and substrate material suppliers are displacing traditional tiered distribution through component distributors. EV powertrain divisions at European and Chinese vehicle manufacturers now specify copper-clad laminate grades and sintering paste chemistries directly, bypassing module assembler input. This pattern concentrates in Germany's Baden-Württemberg automotive electronics cluster and China's Greater Bay Area EV manufacturing belt, where vertical integration into power module assembly shortens feedback loops.
Semiconductor and IC Packaging Materials Market Segmentation
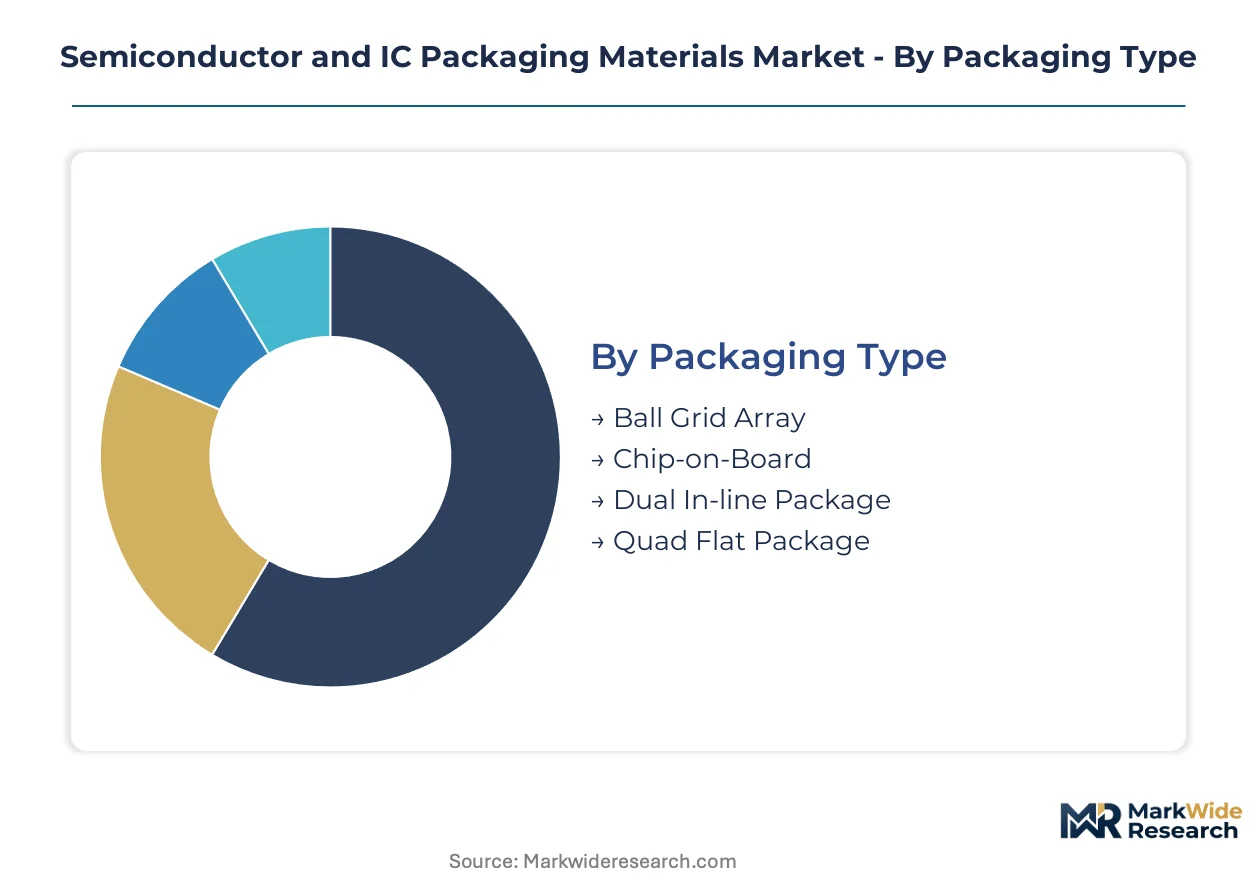
Packaging material selection cascades through thermal cycling requirements, moisture sensitivity levels, and interconnect pitch specifications that vary dramatically across device categories. Each segment exhibits distinct procurement patterns, qualification timelines, and technical barriers that reshape competitive positioning among substrate suppliers.
Packaging Type:
After-sales service intensity varies sharply across formats, with high-I/O packages demanding field failure analysis and rapid substrate replacement protocols that strain distributor logistics networks.
- Ball Grid Array:High-density solder sphere arrays enable I/O counts exceeding 1,000 pins for microprocessors and ASICs. Taiwan's Hsinchu cluster anchors demand as foundry-packaging integration deepens for AI accelerators requiring sub-40 micrometer bump pitches.
- Chip-on-Board:Direct die attachment to PCB substrates eliminates package-level interconnects, reducing thermal resistance for LED drivers and power management ICs. China's Greater Bay Area LED manufacturing belt concentrates procurement of silver-filled die-attach epoxies for this format.
- Dual In-line Package:Through-hole leadframes persist in industrial control and legacy automotive sensor applications where vibration resistance trumps density requirements.
- Quad Flat Package:Gull-wing leads suit consumer electronics cost targets, with epoxy molding compound formulations optimized for high-speed transfer molding cycles.
By volume, Quad Flat Package leads. By growth pace, Ball Grid Array is expanding most quickly.
Material:
Raw material cost tiers separate premium formulations from commodity grades, with specialty polymer precursors commanding 3-5x multiples over standard epoxy resin base stocks.
- Epoxy Resin:Bisphenol-A and phenolic novolac formulations dominate encapsulant applications, with halogen-free hardener variants gaining share under REACH substance restrictions. ECHA's tightening controls on brominated flame retardants are forcing reformulation investments that open market share for compliant suppliers.
- Polyimide:High-temperature stability and low dielectric constant make this the substrate of choice for flexible circuits and high-frequency RF modules. Japan's polyimide precursor suppliers concentrate technical leadership for 5G infrastructure applications.
- Copper:Direct-bond-copper substrates for power modules and redistribution layer metallization for advanced packaging both pull high-purity cathode demand.
- Silicon:Interposer wafers and through-silicon-via structures enable 2.5D and 3D stacking architectures for memory-logic integration.
Epoxy Resin captures the largest volume share. Polyimide is climbing the fastest as RF packaging requirements intensify.
End User:
Customer type fragmentation splits procurement between automotive OEMs demanding 18-month qualification cycles and consumer electronics brands compressing material selection to 6-month windows.
- Consumer Electronics:Smartphone AP and RF module packaging drives fan-out wafer-level demand with aggressive cost-down targets. Taiwan OSATs dominate substrate procurement for this segment.
- Automotive Electronics:Power module packaging for EV traction inverters pulls direct-bond-copper substrates and silver-sintered die-attach pastes into high-volume production. EPA vehicle emission rules and China's dual carbon goals are accelerating this transition.
- Aerospace:Radiation-hardened packaging for satellite electronics demands ceramic substrates and hermetic sealing with decade-long reliability guarantees.
- Telecommunications:Base station power amplifiers and optical transceivers require thermal management materials for continuous operation at elevated junction temperatures.
Consumer Electronics holds volume leadership. Automotive Electronics shows the steepest expansion trajectory.
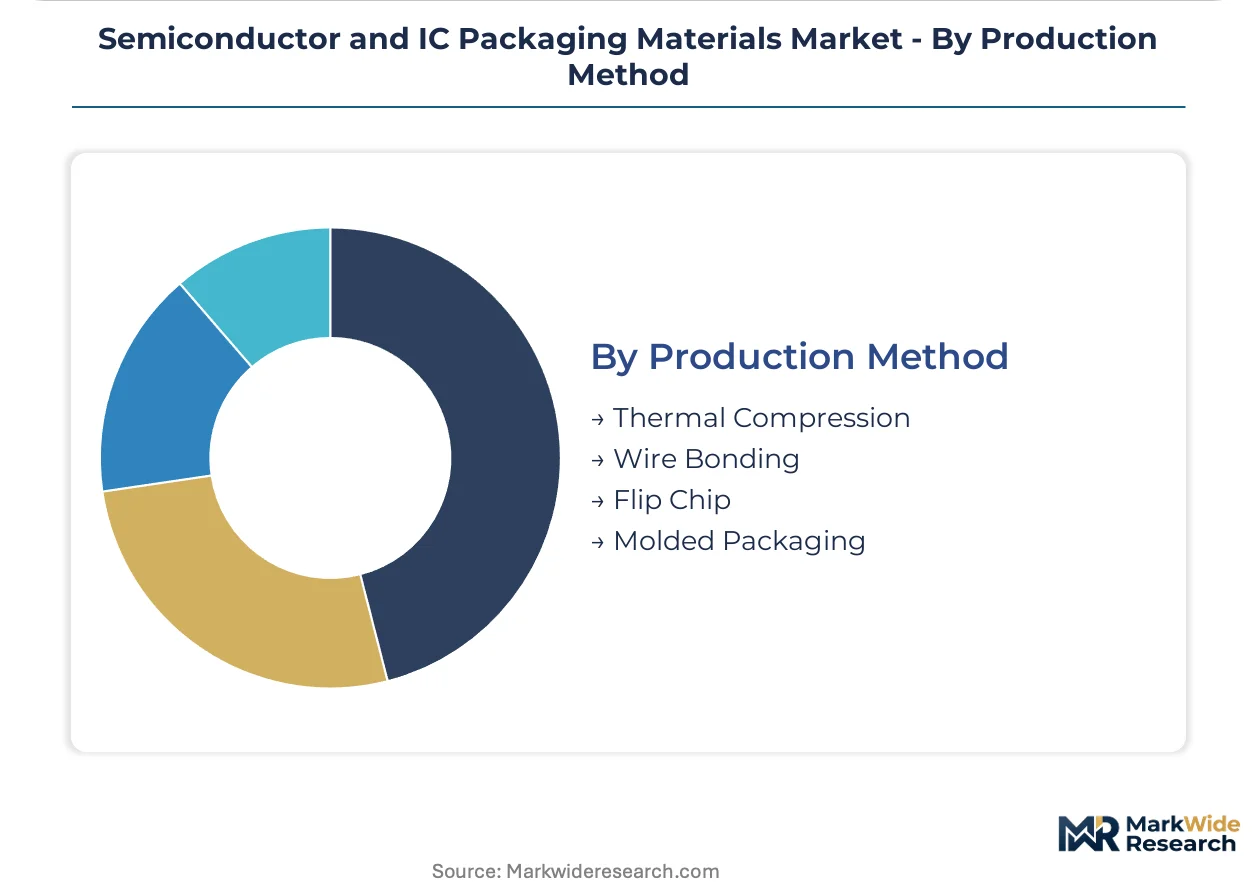
Production Method:
Process maturity determines equipment depreciation schedules and labor skill requirements, with established wire bonding maintaining cost advantages against capital-intensive hybrid bonding alternatives.
- Thermal Compression:Fine-pitch flip-chip assembly for mobile processors requires precise temperature and force control to achieve reliable copper pillar interconnects.
- Wire Bonding:Gold and copper wire interconnects persist in cost-sensitive packages where I/O density remains modest. China's Yangtze River Delta concentrates wire bonder manufacturing and consumables supply.
- Flip Chip:Solder bump and copper pillar technologies enable area-array interconnects for high-performance computing. Taiwan Semiconductor Manufacturing Company anchors captive demand through CoWoS and InFO platforms.
- Molded Packaging:Epoxy molding compound transfer molding protects wire-bonded die from environmental stress in automotive underhood applications.
Wire Bonding dominates current volume. Flip Chip is gaining share fastest as heterogeneous integration architectures proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's dual carbon goals and GB standards are accelerating substrate material transitions toward lower-emission chemistries. Taiwan's Hsinchu Science Park cluster anchors foundry-packaging integration for AI accelerators. EPA toxics release rules and REACH substance restrictions are tightening permissible formulations across North American and European supply bases.
United States
EPA vehicle emission rules are pulling direct-bond-copper substrates and silver-sintered die-attach pastes into high-volume production for EV power modules. NHTSA coordinates with automotive OEMs on packaging reliability standards for underhood electronics. Texas Instruments and Intel Corporation anchor captive packaging demand in the Southwest and Pacific Northwest corridors.
China
MIIT's GB standards and MEE environmental enforcement are reshaping regional cost structures for high-purity copper smelting and substrate plating. The Yangtze River Delta concentrates specialty polyimide precursor synthesis despite power rationing exposure. JCET Group competes aggressively in fan-out wafer-level packaging for mobile APs across the Pearl River Delta manufacturing belt.
Taiwan
TSMC's CoWoS and InFO platforms anchor captive packaging demand for AI accelerators requiring sub-40 micrometer bump pitches. The national semiconductor regulator harmonizes automotive-grade packaging certification with ISO 9001 and IATF 16949 auditors across the OSAT ecosystem. Hsinchu Science Park concentrates foundry-packaging integration deeper than any comparable cluster worldwide.
South Korea
Samsung Electronics extends vertical control from memory wafer fabrication through to 2.5D assembly for high-bandwidth memory stacks. MFDS and METI-aligned standards govern materials qualification for automotive and consumer electronics exports. Seoul Capital Area fabrication complexes source redistribution layer metallurgy from domestic plating chemistry suppliers.
Germany
ECHA's REACH substance restrictions on halogenated flame retardants are forcing epoxy resin hardener reformulations across European supply chains. KBA automotive certification protocols compress qualification timelines for power module substrate suppliers. Baden-Württemberg's automotive electronics cluster concentrates direct procurement contracts between EV OEMs and copper-clad laminate vendors.
Semiconductor and IC Packaging Materials Market Competitive Landscape
On the supply side, the industry is consolidating around foundry-captive packaging operations and tier-one OSATs with advanced substrate qualification capabilities. Three strategic archetypes dominate: foundry-integrated packaging divisions controlling interposer metallurgy specifications, independent OSATs competing on fan-out wafer-level cost structures, and specialty chemical suppliers reformulating epoxy resins for REACH compliance. Capacity expansion in 300mm-equivalent mold compound handling and strategic partnerships for glass interposer development represent the dominant competitive moves.
Among Asia-Pacific-based fabricators, Taiwan Semiconductor Manufacturing Company, JCET Group, and Samsung Electronics exemplify the three archetypes. TSMC occupies a position as the foundry-integrated standard-setter for CoWoS and InFO platforms. JCET represents the independent OSAT competing aggressively in mobile and RF module packaging. Samsung anchors the vertically integrated memory-to-assembly model for HBM and logic stacking applications.
| Leading Market Players |
|---|
| Advanced Semiconductor Engineering |
| JCET Group |
| Taiwan Semiconductor Manufacturing Company |
| Unimicron Technology |
| Siliconware Precision Industries |
| Intel Corporation |
| Amkor Technology |
| Texas Instruments |
| Samsung Electronics |
| Others |
Value Network & Pricing Analysis
China's Yangtze River Delta concentration for high-purity copper smelting and specialty polyimide precursor synthesis anchors margin pools at substrate plating facilities and epoxy resin formulators downstream. MEE environmental enforcement actions and power rationing in this cluster transmit cost volatility directly to direct-bond-copper substrate pricing for EV power modules.
Pricing Analysis
Volume-discount tiering structures separate automotive-grade IATF 16949-certified epoxy molding compounds from standard consumer electronics grades. Three-tier pricing stratifies across AEC-Q100 qualified, industrial-temperature-range, and commercial-temperature-range certification levels. Cost compression in standard-grade encapsulants intensifies as China's substrate plating capacity expands. Consumer electronics OSATs exhibit highest price sensitivity, while automotive OEMs accept premiums for traceability and thermal cycling guarantees.
Supply Chain Analysis
Extended payment terms from foundry-captive packaging divisions to specialty chemical suppliers are restructuring working capital requirements across the supplier base. Raw material feedstock draws from China's copper smelting complex, Japan's polyimide precursor synthesis, and Taiwan's redistribution layer metallurgy. Single-source vulnerability concentrates in high-purity copper cathode supply. Distribution runs through direct procurement contracts between automotive OEMs and substrate material suppliers, displacing traditional component distributor channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Semiconductor packaging materials are cycling through a recovery phase as AI accelerator demand absorbs excess organic substrate capacity. Foundry-packaging integration at Taiwan's Hsinchu cluster is the cyclical driver resetting utilization rates.
For Market Incumbents: Insulate formulation IP from REACH substance restrictions by accelerating silicon-based dielectric additive R&D ahead of ECHA's PFAS enforcement timeline. Backward integration into copper smelting partnerships in Indonesia or Australia reduces exposure to China's MEE regulatory actions. Lock in automotive-grade certification pipelines with tier-one OSATs before qualification timelines compress further. For New Entrants and Emerging Players: India's PLI-subsidized display and compound semiconductor fabs represent the most penetrable entry point for epoxy molding compound suppliers before indigenous substrate capacity matures. Glass interposer qualification windows for photonic chiplet integration offer second-mover advantage as organic substrate warpage limits harden. Partner with domestic plating chemistry suppliers in South Korea's Seoul Capital Area to bypass established Taiwan-Japan supply relationships. For Investors and Strategic Acquirers: Capital is best deployed toward specialty chemical suppliers with REACH-compliant epoxy resin hardener portfolios and pre-validated automotive-grade formulations. Long-term viability hinges on heterogeneous integration architectures proliferating through 2030. Monitor TSMC's CoWoS capacity expansion announcements as the inflection indicator for ultra-low-loss organic substrate demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Copper Feedstock | Secures cathode supply outside China's MEE enforcement jurisdiction for substrate plating. |
| REACH-Compliant Formulation Launch | Opens market share as ECHA restrictions on halogenated flame retardants tighten. |
| Automotive-Grade Certification Acceleration | Compresses IATF 16949 qualification cycles to 12 months through tier-one OSAT pre-validation. |
| Glass Interposer Development Partnership | Bypasses organic substrate warpage limits for panel-level packaging and photonic integration. |
| India PLI Scheme Market Entry | Captures first-mover substrate qualification windows before indigenous packaging capacity matures. |
Research Methodology
Desk research of SEC filings from packaging material suppliers, EPA toxics release inventories, and ECHA substance restriction proposals preceded structured interviews with substrate plating facility managers, epoxy resin formulators, automotive OEM powertrain procurement leads, and foundry packaging integration engineers. Secondary validation drew from Taiwan's national semiconductor regulator disclosures, China's MIIT GB standards documentation, and customs trade data for high-purity copper cathode flows. Bottom-up build-ups of segment-level consumption crossed against top-down foundry capacity forecasts.
Assumptions held fixed include sustained EPA vehicle emission rules, ECHA's PFAS restriction timeline, and China's dual carbon enforcement intensity. Variables included heterogeneous integration adoption rates, bump pitch scaling trajectories below 40 micrometers, and automotive-grade certification compression timelines. Segmentation modeling spanned packaging type, material chemistry, end-use vertical, and production method. CAGRs derived from elasticity-adjusted consumption curves against foundry node migration schedules. Forecast inputs included CoWoS capacity build-out disclosures and EV power module packaging content per vehicle.
Practitioners should monitor ECHA regulatory enforcement intensity, TSMC's interposer metallurgy specification changes, and China's MEE power rationing announcements for early signals of forecast deviation. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Packaging
Semiconductor Packaging Market
Semiconductor Packaging
Through Silicon via (TSV) Packaging Market
Semiconductor Packaging
Global Interposer and Fan-Out WLP Market
Semiconductor Packaging
Epoxy Potting Market
Semiconductor Packaging
Semiconductor Packaging Material Market
Semiconductor Packaging
Quad-Flat-No-Lead Packaging (QFN) Market
Semiconductor Packaging
Bonding Wire Packaging Market
Semiconductor Packaging
System in Package (Sip) Technology Market
Semiconductor Packaging
Memory Packaging Market
Semiconductor Packaging
3D Semiconductor Packaging Market
Semiconductor Packaging
Global High-End Semiconductor Packaging Market
Semiconductor Packaging
Wafer Level Packaging (WPL) Market
Semiconductor Packaging
2.5D and 3D Semiconductor Packaging Market
Semiconductor Packaging
Fan Out Packaging Market
Semiconductor Packaging
Multichip Package Market
Semiconductor Packaging
Through-Silicon via (TSV) IC Packaging Market