
 COG Bonder Market | 2026-2036
COG Bonder Market Size, Share, and Industry Trends Forecast 2026-2036
COG Bonder Market Insights
Chip-on-glass flip-chip integration is reshaping how display driver ICs mount directly onto glass substrates, eliminating traditional TAB packaging and reducing bezel width in mobile displays. Shibaura Mechatronics leverages its precision motion control heritage to dominate high-accuracy alignment systems for sub-10 micron pitch bonding. Panasonic anchors the automotive display segment with equipment rated for larger substrate formats and extended thermal cycling reliability. Shenzhen Olian competes aggressively on cost structure for mid-tier smartphone assembly lines across Chinese panel makers.
A COG bonder is precision semiconductor assembly equipment that thermocompression-bonds gold-bumped or solder-bumped driver ICs onto indium tin oxide trace patterns on glass using alignment accuracy below 3 microns and force control within gram-level resolution. The technology serves flat-panel display manufacturing where miniaturized interconnects must survive thermal expansion mismatches between silicon and glass. Film-based adhesive bonding leads volume shipments due to its established use in smartphone OLED and LCD production, while flip-chip technology commands the fastest expansion as panel makers adopt copper-pillar bumping for finer pitches. Wire bonding retains share in cost-sensitive tablet and automotive displays where legacy infrastructure amortization matters more than bezel reduction.
Japan's METI semiconductor equipment standards and China's GB/T national standards for flat-panel display manufacturing equipment shape product certification requirements and cross-border market access for COG bonder vendors. The EU RoHS and REACH frameworks restrict lead-based solder formulations, pushing equipment makers to qualify lead-free bumping processes for European-bound display exports. Stakeholders must monitor how China's dual carbon goals and Japan's METI green innovation fund redirect capital toward energy-efficient bonding platforms with reduced thermal budgets.
Market Dynamics
Flip-chip copper-pillar bumping is compressing interconnect pitches below 10 microns, forcing COG bonder vendors to recalibrate alignment systems and thermal profiles for sub-3 micron accuracy at mass-production speeds.
Growth Catalysts
- MIIT domestic semiconductor packaging mandates:China's push for localized supply chains redirects procurement toward indigenous equipment vendors in Shenzhen and Suzhou manufacturing clusters.
- OLED panel miniaturization:Smartphone bezel reduction requirements below 1 millimeter demand gold-bumped driver IC bonding with gram-level force resolution.
- Automotive display thermal cycling standards:Extended reliability testing for heads-up displays and curved instrument panels expands equipment qualification programs.
Market Restraints
- Precision granite substrate cost volatility:Vibration-dampening base materials for sub-micron alignment systems face concentrated supply from Japanese quarries.
- Gold bumping process substitution threat:Copper-pillar and solder-bump alternatives reduce noble metal dependence but require incompatible bonding head thermal profiles.
- EU RoHS lead-free solder restrictions:Equipment qualification timelines extend 18-24 months for European-bound display exports using alternative bump metallurgies.
Strategic Opportunities
- India display fab greenfield construction:PLI scheme subsidies for semiconductor and display manufacturing attract first-mover equipment vendors establishing service infrastructure.
- MicroLED transfer bonding convergence:Mass-transfer pick-and-place technologies merge with COG precision alignment for next-generation emissive displays.
- Energy-efficient thermal budget platforms:Japan's METI green innovation fund prioritizes reduced-power bonding systems aligned with factory decarbonization targets.
Industry Challenges
- Multi-axis motion control engineering scarcity:Sub-micron stage design expertise concentrates in legacy Japanese and German precision equipment sectors.
- Cross-border GB/T and JIS certification synchronization:Divergent national standards for flat-panel display manufacturing equipment create redundant qualification burdens.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | COG Bonder Market |
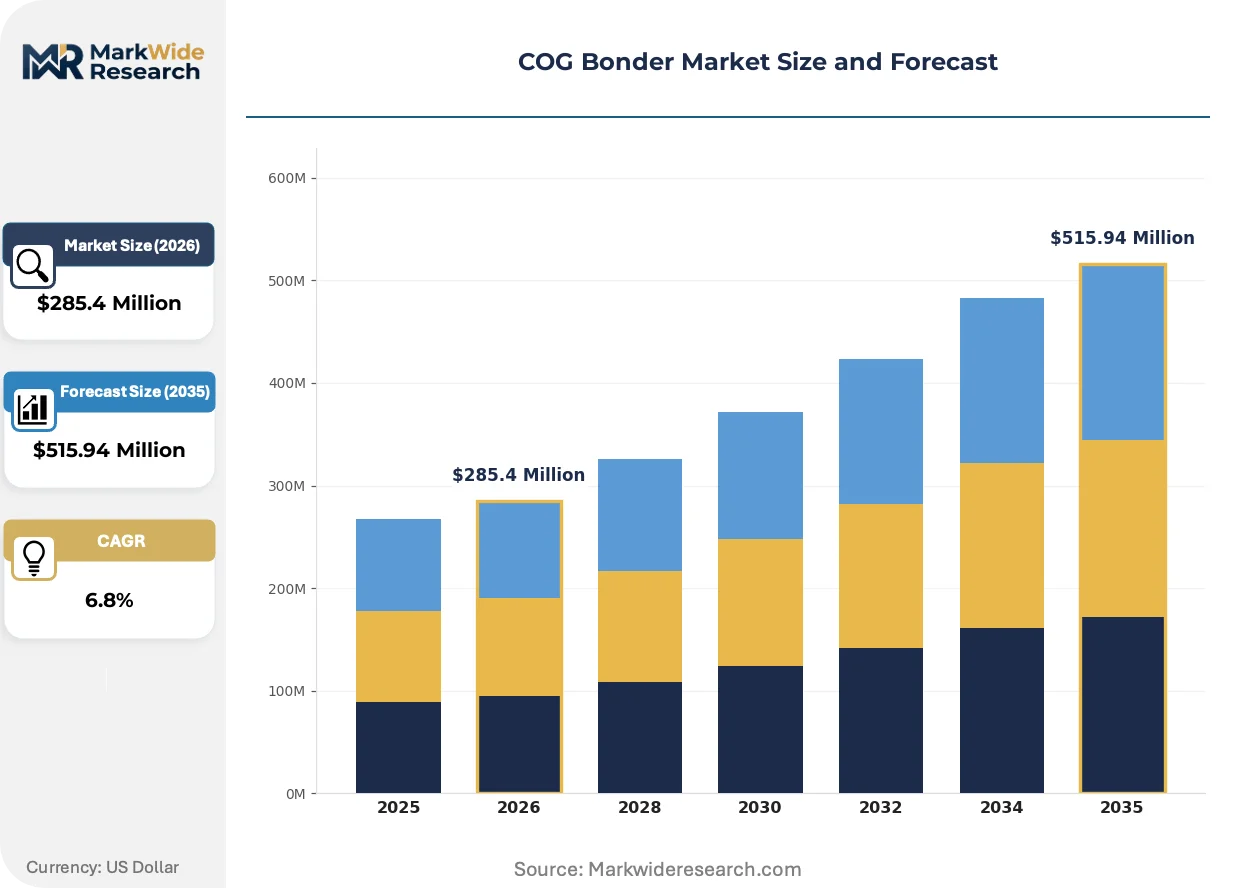
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $515.94 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Film-Based, Sheet-Based, Liquid Adhesives, Paste End User: Consumer Electronics, Automotive Electronics, Medical Devices, Renewable Energy Technology: Die Attach, Wire Bonding, Flip Chip, EMI Shielding Application: Smartphones, Tablets, Wearables, LED Displays |
| Companies Covered | Shibaura Mechatronics, Ings Shinano, Core Precision Material, Panasonic, SJ-Himech, Ohashi Engineering, Shenzhen Olian, Wanbo Hi-Tech, Santek, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
COG Bonder Market Trends and Innovations
Machine vision integration and predictive thermal modeling are transforming how COG bonders self-calibrate during production runs, reducing setup waste and enabling smaller lot sizes for flexible display manufacturing.
Real-time adaptive alignment using high-speed camera feedback is digitizing the traditional mechanical settling approach to die placement. Korean and Chinese panel makers deploy these systems for foldable OLED production where substrate deformation during bonding requires dynamic position correction. The technology is digitizing quality control by embedding dimensional verification directly into the bonding cycle rather than post-process inspection.
REACH restrictions on indium compounds are accelerating transparent conductive oxide alternatives in display trace patterns. Equipment vendors must qualify bonding profiles for silver nanowire and metal mesh substrates with different surface energies and thermal conductivities. European automotive display exports face the tightest compliance timelines as reformulated trace materials enter qualification pipelines.
Consolidated procurement through display panel consortiums is compressing vendor negotiation cycles and unbundling after-sales service contracts. Chinese fab operators now separate equipment purchase from multi-year maintenance agreements, forcing Japanese and European vendors to establish localized technical service centers. This restructuring is most advanced in Shenzhen and Suzhou where panel maker procurement teams centralize cross-fab equipment standardization.
COG Bonder Market Segmentation
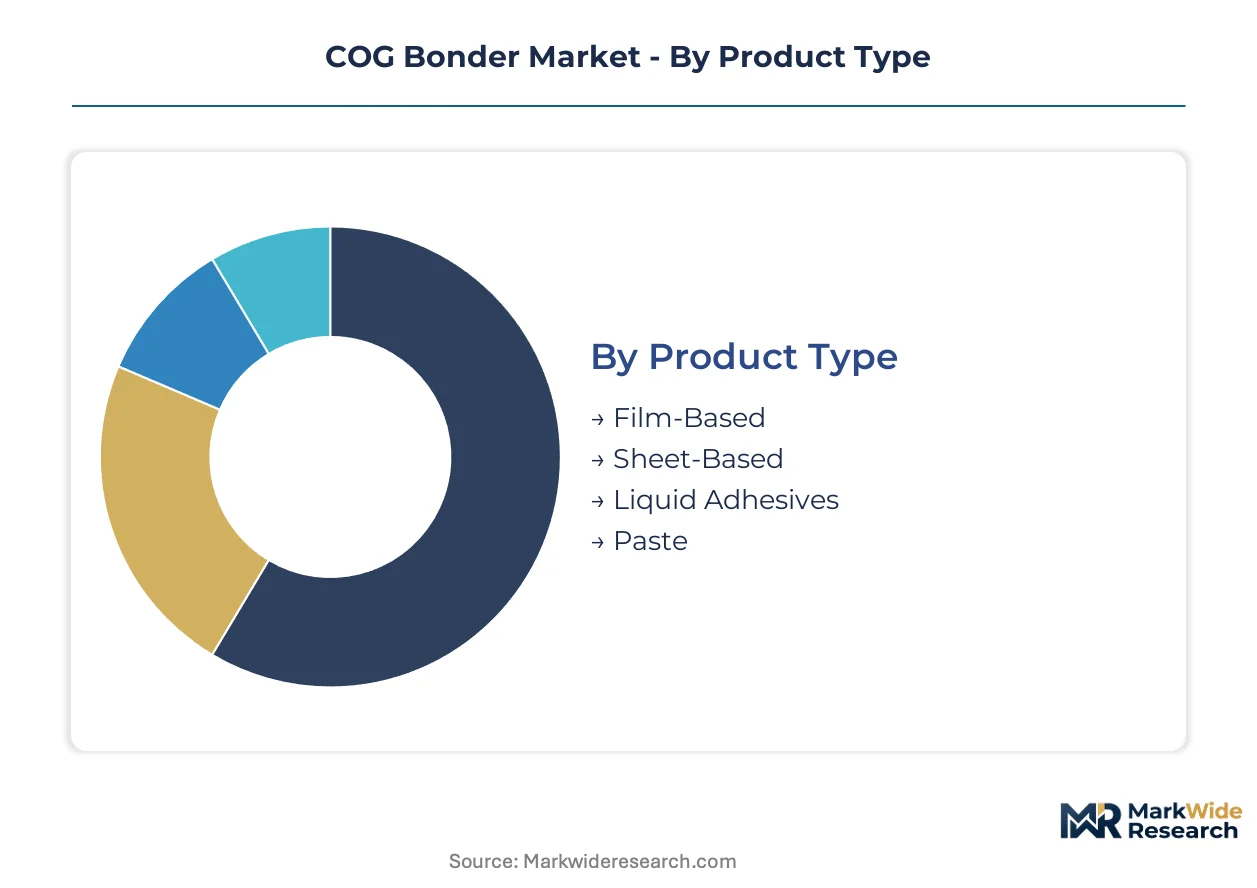
COG bonder procurement patterns diverge sharply across bonding chemistry formats, end-use reliability requirements, and interconnect technologies. Equipment specifications must align with substrate thermal expansion coefficients and bump metallurgies unique to each segment.
Product Type:
Film-based systems cycle fastest in high-volume smartphone lines, while paste formulations linger in qualification for automotive thermal cycling validation. Sheet-based platforms occupy mid-cycle refresh intervals for tablet manufacturing.
- Film-Based:Anisotropic conductive film bonding dominates smartphone OLED production with sub-3 micron alignment tolerances and 150°C thermal compression profiles. Shenzhen and Suzhou panel fabs consume these systems in six-month equipment refresh cycles driven by bezel reduction roadmaps.
- Sheet-Based:Pre-cut adhesive sheets serve mid-size tablet displays requiring consistent bondline thickness across 300mm+ glass substrates. Korean display makers favor this format for curved automotive instrument panels where uniform thermal distribution matters more than absolute pitch density.
- Liquid Adhesives:Dispensed epoxy systems enable repair-friendly bonding for medical display assemblies requiring biocompatibility certification.
- Paste:Screen-printable conductive pastes retain position in cost-constrained LED signage where manual rework tolerance outweighs automation precision.
Film-based systems dominate installed base. Paste formulations are where expansion concentrates for specialty display applications.
End User:
Consumer electronics drives absolute unit volume, yet automotive electronics commands the longest equipment qualification timelines and highest service contract values.
- Consumer Electronics:Smartphone and tablet manufacturers in China, Japan, and South Korea account for the majority of annual COG bonder procurement. MIIT localization mandates redirect equipment sourcing toward domestic Chinese vendors for new Shenzhen fab capacity.
- Automotive Electronics:Heads-up displays and curved instrument panels require extended thermal cycling validation per METI reliability standards. Panasonic anchors this segment with equipment rated for -40°C to 105°C operational envelopes.
- Medical Devices:Diagnostic imaging displays demand sterile bonding environments and traceable process documentation for FDA and PMDA submissions.
- Renewable Energy:Solar inverter display modules use simplified COG bonding with relaxed pitch requirements compared to mobile applications.
Consumer electronics dominates installed base. Automotive electronics is where expansion concentrates for thermal cycling-rated platforms.
Technology:
Flip-chip platforms refresh fastest as copper-pillar bumping displaces gold wire interconnects, while wire bonding persists in legacy infrastructure amortization.
- Flip Chip:Copper-pillar bumping compresses interconnect pitches below 10 microns, forcing sub-micron alignment system recalibration. Chinese panel makers adopt this technology fastest under MIIT semiconductor packaging mandates.
- Wire Bonding:Gold and aluminum wedge bonding retains share in automotive and industrial displays where TAB infrastructure depreciation outweighs bezel reduction imperatives. Equipment vendors extend service life through head retrofits rather than full system replacement.
- Die Attach:Epoxy-based die bonding serves cost-sensitive tablet displays where electrical interconnect density requirements remain modest.
- EMI Shielding:Conductive adhesive bonding for electromagnetic interference mitigation accompanies 5G smartphone display driver integration.
Wire bonding dominates installed base. Flip chip is where expansion concentrates for pitch compression roadmaps.
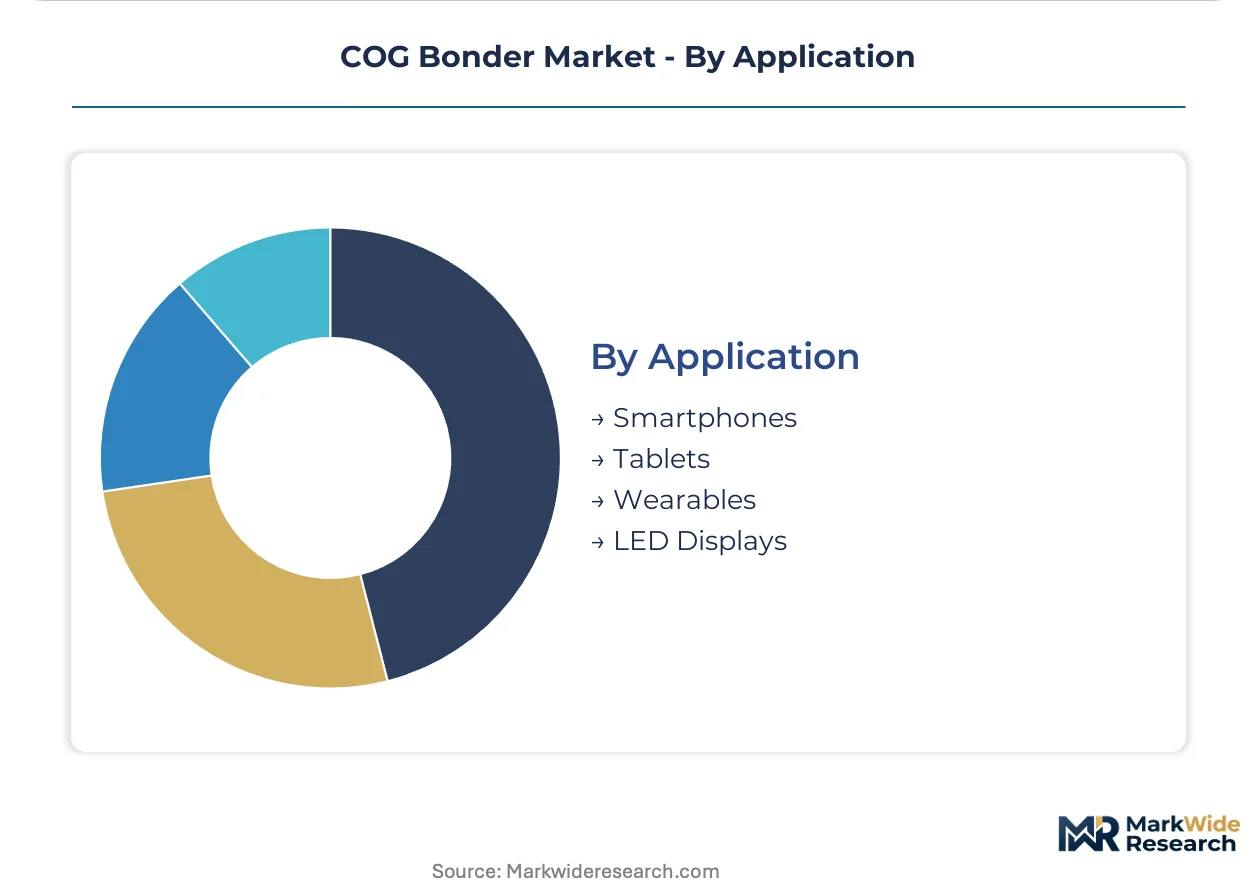
Application:
Smartphone manufacturing cycles equipment fastest for bezel reduction, while LED display bonding platforms operate on decade-long depreciation schedules.
- Smartphones:Foldable OLED production demands real-time adaptive alignment for substrate deformation during bonding. Korean panel makers deploy machine vision-integrated systems for dynamic position correction in 1mm bezel target designs.
- Tablets:Larger substrate formats prioritize throughput over absolute pitch density, favoring gantry-style bonders with 500mm+ travel ranges.
- Wearables:Circular and irregular display geometries require programmable bonding head paths for smartwatch and AR glass applications.
- LED Displays:Direct-view LED modules use simplified COG bonding for driver IC attachment to ceramic or PCB substrates rather than glass.
LED displays dominate installed base. Smartphones are where expansion concentrates for adaptive alignment platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japanese precision equipment exports to Chinese display fabs dominate trade flows, with Korean panel makers sourcing alignment systems from both domestic and Japanese vendors. Equipment procurement concentrates in East Asian manufacturing corridors where MIIT localization mandates redirect supply chains toward indigenous Chinese suppliers.
China
Shenzhen and Suzhou manufacturing clusters drive COG bonder demand as BOE, CSOT, and Tianma expand OLED capacity for smartphone exports. MIIT semiconductor packaging mandates redirect procurement toward domestic equipment vendors including Shenzhen Olian and Wanbo Hi-Tech. Suzhou's display fab concentration now sources over half of new bonding equipment from local suppliers under import substitution programs.
Japan
Chubu and Kansai industrial regions anchor precision motion control supply for sub-micron alignment systems. METI green innovation fund priorities channel R&D subsidies toward reduced-thermal-budget bonding platforms. Shibaura Mechatronics and Panasonic maintain technical service centers in Nagoya and Osaka to support Chinese and Korean fab customers directly.
South Korea
Samsung Display and LG Display procurement drives flip-chip copper-pillar bonding equipment refresh cycles in Gyeonggi and Chungcheong provinces. Korean panel makers deploy machine vision-integrated systems for foldable OLED production requiring real-time substrate deformation correction. Domestic equipment vendors compete with Japanese imports for Samsung's Gumi and Asan fab expansions.
Taiwan
AUO and Innolux procurement sustains COG bonder demand for automotive and industrial display segments. Taiwanese panel makers prioritize equipment qualifying for extended thermal cycling per automotive reliability standards. Hsinchu Science Park concentration attracts Japanese bonding equipment vendors establishing localized calibration and service operations.
India
PLI scheme subsidies for semiconductor and display manufacturing attract first-mover equipment vendors establishing service infrastructure. Vedanta-Foxconn and ISMC Digital fab projects in Gujarat and Karnataka create greenfield demand for bonding equipment qualification. Domestic display assembly operations in Noida and Chennai currently rely on imported bonding systems from Chinese and Japanese suppliers.
COG Bonder Market Competitive Landscape
On the supply side, the industry is bifurcated between Japanese precision heritage vendors and Chinese cost-optimized challengers. The vendor base clusters around three strategic archetypes: sub-micron alignment specialists, mid-tier smartphone line suppliers, and automotive thermal-cycling platform providers. Dominant competitive moves include geographic service center localization and multi-year maintenance contract unbundling.
Among Japanese precision equipment fabricators, Shibaura Mechatronics and Panasonic occupy positions exemplifying the alignment-specialist and automotive-platform archetypes respectively. Shenzhen Olian represents the Chinese cost-optimized tier competing aggressively on equipment pricing for domestic panel maker procurement. These three companies illustrate how vendor strategies diverge across precision requirements, thermal cycling specifications, and geographic service proximity.
| Leading Market Players |
|---|
| Shibaura Mechatronics |
| Ings Shinano |
| Core Precision Material |
| Panasonic |
| SJ-Himech |
| Ohashi Engineering |
| Shenzhen Olian |
| Wanbo Hi-Tech |
| Santek |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in Chinese display panel fabs is compressing equipment pricing power while simultaneously accelerating procurement localization under MIIT mandates. Utilization rates below 70% at Shenzhen and Suzhou facilities are forcing domestic equipment vendors to absorb margin pressure to maintain market share against Japanese precision imports.
Pricing Analysis
The technology-generation pricing gap between wire-bonding legacy systems and flip-chip copper-pillar platforms spans approximately 40-60% at list price, with next-generation microLED-ready bonders commanding additional premiums. Three-tier pricing structure across premium, standard, and economy levels segments by alignment accuracy certification and after-sales service bundling. Cost compression in mid-tier smartphone assembly lines is intensifying because Chinese vendors are unbundling multi-year maintenance contracts. Chinese panel makers exhibit highest price sensitivity, while Korean foldable OLED producers prioritize sub-micron accuracy over equipment cost.
Supply Chain Analysis
Tariff exposure between Japan and China dominates supply chain risk planning for precision motion control components. Manufacturing concentrates in Japan for granite vibration-dampening substrates and high-precision linear motors, in Germany for multi-axis controller hardware, and in China for structural frames and power electronics. Component sourcing draws from Japanese quarries for granite bases, Swiss suppliers for optical encoders, and Taiwanese foundries for specialized ASICs. Single-source vulnerability persists for sub-micron stage design expertise concentrated in legacy Japanese precision equipment sectors. Distribution runs through direct technical sales for premium tiers and regional equipment distributors for cost-optimized segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hardware-software unbundling is expanding the service-attach opportunity faster than equipment sales, with predictive maintenance subscriptions and real-time alignment calibration services now representing the fastest-growing revenue layer.
For Market Incumbents: Entrench market position by localizing technical service centers in Shenzhen and Suzhou to match Chinese panel maker procurement centralization, while investing in JIS-GB/T dual certification to eliminate redundant qualification burdens. Copper-pillar bumping thermal profile incompatibility threatens gold-bump equipment installed base; backward integration into bonding head retrofit kits extends asset life and defends recurring revenue streams. For New Entrants and Emerging Players: Mid-market automotive display bonding in India represents the most penetrable entry point, with Vedanta-Foxconn and ISMC Digital fab projects creating greenfield demand absent entrenched vendor relationships. Medical device display assemblies requiring biocompatibility certification offer specialty positioning away from smartphone price wars. Partner with Japanese precision component suppliers for granite substrate and encoder sourcing to bypass motion control engineering scarcity. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among vendors with unbundled predictive maintenance platforms and multi-fab service contracts. Long-term viability across the analysis window favors equipment makers with demonstrated cross-certification agility between METI semiconductor standards and China's GB/T national frameworks. Acquisition target archetype: precision alignment specialists with existing JIS certification and underutilized capacity in secondary Japanese industrial regions. Watch for MIIT localization mandate enforcement intensity as inflection indicator for indigenous vendor market share trajectory.| Strategic Initiative | Industry Significance |
|---|---|
| Service Infrastructure Localization | Establishing technical centers in Shenzhen and Suzhou aligns with Chinese panel maker procurement centralization requirements. |
| Dual Certification Investment | Simultaneous JIS and GB/T qualification reduces redundant validation timelines for cross-border equipment sales. |
| Predictive Maintenance Platform Launch | Machine vision-integrated self-calibration enables subscription-based recurring revenue from installed base. |
| Copper-Pillar Thermal Profile Development | Next-generation bonding head compatibility defends market position against gold-bump substitution threat. |
| MicroLED Transfer Bonding Convergence | Mass-transfer pick-and-place technology integration captures next-generation emissive display equipment demand. |
Research Methodology
Cross-validation between equipment vendor technical documentation and panel maker procurement specifications anchors the qualitative findings in this study. Primary interviews with display fab engineering directors, semiconductor packaging equipment procurement managers, precision motion control R&D leads, and aftermarket service operations heads combined with secondary analysis of METI green innovation fund disclosures, MIIT domestic semiconductor packaging policy circulars, SEC filings from listed display panel makers, and Japanese customs equipment export data. Bottom-up triangulation across bonding chemistry format shipments and top-down validation against fab capacity expansion announcements ensured consistency.
Calibration against historical equipment refresh cycles and technology substitution patterns shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include bonding chemistry format, end-use reliability tier, interconnect technology generation, and regional regulatory cluster. CAGRs derived from equipment unit demand projections weighted by average selling price evolution, with specific inputs from OLED panel miniaturization roadmaps and automotive thermal cycling standard revisions.
Macroeconomic conditions sit as an overlay; deviation in display panel fab utilization rates, yen-yuan exchange volatility, or indium compound supply constraints would shift the trajectory. Forecasts reflect documented assumptions regarding MIIT mandate enforcement pacing and copper-pillar bumping adoption curves across Chinese manufacturing clusters. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Equipment
United States Ball Bearing Market
Industrial Equipment
Air Filters Market
Industrial Equipment
Precision Machine Market
Industrial Equipment
Automatic Laser Welding Machine Market
Industrial Equipment
Bellows Vacuum Suction Cup Market
Industrial Equipment
Air Bearing Spindle Market
Industrial Equipment
Electronic Beam Machining Market
Industrial Equipment
Middle-East Fans and Blowers Market
Industrial Equipment
North America Fans and Blowers Market
Industrial Equipment
Electric Cartridge Heaters Market
Industrial Equipment
Vacuum Concentrators Market
Industrial Equipment
Hot Runner Temperature Controller Market
Industrial Equipment
Global DC Drives Market
Industrial Equipment
Laser Cleaning Market
Industrial Equipment
Refrigeration Coolers Market
Industrial Equipment
High-Speed Electric Spindle Market