
 Global Semiconductor Seals Market | 2026-2036
Global Semiconductor Seals Market Size, Share, and Industry Trends Forecast 2026-2036
Global Semiconductor Seals Market Outlook
East Asian elastomer compounders is repositioning capacity toward semiconductor-grade fluoroelastomer production. DuPont leverages its Kalrez product line to sustain premium positioning in vacuum chamber sealing applications. Trelleborg Sealing Solutions anchors European demand through cleanroom-certified manufacturing facilities in Germany and Sweden. Greene Tweed specializes in chemically resistant perfluoroelastomer formulations for sub-7nm lithography environments.
Semiconductor seals are precision-engineered elastomeric or polymeric barriers designed to maintain vacuum integrity, chemical isolation, and thermal stability in wafer processing equipment, typically rated for temperatures exceeding 200°C and exposure to plasma chemistries. Their primary purpose is preventing contamination of silicon wafers during deposition, etch, and lithography steps where particulate outgassing causes catastrophic yield loss. Fluoroelastomer materials lead revenue contribution due to their plasma resistance and extended service intervals in aggressive process chemistries. O-rings represent the most widely consumed product geometry, though sealing films for 3D-IC bonding applications exhibit the steepest growth trajectory as advanced packaging architectures proliferate. Epoxy-based thermal pads remain a mature margin pool, with pricing pressure concentrated in consumer electronics supply chains.
EPA enforcement of PFAS reporting under TSCA Section 8(a)(7) is tightening material traceability requirements for seals entering US semiconductor fabs. REACH restrictions on per- and polyfluoroalkyl substances are accelerating European transitions to fluorine-free alternatives, while Japan's METI promotes domestic supply chain resilience through JIS-certified seal qualification programs. China's NMPA and GB standards enforcement shapes import access for foreign seal suppliers serving domestic foundry expansion. Stakeholders must monitor regulatory divergence between jurisdictions, as compliance fragmentation threatens to bifurcate global product portfolios and strain R&D allocation decisions.
Market Dynamics
Advanced packaging architectures for AI accelerators are compressing seal replacement cycles while forcing material upgrades to withstand higher thermal loads and plasma exposure in 3D-IC bonding processes.
Growth Catalysts
- Fluorocarbon plasma resistance:Aggressive chemistries in sub-7nm etch chambers degrade standard elastomers within weeks, forcing specification upgrades that expand addressable seal volume per tool.
- Taiwan cluster expansion:Hsinchu Science Park foundries operate the world's densest concentration of EUV lithography systems, each requiring ultra-high purity sealing solutions replaced on accelerated maintenance schedules.
- EPA TSCA Section 8(a)(7):Mandatory PFAS reporting for seals entering US fabs tightens material traceability, advantaging qualified suppliers with established compliance documentation.
Market Restraints
- Fluorine feedstock volatility:Perfluorinated monomer supply concentrates among Japanese and Belgian chemical producers, exposing compounders to input cost swings and allocation constraints.
- REACH substance restrictions:ECHA's accelerating limits on per- and polyfluoroalkyl substances force European fabs into costly material qualification cycles with uncertain alternative performance.
- Physical vapor deposition limits:Thermal spray coatings on metal seals cannot achieve the angstrom-level surface finish required for EUV vacuum chambers, capping metallic substitution.
Strategic Opportunities
- India semiconductor manufacturing:PLI scheme subsidies for domestic foundry construction create first-mover advantage for seal suppliers establishing local compounding and cleanroom finishing capacity.
- Photonic packaging crossover:Silicon photonics assembly requires hermetic sealing for optical interconnects, opening adjacent demand from datacom transceiver manufacturers.
- Japan METI resilience programs:JIS-certified seal qualification mandates for critical supply chains direct procurement toward domestic-qualified vendors with proven contamination control.
Industry Challenges
- Cleanroom polymer science talent:Formulation chemists capable of balancing plasma resistance against metallic ion outgassing remain concentrated among a handful of specialized compounders.
- EUV chamber certification timelines:ASML and foundry joint qualification protocols for new seal materials extend 18-24 months, delaying revenue recognition for reformulated products.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Semiconductor Seals Market |
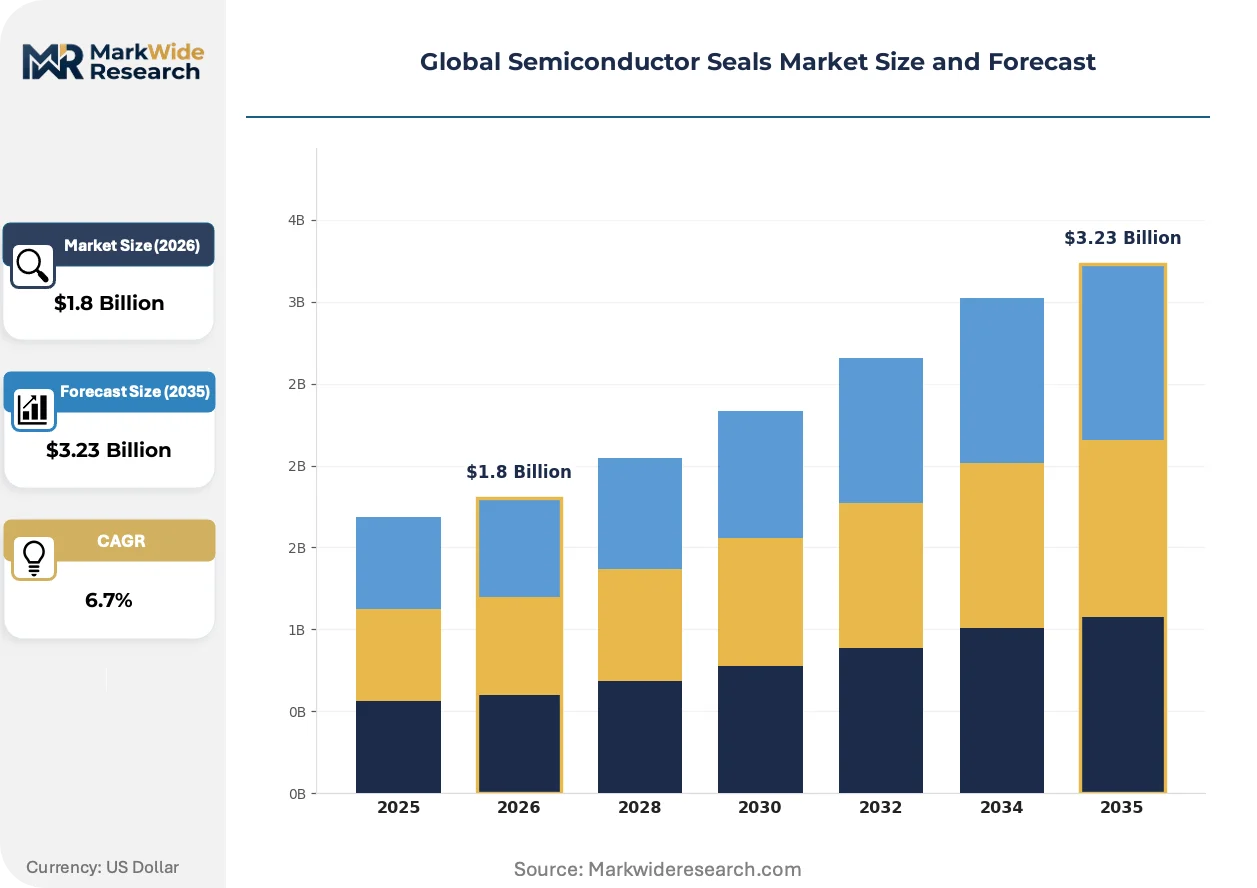
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: O-Rings, Gaskets, Sealing Films, Thermal Pads Material: Silicone, Fluoroelastomer, Polyurethane, Epoxy Application: Telecommunications, Consumer Electronics, Automotive, Industrial Equipment End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Device Manufacturers |
| Companies Covered | DuPont, Parker Hannifin, Trelleborg Sealing Solutions, NOK Corporation, Eagle Industry, Daikin, Valqua, Greene Tweed, Freudenberg Sealing Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Semiconductor Seals Market Strategic Shifts
Material science breakthroughs are compressing the performance gap between legacy fluoroelastomers and next-generation alternatives while regulatory chemistry bans force simultaneous portfolio diversification.
Perfluoroelastomer nanocomposites are integrating ceramic fillers to extend service intervals in high-power plasma etch environments. Leading memory manufacturers in South Korea and Taiwan specify these formulations for 3D NAND stack etch chambers where process chemistries attack conventional seals. The technology is integrating thermal management and chemical resistance into unified material platforms that reduce unplanned maintenance events.
REACH F-Gas Regulation amendments are accelerating European transitions toward hydrogenated nitrile and thermoplastic elastomer alternatives for non-plasma applications. German and Swedish seal manufacturers are requalifying cleanroom production lines for fluorine-free compounds ahead of anticipated substance bans. Packaging equipment in legacy node fabs faces the steepest reformulation pressure as grandfathering provisions expire.
Foundry procurement organizations are consolidating vendor panels to three approved suppliers per seal category, compressing qualification slots for emerging compounders. Taiwan-based buyers now require dedicated local technical service teams as a precondition for specification inclusion. This concentration is most visible in Hsinchu and Taichung Science Park procurement where tool uptime guarantees dominate supplier selection criteria.
Global Semiconductor Seals Market Segmentation
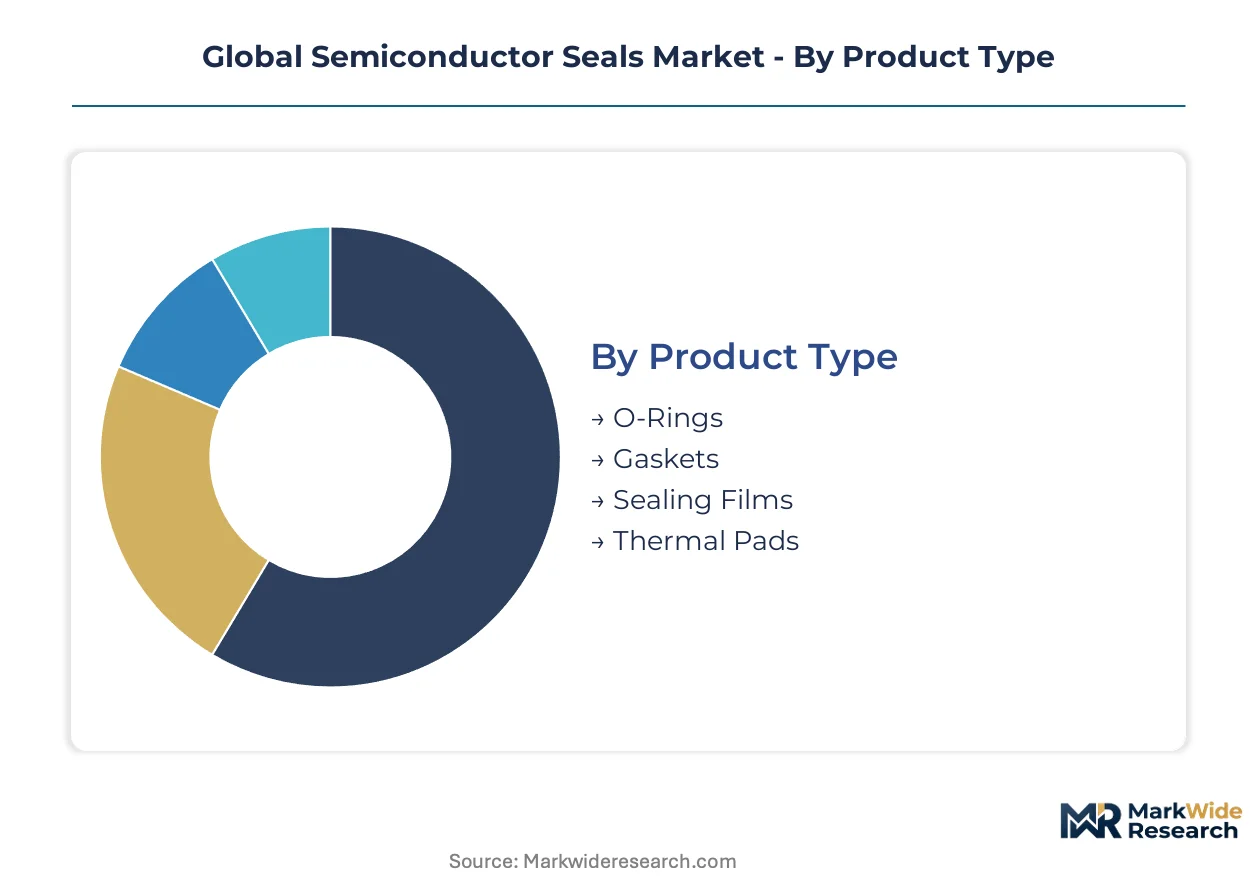
Semiconductor seal procurement varies sharply by performance tier and contamination risk exposure. Specification divergence across product geometries and material platforms creates distinct margin pools that suppliers must navigate simultaneously.
Product Type:
Volume concentration favors standardized geometries, while premium capture concentrates in advanced packaging formats requiring atomic-level sealing precision.
- O-Rings:Circular elastomeric profiles dominate wafer processing tool maintenance schedules due to standardized groove compatibility and rapid field replacement protocols. Taiwan's Hsinchu Science Park fabs consume the densest volumes, driven by EUV lithography chamber refurbishment cycles that demand weekly seal exchanges.
- Sealing Films:Ultra-thin polymer barriers enable hermetic 3D-IC bonding where thermal compression bonding requires angstrom-scale surface conformity. Memory manufacturers in South Korea specify these formulations for high-bandwidth memory stack assembly, compressing replacement cycles as chiplet architectures proliferate.
- Gaskets:Custom-molded profiles seal chamber flanges and viewport assemblies in plasma etch equipment.
- Thermal Pads:Epoxy-based interface materials manage heat dissipation in legacy packaging equipment.
Mature deployment sits with O-Rings. Newer deployment is concentrated in Sealing Films.
Material:
Plasma resistance requirements stratify material selection by process chemistry aggressiveness.
- Fluoroelastomer:Perfluorinated polymer chains deliver extended service intervals in fluorine-based plasma environments where standard elastomers degrade within days. Sub-7nm etch chambers at leading foundries mandate these formulations, with EPA TSCA Section 8(a)(7) reporting requirements now filtering supplier qualification.
- Silicone:Hydrogen-modified formulations serve non-plasma applications where metallic ion outgassing tolerance permits lower-cost alternatives. European packaging equipment manufacturers are transitioning toward these compounds ahead of REACH substance restrictions on perfluorinated chemistries.
- Polyurethane:Thermoset variants seal atmospheric pressure process modules with moderate chemical exposure.
- Epoxy:Rigid polymer systems anchor thermal management applications in mature node packaging.
Established volume concentrates in Fluoroelastomer. Fastest specification migration is occurring in Silicone.
Application:
End-use thermal profiles and cleanliness requirements drive material specification divergence.
- Consumer Electronics:High-volume smartphone and tablet chip packaging generates recurring demand for cost-optimized seals in wire bonding and flip-chip assembly. Chinese foundry expansion under GB standards enforcement is reshaping supplier access requirements for this segment.
- Telecommunications:Baseband processor and RF front-end modules require hermetic sealing for environmental protection in outdoor installations.
- Automotive:ADAS chip packaging demands extended temperature range performance for under-hood reliability.
- Industrial Equipment:Power semiconductor modules tolerate broader contamination specifications than wafer processing equipment.
Price pressure concentrates in Consumer Electronics. Technical specification intensity peaks in Telecommunications.
End User:
Procurement authority and technical specification control vary across the supply chain hierarchy.
- OEMs:Original equipment manufacturers of deposition, etch, and lithography tools retain final seal specification authority, embedding approved vendor lists into tool configuration documentation. ASML and Tokyo Electron qualification protocols require 18-24 month validation cycles that lock compounders into long-term supply relationships.
- Tier-1 Suppliers:Subsystem integrators procure seals for chamber refurbishment and upgrade services.
- Device Manufacturers:Leading foundries and IDMs influence material selection through joint development agreements.
- Aftermarket Providers:Independent service organizations source equivalent seals for out-of-warranty equipment maintenance.
Specification control rests with OEMs. Procurement volume concentrates with Device Manufacturers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Belgian and Japanese chemical producers anchor perfluorinated monomer supply chains that feed compounders serving wafer fabrication clusters worldwide.
United States
EPA enforcement of TSCA Section 8(a)(7) PFAS reporting tightens material traceability for seals entering domestic fabs. The CHIPS Act subsidies accelerate construction of new foundry capacity in Arizona and Texas. Phoenix and Austin metropolitan areas concentrate emerging cleanroom seal demand from Intel and TSMC greenfield projects.
Taiwan
Hsinchu Science Park foundries operate the densest concentration of EUV lithography systems globally, each requiring ultra-high purity sealing solutions. The National Development Council prioritizes domestic supply chain resilience for critical semiconductor materials. Taichung Science Park procurement teams now mandate dedicated local technical service teams as a precondition for vendor qualification.
South Korea
Samsung and SK Hynix memory manufacturers specify perfluoroelastomer nanocomposites for 3D NAND stack etch chambers where aggressive chemistries attack conventional seals. The Ministry of Trade, Industry and Energy channels support through K-Semiconductor Belt initiatives. Yongin and Icheon industrial complexes anchor domestic demand for plasma-resistant sealing formulations.
Japan
Tokyo Electron and Shin-Etsu Chemical anchor equipment and material supply chains that shape regional seal specifications. METI promotes domestic supply chain resilience through JIS-certified seal qualification programs for critical infrastructure. Kyoto and Osaka prefectures concentrate specialized compounders serving foundry refurbishment cycles.
Germany
ECHA REACH restrictions on per- and polyfluoroalkyl substances force costly material qualification cycles with uncertain alternative performance. The Federal Ministry for Economic Affairs funds transition programs toward fluorine-free compounds for packaging equipment. Dresden and Bavarian microelectronics clusters drive cleanroom-certified seal demand from legacy and advanced node fabs.
Global Semiconductor Seals Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue adjacent spaces in photonic packaging and fluorine-free alternatives. The vendor base stratifies across three performance tiers: premium perfluoroelastomer specialists, mid-tier fluoroelastomer compounders, and cost-optimized silicone suppliers. Strategic archetypes include integrated chemical-to-seal manufacturers, cleanroom-certified precision molders, and regional aftermarket distributors. Dominant competitive moves center on portfolio diversification toward REACH-compliant formulations and geographic expansion into India PLI-subsidized foundry zones.
Within the premium-tier vector, DuPont and Greene Tweed exemplify specialized compounders commanding specification authority in sub-7nm lithography environments. Trelleborg Sealing Solutions anchors European demand through cleanroom-certified manufacturing presence. These three represent distinct archetypes: the integrated materials science conglomerate, the application-specific formulation specialist, and the regional precision molder with foundry-adjacent service infrastructure.
| Leading Market Players |
|---|
| DuPont |
| Parker Hannifin |
| Trelleborg Sealing Solutions |
| NOK Corporation |
| Eagle Industry |
| Daikin |
| Valqua |
| Greene Tweed |
| Freudenberg Sealing Technologies |
| Others |
Value Chain & Pricing Dynamics
Foundry procurement consolidation to three approved suppliers per seal category is forcing compounders to absorb qualification costs and extend technical service commitments, compressing margins while elevating performance guarantees as non-negotiable table stakes. This buyer-driven concentration rewards incumbents with established ASML and Tokyo Electron approvals while squeezing emerging suppliers into price-competitive aftermarket channels.
Pricing Analysis
Warranty and field service bundling now separates premium compounders from transactional suppliers, with DuPont and Greene Tweed commanding 40-60% price premiums for Kalrez and perfluoroelastomer formulations that include 24-hour technical response and contamination failure indemnification. Three-tier pricing structure across premium certified, standard qualified, and economy aftermarket levels stratifies by EUV chamber certification status and metallic ion outgassing documentation depth. Cost compression in consumer electronics packaging seals is intensifying because Chinese foundry expansion under GB standards enforcement favors local qualified suppliers with lower logistics overhead. Device manufacturers in Taiwan's Hsinchu cluster exhibit lowest price sensitivity due to tool uptime guarantee penalties, while aftermarket service organizations serving mature node fabs face acute margin pressure from equivalent seal sourcing.
Supply Chain Analysis
Dual-sourcing mandates from TSMC and Samsung procurement organizations require qualification of redundant suppliers for critical fluoroelastomer O-rings, driving compounders to maintain parallel production lines across Taiwan and South Korea despite 18-24 month ASML joint validation timelines. Perfluorinated monomer supply draws from Belgian and Japanese chemical producers, with Daikin and Solvay anchoring feedstock availability for semiconductor-grade polymerization. Single-source vulnerability concentrates in sub-7nm perfluoroelastomer nanocomposite formulations where Greene Tweed and DuPont hold effective duopoly. Distribution runs through OEM-embedded vendor lists for new tool builds, while device manufacturer direct procurement dominates chamber refurbishment volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market is executing a material transition from legacy perfluorinated chemistries to REACH-compliant alternatives and ceramic-filled nanocomposites, with fluorine-free qualification cycles and EUV thermal load tolerance defining competitive survival.
For Market Incumbents: To counter REACH substance restrictions and ECHA F-Gas Regulation amendments, DuPont and Trelleborg must accelerate fluorine-free compound qualification ahead of grandfathering expiration while securing backward integration into hydrogenated nitrile feedstocks to control input cost volatility. Certification investment in JIS-qualified cleanroom facilities for Japan METI resilience programs provides defensive moat against emerging Asian compounders. For New Entrants and Emerging Players: Photonics packaging specialists and silicon photonics transceiver manufacturers represent the most penetrable buyer archetype, as hermetic sealing for optical interconnects lacks established incumbent relationships and tolerates shorter qualification cycles than EUV lithography. Target India's PLI-subsidized foundry construction with local compounding partnerships to bypass 18-24 month import qualification barriers. For Investors and Strategic Acquirers: The window for entry favors specialized compounders with proven ceramic nanocomposite formulation IP and existing cleanroom infrastructure in Taiwan or South Korea. Long-term viability hinges on regulatory chemistry transition execution rather than volume scale. Watch ECHA substance restriction enforcement velocity as the primary inflection indicator for portfolio reallocation toward fluorine-free alternatives.| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Compliant Formulation Development | ECHA substance restrictions force 18-24 month requalification cycles for European packaging equipment. |
| India Local Compounding Capacity | PLI scheme subsidies for domestic foundry construction create first-mover advantage for qualified suppliers. |
| Ceramic Nanocomposite R&D Partnership | Samsung and SK Hynix specifications for 3D NAND etch chambers drive premium formulation demand. |
| JIS-Certified Cleanroom Investment | METI resilience programs direct procurement toward domestic-qualified vendors with contamination control. |
| Photonics Packaging Technical Service Teams | Silicon photonics assembly for datacom transceivers opens adjacent hermetic sealing demand. |
Study Parameters
Independent corroboration across foundry procurement executives, OEM platform engineers, and aftermarket service directors underwrites the qualitative findings, with secondary validation drawing from EPA TSCA Section 8(a)(7) filings, ECHA REACH substance restriction updates, and Japan METI supply chain resilience program documentation. Bottom-up seal consumption estimates triangulate against top-down wafer fabrication equipment capex disclosures and chamber refurbishment cycle frequencies.
The forecast window anchors to historical replacement cycle intensification during EUV lithography ramp periods and advanced packaging architecture transitions, with segmentation modeling across product geometry, material platform, application thermal profile, and end-user procurement authority. CAGRs derive from tool installation base expansion, seal replacement frequency compression, and specification upgrade penetration. Industry-specific inputs include ASML EUV system delivery schedules and foundry node transition timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to ECHA substance restriction enforcement velocity, perfluorinated monomer supply allocation constraints, and China GB standards import access revisions. Deviation in EUV lithography adoption rates or 3D-IC packaging architecture proliferation would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Packaging
Multichip Package Market
Semiconductor Packaging
Advanced Semiconductor Packaging Market
Semiconductor Packaging
Wafer Level Packaging (WPL) Market
Semiconductor Packaging
Through-Silicon via (TSV) IC Packaging Market
Semiconductor Packaging
System-On-Package Market
Semiconductor Packaging
Chip Carrier Socket Market
Semiconductor Packaging
Memory Packaging Market
Semiconductor Packaging
NOR-Based Multi-Chip Packages Market
Semiconductor Packaging
System in Package (SIP) Die Market
Semiconductor Packaging
Asia Pacific LED Packaging Market
Semiconductor Packaging
Wafer Carrier Boxes Market
Semiconductor Packaging
ESD Stackable Boxes Market
Semiconductor Packaging
Ceramic IC Packages Market
Semiconductor Packaging
Global Semiconductor Equipment Packaging and Test Market
Semiconductor Packaging
Fan Out Packaging Market
Semiconductor Packaging
Semiconductor Packaging Material Market