
 Through Silicon via (TSV) Packaging Market | 2026-2036
Through Silicon via (TSV) Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Through Silicon via (TSV) Packaging Market Analytics
Advanced packaging engineering talent is collapsing across East Asian foundry zones, forcing TSMC and Samsung Electronics to escalate apprenticeship pipelines and automated process controls. TSMC leverages its captive CoWoS capacity to dominate high-bandwidth memory interposers. Intel Corporation sustains aggressive R&D outlays on Foveros Direct bonding to differentiate from foundry competitors. Amkor Technology anchors outsourced assembly and test for fabless designers lacking in-house TSV capability.
Through Silicon via packaging creates vertical electrical interconnects by etching high-aspect-ratio holes through silicon wafers, filling them with copper, and achieving pitch densities below 40 micrometers to enable multi-die stacking with signal paths shorter than wirebond alternatives. Memory Devices command the largest revenue pool among product types because HBM stack penetration in AI accelerators requires TSV as a foundational enabler. Wafer Level Packaging is the fastest-growing technology segment as chip-on-wafer integration schemes displace older die-on-wafer flows for yield and throughput gains.
China's MIIT enforces GB standards on semiconductor manufacturing emissions while the EU's REACH and RoHS frameworks restrict hazardous substances in TSV metallization chemistries, elevating compliance costs for equipment and material suppliers. The US EPA and OSHA jointly govern fab chemical handling and worker exposure limits that shape domestic packaging capacity decisions. Stakeholders must monitor how export control alignments across Washington, Brussels, and Beijing reroute equipment procurement channels and alter joint venture feasibility for new TSV fabs.
Market Dynamics
TSV pitch density compression below 40 micrometers is forcing capital reallocation toward hybrid bonding equipment as memory stack complexity outpaces conventional copper-filling throughput. Foundries now face a binary choice between captive capacity expansion or outsourced assembly partnerships.
Growth Catalysts
- HBM penetration in AI accelerators:Datacenter clusters require TSV-enabled memory stacks to feed GPU bandwidth demands. This end-use pull is accelerating wafer-level packaging adoption.
- EU F-Gas Regulation:Tighter process-gas compliance for etching and deposition steps is filtering out marginal equipment suppliers. Tier-one vendors capture displaced demand.
- Taiwan's Hsinchu corridor:Concentrated foundry and OSAT infrastructure creates agglomeration economies. Packaging engineering talent pools deepen through co-location effects.
Market Restraints
- Copper fill chemistry volatility:Electroplating bath chemistry costs fluctuate with commodity metal markets. Margin compression hits mid-tier packaging houses hardest.
- Equipment supplier concentration:Deep reactive-ion etching tools source predominantly from Japanese and German precision engineering clusters. Single-source dependencies create procurement risk.
- Hybrid bonding yield limits:Sub-10 micrometer pitch alignment tolerances exceed current optical inspection capabilities. Defect rates constrain stack heights in production environments.
Strategic Opportunities
- India's semiconductor PLI scheme:Subsidized fab and ATMP investments attract TSV packaging lines seeking tariff-advantaged export platforms. The policy window favors early entrants.
- Automotive sensor fusion modules:LiDAR and camera stack integration demands vertical interconnect density. This emerging application opens non-memory revenue pools.
- Chiplet standardization:UCIe and BoW protocol convergence enables interoperable TSV-based die stacks. Technology convergence reduces customer lock-in and expands addressable market.
Industry Challenges
- Advanced packaging engineering scarcity:Hybrid bonding process engineering expertise concentrates in Hsinchu and Yongin corridors. Apprenticeship pipelines require multi-year gestation.
- Cleanroom capex intensity:Class 1 particulate control for sub-40 micrometer processing demands facility investments exceeding legacy wirebond lines by an order of magnitude.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Through Silicon via (TSV) Packaging Market |
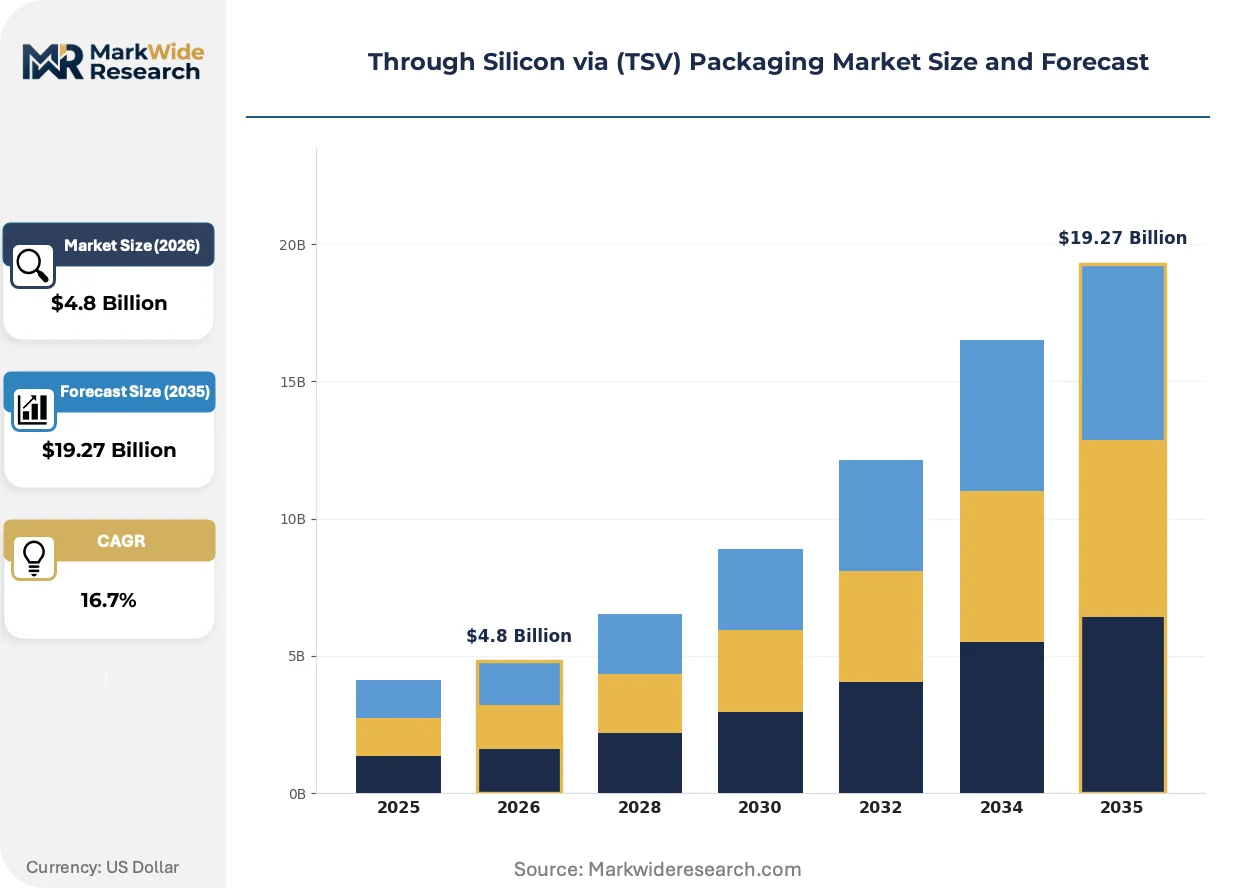
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $19.27 Billion |
| CAGR (2026 – 2036) | 16.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: 3D ICs, Memory Devices, FPGAs, ASICs Technology: Wafer Level Packaging, Chip-on-Wafer, Die-on-Wafer, Advanced Packaging End User: Consumer Electronics, Telecommunications, Automotive, Healthcare Application: High-Performance Computing, Mobile Devices, Networking Equipment, Datacenters |
| Companies Covered | Taiwan Semiconductor Manufacturing Company (TSMC), Intel Corporation, Samsung Electronics, Amkor Technology, STMicroelectronics, ASE Group, Qualcomm Inc., Micron Technology, NXP Semiconductors, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Through Silicon via (TSV) Packaging Market Evolving Landscape
Process integration complexity is compressing development cycles as memory and logic roadmaps synchronize. Equipment vendors now embed machine learning into deposition control loops.
Hybrid bonding is miniaturizing interconnect pitch below 10 micrometers by eliminating copper pillar geometries entirely. AI accelerator designers are adopting this technology within single product generations. The structural consequence is collapsing interposer area requirements and enabling denser multi-die integration than TSV-plus-microbump alternatives permit.
China's MIIT enforces GB emission standards on semiconductor manufacturing that elevate wet chemistry treatment costs. Domestic foundries must retrofit abatement systems or face production quota restrictions. Memory packaging lines in Shanghai and Beijing clusters bear the heaviest compliance burden, accelerating migration toward dry process alternatives.
Datacenter procurement teams now specify TSV stack configurations directly in GPU accelerator tenders, bypassing traditional memory module vendor relationships. This disintermediation concentrates specification power with hyperscale compute architects. The pattern is most pronounced in North American cloud infrastructure deployments where vertical integration into silicon design enables custom stack heights.
Through Silicon via (TSV) Packaging Market Segmentation
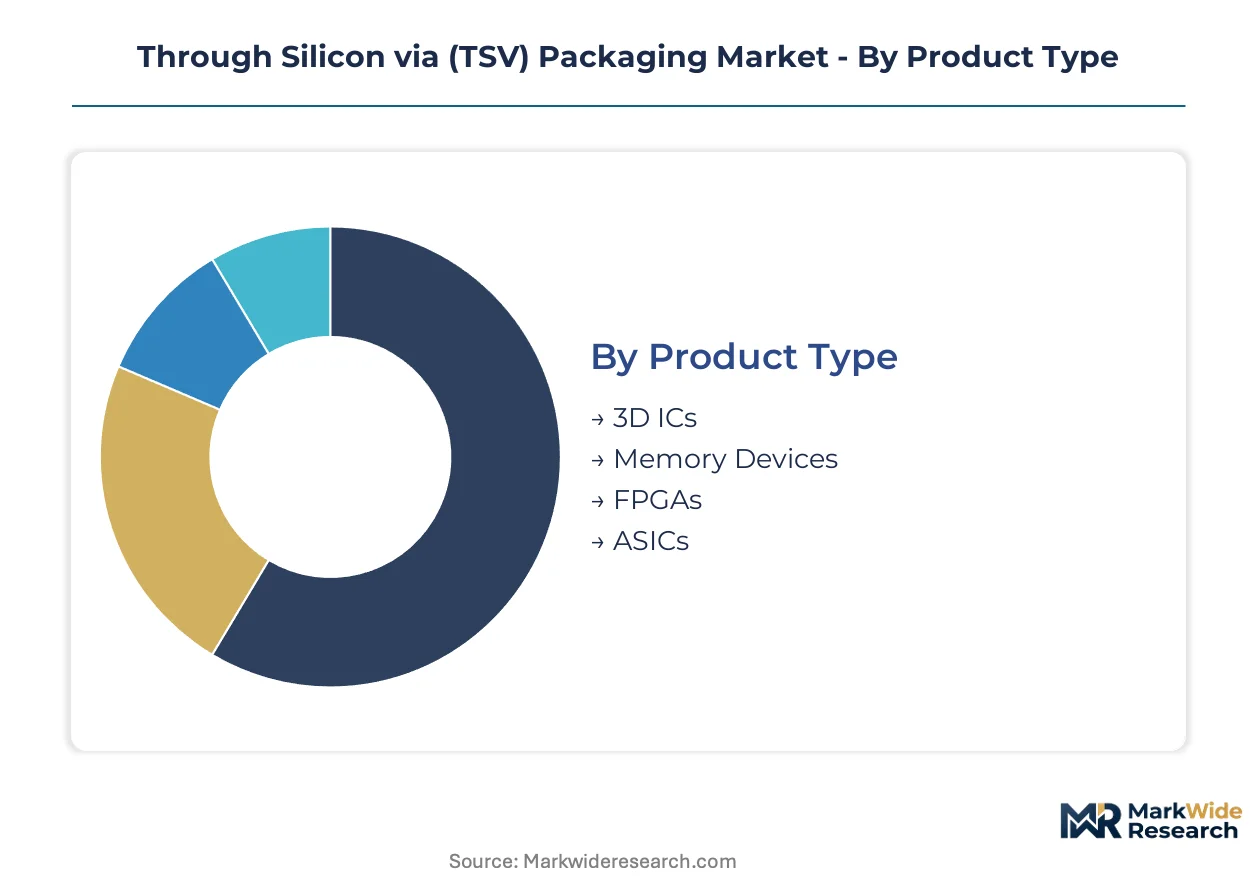
TSV packaging configurations fragment sharply across memory versus logic applications, with each segment demanding distinct pitch densities, stack heights, and thermal management protocols. Understanding where margin pools concentrate within each dimension enables targeted equipment and materials positioning.
Product Type:
Memory Devices capture the deepest margin pools due to HBM stack complexity and datacenter procurement concentration, while ASICs and FPGAs compete on customization premiums versus volume scale.
- Memory Devices:High-bandwidth memory stacks require copper-filled TSV arrays at sub-40 micrometer pitch to interconnect 8-12 DRAM layers vertically. Datacenter GPU accelerator tenders in Taiwan and the United States now specify TSV configurations directly, bypassing traditional module vendors and concentrating specification power with hyperscale architects.
- 3D ICs:Logic-on-logic stacking employs TSV for cache and accelerator integration, with hybrid bonding displacing microbump alternatives below 10 micrometer pitch. Yield constraints at sub-10 micrometer alignment tolerances currently limit stack heights in production environments, constraining volume ramp.
- ASICs:Custom silicon for AI inference and cryptocurrency mining demands moderate TSV density with aggressive cost targets. Fabless designers in China's Shanghai cluster source outsourced assembly through OSAT partnerships to avoid captive fab investments.
- FPGAs:Programmable logic devices utilize TSV for inter-die routing flexibility, serving aerospace and defense applications requiring field reconfigurability. Volume remains constrained by long qualification cycles and dual-source mandates.
The dominant share belongs to Memory Devices, while 3D ICs is closing the gap fastest.
Technology:
Wafer-level integration schemes command pricing premiums over die-level alternatives by eliminating pick-and-place handling and improving placement accuracy through chuck-based alignment.
- Wafer Level Packaging:Chip-on-wafer flows bond known-good dies to active wafers before dicing, achieving throughput advantages and yield recovery through parallel processing. Taiwan's Hsinchu Science Park corridor hosts the densest concentration of WLP capacity, with TSMC leveraging captive CoWoS infrastructure for HBM interposers.
- Advanced Packaging:Hybrid bonding eliminates copper pillars entirely, compressing interconnect pitch below 10 micrometers and collapsing interposer area requirements. AI accelerator designers in South Korea and the United States are adopting this technology within single product generations, forcing equipment vendors to embed machine learning into deposition control loops.
- Chip-on-Wafer:Individual die placement onto carrier wafers enables mixed-node integration but sacrifices throughput versus full-wafer approaches. Mid-tier packaging houses in Malaysia and Vietnam utilize this flow for cost-sensitive consumer applications.
- Die-on-Wafer:Legacy sequential placement remains prevalent in automotive sensor modules where traceability and rework requirements outweigh density demands. LiDAR and camera stack integration in Germany and Japan continues specifying this mature flow.
Wafer Level Packaging holds the revenue concentration, though Advanced Packaging is expanding most quickly.
End User:
Telecommunications infrastructure generates the most stable demand profile, while Automotive applications are climbing fastest on sensor fusion module requirements.
- Telecommunications:Baseband and RF front-end modules employ TSV for 5G millimeter-wave antenna-in-package integration. Network equipment vendors in Finland and Sweden specify TSV-based phased arrays for beamforming applications.
- Automotive:LiDAR and camera stack integration demands vertical interconnect density for autonomous driving compute platforms. Tier-one suppliers in Germany and Japan are qualifying TSV packaging for ASIL-D safety integrity levels.
- Consumer Electronics:Smartphone application processors utilize TSV for image sensor and memory stacking, though form factor constraints limit stack heights versus datacenter counterparts.
- Healthcare:Medical imaging and implantable devices require hermetic TSV sealing and biocompatible metallization, extending qualification timelines and supporting premium pricing.
Telecommunications maintains the largest installed base, while Automotive is gaining share fastest.
Application:
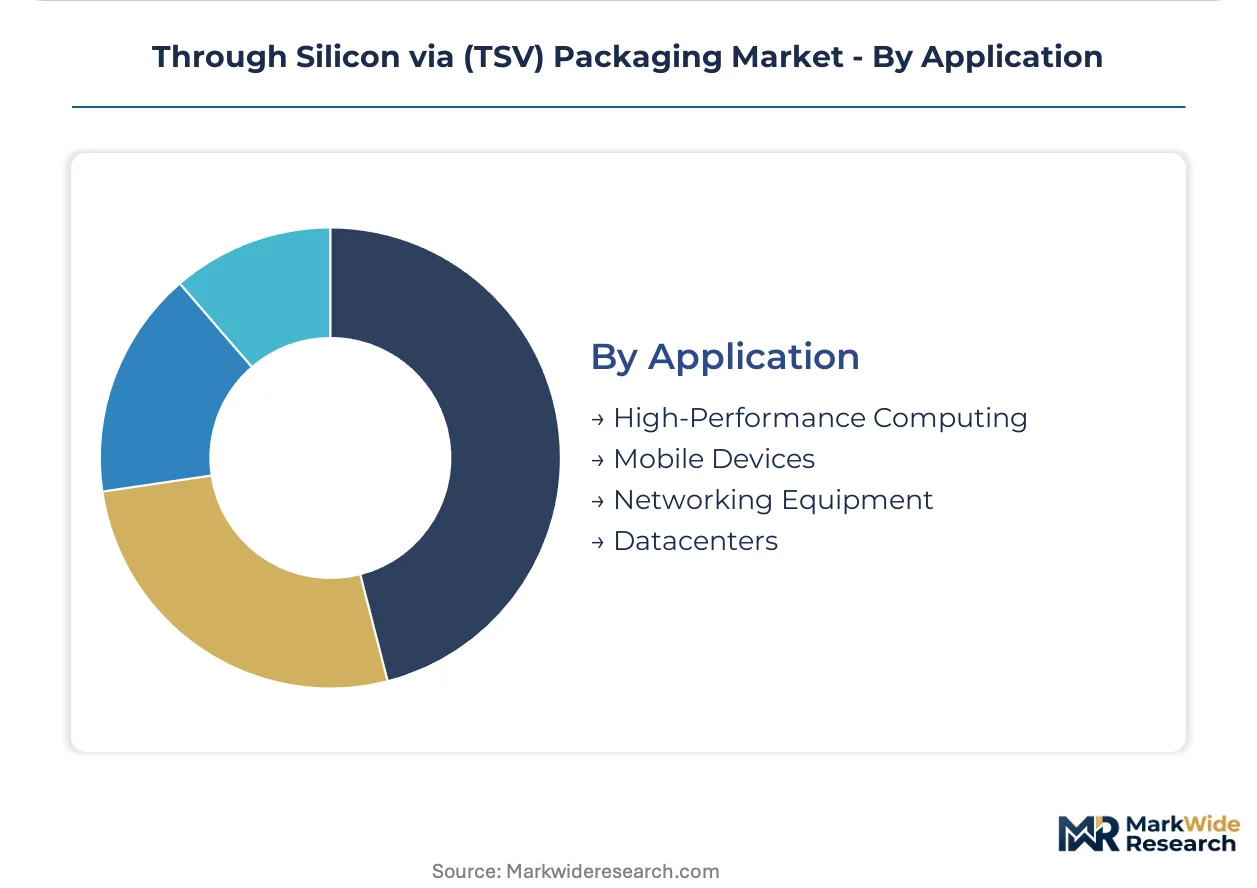
Datacenter deployments absorb the highest-value TSV configurations, with Mobile Devices competing on unit volume against severe cost compression.
- Datacenters:GPU accelerator cards and AI training clusters require TSV-enabled HBM stacks to feed memory bandwidth demands exceeding 3 terabytes per second. Hyperscale procurement teams in the United States specify custom stack heights through direct silicon design integration.
- High-Performance Computing:Supercomputer nodes utilize TSV for processor-memory disaggregation and optical I/O integration. National laboratory procurements in the United States and Japan prioritize domestic packaging capacity for supply security.
- Mobile Devices:Smartphone and tablet form factors drive TSV adoption for camera module and application processor stacking, with Chinese OEMs sourcing aggressively from Taiwan-based OSATs.
- Networking Equipment:Switch and router ASICs employ moderate TSV density for packet buffer integration, with Cisco and Juniper specifications driving foundry process development.
Datacenters command the dominant revenue position, while High-Performance Computing is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Taiwan's MIIT enforces emission standards that elevate wet chemistry treatment costs for packaging operations. The EPA and OSHA jointly govern chemical handling in domestic fabs. Taiwan, China, South Korea, the United States, and Japan concentrate the majority of TSV capacity.
Taiwan
HBM stack demand from AI accelerator designers drives foundry utilization rates above 90 percent. Taiwan's EPA enforces hazardous substance restrictions under REACH-aligned frameworks. Hsinchu Science Park anchors captive CoWoS capacity, with TSMC expanding interposer lines to meet hyperscale GPU procurement.
China
Domestic memory packaging lines absorb displaced demand from import-dependent flows. MIIT enforces GB emission standards that retrofit abatement systems or trigger production quota restrictions. Shanghai and Beijing clusters bear the heaviest compliance burden, accelerating migration toward dry process alternatives.
South Korea
AI accelerator designers adopt hybrid bonding within single product generations. MFDS governs worker exposure limits in fab environments. Yongin corridors concentrate hybrid bonding process engineering expertise, with apprenticeship pipelines requiring multi-year gestation periods.
United States
Hyperscale procurement teams specify custom TSV stack heights through direct silicon design integration. The EPA and OSHA jointly govern chemical handling and worker exposure limits. Arizona and Oregon fabs anchor Intel's Foveros Direct bonding development, differentiating from foundry competitors.
Japan
Deep reactive-ion etching tools source predominantly from precision engineering clusters. METI coordinates domestic equipment vendor consolidation. Tokyo and Osaka regions concentrate etching and deposition equipment manufacturing, filtering marginal suppliers under tightened process-gas compliance.
Through Silicon via (TSV) Packaging Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with captive foundry capacity separating from outsourced assembly providers. Taiwan Semiconductor Manufacturing Company dominates high-bandwidth memory interposers through captive CoWoS infrastructure. Samsung Electronics and Intel Corporation sustain aggressive R&D outlays on hybrid bonding and Foveros Direct respectively. Capacity expansion and strategic partnerships constitute the dominant competitive moves, with foundries facing binary choices between captive expansion or OSAT alliances.
Within the integrated foundry tier, Taiwan Semiconductor Manufacturing Company exemplifies captive infrastructure dominance, while Intel Corporation occupies a position emphasizing in-house bonding development. Amkor Technology anchors outsourced assembly and test for fabless designers lacking captive TSV capability, representing the specialist tier that absorbs demand overflow from integrated leaders.
| Leading Market Players |
|---|
| Taiwan Semiconductor Manufacturing Company (TSMC) |
| Intel Corporation |
| Samsung Electronics |
| Amkor Technology |
| STMicroelectronics |
| ASE Group |
| Qualcomm Inc. |
| Micron Technology |
| NXP Semiconductors |
| Others |
Value Network & Pricing Analysis
Foundry utilization rates above 90 percent in Taiwan's Hsinchu corridor create scale economies that compress unit costs for TSV-enabled memory stacks while simultaneously elevating price floors for mid-tier packaging houses lacking captive capacity. This concentration dynamic concentrates pricing power with integrated leaders who internalize interposer production, forcing outsourced assembly providers to compete on yield recovery services rather than base wafer processing.
Pricing Analysis
Taiwan-based CoWoS lines command 40-60 percent premiums over Malaysian and Vietnamese packaging houses for equivalent HBM stack configurations. Pricing stratifies across premium, standard, and economy tiers based on alignment tolerance grades and thermal cycling certification levels. Cost compression in consumer-facing tiers is intensifying because Chinese OEMs are consolidating procurement volumes through direct foundry negotiations. Datacenter GPU accelerator designers exhibit the lowest price sensitivity, while smartphone application processor integrators face severe margin constraints.
Supply Chain Analysis
Deep reactive-ion etching tool lead times extending beyond 12 months are forcing foundries to pre-position equipment orders before process node qualifications complete. Manufacturing concentration rests on Taiwan, South Korea, and Japan for precision etching and deposition equipment, with copper fill chemistry and photoresist materials drawing from German and US specialty chemical clusters. Single-source vulnerability pervades hybrid bonding inspection systems. Distribution runs through captive foundry channels for tier-one memory integrators and OSAT partnerships for fabless designers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Process engineering services and yield optimization consulting are expanding faster than bare wafer processing revenue as foundries monetize technical expertise through recurring service contracts rather than transactional unit pricing.
For Market Incumbents: Secure hybrid bonding process engineering talent through multi-year apprenticeship commitments in Hsinchu and Yongin corridors before competitor poaching intensifies. Expand captive CoWoS capacity to capture datacenter GPU procurement volumes that are bypassing traditional memory module vendors. Defend against margin erosion by internalizing copper fill chemistry blending rather than sourcing from commodity electroplating suppliers. For New Entrants and Emerging Players: Anchor in India's semiconductor PLI scheme subsidy window to establish tariff-advantaged export platforms before policy phase-out. Target automotive sensor fusion modules for LiDAR and camera stack integration, where ASIL-D qualification requirements filter out incumbent consumer-electronics-focused competitors. Lead with dry process etching alternatives that sidestep China's MIIT emission compliance burdens affecting Shanghai and Beijing packaging clusters. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors hybrid bonding equipment vendors with machine learning-embedded deposition control capabilities over legacy copper-filling specialists. Long-term viability hinges on sub-10 micrometer pitch alignment roadmaps that enable next-generation AI accelerator stack heights. The acquisition target archetype combines precision etching tool manufacturing with captive process development partnerships. Monitor EU F-Gas Regulation enforcement intensity as an inflection indicator for equipment vendor consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Bonding Capacity Expansion | Sub-10 micrometer pitch adoption by AI accelerator designers in South Korea and the United States collapses interposer area requirements. |
| Process Engineering Apprenticeship Pipeline | Multi-year talent development in Hsinchu and Yongin corridors addresses scarcity constraining production ramp rates. |
| Dry Process Etching Transition | Migration from wet chemistry reduces MIIT compliance burdens in Shanghai and Beijing packaging clusters. |
| Automotive ASIL-D Qualification | Tier-one suppliers in Germany and Japan specify TSV packaging for autonomous driving compute platforms. |
| India PLI Scheme Entry | Subsidized fab and ATMP investments attract TSV packaging lines seeking tariff-advantaged export platforms. |
Research Methodology
Desk research of equipment vendor technical specifications, foundry capacity announcements, and regulatory filing databases preceded structured interviews with packaging process engineers, OSAT procurement directors, and datacenter infrastructure architects. Secondary validation drew from SEC filings of capital equipment suppliers, EPA and OSHA chemical handling guidance documents, and EU REACH substance restriction updates. Bottom-up segment sizing triangulated against top-down foundry utilization and capital expenditure estimates.
Variance decomposition across product type, technology node, and end-use application dimensions shaped the analytical framework over the projection horizon. Modeled segmentation captured memory versus logic applications, wafer-level versus die-level integration flows, and datacenter versus automotive demand profiles. CAGRs were derived from equipment shipment forecasts and foundry capacity expansion announcements, with yield learning curves and process gas compliance cost trajectories serving as industry-specific forecast inputs.
Material uncertainties — export control alignment shifts, hybrid bonding yield breakthroughs, and emission standard enforcement intensity variations — sit outside the modeled envelope. Forecasts reflect assumptions regarding foundry captive capacity expansion timelines and OSAT partnership stability. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Packaging
Through-Silicon via (TSV) IC Packaging Market
Semiconductor Packaging
Global Interposer and Fan-Out WLP Market
Semiconductor Packaging
Wafer Carrier Boxes Market
Semiconductor Packaging
Semiconductor Solder Flux Market
Semiconductor Packaging
Fan Out Packaging Market
Semiconductor Packaging
Global High-End Semiconductor Packaging Market
Semiconductor Packaging
Epoxy Potting Market
Semiconductor Packaging
ESD Stackable Boxes Market
Semiconductor Packaging
System-On-Package Market
Semiconductor Packaging
Global MEMS Packaging Market
Semiconductor Packaging
Semiconductor Packaging Market
Semiconductor Packaging
Semiconductor and IC Packaging Materials Market
Semiconductor Packaging
Bonding Wire Packaging Market
Semiconductor Packaging
Asia-Pacific Quad-Flat-No-Lead Packaging Market
Semiconductor Packaging
NOR-Based Multi-Chip Packages Market
Semiconductor Packaging
2.5D and 3D Semiconductor Packaging Market