
 Southeast Asia Submersible Pumps Market | 2026-2036
Southeast Asia Submersible Pumps Market Size, Share, and Industry Trends Forecast 2026-2036
Southeast Asia Submersible Pumps Market Analytics
The gap between premium and commodity tiers is broadening in the Southeast Asia Submersible Pumps Market as end-users in mining and municipalities demand higher efficiency standards while price-sensitive agricultural buyers prioritize basic dewatering functionality. Grundfos leverages its vertical integration in electric submersible motor technology to command premium positioning across Indonesian municipal contracts. Xylem Inc. anchors its regional presence through specialized wastewater management solutions serving Bangkok's expanding metro drainage networks. Ebara Corporation differentiates via compact borewell pump designs optimized for Southeast Asia's shallow aquifer conditions.
Submersible pumps are hermetically sealed centrifugal units designed to operate fully immersed in fluid, with motor housings typically rated for continuous duty at depths exceeding 300 meters and discharge heads ranging from 10 to 500 meters depending on impeller configuration. Their primary industrial purpose centers on reliable fluid transfer in confined or flooded environments where surface-mounted equipment proves impractical. Borewell pumps occupy the largest volume share across the region's agricultural heartlands, while solar powered technology represents the fastest-expanding segment as off-grid irrigation projects multiply in Myanmar and Cambodia. Sewage pumps concentrate margin pools in urban infrastructure contracts governed by stricter effluent standards, with electric submersible systems dominating due to lower maintenance requirements in submerged installations.
Indonesia's Ministry of Public Works and Housing enforces national efficiency standards for municipal pumping equipment, compelling suppliers to certify products through the country's national standards body. Thailand's Board of Investment ties tax incentives to equipment meeting specified energy performance thresholds, directly shaping procurement criteria for industrial end users. Vietnam's Ministry of Construction regulates drainage system specifications in flood-prone provinces, mandating submersible pump redundancy in critical urban zones. Stakeholders must monitor how divergent national certification requirements affect cross-border product standardization and service network economics across the ASEAN trade bloc.
Market Dynamics
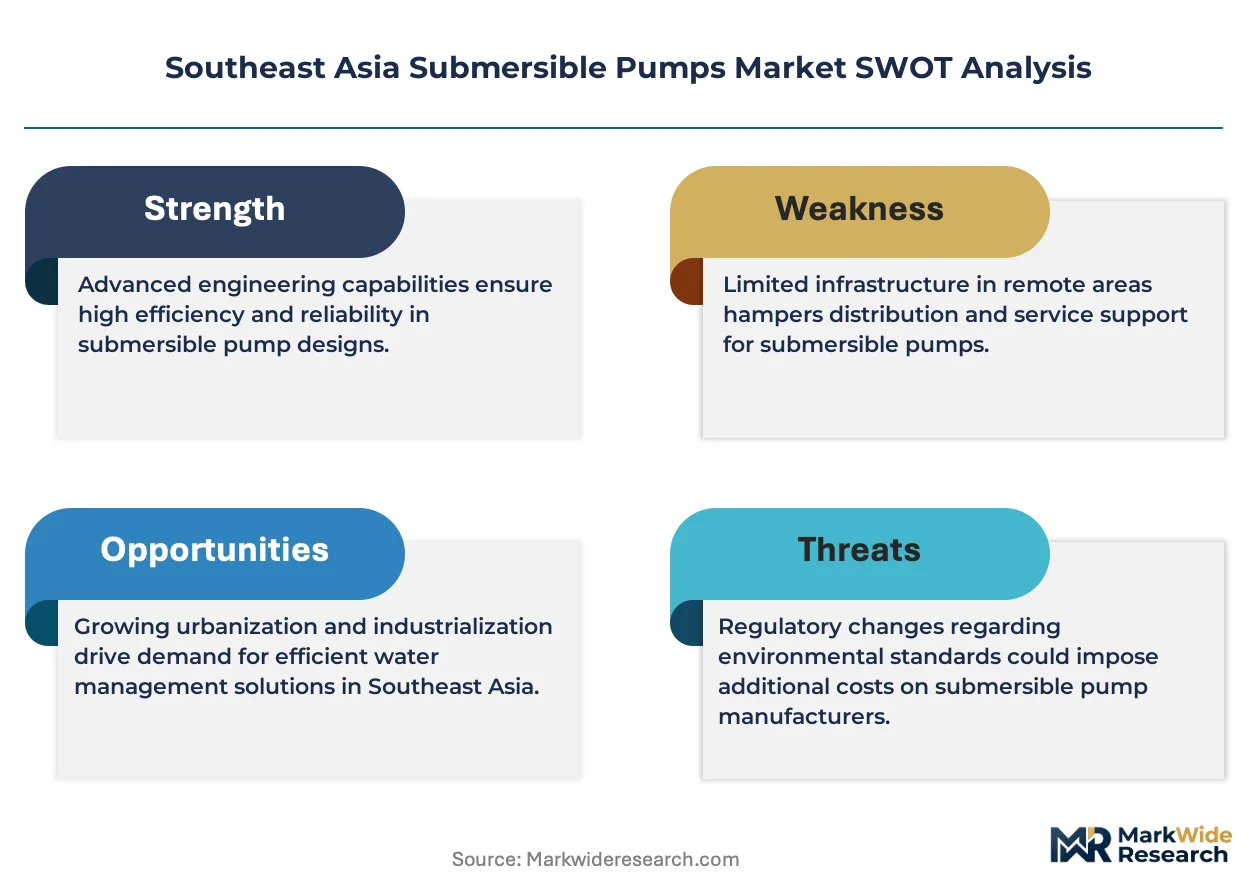
Indonesia's municipal waterworks are driving a structural shift toward certified high-efficiency electric submersible systems, with procurement criteria now mandating national standards body certification that filters supplier participation across the Java-Bali corridor.
Growth Catalysts
- Thailand's Board of Investment incentives:Tax benefits tied to energy performance thresholds accelerate electric pump replacements across municipal waterworks and industrial zones.
- Solar-powered borewell technology:Off-grid irrigation projects in Myanmar and Cambodia expand addressable demand beyond grid-connected agricultural regions.
- Vietnam's flood-resilient drainage mandates:Ministry of Construction regulations require submersible pump redundancy in critical urban zones, institutionalizing backup system procurement.
Market Restraints
- Copper and rare-earth magnet cost volatility:Electric submersible motor manufacturing faces input price instability that compresses margin pools for mid-tier suppliers.
- Chinese motor component concentration:Dependence on integrated stator-rotor assemblies from single-source suppliers creates supply vulnerability during trade friction periods.
- Shallow aquifer technical constraints:Compact borewell pump designs face head-pressure limitations that restrict deployment depth in deep-well mining applications.
Strategic Opportunities
- Cambodia's underpenetrated agricultural electrification:Rural irrigation infrastructure gaps create first-mover positioning for solar-battery pump system integrators.
- Smart monitoring convergence:IoT-enabled predictive maintenance modules paired with submersible units open recurring revenue streams in municipal contracts.
- Myanmar's distributed water access programs:Government rural development schemes fund decentralized borewell installations outside centralized grid zones.
Industry Challenges
- Cross-border certification fragmentation:Divergent national standards across ASEAN complicate product standardization and inflate compliance costs for multi-country service networks.
- Submersible motor rewind technician scarcity:Specialized repair skills for hermetically sealed units concentrate in Thailand and Indonesia, creating service coverage gaps in emerging markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Southeast Asia Submersible Pumps Market |
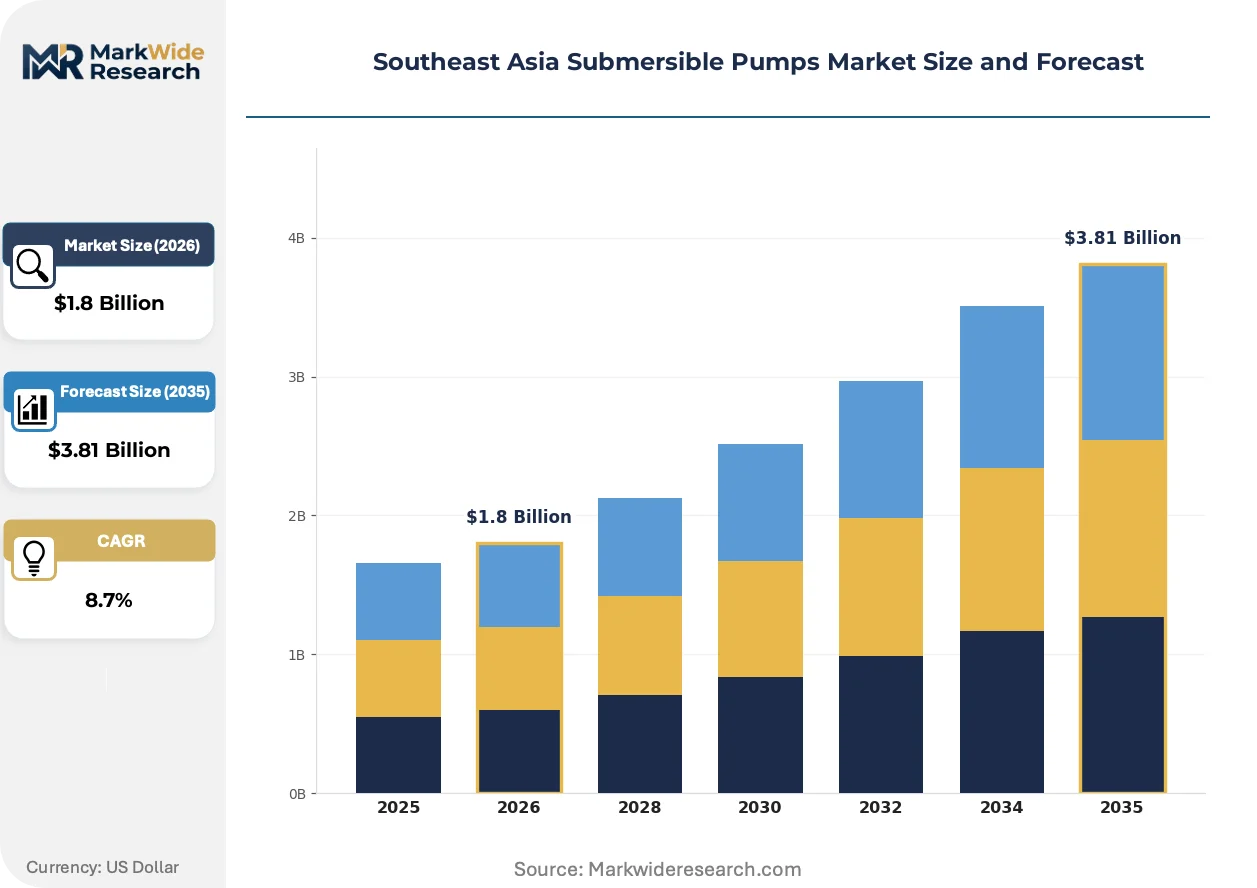
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Trash Pumps, Dewatering Pumps, Borewell Pumps, Sewage Pumps Application: Agricultural Irrigation, Construction, Drainage, Wastewater Management End User: Agriculture, Mining, Municipalities, Industrial Technology: Electric Submersible, Hydraulic Drive, Pneumatic, Solar Powered |
| Companies Covered | Grundfos, ITT Inc., Xylem Inc., Atlas Copco AB, Ebara Corporation, Flowserve Corporation, The Weir Group PLC, Kubota Corporation, KSB SE & Co. KGaA, Others |
| Regions Covered | Southeast Asia: Indonesia, Thailand, Vietnam, Philippines, Malaysia, Singapore, Myanmar, Cambodia, Rest of Southeast Asia |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Southeast Asia Submersible Pumps Market Evolving Landscape
Technology convergence and procurement rationalization are restructuring competitive positioning across Southeast Asia's submersible pump value chain, with efficiency mandates and digital integration defining supplier differentiation.
Permanent magnet synchronous motor technology is electrifying submersible pump efficiency benchmarks across Thailand's municipal waterworks sector. Bangkok's metropolitan drainage authorities specify PM motor systems for new procurements, displacing conventional induction motor architectures in high-duty-cycle installations. This electrifying shift compresses operating cost structures for 24-hour continuous service applications while elevating upfront capital requirements.
Indonesia's national efficiency standards enforcement through the Ministry of Public Works and Housing is reshaping supplier qualification protocols. Certification mandates now govern municipal pumping equipment selection, filtering participation to manufacturers with established testing laboratory relationships. Indonesian municipal contractors are consolidating supplier relationships around pre-certified product lines to accelerate project approval timelines.
Integrated pump-monitoring service bundles are displacing transactional equipment sales in Vietnam's industrial zone contracts. Manufacturing facility operators in Binh Duong and Dong Nai provinces now specify performance-guaranteed maintenance agreements alongside capital purchases. This procurement model shift concentrates margin capture with vertically integrated suppliers capable of field service deployment across southern Vietnam's industrial corridor.
Southeast Asia Submersible Pumps Market Segmentation
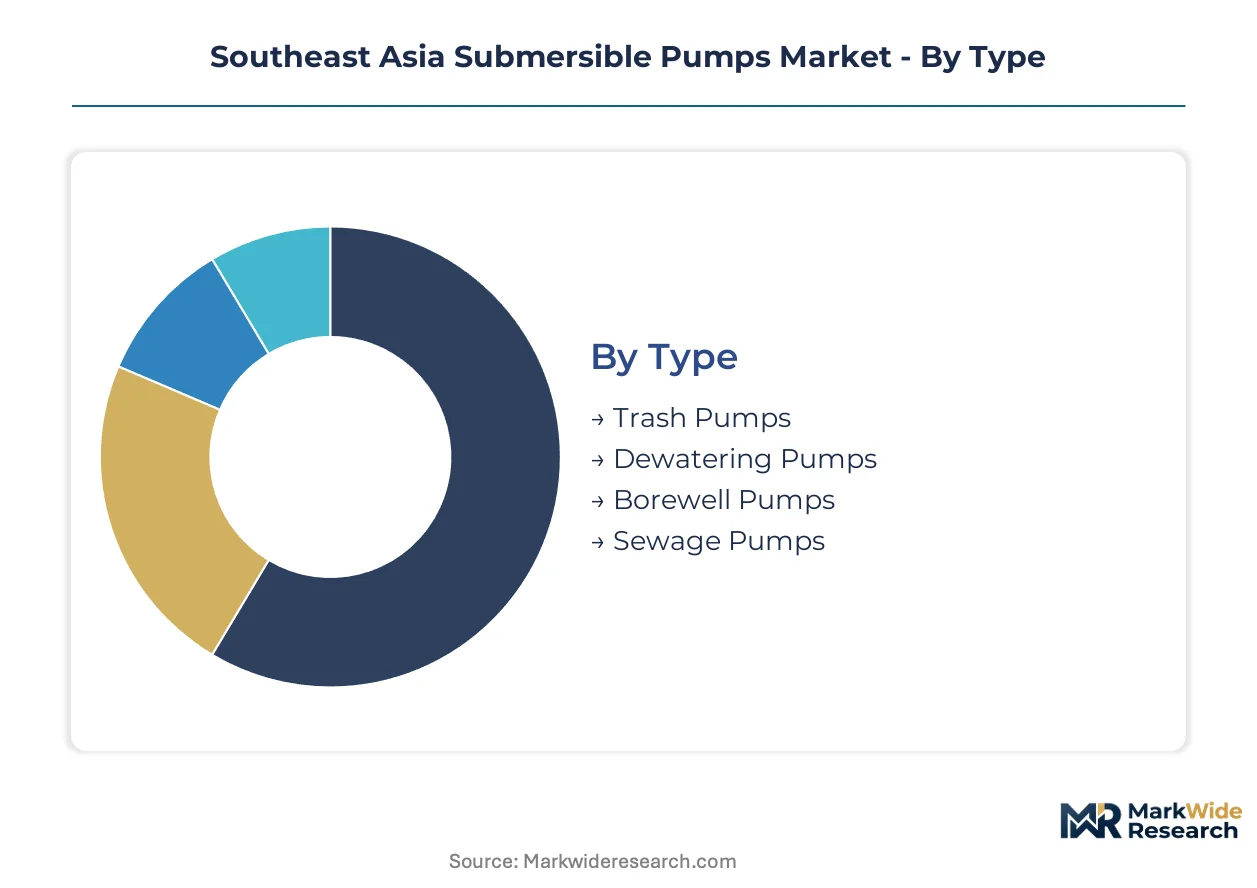
Southeast Asia's submersible pump procurement splits along technical specifications, duty cycles, and power source availability. Segment boundaries matter because Indonesian municipal contractors now disqualify uncertified equipment while Cambodian farmers prioritize solar compatibility over head-pressure ratings.
Type:
Impeller geometry and solids-handling capability define performance ceilings across groundwater extraction and fluid transfer applications.
- Borewell Pumps:Multi-stage centrifugal configurations with submersible motor housings rated for 300-meter depths dominate Vietnam's Mekong Delta irrigation networks. Indonesian agricultural contractors specify stainless-steel impeller stacks to combat corrosive shallow aquifer chemistry in Java's volcanic soil zones.
- Sewage Pumps:Vortex and grinder impeller designs handle 65-millimeter solids passage for Bangkok's combined sewer overflow remediation. Thailand's Ministry of Public Health mandates redundant pump configurations in hospital wastewater systems, institutionalizing dual-unit procurement.
- Dewatering Pumps:Portable electric submersible units with 10-50 meter discharge heads serve Indonesia's nickel mining pit dewatering operations.
- Trash Pumps:Open-vortex impellers process debris-laden floodwater in Philippines municipal emergency response inventories.
Mature deployment sits with borewell pumps across established agricultural zones. Newer deployment is concentrated in sewage pump specifications as ASEAN urban centers tighten effluent discharge enforcement.
Application:
Duty cycle intensity and fluid characteristics determine motor sizing, material selection, and maintenance interval economics.
- Wastewater Management:Continuous-duty electric submersible systems with cast-iron volutes and epoxy-coated windings process municipal sewage in Jakarta's Pluit and Tanjung Priok treatment zones. Indonesia's national standards body certifies equipment for 87,600 annual operating hours, filtering supplier participation to manufacturers with in-house testing facilities.
- Agricultural Irrigation:Intermittent-duty borewell pumps with floating intake assemblies extract groundwater for Vietnam's rice intensification programs. Solar-powered variants are expanding most quickly in Myanmar's Magway and Mandalay regions where grid extension lags behind irrigation demand.
- Drainage:High-capacity axial-flow submersibles manage monsoon runoff in Ho Chi Minh City's District 2 and Thu Duc flood control infrastructure.
- Construction:Portable dewatering units with automatic level controls serve foundation pit excavation in Bangkok's Rama IX commercial corridor.
Margin concentration tracks toward wastewater management where performance-guaranteed service contracts displace transactional sales. Volume leadership remains with agricultural irrigation across the region's rice-producing lowlands.
End User:
Procurement sophistication and total cost of ownership horizons diverge sharply between public infrastructure authorities and private operators.
- Municipalities:Indonesian city waterworks in Surabaya and Bandung specify permanent magnet synchronous motor efficiency tiers for 24-hour distribution pumping. Certification compliance costs elevate supplier qualification barriers, consolidating procurement around pre-tested product lines.
- Agriculture:Vietnamese cooperatives in An Giang and Dong Thap provinces prioritize first-cost minimization for seasonal flood recession irrigation. Diesel-to-solar conversion programs in Cambodia's Battambang province are opening addressable demand beyond grid-connected zones.
- Mining:Indonesian nickel and tin operations in Sulawesi specify abrasion-resistant hardened impellers for acidic pit dewatering.
- Industrial:Thai manufacturing zones in Rayong and Chonburi procure integrated pump-monitoring bundles with predictive maintenance modules.
Specification authority concentrates with municipalities enforcing national efficiency mandates. Price sensitivity peaks in agricultural procurement where equipment financing constraints dominate capital planning.
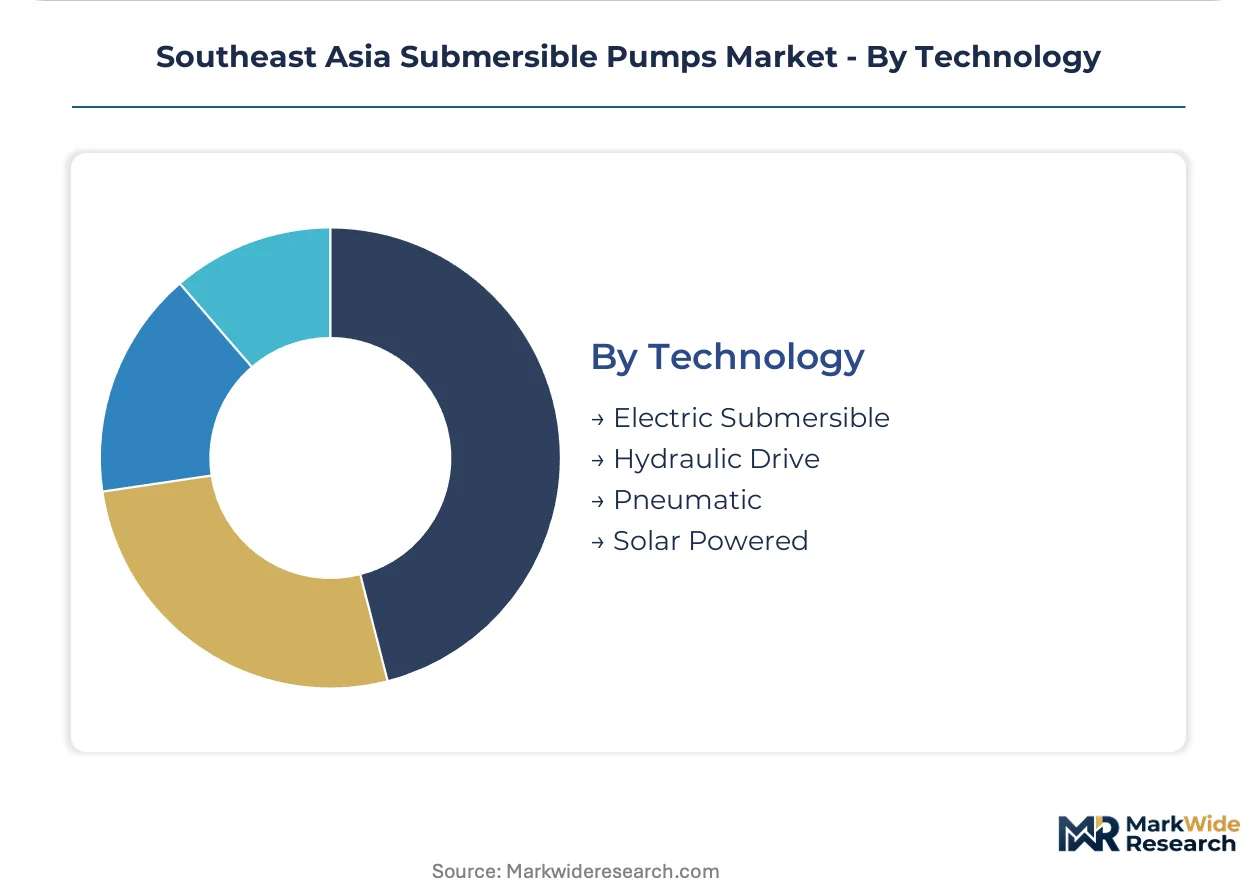
Technology:
Power source availability and operating cost structures determine technology selection across grid-connected and off-grid deployment scenarios.
- Electric Submersible:Hermetically sealed induction and permanent magnet motor configurations deliver 10-500 meter discharge heads for Thailand's municipal waterworks. Bangkok Metropolitan Administration procurement guidelines now specify IE4 efficiency minimums for new installations, accelerating motor architecture displacement.
- Solar Powered:DC brushless motor systems with maximum power point tracking controllers serve Myanmar's decentralized rural water access programs. Battery-buffered configurations enable dawn and dusk irrigation windows independent of immediate solar irradiance.
- Hydraulic Drive:Explosion-proof deployments in Indonesian oil palm processing facilities where electrical ignition risks constrain motor selection.
- Pneumatic:Compressed-air powered units for temporary mine dewatering in confined spaces with electrical hazard classification.
Technology transition is accelerating toward electric submersible systems where grid reliability supports continuous duty. Solar powered configurations are gaining share fastest in Cambodia and Myanmar's agricultural electrification gaps.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Jakarta's Java-Bali corridor concentrates the region's most intensive submersible pump procurement activity, with municipal waterworks and industrial zone expansions driving sustained equipment demand across Indonesia's most developed infrastructure backbone.
Indonesia
Java's urban drainage upgrades and nickel mining dewatering operations in Sulawesi propel electric submersible system orders. The Ministry of Public Works and Housing enforces national efficiency standards that filter supplier participation through mandatory certification. Municipal contractors in Surabaya and Bandung consolidate procurement around pre-certified permanent magnet motor product lines.
Thailand
Bangkok's metropolitan drainage networks and Rayong-Chonburi industrial zones accelerate pump replacements with energy-efficient specifications. The Board of Investment ties tax incentives to equipment meeting specified energy performance thresholds. Municipal waterworks procurement guidelines now specify IE4 efficiency minimums for new installations.
Vietnam
Mekong Delta irrigation intensification and Ho Chi Minh City flood control infrastructure expand borewell and drainage pump deployment. The Ministry of Construction regulates drainage system specifications in flood-prone provinces, mandating submersible pump redundancy. Manufacturing operators in Binh Duong and Dong Nai provinces specify integrated pump-monitoring service bundles.
Myanmar
Magway and Mandalay agricultural regions drive solar-powered borewell adoption where grid extension lags behind irrigation demand. Government rural development schemes fund decentralized borewell installations outside centralized grid zones. Off-grid irrigation projects multiply across the country's central dry zone.
Cambodia
Battambang province diesel-to-solar conversion programs open addressable demand beyond grid-connected agricultural regions. Rural irrigation infrastructure gaps create positioning opportunities for solar-battery pump system integrators. Battery-buffered configurations enable dawn and dusk irrigation windows independent of immediate solar irradiance.
Southeast Asia Submersible Pumps Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification compliance and service integration capabilities, with municipal contract qualification barriers consolidating procurement relationships around pre-tested product lines. The supplier base stratifies between vertically integrated motor manufacturers and assembly-focused distributors. Three archetypes dominate: efficiency-certified system integrators, solar-battery hybrid specialists, and mining-focused dewatering suppliers. Competitive moves center on backward integration into permanent magnet motor production and predictive maintenance service bundling.
Within the premium-tier certified equipment segment, Grundfos anchors positioning through established testing laboratory relationships with Indonesian national standards bodies. Xylem Inc. occupies a position exemplifying wastewater management specialization for metropolitan drainage networks. Ebara Corporation represents compact borewell pump design optimization for shallow aquifer conditions.
| Leading Market Players |
|---|
| Grundfos |
| ITT Inc. |
| Xylem Inc. |
| Atlas Copco AB |
| Ebara Corporation |
| Flowserve Corporation |
| The Weir Group PLC |
| Kubota Corporation |
| KSB SE & Co. KGaA |
| Others |
Value Network & Pricing Analysis
Indonesian municipal waterworks procurement consolidation around pre-certified permanent magnet motor systems anchors value-based pricing across the Java-Bali corridor. Certification compliance costs and 24-hour duty-cycle performance guarantees separate premium-tier suppliers from commodity assemblers serving price-sensitive agricultural cooperatives.
Pricing Analysis
Performance-guaranteed uptime contracts anchor value-based pricing for Bangkok Metropolitan Administration drainage procurements and Vietnamese industrial zone service bundles. Price differentiation rests on IE4 efficiency certification tier and integrated predictive maintenance modules. Cost compression in mid-tier electric submersible motors intensifies as Chinese stator-rotor assembly imports face trade friction volatility. Agricultural buyers in Vietnam's Mekong Delta exhibit highest price sensitivity, while Indonesian municipalities prioritize lifecycle cost over first-cost minimization.
Supply Chain Analysis
Indonesia's national standards body certification mandates reshape sourcing toward domestic testing laboratory partnerships and local assembly facilities. Manufacturing concentration centers on China for copper windings and rare-earth permanent magnets, Thailand for precision machining of pump housings, and Japan for hermetic motor sealing technology. Supply chain risk hinges on single-source dependence for integrated motor assemblies during trade restriction periods. Distribution runs through Indonesian municipal contractor networks, Thai industrial zone system integrators, and Vietnamese agricultural equipment dealers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Permanent magnet synchronous motor technology is displacing conventional induction architectures across Southeast Asian municipal waterworks, compressing the window for legacy equipment positioning. This electrification transition rewards suppliers with backward integration into magnet supply and certified testing capabilities.
For Market Incumbents: Cement municipal contract retention by deepening in-house permanent magnet motor production and securing Indonesian national standards body pre-certification for complete product lines. Solar-battery hybrid specialists from Myanmar and Cambodia threaten agricultural segment share through off-grid irrigation positioning. Certification investment in Vietnam's flood-resilient redundancy specifications offers defensive moat construction. For New Entrants and Emerging Players: Solar-battery pump system integration offers the most penetrable wedge into Cambodia's Battambang province diesel conversion programs and Myanmar's Magway decentralized water access schemes. First-mover positioning in battery-buffered dawn-dusk irrigation configurations bypasses established electric submersible distribution networks. Direct engagement with Myanmar's rural development ministry procurement channels accelerates market entry outside Thai and Indonesian incumbent strongholds. For Investors and Strategic Acquirers: The window for entry favors solar-battery hybrid specialists with proven Magway or Battambang deployment track records and testing laboratory relationships with ASEAN national standards bodies. Long-term viability rests on technology transition capture across the agricultural electrification gap. Monitor Indonesian Ministry of Public Works and Housing certification mandate expansion as inflection signal for premium-tier supplier consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Permanent Magnet Motor Backward Integration | Captures efficiency tier premium in Indonesian municipal contracts requiring national standards body certification. |
| Solar-Battery Hybrid System Development | Addresses Cambodia and Myanmar agricultural electrification gaps beyond centralized grid zones. |
| Predictive Maintenance Service Bundling | Converts Vietnamese Binh Duong industrial zone transactions into recurring performance-guaranteed revenue streams. |
| ASEAN Cross-Border Certification Harmonization | Reduces compliance cost inflation from divergent Indonesian, Thai, and Vietnamese national standards. |
| Local Assembly Facility Establishment | Satisfies Indonesian content requirements while shortening Java-Bali corridor delivery timelines. |
Research Methodology
Trade databases, ASEAN national standards body certification registries, and municipal procurement disclosure records formed the secondary backbone of this analysis. Primary interviews with Indonesian municipal waterworks engineers, Thai Board of Investment incentive program administrators, Vietnamese agricultural cooperative equipment purchasers, and aftermarket service technicians in Surabaya and Bangkok triangulated operational demand patterns. Bottom-up equipment shipment tracking and top-down infrastructure investment flow analysis validated segmentation splits across the analysis window.
Historical trendline analysis of municipal waterworks capital expenditure cycles, agricultural electrification program rollouts, and mining dewatering equipment replacement intervals informed projection modeling. Segmentation dimensions span pump type, power source technology, end-user procurement sophistication, and national regulatory framework clusters. CAGRs were derived from fitted growth curves against certified equipment deployment trajectories and solar-powered system adoption rates in off-grid zones.
Several conditions sit outside the modeled scope, including unannounced ASEAN trade bloc tariff reconfigurations, abrupt rare-earth magnet export restrictions, and force-majeure disruptions to Indonesian nickel mining operations. Forecasts reflect documented assumptions regarding continuity of Thai Board of Investment incentive structures and Vietnamese flood-resilience mandate enforcement. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pumps and Control Devices
Rotary Pump Market
Pumps and Control Devices
APAC Positive Displacement Pumps Market
Pumps and Control Devices
Progressive Cavity Pump (PCP) Market
Pumps and Control Devices
North America Axial Flow Pump Market
Pumps and Control Devices
Peristaltic Pumps Market
Pumps and Control Devices
Electrostatic Coalescers Market
Pumps and Control Devices
Gasketed Plate Heat Exchanger Market
Pumps and Control Devices
Global Vacuum Pump Market
Pumps and Control Devices
Slurry Pumps Market
Pumps and Control Devices
In Pipe Hydro Systems Market
Pumps and Control Devices
Mud Pumps Market
Pumps and Control Devices
Chemical Injection Pump Market
Pumps and Control Devices
Heavy Duty Dewatering Pumps Market
Pumps and Control Devices
Heating Tape Market
Pumps and Control Devices
Radial Piston Pumps Market
Pumps and Control Devices
Marine Pump Market