
 Centrifugal Air Compressor Market | 2026-2036
Centrifugal Air Compressor Market Size, Share, and Industry Trends Forecast 2026-2036
Centrifugal Air Compressor Market Analysis
ISO 8573-1 Class 0 certification is bifurcating the centrifugal air compressor landscape into premium oil-free and conventional lubricated tiers. Atlas Copco leverages its aftermarket service network to sustain recurring revenue across installed bases. Ingersoll Rand anchors its position through energy-efficient airend designs that reduce lifecycle power consumption. Siemens Energy competes on integrated electrification packages that pair compressors with variable-speed drives.
A centrifugal air compressor accelerates air through an impeller to achieve dynamic compression, typically delivering pressures from 100 to 150 psig with flow rates exceeding 1,000 cubic feet per minute for continuous industrial duty. The oil-free segment commands premium positioning as food and beverage processors and pharmaceutical manufacturers enforce zero-contamination protocols. Oil-lubricated compressors retain cost advantages in mining and heavy manufacturing where air quality requirements permit trace oil carryover. The above 500 HP power rating category dominates capital expenditure volumes while the 100-250 HP range represents the fastest replacement cycle due to mid-scale facility upgrades.
EPA emissions guidelines and OSHA workplace safety standards shape compressor efficiency mandates and noise exposure limits in U.S. industrial settings. The EU F-Gas Regulation and CE marking requirements drive refrigerant-based dryer integration and material traceability for European market access. Stakeholders must monitor evolving carbon border adjustments and efficiency labeling schemes that will redefine total cost of ownership calculations across procurement decisions.
Market Dynamics
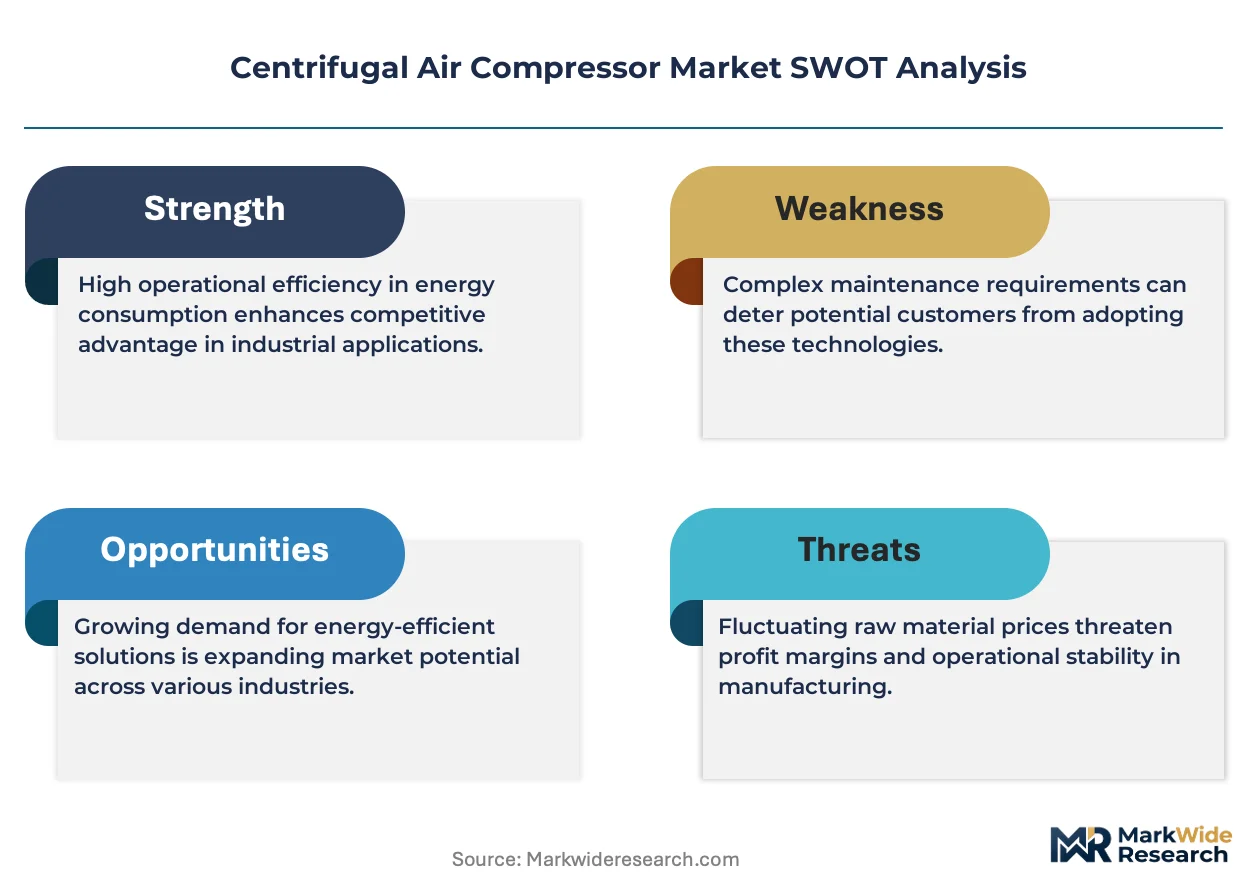
The centrifugal air compressor market is bifurcating around oil-free certification tiers, with ISO 8573-1 Class 0 compliance becoming a non-negotiable filter for pharmaceutical and food-grade procurement while conventional lubricated systems retain mining and heavy manufacturing footholds.
Growth Catalysts
- EPA emissions guidelines:U.S. industrial efficiency mandates are accelerating replacement cycles in aging Midwest manufacturing corridors. Compressor fleets installed before 2015 face compliance-driven upgrade pressure.
- Pharmaceutical manufacturing:Sterile process requirements in active pharmaceutical ingredient production are eliminating oil-lubricated alternatives from qualified supplier lists. Zero-contamination protocols now extend to packaging air systems.
- Variable-speed drive integration:Electrification packages pairing compressors with intelligent motor controls are compressing payback periods for continuous-duty operations. Energy-intensive chemical processors in Germany's Ruhr region are standardizing on these configurations.
Market Restraints
- Specialized alloy supply concentration:High-strength titanium and nickel-based superalloys for impeller casting concentrate among a limited supplier base. Foundry capacity constraints in precision engineering clusters create procurement bottlenecks.
- EU F-Gas Regulation:Refrigerant-based dryer integration requirements add compliance layers and extended certification timelines for European market entry. Third-party verification costs disproportionately burden mid-scale equipment manufacturers.
- Magnetic bearing cost premium:Oil-free compressor architectures dependent on active magnetic bearing systems carry 40-60% capital cost premiums over conventional hydrodynamic alternatives. This cost structure limits penetration in price-sensitive heavy industrial segments.
Strategic Opportunities
- India's PLI scheme for manufacturing:Production-linked incentives for domestic capital goods production are attracting assembly localization investments. Compressor OEMs can establish cost-competitive supply positions for South Asian chemical and textile processing demand.
- Hydrogen compression infrastructure:Electrolyzer and fuel cell manufacturing facilities require ultra-high-purity compressed air for membrane protection and process control. This emerging application demands specialized oil-free configurations with enhanced filtration.
- CE marking and material traceability convergence:Integrated compliance packages bundling compressor certification with downstream dryer and filtration documentation reduce buyer procurement friction. European engineering procurement departments are consolidating vendor relationships around full-system certifiers.
Industry Challenges
- Aerodynamic design specialization:Computational fluid dynamics expertise for impeller optimization resides within a narrow talent pool. Universities in Germany and Switzerland produce the majority of qualified engineers, creating recruitment competition.
- ISO 8573-1 Class 0 certification timelines:Third-party validation for oil-free performance claims requires 12-18 month testing protocols. Manufacturers face revenue recognition delays while certification is pending.
- Legacy control system integration:Brownfield industrial sites operate compressor fleets on proprietary automation architectures from the 1990s. Modern variable-speed drives require costly middleware development for seamless integration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Centrifugal Air Compressor Market |
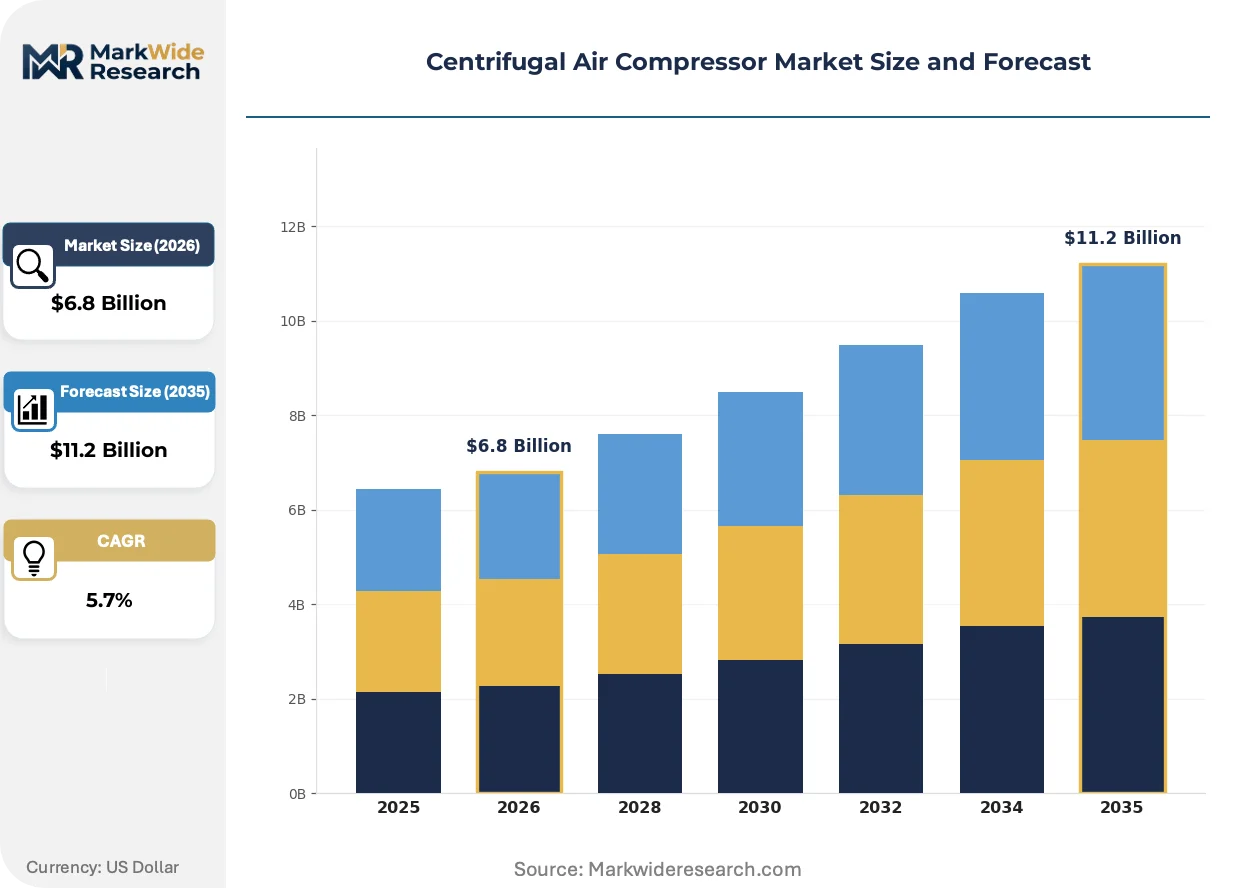
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Oil-Free Compressors, Oil-Lubricated Compressors, Portable Compressors, Stationary Compressors End User: Manufacturing, Food & Beverage, Pharmaceuticals, Mining Power Rating: Below 100 HP, 100-250 HP, 251-500 HP, Above 500 HP Distribution Channel: Online Sales, Direct Sales, Distributors, Retail |
| Companies Covered | Atlas Copco, Ingersoll Rand, Siemens Energy, Gardner Denver, Mitsubishi Heavy Industries, Elliott Group, Baker Hughes, Sundyne, Howden Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Centrifugal Air Compressor Market Emerging Trajectories
Digital twin deployment and predictive maintenance algorithms are compressing service response times while high-speed permanent magnet motors are displacing conventional induction drives in premium efficiency tiers.
High-speed permanent magnet motor technology is miniaturizing airend footprints while maintaining output density. Pharmaceutical cleanroom installations in Switzerland and Singapore are specifying these compact configurations to maximize floor space utility. The technology is miniaturizing ancillary equipment requirements, reducing total installation envelope by 30-40% compared to conventional gear-driven alternatives.
REACH substance restrictions and RoHS material compliance are forcing reformulation of bearing coatings and electrical insulation systems. Compressor manufacturers must requalify component supply chains to maintain European market access. The above 500 HP power rating category faces the most intensive material documentation requirements due to extended operational lifecycles.
After-sales service unbundling is fragmenting traditional OEM revenue models. Industrial buyers in Germany's chemical processing corridor are separating compressor procurement from maintenance contracts, engaging independent service providers with specialized magnetic bearing expertise. This pattern is most visible in continuous-process industries where downtime costs exceed premium OEM service pricing.
Centrifugal Air Compressor Market Segmentation
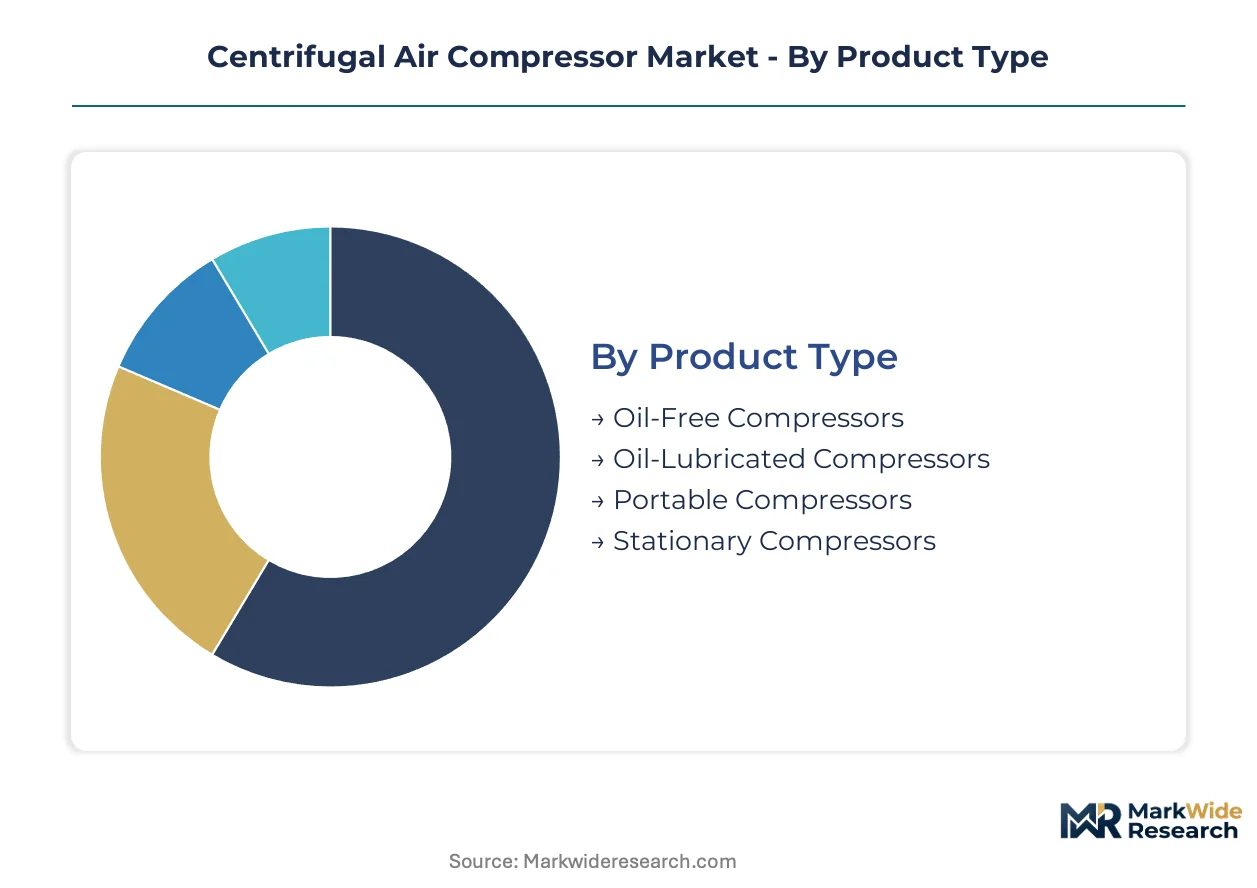
Centrifugal air compressor procurement splits across four distinct dimensions, each reshaping vendor priorities and buyer decision frameworks. Technology certification tiers, end-use contamination protocols, power density requirements, and channel accessibility create overlapping segment boundaries that complicate straightforward market entry.
Product Type:
Portable compressor configurations face the most acute substitution pressure from rental fleets and modular screw compressor deployments at construction and temporary industrial sites.
- Oil-Free Compressors:These systems eliminate lubricant contact with compressed air through sealed bearing architectures and advanced filtration. Pharmaceutical manufacturing facilities in Germany's Rhine-Main region specify ISO 8573-1 Class 0 configurations for sterile process air, with zero-contamination protocols now extending to secondary packaging lines.
- Oil-Lubricated Compressors:Conventional hydrodynamic bearing systems permit trace oil carryover in exchange for 40-60% lower capital outlay. Mining operations in Australia's Pilbara region and heavy manufacturing corridors in the US Midwest retain these systems where air quality specifications tolerate minimal contamination.
- Portable Compressors:Trailer-mounted or skid-based units serve temporary industrial demand and emergency backup requirements. Construction contractors and offshore maintenance crews represent the primary procurement base for these mobile configurations.
- Stationary Compressors:Fixed installations anchor continuous-process manufacturing infrastructure. Chemical processing facilities and automotive assembly plants standardize on these permanent configurations for baseline compressed air supply.
Oil-lubricated compressors anchor the volume base while oil-free configurations gain share at the steepest rate.
End User:
Cost tier stratification separates premium-certified equipment for contamination-sensitive processes from standard industrial configurations serving tolerance-heavy applications.
- Manufacturing:Automotive stamping, metal fabrication, and general assembly operations consume the largest installed base of centrifugal compressors. Plants in Germany's Ruhr industrial cluster prioritize energy-efficient variable-speed configurations to manage continuous-duty power costs.
- Pharmaceuticals:Active pharmaceutical ingredient production and sterile packaging demand oil-free air with validated contamination control. FDA and EMA inspection protocols now mandate documented compressor maintenance records as part of good manufacturing practice compliance.
- Food & Beverage:Dairy processing, brewing, and packaged food production require compressed air free from oil and particulate contamination. Swiss and Danish processing facilities lead adoption of certified oil-free systems for product contact applications.
- Mining:Underground ventilation, pneumatic tool supply, and mineral processing operations tolerate higher contamination levels. Remote site locations in Western Australia and Chile's Atacama Desert prioritize equipment durability over air purity specifications.
Manufacturing anchors the volume base while pharmaceuticals climbs the fastest as regulatory contamination protocols tighten.
Power Rating:
Application scale determines equipment architecture, with larger power categories demanding specialized foundation engineering and electrical infrastructure.
- Above 500 HP:Large-frame compressors serve centralized plant air systems and chemical process applications. These units require custom foundation design and dedicated electrical substations, concentrating demand among major integrated manufacturing sites.
- 100-250 HP:Mid-scale configurations represent the most active replacement cycle as facilities upgrade aging equipment for efficiency compliance. Germany's precision engineering clusters and US Midwest manufacturing corridors drive procurement volume in this bracket.
- 251-500 HP:Heavy industrial duty compressors bridge centralized and distributed air system architectures. Petrochemical processors and steel manufacturing facilities standardize on this power range for primary process air supply.
- Below 100 HP:Compact centrifugal units compete with rotary screw alternatives in light manufacturing and workshop applications. Limited adoption reflects screw compressor cost advantages at smaller scales.
Above 500 HP anchors the volume base while 100-250 HP expands most quickly through compliance-driven replacement cycles.
Distribution Channel:
Customer type and purchase complexity shape channel preference, with large capital projects diverging from routine maintenance procurement patterns.
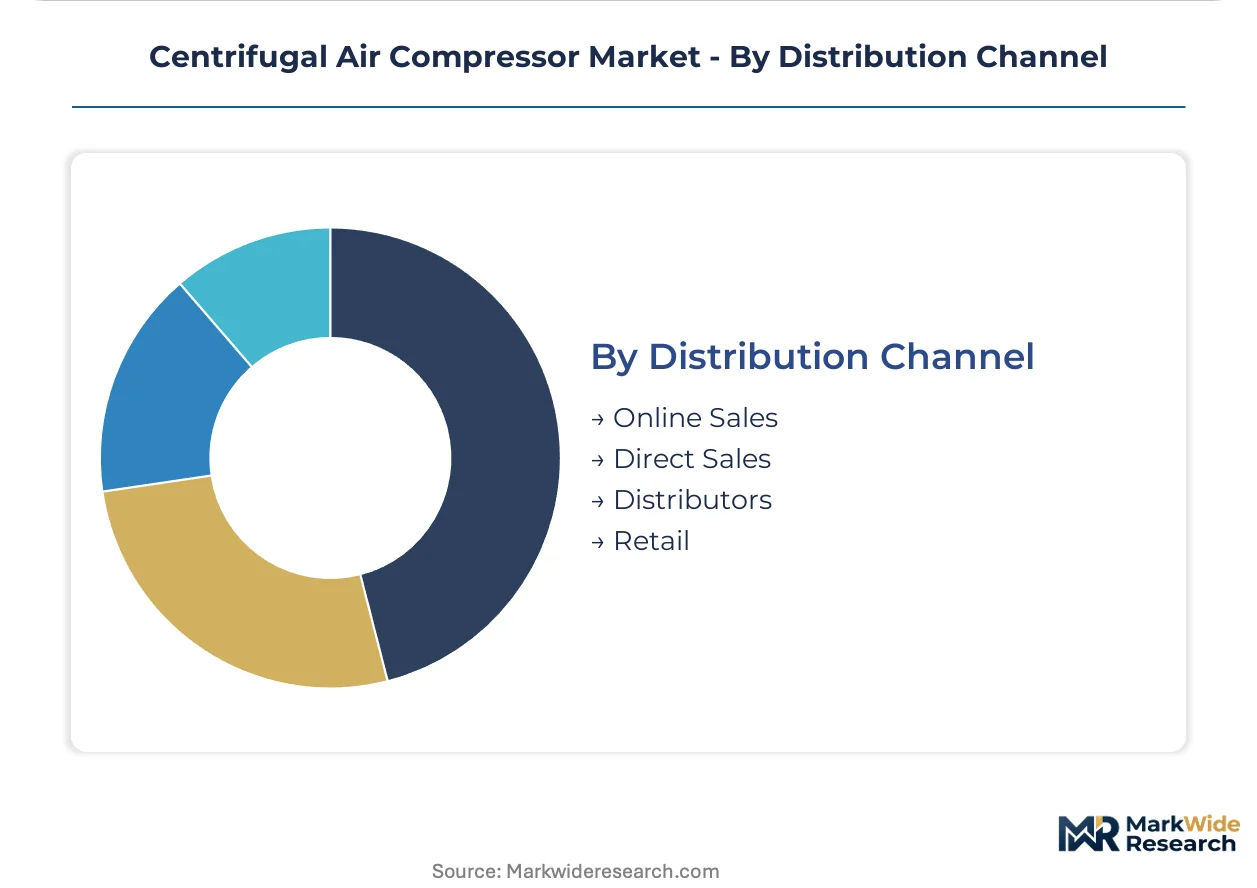
- Direct Sales:OEM field engineers engage directly for large-frame compressor projects requiring custom specification. Major chemical processors and automotive manufacturers negotiate enterprise pricing through direct procurement relationships.
- Distributors:Authorized dealer networks handle mid-scale equipment sales and regional service coverage. Independent distributors dominate in India's industrial corridors and Southeast Asian manufacturing zones.
- Online Sales:Digital procurement platforms serve replacement parts, consumables, and small ancillary equipment. MRO procurement departments increasingly route standard spare orders through e-commerce channels.
- Retail:Limited to portable compressor units and consumer-grade equipment through industrial supply stores. Construction contractors and small workshop operators represent the primary retail customer base.
Direct sales anchors the volume base while online channels gain share fastest as procurement digitization penetrates maintenance operations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Foundry capacity for titanium and nickel-based superalloys concentrates in Germany's precision engineering clusters and select Asian manufacturing hubs. Compressor OEMs source critical impeller castings from these concentrated supplier bases, creating geographic dependencies that shape regional market dynamics.
Germany
Chemical processors in the Ruhr region and pharmaceutical manufacturers along the Rhine-Main corridor drive premium oil-free compressor procurement. The EU F-Gas Regulation mandates refrigerant-based dryer integration for European market access. Stuttgart's precision engineering clusters anchor impeller casting expertise and active magnetic bearing development.
United States
Midwest manufacturing corridors face EPA emissions-driven replacement cycles for pre-2015 compressor fleets. OSHA workplace safety standards enforce noise exposure limits and efficiency mandates across industrial settings. Houston's petrochemical processors and Detroit's automotive stamping plants anchor above 500 HP equipment demand.
China
Steel manufacturing and petrochemical expansion in the Yangtze River Delta and Shandong Peninsula sustain heavy industrial compressor procurement. The country's dual carbon goals accelerate energy-efficient variable-speed drive adoption. Shanghai's industrial equipment distributors serve as regional supply hubs for Southeast Asian export markets.
India
Textile processing in Gujarat and chemical manufacturing in Maharashtra generate mid-scale compressor replacement demand. The PLI scheme for domestic capital goods production attracts assembly localization investments. Pune's industrial corridors host emerging compressor service networks targeting South Asian process industries.
Switzerland
Pharmaceutical cleanroom installations in Basel and biotech processing facilities drive ISO 8573-1 Class 0 certification requirements. Swissmedic inspection protocols mandate documented compressor maintenance records for good manufacturing practice compliance. Zurich's precision engineering sector supplies specialized magnetic bearing components to global OEMs.
Centrifugal Air Compressor Market Vendor Landscape
Concentration sits with diversified industrial conglomerates and specialized compressor engineering houses. The market structure reflects tiered competition between full-system integrators and component specialists. Two strategic archetypes dominate: integrated energy technology providers bundling electrification packages, and precision engineering specialists focused on aerodynamic optimization. Competitive moves center on aftermarket service network expansion and magnetic bearing technology licensing arrangements.
Among European-based industrial technology groups, Atlas Copco, Ingersoll Rand, and Siemens Energy occupy distinct positioning vectors. Atlas Copco exemplifies the aftermarket-centric archetype leveraging installed base service relationships. Ingersoll Rand represents energy efficiency-focused engineering with airend design specialization. Siemens Energy anchors integrated electrification positioning pairing compressor hardware with variable-speed drive systems.
| Leading Market Players |
|---|
| Atlas Copco |
| Ingersoll Rand |
| Siemens Energy |
| Gardner Denver |
| Mitsubishi Heavy Industries |
| Elliott Group |
| Baker Hughes |
| Sundyne |
| Howden Group |
| Others |
Supply Flow & Price Mechanics
ISO 8573-1 Class 0 certification gates both supplier qualification and price differentiation simultaneously, bifurcating procurement into premium oil-free and cost-optimized lubricated tiers while concentrating margin capture among certified OEMs serving pharmaceutical and food-grade buyers.
Pricing Analysis
ISO 8573-1 Class 0 dictates the pricing tier structure across the centrifugal air compressor landscape. Three-tier pricing separates certified oil-free systems from conventional lubricated units and economy-grade alternatives, with certification level and after-sales service bundling as primary differentiation drivers. Cost compression in the oil-lubricated tier is intensifying because mining and heavy manufacturing buyers prioritize capital outlay over lifecycle efficiency. Pharmaceutical processors show least price sensitivity due to contamination liability exposure, while construction contractors and mid-scale manufacturers anchor the most price-sensitive demand bracket.
Supply Chain Analysis
Extended lead times for titanium and nickel-based superalloy impeller castings signal supply-side constraints across precision engineering tiers. Foundry capacity concentrates in Germany, Japan, and select Chinese manufacturing hubs, with raw material procurement drawing from Australian titanium sponge and Russian nickel feedstock. Single-source vulnerability runs through active magnetic bearing component suppliers in Switzerland and Germany. Distribution runs through OEM-direct channels for large-frame projects and authorized dealer networks for mid-scale equipment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Procurement consolidation among European chemical processors and North American automotive OEMs is shifting bargaining power toward buyers, compressing OEM margins and unbundling traditional equipment-service contract packages.
For Market Incumbents: Shield installed base revenue through captive aftermarket service networks targeting magnetic bearing maintenance, where specialized expertise limits independent provider penetration. Deepen backward integration into precision casting capabilities to secure impeller supply against foundry bottlenecks. Prioritize ISO 8573-1 Class 0 certification maintenance as emerging Asian competitors challenge premium positioning. For New Entrants and Emerging Players: ISO 8573-1 Class 0 fast-track partnerships with European testing laboratories accelerate market entry timelines for oil-free compressor architectures. White-space concentration sits with India's chemical and textile processing corridors under PLI scheme incentives, where domestic assembly cost positions undercut landed European equipment. Go-to-market execution should anchor on distributor relationships in Pune and Ahmedabad rather than direct sales replication. For Investors and Strategic Acquirers: EU F-Gas Regulation implementation reshapes the acquisition landscape by elevating full-system certifiers with integrated dryer and filtration documentation capabilities. Long-term viability centers on electrification package providers pairing compressor hardware with variable-speed drive integration. Acquisition target archetype: mid-scale magnetic bearing specialists with pharmaceutical cleanroom installation track records. Signal to monitor: carbon border adjustment mechanism expansion beyond pilot sectors.| Strategic Initiative | Industry Significance |
|---|---|
| Magnetic Bearing Technology Licensing | Accelerates oil-free compressor development for pharmaceutical cleanroom specifications in Basel and Singapore. |
| Aftermarket Service Network Expansion | Captures recurring revenue from Germany's chemical processing corridor where downtime costs exceed premium pricing. |
| India PLI Scheme Localization | Establishes cost-competitive assembly positions for South Asian chemical and textile processing demand. |
| Hydrogen Compression Infrastructure Development | Addresses electrolyzer manufacturing requirements for ultra-high-purity compressed air with enhanced filtration. |
| Integrated Electrification Package Launch | Pairs compressor hardware with variable-speed drives for Ruhr region chemical processors managing continuous-duty power costs. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of trade customs data, OEM financial disclosures, and regulatory certification databases. Primary interviews engaged maintenance directors at pharmaceutical manufacturing facilities, plant engineers in Germany's chemical processing corridor, aftermarket service heads at major OEMs, and procurement leads at automotive stamping operations. Secondary validation drew from EPA emissions filings, EU F-Gas Regulation implementation reports, and SEC 10-K equipment segment disclosures. Bottom-up equipment shipment analysis triangulates against top-down industrial energy consumption modeling.
Segmentation dimensions modeled span technology certification tier, end-use contamination protocol, power rating category, and distribution channel structure across the projection horizon. CAGRs derive from equipment replacement cycle analysis, regulatory compliance-driven upgrade timelines, and electrification adoption curves in energy-intensive processing industries. Industry-specific forecast inputs include foundry capacity utilization for superalloy castings and pharmaceutical facility construction permitting activity in FDA and EMA jurisdictions.
Decision-makers should treat outputs as directional under sustained EPA efficiency mandate enforcement and EU carbon border adjustment progression; material deviation would warrant model refresh. Specific risk factors include titanium supply disruption from geopolitical tension, magnetic bearing component export restrictions, and pharmaceutical capital expenditure cycle downturns. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Compressors
Compressor Rental Market
Compressors
Compressed Air Lubricators Market
Compressors
Reciprocating Hydrogen Compressor Market
Compressors
Centrifugal Compressors Market
Compressors
Desiccant Compressed Air Dryer Market
Compressors
North America Air Compressor Market
Compressors
Booster Compressor Market
Compressors
Chlorine Compressors Market
Compressors
Air and Gas Compressor Market
Compressors
Reciprocating Compressor Market
Compressors
Scroll Compressor Market
Compressors
Rotary Lobe Compressor Market
Compressors
Rotary Air Compressor Market
Compressors
High Speed Blowers Market
Compressors
Reciprocating Air Compressor Market
Compressors
PAG Compressor Oil Market