
 Southeast Asia Industrial Pumps Market | 2026-2036
Southeast Asia Industrial Pumps Market Size, Share, and Industry Trends Forecast 2026-2036
Southeast Asia Industrial Pumps Market Analytics
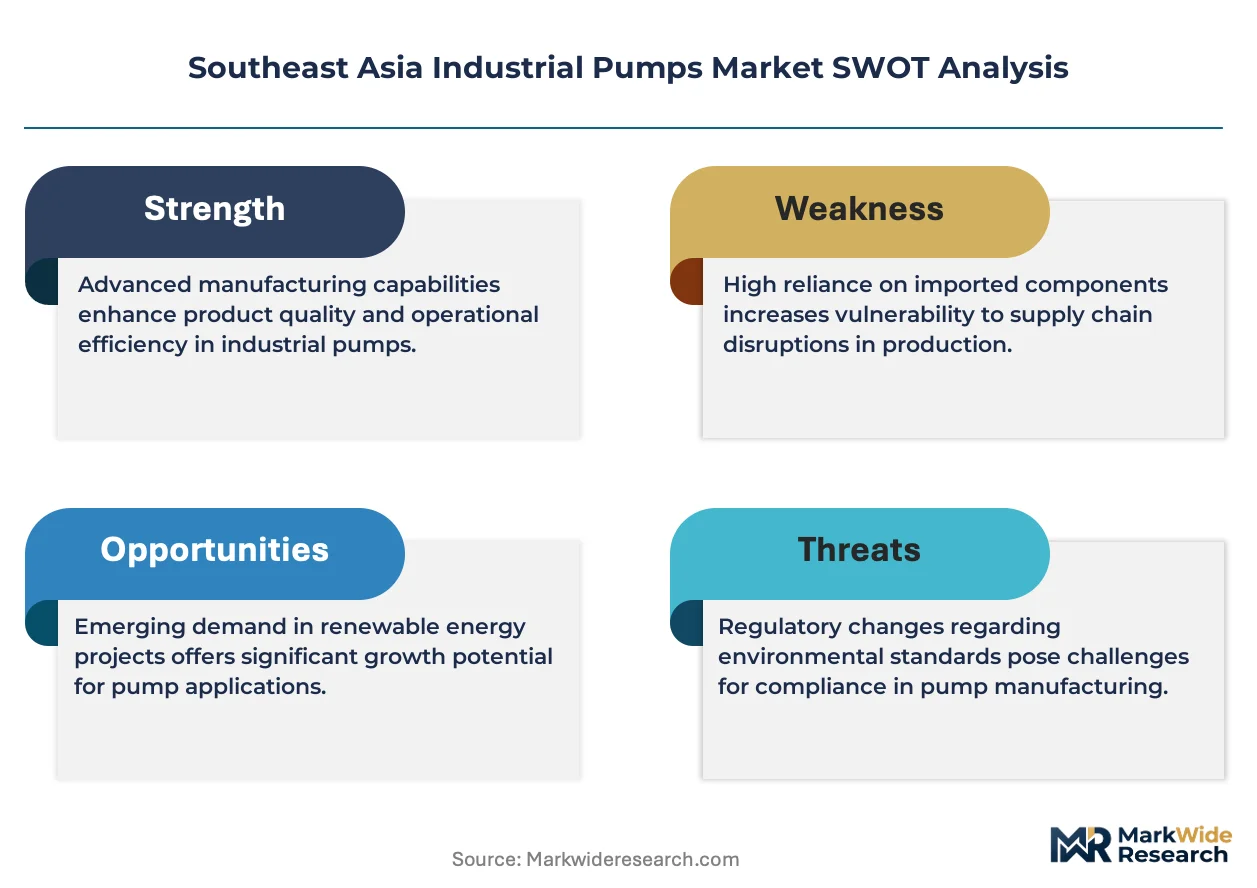
ASEAN green building codes are expanding the addressable market for high-efficiency pumping systems across commercial and industrial construction. Grundfos Holding A/S leverages its digital monitoring platforms to anchor service contracts in Thailand's municipal water sector. Flowserve Corporation competes through specialized alloy configurations for corrosive chemical environments in Singapore and Malaysia. KSB SE & Co. KGaA dominates large-project bidding for Indonesia's state-owned refinery expansions.
Southeast Asia industrial pumps are mechanical devices engineered to transfer fluids through rotational kinetic energy or positive displacement mechanisms, typically constructed from cast iron, stainless steel, or duplex alloys with flow capacities ranging from liters per minute to thousands of cubic meters per hour. Centrifugal pumps lead installed base volumes due to lower capital outlay and simpler maintenance protocols across water supply networks. Positive displacement pumps command premium positioning in oil and gas applications where precise flow control and high-viscosity handling justify elevated price points. Submersible installations are gaining fastest in wastewater management across flood-prone Indonesian and Vietnamese urban centers.
Thailand's Department of Industrial Works enforces effluent discharge standards that compel manufacturers to upgrade aging pump fleets, while Indonesia's Ministry of Environment and Forestry implements stricter hazardous substance containment rules affecting chemical processing operations. Singapore's PUB and Malaysia's SPAN both mandate energy performance labeling for water infrastructure equipment, narrowing market access for non-compliant suppliers. Stakeholders must weigh local content requirements against technology transfer costs when selecting manufacturing partnerships across ASEAN member states.
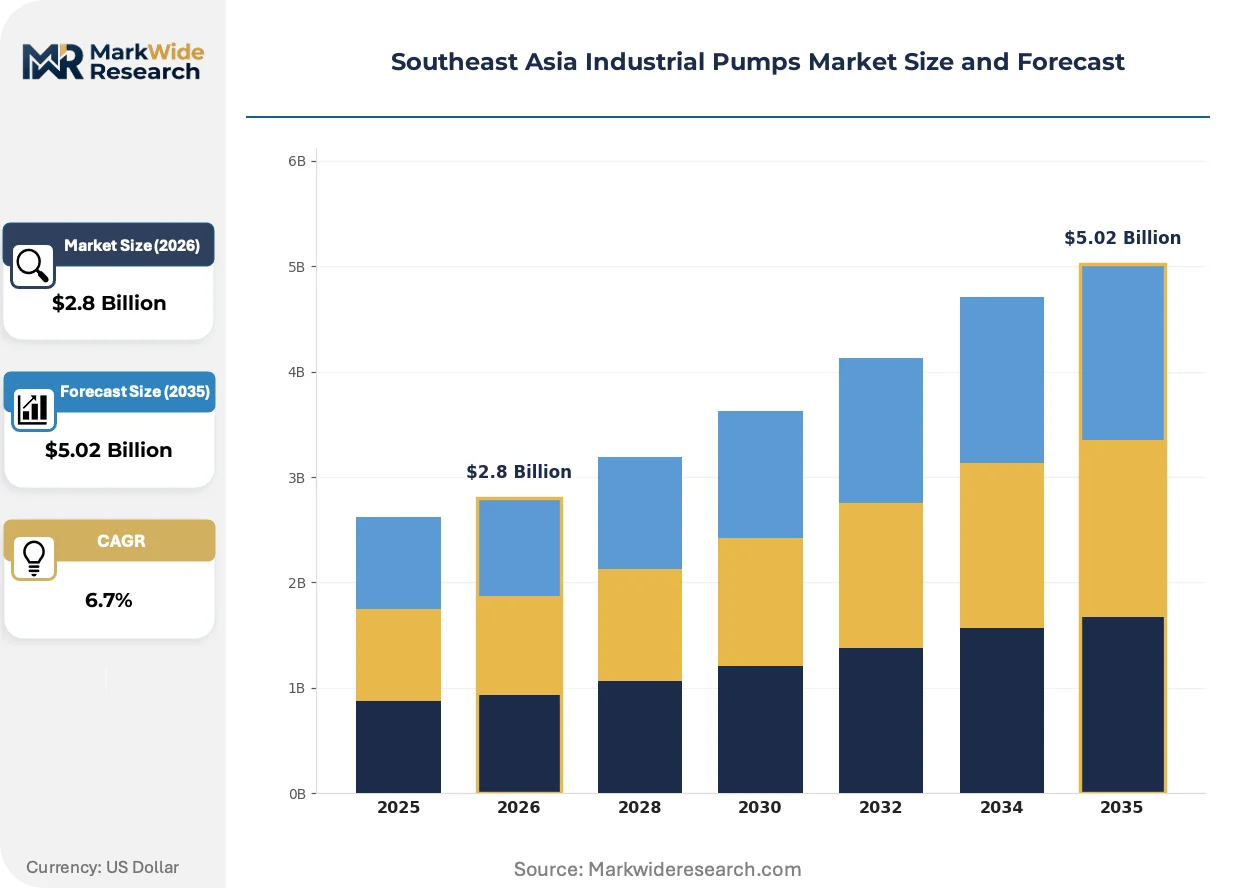
Market Dynamics
ASEAN green building codes are compressing replacement cycles for industrial pumping infrastructure across Thailand, Vietnam, and Indonesia, forcing facility operators to retire sub-IE3 motor systems ahead of depreciation schedules.
Growth Catalysts
- Thailand's effluent discharge standards:The Department of Industrial Works mandates real-time monitoring of wastewater volumes, compelling textile and food processing plants to install variable-frequency drive pumps with embedded flow sensors.
- Submersible pump adoption:Flood-prone urban centers in Jakarta and Ho Chi Minh City are standardizing submersible configurations for wastewater networks to prevent infrastructure damage during monsoon events.
- Indonesia's manufacturing corridor expansion:State-owned refinery projects along the Java north coast are generating concentrated demand for API-compliant centrifugal systems in high-temperature hydrocarbon service.
Market Restraints
- Duplex alloy supply concentration:Super-duplex stainless steel plate for corrosive chemical pumps relies on European and Japanese mill capacity, exposing ASEAN fabricators to 16-20 week lead times and currency volatility.
- Local content thresholds:Indonesia's Ministry of Industry enforces 40% domestic value-add requirements for public infrastructure tenders, forcing foreign OEMs to absorb technology transfer costs or cede bidding eligibility.
- Skilled technician scarcity:Precision alignment and vibration analysis for high-speed centrifugal installations exceeds the current certification depth of vocational training programs in Vietnam and the Philippines.
Strategic Opportunities
- Myanmar's underpenetrated industrial base:Yangon's Special Economic Zone development lacks established pump service networks, creating first-mover advantage for integrated supply-and-maintenance contracts.
- Digital twin integration:Cloud-based pump performance modeling is converging with ASEAN smart factory initiatives, enabling predictive maintenance revenue streams in Singapore's precision chemical sector.
- Singapore's PUB energy labeling mandate:The national water utility's efficiency certification program creates preferential procurement pathways for suppliers achieving designated performance tiers.
Industry Challenges
- Legacy control system integration:Brownfield installations in Malaysia's palm oil processing sector require custom protocol bridges to connect modern variable-speed drives with 1990s-era SCADA architectures.
- Cross-border spare parts logistics:Customs classification inconsistencies for pump impellers and mechanical seals between Thailand, Cambodia, and Laos extend critical repair timelines beyond acceptable downtime windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Southeast Asia Industrial Pumps Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Centrifugal Pumps, Positive Displacement Pumps, Diaphragm Pumps, Gear Pumps End User: Manufacturing, Oil & Gas, Water Treatment, Chemical Processing Installation Type: Submersible, Vertical, Horizontal, Portable Application: Water Supply, Wastewater Management, Heating Systems, Pest Control |
| Companies Covered | Kirloskar Brothers Limited, Grundfos Holding A/S, Flowserve Corporation, Sulzer Ltd, Ebara Corporation, KSB SE & Co. KGaA, Pumpco International Pte Ltd, Dancomech Holdings Berhad, Xylem Inc., Others |
| Regions Covered | Southeast Asia: Indonesia, Thailand, Vietnam, Philippines, Malaysia, Singapore, Myanmar, Cambodia, Rest of Southeast Asia |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Southeast Asia Industrial Pumps Market Evolving Landscape
Digital monitoring platforms are displacing scheduled maintenance paradigms across Southeast Asia's municipal water and chemical processing sectors, compressing service contract structures and rewiring supplier-buyer relationships.
Magnetic drive sealless pump technology eliminates mechanical seal failure points in hazardous chemical transfer applications. Singapore's Jurong Island petrochemical cluster is adopting these configurations for aromatics and acid service at replacement rates exceeding conventional sealed pumps. This architecture is converging with remote vibration monitoring to enable continuous health diagnostics without personnel exposure to toxic process fluids.
Indonesia's Ministry of Environment and Forestry is implementing hazardous substance containment rules that mandate secondary containment and leak detection for chemical processing pump installations. The regulation forces retrofit investments in double-walled piping and sensor networks. Refinery and specialty chemical producers in Cilegon and Gresik are responding by consolidating procurement specifications to reduce vendor qualification burden.
Performance-based service agreements are displacing traditional equipment-plus-spares purchasing in Thailand's municipal water sector. Provincial water authorities are unbundling capital expenditure from operational responsibility, transferring uptime risk to OEM service providers. This restructuring is most visible in Bangkok Metropolitan Waterworks Authority tenders, where 10-year lifecycle cost guarantees now outweigh initial capital cost weighting in bid evaluation.
Southeast Asia Industrial Pumps Market Segmentation
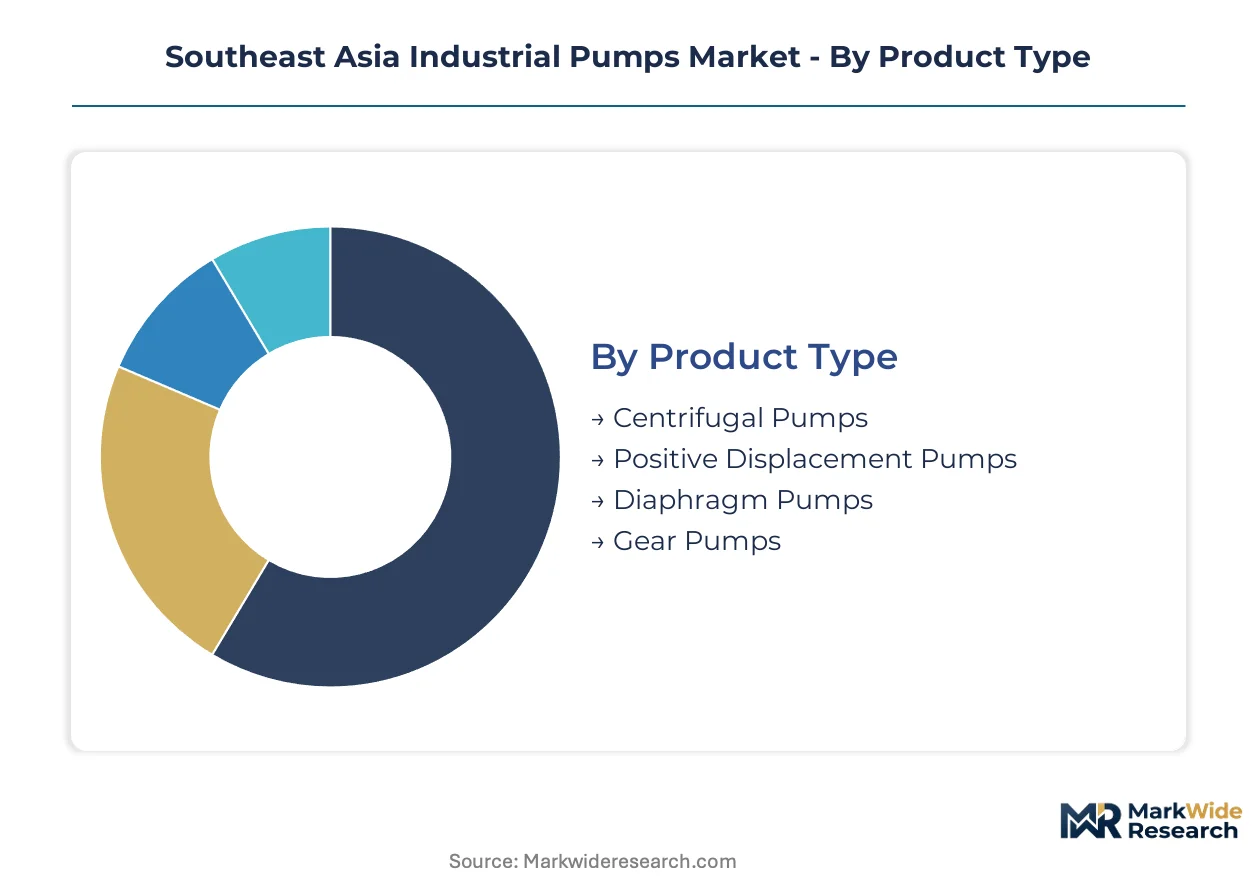
Pump specification in Southeast Asia diverges sharply across installation environments and fluid characteristics. Procurement committees weight capital efficiency against lifecycle operating costs, creating distinct competitive arenas for each configuration type.
Product Type:
Capital outlay thresholds and maintenance accessibility drive buyer selection between kinetic and positive displacement architectures.
- Centrifugal Pumps:These systems convert rotational kinetic energy into hydrodynamic energy through impeller action, with flow rates scalable from municipal water distribution to refinery cooling circuits. Thai provincial water authorities and Indonesian state-owned refineries along the Java north coast concentrate procurement here, drawn by lower upfront costs and standardized spare parts availability.
- Positive Displacement Pumps:Fixed-volume displacement mechanisms deliver precise flow control for high-viscosity hydrocarbons and chemical slurries. Singapore's Jurong Island petrochemical cluster and Malaysia's specialty chemical processors specify these for aromatics transfer, accepting premium pricing to eliminate shear damage and ensure containment integrity.
- Diaphragm Pumps:Air-operated double-diaphragm configurations isolate process fluid from mechanical components, serving corrosive chemical dosing in Vietnam's emerging electronics chemical sector.
- Gear Pumps:Interlocking gear mechanisms handle lubricating oils and viscous resins across Indonesia's palm oil processing and rubber manufacturing facilities.
Centrifugal pumps lead on scale across ASEAN municipal infrastructure; positive displacement pumps lead on momentum in Singapore-Malaysia chemical corridor expansions.
End User:
Regulatory stringency and process criticality determine specification grade and service contract structure.
- Manufacturing:Textile plants in Thailand's Eastern Economic Corridor and food processing facilities in Vietnam's industrial zones drive demand for stainless steel centrifugal systems with variable-frequency drives. Thailand's Department of Industrial Works effluent monitoring mandates compel real-time flow sensing integration.
- Oil & Gas:API-compliant centrifugal and twin-screw pumps handle high-temperature hydrocarbon service across Indonesia's Cilegon-Gresik refinery belt. State-owned operator procurement specifications emphasize 10-year lifecycle guarantees over initial capital weighting.
- Water Treatment:Municipal utilities in Jakarta, Bangkok, and Ho Chi Minh City standardize submersible configurations for flood-resilient wastewater networks, with Singapore's PUB energy labeling narrowing supplier qualification.
- Chemical Processing:Hazardous substance containment rules from Indonesia's Ministry of Environment and Forestry mandate magnetic drive sealless architectures and secondary containment systems for acid and solvent transfer.
Water treatment commands the broadest installed base; oil and gas generates the highest per-unit specification value.
Installation Type:
Site constraints and climate exposure dictate physical configuration and access protocol.
- Submersible:Motor and pump assemblies operate fully immersed, eliminating suction lift limitations and flood damage risk. Jakarta and Ho Chi Minh City wastewater authorities specify these for monsoon-resilient infrastructure, with dry-pit installation costs avoided.
- Vertical:Space-constrained installations in Singapore's Jurong Island chemical cluster and Bangkok's dense industrial zones favor column-suspended pumps with above-ground motor accessibility.
- Horizontal:Split-case and end-suction configurations dominate Thailand's provincial water treatment plants and Malaysian palm oil mills, where floor-mounted maintenance access reduces technician certification requirements.
- Portable:Engine-driven dewatering pumps serve construction and emergency response across flood-prone Vietnamese and Indonesian job sites.
Horizontal installations retain the largest legacy footprint; submersible configurations are climbing the fastest on urban flood adaptation spending.
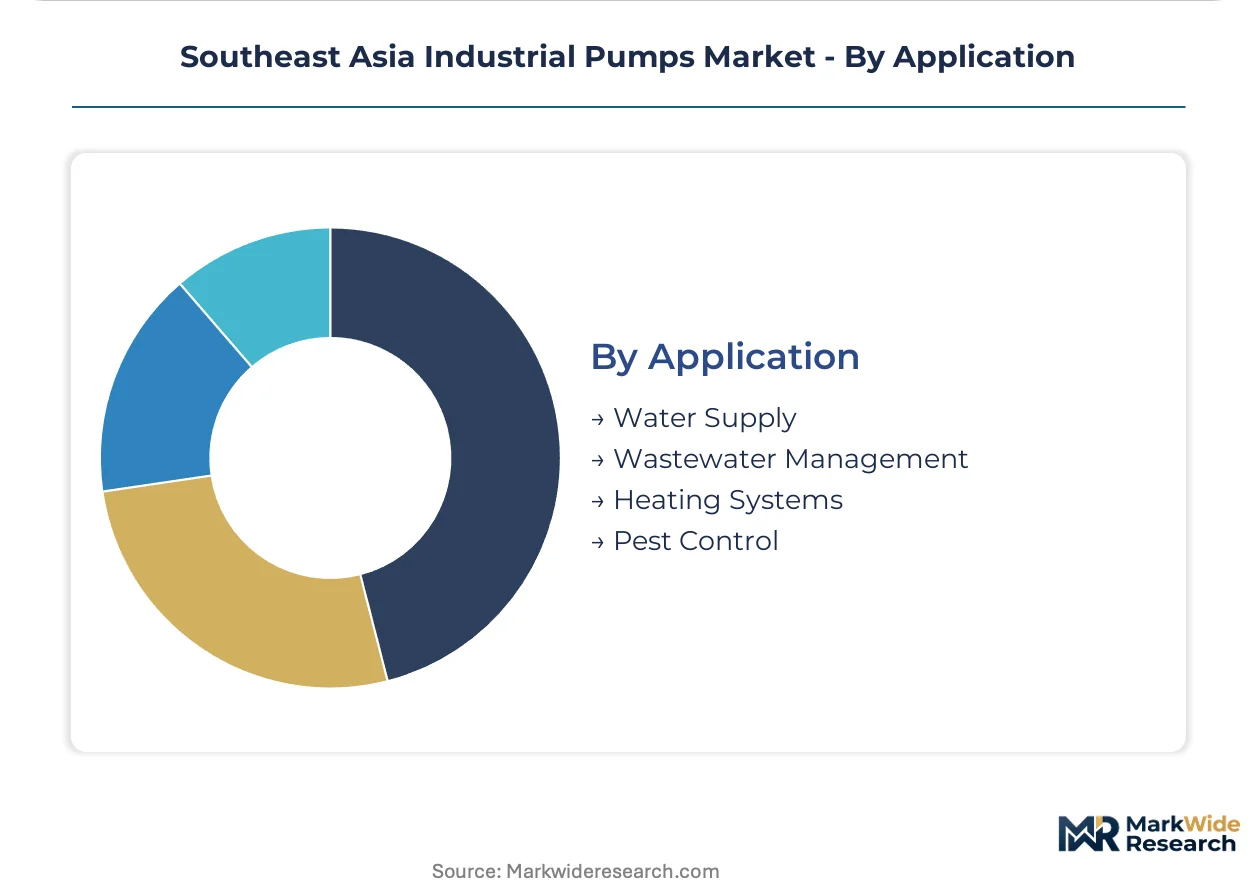
Application:
Fluid properties and duty cycle intensity determine material specification and monitoring integration.
- Water Supply:Clean water distribution networks across Thailand, Vietnam, and Indonesia specify cast iron or stainless steel centrifugal systems with IE3 motor minimums. Singapore's PUB and Malaysia's SPAN energy labeling programs filter non-compliant suppliers from tender eligibility.
- Wastewater Management:Solids-handling submersible pumps with vortex or channel impellers serve municipal sewage and industrial effluent in Jakarta and Bangkok. Thailand's real-time discharge monitoring mandates embed flow sensors and variable-frequency drives.
- Heating Systems:Circulator pumps for district heating and industrial boiler feed operate across Vietnam's northern manufacturing zones and Indonesia's state-owned facility retrofits.
- Pest Control:Small-scale diaphragm and centrifugal pumps support agricultural spraying in Thailand's Central Plains and Mekong Delta operations.
Water supply anchors procurement volume; wastewater management is gaining share fastest on regulatory enforcement and climate adaptation investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Engineering talent pools and vocational certification depth concentrate industrial pump demand across ASEAN's manufacturing belt, with facility operators prioritizing local service network density over pure equipment cost in procurement decisions.
Indonesia
State-owned refinery expansions along Java's north coast from Cilegon to Gresik drive API-compliant centrifugal system procurement. The Ministry of Industry enforces 40% domestic value-add thresholds for public infrastructure tenders. Manufacturing clusters in Surabaya and Bekasi absorb the highest volumes of submersible wastewater configurations for flood-resilient urban infrastructure.
Thailand
Textile and food processing plants in the Eastern Economic Corridor require variable-frequency drive pumps with embedded flow sensors for effluent compliance. The Department of Industrial Works mandates real-time wastewater volume monitoring. Bangkok Metropolitan Waterworks Authority tenders now weight 10-year lifecycle cost guarantees above initial capital outlay.
Singapore
Jurong Island petrochemical processors specify magnetic drive sealless architectures for hazardous aromatics and acid service. PUB's energy performance labeling program narrows supplier qualification to designated efficiency tiers. The precision chemical sector is converging cloud-based pump performance modeling with smart factory initiatives.
Vietnam
Emerging electronics chemical producers in northern manufacturing zones specify air-operated double-diaphragm pumps for corrosive dosing applications. Ho Chi Minh City wastewater authorities standardize submersible configurations for monsoon-resilient networks. Vocational training programs currently lack depth in precision alignment certification for high-speed centrifugal installations.
Malaysia
Palm oil processing facilities in Peninsular Malaysia require custom protocol bridges to integrate modern variable-speed drives with legacy SCADA architectures. SPAN mandates energy performance labeling for water infrastructure equipment. Specialty chemical processors specify positive displacement systems for high-viscosity transfer with containment integrity priorities.
Southeast Asia Industrial Pumps Market Competitive Landscape
Capital-heavy producers with integrated foundry and machining capabilities compete with asset-light designers outsourcing fabrication to regional contract manufacturers. The vendor base stratifies across three tiers: global OEMs with full lifecycle service platforms, regional fabricators leveraging local content compliance, and specialized alloy component suppliers. Strategic moves concentrate on technology transfer partnerships to satisfy domestic value-add mandates and predictive maintenance service contract unbundling to capture recurring revenue streams.
Within the premium-tier service vector, Grundfos Holding A/S and Flowserve Corporation exemplify platform-anchored positioning, while KSB SE & Co. KGaA occupies a position aligned with large-project state-owned procurement. Among Asia-Pacific headquartered fabricators, Ebara Corporation and Kirloskar Brothers Limited sit within regional manufacturing archetypes balancing cost positioning against specification breadth. Xylem Inc. and Sulzer Ltd represent integrated technology-service hybrids converging digital monitoring with equipment supply.
| Leading Market Players |
|---|
| Kirloskar Brothers Limited |
| Grundfos Holding A/S |
| Flowserve Corporation |
| Sulzer Ltd |
| Ebara Corporation |
| KSB SE & Co. KGaA |
| Pumpco International Pte Ltd |
| Dancomech Holdings Berhad |
| Xylem Inc. |
| Others |
Value Network & Pricing Analysis
Family-owned mid-cap fabricators across Thailand and Indonesia anchor production capacity, tightening pricing discipline through captive foundry operations while foreign OEMs absorb technology transfer costs to satisfy domestic value-add mandates. This ownership pattern concentrates bargaining power among established regional suppliers and compresses margin flexibility for asset-light competitors seeking market entry.
Pricing Analysis
The bundled-vs-unbundled service split defines competitive positioning across Southeast Asia's municipal and industrial procurement channels. Equipment-plus-spares purchasing dominates legacy horizontal installations in Malaysian palm oil processing, while performance-based service agreements with 10-year lifecycle guarantees now outweigh initial capital weighting in Bangkok Metropolitan Waterworks Authority tenders. Pricing stratifies across premium API-compliant systems for Indonesian refinery service, mid-tier stainless steel configurations for Thai effluent compliance, and economy cast iron models for basic water supply networks. Cost compression in the mid-tier segment intensifies as regional fabricators expand machining capacity and foreign OEMs localize assembly to meet Indonesia's 40% domestic value-add threshold. Municipal utilities exhibit highest price sensitivity due to budgetary constraints, while petrochemical processors on Singapore's Jurong Island prioritize containment integrity over unit cost.
Supply Chain Analysis
Super-duplex stainless steel plate for corrosive chemical pump construction rests on European and Japanese mill capacity, exposing ASEAN fabricators to extended procurement timelines and currency volatility. Duplex alloy supply concentrates in Germany, Sweden, and Japan, with nickel and chromium feedstock sourcing from Indonesian and Philippine mining operations. Mechanical seal assemblies and precision bearings draw from German and Japanese specialty component manufacturers. Single-source vulnerability in super-duplex plate creates bottleneck risk for API-compliant refinery pump deliveries along Java's north coast. Distribution runs through authorized distributor networks for spare parts and direct OEM engagement for large-project tenders, with local content compliance requirements forcing foreign suppliers into joint venture structures for public infrastructure access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Southeast Asia's industrial pumps market functions as a stable compounder, with regulatory enforcement of efficiency mandates and effluent standards generating predictable replacement demand across municipal and industrial installed bases.
For Market Incumbents: Anticipate margin compression from regional fabricators expanding into premium alloy configurations by deepening aftermarket service platform density and securing exclusive maintenance contracts with Indonesian state-owned refineries. Vertical integration into precision casting capabilities in Thailand or Vietnam defends position against local content compliance pressures while reducing exposure to European mill lead times for duplex material. For New Entrants and Emerging Players: Launch via integrated supply-and-maintenance contracts targeting Myanmar's Yangon Special Economic Zone, where established service networks remain absent and first-mover advantage accrues to operators offering localized technical support. Digital twin integration for predictive maintenance presents the most penetrable wedge into Singapore's precision chemical sector, where smart factory initiatives converge with cloud-based pump performance modeling. For Investors and Strategic Acquirers: Valuations sit cheapest among regional fabricators with established local content compliance and underutilized machining capacity, particularly those positioned near Indonesia's manufacturing corridor from Jakarta to Surabaya. Long-term viability hinges on technology transfer partnerships that unlock public infrastructure bidding eligibility. The signal to watch is acceleration in Indonesia's Ministry of Industry enforcement of domestic value-add thresholds, which would compress acquisition timelines for compliant assets.| Strategic Initiative | Industry Significance |
|---|---|
| Technology Transfer Partnership | Unlocks bidding eligibility for Indonesian state-owned refinery expansions under 40% local content rules. |
| Predictive Maintenance Platform Deployment | Captures recurring revenue streams from Bangkok Metropolitan Waterworks Authority lifecycle cost guarantee tenders. |
| Backward Integration into Precision Casting | Reduces duplex alloy plate dependency and shortens lead times for corrosive chemical pump deliveries. |
| Joint Venture with Local Fabricator | Satisfies Indonesia's domestic value-add mandates while preserving proprietary impeller designs. |
| Digital Twin Integration Development | Aligns with Singapore's smart factory initiatives and PUB energy labeling efficiency tiers. |
Research Methodology
Bottom-up end-use modeling reconciled against top-down supply-side tracking forms the analytical core of this study. Primary interviews with plant engineers at Thai textile and food processing facilities, procurement leads at Indonesian state-owned refineries, maintenance directors at Malaysian palm oil mills, and aftermarket service heads at regional distributors generated field-level validation. Secondary sources include customs and trade data for pump import flows, SEC filings from listed OEMs, ASEAN regulatory gazettes for efficiency mandate implementation, and tender documentation from Bangkok Metropolitan Waterworks Authority and Indonesia's Ministry of Industry.
Input-output matrices connect pump specification requirements across centrifugal, positive displacement, and submersible configurations to manufacturing capacity, raw material availability, and regulatory compliance thresholds. Segmentation dimensions span product type, end-use industry, installation environment, and application duty cycle. CAGRs derive from installed base replacement velocity, green building code enforcement timelines, and state-owned infrastructure procurement pipelines. Forecast inputs incorporate Indonesia's refinery expansion schedule, Thailand's effluent monitoring mandate rollout, and Singapore's PUB energy labeling tier evolution.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt currency volatility affecting duplex alloy procurement or sudden relaxation of Indonesian local content enforcement. A small set of named triggers warrants ongoing watch: ASEAN green building code adoption acceleration, Indonesia's Ministry of Industry tender rule changes, and European super-duplex mill capacity utilization shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pumps and Control Devices
Fluid Transfer System Market
Pumps and Control Devices
Water Desalination Pumps Market
Pumps and Control Devices
Industrial Pumps Market
Pumps and Control Devices
Heavy Duty Dewatering Pumps Market
Pumps and Control Devices
Fire Pump Test Meters Market
Pumps and Control Devices
Seawater Cooling Pumps Market
Pumps and Control Devices
Vacuum Pump Stations Market
Pumps and Control Devices
Electrohydraulic Pumps Market
Pumps and Control Devices
Global Compressor Control Systems Market
Pumps and Control Devices
Liquid Dispensing Pump Market
Pumps and Control Devices
Global Pumps Market
Pumps and Control Devices
North America Axial Flow Pump Market
Pumps and Control Devices
Automatic Tube Cleaning System Market
Pumps and Control Devices
Global Smart Pumps Market
Pumps and Control Devices
Circulators Market
Pumps and Control Devices
Global Diaphragm Pump Market