
 Automatic Tube Cleaning System Market | 2026-2036
Automatic Tube Cleaning System Market Size, Share, and Industry Trends Forecast 2026-2036
Automatic Tube Cleaning System Market Analysis
A shortage of certified heat exchanger maintenance technicians is unwinding traditional service models and pushing asset owners toward autonomous cleaning platforms. Taprogge GmbH leverages its decades of sponge-ball system expertise to dominate retrofit installations across European power stations. Alfa Laval sustains competitive pressure through integrated heat transfer and cleaning portfolios that reduce procurement complexity for plant operators.
An automatic tube cleaning system deploys mechanical, pneumatic, hydraulic, or electric mechanisms to remove biofouling, scale, and debris from the interior surfaces of heat exchanger and condenser tubes without disassembly, typically operating at pressures between 6 and 16 bar and cycle frequencies tuned to water chemistry conditions. Its primary industrial purpose is restoring thermal transfer efficiency and extending tube life in continuous-process environments. Pneumatic technology leads installed base volumes due to proven reliability in heavy-fouling marine and coastal power applications, while electric systems represent the fastest-expanding category as variable-frequency drives enable precision control over brush rotation speeds. Fully automatic system types command the strongest margin pools because they eliminate operator intervention and integrate directly with plant distributed control systems.
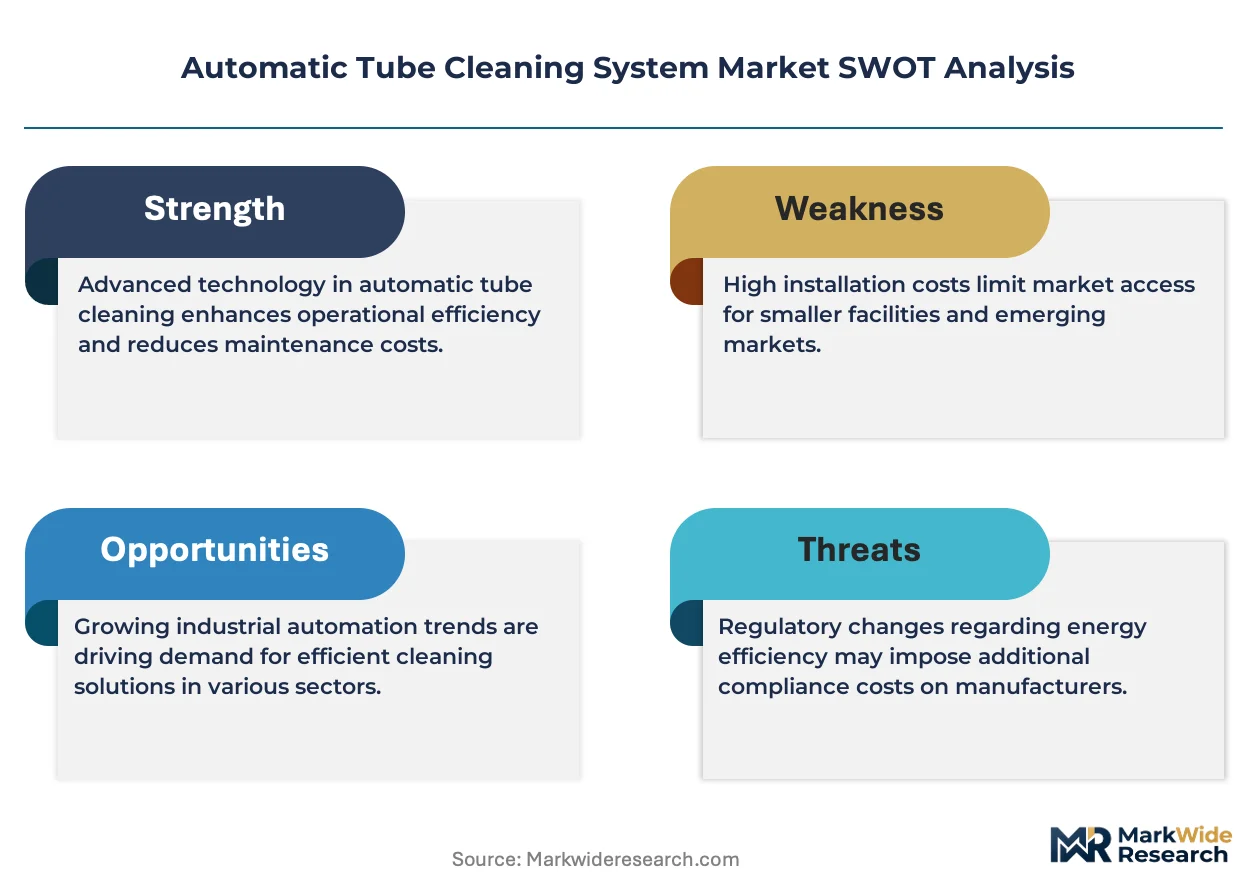
EPA cooling water intake regulations under Section 316(b) of the Clean Water Act and the EU Industrial Emissions Directive shape product standards by mandating reduced biocide discharge and thermal efficiency benchmarks that automated cleaning helps achieve. CE marking and ISO 9001 certification function as baseline market access requirements for European and international procurement frameworks. Stakeholders must monitor evolving carbon border adjustment mechanisms that could penalize inefficient thermal systems and accelerate replacement cycles for legacy manual cleaning infrastructure.
Market Dynamics
Power utilities face mounting pressure to sustain condenser thermal efficiency amid tightening discharge regulations and vanishing maintenance labor pools, forcing rapid automation of tube cleaning operations.
Growth Catalysts
- EPA Section 316(b) mandates:Cooling water intake rules compel US thermal plants to reduce biocide discharge through continuous mechanical cleaning rather than chemical dosing.
- Sponge-ball technology maturation:Decades of operational data from marine condenser applications now validate reliability metrics that satisfy utility procurement committees.
- German utility retrofit wave:Aging lignite and combined-cycle stations along the Rhine corridor require non-disassembly cleaning systems to extend asset life without extended outages.
Market Restraints
- Specialized alloy supply concentration:High-grade stainless brush components and corrosion-resistant pneumatic cylinders depend on concentrated German and Japanese metallurgical suppliers.
- Retrofit integration complexity:Legacy condenser designs from the 1970s-1980s lack standardized tube sheet configurations, forcing custom engineering on each installation.
- Manual cleaning substitution persistence:Low-labor-cost jurisdictions in Southeast Asia continue deploying dive teams and rodding crews for periodic maintenance.
Strategic Opportunities
- India thermal expansion:National supercritical coal additions and coastal nuclear projects create first-install demand without legacy equipment displacement costs.
- EU carbon border adjustment mechanism:Impending carbon intensity penalties on imported electricity will reward plants demonstrating verified thermal efficiency improvements through automated cleaning verification.
- Digital twin convergence:Integration of tube fouling sensors with predictive analytics platforms enables condition-based cleaning cycles rather than fixed intervals.
Industry Challenges
- Certified technician scarcity:Heat exchanger maintenance specialists with pneumatic system and controls expertise command premium wages that erode project margins.
- CE marking timeline compression:Pressure equipment directive compliance for high-pressure water jet modules adds 4-6 month certification delays to European deliveries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automatic Tube Cleaning System Market |
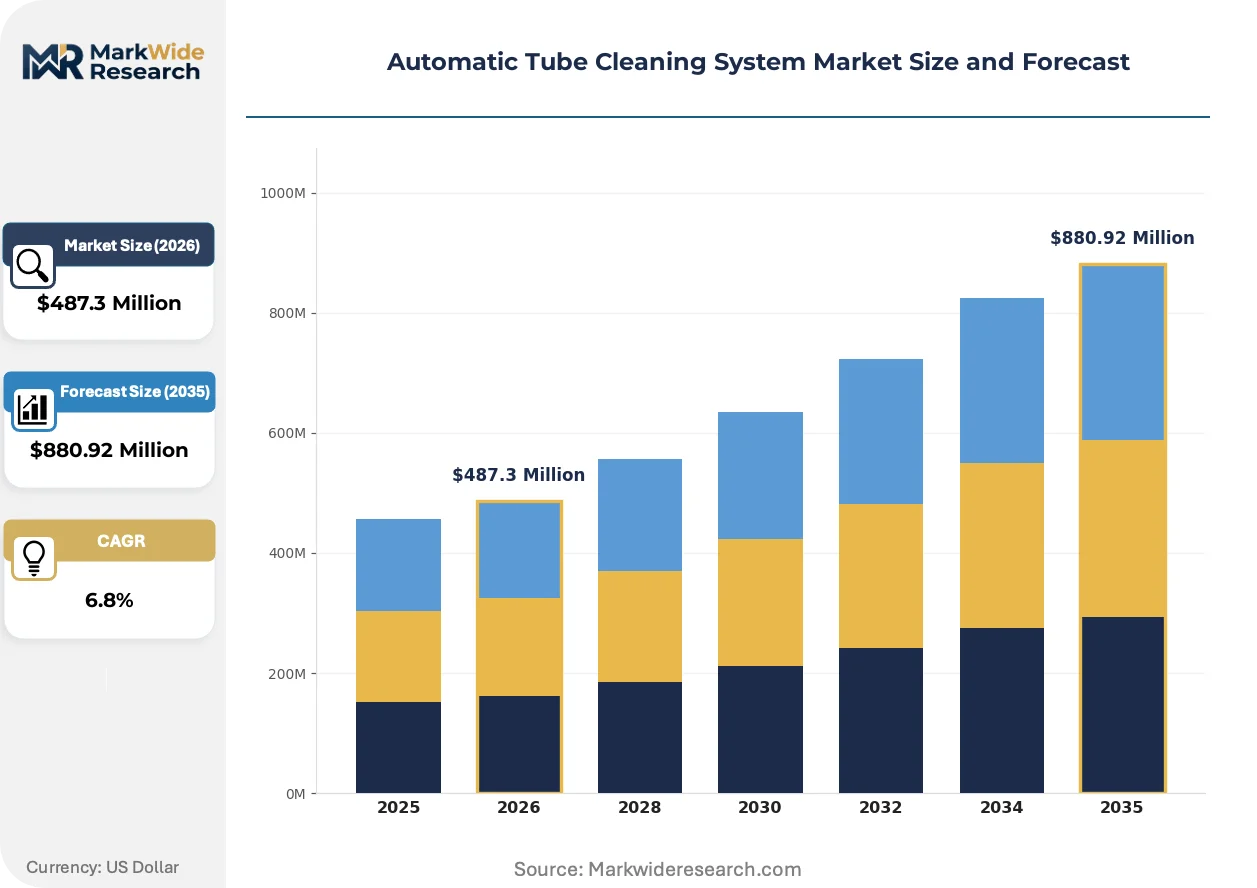
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Pneumatic, Hydraulic, Electric, Mechanical Application: Power Generation, Chemical Processing, Marine, Food Processing End User: Utilities, Manufacturing Plants, Oil Refinery, Hospitals System Type: Fixed, Portable, Semi-Automatic, Fully Automatic |
| Companies Covered | Taprogge GmbH, Alfa Laval, GEA Group, Ovivo, WSA Engineered Systems, Balltech Energy Ltd., Innovas Technologies LLC, WesTech Engineering, LLC, Hydroball Technics Holdings PTE Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automatic Tube Cleaning System Market Emerging Trajectories
Tube cleaning technology is bifurcating between proven pneumatic reliability and precision electric control, while regulatory compliance frameworks and procurement models undergo parallel restructuring.
Electric brush drive systems with variable-frequency control are fragmenting the historical pneumatic dominance in coastal power applications. US Gulf Coast utilities now specify electric units for precision rotation speed matching to tube metallurgy. The technology is fragmenting vendor specialization boundaries as electrical contractors compete with traditional mechanical cleaning firms.
REACH restrictions on biocidal active substances are eliminating copper-based antifoulants from cooling water treatment protocols. German and Dutch power operators must demonstrate reduced chemical discharge through verified mechanical cleaning performance. Marine condenser installations in the North Sea basin face the most acute compliance pressure and fastest electric system adoption.
Asset owners now unbundle cleaning system procurement from long-term service contracts, reversing decades of integrated vendor lock-in. Independent service providers in Texas and Florida are capturing aftermarket maintenance through remote diagnostic capabilities. This disaggregation is most advanced in deregulated US power markets where plant operators optimize opex through competitive sourcing.
Automatic Tube Cleaning System Market Segmentation
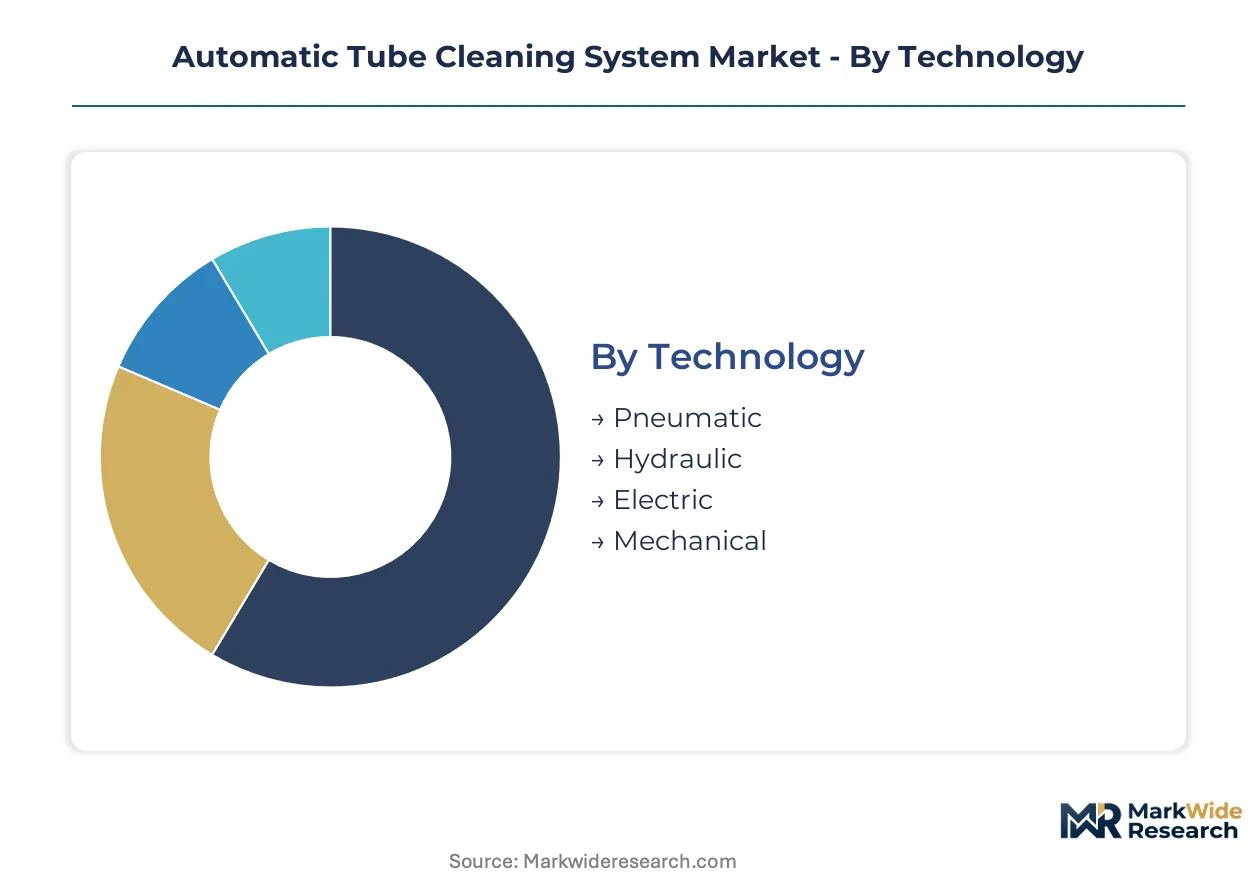
Technology and automation level determine margin capture in tube cleaning systems. Application-specific fouling chemistries and regulatory exposure further stratify procurement patterns across end-use verticals.
Technology:
Pneumatic systems command the deepest margin pools due to proven reliability in heavy-fouling environments and established aftermarket service revenues.
- Pneumatic:Compressed air drives sponge-ball circulation through condenser tubes at 6-16 bar operating pressure. Rhine corridor lignite stations and US Gulf Coast utilities specify these for continuous-duty marine condenser maintenance where salt-laden biofouling accumulates fastest.
- Electric:Variable-frequency drives enable brush rotation speed matching to tube metallurgy specifications. German and Dutch North Sea installations are rotating toward electric units as REACH restrictions eliminate copper-based antifoulants and demand precision cleaning verification.
- Hydraulic:High-pressure water jet modules deliver 150-300 bar cleaning force for hardened scale removal in chemical processing heat exchangers.
- Mechanical:Rod and brush manual-assist systems persist in Southeast Asian dive-team maintenance protocols.
Pneumatic technology holds installed capacity. Electric systems are rotating up the share rankings.
Application:
Power generation concentrates procurement volume, while marine and chemical processing yield premium pricing through corrosion-resistant specifications.
- Power Generation:Thermal and nuclear plants deploy continuous cleaning to sustain condenser vacuum and turbine efficiency. US utilities facing EPA Section 316(b) mandates favor automated systems over chemical dosing for cooling water compliance.
- Chemical Processing:Petrochemical crackers and fertilizer plants require explosion-rated pneumatic systems for hydrocarbon-fouled exchangers. German BASF and Bayer complexes specify ATEX-certified units for ethylene plant maintenance.
- Marine:Cruise ship and container vessel operators fit compact sponge-ball systems for seawater-cooled auxiliary machinery.
- Food Processing:Dairy pasteurizers and sugar refinery evaporators demand sanitary-grade stainless construction with CIP compatibility.
Power generation dominates current order books. Marine applications are climbing the fastest.
End User:
Utilities separate from industrial buyers through long-term service contracting patterns and DCS integration requirements.
- Utilities:Public and investor-owned power stations specify fully automatic systems with SCADA integration. Texas and Florida deregulated markets now unbundle cleaning procurement from vendor lock-in contracts.
- Manufacturing Plants:Pulp and paper mills, steel works, and cement plants favor portable units for seasonal turnaround maintenance.
- Oil Refinery:FCC unit overhead condensers and crude preheat trains require high-temperature hydraulic cleaning for coke and asphaltene deposits.
- Hospitals:District heating and medical sterilization systems specify compact electric units for 24/7 critical infrastructure uptime.
Utilities anchor replacement demand. Manufacturing plants are expanding most quickly in developing economies.
System Type:
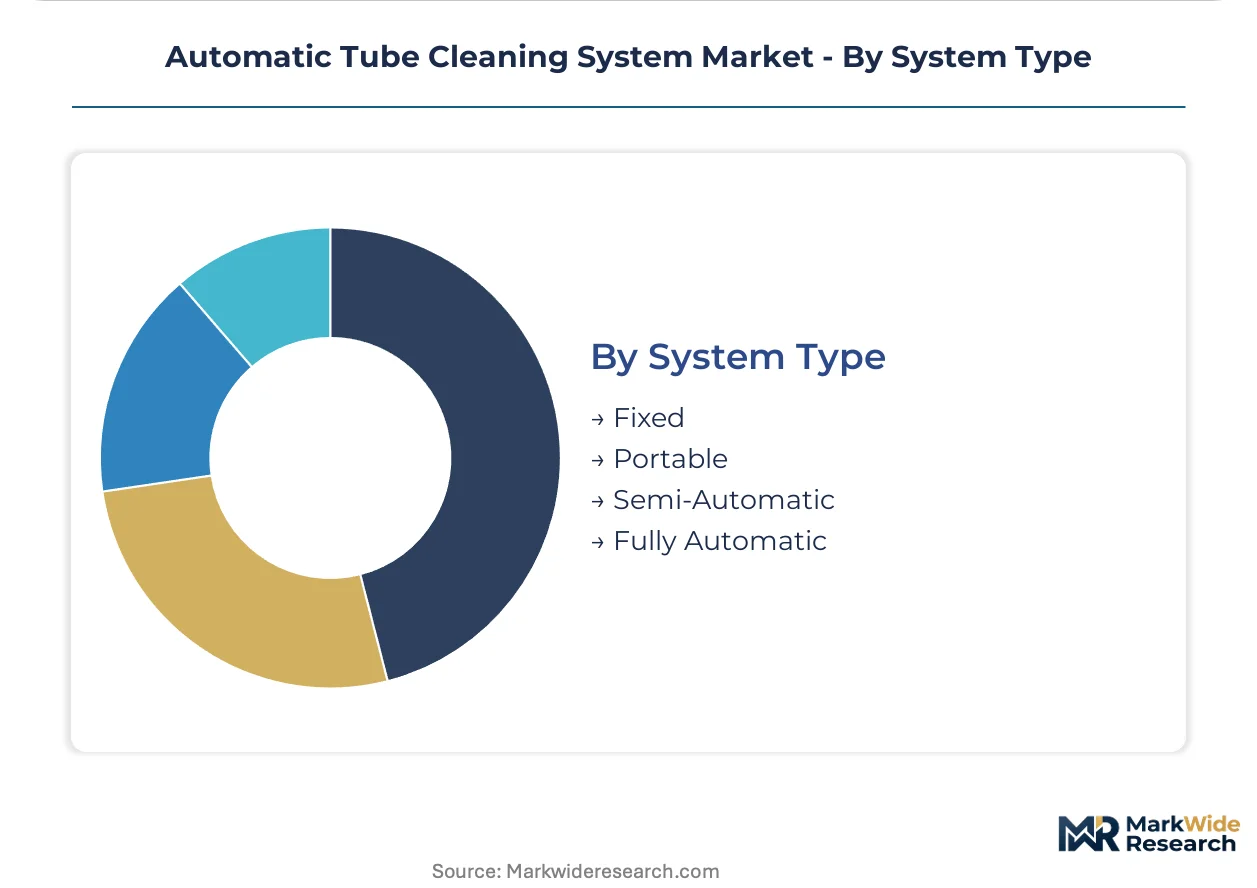
Fully automatic configurations capture the strongest margins through eliminated labor and direct plant control system integration.
- Fully Automatic:Sensor-triggered cleaning cycles operate without operator intervention and log performance data for regulatory verification. EU carbon border adjustment preparation is accelerating adoption across German and Dutch power stations.
- Fixed:Permanent installation on single heat exchanger or condenser unit. Indian supercritical coal additions specify fixed sponge-ball systems for first-install efficiency without legacy displacement costs.
- Portable:Trailer-mounted or skid-based units service multiple assets across plant sites. US independent service providers in Texas deploy these for competitive aftermarket capture.
- Semi-Automatic:Operator-initiated cycles with automated mechanical execution. Southeast Asian facilities with available maintenance labor favor this cost-controlled intermediate.
Fully automatic systems command pricing premiums. Portable configurations are gaining share fastest in deregulated service markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Power utilities in the United States deploy sponge-ball systems for continuous condenser maintenance, while German operators favor electric brush units for precision compliance with REACH-mandated chemical reductions. This consumption-mix differential reflects divergent regulatory pressures and labor cost structures across major markets.
United States
Gulf Coast utilities specify electric tube cleaning systems for variable-frequency brush control matched to coastal condenser metallurgy. EPA Section 316(b) cooling water intake rules compel Texas and Florida plants to replace chemical dosing with verified mechanical cleaning performance. The ERCOT deregulated market drives competitive unbundling of cleaning procurement from long-term service contracts.
Germany
Rhine corridor lignite and combined-cycle stations require non-disassembly cleaning systems to extend aging asset life without extended outages. The EU Industrial Emissions Directive and impending carbon border adjustment mechanisms reward plants demonstrating thermal efficiency improvements through automated cleaning verification. North Rhine-Westphalia power clusters anchor European demand for fully automatic DCS-integrated configurations.
India
National supercritical coal additions and coastal nuclear projects create first-install demand without legacy equipment displacement costs. Central Electricity Authority efficiency mandates push state-owned NTPC and private Reliance operators toward continuous cleaning for condenser vacuum optimization. Gujarat and Tamil Nadu industrial corridors concentrate manufacturing plant demand for portable seasonal maintenance units.
Netherlands
North Sea marine condenser installations face acute REACH compliance pressure eliminating copper-based antifoulants from cooling water treatment. Dutch power operators rotate toward electric systems for precision cleaning verification required by environmental regulators. Rotterdam port industrial clusters drive specification of sanitary-grade stainless construction for food processing heat exchanger applications.
Japan
Coastal thermal plants and nuclear facilities deploy pneumatic sponge-ball systems for heavy-fouling seawater condenser maintenance. METI efficiency standards and carbon neutrality targets compel utilities to demonstrate measurable heat rate improvements through automated cleaning data logging. Kansai and Kyushu regional power markets concentrate retrofit demand for fixed installation configurations.
Automatic Tube Cleaning System Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in the automatic tube cleaning system market. The upper tier combines heat transfer equipment manufacturing with automated cleaning technology portfolios, while mid-tier specialists focus exclusively on pneumatic or electric cleaning mechanisms. Three archetypes define competitive positioning: integrated thermal solution providers, dedicated cleaning technology specialists, and regional service contractors with portable equipment fleets. Dominant competitive moves include backward integration into corrosion-resistant alloy component production and technology licensing agreements for electric variable-frequency drive modules.
Within the integrated thermal solutions tier, Taprogge GmbH and Alfa Laval exemplify divergent strategic positions. The German GmbH structure of Taprogge signals long-standing engineering specialization, while the Swedish multinational form of Alfa Laval reflects diversified industrial equipment scale. Among dedicated cleaning specialists, Innovas Technologies LLC represents the US limited liability company model focused on aftermarket service capture in deregulated power markets. These three anchors illustrate how corporate form and geographic origin map onto distinct competitive vectors in a market where technology reliability and regulatory compliance documentation determine procurement outcomes.
| Leading Market Players |
|---|
| Taprogge GmbH |
| Alfa Laval |
| GEA Group |
| Ovivo |
| WSA Engineered Systems |
| Balltech Energy Ltd. |
| Innovas Technologies LLC |
| WesTech Engineering, LLC |
| Hydroball Technics Holdings PTE Ltd. |
| Others |
Supply Flow & Price Mechanics
Four-to-six month CE marking timelines for high-pressure water jet modules concentrate pricing power with German and Japanese metallurgical suppliers of corrosion-resistant pneumatic cylinders and stainless brush components. This lead-time band forces asset owners to absorb premium pricing for certified components or accept extended project delays, tightening margins for system integrators while rewarding backward integration into alloy production.
Pricing Analysis
Long-term service contracting dominates utility procurement, though deregulated US markets are fragmenting toward spot-based aftermarket competition. Three-tier pricing structure across premium, standard, and economy levels separates fully automatic DCS-integrated configurations from fixed installations and portable seasonal units. Cost compression in the portable tier intensifies as Texas and Florida independent service providers compete on opex optimization. Manufacturing plants in developing economies exhibit highest price sensitivity, while German and Dutch utilities facing REACH compliance show lowest sensitivity due to regulatory verification requirements.
Supply Chain Analysis
Germany and Japan anchor production of high-grade stainless brush components and corrosion-resistant pneumatic cylinders that feed global system assembly. Raw material flows draw from specialized alloy feedstock, precision-machined valve assemblies, and variable-frequency drive modules sourced from regional electrical contractors. Single-source vulnerability concentrates in German metallurgical suppliers serving the Rhine corridor retrofit wave. Distribution runs through OEM direct sales for utility-scale installations and independent service provider fleets for aftermarket portable deployment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electric variable-frequency drive technology is disrupting pneumatic dominance in coastal power applications, creating acceleration windows for vendors with precision control capabilities and regulatory verification platforms.
For Market Incumbents: Secure captive supply of corrosion-resistant alloy components to defend against Japanese and German metallurgical concentration risks. Deepen integration with plant distributed control system vendors to lock in utility procurement specifications before electric system specialists fragment vendor boundaries. Priority certification investment in ATEX and CE marking compression capabilities protects European delivery timelines.
For New Entrants and Emerging Players: Aftermarket remote diagnostic capabilities represent the most penetrable service-layer gap where incumbents under-serve deregulated US power markets. Target portable system deployment for competitive opex capture in Texas and Florida ERCOT territories. Go-to-market through independent service provider channel partnerships bypasses entrenched OEM procurement relationships.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial equipment parents with under-monetized tube cleaning technology portfolios. Long-term viability centers on regulatory compliance verification platforms rather than hardware margins alone. Signal to monitor: EU carbon border adjustment mechanism implementation pace and associated thermal efficiency documentation requirements.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alloy Production | Captive supply of German and Japanese corrosion-resistant components defends margin against metallurgical concentration. |
| Electric Drive Module Development | Variable-frequency control capabilities capture German and Dutch REACH compliance-driven replacement cycles. |
| Remote Diagnostic Platform Launch | Texas and Florida deregulated markets reward aftermarket service unbundling from OEM lock-in contracts. |
| CE Marking Acceleration Program | Pressure equipment directive compliance compression captures Rhine corridor lignite station retrofit demand. |
| DCS Integration Partnership | SCADA-native cleaning cycles lock in utility procurement specifications against emerging electric specialists. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of EPA enforcement databases, EU Industrial Emissions Directive implementation reports, and power utility procurement documentation. Interviews with maintenance directors at thermal and nuclear facilities, plant engineers specifying condenser retrofits, aftermarket service heads at independent providers, and OEM procurement teams at integrated heat transfer equipment manufacturers inform demand-side validation. Top-down market sizing from regulatory mandate scopes triangulates against bottom-up installation tracking across US Gulf Coast, German Rhine corridor, and Indian supercritical coal additions.
Segmentation dimensions modeled span technology type, automation level, application vertical, and end-user contracting structure across the analysis window. Power generation capacity additions, REACH restriction implementation phases, and certified technician wage inflation feed growth trajectory derivation. CAGRs reflect installed base replacement cycles, first-install penetration in greenfield projects, and technology switching patterns between pneumatic and electric systems.
Forecasts assume regulatory continuity in EPA Section 316(b) enforcement and EU carbon border adjustment preparation; material policy shifts would require re-modeling. Recalibration cycles align with material shifts in biocide discharge restriction timelines and utility labor pool contraction rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pumps and Control Devices
North America Positive Displacement Pumps Market
Pumps and Control Devices
Global Diaphragm Pump Market
Pumps and Control Devices
Multistage Pump Market
Pumps and Control Devices
Europe Subsea Pumps Market
Pumps and Control Devices
Europe, Middle-East and Africa Diaphragm Pump Market
Pumps and Control Devices
Marine Pump Market
Pumps and Control Devices
Bubble Membrane Disc Diffuser Market
Pumps and Control Devices
Energy-Saving Canned Motor Pump Market
Pumps and Control Devices
Global Smart Pumps Market
Pumps and Control Devices
Rotary Vane Vacuum Pump Market
Pumps and Control Devices
Asia Pacific Industrial Pumps Market
Pumps and Control Devices
Southeast Asia Submersible Pumps Market
Pumps and Control Devices
Global Self Priming Pumps Market
Pumps and Control Devices
Package Pumping Station Market
Pumps and Control Devices
Electric Submersible Pump (ESP) in Oil and Gas Market
Pumps and Control Devices
North America Submersible Pumps Market