
 End Suction Pump Market | 2026-2036
End Suction Pump Market Size, Share, and Industry Trends Forecast 2026-2036
End Suction Pump Market Analysis
Municipal water infrastructure is repositioning toward higher-efficiency end suction pump architectures as cities upgrade aging distribution networks. Grundfos leverages its digital pump monitoring platforms to anchor technology leadership in intelligent water systems. Xylem competes through vertical integration into advanced controls and analytics, while KSB sustains manufacturing scale advantages across European and Asian production bases.
An end suction pump draws fluid through a single inlet located at the front of the impeller eye, with the pump casing typically fabricated from cast iron, stainless steel, or bronze alloys depending on corrosion resistance requirements; this configuration permits direct motor coupling and simplifies maintenance access in commercial and industrial fluid transfer duties. Centrifugal pumps dominate installed capacity across water treatment and building services applications, while magnetic drive pumps capture margin pools in chemical processing where zero-leakage compliance commands pricing premiums. Submersible variants are gaining share in groundwater extraction and wastewater lift stations where space constraints and flood protection priorities reshape specification standards.
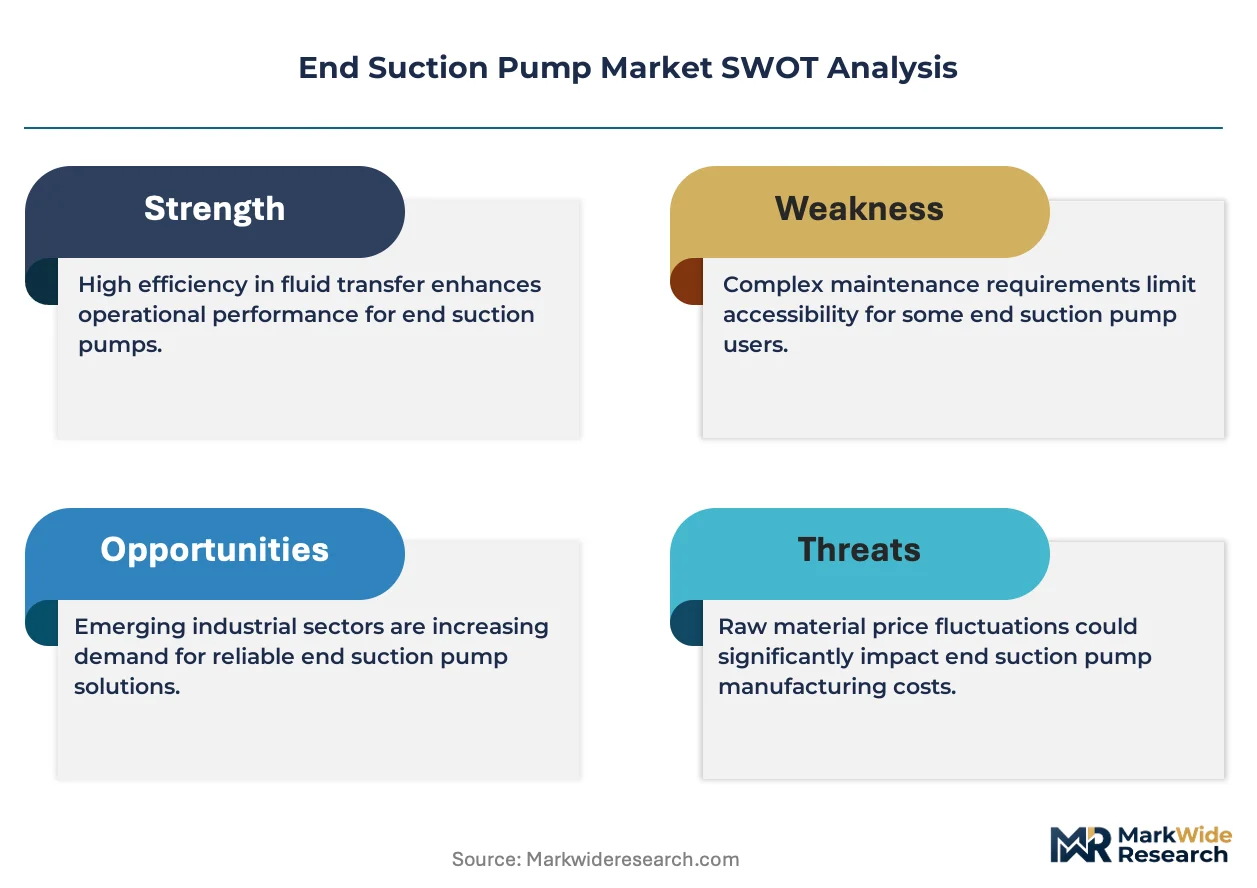
The EU Ecodesign Directive and ErP regulations mandate minimum efficiency index thresholds that OEMs must satisfy for market access, while EPA energy conservation standards in the United States parallel these requirements for clean water pumps used in commercial buildings. India's Bureau of Energy Efficiency has introduced star-rating labels for agricultural and industrial pumps that redirect procurement toward premium-efficiency models. Stakeholders must monitor how tightening efficiency regulations interact with raw material cost volatility to determine whether localized manufacturing or modular platform strategies offer more durable margin protection.
Market Dynamics
Energy efficiency mandates from the EU Ecodesign Directive and ErP regulations are compressing legacy pump architectures while accelerating premium-efficiency platform adoption across municipal and industrial procurement channels.
Growth Catalysts
- EU ErP Minimum Efficiency Index:Tiered performance thresholds force replacement of non-compliant installed bases in commercial building services and water treatment utilities across Germany, France, and Italy.
- Cast Iron Price Stabilization:Input cost normalization for pump housings and impellers enables OEMs to restore margin on mid-range centrifugal configurations after two years of volatility.
- Southeast Asian Municipal Infrastructure:Indonesian and Vietnamese water utilities are consolidating procurement specifications around single-stage end suction designs for distribution network rehabilitation.
Market Restraints
- Permanent Magnet Motor Cost Premium:Rare earth magnet supply concentration in China sustains 15-25% price gaps between IE4 and IE3 efficiency classes, constraining retrofit economics.
- Submersible Pump Substitution:Flooded-suction and borehole extraction applications in groundwater management increasingly specify submersible architectures that eliminate suction lift limitations.
- REACH Compliance Burden:European chemical registration requirements for bronze and nickel-aluminum bronze alloys extend qualification timelines for corrosion-resistant pump variants.
Strategic Opportunities
- India Bureau of Energy Efficiency Star Labels:Mandatory efficiency disclosure for agricultural and industrial pumps redirects public sector procurement toward premium-tier domestic manufacturers.
- Digital Twin Integration:Convergence of vibration sensing with cloud-based performance analytics creates recurring revenue attachment for pump OEMs in predictive maintenance contracts.
- Wastewater Lift Station Modernization:Urban flood protection priorities in Bangladesh and Philippines are specifying dry-pit end suction configurations with submersible motor options.
Industry Challenges
- Hydraulic Design Talent Scarcity:Specialized computational fluid dynamics expertise for impeller optimization concentrates at a handful of European and Japanese engineering centers.
- Legacy Control System Integration:Building management system retrofit projects demand analog-to-digital signal conversion hardware that complicates intelligent pump commissioning.
- Multi-Standard Certification Overlap:Simultaneous pursuit of ATEX, UL, and IECEx hazardous area approvals fragments testing budgets for chemical process pump variants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | End Suction Pump Market |
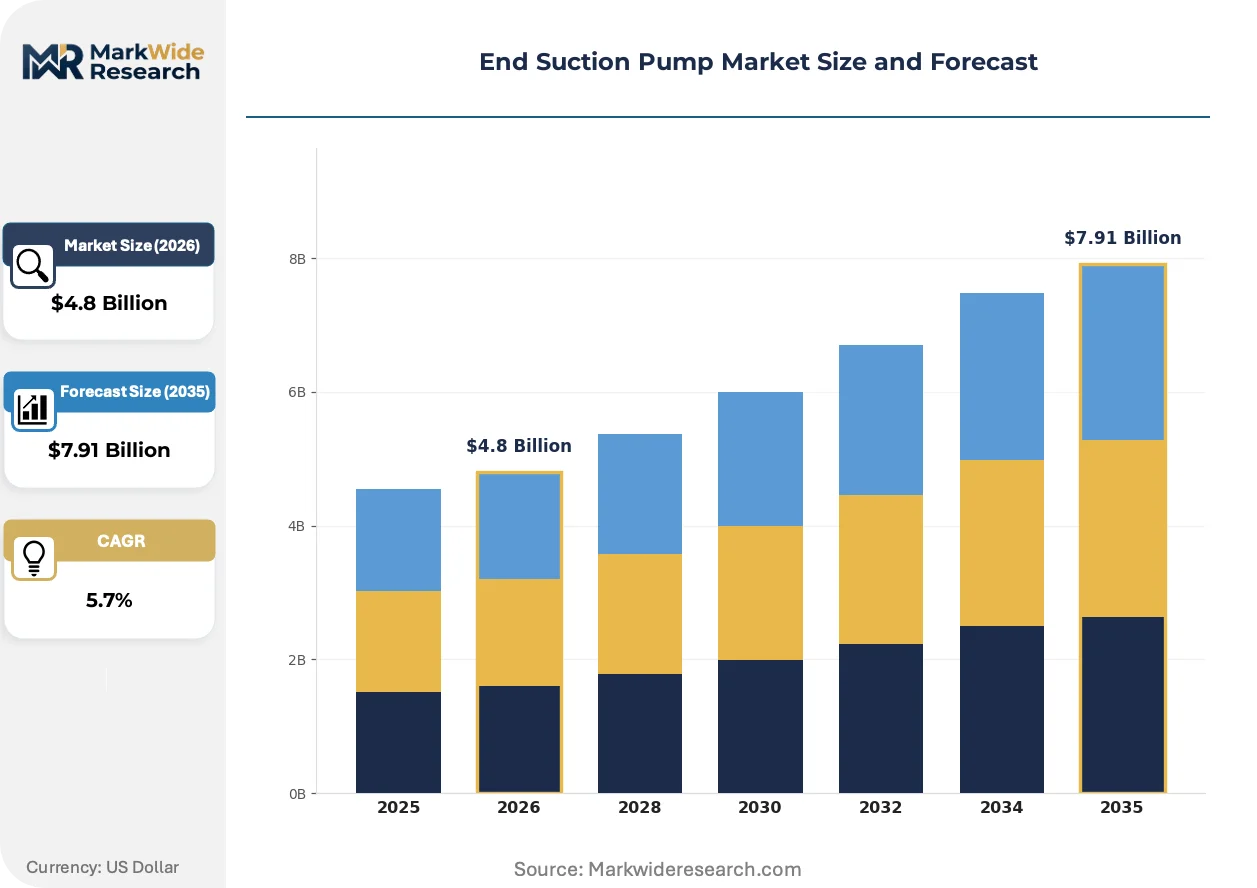
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Centrifugal Pumps, Submersible Pumps, Diaphragm Pumps, Magnetic Drive Pumps End User: Agriculture, Oil & Gas, Chemical Processing, Water Treatment Installation: Fixed Installation, Portable, Inline, Standalone Power Rating: Low Power, Medium Power, High Power, Variable Power |
| Companies Covered | Grundfos, Xylem, KSB, Sulzer, Ebara Corporation, Flowserve Corporation, Wilo, Kirloskar Brothers, Pentair, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
End Suction Pump Market Emerging Trajectories
Permanent magnet synchronous motor technology is compressing the efficiency-performance frontier while digital monitoring platforms reconfigure aftermarket value capture for pump OEMs.
Permanent magnet synchronous motor (PMSM) technology is electrifying the high-efficiency segment of the end suction pump market. Water treatment utilities in Denmark and the Netherlands are specifying PMSM-coupled configurations for variable-load distribution applications. The technology is electrifying demand for integrated variable frequency drive packages that eliminate mechanical throttling losses.
The EU F-Gas Regulation and parallel EPA SNAP program restrictions are phasing out high-global-warming-potential refrigerants in building HVAC systems that share pump infrastructure with chilled water circuits. Pump manufacturers serving commercial heating and cooling applications must now certify compatibility with lower-flammability A2L refrigerant alternatives. European OEMs are responding with expanded stainless steel casting capacity for mildly corrosive heat transfer fluid handling.
Performance-based service contracting is displacing traditional break-fix maintenance relationships in municipal water utilities. Danish and Singaporean operators are procuring guaranteed-availability agreements that transfer uptime risk to pump suppliers. This model concentrates most visibly in desalination pre-treatment and distribution booster station applications where unplanned downtime carries regulatory penalties.
End Suction Pump Market Segmentation
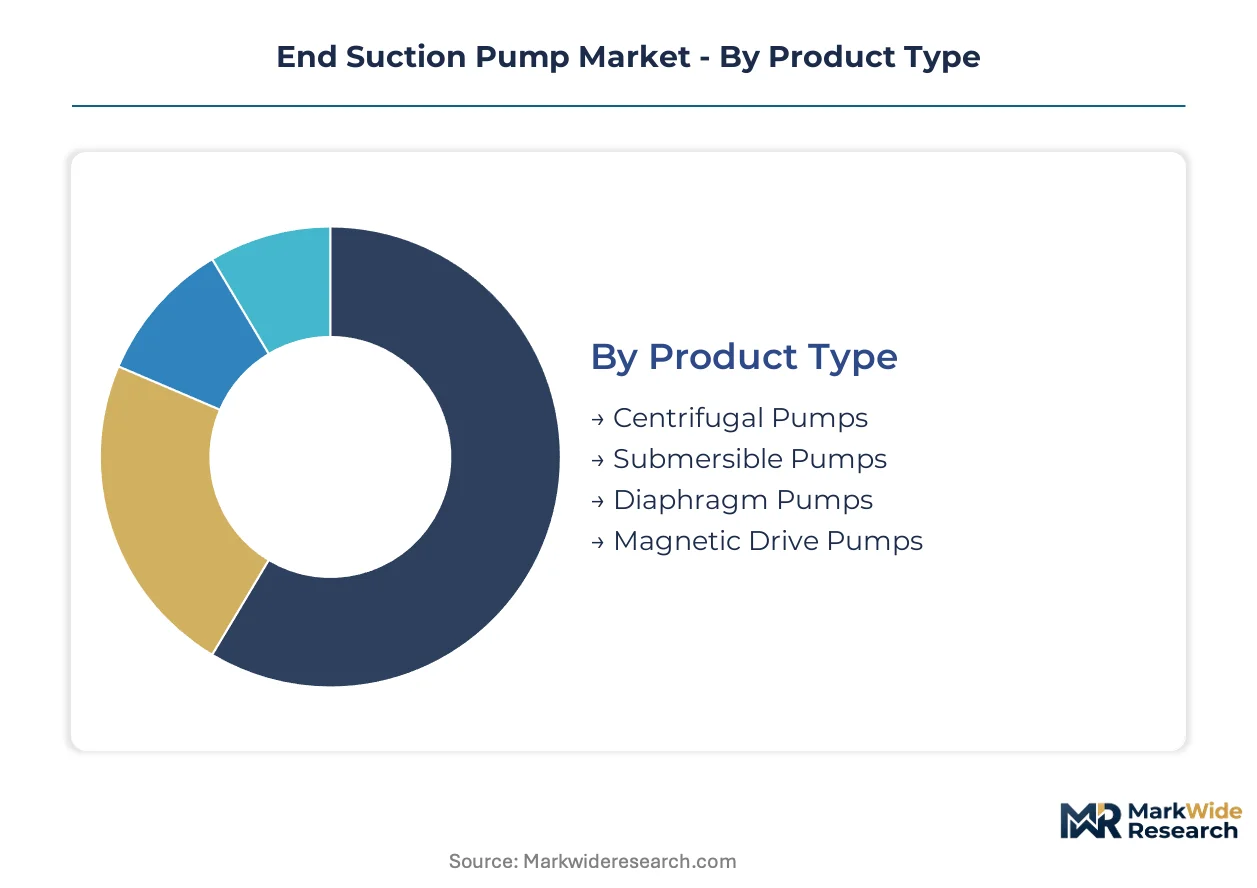
End suction pump procurement varies sharply by duty cycle and integration depth. Specification standards diverge across municipal infrastructure, chemical process plants, and agricultural distribution networks. Understanding segment boundaries clarifies where efficiency mandates reshape procurement versus where legacy architectures persist.
Product Type:
Standalone pump-motor assemblies dominate replacement demand, while embedded configurations in packaged water treatment skids concentrate new-build procurement.
- Centrifugal Pumps:Single-stage volute designs with radial or mixed-flow impellers handle clean water transfer across building services and municipal distribution. Danish and Dutch water utilities specify these for variable-load district cooling networks where IE4 motor pairings satisfy ErP minimum efficiency index thresholds.
- Submersible Pumps:Close-coupled motor-pump units operate fully immersed, eliminating suction lift constraints in borehole extraction and wastewater lift stations. Indonesian municipal utilities are consolidating procurement around these configurations for urban flood protection infrastructure in Jakarta and Surabaya.
- Diaphragm Pumps:Positive displacement mechanisms with elastomeric membranes handle viscous fluids and abrasive slurries in mining and construction dewatering.
- Magnetic Drive Pumps:Canned motor or magnetic coupling architectures deliver zero-leakage compliance for chemical transfer duties. Nickel-aluminum bronze and stainless steel casings address corrosive process fluids in European REACH-regulated chemical processing.
Centrifugal pumps lead volumes today; magnetic drive pumps are gaining share fastest.
End User:
Cost-tier stratification separates premium-efficiency municipal procurement from price-sensitive agricultural volume.
- Agriculture:Surface irrigation and groundwater extraction systems specify single-stage end suction pumps with cast iron housings. India's Bureau of Energy Efficiency star-rating labels redirect procurement toward premium-efficiency models in Gujarat and Maharashtra industrial corridors.
- Oil & Gas:Pipeline transfer and tank farm circulation duties demand API 610-compliant designs with heavy-duty bearing frames. Upstream operators in the Permian Basin specify these for crude oil gathering and refined product distribution.
- Chemical Processing:Corrosive fluid handling and high-temperature process streams require alloy-specific material selection. ATEX and IECEx hazardous area certifications fragment testing budgets for pump variants serving European and Asian petrochemical complexes.
- Water Treatment:Filtration backwash, chemical dosing, and distribution boosting constitute the largest addressable demand pool. Vietnamese water utilities are standardizing on end suction configurations for network rehabilitation in Hanoi and Ho Chi Minh City.
Water treatment leads volumes today; agriculture is expanding most quickly under efficiency-label redirection.
Installation:
Volume concentration favors fixed infrastructure, though portability commands margin premiums in temporary dewatering and emergency response.
- Fixed Installation:Permanent concrete pad or skid-mounted bases serve continuous-duty municipal and industrial applications. German and French commercial building codes mandate these configurations for HVAC chilled water circuits under F-Gas Regulation compliance timelines.
- Portable:Trailer or frame-mounted units with quick-connect suction and discharge enable construction site dewatering and flood response. Rental fleet operators in Bangladesh specify these for monsoon season deployment across Dhaka and Chittagong.
- Inline:Compact flange-to-flange designs integrate directly into piping systems with minimal footprint. These configurations serve space-constrained building services retrofits in Singaporean commercial developments.
- Standalone:Baseplate-mounted pump-motor assemblies with independent foundation requirements dominate industrial process applications. Philippine wastewater operators specify dry-pit standalone configurations with submersible motor options for urban lift station modernization.
Fixed installation leads volumes today; portable configurations show steepest expansion in climate adaptation infrastructure.
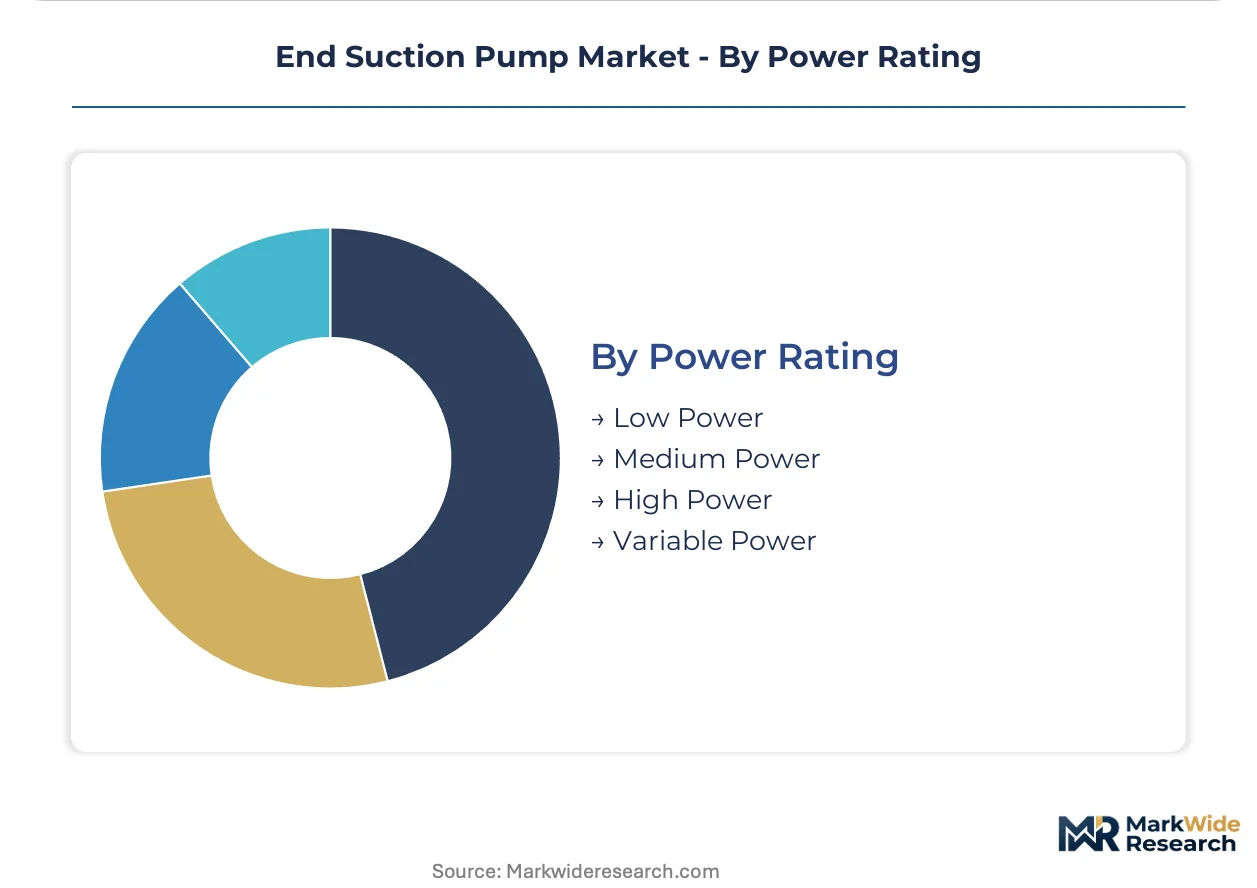
Power Rating:
Efficiency regulation tightens fastest at medium power bands where IE3 and IE4 motor upgrades deliver measurable energy savings.
- Low Power:Fractional horsepower units serve residential pressure boosting and small-scale agricultural transfer. Italian and Spanish residential building codes drive replacement demand under parallel EU Ecodesign Directive implementation.
- Medium Power:1-75 kW range covers the majority of municipal water distribution and commercial HVAC applications. EPA energy conservation standards for clean water pumps in US commercial buildings concentrate compliance investment in this band.
- High Power:Above 75 kW units serve large-scale desalination pre-treatment and industrial process cooling. Singaporean desalination operators procure guaranteed-availability service contracts transferring uptime risk to suppliers.
- Variable Power:Integrated variable frequency drive packages eliminate mechanical throttling losses across fluctuating demand profiles. Dutch water utilities specify these for distribution networks with diurnal flow variation.
Medium power leads volumes today; variable power configurations are climbing the fastest as digital monitoring platforms proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gujarat's industrial corridor anchors global demand concentration for end suction pumps, with municipal infrastructure upgrades and energy efficiency mandates reshaping procurement patterns across manufacturing clusters and water treatment networks.
United States
EPA energy conservation standards for clean water pumps in commercial buildings drive replacement cycles across HVAC and building services applications. The Department of Energy enforces minimum efficiency requirements that accelerate IE3 and IE4 motor adoption. Texas and California industrial corridors concentrate procurement for oilfield water transfer and desalination pre-treatment infrastructure.
Germany
EU Ecodesign Directive tiered thresholds force wholesale replacement of non-compliant pump installed bases in municipal water utilities and commercial heating systems. The Federal Environment Agency coordinates F-Gas Regulation compliance timelines affecting chilled water circuit specifications. The Ruhr industrial basin and Bavarian manufacturing zones anchor demand for premium-efficiency centrifugal configurations.
China
Rare earth magnet supply concentration sustains permanent magnet synchronous motor cost advantages for domestic pump manufacturers serving variable-load applications. The Ministry of Ecology and Environment enforces dual carbon goals that redirect municipal procurement toward high-efficiency models. Yangtze River Delta water treatment operators consolidate specifications around intelligent monitoring-integrated pump systems.
India
Bureau of Energy Efficiency star-rating labels redirect agricultural and industrial pump procurement toward premium-efficiency domestic manufacturers. The Central Electricity Authority coordinates with state distribution companies to enforce efficiency disclosure mandates. Maharashtra and Gujarat industrial corridors expand manufacturing capacity for export-oriented pump-motor assemblies.
Netherlands
Variable-load district cooling networks specify IE4 motor pairings to satisfy ErP minimum efficiency index thresholds in urban water distribution applications. The Human Environment and Transport Inspectorate enforces REACH compliance timelines for corrosion-resistant alloy pump variants. Rotterdam and Amsterdam municipal utilities pioneer performance-based service contracting with guaranteed-availability agreements.
End Suction Pump Market Vendor Landscape
Strategic partnerships dominate the current landscape as OEMs converge on digital monitoring platforms and predictive maintenance service models. The vendor base concentrates around three tiers: integrated multinational systems providers, regional manufacturing specialists with captive foundry capacity, and niche magnetic drive fabricators serving chemical process zero-leakage requirements. Technology licensing agreements and backward integration into permanent magnet motor production represent the two dominant competitive vectors reshaping margin structures.
Among European-based integrated providers, Grundfos and KSB exemplify the systems-tier archetype through captive digital platform development and continental manufacturing scale. Xylem occupies a position anchoring the North American premium segment through analytics-forward positioning. Kirloskar Brothers represents the emerging-market specialist archetype, leveraging domestic efficiency-label compliance to defend share in India's agricultural and industrial procurement channels.
| Leading Market Players |
|---|
| Grundfos |
| Xylem |
| KSB |
| Sulzer |
| Ebara Corporation |
| Flowserve Corporation |
| Wilo |
| Kirloskar Brothers |
| Pentair |
| Others |
Supply Flow & Price Mechanics
EU Ecodesign Directive tiered efficiency mandates are forcing municipal water utilities and commercial building operators to specify IE4 motor pairings and corrosion-resistant alloy variants, compelling foundries to expand stainless steel casting capacity and OEMs to absorb rare earth magnet cost premiums that compress margins on mid-range centrifugal configurations.
Pricing Analysis
Cast iron price normalization is restoring margin stability for pump housings and impellers after sustained volatility, though permanent magnet synchronous motor cost premiums sustain 15-25% gaps between IE4 and IE3 efficiency classes. Pricing stratifies across premium, standard, and economy tiers based on motor efficiency certification and after-sales service bundling. Cost compression in standard-tier cast iron configurations is intensifying because Indian and Southeast Asian procurement consolidation rewards volume scale. Agricultural distributors in Gujarat and Maharashtra exhibit highest price sensitivity, while Singaporean desalination operators accept premium positioning for guaranteed-availability contracts.
Supply Chain Analysis
Rare earth magnet supply rests on Chinese processing concentration that anchors permanent magnet motor cost structures for variable-load pump configurations. Pump manufacturing draws from German and Italian foundry capacity for stainless steel castings, Indian domestic production for cast iron housings, and Japanese precision machining for bearing assemblies. Single-source vulnerability in neodymium-dysprosium supply chains exposes OEMs to export restriction risk. Distribution runs through authorized dealer networks for municipal procurement and direct OEM relationships for large industrial accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion potential concentrates in premium-efficiency segments where IE4 motor adoption and digital monitoring service bundling shift procurement economics toward recurring revenue models, while cast iron input cost normalization restores profitability in mid-range replacement demand.
For Market Incumbents: Extend digital twin platform penetration into predictive maintenance contracts to lock in municipal water utility relationships before submersible pump substitution accelerates in groundwater extraction applications. Deepen backward integration into permanent magnet motor production to defend margin position against rare earth cost volatility. Prioritize REACH-compliant alloy qualification timelines to capture chemical processing zero-leakage demand in European petrochemical complexes. For New Entrants and Emerging Players: The 15-25% price gap between IE4 premium and IE3 standard motor pairings creates entry space for domestic Indian manufacturers leveraging Bureau of Energy Efficiency star-rating compliance to redirect agricultural procurement. Target portable dewatering configurations for Bangladesh and Philippines climate adaptation infrastructure where rental fleet operators consolidate specifications. Pursue channel partnerships with Southeast Asian municipal procurement consortia to bypass established OEM service networks. For Investors and Strategic Acquirers: Asymmetric upside sits with regional manufacturing specialists possessing captive foundry capacity and domestic efficiency-label compliance in high-growth procurement corridors. Long-term viability favors targets with demonstrated digital platform integration and performance-based service contracting capabilities. Watch for inflection where Indian state distribution companies accelerate enforcement of mandatory efficiency disclosure mandates.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Permanent Magnet Motors | Captive rare earth motor production insulates Grundfos and KSB from Chinese supply concentration risk. |
| Digital Twin Platform Deployment | Vibration sensing with cloud analytics creates recurring revenue attachment for Dutch and Singaporean utility contracts. |
| Stainless Steel Casting Capacity Expansion | European OEMs address F-Gas Regulation compliance timelines for mildly corrosive heat transfer fluid handling. |
| Performance-Based Service Contracting | Guaranteed-availability agreements transfer uptime risk to suppliers in Vietnamese desalination pre-treatment applications. |
| REACH-Compliant Alloy Qualification | Nickel-aluminum bronze certification unlocks European chemical processing zero-leakage procurement channels. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with municipal water utility procurement directors, plant engineers at chemical processing facilities, aftermarket service heads at pump OEMs, and distribution channel partners in Southeast Asian industrial corridors with secondary validation from EU Ecodesign Directive implementation reports, EPA energy conservation standard filings, Indian Bureau of Energy Efficiency star-rating databases, and customs trade data for pump-motor assembly imports. Bottom-up segment sizing and top-down macroeconomic anchoring were triangulated to ensure consistency.
Historical reference periods spanning efficiency regulation phase-in timelines anchored the projection horizon, with analytical frameworks modeling centrifugal, submersible, diaphragm, and magnetic drive product types alongside agriculture, oil and gas, chemical processing, and water treatment end-use segments. CAGRs were derived from segment-level demand elasticity analysis and regulatory compliance-driven replacement cycle assumptions. Forecast inputs incorporated permanent magnet motor cost trajectory scenarios and municipal infrastructure investment pipelines across Indonesian, Vietnamese, and Philippine water utilities.
Caveats apply where rare earth export restrictions, REACH compliance timeline extensions, or submersible pump technology substitution could materially shift the outlook. Forecasts reflect assumptions about efficiency mandate enforcement consistency and foundry capacity expansion schedules. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pumps and Control Devices
Single-Use Pump Market
Pumps and Control Devices
Jetting Pumps Market
Pumps and Control Devices
Vacuum Pump Stations Market
Pumps and Control Devices
Air-Operated Double Diaphragm (AODD) Pumps Market
Pumps and Control Devices
Electric Oil Pump Market
Pumps and Control Devices
Europe Positive Displacement Pumps Market
Pumps and Control Devices
Lubrication Pump Systems Market
Pumps and Control Devices
Condensate Pump Market
Pumps and Control Devices
Solar Pump Market
Pumps and Control Devices
Global Reciprocating Pumps Market
Pumps and Control Devices
Ultra High Pressure Water Pump Market
Pumps and Control Devices
Fluid Transfer System Market
Pumps and Control Devices
Oil and Gas Actuators Market
Pumps and Control Devices
Air Breathing Hose Market
Pumps and Control Devices
Subsea Pump System Market
Pumps and Control Devices
Dosing Pumps Market