
 Rental Industrial Pump Market | 2026-2036
Rental Industrial Pump Market Size, Share, and Industry Trends Forecast 2026-2036
Rental Industrial Pump Market Analytics
The capital-intensity divergence between fleet-scale incumbents and regional specialists is unwinding competitive dynamics in rental industrial pumps. United Rentals leverages its North American branch density to sustain same-day deployment capabilities across dewatering and fluid transfer contracts. Ashtead Group anchors European market presence through Sunbelt Rentals' infrastructure-focused fleet positioning. Xylem differentiates via technology leadership in smart pump monitoring and energy-efficient submersible systems.
Rental industrial pumps are temporary-use pumping systems, typically diesel or electrically driven, designed to move liquids at specified flow rates and head pressures for defined project durations rather than permanent installation. Their primary purpose is to provide flexible fluid management capacity for construction dewatering, municipal bypass operations, and industrial process support without capital expenditure. Centrifugal pumps dominate rental fleet composition due to versatility across head-pressure ranges, while submersible configurations are gaining share in confined-space dewatering applications where portability commands premium rates. Positive displacement pumps occupy specialized niches in high-viscosity fluid transfer and oilfield chemical injection where precise flow control justifies higher rental tariffs.
EPA Clean Water Act discharge limits and OSHA confined-space entry standards shape equipment specification requirements across US rental fleets, while EU F-Gas Regulation and CE machinery directives govern refrigerant-handling and safety compliance in European deployments. ISO 5199 centrifugal pump standards and API 674 positive displacement specifications define baseline performance certification that rental providers must maintain for oil & gas and water utility contracts. Stakeholders must monitor how emerging carbon-border adjustments and methane-emission tracking requirements reshape fleet replacement cycles and regional equipment sourcing decisions.
Market Dynamics
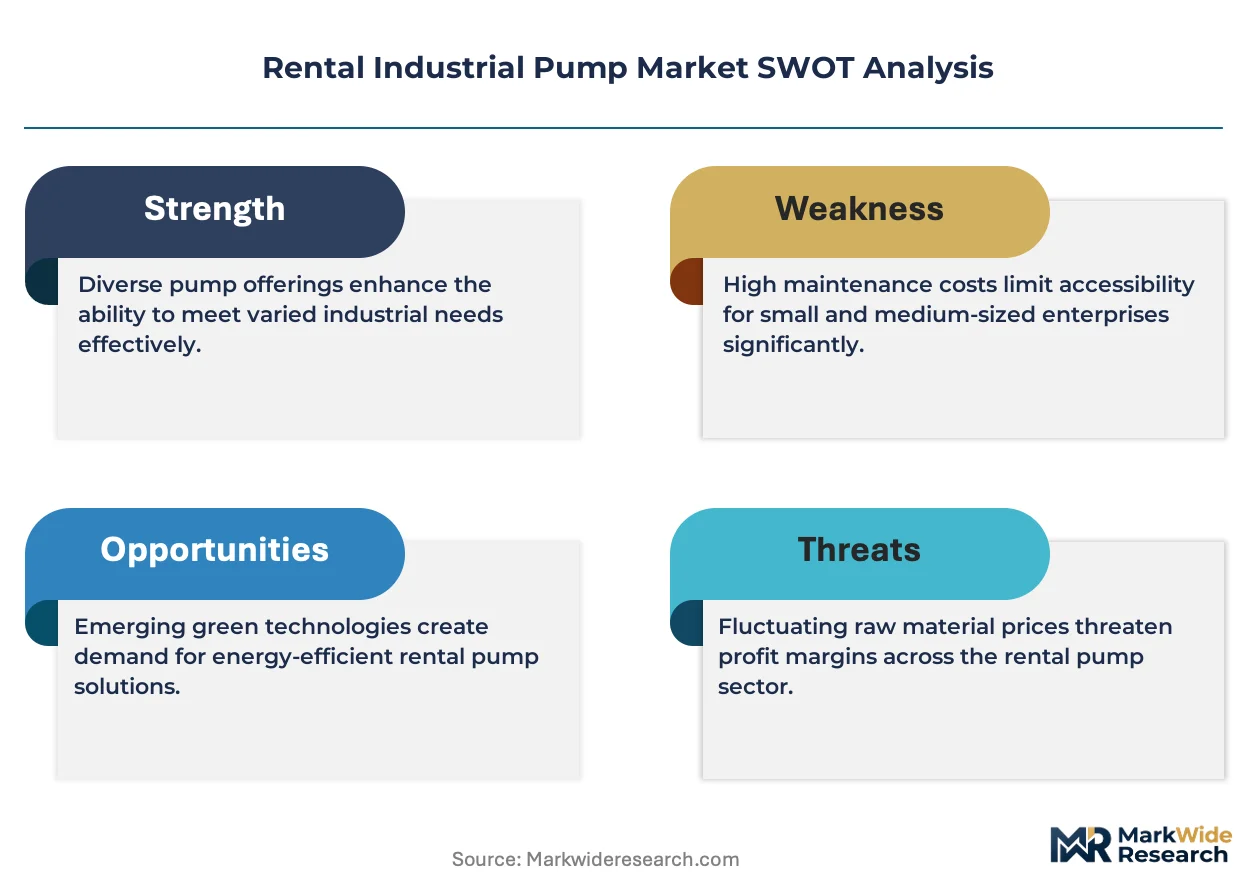
The Rental Industrial Pump Market operates under acute capital-efficiency pressure, where fleet owners must balance utilization rates against EPA discharge mandates and ISO vibration certification costs that escalate equipment replacement cycles.
Growth Catalysts
- Seasonal Peak Load Management:Water treatment utilities in the United States Gulf Coast petrochemical corridor expand rental commitments to handle turnaround maintenance cycles without permanent fleet investment.
- EPA Clean Water Act Enforcement:Tightening discharge limits under Section 402 NPDES permits force construction and municipal contractors toward certified rental equipment rather than aging owned assets.
- Smart Pump Telemetry:IoT-enabled condition monitoring systems reduce unplanned downtime for dewatering contractors, justifying premium rental rates across infrastructure bypass operations.
Market Restraints
- Diesel Engine Input Volatility:Tier 4 Final and Stage V emission compliance engines carry 25-40% higher capital costs per unit, compressing rental provider margins on standard dewatering fleets.
- Specialized Positive Displacement Supply Concentration:High-pressure chemical injection pump manufacturing concentrates among German and Italian OEMs, exposing rental operators to extended lead times and currency risk.
- Submersible Motor Technical Limitations:Conventional wound-rotor designs face depth and temperature constraints in deep-well dewatering applications, restricting addressable project scope.
Strategic Opportunities
- EU Green Deal Decarbonization Incentives:Battery-electric and hydrogen fuel cell pump systems qualify for CE marking fast-track and national subsidy programs across German and French infrastructure tenders.
- Digital Rental Platform Convergence:Equipment-as-a-service marketplaces integrating predictive maintenance APIs are capturing mid-market contractors previously served by traditional branch networks.
- Confined-Space Dewatering Specialization:Portable submersible configurations command rate premiums in mining and tunneling applications where OSHA 1910.146 compliance mandates redundant pumping capacity.
Industry Challenges
- Certified Technician Scarcity:EPA spill response certification and API 674 maintenance qualifications limit field service team scaling for multi-unit deployment contracts.
- Legacy Fleet Integration Complexity:Retrofitting older centrifugal pumps with smart monitoring hardware requires custom sensor mounting and calibration protocols that delay revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rental Industrial Pump Market |
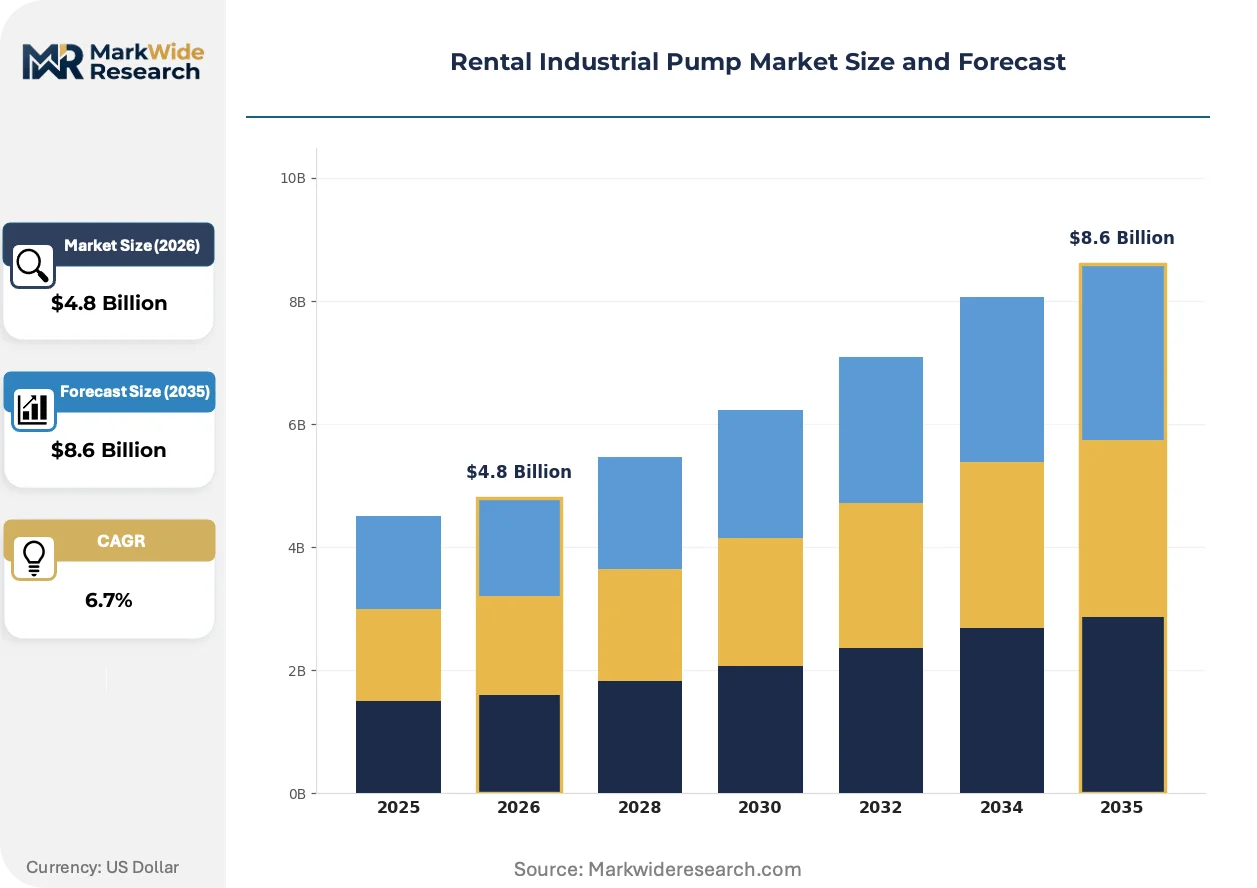
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Submersible Pumps, Centrifugal Pumps, Diaphragm Pumps, Positive Displacement Pumps End User: Construction, Oil & Gas, Water Treatment, Mining Application: Draining, Dewatering, Fluid Transfer, Pressure Boosting Distribution Channel: Direct Rental, Rental Agencies, Online Platforms, Equipment Dealers |
| Companies Covered | United Rentals, Ashtead Group, Xylem, Holland Pump, Thompson Pump, Integrated Pump Rental, Power Zone Equipment, Barco Pump, Global Pump, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rental Industrial Pump Market Evolving Landscape
Equipment intelligence and emission compliance are restructuring competitive advantage in rental industrial pumps. Fleet differentiation increasingly depends on real-time performance visibility and alternative powertrains rather than unit availability alone.
Permanent magnet synchronous motor (PMSM) submersible drive systems are supplanting conventional induction motors in high-duty dewatering applications. Mining contractors in Western Australia and Chilean copper operations specify PMSM-equipped rentals for 15-20% energy reduction. The technology is compressing total operating cost comparisons between owned and rented assets in 24/7 process applications.
EU F-Gas Regulation phase-down schedules are accelerating refrigerant-handling pump fleet turnover across European HVAC and industrial process rental providers. The 2024-2030 stepped reduction in hydrofluorocarbon availability forces rental operators to source compatible seal materials and lubricants for recovered refrigerant transfer. German rental fleets face the steepest compliance timeline, with January 2025 prohibitions on certain service gases already disrupting maintenance scheduling.
Performance-based contracting models now dominate municipal bypass and flood response tenders in the United Kingdom and Netherlands. Contractors pay per cubic meter moved rather than daily rates, transferring operational risk to rental providers who must guarantee uptime through telemetry-enabled preventive dispatch. This restructuring favors fleet owners with dense service networks and predictive maintenance capabilities over asset-heavy regional specialists.
Rental Industrial Pump Market Segmentation
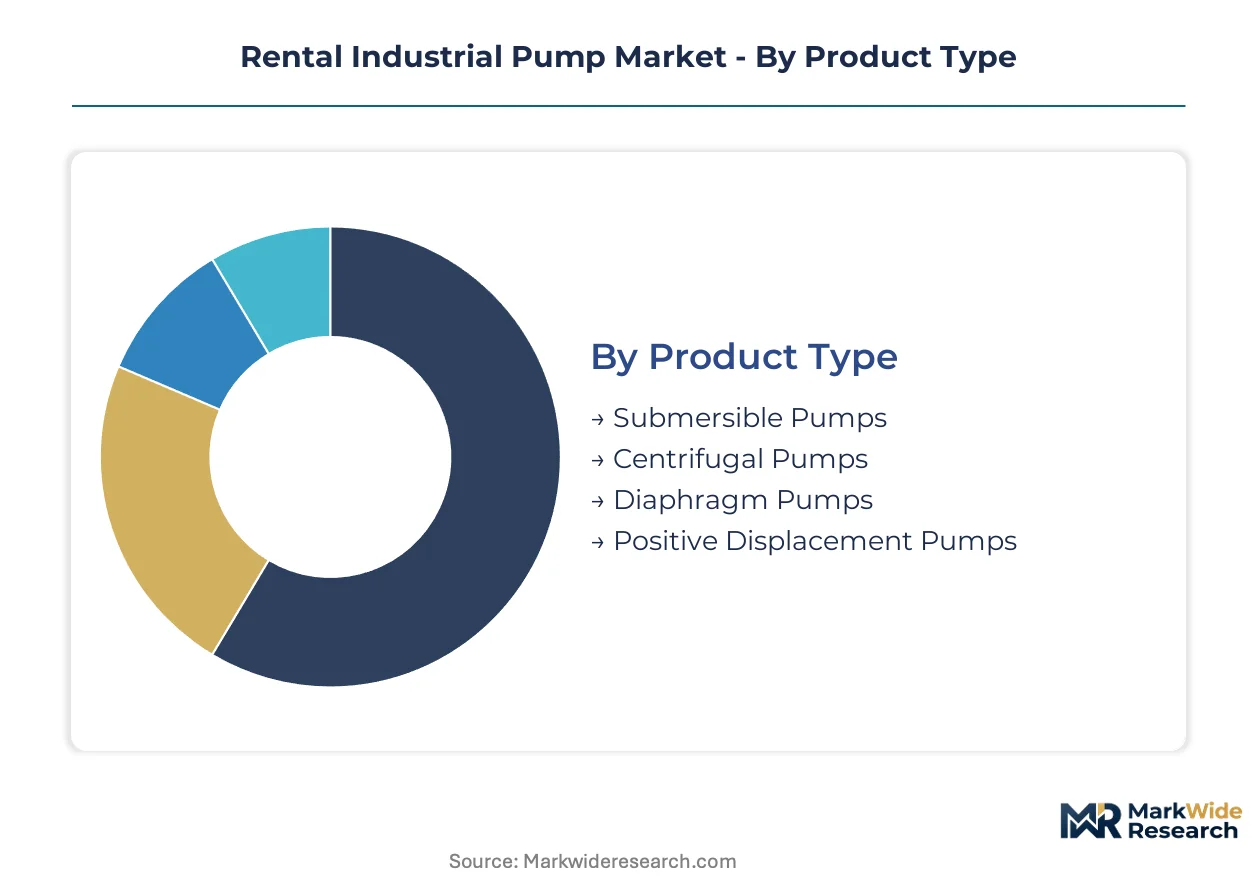
Rental pump fleet composition determines utilization economics and replacement cycles. Segment boundaries shift as submersible systems displace centrifugal units in confined-space applications and performance-based contracting restructures channel economics.
Product Type:
Substitution pressure from smart monitoring systems and alternative powertrains is reshaping equipment mix across rental fleets, with energy efficiency and emission compliance driving upgrade decisions.
- Centrifugal Pumps:Radial and mixed-flow impeller designs deliver variable head-pressure performance across construction dewatering and municipal bypass operations. United States Gulf Coast petrochemical corridor turnaround maintenance contracts specify ISO 5199-certified centrifugal rentals for fluid transfer reliability.
- Submersible Pumps:Sealed motor-housing configurations enable portable deployment in confined-space mining and tunneling applications where OSHA 1910.146 mandates redundant pumping capacity. Permanent magnet synchronous motor variants command rate premiums for 24/7 process duty.
- Diaphragm Pumps:Air-operated double-diaphragm systems handle abrasive slurries and high-viscosity fluids in chemical transfer applications.
- Positive Displacement Pumps:Reciprocating and rotary designs deliver precise flow control for oilfield chemical injection and refrigerant recovery under EU F-Gas Regulation compliance.
Centrifugal pumps retain volume leadership across standard dewatering fleets; submersible configurations hold the steepest expansion curve in mining and tunneling specialties.
End User:
Capital commitment avoidance patterns vary sharply across customer types, with utility seasonal peaks and industrial turnaround cycles generating contrasting rental duration profiles.
- Construction:General contractors deploy rental fleets for site dewatering and stormwater management under EPA NPDES permit compliance. Tier 4 Final engine specifications escalate equipment costs for diesel-driven units in US infrastructure projects.
- Oil & Gas:Downstream operators in the United States Gulf Coast petrochemical corridor rely on rental pumps for turnaround maintenance and process unit bypass during scheduled outages.
- Water Treatment:Municipal utilities expand rental commitments to manage seasonal peak loads without permanent fleet investment.
- Mining:Open-pit and underground operations specify submersible rentals for pit dewatering and shaft drainage in Western Australia and Chilean copper belts.
Construction commands the largest equipment days; oil and gas generates the highest revenue per rental day through specialized specification requirements.
Application:
Project scope definitions determine rate structures, with outcome-based cubic-meter pricing displacing daily rates in municipal and flood-response tenders.
- Dewatering:Groundwater control and excavation drainage applications dominate construction rental volumes, with smart telemetry enabling preventive dispatch guarantees.
- Draining:Stormwater and sump evacuation operations utilize portable centrifugal and submersible configurations for rapid deployment.
- Fluid Transfer:Process liquid movement between storage and treatment facilities requires certified equipment under EPA discharge mandates.
- Pressure Boosting:Temporary system augmentation for municipal distribution networks and industrial process lines.
Dewatering absorbs the greatest equipment hours; fluid transfer commands premium rates through certification and specification complexity.
Distribution Channel:
Digital platform convergence is capturing mid-market contractors previously served by traditional branch networks, restructuring channel economics.
- Direct Rental:Fleet owners deploy company-operated branches for same-day equipment availability and field service support.
- Rental Agencies:Independent brokers aggregate multi-brand fleets for regional contractors without national account status.
- Online Platforms:Equipment-as-a-service marketplaces integrate predictive maintenance APIs for contractor self-service procurement.
- Equipment Dealers:OEM-authorized distributors offer rental-as-a-pathway-to-purchase programs for capital-averse customers.
Direct rental retains share leadership in turnkey service contracts; online platforms are climbing fastest in mid-market contractor penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply by geography. United States operators prioritize same-day deployment density for petrochemical turnaround cycles, while European rental demand centers on emission-compliant fleet turnover under decarbonization mandates.
United States
Gulf Coast petrochemical corridor turnaround maintenance drives recurring rental volumes for ISO 5199-certified centrifugal systems. EPA Clean Water Act Section 402 NPDES permit enforcement pushes contractors toward certified rental equipment rather than aging owned assets. Houston and Beaumont industrial clusters concentrate demand for high-availability dewatering fleets during scheduled outage windows.
Germany
EU F-Gas Regulation phase-down schedules accelerate refrigerant-handling pump fleet replacement across HVAC and industrial process rental providers. CE machinery directives and national subsidy programs under EU Green Deal decarbonization incentives favor battery-electric system procurement. Rhine-Ruhr industrial basin rental operators face January 2025 service gas prohibitions disrupting maintenance scheduling.
United Kingdom
Performance-based contracting models now dominate municipal bypass and flood response tenders with per-cubic-meter pricing structures. Contractors transfer operational risk to rental providers who guarantee uptime through telemetry-enabled preventive dispatch. Thames Estuary and Humber region infrastructure projects specify smart-monitored submersible configurations for redundant pumping capacity.
Australia
Mining contractors in Western Australia specify permanent magnet synchronous motor submersible rentals for 24/7 pit dewatering operations. The technology compresses total operating cost comparisons between owned and rented assets in continuous process applications. Pilbara iron ore and Queensland coal basins drive demand for high-duty portable configurations.
Chile
Chilean copper belt open-pit and underground operations deploy submersible rentals for shaft drainage and excavation dewatering. Mining investment cycles concentrate equipment demand in Antofagasta and Atacama regions where water scarcity intensifies fluid management requirements. Rental providers compete on energy efficiency metrics as power costs escalate.
Rental Industrial Pump Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in rental industrial pump markets. Fleet-scale incumbents leverage branch density for same-day deployment capabilities, while regional specialists compete on application-specific technical service. Three archetypes dominate: integrated rental conglomerates with multi-equipment portfolios, pump-focused technical specialists with deep OEM relationships, and digital platform operators aggregating distributed fleet capacity. Competitive moves center on M&A for geographic density expansion and strategic partnerships for smart telemetry integration.
Within the integrated conglomerate tier, United Rentals and Ashtead Group exemplify scale-driven positioning through North American and European branch networks respectively. Xylem occupies a technology-leadership position representing the OEM-anchored specialist archetype with energy-efficient system differentiation. These three companies illustrate the structural divergence between asset-heavy rental operators and technology-integrated equipment providers competing for infrastructure and industrial process contracts.
| Leading Market Players |
|---|
| United Rentals |
| Ashtead Group |
| Xylem |
| Holland Pump |
| Thompson Pump |
| Integrated Pump Rental |
| Power Zone Equipment |
| Barco Pump |
| Global Pump |
| Others |
Value Network & Pricing Analysis
Permanent magnet synchronous motor substitution for conventional induction motors simultaneously compresses supply geography toward German and Japanese drive-system OEMs and compresses pricing economics through energy-efficiency guarantees that justify rate premiums.
Pricing Analysis
Preventive maintenance contracts and telemetry-enabled uptime guarantees drive lifetime value beyond base rental rates. Three-tier pricing structure across ISO 5199-certified premium, standard dewatering, and economy portable tiers reflects certification grade and smart-monitoring bundling. Pricing pressure stems from Tier 4 Final engine cost escalation compressing margins on diesel-driven fleets. Municipal utilities exhibit highest price sensitivity through competitive tender processes; mining contractors show lowest sensitivity where downtime costs dwarf rental premiums.
Supply Chain Analysis
Inventory lead times for high-pressure positive displacement pumps extend due to concentrated German and Italian OEM manufacturing. Pump manufacturing draws from China for cast housings, Germany for precision drives, and the United States for Tier 4 Final engines. Single-source vulnerability concentrates in specialized chemical-injection pump supply. Distribution runs through company-operated branch networks for same-day deployment, with digital platforms capturing mid-market contractor procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The rental industrial pump market functions as a service-attach opportunity where predictive maintenance subscriptions and telemetry-enabled uptime guarantees expand faster than base equipment rental revenue.
For Market Incumbents: Consolidate regional specialist acquisitions to deepen Gulf Coast petrochemical corridor density against digital platform encroachment. Prioritize backward integration into permanent magnet synchronous motor supply to secure energy-efficient fleet differentiation and compress replacement cycle costs.
For New Entrants and Emerging Players: Anchor in confined-space dewatering specialties where OSHA 1910.146 compliance mandates redundant pumping capacity and rate premiums persist. Target Western Australian mining contractors with PMSM-equipped submersible rentals through equipment-as-a-service marketplace positioning.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional pump specialists lacking smart telemetry integration. Long-term viability hinges on fleet digitization and emission-compliant turnover velocity. Monitor EU F-Gas Regulation enforcement intensity as fleet replacement inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Telemetry Platform Integration | IoT-enabled condition monitoring transfers operational risk to rental providers through uptime guarantees. |
| Alternative Powertrain Fleet Conversion | Battery-electric and hydrogen fuel cell systems qualify for EU Green Deal subsidy programs. |
| Regional Density Expansion | Gulf Coast branch concentration secures same-day deployment for petrochemical turnaround cycles. |
| Certification Investment | ISO 5199 and API 674 maintenance qualifications unlock oil and gas contract access. |
| Digital Marketplace Partnership | Equipment-as-a-service platforms capture mid-market contractors outside traditional networks. |
Research Methodology
Initial hypotheses were tested against primary input from fleet operations directors, municipal procurement managers, mining maintenance superintendents, and OEM technical sales leads and refined through secondary validation. Bottom-up equipment deployment data triangulated against top-down rental revenue estimates. Secondary sources included EPA NPDES permit filings, ISO certification registries, SEC equipment rental company disclosures, and EU F-Gas Regulation compliance databases.
Variance decomposition across product type, end-use vertical, powertrain technology, and regional regulatory cluster shaped the analytical framework. CAGRs derived from segment-level deployment trajectories and replacement cycle modeling. Forecast inputs incorporated petrochemical turnaround scheduling patterns and mining investment cycle phasing.
Material uncertainties — EPA enforcement intensity shifts, EU decarbonization subsidy revisions, and battery-electric pump technology maturation — sit outside the modeled envelope. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pumps and Control Devices
APAC Centrifugal Pumps Market
Pumps and Control Devices
Ion Pump Market
Pumps and Control Devices
Droplet Separator Market
Pumps and Control Devices
Global Smart Pumps Market
Pumps and Control Devices
Plate Heat Exchanger Market
Pumps and Control Devices
Plunger Pumps Market
Pumps and Control Devices
Subsea Pump System Market
Pumps and Control Devices
Liquid Dispensing Pump Market
Pumps and Control Devices
Asia Pacific Submersible Pump Market
Pumps and Control Devices
Electric Submersible Pump (ESP) in Oil and Gas Market
Pumps and Control Devices
Energy-Saving Canned Motor Pump Market
Pumps and Control Devices
Southeast Asia Submersible Pumps Market
Pumps and Control Devices
Sanitary Pumps Market
Pumps and Control Devices
Food and Beverages Industry Pumps Market
Pumps and Control Devices
Centrifugal Pump Market
Pumps and Control Devices
Asia Pacific Vacuum Pumps Market