
 Self-Priming Centrifugal Pump Market | 2026-2036
Self-Priming Centrifugal Pump Market Size, Share, and Industry Trends Forecast 2026-2036
Self-Priming Centrifugal Pump Market Analytics
Asset-light leasing and pump-as-a-service models is rewriting capital deployment across the competitive landscape. Sulzer Ltd. leverages its aftermarket service network to lock in long-term municipal contracts. KSB SE & Co. KGaA anchors European industrial demand through localized manufacturing footprints. Flowserve Corporation specializes in severe-duty configurations for chemical processing environments.
A self-priming centrifugal pump combines an air-handling volute with a recirculation chamber, enabling automatic evacuation of suction-line air without external priming assistance; typical units achieve suction lifts of 5–8 meters and handle solids up to 76 millimeters. The pump's primary purpose is to maintain uninterrupted fluid transfer in intermittent-duty or remotely supervised installations where manual priming is impractical. Single-stage pumps dominate volume in agricultural and firefighting applications due to lower first cost and simpler maintenance profiles. Multi-stage configurations command premium positioning in industrial process and high-head water treatment duties where efficiency thresholds justify capital intensity. Electric technology leads installed base across municipalities and manufacturing, though diesel retains share in mining and remote construction where grid access remains unreliable.
EPA effluent guidelines and OSHA process safety mandates in the United States shape product specifications for industrial end users, while REACH and Ecodesign Directive compliance in Europe filters market access for non-conforming suppliers. China's GB standards and MIIT energy-efficiency classifications impose parallel certification burdens on manufacturers targeting domestic infrastructure tenders. Stakeholders must monitor how fragmented national efficiency regimes fragment procurement standards and whether modular platform designs can absorb compliance cost without eroding margin pools.
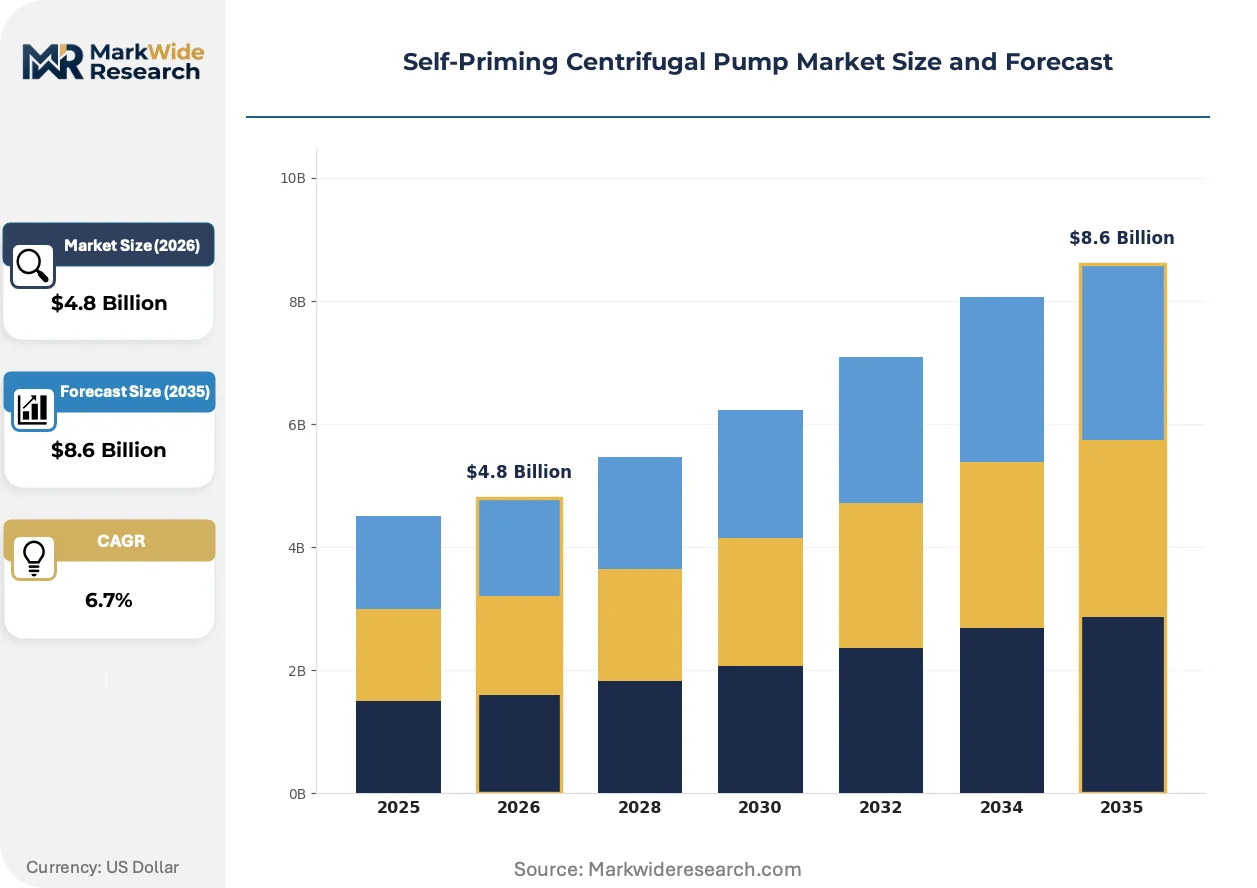
Market Dynamics
Asset-light leasing models are compressing capital deployment cycles across municipal and industrial procurement channels, forcing manufacturers to restructure revenue recognition around service attach rates rather than unit shipments.
Growth Catalysts
- EPA effluent standards:Industrial end users in the United States face mandatory replacement schedules for legacy pumping systems that fail new discharge thresholds, accelerating upgrade procurement.
- Solar irrigation clusters:India's agricultural heartland in Gujarat and Maharashtra is displacing diesel-powered alternatives with solar-electric self-priming units, driven by state-level subsidy frameworks.
- Peripheral volute redesigns:Advanced air-handling geometries now achieve 8-meter suction lifts without auxiliary priming tanks, opening remote installation applications previously requiring submersible configurations.
Market Restraints
- Cast iron price volatility:Foundry input costs for pump housings and impellers swing with scrap metal indices, compressing margin predictability for mid-tier manufacturers.
- Regional supply concentration:Precision-machined seal assemblies concentrate among German and Japanese specialist suppliers, creating single-source vulnerability for severe-duty configurations.
- Legacy infrastructure lock-in:Existing pipeline diameters and flange standards in mature water networks constrain specification flexibility for higher-efficiency pump geometries.
Strategic Opportunities
- Indonesian archipelago water security:Dispersed island municipalities lack grid reliability for conventional electric pumps, creating white space for hybrid solar-diesel self-priming units with integrated storage.
- EU Ecodesign Directive tier upgrades:Efficiency band reclassifications scheduled for implementation will disqualify current product lines from public tender eligibility, rewarding early redesign investment.
- Digital twin integration:Convergence of vibration sensors with cloud-based predictive analytics enables outcome-based maintenance contracts that capture lifetime value from installed bases.
Industry Challenges
- Multiphase flow simulation expertise:Computational fluid dynamics competency for air-liquid mixture modeling remains scarce among regional pump design teams, slowing product iteration cycles.
- Cross-border certification reciprocity:Divergent testing protocols between China's GB standards and EU CE marking requirements force redundant validation expenditures for platform designs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Self-Priming Centrifugal Pump Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Agriculture, Industrial Processes, Water Treatment, Firefighting Product Type: Multi-Stage Pumps, Single-Stage Pumps, Submersible Pumps, Portable Pumps End User: Manufacturing, Construction, Municipalities, Mining Technology: Electric, Diesel, Solar, Hydraulic |
| Companies Covered | Sulzer Ltd., KSB SE & Co. KGaA, Flowserve Corporation, Xylem Inc., Ebara Corporation, Grundfos Holding A/S, ITT Inc., Andritz AG, Gorman-Rupp Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Self-Priming Centrifugal Pump Market Evolving Landscape
Digital instrumentation and materials science are converging to redefine performance benchmarks and ownership economics across the installed base.
Composite impeller manufacturing is collapsing the weight-efficiency tradeoff that historically favored cast metal designs. Agricultural OEMs in Brazil and Australia are specifying glass-reinforced polymer impellers for portable irrigation sets, cutting field-handling labor by half while maintaining abrasion resistance against sandy intake water. The technology is collapsing service-interval expectations and expanding rental-fleet utilization rates.
REACH substance restrictions on perfluorinated seal compounds are forcing reformulation of mechanical face materials across European supply chains. Industrial process pump manufacturers must revalidate chemical compatibility databases and retrain field service protocols before 2026 enforcement deadlines. Chemical processing facilities in Germany's Ruhr cluster are front-loading procurement to secure grandfathered inventory positions.
Performance contracting is displacing capital purchase in municipal water authorities. Brazilian state water companies now specify guaranteed flow-rate uptime rather than equipment ownership, transferring operational risk to OEM service networks. The model concentrates most visibly in São Paulo's metropolitan sanitation district, where fifteen-year concession structures favor vendors with captive maintenance infrastructure.
Self-Priming Centrifugal Pump Market Segmentation
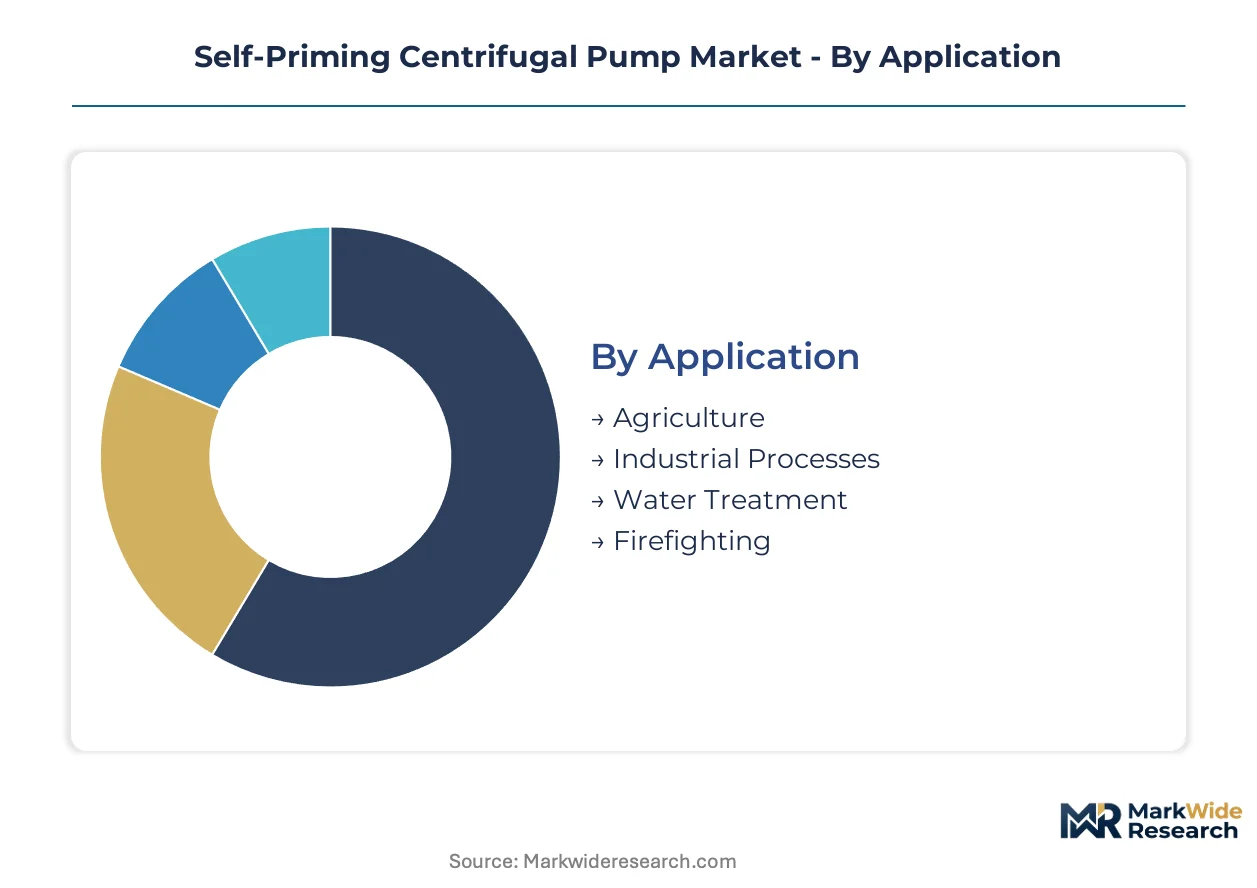
Segmentation in the self-priming centrifugal pump market reveals how application demands, product architectures, and power technologies fragment procurement patterns. Understanding these divisions exposes where margin pools concentrate and which configurations face substitution pressure.
Application:
Irrigation districts, chemical plants, municipal utilities, and emergency services each impose distinct duty cycles and reliability thresholds on pump specifications.
- Agriculture:Intermittent operation cycles and remote field locations favor units with automatic priming capability and tolerance for debris-laden surface water. Gujarat and Maharashtra state subsidy programs are accelerating solar-electric adoption in India's agricultural heartland, displacing diesel-powered alternatives.
- Industrial Processes:Continuous-duty chemical transfer and wastewater handling demand corrosion-resistant metallurgy and seal configurations rated for hazardous media. EPA effluent standards in the United States are forcing replacement schedules for legacy systems that fail new discharge thresholds.
- Water Treatment:Head pressure requirements and solids-handling capacity vary sharply between raw intake, clarifier recirculation, and final discharge stages.
- Firefighting:Rapid deployment protocols and suction lift capability under emergency conditions prioritize reliability over efficiency optimization.
Established volume favors Agriculture; emerging adoption favors Industrial Processes.
Product Type:
Architectural complexity separates capital-intensive multi-stage designs from portable units optimized for field mobility.
- Single-Stage Pumps:One impeller and simplified volute geometry deliver lower first cost and reduced maintenance overhead. These units dominate agricultural and firefighting procurement channels where capital constraints outweigh efficiency premiums.
- Multi-Stage Pumps:Series impeller arrangements generate high discharge pressures for industrial process and water treatment duties. Efficiency thresholds in these applications justify capital intensity through reduced lifecycle energy expenditure.
- Submersible Pumps:Motor-housing integration eliminates suction line air handling entirely, competing with self-priming designs in deep-well applications.
- Portable Pumps:Lightweight construction and quick-connect fittings serve rental fleets and emergency response inventories.
Single-Stage Pumps capture the highest shipment volumes; Multi-Stage Pumps command the steepest expansion trajectory in value terms.
End User:
Ownership models and procurement authority diverge sharply between public infrastructure authorities and private industrial operators.
- Municipalities:Water and sanitation authorities specify equipment through public tender processes with extended service contract attachments. Brazilian state water companies now structure fifteen-year concessions around guaranteed flow-rate uptime rather than equipment ownership.
- Manufacturing:Process industries integrate pumps into continuous production lines where unplanned downtime carries substantial revenue impact.
- Construction:Project-based demand cycles and temporary dewatering applications favor rental procurement over capital purchase.
- Mining:Remote site locations and unreliable grid access sustain diesel technology share despite emissions compliance burdens.
Municipalities anchor replacement demand; Manufacturing shows the fastest uptake of predictive maintenance instrumentation.
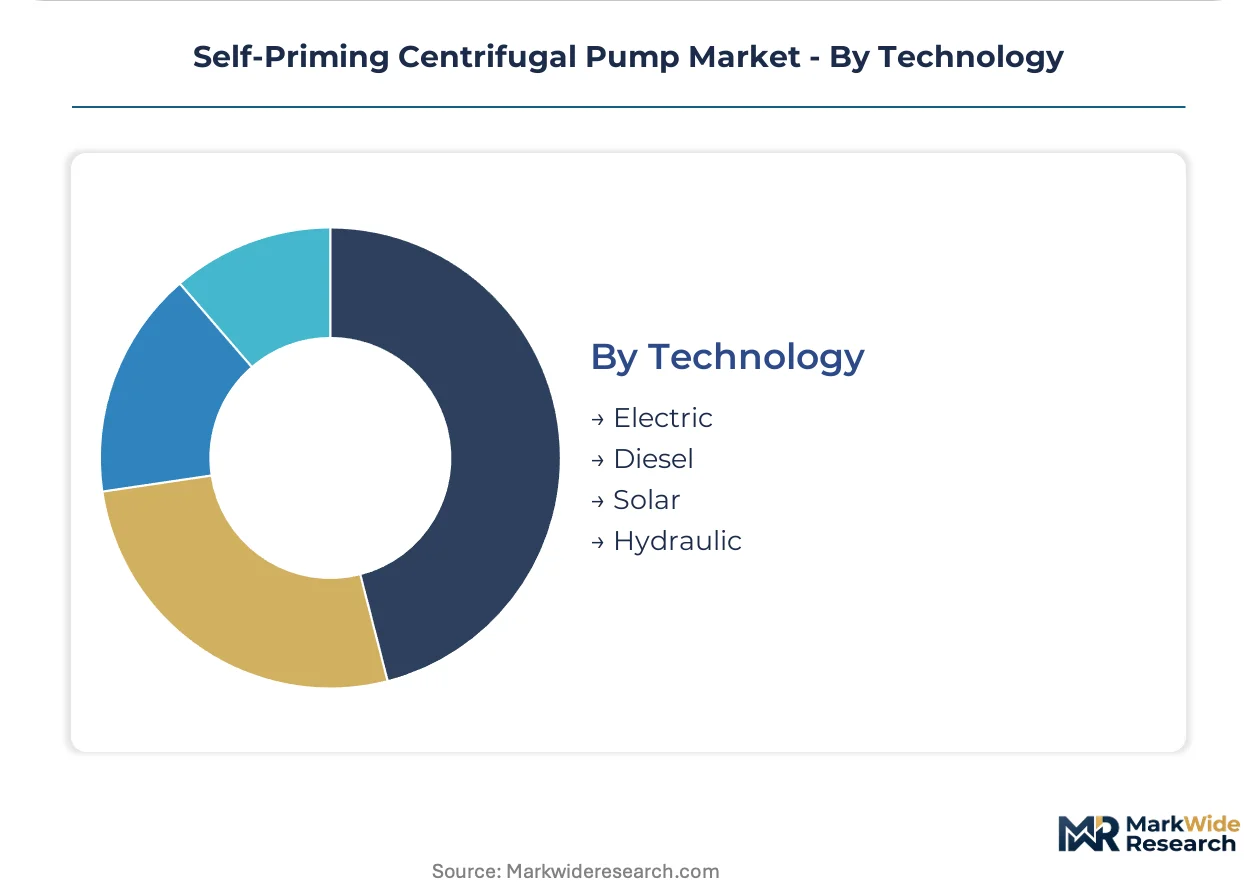
Technology:
Power source selection reflects grid availability, fuel logistics, and regulatory pressure on emissions profiles.
- Electric:Grid-connected motors dominate municipal and manufacturing installations where infrastructure reliability supports continuous operation. China's MIIT energy-efficiency classifications and the EU Ecodesign Directive impose parallel certification requirements on suppliers targeting public tenders.
- Solar:Photovoltaic arrays with battery storage enable off-grid irrigation in dispersed agricultural regions. Indonesian archipelago municipalities lacking grid reliability represent white space for hybrid solar-diesel configurations.
- Diesel:Internal combustion engines retain share in mining and remote construction where electrification remains uneconomical.
- Hydraulic:Power-take-off drives from mobile equipment serve specialized construction and emergency applications.
Electric technology holds the installed base majority; Solar is climbing the fastest among new installations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
State-level subsidy programs and federal emissions mandates are redirecting procurement patterns toward electrified and solar-hybrid configurations. Infrastructure vulnerability in dispersed geographies sustains demand for self-priming architectures that eliminate auxiliary priming equipment. Municipal tender processes increasingly attach long-term service obligations to equipment awards.
United States
Industrial facility retrofits dominate volume as EPA effluent guidelines force replacement schedules for legacy wastewater pumping systems. OSHA process safety mandates shape seal specifications and metallurgical requirements for chemical transfer duties. The Gulf Coast petrochemical corridor concentrates severe-duty procurement, with Texas and Louisiana refineries upgrading corrosion-resistant pump fleets.
Germany
REACH substance restrictions on perfluorinated seal compounds are accelerating mechanical face material reformulation ahead of 2026 enforcement deadlines. The EU Ecodesign Directive's efficiency tier upgrades will disqualify current product lines from public tender eligibility, rewarding early redesign investment. The Ruhr industrial cluster is front-loading procurement to secure grandfathered inventory positions before regulatory deadlines bite.
India
Gujarat and Maharashtra state subsidy frameworks are displacing diesel-powered alternatives with solar-electric self-priming units across agricultural heartland regions. The Ministry of New and Renewable Energy's off-grid solar pump programs are compressing payback periods for smallholder irrigation investments. Tamil Nadu's industrial pump manufacturing belt is expanding capacity to serve domestic replacement cycles and Southeast Asian export demand.
Indonesia
Dispersed island municipalities lacking grid reliability are creating white space for hybrid solar-diesel self-priming units with integrated battery storage. The national water security program is channeling infrastructure investment toward archipelago communities previously dependent on manual water distribution. Java's manufacturing corridor is emerging as a regional assembly hub for Southeast Asian pump exports.
Brazil
Performance contracting is displacing capital purchase in state water companies, with São Paulo's metropolitan sanitation district structuring fifteen-year concessions around guaranteed flow-rate uptime rather than equipment ownership. ANVISA certification requirements for potable water contact materials are filtering supplier eligibility for municipal tenders. The agricultural machinery rental market in Mato Grosso is absorbing portable self-priming units for seasonal irrigation deployment.
Self-Priming Centrifugal Pump Market Competitive Landscape
Channel-controlling players compete with product-specialist players across municipal, industrial, and agricultural procurement channels. The vendor base organizes into three recognizable tiers: integrated pump-system houses with captive service networks, component-focused specialists with severe-duty expertise, and regional fabricators serving price-sensitive replacement demand. Consolidation pressure concentrates among mid-tier manufacturers as attach-rate economics favor players with installed-base visibility. Competitive moves center on aftermarket service contract capture and localized manufacturing footprint expansion to satisfy domestic content requirements in public tenders.
Among European-integrated system houses, Sulzer Ltd., KSB SE & Co. KGaA, and Flowserve Corporation occupy positions that exemplify divergent strategic archetypes. Sulzer anchors municipal service-contract concentration through aftermarket infrastructure. KSB represents the localized-manufacturing approach with footprint-driven compliance advantages. Flowserve exemplifies severe-duty specialization for chemical process environments where metallurgical expertise commands premium positioning.
| Leading Market Players |
|---|
| Sulzer Ltd. |
| KSB SE & Co. KGaA |
| Flowserve Corporation |
| Xylem Inc. |
| Ebara Corporation |
| Grundfos Holding A/S |
| ITT Inc. |
| Andritz AG |
| Gorman-Rupp Company |
| Others |
Value Network & Pricing Analysis
The Shanghai-Rotterdam maritime corridor's container rate volatility transmits directly into landed cost spreads for cast iron pump housings, compressing margin pools for mid-tier European fabricators while amplifying price differentiation between CE-certified system houses and uncertified regional suppliers.
Pricing Analysis
Certification level (CE/ISO-grade versus uncertified) creates the primary spread between premium system integrators and commodity assemblers. Three-tier pricing structure across premium, standard, and economy levels reflects bundling intensity of aftermarket service contracts. Cost compression in the economy tier is intensifying because foundry scrap metal indices swing unpredictably. Municipal procurement officers show lowest price sensitivity due to total-cost-of-ownership mandates, while agricultural cooperatives in India's Gujarat belt negotiate hardest on unit economics.
Supply Chain Analysis
Extended payment terms from 90 to 120 days now dominate supplier-finance negotiations between German seal specialists and Italian pump assemblers. Precision-machined mechanical seal assemblies concentrate in Germany and Japan, while cast iron foundries cluster in China and India. Single-source vulnerability for severe-duty fluoropolymer face materials rests on REACH-compliant European compounders. Distribution runs through authorized dealer networks for municipal tenders and rental-fleet operators for portable agricultural units.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Municipal water authority consolidation across Brazil's state-level sanitation companies is shifting procurement leverage toward buyers with fifteen-year concession structures, fragmenting vendor pricing power.
For Market Incumbents: Entrench aftermarket service infrastructure to lock in municipal contract renewals against solar-electric entrants from India's pump manufacturing belt. Deepen backward integration into precision seal manufacturing to offset single-source exposure from German and Japanese suppliers. Prioritize EU Ecodesign Directive pre-certification to capture grandfathered procurement windows before efficiency tier upgrades disqualify legacy product lines. For New Entrants and Emerging Players: Build out hybrid solar-diesel configurations for Indonesia's archipelago municipalities where grid reliability gaps persist. Target agricultural irrigation districts in Maharashtra and Gujarat with state-subsidized solar pump programs as the most penetrable entry segment. Pursue rental-fleet partnerships with Brazilian agricultural machinery cooperatives to bypass capital-purchase procurement barriers. For Investors and Strategic Acquirers: Regional fabricators with captive foundry capacity and MIIT certification for China's infrastructure tenders represent the most defensible acquisition profile. Long-term viability hinges on installed-base visibility enabling outcome-based maintenance contracts. Watch for Indonesian national water security program tender announcements as inflection indicators for hybrid technology demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Seal Manufacturing | Captive supply of REACH-compliant fluoropolymer faces eliminates single-source vulnerability from German compounders. |
| EU Ecodesign Pre-Certification Investment | Early redesign investment secures grandfathered tender eligibility before efficiency tier upgrades bite. |
| Hybrid Solar-Diesel Platform Development | Integrated battery storage configurations unlock Indonesia's archipelago water security white space. |
| Performance Contracting Model Deployment | Fifteen-year São Paulo concession structures transfer operational risk from municipal buyers to OEM service networks. |
| Digital Twin Integration with Predictive Analytics | Vibration sensor convergence enables outcome-based maintenance capturing lifetime value from installed bases. |
Research Methodology
Operator-level perspectives from municipal maintenance directors, plant engineers at chemical processing facilities, aftermarket service heads at integrated pump houses, and procurement leads at Brazilian state water companies anchored the qualitative base. Secondary validation drew from EPA effluent guideline filings, EU Ecodesign Directive implementation notices, India's Ministry of New and Renewable Energy subsidy disbursement records, and customs trade data for cast iron pump component flows. Bottom-up shipment estimates triangulated against top-down infrastructure investment forecasts across the analysis window.
Scenario-bracketing around regulatory implementation timelines and commodity input cost bands shaped the projection horizon. Segmentation dimensions spanned product architecture, power technology, application duty cycle, and regional certification cluster. CAGRs derived from fitted growth curves applied to validated baseline volumes, with specific weighting for solar-electric adoption rates in subsidized agricultural districts and EPA-mandated replacement schedules in U.S. industrial wastewater systems.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese foundry-integrated assemblers or accelerated REACH enforcement timelines would shift outcomes. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pumps and Control Devices
Heating Tape Market
Pumps and Control Devices
Chemical Injection Pump Market
Pumps and Control Devices
Europe Asia Submerged Pump Market
Pumps and Control Devices
Axial Piston Pumps Market
Pumps and Control Devices
Volute Pump Market
Pumps and Control Devices
North America Dispensing Pumps Market
Pumps and Control Devices
North America Axial Flow Pump Market
Pumps and Control Devices
Digital Pump Market
Pumps and Control Devices
Paint Pump Market
Pumps and Control Devices
Fine Bubble Diffusers Market
Pumps and Control Devices
Global Hydraulic Metering Pump Market
Pumps and Control Devices
Middle East and Africa Centrifugal Pumps Market
Pumps and Control Devices
Hydrogen Circulation Pump Market
Pumps and Control Devices
Liquid Dispensing Pump Market
Pumps and Control Devices
Radial Split Pump Market
Pumps and Control Devices
Seawater Pump Market