
 Sealless Magnetic Drive Pump Market | 2026-2036
Sealless Magnetic Drive Pump Market Size, Share, and Industry Trends Forecast 2026-2036
Sealless Magnetic Drive Pump Market Analytics
Chemical processing demand is shifting toward zero-emission fluid handling systems as refineries and specialty chemical plants tighten leak prevention protocols. Flowserve Corporation leverages its aftermarket service network to sustain long-term contracts with North American petrochemical operators. KSB SE & Co. KGaA anchors European demand through localized manufacturing and CE-certified product lines. Iwaki Co., Ltd. dominates Asia-Pacific supply chains with corrosion-resistant alloy configurations tailored to aggressive chemical media.
A sealless magnetic drive pump transfers rotational energy through a containment shell via magnetic coupling, eliminating mechanical shaft seals and achieving leak-free operation typically below 0.1% volumetric loss. Permanent magnet and electromagnetic technologies generate the torque field, while Hastelloy or titanium containment shells withstand pressures exceeding 100 bar in corrosive process streams. Chemical pumps command the deepest specification requirements and highest replacement value pools across the product type spectrum. Water treatment applications are expanding fastest among end-use sectors as desalination and wastewater reuse projects multiply in water-stressed regions. Manufacturing facilities represent the most fragmented yet volume-heavy end user category, with pharmaceutical companies offering concentrated premium pricing for validated hygienic designs.
EPA emissions standards and OSHA process safety management rules in the United States compel facilities handling volatile organic compounds to adopt sealless architectures or face escalating compliance penalties. The EU REACH regulation and F-Gas Directive together restrict hazardous leakage pathways, effectively mandating magnetic drive adoption for fluorinated chemical transfer across member states. Stakeholders must monitor evolving containment shell material certifications and magnetic coupling efficiency benchmarks as these technical parameters increasingly determine competitive qualification for large-scale industrial tenders.
Market Dynamics
Zero-emission mandates across chemical processing corridors are forcing wholesale replacement of mechanical seal pumps with magnetic drive architectures, compressing replacement cycles and elevating containment shell specifications as primary competitive differentiators.
Growth Catalysts
- REACH and F-Gas Regulation in the EU:The ECHA's chemical safety framework and the EU F-Gas Directive together prohibit leakage-prone equipment in fluorinated chemical transfer, mandating sealless architectures for compliance.
- Hastelloy C-276 containment shells:Corrosion-resistant alloy configurations now withstand process streams exceeding 100 bar pressure, opening aggressive chemical applications previously blocked by material limitations.
- China's petrochemical corridor:State-owned refineries in Shandong and Jiangsu provinces are retrofitting aging infrastructure, generating concentrated demand for ANSI/ASME-compliant magnetic drive units.
Market Restraints
- Neodymium permanent magnet cost volatility:Rare earth supply concentration in Chinese processing facilities creates input price instability that compresses manufacturer margins.
- Containment shell thickness limitations:Eddy current losses in metallic barrier cans impose hard efficiency penalties above 50 kW duty ratings, restricting addressable power segments.
- Electromagnetic coupling alternatives:Advanced canned motor pumps compete for zero-leakage applications in nuclear and cryogenic service, fragmenting technology selection.
Strategic Opportunities
- Desalination expansion in the Middle East:Saudi Arabia and UAE utility scale projects require corrosion-resistant brine circulation pumps, opening new volume channels beyond chemical processing.
- Pharmaceutical hygienic validation:FDA-compliant 3A sanitary standards for biologics manufacturing create premium pricing tiers for electropolished 316L stainless configurations.
- SAMR green equipment catalog:China's State Administration for Market Regulation inclusion of sealless pumps in preferred procurement lists accelerates domestic substitution.
Industry Challenges
- Magnetic coupling assembly precision:Sub-millimeter air gap tolerances between inner and outer magnet assemblies require specialized technicians scarce in emerging manufacturing bases.
- CE-PED module H certification timelines:European Pressure Equipment Directive conformity assessment for high-pressure containment shells extends qualification cycles by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sealless Magnetic Drive Pump Market |
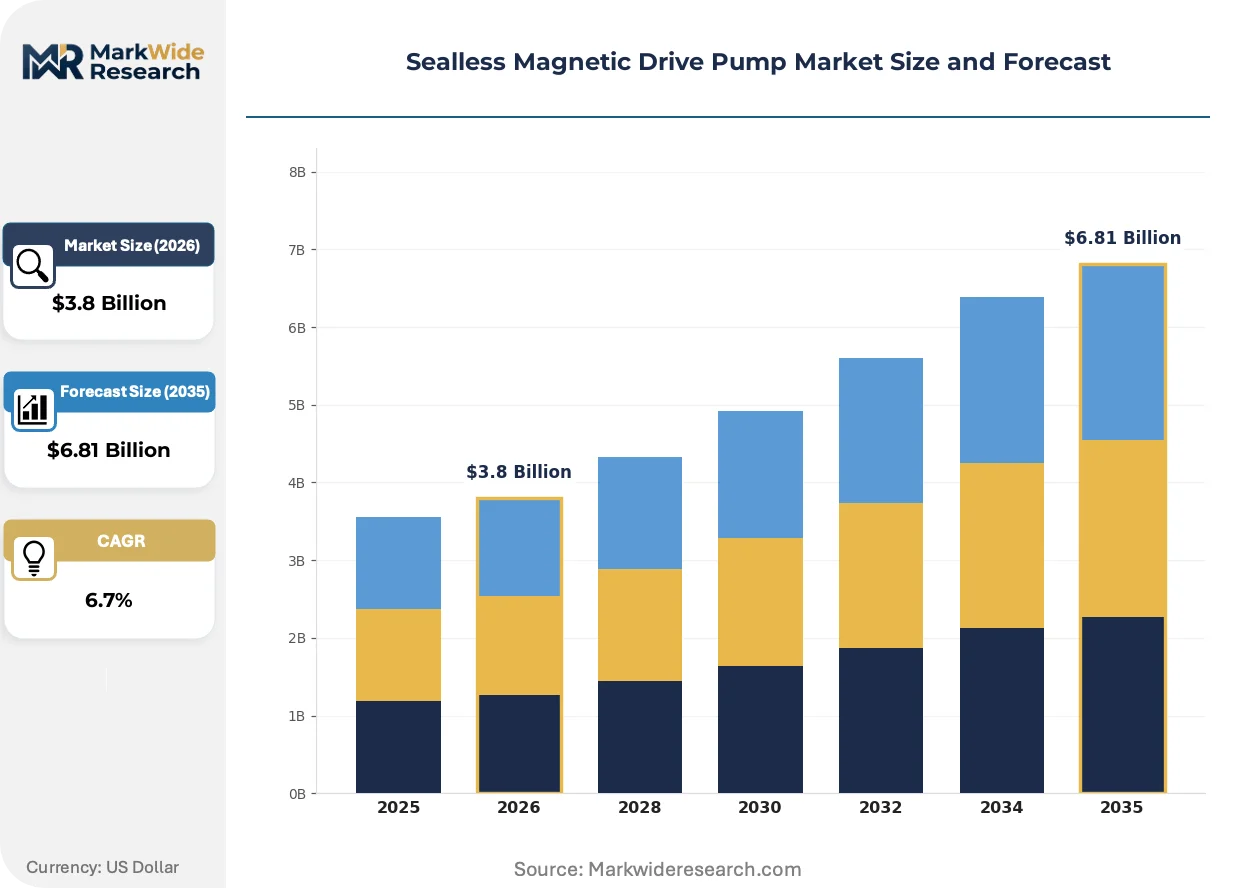
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chemical Pumps, Water Pumps, Oil Pumps, Food Processing Pumps Application: Water Treatment, Chemical Processing, Oil & Gas, Food & Beverage End User: Manufacturing Facilities, Oil Refineries, Hospitals, Pharmaceutical Companies Technology: Electromagnetic, Permanent Magnet, Inductive Coupling, Hydraulic Drive |
| Companies Covered | IDEX Corporation, HMD Kontro, Flowserve Corporation, ITT Goulds Pumps, Iwaki Co., Ltd., KSB SE & Co. KGaA, Wilo SE, Klaus Union, Sundyne Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sealless Magnetic Drive Pump Market Evolving Landscape
Permanent magnet material science and digital monitoring integration are compressing the performance gap between sealless and conventional sealed pumps while elevating lifecycle service expectations.
Samarium-cobalt magnet arrays are consolidating torque transmission efficiency in high-temperature process streams above 300°C. Refinery operators in Texas and Rotterdam are specifying SmCo configurations for hot oil circulation. This material shift is consolidating supplier qualification around magnet traceability and thermal demagnetization protocols.
The EPA's updated National Emission Standards for Hazardous Air Pollutants (NESHAP) for petroleum refineries now explicitly credit sealless pump deployment in leak detection and repair compliance calculations. Facilities handling benzene, butadiene, and other HAPs must demonstrate 95% reduction in fugitive emissions. Chemical pump OEMs are responding with pre-certified package submissions to expedite environmental permitting.
Aftermarket service unbundling is fragmenting traditional OEM-captive maintenance relationships. Third-party pump service specialists in the US Gulf Coast and German Ruhr region now stock standardized containment shell inventories and perform field magnet re-magnetization. This channel shift is most advanced in water treatment utilities where budget constraints override brand loyalty in spare parts procurement.
Sealless Magnetic Drive Pump Market Segmentation
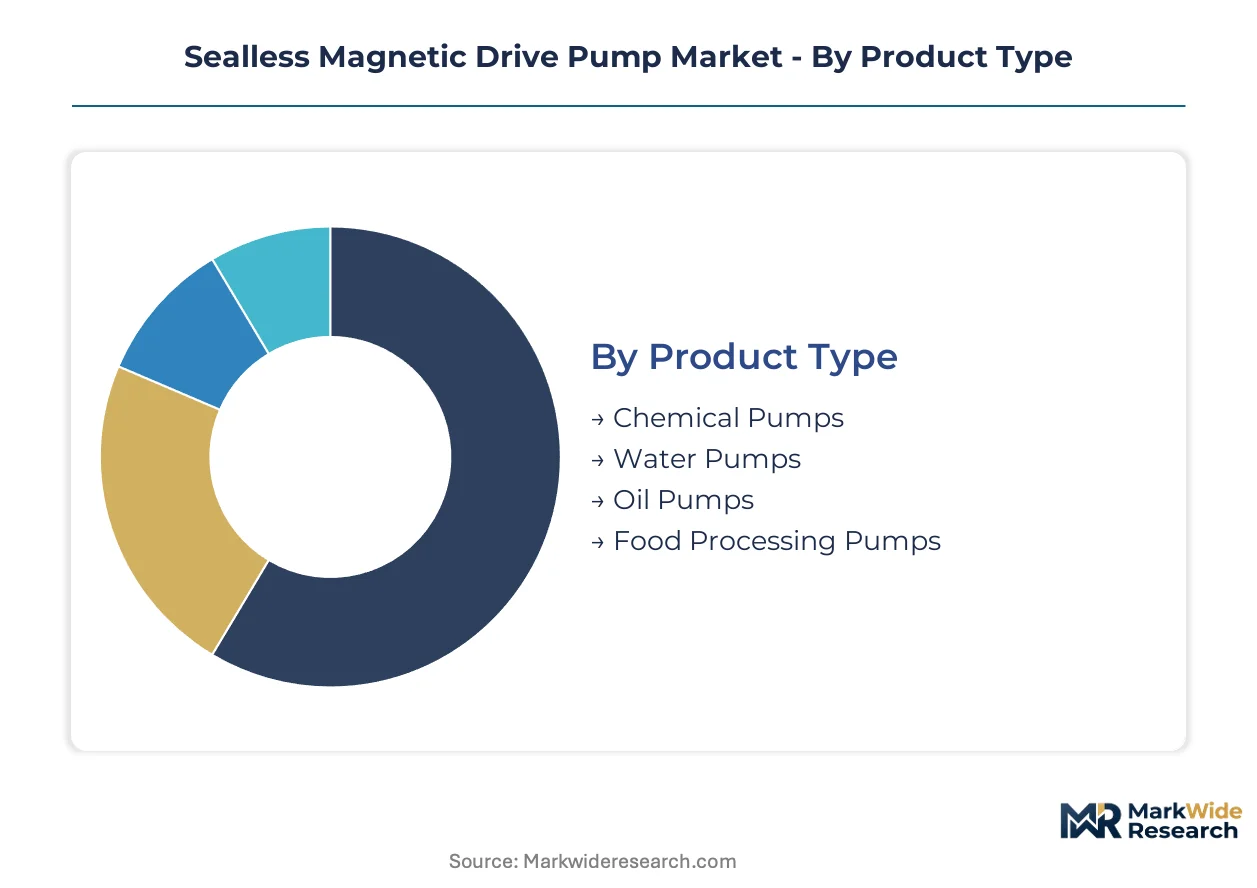
Sealless magnetic drive pump procurement decisions hinge on containment shell specifications, torque transmission architecture, and end-use regulatory exposure. Segmentation reveals how material science investments concentrate in chemical service while water treatment applications scale through standardized configurations.
Product Type:
Containment shell alloy selection and pressure rating specifications define competitive positioning across fluid handling categories.
- Chemical Pumps:Hastelloy C-276 or titanium containment shells withstand process streams exceeding 100 bar pressure in corrosive chemical transfer. German and Japanese specialty chemical plants specify these for REACH-compliant fluorinated compound handling.
- Water Pumps:316L stainless steel configurations dominate desalination brine circulation and wastewater reuse infrastructure. Saudi Arabia and UAE utility projects specify corrosion-resistant alloys for seawater reverse osmosis trains.
- Oil Pumps:High-temperature samarium-cobalt magnet arrays serve hot oil circulation above 300°C in refinery service.
- Food Processing Pumps:Electropolished 316L stainless steel with 3A sanitary certification handles hygienic fluid transfer in dairy and beverage production.
Chemical pumps lead on scale; water pumps lead on momentum.
Application:
Regulatory stringency and emission exposure determine specification depth and replacement value concentration.
- Chemical Processing:Zero-emission mandates under EPA NESHAP and EU REACH compel sealless architectures for benzene, butadiene, and fluorinated chemical transfer. Texas and Rotterdam refineries retrofit mechanical seal pumps to demonstrate 95% fugitive emission reduction.
- Water Treatment:Desalination expansion in water-stressed regions drives corrosion-resistant brine circulation demand. Standardized ANSI/ASME configurations compete on lifecycle cost rather than custom engineering.
- Oil & Gas:Hot hydrocarbon service above 200°C requires thermal demagnetization protocols and specialized magnet traceability documentation.
- Food & Beverage:FDA-compliant hygienic designs command premium pricing for biologics manufacturing and aseptic processing.
Chemical processing anchors replacement value; water treatment expands most quickly.
End User:
Procurement sophistication and validation requirements fragment demand across facility types.
- Manufacturing Facilities:Fragmented volume demand spans general industrial fluid handling with budget-driven standard product selection.
- Oil Refineries:Concentrated large-tender procurement specifies API-compliant configurations with comprehensive magnet traceability and containment shell pressure certification.
- Hospitals:Medical-grade fluid handling requires validated hygienic designs with electropolished surfaces and clean-in-place compatibility.
- Pharmaceutical Companies:FDA 21 CFR Part 11 compliance and 3A sanitary standards create premium pricing tiers for documented validation packages.
Manufacturing facilities dominate unit volume; pharmaceutical companies command margin premiums.
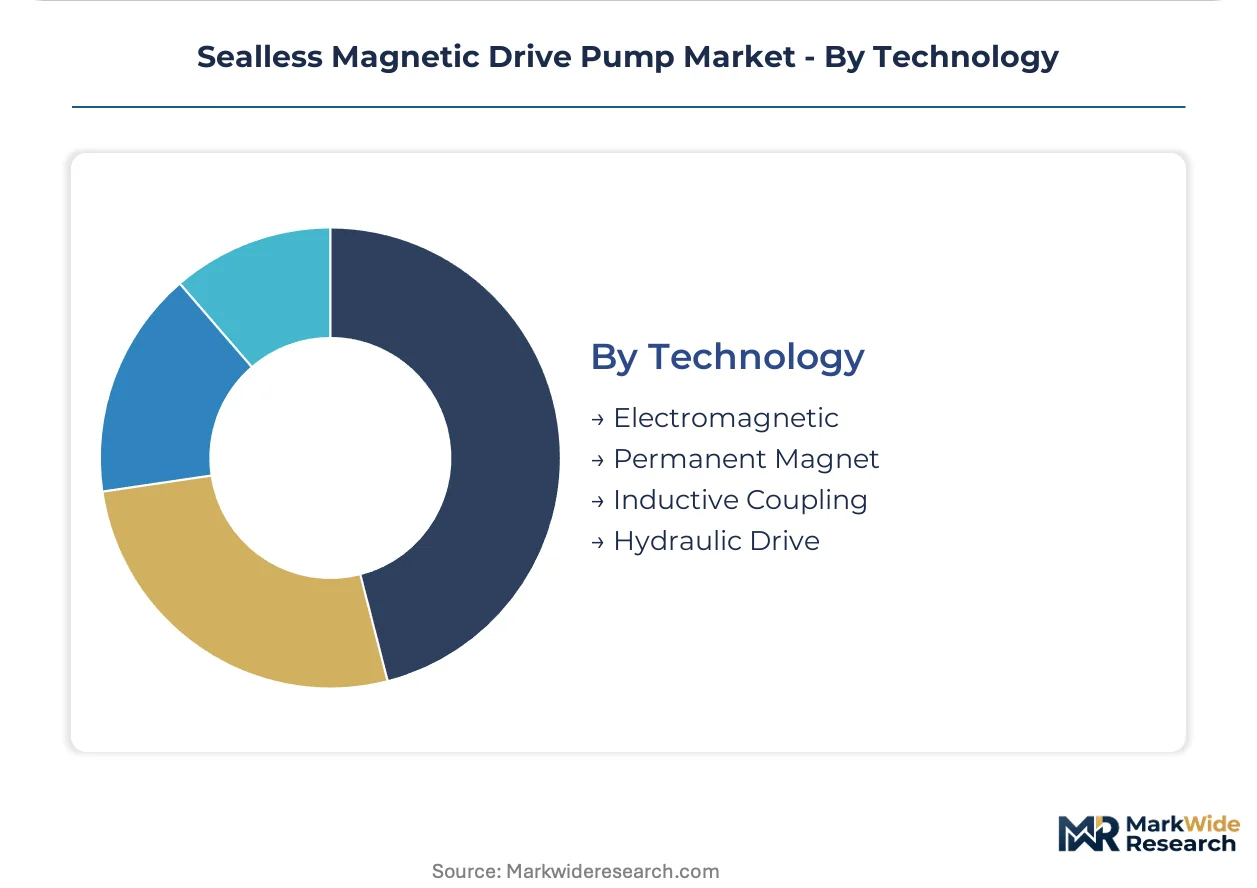
Technology:
Torque transmission architecture determines efficiency profiles and addressable power ranges.
- Electromagnetic:Field-excited configurations enable variable speed control without mechanical coupling. Nuclear and cryogenic service applications favor this architecture for precise torque modulation.
- Permanent Magnet:Neodymium and samarium-cobalt arrays deliver highest torque density with no slip losses. Rare earth supply concentration in Chinese processing facilities creates input cost volatility.
- Inductive Coupling:Eddy current torque transfer eliminates physical containment shell but imposes efficiency penalties above 50 kW duty ratings.
- Hydraulic Drive:Fluid power transmission serves specialized high-viscosity or solids-laden applications where magnetic coupling faces material limitations.
Permanent magnet configurations dominate installed base; electromagnetic architectures gain share in precision service.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's petrochemical corridor generates the densest concentration of sealless magnetic drive pump demand, with state-owned refineries in Shandong and Jiangsu provinces retrofitting aging infrastructure to meet stricter emission controls. Germany and the United States follow as mature markets where regulatory enforcement compresses replacement cycles. Japan's specialty chemical sector sustains premium-tier procurement for corrosion-resistant configurations.
China
State-owned refineries in Shandong and Jiangsu provinces are retrofitting mechanical seal pumps with ANSI/ASME-compliant magnetic drive units to reduce fugitive emissions. SAMR inclusion of sealless pumps in preferred green equipment procurement catalogs accelerates domestic substitution away from imported sealed architectures. The Yangtze River Delta chemical cluster accounts for concentrated demand from fluorinated compound manufacturers facing MEE enforcement.
Germany
Specialty chemical plants in the Ruhr region specify Hastelloy C-276 containment shells for REACH-compliant fluorinated chemical transfer under ECHA enforcement. The EU F-Gas Regulation mandates sealless architectures for equipment handling hydrofluorocarbons, compelling BASF and Evonik facilities to accelerate replacement schedules. North Rhine-Westphalia's chemical corridor anchors European demand for CE-PED module H certified high-pressure configurations.
United States
Texas and Louisiana refineries retrofit benzene and butadiene handling systems to demonstrate 95% fugitive emission reduction under EPA NESHAP compliance calculations. OSHA process safety management rules compel facilities handling volatile organic compounds to adopt sealless architectures or face escalating penalties. The Gulf Coast petrochemical cluster sustains aftermarket service unbundling as third-party specialists stock standardized containment shell inventories.
Japan
Specialty chemical manufacturers in the Chubu and Kansai regions procure corrosion-resistant alloy configurations for aggressive media handling under METI industrial safety guidelines. Iwaki Co., Ltd. dominates domestic supply chains with localized production of titanium containment shells. The Osaka chemical cluster drives premium pricing for validated designs serving fluoropolymer and electronic materials production.
Saudi Arabia
Utility-scale desalination projects in Jubail and Yanbu specify corrosion-resistant brine circulation pumps for seawater reverse osmosis trains. SWCC procurement frameworks prioritize sealless architectures to minimize maintenance intervals in high-salinity environments. The Eastern Province industrial corridor concentrates demand as the kingdom expands potable water capacity to meet domestic consumption targets.
Sealless Magnetic Drive Pump Market Competitive Landscape
Capacity expansion dominates the current landscape as manufacturers scale containment shell forging capabilities to meet compressed delivery timelines for large-tender procurement. The vendor base stratifies across three tiers: integrated industrial pump conglomerates with full aftermarket networks, specialized magnetic drive fabricators focused on corrosion-resistant alloys, and regional assemblers serving water treatment utilities on price. Strategic archetypes include CE-certified European specialists, Asia-Pacific volume producers, and North American service-anchored operators. M&A activity and vertical integration into rare earth magnet supply chains represent the dominant competitive moves as manufacturers defend margin positions against neodymium price volatility.
Among integrated industrial pump conglomerates, Flowserve Corporation and KSB SE & Co. KGaA occupy positions anchored by aftermarket service networks and localized manufacturing footprints. Flowserve exemplifies the North American service-anchored archetype through its Gulf Coast maintenance infrastructure, while KSB represents the CE-certified European specialist model with pressure equipment directive conformity assessment capabilities. Iwaki Co., Ltd. sits within the Asia-Pacific volume producer tier, leveraging corrosion-resistant alloy configurations to serve aggressive chemical media applications across domestic and export markets.
| Leading Market Players |
|---|
| IDEX Corporation |
| HMD Kontro |
| Flowserve Corporation |
| ITT Goulds Pumps |
| Iwaki Co., Ltd. |
| KSB SE & Co. KGaA |
| Wilo SE |
| Klaus Union |
| Sundyne Corporation |
| Others |
Value Network & Pricing Analysis
Neodymium permanent magnet costs cascade through three distinct pricing tiers as rare earth processing concentration in Chinese facilities compresses margins at the standard-product level while premium Hastelloy containment shell configurations retain pricing power through certified European and Japanese supply channels.
Pricing Analysis
Distributor markups widen most aggressively in the aftermarket service layer where third-party specialists stock standardized containment shell inventories and undercut OEM-captive maintenance contracts. Three-tier pricing structure across premium, standard, and economy levels separates CE-PED module H certified high-pressure units from ANSI/ASME compliant mid-tier configurations and basic water treatment specifications. Price differentiation hinges on magnet traceability documentation and containment alloy certification grade. Cost compression in the standard tier is intensifying because rare earth supply volatility feeds directly into neodymium-denominated pump assemblies. Water treatment utilities exhibit highest price sensitivity; pharmaceutical companies demonstrate least sensitivity due to FDA validation requirements.
Supply Chain Analysis
Dual-sourcing requirements from European oil refineries and Japanese specialty chemical plants mandate qualified suppliers in both China and Germany for critical containment shell forgings. Manufacturing gravity centers on China for rare earth magnet processing, Germany for high-pressure alloy fabrication, and Japan for corrosion-resistant titanium configurations. Raw material dependencies span neodymium and samarium-cobalt magnet arrays, Hastelloy C-276 and titanium alloys, and specialized ceramic containment alternatives. Single-source vulnerability concentrates in Chinese rare earth separation facilities. Distribution runs through OEM-direct channels for large-tender refinery procurement and specialized distributors for water treatment utility segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion potential concentrates in containment shell material upgrades as refineries and pharmaceutical facilities shift specification requirements toward certified high-pressure configurations that command sustainable pricing premiums.
For Market Incumbents: Cement aftermarket service control by acquiring third-party pump service specialists in the US Gulf Coast and German Ruhr region before channel unbundling fragments spare parts procurement further. Expand in-house forging capacity for Hastelloy C-276 containment shells to reduce lead time exposure from specialized metallurgical suppliers. Canned motor pump substitutes threaten zero-leakage market share in nuclear and cryogenic applications. For New Entrants and Emerging Players: EU F-Gas Regulation in Germany and France opens a window for specialized magnetic drive fabricators offering REACH-compliant fluorinated chemical transfer configurations. Target desalination brine circulation in Saudi Arabia and UAE utility projects where standardized ANSI/ASME specifications lower barrier to entry against entrenched chemical service specialists. Lead with corrosion-resistant alloy expertise rather than full product range breadth. For Investors and Strategic Acquirers: Consolidation pressure builds where rare earth magnet supply volatility and CE-PED certification timelines strain mid-tier manufacturers lacking captive metallurgical capabilities. Long-term viability favors vertically integrated operators with in-house containment shell forging and established magnet traceability protocols. Watch samarium-cobalt adoption rates in refinery hot oil service as inflection indicator for material science competitive positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rare Earth Magnet Supply | Captive neodymium sourcing insulates margin compression from Chinese processing concentration. |
| CE-PED Module H Certification Investment | European Pressure Equipment Directive conformity unlocks high-pressure tender participation at BASF and Evonik facilities. |
| Aftermarket Service Network Expansion | Gulf Coast maintenance infrastructure captures recurring revenue from Texas and Louisiana refinery retrofits. |
| Desalination Utility Partnership Development | Saudi SWCC procurement frameworks favor sealless architectures for seawater reverse osmosis expansion. |
| Samarium-Cobalt Magnet Array R&D | SmCo configurations above 300°C penetrate hot hydrocarbon service previously blocked by thermal demagnetization limits. |
Research Methodology
Direct dialogue with plant engineers at Texas and Rotterdam refineries, procurement leads at German specialty chemical facilities, aftermarket service heads in the US Gulf Coast, and containment shell metallurgical suppliers grounded qualitative assessment in operational constraints and specification evolution. Secondary validation drew from EPA NESHAP enforcement records, ECHA REACH compliance databases, SEC 10-K filings from listed pump manufacturers, and customs trade data tracking rare earth magnet import flows. Bottom-up unit demand estimates triangulated against top-down industry spend analysis across chemical processing, water treatment, and oil refining end-use sectors.
Bottom-up modeling aggregated addressable unit demand by containment shell pressure rating, magnet array technology, and end-use regulatory exposure across the projection horizon. Segmentation dimensions spanned product type, application severity, end-user procurement sophistication, and regional certification requirements. CAGRs derived from slope analysis of replacement cycle compression, regulatory mandate phase-in schedules, and capacity expansion announcements from state-owned refineries. Industry-specific forecast inputs included MEE enforcement intensity in China's Yangtze River Delta and SAMR green equipment catalog adoption rates.
Forecast precision tightens around the base case; tail outcomes carry wider variance under rare earth export restriction scenarios or accelerated containment shell material substitution. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and refinery retrofit capital allocation priorities. Deviation in neodymium price volatility or CE-PED certification timeline extensions would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pumps and Control Devices
Domestic Booster Pump Market
Pumps and Control Devices
APAC Positive Displacement Pumps Market
Pumps and Control Devices
Radial Piston Pumps Market
Pumps and Control Devices
Fire Pump Test Meters Market
Pumps and Control Devices
Global Leak Detection Solutions Market
Pumps and Control Devices
Global Commercial Pumps Market
Pumps and Control Devices
Electrostatic Coalescers Market
Pumps and Control Devices
Multi-Stage Centrifugal Pumps Market
Pumps and Control Devices
Fuel Transfer Pump Market
Pumps and Control Devices
Seawater Cooling Pumps Market
Pumps and Control Devices
Plunger Pumps Market
Pumps and Control Devices
Heavy Duty Dewatering Pumps Market
Pumps and Control Devices
Pressure Washer Pump Oil Market
Pumps and Control Devices
Solar Fountain Pumps Market
Pumps and Control Devices
Rental Industrial Pump Market
Pumps and Control Devices
Global Smart Pumps Market