
 Brine Tanks Market | 2026-2036
Brine Tanks Market Size, Share, and Industry Trends Forecast 2026-2036
Brine Tanks Market Analytics
Direct distribution from manufacturers to municipal water authorities is reconfiguring procurement patterns for large-capacity brine tanks. Pentair leverages its vertically integrated filtration portfolio to anchor municipal contracts across the Upper Midwest. Snyder Industries competes through rotational molding specialization in polyethylene tank fabrication, while Clack Corporation dominates valve-integrated brine tank systems for residential and light commercial softeners.
Brine tanks are corrosion-resistant containment vessels engineered to store saturated sodium chloride solutions at concentrations between 26% and 28% by weight, primarily serving ion exchange regeneration cycles in water softening and industrial demineralization. Polyethylene vertical tanks lead unit volume due to cost efficiency and chemical inertness, though fiberglass alternatives command premium positioning in high-temperature chemical storage applications. Water treatment end use generates the largest absolute demand, while food processing applications for brine curing and preservation represent a concentrated margin pool.
EPA effluent guidelines under the Clean Water Act shape brine tank specifications for discharge containment, while NSF/ANSI 44 certification governs residential system material safety and structural integrity. The EU F-Gas Regulation indirectly influences brine tank demand by accelerating non-refrigerant industrial cooling alternatives in European manufacturing. Stakeholders must monitor evolving state-level PFAS remediation mandates, as these programs expand centralized water treatment infrastructure requiring regenerable ion exchange systems and associated brine storage capacity.
Market Dynamics
Municipal water authorities in the Great Lakes region are consolidating procurement around large-capacity polyethylene systems, compressing vendor margins while elevating NSF/ANSI 44 certification from optional to table stakes for contract eligibility.
Growth Catalysts
- EPA Effluent Guidelines:Discharge containment mandates under the Clean Water Act are expanding regenerable ion exchange infrastructure across U.S. municipal systems.
- Rotational Molding Advances:Cross-linked polyethylene fabrication techniques are extending tank service life in high-cycle industrial softening applications.
- PFAS Remediation Programs:State-level mandates for centralized treatment are accelerating brine storage procurement in Michigan, Wisconsin, and Ohio.
Market Restraints
- Resin Price Volatility:Polyethylene feedstock costs fluctuate with ethylene spot markets, compressing margins for rotational molders serving price-locked municipal contracts.
- Fiberglass Supply Concentration:High-temperature chemical storage alternatives depend on a narrow supplier base concentrated in Gulf Coast manufacturing corridors.
- Thermal Expansion Limitations:Polyethylene tanks face dimensional stability constraints above 60°C, restricting deployment in certain industrial demineralization loops.
Strategic Opportunities
- Food Processing Brine Curing:Automated pickle and cure-line integration represents an underpenetrated margin pool beyond water treatment's commodity dynamics.
- EU F-Gas Regulation:Non-refrigerant industrial cooling alternatives are expanding ion exchange demand in German and Polish manufacturing facilities.
- Direct Municipal Contracting:Manufacturer-to-authority sales channels are disintermediating traditional distributor networks in the Upper Midwest.
Industry Challenges
- NSF/ANSI 44 Certification Timelines:Material safety validation cycles extend 12-18 months, delaying product launches for new resin formulations.
- Legacy Valve Integration:Proprietary control head interfaces complicate tank replacement in residential retrofit markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brine Tanks Market |
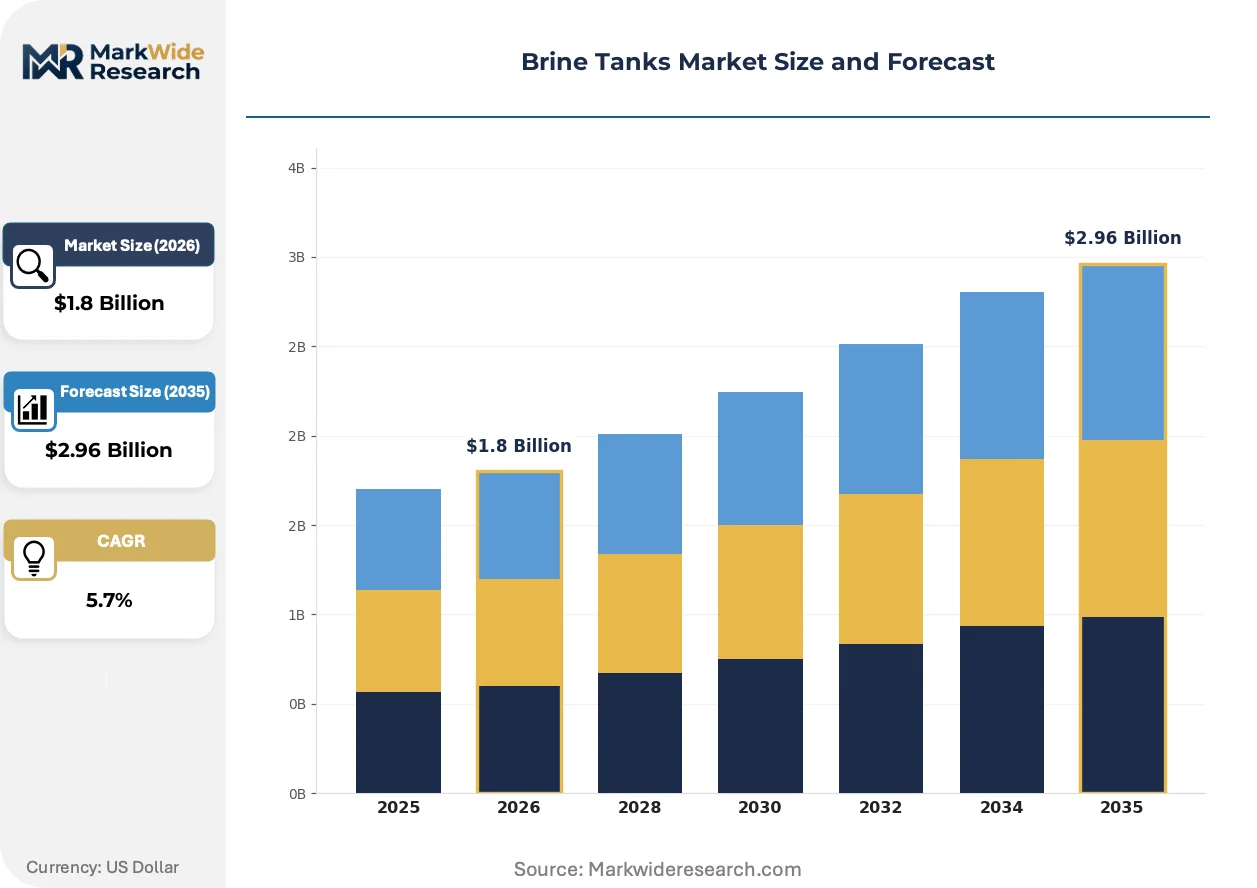
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Tank Type: Vertical Tanks, Horizontal Tanks, Open Top Tanks, Closed Top Tanks Material: Polyethylene, Fiberglass, Steel, Concrete End Use: Food Processing, Water Treatment, Chemical Storage, Agricultural Size: Small Tanks, Medium Tanks, Large Tanks, Custom Tanks |
| Companies Covered | Clack Corporation, Gilmore-Kramer Company, Pentair, M.I.P. NV, Applied Membranes Inc, Snyder Industries, Culligan International, Kinetico Incorporated, A. O. Smith Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brine Tanks Market Evolving Landscape
Digital monitoring systems and predictive maintenance protocols are reconfiguring how operators manage brine saturation levels and regeneration cycles. Material science advances and procurement centralization are simultaneously reshaping competitive positioning.
Smart tank monitoring using ultrasonic level sensing and IoT connectivity is virtualizing manual brine concentration testing. Municipal operators in Minnesota and Illinois are piloting these systems to reduce labor-intensive site visits. The technology is virtualizing traditional service-contract revenue models toward subscription-based remote monitoring.
EPA's evolving PFAS discharge rules are tightening material traceability requirements for brine containment vessels. Manufacturers must now document resin sourcing and additive compositions through the supply chain. Residential system suppliers face the steepest compliance burden as they lack dedicated regulatory affairs functions.
Specification consolidation around integrated tank-valve systems is compressing standalone tank procurement. Water conditioning dealers in the Great Lakes corridor increasingly specify pre-assembled packages rather than sourcing components separately. This pattern concentrates most acutely in Wisconsin's dense network of family-owned softener service operations.
Brine Tanks Market Segmentation
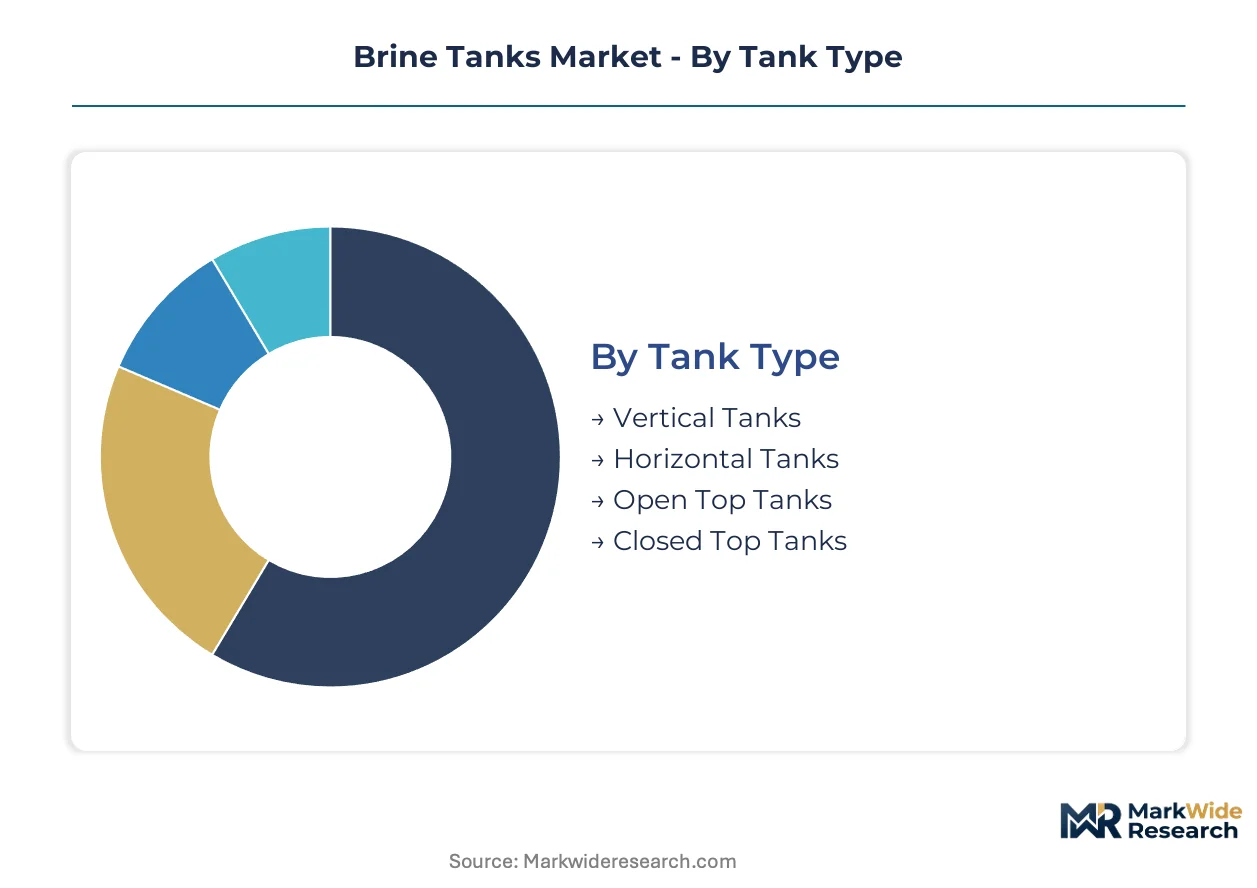
Brine tank procurement cycles vary dramatically across tank geometries, material classes, and end-use applications. Understanding replacement frequency and specification rigor within each segment enables suppliers to align inventory and certification investments with actual demand velocity.
Tank Type:
Vertical tanks turn over fastest in municipal softening applications where cycling stress accelerates fatigue, while horizontal configurations persist longest in fixed industrial installations with stable duty profiles.
- Vertical Tanks:Cylindrical upright vessels dominate polyethylene fabrication due to optimal floor-space utilization and natural brine stratification. Demand concentrates in Great Lakes municipal authorities replacing aging ion exchange infrastructure under tightening EPA discharge guidelines. These units face 10-15 year replacement cycles in high-frequency regeneration environments.
- Horizontal Tanks:Low-profile configurations suit space-constrained mechanical rooms and transportable skid systems. Food processing brine curing lines in Wisconsin and Ohio specify these for clean-in-place accessibility, though slower turnover extends service life to 20+ years in stable temperature conditions.
- Open Top Tanks:Coverless designs serve batch chemical mixing and manual salt loading operations. Agricultural fertilizer blending stations in Michigan's Thumb region favor these for direct bulk salt receipt.
- Closed Top Tanks:Sealed systems with manway access dominate NSF/ANSI 44 certified residential softener applications. Vapor containment requirements are tightening specifications across Upper Midwest dealer networks.
Vertical tanks anchor the volume base while horizontal configurations gain share at the steepest rate in food processing integration.
Material:
Cost tiers separate commodity polyethylene from engineered alternatives, with specification grade determining margin capture and certification burden.
- Polyethylene:Cross-linked and linear low-density formulations command 70%+ of unit volume through rotational molding cost efficiency. Municipal procurement in Illinois and Minnesota standardizes on NSF/ANSI 44 certified grades, though thermal expansion above 60°C limits high-temperature demineralization deployment.
- Fiberglass:Filament-wound reinforced thermoset vessels serve chemical storage above 80°C and concentrated acid containment. Supply concentrates in Gulf Coast manufacturing corridors, creating lead time vulnerability for inland industrial users.
- Steel:Carbon and stainless steel fabrications persist in legacy industrial softening infrastructure. Chicago-area manufacturing facilities maintain these for compatibility with existing valve trains.
- Concrete:Cast-in-place and precast systems anchor large-scale municipal regeneration facilities. Ohio's centralized PFAS treatment programs are expanding specifications for 50,000+ gallon containment.
Polyethylene anchors the volume base while fiberglass climbs the fastest in high-temperature chemical storage substitution.
End Use:
Application maturity shapes margin structure, with established water treatment commoditizing against emerging food automation premiums.
- Water Treatment:Ion exchange regeneration for municipal softening and industrial demineralization generates the largest absolute demand. Michigan, Wisconsin, and Ohio infrastructure replacement cycles are accelerating procurement under state-level PFAS mandates.
- Food Processing:Automated pickle and cure-line integration represents an underpenetrated margin pool beyond water treatment commodity dynamics. Meatpacking facilities in Nebraska and Iowa are specifying NSF-certified polyethylene for brine injection systems.
- Chemical Storage:Saturated salt solutions for chlor-alkali and dye manufacturing require corrosion-resistant containment. Ohio River Valley chemical producers specify fiberglass for concentrated brine above 28% weight concentration.
- Agricultural:Fertilizer blending and livestock nutrient systems favor cost-optimized polyethylene. Illinois grain processing co-ops are consolidating procurement around 5,000-gallon vertical configurations.
Water treatment anchors the volume base while food processing gains share at the steepest rate through automation integration.
Size:
Customer scale determines specification authority, with municipal buyers driving standardization against fragmented residential customization.
- Small Tanks:Residential softener systems under 500 gallons dominate unit volume through dealer network distribution. Wisconsin's family-owned service operations specify pre-assembled tank-valve packages.
- Medium Tanks:Light commercial 500-5,000 gallon systems serve restaurants, hospitals, and small manufacturing. Minnesota healthcare facilities are consolidating procurement around NSF/ANSI 44 certified polyethylene.
- Large Tanks:Municipal and industrial 5,000-50,000 gallon configurations face longest sales cycles but highest contract values. Direct manufacturer-to-authority procurement is disintermediating traditional distribution in the Upper Midwest.
- Custom Tanks:Engineered-to-order systems address non-standard footprints and extreme duty conditions. Ohio PFAS remediation facilities are specifying dual-wall containment with leak detection integration.
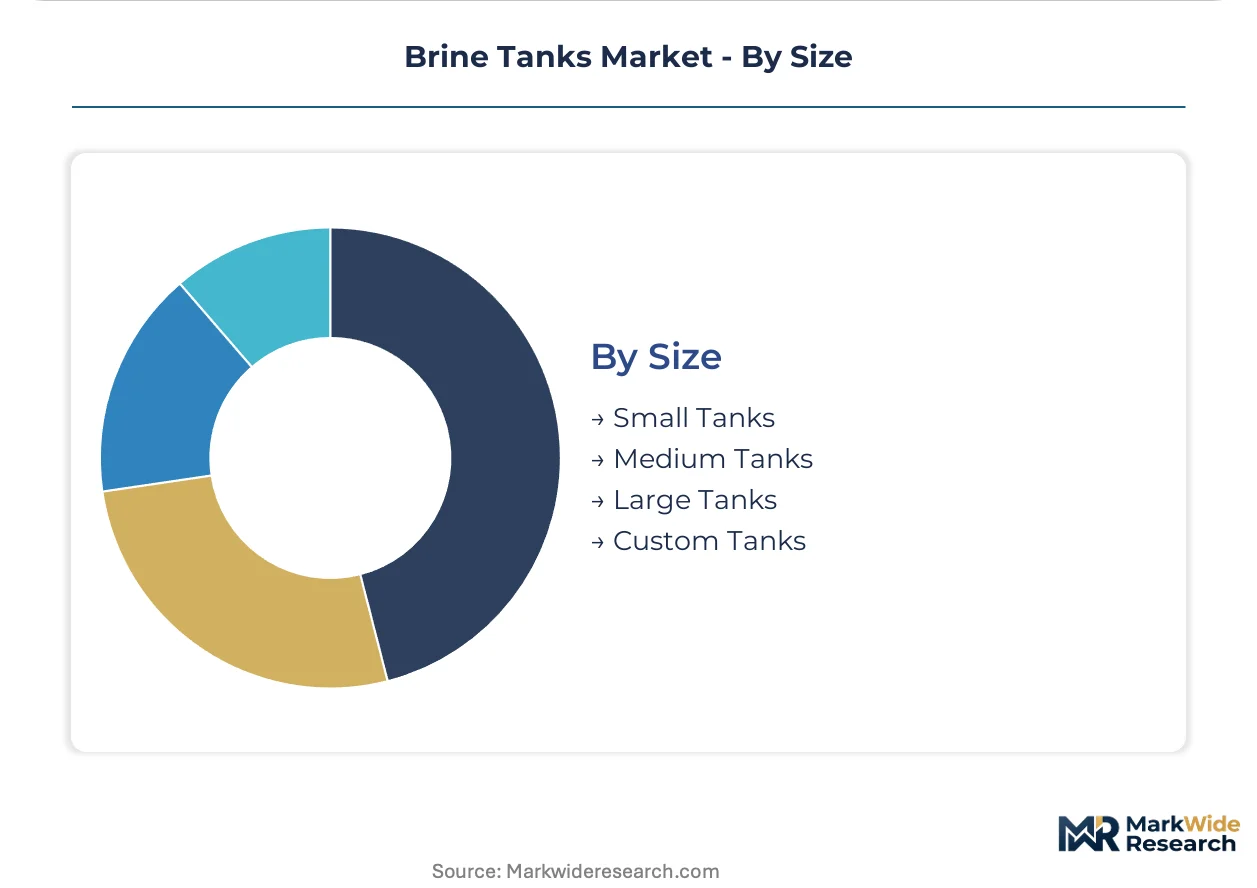
Small tanks anchor the volume base while large tanks gain share at the steepest rate through municipal procurement centralization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Great Lakes-St. Lawrence Seaway system anchors North American brine tank demand, enabling bulk salt transport to municipal regeneration facilities across the Upper Midwest. This maritime corridor underwrites procurement economics for ion exchange infrastructure serving communities from Duluth to Montreal.
United States
EPA discharge regulations under the Clean Water Act are accelerating municipal brine tank replacement cycles across Michigan, Wisconsin, and Ohio. State-level PFAS remediation mandates in these three states are expanding centralized treatment infrastructure requiring regenerable ion exchange systems. The Chicago-Milwaukee-Detroit corridor concentrates procurement authority among consolidated water authorities.
Canada
Aging municipal softening infrastructure in Ontario's Golden Horseshoe region is driving polyethylene tank procurement for ion exchange regeneration. Health Canada's Guidelines for Canadian Drinking Water Quality shape material safety specifications for residential and commercial systems. The Toronto-Hamilton-Niagara industrial belt concentrates demand from food processing brine curing operations.
Germany
EU F-Gas Regulation compliance is accelerating non-refrigerant industrial cooling alternatives, expanding ion exchange demand in German manufacturing facilities. ECHA chemical safety requirements govern material specifications for brine containment in industrial demineralization loops. The Ruhr industrial region and Bavarian manufacturing corridor are specifying NSF-certified polyethylene for process water softening.
Poland
Industrial water treatment modernization programs are expanding brine storage procurement for chemical processing and power generation applications. EU F-Gas Regulation implementation is displacing refrigerant-based cooling systems with ion exchange alternatives in Silesian manufacturing facilities. The Katowice-Opole industrial cluster is consolidating procurement around rotational-molded polyethylene configurations.
China
GB standards for industrial water reuse are tightening brine containment specifications in chemical and textile manufacturing zones. MEE environmental compliance inspections are accelerating tank replacement cycles in coastal provinces with dense chlor-alkali production. The Yangtze River Delta petrochemical corridor is expanding fiberglass-reinforced storage for high-temperature concentrated brine applications.
Brine Tanks Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in fabrication and valve integration. The vendor base separates into consolidated filtration platform owners, rotational molding specialists, and valve-integrated system suppliers. Three archetypes dominate: vertically integrated water treatment platforms, polyethylene fabrication specialists, and control head-integrated package assemblers. Competitive moves concentrate on direct municipal contracting disintermediation and rotational molding capacity expansion for cross-linked polyethylene.
Among North American fabricators, Pentair and Snyder Industries exemplify distinct positioning archetypes. Pentair occupies the integrated platform tier, leveraging captive filtration portfolios to anchor municipal authority contracts. Snyder Industries represents the rotational molding specialization vector, with polyethylene fabrication expertise serving cost-optimized procurement segments. Clack Corporation sits within the valve-integrated system tier, dominating pre-assembled tank-control head configurations for residential and light commercial channels.
| Leading Market Players |
|---|
| Clack Corporation |
| Gilmore-Kramer Company |
| Pentair |
| M.I.P. NV |
| Applied Membranes Inc |
| Snyder Industries |
| Culligan International |
| Kinetico Incorporated |
| A. O. Smith Corporation |
| Others |
Value Network & Pricing Analysis
The Great Lakes-St. Lawrence Seaway corridor shapes cost dynamics across brine tank procurement, with bulk salt transport economics concentrating supplier power among rotational molders near Chicago and Milwaukee while downstream price differentiation separates NSF-certified municipal systems from uncertified agricultural configurations.
Pricing Analysis
Volume-discount tiering structures separate municipal authority contracts from dealer-network residential sales, with direct manufacturer contracting compressing distributor markups in the Upper Midwest. Price differentiation hinges on NSF/ANSI 44 certification grade and polyethylene resin formulation quality. Cost compression in commodity polyethylene runs through price-locked municipal contracts as ethylene feedstock volatility squeezes rotational molder margins. Agricultural buyers exhibit highest price sensitivity, while PFAS remediation programs render certified municipal procurement least sensitive to unit cost fluctuations.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk for fiberglass resin and specialty valve components. Manufacturing concentrates in the United States, Canada, and Germany, with polyethylene fabrication anchored in the Upper Midwest and Gulf Coast petrochemical corridors. Raw material inputs draw from ethylene production, cross-linking agent chemicals, and filament-wound thermoset composites. Single-source vulnerability persists in high-temperature fiberglass alternatives. Distribution runs through direct municipal contracting disintermediating traditional dealer networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized rotational molding capacity for cross-linked polyethylene represents the binding constraint in this market, with NSF certification timelines and resin formulation expertise creating durable capability gaps between incumbent platforms and aspirant entrants.
For Market Incumbents: Harden municipal contract retention by expanding captive cross-linked polyethylene production capacity in Illinois and Wisconsin. Deepen backward integration into resin compounding to offset ethylene price volatility threatening price-locked authority contracts. Prioritize certification pipeline investments to compress NSF/ANSI 44 validation cycles below 12 months. For New Entrants and Emerging Players: Build out automated brine curing integration capabilities for meatpacking facilities in Nebraska and Iowa, where NSF-certified polyethylene penetration remains below water treatment saturation. Target food processing applications through direct OEM relationships bypassing established dealer networks. Lead with clean-in-place horizontal tank configurations differentiated from commodity vertical designs. For Investors and Strategic Acquirers: Regional rotational molding specialists with captive NSF certification pipelines and established Upper Midwest municipal relationships represent the most defensible acquisition profile. Long-term viability rests on PFAS remediation infrastructure buildout sustaining ion exchange demand across the Great Lakes basin. Monitor state-level PFAS mandate acceleration as the primary demand inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Rotational Molding Capacity Expansion | Captive cross-linked polyethylene production secures municipal contract eligibility against resin volatility. |
| NSF/ANSI 44 Certification Investment | Compressed validation timelines unlock Great Lakes authority procurement before competitor product launches. |
| Direct Municipal Contracting Channel | Manufacturer-to-authority sales disintermediate distributor markups in consolidated Upper Midwest markets. |
| Food Processing System Integration | Automated pickle line partnerships capture premium margins beyond water treatment commodity dynamics. |
| Smart Tank Monitoring Platform | IoT-enabled level sensing virtualizes service revenue toward subscription-based remote monitoring models. |
Research Methodology
A spread of perspectives from municipal water authority procurement officers, rotational molding plant managers, water conditioning dealer principals, and NSF certification laboratory directors converged on the working assumptions shaping this analysis. Primary fieldwork combined structured interviews with secondary validation against EPA discharge guideline filings, state-level PFAS remediation program budgets, customs records for polyethylene resin imports, and SEC disclosures from publicly traded filtration platform owners. Bottom-up tank unit demand estimates triangulated against top-down municipal infrastructure spending projections.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, modeling replacement cycles against new installation demand in PFAS remediation infrastructure. Segmentation dimensions included tank geometry, material class, end-use application, and customer scale tier. CAGRs derived from regression analysis of historical procurement patterns and regulatory mandate acceleration trajectories. Industry-specific forecast inputs incorporated ethylene feedstock price elasticity and NSF certification backlog durations.
Stress conditions across resin price volatility bands, PFAS mandate implementation delays, and fiberglass supply disruption scenarios were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding municipal consolidation trajectories and rotational molding capacity expansion timelines. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pumps and Control Devices
Vane Pump Market
Pumps and Control Devices
APAC Positive Displacement Pumps Market
Pumps and Control Devices
High Power Air Pump Market
Pumps and Control Devices
Global Mobile Hydraulic Pump Market
Pumps and Control Devices
Vacuum Pump Stations Market
Pumps and Control Devices
Solar Fountain Pumps Market
Pumps and Control Devices
Industrial Pump Control Panels Market
Pumps and Control Devices
Electrohydraulic Pumps Market
Pumps and Control Devices
Global Heavy Duty Pumps Market
Pumps and Control Devices
Gear Pump Market
Pumps and Control Devices
Axial and Mixed Flow Pumps Market
Pumps and Control Devices
Industrial Oil Filter Machine Market
Pumps and Control Devices
Global Lubrication Pumps Market
Pumps and Control Devices
Industrial ASME B73.1 Centrifugal Pumps Market
Pumps and Control Devices
Europe Asia Submerged Pump Market
Pumps and Control Devices
Oil and Gas Pumps Market