
 Air-Operated Double Diaphragm (AODD) Pumps Market | 2026-2036
Air-Operated Double Diaphragm (AODD) Pumps Market Size, Share, and Industry Trends Forecast 2026-2036
Air-Operated Double Diaphragm (AODD) Pumps Market Outlook
ISO 9001 certification is bifurcating the competitive landscape into qualified system suppliers and marginal regional fabricators. Graco Inc leverages its vertically integrated manufacturing footprint to sustain pricing power across North American chemical processing accounts. Wilden Pump and Engineering LLC anchors its position through specialized elastomer engineering that extends diaphragm life in abrasive fluid transfer. IDEX Corporation dominates the aftermarket channel through an extensive distributor network that controls spare parts availability.
An air-operated double diaphragm pump is a positive-displacement device that uses compressed air to drive two flexible diaphragms in reciprocating motion, creating suction and discharge strokes without mechanical seals; typical units handle pressures up to 125 psi and achieve flow rates exceeding 200 gpm, making them essential for transferring viscous, shear-sensitive, or solids-laden fluids in hazardous environments. Stainless steel configurations command the strongest margin pools in chemical processing and pharmaceutical end users where corrosion resistance governs equipment selection. Plastic material variants compete aggressively in water treatment and food & beverage applications where capital budgets prioritize lower first cost over extended service intervals. Aluminum constructions occupy the volume-driven segment in general manufacturing and construction where portability and initial affordability outweigh lifecycle considerations.
EPA emissions standards and OSHA process safety management requirements shape product design priorities for US-facing manufacturers, while REACH chemical compliance and CE marking obligations govern market access across European Union member states. FDA sanitary standards and 3-A SSI certifications constrain material selection and surface finish specifications for food & beverage and pharmaceutical applications. Stakeholders must monitor evolving PFAS restrictions and perfluoroelastomer phase-out timelines that threaten incumbent diaphragm chemistries and force reformulation investments ahead of regulatory deadlines.
Market Dynamics
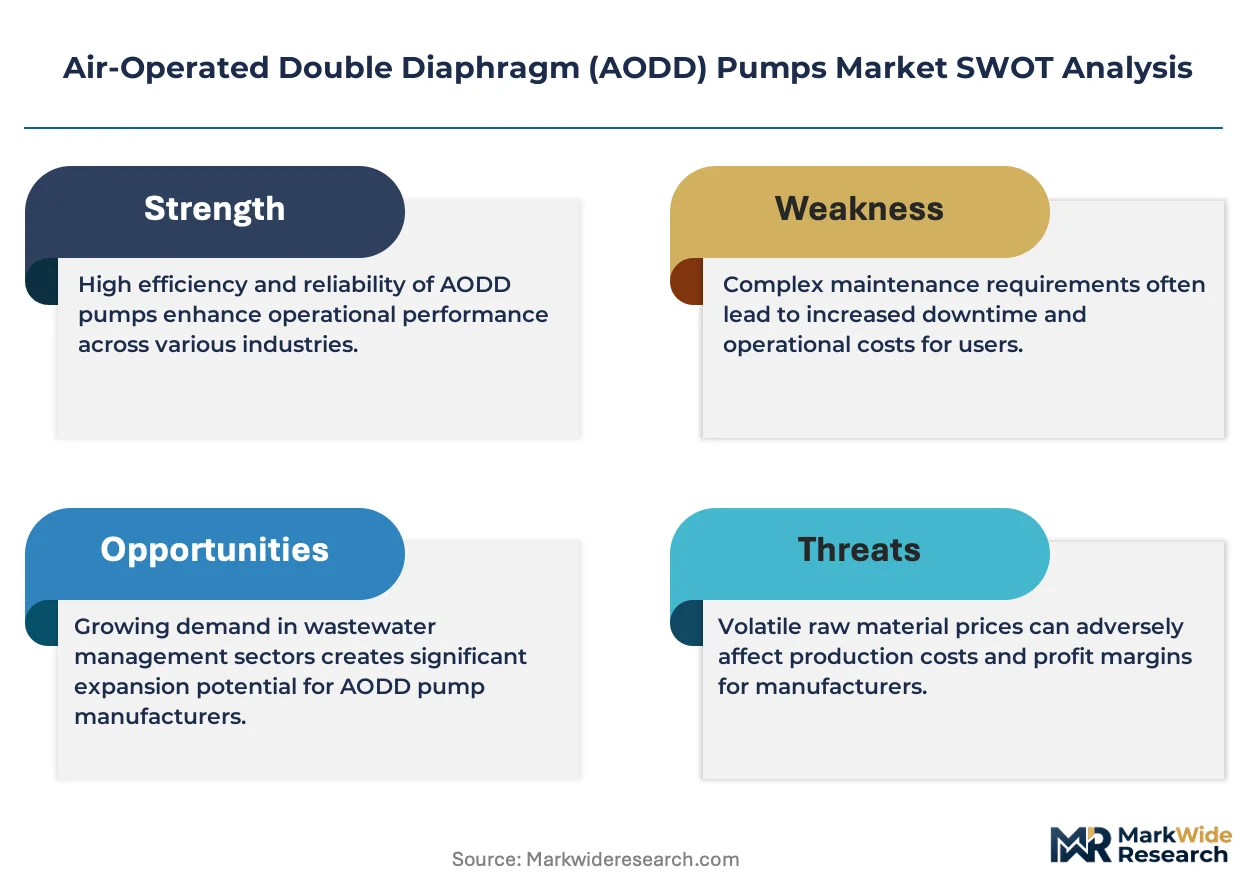
REACH compliance deadlines and EPA emissions rules are forcing chemical processors across Germany and the United States to replace legacy pumping infrastructure ahead of scheduled maintenance cycles, compressing replacement timelines and favoring certified system suppliers over regional fabricators.
Growth Catalysts
- MIIT efficiency mandates:China's Ministry of Industry and Information Technology is accelerating replacement cycles in coastal manufacturing provinces, driving procurement of next-generation diaphragm pumps with improved air consumption metrics.
- PFAS phase-out timelines:Perfluoroelastomer restrictions in the European Union and United States are compelling diaphragm reformulation investments, creating upgrade demand among incumbent installed bases.
- Shear-sensitive fluid transfer:Biopharmaceutical manufacturing expansion requires positive-displacement pumps that preserve cell viability, positioning AODD technology as the preferred solution for vaccine and therapeutic production lines.
Market Restraints
- Fluoropolymer supply concentration:Diaphragm elastomer supply chains cluster among specialty chemical producers in Germany and Japan, exposing pump manufacturers to input cost volatility and allocation constraints.
- Compressed air infrastructure dependency:AODD pump deployment requires facility-scale compressed air systems, limiting adoption in greenfield sites without existing pneumatic infrastructure or capital for compressor installation.
- Electric diaphragm pump substitution:Sealless electric alternatives are capturing share in low-hazard fluid transfer applications where explosion-proofing is not mandated, eroding AODD volume in water treatment and food processing.
Strategic Opportunities
- Modular aftermarket retrofit kits:Component-level upgrade packages enable diaphragm material swaps and air valve conversions without full pump replacement, extending service revenue from installed bases in chemical processing.
- CE-MDR convergence:The EU Medical Device Regulation's expanded scope for process equipment in pharmaceutical manufacturing creates certification pathways for sanitary AODD configurations in drug substance production.
- Remote monitoring integration:IoT-enabled air consumption sensors and predictive diaphragm wear algorithms are opening subscription service models among multi-site industrial operators seeking unplanned downtime reduction.
Industry Challenges
- Elastomer compounding expertise scarcity:Reformulating diaphragm materials to eliminate perfluorinated chemistries while maintaining chemical resistance and flex fatigue life requires polymer scientists with specialized fluoroelastomer experience that concentrates among legacy suppliers.
- Multi-certification stacking:Simultaneous compliance with FDA sanitary standards, 3-A SSI dairy specifications, and ATEX explosion-proofing extends product development timelines and testing costs for universal pump platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Air-Operated Double Diaphragm (AODD) Pumps Market |
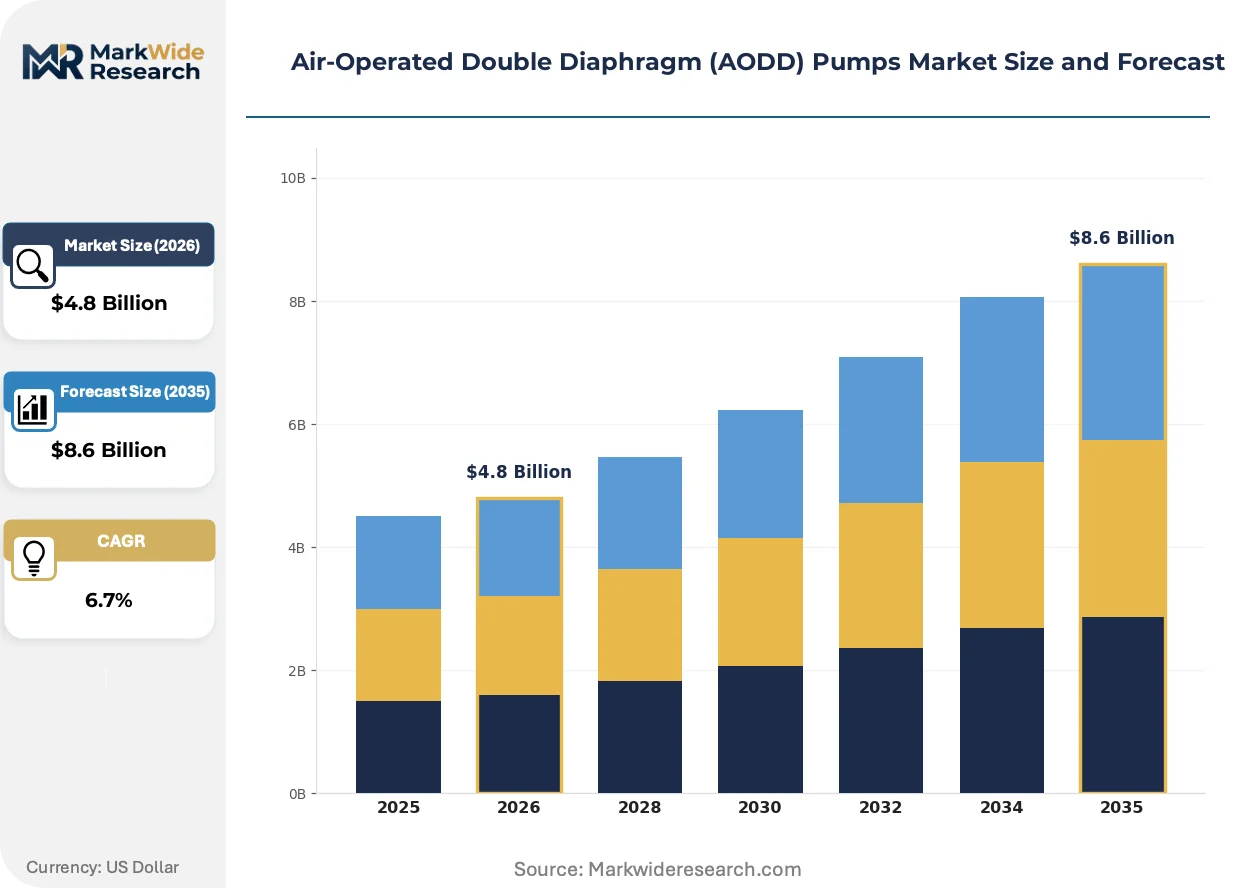
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plunger Pumps, Diaphragm Pumps, Peristaltic Pumps, Rotary Pumps Application: Water Treatment, Chemical Processing, Food & Beverage, Oil & Gas End User: Manufacturing, Energy, Pharmaceutical, Construction Material: Plastic, Stainless Steel, Aluminum, Composite |
| Companies Covered | Graco Inc, Wilden Pump and Engineering LLC, Aro Fluid Management, Yamada Corporation, Sandpiper Pumps, Almatec Maschinenbau GmbH, Versa-Matic Pump Company, IDEX Corporation, Dover Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Air-Operated Double Diaphragm (AODD) Pumps Market Strategic Shifts
Diaphragm pump engineering is pivoting toward modularity and intelligence, with compressed air optimization and predictive service models displacing traditional specification criteria centered on initial capital cost and nominal flow capacity.
Advanced thermoplastic elastomer compounds are replacing conventional rubber diaphragms in abrasive slurry applications, extending mean time between failure by 40-60% in mining and wastewater segments. North American sand and aggregate operators are specifying these configurations for tailings transfer duty. The technology is miniaturizing component footprints while maintaining pressure ratings, enabling portable pump skids for construction dewatering.
REACH Annex XVII restrictions on per- and polyfluoroalkyl substances are compelling diaphragm manufacturers to validate alternative chemistries ahead of 2025-2027 enforcement windows. ECHA substance evaluation is accelerating reformulation timelines beyond typical product development cycles. Pharmaceutical and food processing end users in the European Union are pre-qualifying non-fluorinated elastomer options to avoid supply discontinuity.
Asset-light rental and lease-to-own arrangements are displacing outright purchase for intermittent-duty applications in construction and emergency response. United States municipal utilities and industrial maintenance departments are consolidating pump fleets through third-party equipment providers. This model concentrates in hurricane-prone Gulf Coast states where standby dewatering capacity requirements fluctuate seasonally.
Air-Operated Double Diaphragm (AODD) Pumps Market Segmentation
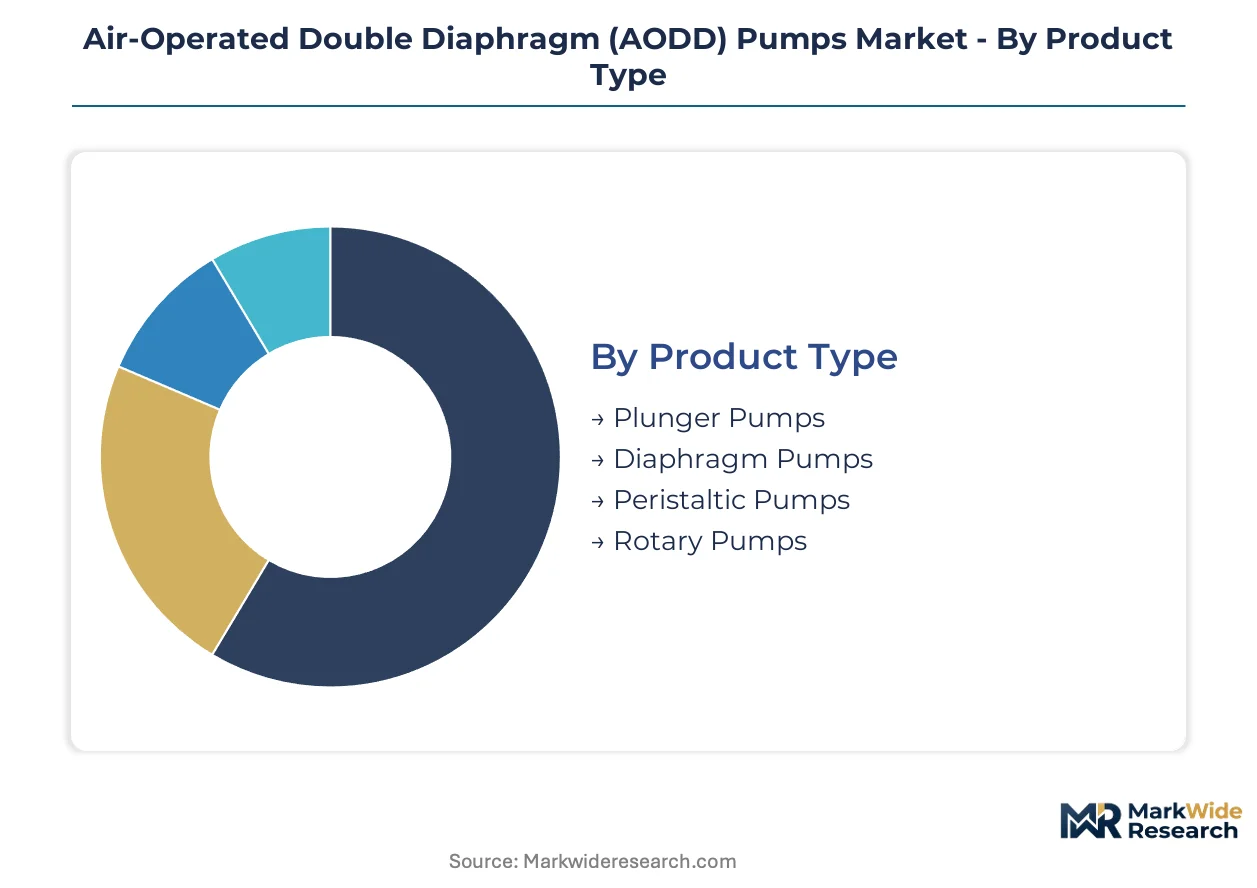
Segmentation in the AODD pump market reveals where electric alternatives and sealless technologies exert the strongest displacement pressure. Understanding these fault lines guides product positioning and R&D allocation across material grades and end-use verticals.
Product Type:
Diaphragm pumps face the most intense substitution threat from progressing cavity and magnetically driven centrifugal designs in low-viscosity fluid transfer.
- Diaphragm Pumps:Compressed air drives reciprocating elastomer membranes without mechanical seals, achieving suction lift to 20 feet and dry-run capability. Chemical processing plants in Germany specify these for hazardous solvent transfer where spark-proof operation is mandatory. REACH compliance deadlines are compressing replacement cycles for legacy units.
- Plunger Pumps:Precision-machined ceramic or stainless steel pistons deliver high-pressure output to 10,000 psi for hydrostatic testing and waterjet cutting. Oil & gas operators in Texas deploy these for wellhead injection where pressure consistency outweighs pulsation concerns. Capital intensity limits adoption in cost-sensitive municipal water applications.
- Peristaltic Pumps:Hose compression mechanisms handle sterile biopharmaceutical fluids without product contact. Single-use tubing configurations dominate vaccine manufacturing lines where cross-contamination protocols are stringent.
- Rotary Pumps:Gear and vane configurations transfer lubricating oils and viscous resins with continuous flow. General manufacturing accounts in China's coastal provinces favor these for hydraulic fluid circulation where air infrastructure is absent.
Diaphragm pumps anchor the volume base while peristaltic configurations gain share at the steepest rate in biopharmaceutical applications.
Application:
Cost tier stratification separates specification-driven process industries from price-sensitive utility operations.
- Chemical Processing:Corrosive acid and caustic transfer demands PTFE-lined diaphragms and Hastelloy wetted components. EPA emissions rules and OSHA process safety mandates in the United States are forcing upgrades to leak-free positive-displacement technologies. Margin pools concentrate here due to certification requirements and aftermarket service attachment.
- Water Treatment:Sludge transfer and chemical dosing applications prioritize polypropylene and PVDF constructions for chlorine resistance. Municipal utilities in Florida specify these for desalination brine handling where salt corrosion accelerates metal fatigue. Electric alternatives are capturing share in non-hazardous clean water zones.
- Food & Beverage:Sanitary AODD units with 3-A SSI certification transfer viscous syrups and dairy products. FDA material compliance constrains elastomer selection to Buna-N and EPDM formulations.
- Oil & Gas:Explosion-proof ATEX configurations handle drilling mud and produced water in offshore platforms. North Sea operators require redundant diaphragm designs for subsea reliability.
Water treatment commands the highest unit volumes while chemical processing delivers the steepest margin expansion trajectory.
End User:
Customer procurement maturity varies sharply between asset-intensive process operators and project-driven construction fleets.
- Manufacturing:Continuous production lines demand predictive maintenance integration and IoT-enabled air consumption monitoring. Automotive paint shops in Michigan specify stainless steel AODD pumps for solvent circulation where shear-sensitive coatings require gentle handling. Total cost of ownership calculations now dominate capital approval processes.
- Pharmaceutical:cGMP compliance and FDA validation protocols govern equipment selection for active pharmaceutical ingredient transfer. Single-use diaphragm technologies are displacing stainless steel in multi-product facilities.
- Energy:Refinery turnaround schedules and pipeline maintenance windows drive rental pump demand. Gulf Coast operators consolidate fleets through third-party equipment providers.
- Construction:Portable aluminum skid configurations serve dewatering and concrete pumping applications. Hurricane-prone regions generate seasonal demand spikes for emergency standby capacity.
Manufacturing anchors the installed base while pharmaceutical end users are expanding procurement fastest.
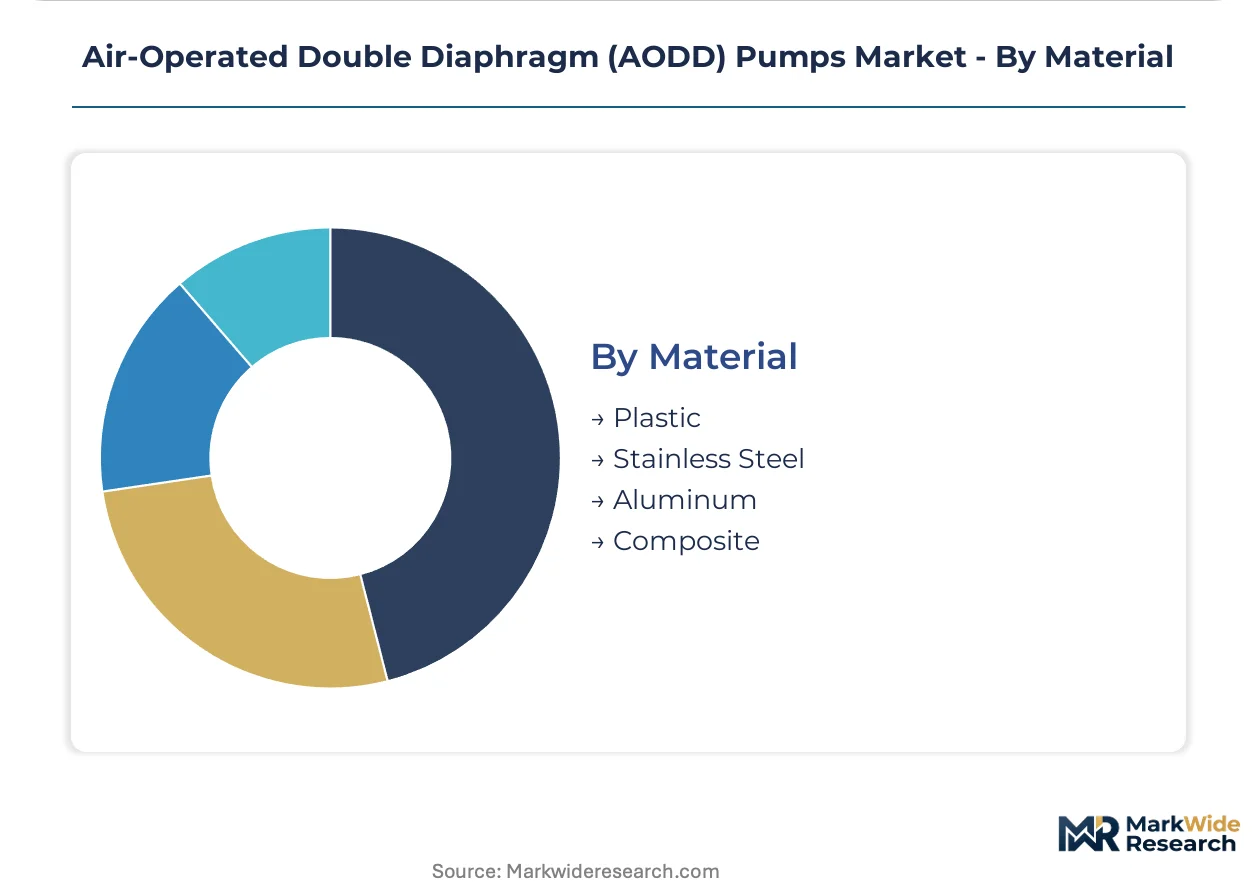
Material:
Supply concentration for specialty elastomers and corrosion-resistant alloys dictates regional sourcing strategies.
- Stainless Steel:316L and duplex grades deliver chemical resistance for pharmaceutical and aggressive chemical duty. Surface finish specifications to Ra 0.8 micrometers satisfy sanitary standards. German chemical processors specify these for sulfuric acid transfer where material integrity governs safety.
- Plastic:Polypropylene, PVDF, and PTFE constructions compete on first cost in water treatment and food processing. Chinese coastal manufacturing provinces favor these for seawater handling where galvanic corrosion destroys metal pumps.
- Aluminum:Lightweight die-cast housings enable portable deployment in construction and mining. Anodized finishes extend service life in abrasive slurry applications.
- Composite:Advanced thermoplastic elastomer compounds replace conventional rubber in mining tailings duty. North American sand and aggregate operators specify these for 40-60% diaphragm life extension.
Stainless steel dominates value capture while plastic materials are climbing fastest in Asian water infrastructure investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA emissions rules and OSHA process safety mandates are compressing replacement cycles for legacy pumping infrastructure across industrialized economies. MIIT efficiency directives in China's coastal provinces are accelerating procurement of next-generation diaphragm pumps. REACH Annex XVII restrictions on perfluorinated chemistries are forcing reformulation investments ahead of 2025-2027 enforcement windows.
United States
Chemical processing plants in Texas and Louisiana are expanding AODD pump procurement as EPA emissions standards tighten process equipment requirements. OSHA process safety management mandates govern equipment selection for hazardous solvent transfer in Gulf Coast refineries. Automotive paint shops in Michigan specify stainless steel configurations for shear-sensitive coating circulation.
Germany
Chemical processors in North Rhine-Westphalia are replacing legacy pumping infrastructure ahead of REACH compliance deadlines. ECHA substance evaluation is accelerating diaphragm reformulation timelines beyond typical product development cycles. BASF-Ludwigshafen and Bayer-Leverkusen clusters drive specification-driven demand for corrosion-resistant alloy constructions.
China
MIIT efficiency mandates are accelerating replacement cycles in Jiangsu and Zhejiang manufacturing provinces. Local air consumption standards favor next-generation diaphragm pumps with optimized pneumatic valve designs. Yangtze River Delta chemical parks are consolidating procurement around certified system suppliers.
Japan
Specialty chemical producers in Osaka and Nagoya clusters face fluoropolymer supply allocation constraints for diaphragm elastomer production. METI industrial efficiency guidelines are driving air consumption optimization in process equipment. Pharmaceutical manufacturers in Kanto region are pre-qualifying non-fluorinated elastomer options.
India
Pharmaceutical manufacturing expansion in Maharashtra and Gujarat is generating demand for cGMP-compliant positive-displacement pumps. CDSCO process equipment validation protocols govern active pharmaceutical ingredient transfer applications. Mumbai-Pune industrial corridor accounts are consolidating spare parts procurement through distributor networks.
Air-Operated Double Diaphragm (AODD) Pumps Market Competitive Environment
Listed leaders compete with private specialists across certification tiers, creating a bifurcated structure where ISO 9001-qualified system suppliers capture specification-driven chemical processing accounts while regional fabricators compete on first cost in utility applications. The vendor base clusters around three strategic archetypes: vertically integrated multinationals with captive elastomer compounding, specialized diaphragm engineering houses, and distributor-network-dependent aftermarket operators. M&A activity concentrates on aftermarket service capabilities and regional distribution control. Technology licensing partnerships are emerging for IoT-enabled air consumption monitoring.
Within the vertically integrated tier, Graco Inc and IDEX Corporation exemplify scale-driven positioning through manufacturing footprint control and spare parts channel dominance. Wilden Pump and Engineering LLC occupies a specialist position anchored in elastomer engineering expertise. Yamada Corporation and Almatec Maschinenbau GmbH represent regional manufacturing champions with proximity advantages in Asian and European chemical processing clusters respectively. Dover Corporation and Aro Fluid Management sit within the diversified industrial conglomerate archetype, leveraging cross-divisional sourcing scale.
| Leading Market Players |
|---|
| Graco Inc |
| Wilden Pump and Engineering LLC |
| Aro Fluid Management |
| Yamada Corporation |
| Sandpiper Pumps |
| Almatec Maschinenbau GmbH |
| Versa-Matic Pump Company |
| IDEX Corporation |
| Dover Corporation |
| Others |
Value Chain & Pricing Dynamics
Capacity utilization at German and Japanese specialty elastomer producers shapes both input cost floors and tiered pricing spreads across the AODD pump market. Scale concentration in perfluoroelastomer compounding creates asymmetric bargaining power that propagates through certified system suppliers to regional fabricators.
Pricing Analysis
Certification level creates the primary spread between ISO 9001-qualified system suppliers and marginal regional fabricators. Three-tier pricing structure across premium FDA-grade stainless steel, standard CE-marked industrial, and economy aluminum portable configurations dominates transactional models. Cost compression in plastic-construction water treatment tiers is intensifying because electric diaphragm alternatives erode volume leverage. Municipal utilities in Florida and construction fleets in Gulf Coast states exhibit highest price sensitivity, while pharmaceutical cGMP-compliant buyers prioritize validation documentation over unit cost.
Supply Chain Analysis
Rhine River logistics corridors and Yokohama port throughput constraints expose diaphragm elastomer flows to weather-related disruption. Fluoropolymer feedstocks concentrate among German and Japanese specialty chemical producers, while corrosion-resistant alloy castings source from Chinese and Indian foundries. Single-source vulnerability in perfluoroelastomer compounding expertise concentrates reformulation risk ahead of REACH enforcement windows. Distribution runs through OEM-direct specification sales for chemical processing accounts and distributor-network spare parts channels for aftermarket service.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aftermarket retrofit kits and predictive maintenance subscriptions are expanding faster than hardware unit sales, reframing competitive advantage around service attach rates and installed base lifetime value.
For Market Incumbents: Secure elastomer compounding capabilities through backward integration or exclusive supply agreements to defend margin position against PFAS-phase-out disruption. Consolidate distributor control in China's Yangtze River Delta chemical parks where MIIT efficiency mandates are compressing replacement timelines and favoring certified suppliers. For New Entrants and Emerging Players: Anchor in modular aftermarket retrofit configurations that enable diaphragm material swaps without full pump replacement, targeting chemical processing installed bases in Germany and the United States facing REACH and EPA compliance deadlines. Pursue technology licensing partnerships for IoT-enabled air consumption monitoring to bypass capital-intensive manufacturing scale requirements. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors vertically integrated specialists with captive elastomer engineering and established aftermarket channels over pure-play hardware manufacturers. Acquisition screening should prioritize targets with diagnostic service revenue streams and multi-site industrial operator relationships. Watch for inflection when non-fluorinated elastomer validation timelines accelerate beyond typical product development cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Elastomer Compounding | Captive supply of perfluoroelastomer alternatives secures margin pools ahead of REACH phase-out deadlines. |
| IoT-Enabled Predictive Maintenance Platform | Air consumption sensors and diaphragm wear algorithms unlock subscription revenue from multi-site operators. |
| CE-MDR Certification Pathway Investment | EU Medical Device Regulation scope expansion opens pharmaceutical process equipment procurement channels. |
| Modular Retrofit Kit Development | Component-level upgrade packages extend service revenue from chemical processing installed bases. |
| Distributor Network Consolidation | Spare parts availability control determines aftermarket capture in China's coastal manufacturing provinces. |
Study Parameters
Operator-level perspectives from maintenance directors at chemical processing plants, OEM procurement teams, aftermarket service heads, and distributor channel managers anchored the qualitative base. Primary interview insights triangulated against customs trade data, SEC manufacturing disclosures, chemical industry association reports, and EPA regulatory filings. Bottom-up unit economics from end-user procurement patterns reconciled with top-down value chain analysis across material grades and certification tiers.
Sensitivity analysis across elastomer cost scenarios, regulatory enforcement timelines, and electric substitution rates tested forecast robustness. Segmentation modeling spanned product type, application vertical, end-user procurement maturity, and material construction grade. CAGRs derived from replacement cycle compression in REACH-affected markets and MIIT-mandated efficiency upgrades in China. Industry-specific inputs included fluoropolymer supply allocation constraints and compressed air infrastructure penetration rates.
Material uncertainties — PFAS restriction enforcement timing, fluoropolymer supply disruption, and electric diaphragm pump substitution velocity — sit outside the modeled envelope. Forecasts reflect documented assumptions about regulatory implementation schedules and technology adoption curves. Practitioners should keep alternative scenarios live as ECHA substance evaluation timelines and METI efficiency guideline revisions evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pumps and Control Devices
Hydraulic Dosing Pump Market
Pumps and Control Devices
Global Hydraulic Submersible Pump Market
Pumps and Control Devices
Bubble Membrane Disc Diffuser Market
Pumps and Control Devices
North America Positive Displacement Pumps Market
Pumps and Control Devices
Global Lobe Pumps Market
Pumps and Control Devices
Chemical Pump Market
Pumps and Control Devices
Rotating Equipment Market
Pumps and Control Devices
Vertical Inline Pumps Market
Pumps and Control Devices
Reverse Osmosis Pump Market
Pumps and Control Devices
Global Submersible Pumps Market
Pumps and Control Devices
United States Subsea Pumps Market
Pumps and Control Devices
Energy-Saving Canned Motor Pump Market
Pumps and Control Devices
North America Dispensing Pumps Market
Pumps and Control Devices
Latin America Pumps Market
Pumps and Control Devices
Seawater Cooling Pumps Market
Pumps and Control Devices
Axial Piston Pumps Market