
 Global Vacuum Pump Market | 2026-2036
Global Vacuum Pump Market Size, Share, and Industry Trends Forecast 2026-2036
Global Vacuum Pump Market Outlook
The performance gap between premium dry vacuum systems and commodity oil-sealed units is expanding as semiconductor fabs demand contamination-free process environments. Atlas Copco AB leverages its compressor technology heritage to anchor positions in industrial vacuum, while Pfeiffer Vacuum specializes in high-vacuum solutions for analytical instruments and research. Edwards Vacuum dominates semiconductor dry pump supply through extensive installed bases in leading fabs.
A vacuum pump is a mechanical device that removes gas molecules from a sealed volume to create partial or complete vacuum, typically achieving ultimate pressures from rough vacuum (above 10⁻³ mbar) through ultra-high vacuum (below 10⁻⁹ mbar) depending on pump architecture and staging configuration. Its primary industrial purpose is to enable processes requiring controlled gas environments, from thin-film deposition to degassing and freeze-drying operations. Rotary vane pumps retain the largest installed base across general industrial applications, though scroll technology is displacing them in cleanroom settings where oil backstreaming poses yield risks. Semiconductor application demand commands the highest unit margins, while food processing represents a stable replacement-driven volume pool with less technology volatility.
EPA emissions guidelines in the United States restrict volatile organic compound releases from oil-sealed pump exhausts, while REACH in Europe mandates chemical safety documentation for lubricants and sealing materials used in vacuum equipment. These frameworks compel manufacturers to reformulate fluids and accelerate dry pump development timelines. Stakeholders must monitor evolving fluorinated gas restrictions across multiple jurisdictions, as lubricant chemistry choices increasingly determine market access rather than merely product performance.
Market Dynamics
Semiconductor node shrinkage below 7nm is forcing fabs to abandon oil-sealed pumps entirely, creating a bifurcation between contamination-capable and contamination-intolerant process equipment. This technical threshold is restructuring supplier relationships and capital allocation across the vacuum equipment value chain.
Growth Catalysts
- China's domestic foundry buildouts:Massive state-backed investments in semiconductor self-sufficiency are concentrating demand for dry vacuum systems in Shanghai, Beijing, and Hefei manufacturing clusters.
- EU F-Gas Regulation phase-down:Restrictions on fluorinated lubricants are accelerating substitution toward oil-free scroll and screw pump architectures in European pharmaceutical and chemical processing.
- Advanced packaging expansion:Fan-out wafer-level packaging and 3D integration processes require ultra-clean vacuum environments that only dry pump technologies can reliably deliver.
Market Restraints
- Specialized metallurgy costs:Dry pumps require corrosion-resistant coatings and exotic alloys that inflate unit manufacturing costs versus conventional cast iron rotary vane constructions.
- Chinese supply concentration:Rare earth magnet dependencies for high-efficiency motor drives create vulnerability to export control disruptions from dominant Chinese processors.
- Ultimate pressure limitations:Single-stage dry pumps cannot achieve the deep vacuum levels required for certain electron microscopy and mass spectrometry applications without costly multi-stage configurations.
Strategic Opportunities
- India's PLI scheme for semiconductors:Production-linked incentives are attracting fabs to Gujarat and Tamil Nadu, creating virgin installed base demand for contamination-free vacuum infrastructure.
- Hydrogen economy infrastructure:Electrolyzer manufacturing and fuel cell production require specialized vacuum drying and leak detection equipment with performance specifications distinct from semiconductor applications.
- Digital twin integration:IoT-enabled predictive maintenance platforms allow pump OEMs to capture recurring software and service revenue streams alongside hardware sales.
Industry Challenges
- Vacuum engineering talent scarcity:The specialized knowledge required for molecular flow simulation and outgassing analysis is concentrated among aging specialists in Germany, Japan, and the United States.
- Legacy system integration friction:Retrofitting dry pumps into existing fabs with oil-sealed infrastructure requires custom plumbing, control system reprogramming, and process requalification that extends deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Vacuum Pump Market |
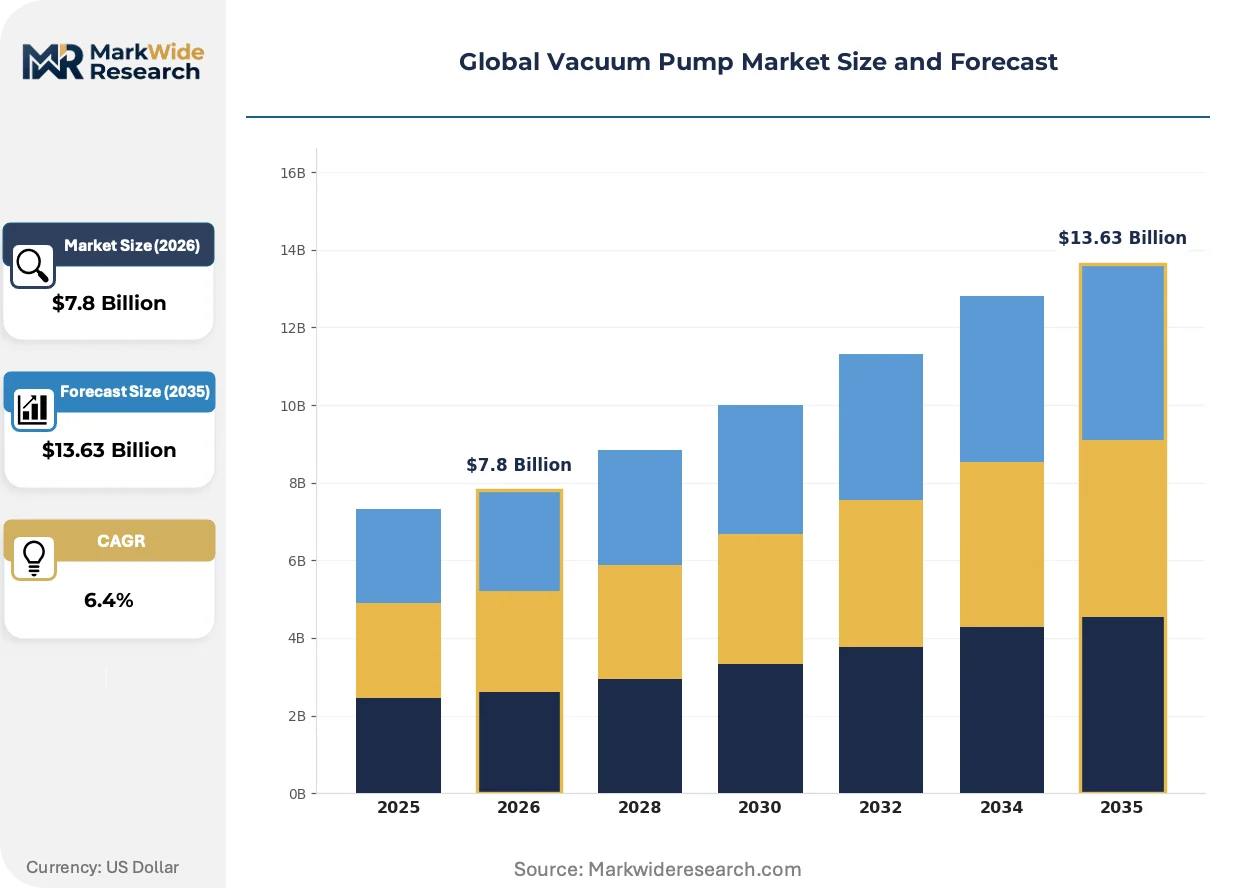
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $13.63 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rotary Vane, Diaphragm, Scroll, Liquid Ring Application: Semiconductor, Packaging, Food Processing, Chemical Processing End User: Manufacturing, Pharmaceuticals, Electronics, Automotive Technology: Electric, Pneumatic, Magnetic, Hybrid |
| Companies Covered | Edwards Vacuum, Ingersoll Rand, Atlas Copco AB, Leybold, Flowserve Corporation, Busch Vacuum Solutions, ULVAC Inc., Agilent Technologies, Pfeiffer Vacuum, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Vacuum Pump Market Strategic Shifts
Dry vacuum technology is consolidating its position as the default architecture for contamination-sensitive manufacturing, while regulatory chemistry restrictions and service model digitization reshape competitive boundaries. These intersecting forces are compressing the viable technology set and elevating aftermarket capabilities as differentiation vectors.
Variable pitch screw technology is consolidating market preference for medium-vacuum roughing applications. Semiconductor fabs in Taiwan and South Korea are specifying these pumps for CVD and etch processes previously served by scroll architectures. The technology's tolerance to particulate carryover and reduced power consumption is consolidating supplier margins by extending mean time between overhauls beyond 30,000 hours.
REACH authorization requirements for per- and polyfluoroalkyl substances are forcing reformulation of fluorinated vacuum pump fluids across European chemical and pharmaceutical manufacturing. Equipment operators face mandatory substitution timelines that compress technology transition windows. German and Swiss pharmaceutical clusters are responding by accelerating capital deployment toward oil-free systems that eliminate fluid compliance exposure entirely.
Performance-based service contracting is displacing traditional break-fix maintenance relationships in high-availability semiconductor fabs. Equipment uptime guarantees with penalty clauses are transferring operational risk from fabs to pump OEMs. This model is most advanced in Taiwan's foundry ecosystem, where TSMC and UMC procurement specifications now require 99.5% availability commitments with sub-4-hour response SLAs.
Global Vacuum Pump Market Segmentation
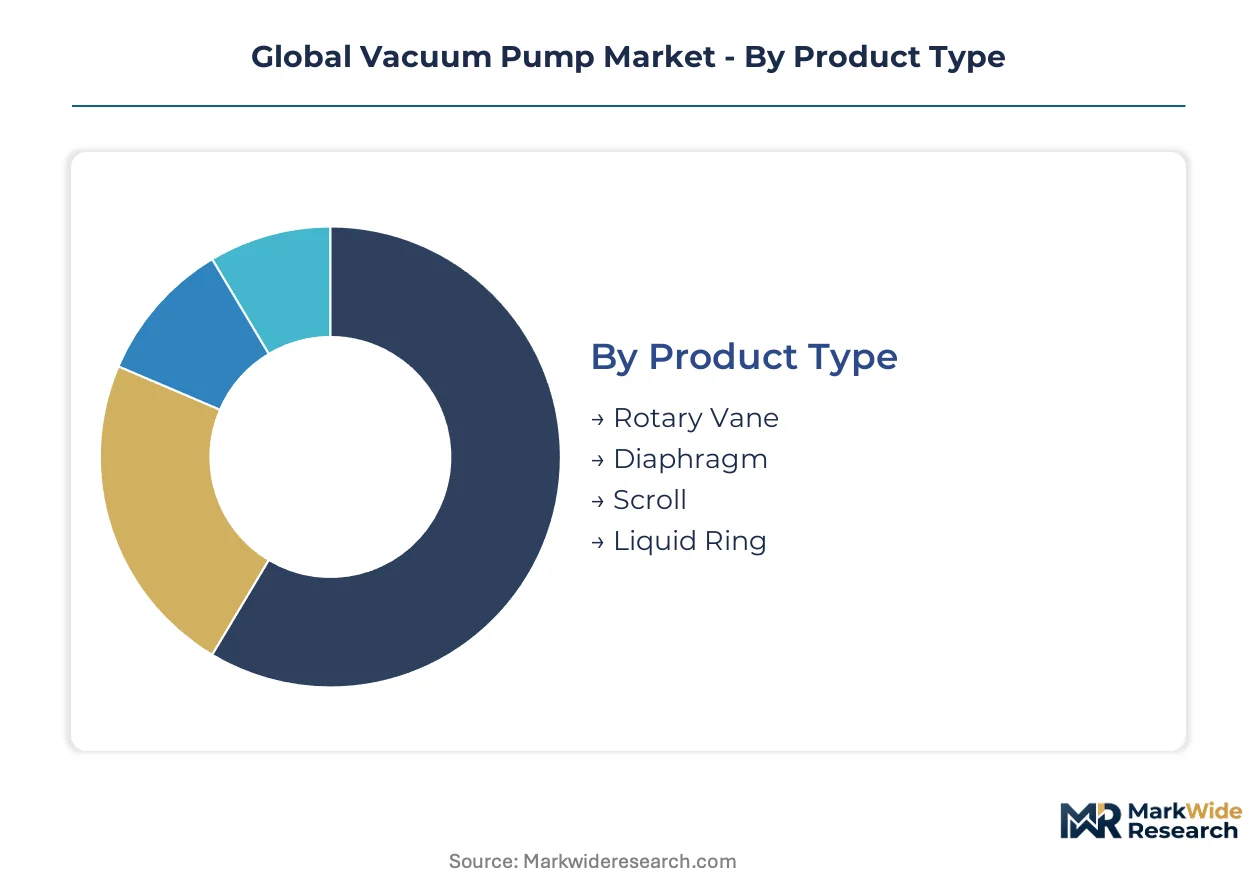
Vacuum pump architecture and application environments determine contamination tolerance, energy consumption, and maintenance intervals. Segment boundaries reflect irreversible technical transitions in semiconductor manufacturing and tightening chemical regulations across industrial jurisdictions.
Product Type:
Technical specifications around lubrication chemistry and ultimate pressure capability define competitive positioning across pump architectures.
- Rotary Vane:Oil-sealed positive displacement pumps achieve ultimate pressures near 10⁻³ mbar through eccentric rotor-vane compression. Demand concentrates in legacy chemical processing facilities across Germany's Ruhr industrial cluster, constrained by EPA emissions guidelines and REACH lubricant documentation burdens that extend procurement cycles.
- Scroll:Orbiting spiral plate architecture eliminates lubricant entirely through tip-seal contact geometry. Newer deployment concentrates in Taiwan's Hsinchu Science Park semiconductor fabs, driven by sub-7nm node contamination intolerance that bans oil-sealed alternatives from etch and deposition processes.
- Diaphragm:Reciprocating elastomer membrane separates process gas from mechanical drive. Pharmaceutical lyophilization in Swiss and German clusters favors this architecture for sterile product contact surfaces.
- Liquid Ring:Impeller-driven sealing liquid forms compressible annular ring. Paper manufacturing and geothermal gas extraction in Indonesia and the Philippines deploy these for wet gas tolerance.
Mature deployment sits with Rotary Vane systems. Newer deployment is concentrated in Scroll architectures.
Application:
Process contamination sensitivity and throughput requirements stratify demand across industrial verticals.
- Semiconductor:Dry vacuum infrastructure enabling sub-7nm node manufacturing commands premium positioning through contamination-free process integration.
- Packaging:Modified atmosphere packaging for protein products drives vacuum demand in Brazilian and Australian food export corridors.
- Food Processing:Freeze-drying and vacuum cooling operations in California's Central Valley and France's Brittany dairy cluster require hygienic pump architectures with CIP compatibility.
- Chemical Processing:Solvent recovery and distillation operations in India's Gujarat chemical belt and Saudi Arabia's Jubail Industrial City deploy corrosion-resistant pump specifications.
Volume concentration favors Food Processing. Value capture climbs steepest in Semiconductor applications.
End User:
Capital intensity and uptime requirements differentiate procurement patterns across buyer categories.
- Manufacturing:General industrial vacuum demand spans automotive component degassing in Mexico's Bajío region and composite autoclave operations in Italy's Emilia-Romagna aerospace cluster.
- Pharmaceuticals:Sterile manufacturing environments in Ireland's Cork pharmaceutical hub and Singapore's Tuas biomedical park mandate oil-free pump architectures with full batch traceability.
- Electronics:Display panel fabrication in South Korea's Gumi industrial complex and Vietnam's Bac Ninh province concentrates demand for ultra-clean roughing and high-vacuum systems.
- Automotive:Battery cell manufacturing in Hungary's Debrecen and Poland's Lower Silesia requires specialized vacuum drying for electrolyte impregnation processes.
Replacement cycle stability sits with Manufacturing. Technology transition velocity peaks in Electronics.
Technology:
Drive system architecture determines efficiency profiles and maintenance accessibility across installation environments.
- Electric:Variable frequency motor drives dominate installed base across all regions, with efficiency regulations in Japan's Top Runner program and EU Ecodesign directives accelerating premium motor adoption.
- Pneumatic:Compressed air-driven venturi systems serve hazardous area classifications in Norwegian offshore platforms and Australian mining operations where electrical ignition risks prohibit standard motors.
- Magnetic:Rare earth magnet synchronous motors eliminate mechanical bearings for hermetic sealing in nuclear fuel processing and tritium handling facilities.
- Hybrid:Combined electric-pneumatic architectures optimize energy recovery in large-scale semiconductor fabs in Shanghai and Hefei.
Standard deployment sits with Electric systems. Specialized deployment concentrates in Magnetic configurations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hsinchu Science Park concentrates the world's most advanced semiconductor vacuum infrastructure. Taiwan's foundry ecosystem commands premium dry pump specifications that define global technology roadmaps. National industrial policies across three continents are reshaping supplier access and procurement patterns.
China
Shanghai, Beijing, and Hefei manufacturing clusters are absorbing massive dry vacuum system deployment from state-backed foundry buildouts. MIIT domestic equipment procurement mandates and dual carbon goals are accelerating substitution away from imported oil-sealed architectures. Yangtze Memory Technologies and SMIC fabs in Shanghai's Lingang New Area specify contamination-free roughing pumps for sub-14nm pilot lines.
United States
EPA emissions guidelines restrict volatile organic compound releases from oil-sealed pump exhausts across chemical processing corridors. CHIPS Act subsidies are reshoring advanced logic fabrication to Arizona and Texas, creating virgin installed base demand for ultra-clean vacuum infrastructure. Intel's Ocotillo campus in Chandler and Samsung's Taylor expansion are specifying dry pump architectures from project inception.
Germany
REACH authorization requirements for per- and polyfluoroalkyl substances are forcing fluorinated vacuum pump fluid reformulation across pharmaceutical manufacturing. The Ruhr industrial cluster's legacy chemical facilities face extended procurement cycles for lubricant documentation compliance. BASF and Bayer operations in Ludwigshafen are accelerating capital deployment toward oil-free systems that eliminate fluid compliance exposure entirely.
South Korea
Samsung and SK Hynix memory fabs in Gumi and Icheon are specifying variable pitch screw pumps for CVD and etch processes. METI-equivalent efficiency regulations and national semiconductor self-sufficiency programs are concentrating procurement through domestic equipment integrators. Yongin semiconductor cluster expansion is transferring Taiwanese performance-based service contracting models with 99.5% uptime guarantees.
Switzerland
Swissmedic pharmaceutical manufacturing standards and REACH-aligned chemical safety documentation mandate oil-free pump architectures in Basel and Geneva biologics corridors. Roche and Novartis sterile manufacturing facilities specify diaphragm and scroll technologies with full batch traceability. Swiss pharmaceutical clusters are responding to fluorinated lubricant phase-downs by eliminating fluid-bearing systems entirely from validated processes.
Global Vacuum Pump Market Competitive Environment
Premium-margin players sit above commodity-margin players across contamination tolerance and service integration capabilities. The market structures around three tiers: integrated industrial conglomerates with compressor technology heritage, specialized high-vacuum technology houses, and regional fabrication specialists serving replacement demand. Consolidation pressures favor players with captive semiconductor fab relationships and predictive maintenance platform deployment. Technology licensing and geographic expansion through local integrator partnerships represent the dominant competitive moves reshaping supplier access.
Within the integrated industrial tier, Atlas Copco AB and Ingersoll Rand occupy positions anchored by compressor technology heritage and broad industrial distribution networks. Edwards Vacuum exemplifies the semiconductor-specialist archetype through extensive dry pump installed bases in leading foundries. Pfeiffer Vacuum represents the high-vacuum analytical instrumentation segment with research and mass spectrometry positioning. Busch Vacuum Solutions and Leybold sit within European-rooted industrial vacuum traditions serving chemical and food processing replacement cycles.
| Leading Market Players |
|---|
| Edwards Vacuum |
| Ingersoll Rand |
| Atlas Copco AB |
| Leybold |
| Flowserve Corporation |
| Busch Vacuum Solutions |
| ULVAC Inc. |
| Agilent Technologies |
| Pfeiffer Vacuum |
| Others |
Value Chain & Pricing Dynamics
Vacuum engineering specialists concentrated in Stuttgart, Dresden, and Aachen command wage premiums that compress margin spreads between premium dry pump tiers and commodity rotary vane alternatives. This labor-cost differential propagates through final pricing, widening the gap between contamination-intolerant semiconductor specifications and general industrial replacement cycles.
Pricing Analysis
Equipment uptime guarantees anchor value-based pricing in Taiwan's foundry ecosystem, where TSMC procurement specifications mandate 99.5% availability commitments with sub-4-hour response SLAs. Three-tier pricing structure across premium, standard, and economy levels differentiates by contamination tolerance certification and mean-time-between-overhaul metrics. Cost compression in the economy tier intensifies because Chinese domestic equipment procurement mandates under MIIT directives are accelerating local manufacturing scale. Semiconductor fabs exhibit the lowest price sensitivity, while general chemical processing facilities in legacy Ruhr industrial clusters prioritize capital expenditure minimization over performance specifications.
Supply Chain Analysis
Regional distribution centers in Rotterdam, Singapore, and Los Angeles coordinate hub-and-spoke patterns for spare parts and consumables, positioning inventory within 48-hour reach of major semiconductor clusters. Manufacturing concentration in Germany, Japan, and the United States draws from rare earth magnet dependencies for high-efficiency motor drives sourced through dominant Chinese processors. Single-source vulnerability in fluorinated lubricant formulations creates exposure to REACH authorization timelines. Distribution runs through authorized service integrators who bundle installation, commissioning, and predictive maintenance contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH and EU F-Gas Regulation compliance costs erect barrier-to-entry moats that protect incumbent positions while forcing laggards toward asset obsolescence. Fluorinated lubricant phase-downs and documentation burdens favor players with pre-positioned oil-free architectures.
For Market Incumbents: Hedge against Chinese supply concentration by securing alternative rare earth magnet sourcing through Australian and Vietnamese channels. Accelerate predictive maintenance platform deployment to capture recurring software revenue and lock in fab relationships before digital twin integration becomes standard procurement specification. For New Entrants and Emerging Players: The price-point gap between premium dry semiconductor pumps and economy rotary vane units creates entry space for mid-tier scroll architectures targeting India's PLI-driven fab buildouts in Gujarat and Tamil Nadu. Focus initial penetration on pharmaceutical lyophilization applications in Swiss and German clusters where batch traceability requirements favor new supplier relationships over legacy equipment loyalty. For Investors and Strategic Acquirers: Re-rating potential sits with semiconductor-specialist service integrators given the transfer of performance-based contracting models from Taiwan to South Korea and China. Long-term viability hinges on captive fab relationships and aftermarket platform deployment. Monitor MIIT domestic equipment procurement mandate enforcement intensity as inflection indicator for imported technology access windows.| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Maintenance Platform Launch | Captures recurring revenue from TSMC and UMC uptime guarantee contracts. |
| Backward Integration into Rare Earth Magnet Supply | Mitigates export control exposure from dominant Chinese processors. |
| Fluorinated Lubricant Elimination Program | Preempts REACH authorization timelines in German pharmaceutical clusters. |
| India PLI Scheme Localization Partnership | Positions for virgin installed base demand in Gujarat semiconductor corridor. |
| Variable Pitch Screw Technology Licensing | Accelerates displacement of scroll architectures in Korean CVD applications. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with vacuum pump OEM product managers, fab facilities engineers, and aftermarket service heads combined with ECHA substance registration databases, EPA emissions compliance records, and semiconductor equipment customs classifications. Bottom-up unit demand modeling triangulated against top-down industrial capital expenditure surveys.
Data-stream reconciliation across shipment volumes, fab equipment procurement disclosures, and lubricant formulation registrations calibrated the analytical framework across the projection horizon. Segmentation dimensions modeled include pump architecture, contamination tolerance tier, end-use industry vertical, and regional regulatory cluster. CAGRs derived from installed base growth rates, replacement cycle compression, and technology substitution curves. Forecast inputs incorporated MIIT domestic equipment mandates and EU F-Gas phase-down schedules.
Inputs from ECHA, EPA, and MIIT regulatory databases were available through the study window; gaps in real-time fab capital expenditure timing introduce uncertainty bands around near-term demand inflection points. Forecasts reflect assumptions regarding node shrinkage velocity, rare earth supply stability, and REACH enforcement consistency. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pumps and Control Devices
Vertical Inline Pumps Market
Pumps and Control Devices
Cryogenic Process Pumps Market
Pumps and Control Devices
Centrifugal Pumps Machines Market
Pumps and Control Devices
Global Hydraulic Gear Pump Market
Pumps and Control Devices
North America Axial Flow Pump Market
Pumps and Control Devices
Lubrication Pump Systems Market
Pumps and Control Devices
Ultra High Pressure Water Pump Market
Pumps and Control Devices
Radial Piston Pumps Market
Pumps and Control Devices
Heating Tape Market
Pumps and Control Devices
Turbomolecular Pumps Market
Pumps and Control Devices
Horizontal Pumping Systems (HPS) Market
Pumps and Control Devices
Spiral Classifier Market
Pumps and Control Devices
North America Positive Displacement Pumps Market
Pumps and Control Devices
Water Desalination Pumps Market
Pumps and Control Devices
Energy-Saving Canned Motor Pump Market
Pumps and Control Devices
Progressing Cavity Pump Market