
 Asia Pacific Vacuum Pumps Market | 2026-2036
Asia Pacific Vacuum Pumps Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Vacuum Pumps Market Outlook
Aftermarket service revenue is narrowing as original equipment manufacturers bundle predictive maintenance contracts with new unit sales. Atlas Copco leverages its compressor service infrastructure to cross-sell vacuum pump lifecycle agreements across Southeast Asian manufacturing corridors. Ebara Corporation anchors its position through captive supply of precision cast components for its own dry pump assemblies. ULVAC Inc. specializes in high-purity oil-free systems for semiconductor wafer processing, commanding premium positioning in Japanese and Taiwanese fabs.
Vacuum pumps are mechanical devices that remove gas molecules from sealed chambers to create pressure differentials below atmospheric levels, typically achieving ultimate pressures from rough vacuum through ultra-high vacuum ranges depending on pump architecture. These systems employ rotary vane, screw, claw, or turbomolecular mechanisms to sustain process environments for deposition, distillation, or contamination-free handling. Positive displacement pumps retain dominance in chemical processing and general industrial duty cycles where robustness outweighs ultimate vacuum requirements. Kinetic technology captures expanding share in electronics manufacturing as dry screw and multistage roots configurations displace oil-sealed alternatives in cleanroom environments. Oil-free technology leads technology segmentation as pharmaceutical companies and semiconductor industry end users enforce particulate-free process guarantees.
Japan's METI enforces Top Runner efficiency standards that compel vacuum pump manufacturers to document power consumption curves across operating envelopes. China's MEE implements emission controls that restrict hydrocarbon discharge from oil-sealed pump exhaust streams in populated industrial zones. South Korea's MFDS and KOSHA jointly regulate workplace exposure limits that accelerate substitution of oil-sealed systems with dry vacuum technology in pharmaceutical manufacturing plants. Stakeholders must monitor evolving efficiency benchmarks across these regulatory regimes to anticipate product certification requirements and manufacturing relocation incentives.
Market Dynamics
East Asian semiconductor foundries are consolidating vacuum pump specifications around dry screw architectures, forcing manufacturers to abandon oil-sealed legacy platforms and requalify entire product lines for sub-10 nanometer process nodes.
Growth Catalysts
- Dual Carbon Goals:China's MEE emission mandates are accelerating replacement cycles for hydrocarbon-emitting oil-sealed pumps in chemical processing corridors around Shanghai and Ningbo.
- Memory Chip Cluster Expansion:Pyeongtaek and Yongin foundry zones are scaling lithography tool installations, each requiring matched high-purity vacuum systems for wafer handling.
- Top Runner Standards:Japan's METI efficiency benchmarks compel documented power consumption curves, creating certification barriers that favor established dry pump suppliers.
Market Restraints
- Precision Casting Bottleneck:Captive supply of corrosion-resistant pump housings concentrates among Japanese and Korean foundries, limiting capacity expansion for second-tier assemblers.
- Fluoropolymer Cost Volatility:Dry pump seal materials face feedstock price swings tied to fluorspar concentrate availability from Mongolian and Chinese mines.
- Technical Ceiling in Ultra-High Vacuum:Turbomolecular pump architectures hit performance limits below 10^-9 mbar for next-generation quantum computing substrate preparation.
Strategic Opportunities
- Vietnam Electronics Corridor:Northern industrial zones around Bac Ninh and Hai Phong lack qualified vacuum service infrastructure, creating first-mover advantage for lifecycle contract providers.
- Hydrogen Economy Interface:Electrolyzer and fuel cell membrane manufacturing requires oil-free roughing pumps, opening adjacent market entry for semiconductor-qualified suppliers.
- AI-Enabled Predictive Maintenance:Sensor-integrated pump fleets allow remote vibration monitoring, shifting revenue from emergency repairs to subscription uptime guarantees.
Industry Challenges
- Cryogenic Pump Specialist Shortage:Turbomolecular bearing alignment and magnetic levitation calibration demand physics-trained technicians scarce across Southeast Asian service networks.
- Fab Tool Integration Complexity:Vacuum pump control protocols must synchronize with AMHS wafer transport and chamber pressure management, extending commissioning timelines.
- Cross-Border Certification Lag:Separate MFDS, PMDA, and NMPA approval tracks for pharmaceutical-grade oil-free systems delay regional product launches by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Vacuum Pumps Market |
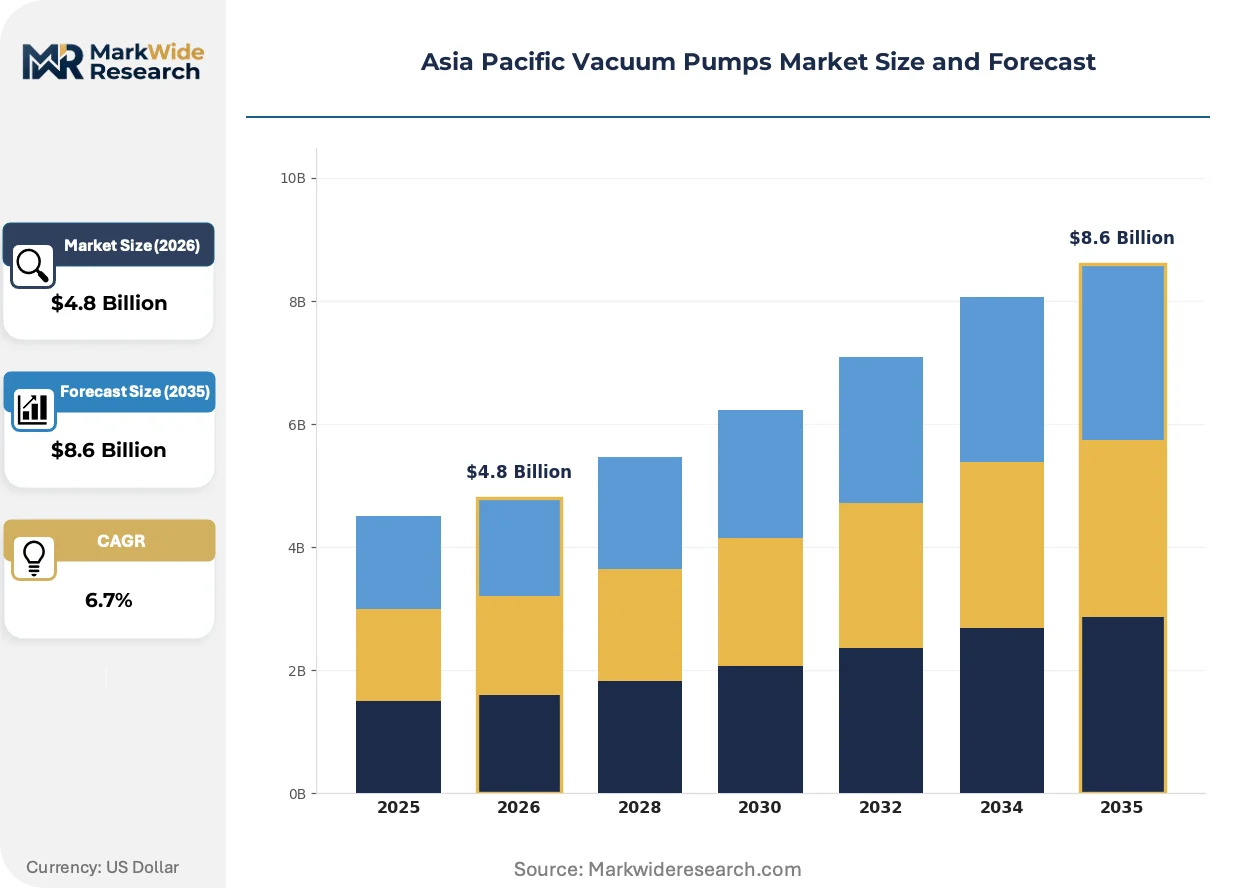
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Positive Displacement, Kinetic, Hybrid, Liquid Ring Application: Chemical Processing, Food Packaging, Electronics Manufacturing, Medical Devices End User: Manufacturing Plants, Research Laboratories, Pharmaceutical Companies, Semiconductor Industry Technology: Oil-Free, Oil-Sealed, Dry Vacuum, Regenerative |
| Companies Covered | Atlas Copco, Ebara Corporation, Agilent Technologies Inc., Flowserve Corporation, Wintek Corporation, ULVAC Inc., Busch Vacuum Solutions, Tsurumi Manufacturing Co Ltd, Ingersoll Rand Inc, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Vacuum Pumps Market Strategic Shifts
Dry vacuum architectures are capturing process tool specifications previously reserved for oil-sealed alternatives, while regulatory pressure on energy consumption and particulate emissions accelerates qualification timelines for next-generation platforms.
Multistage roots blower technology is hybridizing with variable frequency drive controls to deliver precise pumping speed modulation across semiconductor etch process recipes. Memory foundries in South Korea and Taiwan are specifying these configurations for atomic layer deposition chambers. The convergence is compressing demand for fixed-speed legacy pumps and rewarding suppliers with embedded control software capabilities.
China's MEE is tightening hydrocarbon discharge permits for oil-sealed pump exhaust streams in populated industrial zones, effectively banning wet pump deployments near urban centers. Chemical processing operators in Jiangsu and Zhejiang provinces face retrofit deadlines or relocation penalties. Dry screw and claw pump suppliers are capturing replacement demand with lease-to-own financing structures.
Service contract unbundling is fragmenting traditional aftermarket revenue streams as semiconductor fabs negotiate direct spare parts procurement and self-perform routine maintenance. Equipment lessors in Japanese and Taiwanese markets are responding with performance-based contracts that guarantee uptime rather than specifying labor hours. The shift is most visible in 300mm wafer facilities where tool availability penalties exceed service contract values.
Asia Pacific Vacuum Pumps Market Segmentation
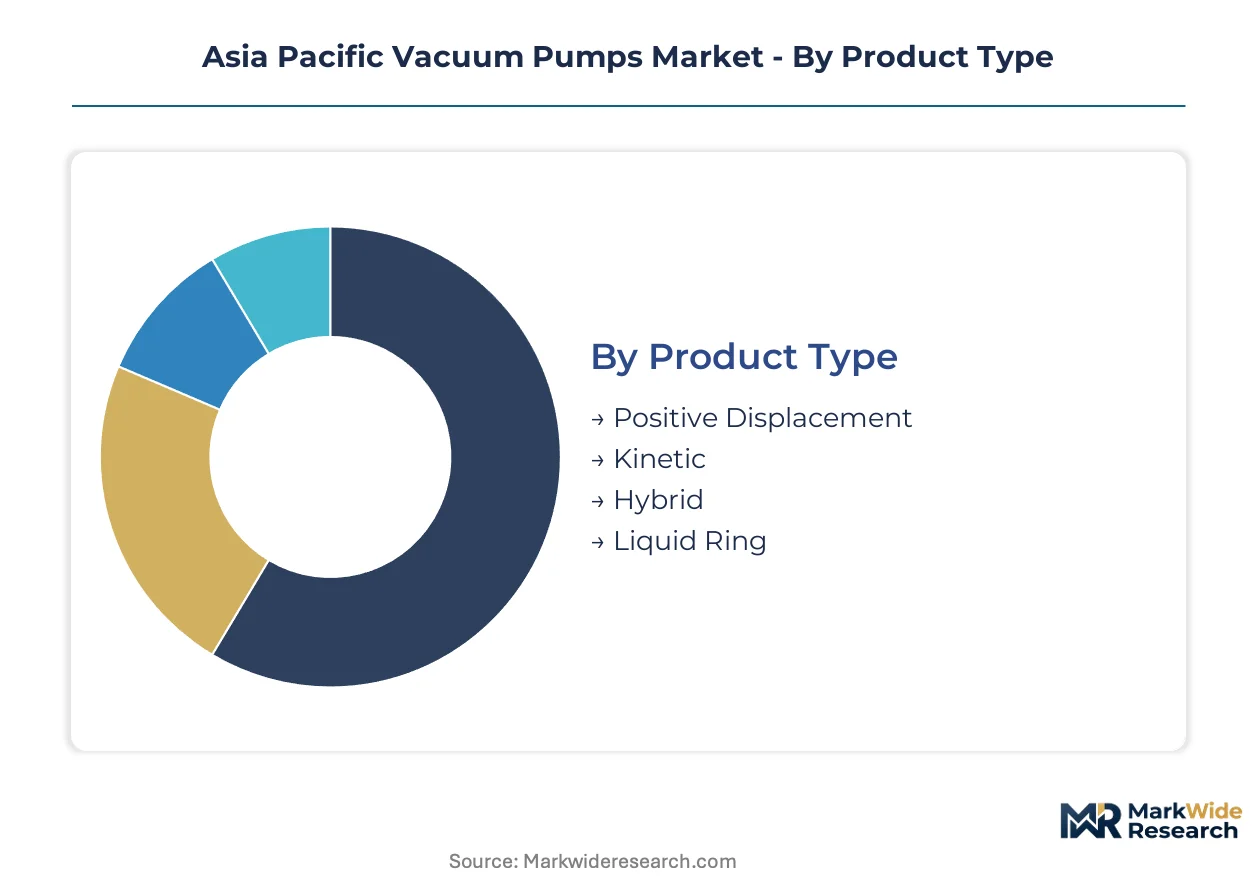
Vacuum pump procurement across Asia Pacific follows divergent technical specifications by end-use environment, with semiconductor fabs demanding molecular-level purity while chemical processors prioritize corrosion resistance. Segmentation reveals how regional regulatory regimes and industry cluster locations reshape product mix priorities across national markets.
Product Type:
Cost tier differentiation separates legacy platforms from precision-engineered architectures, with capital intensity and operating envelope determining adoption patterns across industrial verticals.
- Positive Displacement:Rotary vane and claw mechanisms dominate rough vacuum duty cycles through robust sealing against particulate contamination. Chemical processing corridors around Shanghai and Ningbo specify these units for distillation and solvent recovery operations facing China's MEE emission enforcement.
- Kinetic:Turbomolecular and drag pump configurations achieve ultra-high vacuum through momentum transfer to gas molecules. South Korean memory foundries in Pyeongtaek deploy these systems for atomic layer deposition chambers requiring sub-10^-6 mbar base pressures.
- Hybrid:Multistage roots blower combinations with variable frequency drives modulate pumping speed across etch process recipes. Japanese METI efficiency documentation requirements favor these architectures for documented power consumption curves.
- Liquid Ring:Water-sealed compression handles saturated vapor loads in pharmaceutical solvent recovery. Taiwanese bulk chemical manufacturers specify these for explosion-proof duty in acetic acid vapor streams.
Positive Displacement commands the established base. The steepest expansion runs through Kinetic technology.
Application:
Application segmentation tracks how process environment constraints—purity thresholds, chemical compatibility, throughput demands—dictate pump architecture selection.
- Chemical Processing:Distillation, drying, and solvent recovery operations expose pumps to corrosive vapor streams. Jiangsu and Zhejiang province operators face retrofit deadlines as China's MEE tightens hydrocarbon discharge permits near urban centers.
- Food Packaging:Modified atmosphere packaging and vacuum sealing demand oil-free compression to prevent product contamination. Australian meat processing corridors specify hygienic-design rotary lobe pumps for export certification compliance.
- Electronics Manufacturing:Semiconductor lithography and etching tools require matched high-purity vacuum systems for wafer handling. East Asian foundry clusters concentrate procurement for sub-10 nanometer process node qualification.
- Medical Devices:Sterilization and diagnostic equipment manufacturing enforces particulate-free process guarantees. Japan's PMDA and South Korea's MFDS jointly regulate workplace exposure limits that accelerate dry vacuum substitution.
Electronics Manufacturing captures premium pricing. Chemical Processing shows the fastest volume climb as emission mandates force replacement cycles.
End User:
Customer type segmentation reflects divergent procurement authority structures, with centralized fab tool purchasing contrasting fragmented plant-level decision making.
- Manufacturing Plants:General industrial operators prioritize mean time between failures and local service response. Southeast Asian manufacturing corridors lack qualified vacuum infrastructure, creating lifecycle contract opportunities.
- Research Laboratories:Universities and national institutes specify custom pumping stations for materials science and physics applications. Australian synchrotron facilities drive demand for ultra-high vacuum turbomolecular arrays.
- Pharmaceutical Companies:Sterile manufacturing and active pharmaceutical ingredient synthesis enforce oil-free process guarantees. Cross-border certification lag across MFDS, PMDA, and NMPA approval tracks delays regional product launches.
- Semiconductor Industry:Memory and logic foundries consolidate specifications around dry screw architectures, forcing manufacturers to abandon oil-sealed legacy platforms. Tool integration complexity extends commissioning timelines for AMHS synchronization.
Manufacturing Plants anchor volume throughput. Semiconductor Industry delivers margin expansion through specification tightening.
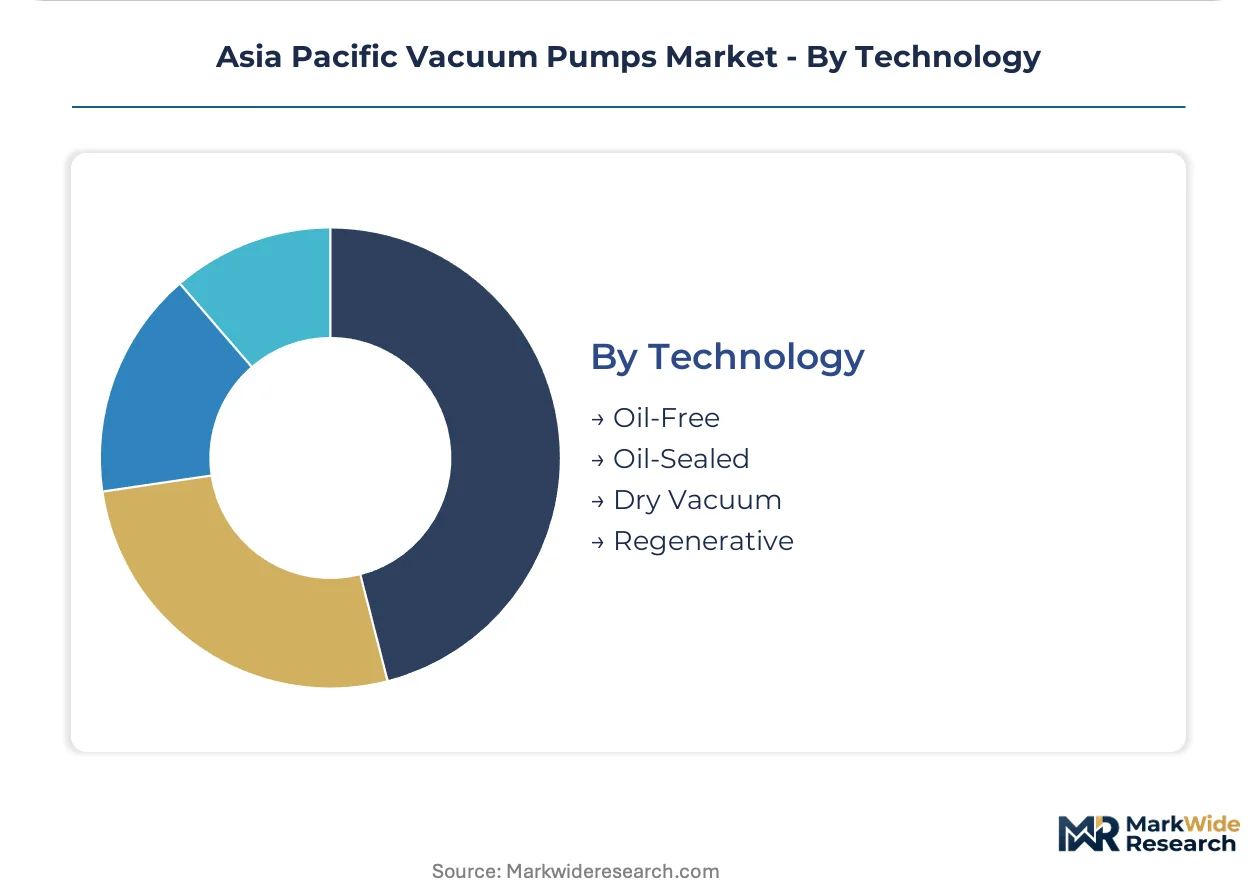
Technology:
Technology segmentation captures the displacement of oil-sealed architectures by dry alternatives, driven by regulatory pressure on emissions and particulate contamination.
- Oil-Free:Dry screw and claw configurations eliminate hydrocarbon contamination risk for pharmaceutical and semiconductor process guarantees. China's MEE effectively bans wet pump deployments near urban centers, accelerating replacement demand.
- Oil-Sealed:Rotary vane and piston pumps retain cost advantage in general industrial applications where ultimate vacuum requirements are modest. Legacy installed base concentrates in chemical processing corridors facing retrofit deadlines.
- Dry Vacuum:Multistage roots and screw architectures dominate new fab tool specifications previously reserved for oil-sealed alternatives. Memory foundries in South Korea and Taiwan specify these for atomic layer deposition chamber matching.
- Regenerative:Side-channel blowers deliver intermediate vacuum for pneumatic conveying and holding applications. Food packaging lines across Thailand and Vietnam deploy these for cost-sensitive modified atmosphere operations.
Oil-Sealed retains installed base dominance. Dry Vacuum posts the steepest share gain trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across the region. Semiconductor fabs in South Korea and Taiwan absorb premium pricing for contamination-free systems without volume reduction. Chemical processors in Southeast Asia face capital constraints that compress procurement timelines and favor refurbished units.
China
Dual carbon goals and MEE emission mandates are accelerating replacement cycles for hydrocarbon-emitting oil-sealed pumps. Chemical processing corridors around Shanghai and Ningbo face retrofit deadlines or relocation penalties. Dry screw and claw pump suppliers are capturing replacement demand with lease-to-own financing structures.
Japan
METI enforces Top Runner efficiency standards that compel documented power consumption curves across operating envelopes. Certification barriers favor established dry pump suppliers with embedded control software capabilities. Precision cast component supply concentrates around Nagoya and Osaka industrial zones.
South Korea
MFDS and KOSHA jointly regulate workplace exposure limits that accelerate substitution of oil-sealed systems with dry vacuum technology. Memory chip foundry clusters around Pyeongtaek and Yongin are scaling lithography tool installations. Each tool requires matched high-purity vacuum systems for wafer handling.
Taiwan
Semiconductor fabs consolidate specifications around dry screw architectures for sub-10 nanometer process node qualification. Tool integration complexity extends commissioning timelines for AMHS synchronization. Tainan and Hsinchu science parks concentrate procurement authority for centralized fab tool purchasing.
Vietnam
Northern industrial zones around Bac Ninh and Hai Phong lack qualified vacuum service infrastructure. Electronics manufacturing investment is outpacing technical support capacity. Lifecycle contract providers gain first-mover advantage through predictive maintenance subscription models.
Asia Pacific Vacuum Pumps Market Competitive Environment
Capability concentration sits with established Japanese and European manufacturers; scale advantage sits with diversified industrial conglomerates with compressor service infrastructure. The vendor base spans three tiers: precision-engineered specialists, diversified industrial equipment providers, and regional assembly operations. Strategic moves center on predictive maintenance bundling and captive supply of corrosion-resistant cast components.
Within the precision-engineered tier, ULVAC Inc. and Ebara Corporation exemplify manufacturers with integrated component supply chains. Atlas Copco occupies a position bridging industrial scale with vacuum-specific technical depth. These three anchors demonstrate how geographic origin and corporate structure map to competitive archetype in this market.
| Leading Market Players |
|---|
| Atlas Copco |
| Ebara Corporation |
| Agilent Technologies Inc. |
| Flowserve Corporation |
| Wintek Corporation |
| ULVAC Inc. |
| Busch Vacuum Solutions |
| Tsurumi Manufacturing Co Ltd |
| Ingersoll Rand Inc |
| Others |
Value Chain & Pricing Dynamics
Nagoya and Osaka industrial zones concentrate precision cast component supply for dry pump housings, concentrating upstream capacity among Japanese foundries and amplifying pricing power for integrated manufacturers against second-tier assemblers facing capacity bottlenecks. China's MEE emission mandates accelerate replacement demand for oil-sealed systems, compressing procurement timelines and forcing lease-to-own financing structures that reshape lifetime value capture across the supplier base.
Pricing Analysis
Lifecycle service contracts now drive lifetime value more than initial unit sales, with predictive maintenance subscriptions capturing recurring revenue streams that offset transactional hardware margins. Pricing stratifies across premium certified tiers for semiconductor fabs, standard efficiency tiers for chemical processors, and economy refurbished tiers for Southeast Asian manufacturing plants. Cost compression in the economy tier intensifies because Vietnamese and Indonesian operators prioritize capital expenditure minimization over uptime guarantees. Semiconductor fabs show least price sensitivity, absorbing premium positioning for contamination-free process guarantees without volume reduction.
Supply Chain Analysis
Export control regimes on precision bearing technology and magnetic levitation systems limit component flows from Japanese and German suppliers to Chinese assembly operations, fragmenting sourcing strategies. Manufacturing concentrates in Japan, South Korea, and China, with precision casting and turbomolecular bearing alignment anchoring in Nagoya and Pyeongtaek. Raw material dependencies center on fluoropolymer seal compounds from Mongolian fluorspar concentrate, corrosion-resistant nickel alloys, and high-purity aluminum castings. Single-source vulnerability runs through Japanese captive supply of precision pump housings. Distribution runs through direct fab tool integration contracts and regional service depot networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where regulatory certification entrenchment creates switching costs that lock semiconductor fabs into qualified supplier relationships across multi-year process node transitions.
For Market Incumbents: Build switching-cost moats through embedded control software that synchronizes with AMHS wafer transport protocols, extending commissioning timelines that deter replacement. Deepen captive supply of corrosion-resistant cast components to defend against second-tier assemblers gaining precision casting capacity. Counter the threat of dry pump commoditization by bundling predictive maintenance subscriptions that shift buyer evaluation criteria from unit price to guaranteed uptime. For New Entrants and Emerging Players: Build out lifecycle service infrastructure in Vietnam's Bac Ninh and Hai Phong corridors, where electronics manufacturing investment outpaces qualified technical support capacity. Target pharmaceutical manufacturing plants in South Korea and Taiwan as the most penetrable segment, where MFDS and PMDA joint regulations accelerate dry vacuum substitution but cross-border certification lags delay established players. Pursue lease-to-own financing structures as the go-to-market angle, matching capital constraints of Southeast Asian chemical processors facing MEE retrofit deadlines. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors precision-engineered specialists with integrated component supply chains over diversified industrial conglomerates dependent on compressor service cross-selling. Long-term viability hinges on qualification timelines for sub-10 nanometer process nodes, where certification barriers compound over successive technology transitions. Acquisition targets should display captive supply of corrosion-resistant castings and embedded software capabilities for fab tool integration. Watch dry pump specification consolidation at memory foundries as the inflection signal indicating which architectures capture next-generation process node mandates.| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Maintenance Platform Launch | Shifts revenue from emergency repairs to subscription uptime guarantees at 300mm wafer facilities. |
| Captive Precision Casting Expansion | Secures corrosion-resistant pump housing supply against Japanese and Korean foundry bottlenecks. |
| Fab Tool Control Protocol Integration | Extends commissioning timelines through AMHS synchronization, embedding switching costs. |
| Vietnam Service Depot Network Buildout | Captures first-mover advantage in Bac Ninh and Hai Phong electronics manufacturing corridors. |
| Hydrogen Economy Pump Qualification | Opens adjacent market entry for semiconductor-qualified suppliers in electrolyzer membrane manufacturing. |
Study Parameters
The analysis maps dry vacuum architectures, oil-sealed legacy platforms, and hybrid kinetic systems, each validated through maintenance directors at semiconductor fabs, plant engineers at chemical processing facilities, OEM procurement teams for fab tool integration, and aftermarket service heads at regional distributors. Primary interviews combined with secondary validation from customs and trade data, METI efficiency documentation filings, MEE emission permit records, and SEC 10-K disclosures from diversified industrial equipment providers. Bottom-up unit shipment estimates triangulated against top-down market value reconstructions across the projection horizon.
Assumptions held fixed include current regulatory enforcement intensity for China's dual carbon goals and Japan's Top Runner standards, while variables included dry pump adoption velocity at sub-10 nanometer nodes and fluoropolymer feedstock price volatility. The analytical framework modeled product type segmentation by displacement mechanism, application segmentation by contamination tolerance, and technology segmentation by lubrication architecture. CAGRs derived from regression analysis against semiconductor capital expenditure cycles and chemical processing retrofit timelines, with atomic layer deposition chamber specifications and hydrogen economy membrane manufacturing demand as industry-specific inputs.
Stress conditions across fluorspar concentrate supply disruptions, turbomolecular bearing alignment technician scarcity, and cross-border certification timeline extensions were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding process node transition schedules and regulatory enforcement consistency. Material shifts in MEE emission mandate retroactivity or METI efficiency benchmark stringency would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pumps and Control Devices
Fine Bubble Diffusers Market
Pumps and Control Devices
Twin Screw Pumps Market
Pumps and Control Devices
Positive Displacement (PD) Sanitary Pumps Market
Pumps and Control Devices
Electric Submersible Pump Market
Pumps and Control Devices
Chopper Pumps Market
Pumps and Control Devices
Mist Sprayer Pumps Market
Pumps and Control Devices
Mud Pumps Market
Pumps and Control Devices
Brine Tanks Market
Pumps and Control Devices
Pump Over Tanks Market
Pumps and Control Devices
Fertilizer Injection Pumps Market
Pumps and Control Devices
Industrial Pumps Market
Pumps and Control Devices
Solar Pump Inverter Market
Pumps and Control Devices
Southeast Asia Industrial Pumps Market
Pumps and Control Devices
Industrial Aerators Market
Pumps and Control Devices
Sea Water Injection Pumps Market
Pumps and Control Devices
Water Intake Screens Market