
 Europe, Middle-East and Africa Diaphragm Pump Market | 2026-2036
Europe, Middle-East and Africa Diaphragm Pump Market Size, Share, and Industry Trends Forecast 2026-2036
Europe, Middle-East and Africa Diaphragm Pump Market Insights
Hygienic-grade and ATEX-certified specifications is redrawing procurement criteria across the EMEA diaphragm pump landscape. Atlas Copco AB leverages its compressor and vacuum technology heritage to anchor positions in oil and gas applications across the Middle East. LEWA GmbH specializes in precision-metering diaphragm systems for high-pressure chemical injection, sustaining premium positioning in European pharmaceutical corridors.
A diaphragm pump employs a flexible membrane to isolate the pumped fluid from mechanical components, achieving leak-free transfer of corrosive, abrasive, or shear-sensitive media with discharge pressures typically reaching 100 bar depending on configuration. Its primary industrial purpose centers on safe handling of aggressive chemicals, sterile pharmaceutical formulations, and abrasive slurries where seal integrity prevents contamination or environmental release. Air-operated double-diaphragm configurations dominate maintenance-intensive mining and construction applications across Africa, while electric-driven precision units capture margin pools in pharmaceutical and food processing installations throughout Europe. Hydraulic diaphragm pumps occupy critical niches in high-pressure chemical injection for upstream oil and gas operations across Saudi Arabia and the UAE.
EMA's Good Manufacturing Practice guidelines and ATEX directives shape material selection and validation protocols for pharmaceutical and chemical processing pumps sold into EU member states. REACH compliance restricts certain elastomer and coating chemistries, forcing reformulation of diaphragm materials toward perfluoroelastomer and PTFE composites. Saudi Arabia's SFDA and the UAE's MOHAP impose parallel pharmaceutical equipment standards that create incremental certification burdens for suppliers serving Gulf Cooperation Council markets. Stakeholders must monitor divergence between EU MDR-aligned quality frameworks and emerging Middle Eastern localization requirements when configuring regional product portfolios.
Market Dynamics
REACH compliance and EU Green Deal mandates are forcing diaphragm material reformulation toward perfluoroelastomer composites, while EMA's Good Manufacturing Practice guidelines lock in validation protocols that extend procurement cycles for pharmaceutical-grade equipment.
Growth Catalysts
- EU Green Deal decarbonization targets:Chemical processors in Germany's Ludwigshafen cluster are specifying zero-emission pump configurations to meet Scope 3 reduction commitments, driving fluoropolymer-lined procurement.
- Upstream oil and gas expansion:Saudi Arabia and the UAE are deploying hydraulic diaphragm pumps for high-pressure chemical injection in offshore and unconventional fields, sustaining demand for 100-bar discharge systems.
- Pharmaceutical serialization mandates:EMA's track-and-trace requirements for sterile formulations are compelling fine-chemical facilities to upgrade to ATEX-certified, hygienic-grade metering systems.
Market Restraints
- Perfluoroelastomer input cost volatility:Specialty polymer supply concentrates among Japanese and US chemical suppliers, exposing European pump manufacturers to feedstock price swings and extended lead times.
- REACH authorization bottlenecks:Restricted substance lists are forcing reformulation of legacy diaphragm elastomers, creating compliance lag for equipment already installed in chemical processing plants.
- Centrifugal pump substitution in low-pressure water treatment:Municipal and industrial water facilities in North Africa are defaulting to lower-cost alternatives where shear sensitivity and chemical compatibility are secondary concerns.
Strategic Opportunities
- Localization requirements in Saudi Arabia:Vision 2030 industrial content rules are creating openings for joint-venture manufacturing to serve Aramco's procurement localization targets.
- Digital twin integration with predictive maintenance:IIoT-enabled diaphragm pumps combining vibration sensing with cloud analytics are capturing service-contract value pools in European pharmaceutical corridors.
- Green hydrogen electrolyte circulation:Alkaline and PEM electrolyzer projects across the Netherlands and Germany are specifying corrosion-resistant diaphragm pumps for potassium hydroxide and deionized water handling.
Industry Challenges
- Cross-border certification fragmentation:Equipment validated under EMA frameworks requires parallel SFDA and MOHAP submissions for Gulf Cooperation Council pharmaceutical markets, extending time-to-revenue by 8-14 months.
- Legacy DCS integration complexity:Brownfield chemical plants in Belgium and France are demanding retrofittable pump control interfaces compatible with 1990s-era distributed control systems, constraining design flexibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe, Middle-East and Africa Diaphragm Pump Market |
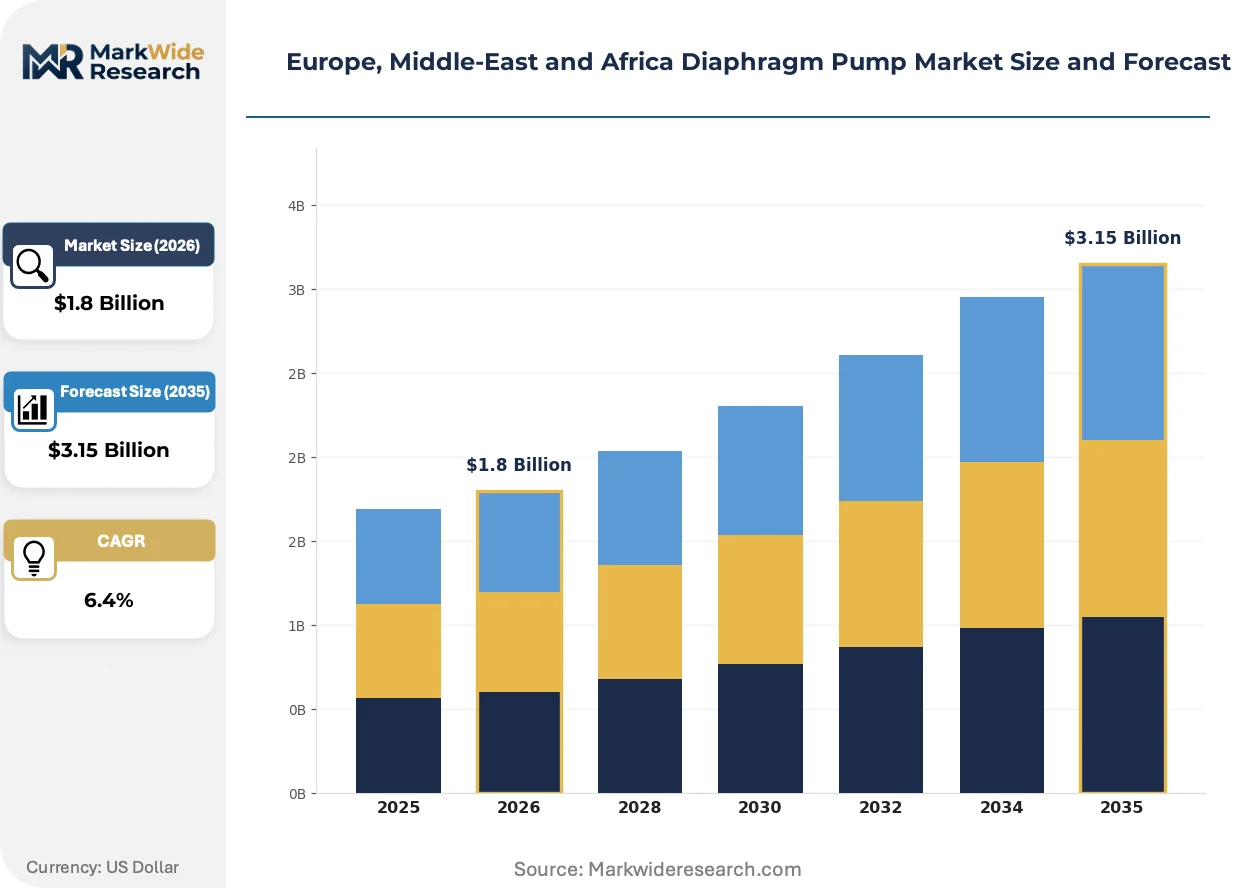
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Air-Operated, Electric, Hydraulic, Hand-Operated Application: Food & Beverage, Chemical Processing, Water Treatment, Pharmaceuticals Technology: Diaphragm Design, Pump Configuration, Flow Rate Optimization, Material Handling End User: Oil & Gas, Mining, Agriculture, Construction |
| Companies Covered | Atlas Copco AB, Dover Corporation, Idex Corporation, Ingersoll-Rand PLC, Tapflo Group, Flowserve Corporation, Grundfos, Verder International B.V., LEWA GmbH, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe, Middle-East and Africa Diaphragm Pump Market Trends and Innovations
Electrification of precision metering and material science advances in fluoropolymer composites are compressing the performance gap between air-operated and electric-driven configurations across EMEA process industries.
PTFE-overmolded elastomer diaphragms is supplanting conventional rubber-and-fabric laminates in aggressive chemical service. Fine-chemical manufacturers in Germany's Leverkusen industrial cluster are specifying these composite membranes for sulfuric acid and chlorinated solvent transfer, extending mean time between replacement from 4,000 to 12,000 operating hours and compressing lifecycle cost calculations for procurement teams.
REACH Annex XIV authorization requirements are restricting long-chain perfluorinated chemistries in diaphragm coatings and secondary seals. Equipment manufacturers serving EU chemical processing are accelerating qualification of short-chain fluoropolymer alternatives and ceramic-filled elastomer formulations, with pharmaceutical-grade pump lines most affected due to EMA's material traceability mandates.
Service-unbundling is fragmenting traditional OEM-aftermarket relationships. Mining operators in South Africa's platinum belt are sourcing diaphragm kits and valve assemblies through independent distributors rather than factory channels, compressing spare parts margins and forcing manufacturers to defend position through remote diagnostics subscriptions and certified rebuild programs.
Europe, Middle-East and Africa Diaphragm Pump Market Segmentation
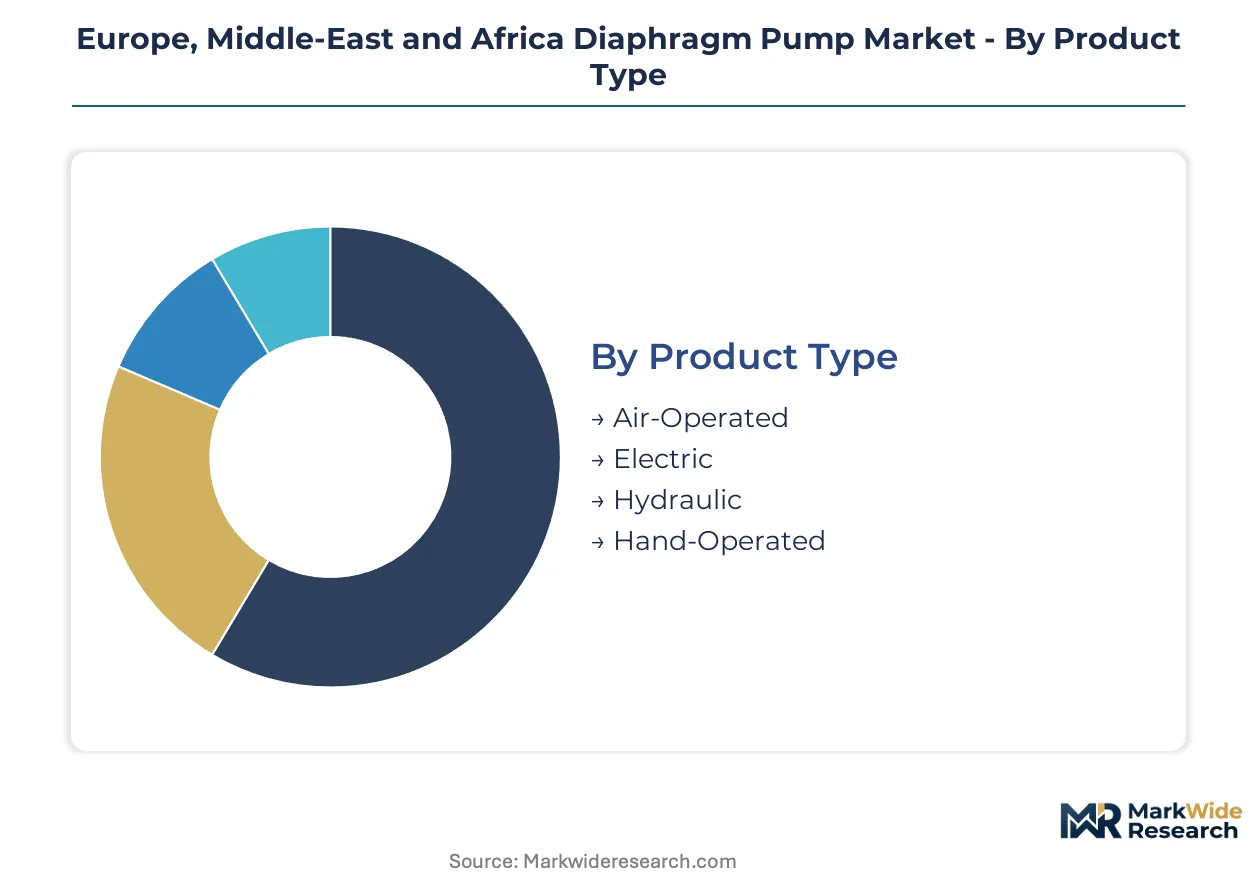
Channel configurations across EMEA diaphragm pump markets diverge sharply by segment specification. Air-operated units flow through industrial distributors serving African mining belts, while precision electric and hydraulic systems route through direct OEM channels anchored in European chemical clusters and Middle Eastern oilfield service networks.
Product Type:
Distributor and direct-sales channels partition sharply across these four mechanical configurations, with specification intensity determining route selection.
- Air-Operated:Double-diaphragm pneumatic configurations dominate maintenance-intensive environments across South Africa's platinum belt and Nigerian construction sites. Compressed-air infrastructure availability and explosion-risk tolerance make these units default choices for abrasive slurry handling in open-pit extraction.
- Electric:Servo-driven precision metering systems capture specification-grade procurement from pharmaceutical formulators in Germany's Leverkusen cluster and dairy processors in the Netherlands. EMA validation protocols and ATEX certification requirements lock these configurations into direct manufacturer relationships with extended commissioning support.
- Hydraulic:High-pressure chemical injection systems serve Aramco and ADNOC upstream operations across Saudi Arabia and the UAE, with discharge pressures reaching 100 bar for well stimulation and enhanced oil recovery.
- Hand-Operated:Portable manual pumps address intermittent dosing needs in remote agricultural cooperatives across Ethiopia and Kenya, where electrical infrastructure is unreliable and maintenance capabilities are limited.
By volume, Air-Operated leads. By growth pace, Electric is ahead.
Application:
End-use specifications cascade through fundamentally different procurement channels, with hygienic-grade applications demanding manufacturer-direct relationships and commodity chemical flows defaulting to distributor networks.
- Food & Beverage:EHEDG-certified and 3A-sanitary pumps serve dairy processors in Ireland and breweries in Belgium through specialized hygienic equipment distributors with validation documentation capabilities.
- Chemical Processing:Fluoropolymer-lined configurations handling sulfuric acid and chlorinated solvents concentrate procurement from BASF's Ludwigshafen complex and INEOS facilities across the UK and Belgium, with REACH-compliant material traceability mandatory.
- Water Treatment:Municipal desalination plants in Algeria and Morocco specify corrosion-resistant units for brine handling, though centrifugal alternatives capture share in low-pressure pre-treatment stages.
- Pharmaceuticals:Sterile single-use and multi-use systems face EMA GMP validation requirements that extend procurement cycles, with fine-chemical API manufacturers in Switzerland and Italy driving specification-grade demand.
Water Treatment generates the highest unit volumes. Pharmaceuticals commands the steepest expansion trajectory.
Technology:
Engineering specification depth determines whether these technical dimensions route through systems integrators or component distributors.
- Diaphragm Design:PTFE-overmolded elastomer composites are supplanting rubber-fabric laminates in aggressive chemical service across German fine-chemical corridors, extending replacement intervals fourfold.
- Pump Configuration:Modular skid-mounted systems with integrated pulsation dampeners capture chemical injection packages for North Sea and West African offshore platforms.
- Flow Rate Optimization:Variable-frequency drive integration and smart sensor packages enable IIoT-enabled predictive maintenance contracts in European pharmaceutical installations.
- Material Handling:Ceramic-filled elastomer formulations are accelerating qualification as REACH Annex XIV restrictions constrain legacy perfluorinated chemistries in diaphragm coatings.
Material Handling shows the most rapid specification evolution. Diaphragm Design retains the largest installed base.
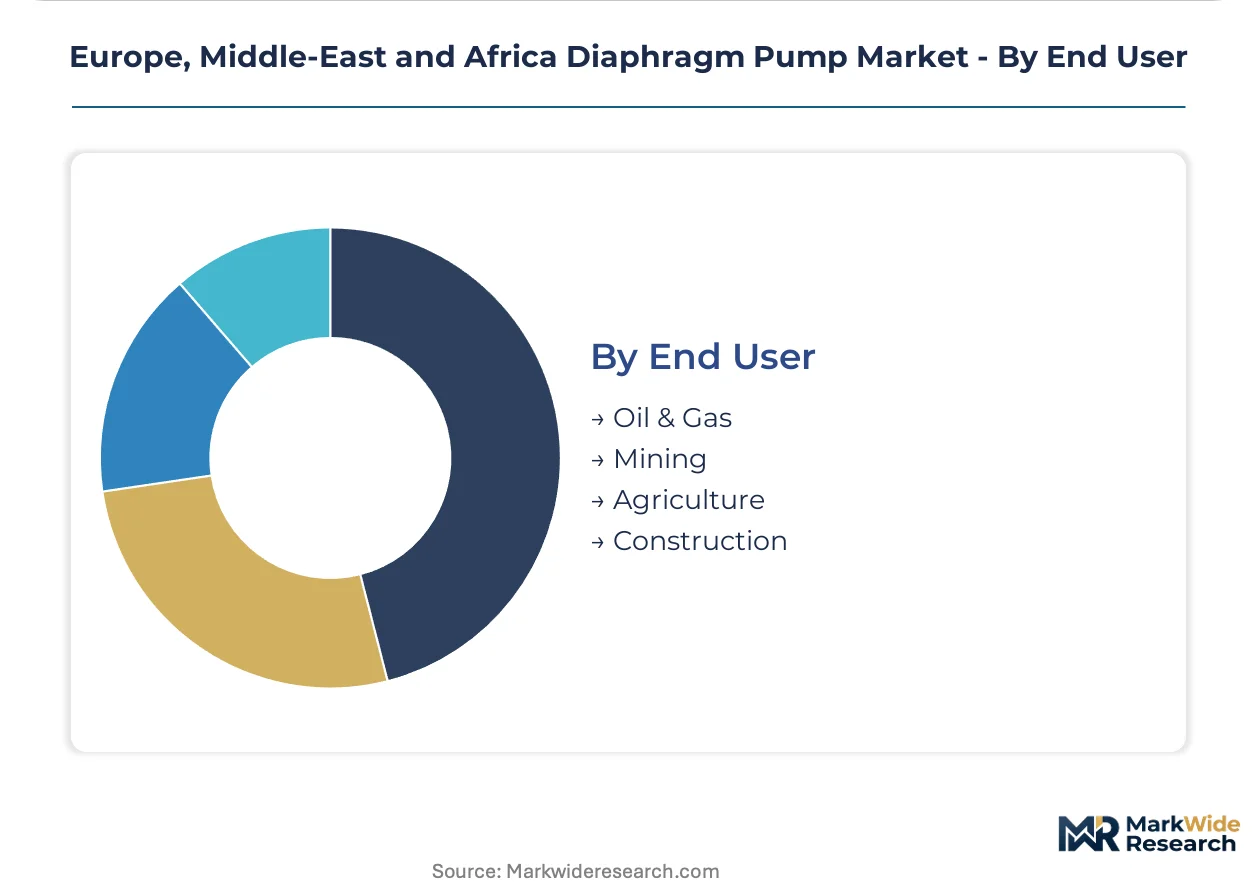
End User:
Capital intensity and operational criticality segment these verticals across OEM-direct, rental, and aftermarket channels.
- Oil & Gas:Hydraulic high-pressure systems for chemical injection sustain manufacturer-direct procurement from Saudi Aramco, ADNOC, and Eni across North African concessions, with localization requirements under Vision 2030 reshaping supply arrangements.
- Mining:Air-operated abrasive slurry pumps in South Africa's platinum and gold sectors flow through independent distributors, with service-unbundling compressing OEM aftermarket margins.
- Agriculture:Small-scale irrigation and fertilizer dosing across the Nile Delta and Maghreb regions default to lower-cost hand-operated and small electric units through agricultural supply cooperatives.
- Construction:Dewatering and grout injection applications in UAE and Qatari infrastructure projects specify rental-fleet configurations with rapid field-service response.
Oil & Gas dominates value concentration. Mining represents the largest unit deployment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity fragments sharply across the EMEA diaphragm pump landscape. African mining belts prioritize lowest total cost of ownership, while European pharmaceutical corridors absorb premium specifications for ATEX-certified and hygienic-grade systems.
Germany
Chemical processing clusters around Ludwigshafen and Leverkusen drive specification-grade procurement for aggressive fluid handling. REACH compliance and EU Green Deal mandates force fluoropolymer-lined pump configurations with zero-emission specifications. BASF's Ludwigshafen complex anchors regional demand for corrosion-resistant metering systems.
Saudi Arabia
Upstream oil and gas expansion sustains demand for hydraulic diaphragm pumps reaching discharge pressures of 100 bar. Vision 2030 localization requirements reshape procurement toward joint-venture manufacturing partnerships. Aramco's procurement targets concentrate chemical injection system demand in the Eastern Province.
United Arab Emirates
Offshore and unconventional field development drives high-pressure chemical injection applications across ADNOC concessions. MOHAP pharmaceutical equipment standards create parallel certification requirements for Gulf Cooperation Council markets. Dubai and Abu Dhabi industrial zones concentrate oilfield service procurement.
South Africa
Platinum and gold mining operations deploy air-operated double-diaphragm pumps for abrasive slurry handling. Service-unbundling compresses OEM aftermarket margins as operators source diaphragm kits through independent distributors. The Bushveld Igneous Complex anchors regional mining pump demand.
Netherlands
Green hydrogen electrolyzer projects specify corrosion-resistant diaphragm pumps for potassium hydroxide and deionized water circulation. EMA validation protocols extend procurement cycles for pharmaceutical-grade equipment. Rotterdam and Eindhoven industrial corridors concentrate dairy processing and fine-chemical demand.
Europe, Middle-East and Africa Diaphragm Pump Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the EMEA diaphragm pump landscape. Precision-metering specialists command premium positioning in European pharmaceutical corridors, while scale-oriented fabricators dominate African mining applications through distributor networks. The vendor base stratifies into three tiers: integrated industrial conglomerates with compressor heritage, specialized precision-pump engineers, and regional fabrication houses serving price-sensitive segments. Competitive dynamics center on M&A activity consolidating aftermarket service capabilities and strategic partnerships securing fluoropolymer material supply.
Within the precision-engineering tier, LEWA GmbH and Atlas Copco AB occupy distinct positioning. LEWA GmbH exemplifies the specialized German GmbH structure focused on high-pressure chemical injection systems. Atlas Copco AB anchors Scandinavian-origin industrial technology conglomeration with compressor and vacuum heritage extending into oil and gas applications. Among diversified industrial players, Dover Corporation and Idex Corporation represent US-based multi-industry manufacturing structures with pump portfolio diversification. These named entities illustrate archetype concentration rather than exhaustive market coverage.
| Leading Market Players |
|---|
| Atlas Copco AB |
| Dover Corporation |
| Idex Corporation |
| Ingersoll-Rand PLC |
| Tapflo Group |
| Flowserve Corporation |
| Grundfos |
| Verder International B.V. |
| LEWA GmbH |
| Others |
Pricing and Supply Chain Analysis
Capacity utilization at German and Japanese fluoropolymer resin plants sets regional price floors for precision-grade diaphragm pumps across EMEA. BASF's Ludwigshafen complex and Daikin Industries' Osaka facilities anchor feedstock supply, concentrating pricing power among integrated chemical processors while forcing pump OEMs to absorb volatility through long-term offtake contracts.
Pricing Analysis
REACH authorization dictates the pricing tier structure across European chemical processing applications. Three-tier pricing structure across premium, standard, and economy levels separates ATEX-certified pharmaceutical systems from general-purpose chemical units and African mining-grade pneumatic pumps. Price differentiation centers on certification grade and volume scale, with EMA-validated sterile systems commanding substantial premiums over distributor-sold mining configurations. Cost compression in economy-tier air-operated units is intensifying because South African platinum belt operators are consolidating procurement through independent distributors. Mining applications exhibit highest price sensitivity; pharmaceutical corridors show lowest.
Supply Chain Analysis
Extended lead times for perfluoroelastomer diaphragm materials stretch 14-20 weeks from Japanese and US specialty polymer suppliers. Geographic supply concentration rests on Germany, Japan, and the United States for fluoropolymer resins and precision-machined pump heads. Raw material dependencies draw from PTFE composites, perfluoroelastomer feedstocks, and ceramic-filled elastomer formulations. Single-source vulnerability concentrates in long-chain fluorinated chemistries facing REACH Annex XIV restrictions. Distribution runs through direct OEM channels for European pharmaceutical and Middle Eastern oilfield applications, while industrial distributors serve African mining belts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EMEA diaphragm pump market is entering a cyclical recovery phase. Upstream oil and gas capital deployment across Saudi Arabia and the UAE provides the cyclical anchor, with Aramco's procurement localization targets under Vision 2030 sustaining demand momentum.
For Market Incumbents: Compound aftermarket service revenues through predictive maintenance subscriptions and certified rebuild programs. LEWA GmbH and Atlas Copco AB should deepen backward integration into fluoropolymer diaphragm manufacturing to offset Japanese feedstock volatility. Defend against centrifugal pump substitution in North African water treatment by emphasizing corrosion-resistant specifications for brine handling applications. For New Entrants and Emerging Players: Lead with green hydrogen electrolyte circulation applications across Dutch and German alkaline and PEM electrolyzer projects. Target Saudi joint-venture manufacturing partnerships to satisfy Aramco localization requirements. Agricultural cooperatives in Ethiopia and Kenya represent underpenetrated terrain for portable hand-operated dosing pumps with simplified maintenance protocols. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among IIoT-enabled pump-as-a-service providers in European pharmaceutical corridors. Long-term viability over the next decade hinges on fluoropolymer material science capabilities and regulatory compliance infrastructure. Acquisition candidates should demonstrate established EMA validation protocols and ATEX certification competencies. The signal to monitor is divergence between EU MDR-aligned quality frameworks and emerging Middle Eastern localization mandates.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fluoropolymer Manufacturing | Captive supply of PTFE composites insulates margins from Japanese feedstock volatility. |
| Joint Venture Manufacturing in Saudi Arabia | Vision 2030 localization requirements favor partnerships serving Aramco procurement targets. |
| IIoT Predictive Maintenance Platform Launch | Cloud-enabled vibration analytics capture service-contract value pools in pharmaceutical corridors. |
| Short-Chain Fluoropolymer Qualification Program | REACH Annex XIV compliance accelerates adoption of ceramic-filled elastomer alternatives. |
| Green Hydrogen Electrolyzer Partnership | Rotterdam and Eindhoven electrolyzer projects specify corrosion-resistant potassium hydroxide pumps. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with industry stakeholders and systematic secondary validation across regulatory and trade databases. Primary fieldwork engaged plant engineers at BASF Ludwigshafen and INEOS facilities, procurement leads at Saudi Aramco and ADNOC, aftermarket service heads at South African mining distributors, and technical R&D directors at German pump OEMs. Secondary sources encompassed ECHA REACH authorization databases, EU customs trade statistics, SEC 10-K filings from listed pump manufacturers, and EMA GMP inspection records. Bottom-up unit demand modeling triangulated against top-down chemical processing capacity expansion announcements.
Across the analysis window, the forecasting framework modeled volume and value trajectories through segmented demand drivers. Segmentation dimensions encompassed mechanical configuration, application severity, discharge pressure tier, and regional regulatory cluster. CAGRs were derived from regression analysis of historical procurement patterns against announced chemical processing and oilfield capital programs. Industry-specific inputs included Aramco's in-country value targets, EU Green Deal decarbonization timelines, and pharmaceutical serialization mandate implementation schedules.
The analysis sits within stated boundaries; outcomes outside sustained upstream oil and gas investment or accelerated REACH authorization timelines would require recalibration. Forecasts reflect documented assumptions regarding fluoropolymer supply continuity and certification protocol stability. Perfluoroelastomer feedstock disruptions or divergence between EMA and SFDA validation requirements represent primary revision risks. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pumps and Control Devices
Centrifugal Pump Market
Pumps and Control Devices
Global Positive Displacement (PD) Pumps Market
Pumps and Control Devices
Cryogenic Pump Market
Pumps and Control Devices
Droplet Separator Market
Pumps and Control Devices
Vane Pump Market
Pumps and Control Devices
Vertical Turbine Pumps Market
Pumps and Control Devices
Intelligent Pump Market
Pumps and Control Devices
Liquid Dispensing Pump Market
Pumps and Control Devices
Food and Beverages Industry Pumps Market
Pumps and Control Devices
Flow Back Equipment Market
Pumps and Control Devices
Asia Pacific Side Channel Pumps Market
Pumps and Control Devices
North America Positive Displacement Pumps Market
Pumps and Control Devices
Global Hydraulic Submersible Pump Market
Pumps and Control Devices
Industrial ASME B73.1 Centrifugal Pumps Market
Pumps and Control Devices
Fertilizer Injection Pumps Market
Pumps and Control Devices
North America Dispensing Pumps Market