
 Water Intake Screens Market | 2026-2036
Water Intake Screens Market Size, Share, and Industry Trends Forecast 2026-2036
Water Intake Screens Market Analytics
Power generation is realigning the intake screen demand profile as utilities retrofit cooling systems to meet stricter environmental discharge rules. Johnson Screens leverages its wedge-wire manufacturing depth to dominate large-diameter offshore and riverine installations. Evoqua Water Technologies competes through aftermarket service networks that sustain recurring revenue across municipal and industrial accounts. Aqseptence Group anchors European demand with stainless-steel screen systems engineered for Rhine and Danube basin thermal plants.
Water intake screens are perforated or wedgewire filtration barriers installed at raw water extraction points, typically fabricated from 304 or 316 stainless steel with aperture sizes ranging from 0.5 mm to 100 mm depending on debris load and aquatic species protection requirements. Their primary purpose is to block debris, fish, and sediment from entering pumps, condensers, and treatment trains while maintaining hydraulic throughput. Self-cleaning screens command premium positioning because automated backwash and raked systems reduce manual labor and outage frequency in continuous-flow environments. Mechanical screens retain volume leadership in developing markets where capital constraints favor simpler, maintainable designs. Coarse screens face margin compression as they become commoditized, while fine screens gain traction in aquaculture and sensitive ecosystem withdrawals.
EPA 316(b) regulations in the United States compel power producers to install fish-impingement and entrainment reduction technologies, directly shaping screen slot geometry and approach velocity specifications. EMA and national water framework directives across Europe enforce comparable ecological standards, creating harmonized product requirements for suppliers serving multiple jurisdictions. China's MEE administers discharge permits that increasingly reference GB standards for cooling water intake structures. Stakeholders must monitor how biodiversity credit schemes and carbon border adjustments reshape total cost of ownership calculations for intake infrastructure investments.
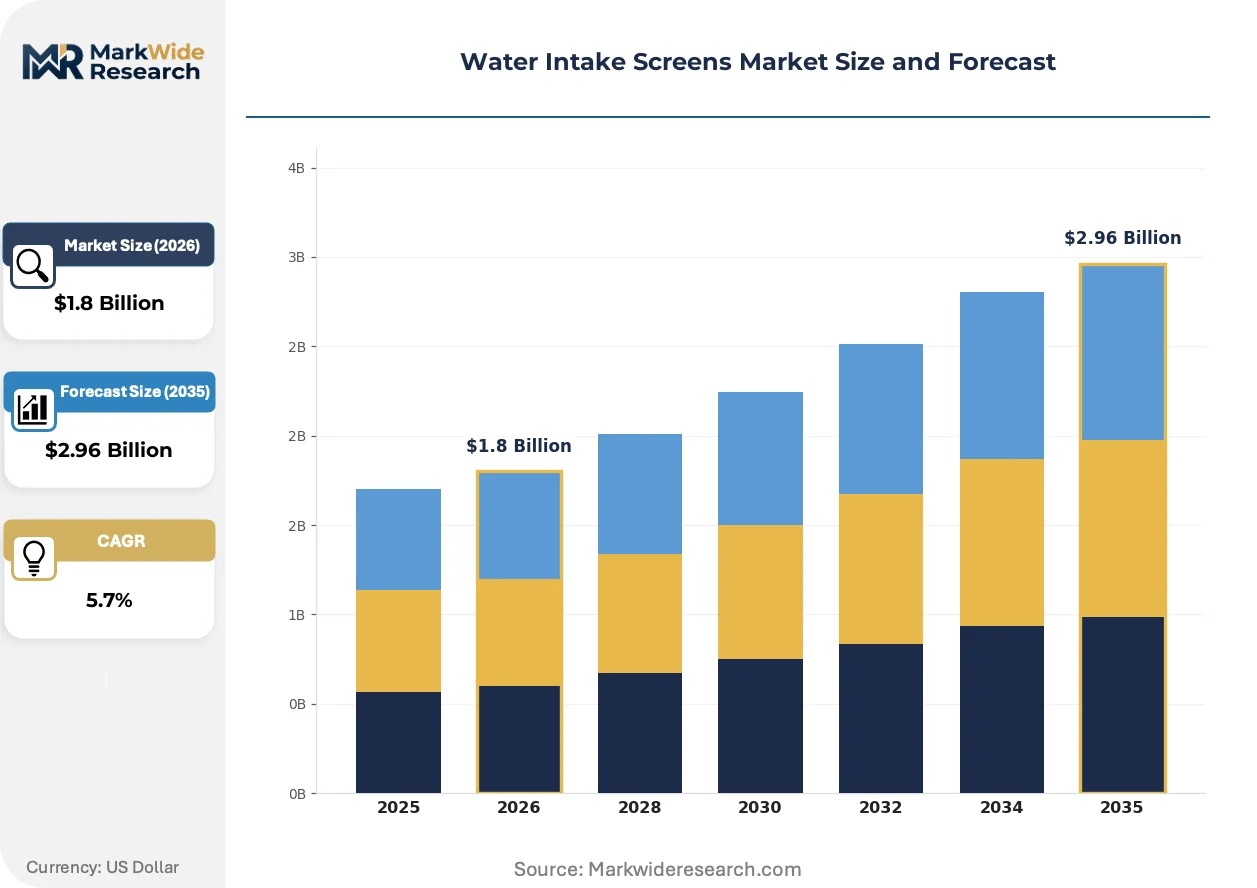
Market Dynamics
EPA Section 316(b) compliance mandates are restructuring capital allocation across thermal power operators, forcing wholesale replacement of legacy coarse-bar screens with fine-slot wedge-wire systems designed to reduce fish impingement mortality rates below regulatory thresholds.
Growth Catalysts
- EPA 316(b) Implementation:US power generators face hard deadlines to retrofit cooling water intakes with fish-friendly screen technologies, creating sustained replacement demand across the Ohio River and Great Lakes basin plant clusters.
- Stainless Steel Wedge-Wire Fabrication:Advanced welding automation is reducing slot tolerance variation below 50 microns, enabling hydraulic performance guarantees that accelerate utility procurement decisions.
- China Thermal Expansion:Provincial energy commissions in Guangdong and Shandong are approving combined-cycle gas turbine complexes that specify dual-flow intake configurations with redundant screen arrays.
Market Restraints
- 316(b) Compliance Cost Burden:Small municipal water treatment districts in the US Midwest lack capital reserves to replace passive coarse screens with automated self-cleaning systems, deferring procurement indefinitely.
- Nickel Alloy Price Volatility:316L stainless steel screen fabrication faces margin compression when London Metal Exchange nickel futures spike above historical baselines, squeezing fixed-price contract profitability.
- Technical Slot Geometry Limits:Wedge-wire screens below 1.0 mm aperture face structural deformation under high debris loading in tropical river systems with seasonal organic matter surges.
Strategic Opportunities
- Offshore Aquaculture Withdrawals:Norwegian salmon farming operators are specifying titanium-clad intake screens for deep fjord installations where biofouling resistance justifies material premiums.
- EU Green Deal Cooling Standards:The European Commission's revised industrial emissions directive is mandating closed-cycle cooling retrofits that require fine-mesh entrainment protection at coastal refineries.
- Digital Twin Integration:Computational fluid dynamics modeling is converging with IoT pressure sensors to enable predictive screen maintenance scheduling, opening recurring software revenue streams for equipment suppliers.
Industry Challenges
- 316(b) Biological Demonstration Timelines:US utilities must complete 24-month impingement mortality studies before regulatory approval, extending project commissioning cycles and freezing capital deployment.
- Legacy Intake Structure Compatibility:Pre-1980 concrete intake bays at aging coal plants lack dimensional tolerances for modern cylindrical screen installations, forcing costly civil modifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Water Intake Screens Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mechanical Screens, Self-Cleaning Screens, Coarse Screens, Fine Screens Technology: Hydraulic, Electro-Mechanical, Manual, Automated End User: Municipal Water Systems, Industrial Plants, Power Generation, Irrigation Application: Water Treatment, Cooling Systems, Aquaculture, Wastewater Management |
| Companies Covered | Atlas Manufacturing, Evoqua Water Technologies, Johnson Screens, Aquatech, Veolia, Aqseptence Group, Hendrick Screen Company, Culligan, Hydrolox, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Water Intake Screens Market Evolving Landscape
Intake screen engineering is pivoting from passive debris exclusion toward active ecological protection systems that satisfy tightening biodiversity mandates while maintaining hydraulic efficiency in high-volume cooling applications.
Computational fluid dynamics simulation is converging with additive manufacturing to produce optimized screen slot geometries that reduce approach velocities below 0.5 feet per second. US nuclear operators at Columbia River and Chesapeake Bay facilities are piloting these topology-optimized wedge-wire arrays. This convergence is compressing the engineering validation cycle from 18 months to 90 days for custom intake configurations.
China's MEE is enforcing GB 50050 cooling water design standards that incorporate entrainment mortality limits previously absent from national construction codes. Thermal plant developers in Jiangsu and Zhejiang provinces must now submit aquatic impact assessments with intake screen specifications before construction permits issue. European suppliers with established fish-protection engineering capabilities are securing preferred vendor status for these greenfield projects.
Utility procurement departments are unbundling screen supply from installation and commissioning services, creating separate competitive bids for each phase. This disintermediation is fragmenting vendor relationships that previously relied on turnkey EPC contracts. The pattern is most visible in German municipal utility associations, where technical specification committees now source wedge-wire elements directly from specialized fabricators while contracting civil works to regional construction consortia.
Water Intake Screens Market Segmentation
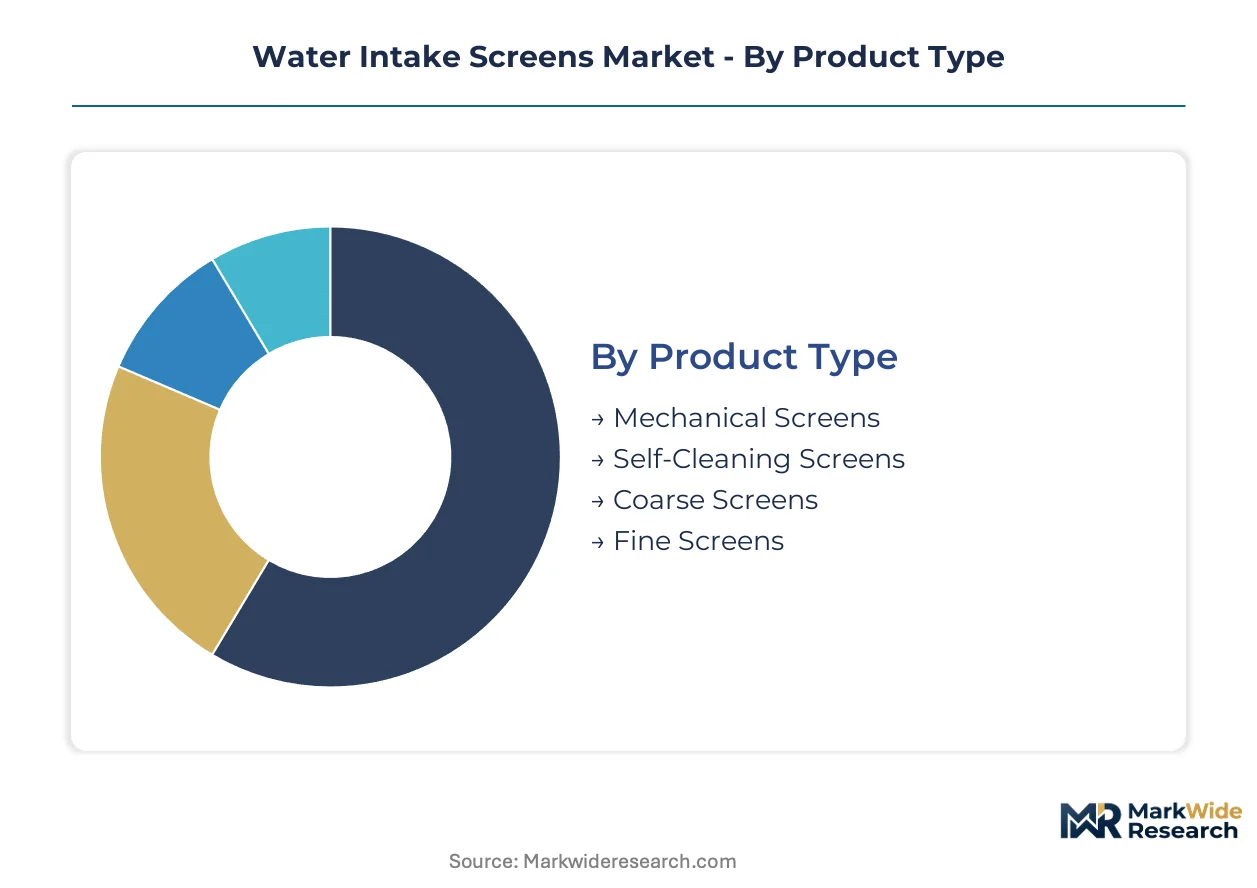
Water intake screen procurement splits sharply between capital-constrained operators seeking maintainable mechanical solutions and utilities mandated to install premium automated systems for fish protection compliance. Segmentation reveals how regulatory pressure and application-specific hydraulic demands reshape vendor priorities across product categories.
Product Type:
Volume concentrates in mechanically simple designs, while premium positioning flows to automated self-cleaning architectures that command higher unit economics.
- Self-Cleaning Screens:Automated backwash and raked mechanisms eliminate manual debris removal in continuous-flow cooling water intakes. US power generators facing EPA 316(b) deadlines specify these systems for Ohio River and Great Lakes basin retrofits where outage minimization justifies capital expenditure.
- Mechanical Screens:Passive bar and mesh configurations fabricated from 304 or 316 stainless steel dominate developing markets with constrained procurement budgets. Municipal water treatment districts across India's state-level utilities favor these maintainable designs for raw water extraction points with moderate debris loading.
- Coarse Screens:Heavy-duty perforated plate systems with 10-100 mm apertures block large debris at river and offshore intakes. China's provincial energy commissions specify redundant coarse arrays for new thermal plant construction in Guangdong province.
- Fine Screens:Wedge-wire elements with sub-1.0 mm slots protect sensitive aquatic ecosystems and aquaculture withdrawals. Norwegian salmon farming operators in deep fjord installations drive specification of titanium-clad variants for biofouling resistance.
Today's leader: Mechanical Screens. Tomorrow's challenger: Self-Cleaning Screens.
Technology:
Control sophistication separates cost tiers, with hydraulic simplicity anchoring developing markets and electro-mechanical automation capturing regulatory-driven replacement cycles.
- Automated:PLC-controlled raking and backwash systems integrate with SCADA networks for remote monitoring of intake performance. German municipal utility associations source automated wedge-wire arrays directly from specialized fabricators while unbundling civil installation contracts.
- Electro-Mechanical:Motor-driven rake mechanisms combine mechanical reliability with programmable cleaning cycles. European coastal refineries facing EU Green Deal cooling standards specify these systems for closed-cycle retrofit projects requiring fine-mesh entrainment protection.
- Hydraulic:Passive flow-driven cleaning heads reduce energy consumption in remote installations. India's irrigation departments deploy hydraulic self-cleaning screens for canal headworks where electrical infrastructure remains unreliable.
- Manual:Hand-raked bar screens persist in small-scale municipal systems with intermittent operation and accessible intake bays. US Midwest water districts defer automated upgrades due to capital reserve constraints.
Automated systems command the steepest expansion trajectory as compliance deadlines compress procurement timelines.
End User:
Customer scale and regulatory exposure determine specification intensity, with centralized power generators driving the most demanding technical requirements.
- Power Generation:Thermal and nuclear utilities specify redundant screen arrays with guaranteed hydraulic throughput and fish mortality compliance. China's MEE discharge permit requirements for Jiangsu and Zhejiang province plants mandate aquatic impact assessments with intake specifications before construction approval.
- Municipal Water Systems:City-scale treatment plants balance capital constraints against debris exclusion reliability. US municipal utilities fragment procurement across direct wedge-wire supply and regional civil installation contracts.
- Industrial Plants:Manufacturing facilities with process cooling demands prioritize maintainable designs over ecological performance. Chemical and petrochemical operators in the US Gulf Coast specify coarse screens for raw water intakes with heavy sediment loading.
- Irrigation:Agricultural water districts favor robust mechanical designs tolerant of seasonal debris surges. Australia's Murray-Darling basin operators deploy traveling water screens for canal diversion structures.
Power Generation anchors current procurement volume. Municipal Water Systems present the broadest addressable expansion base.
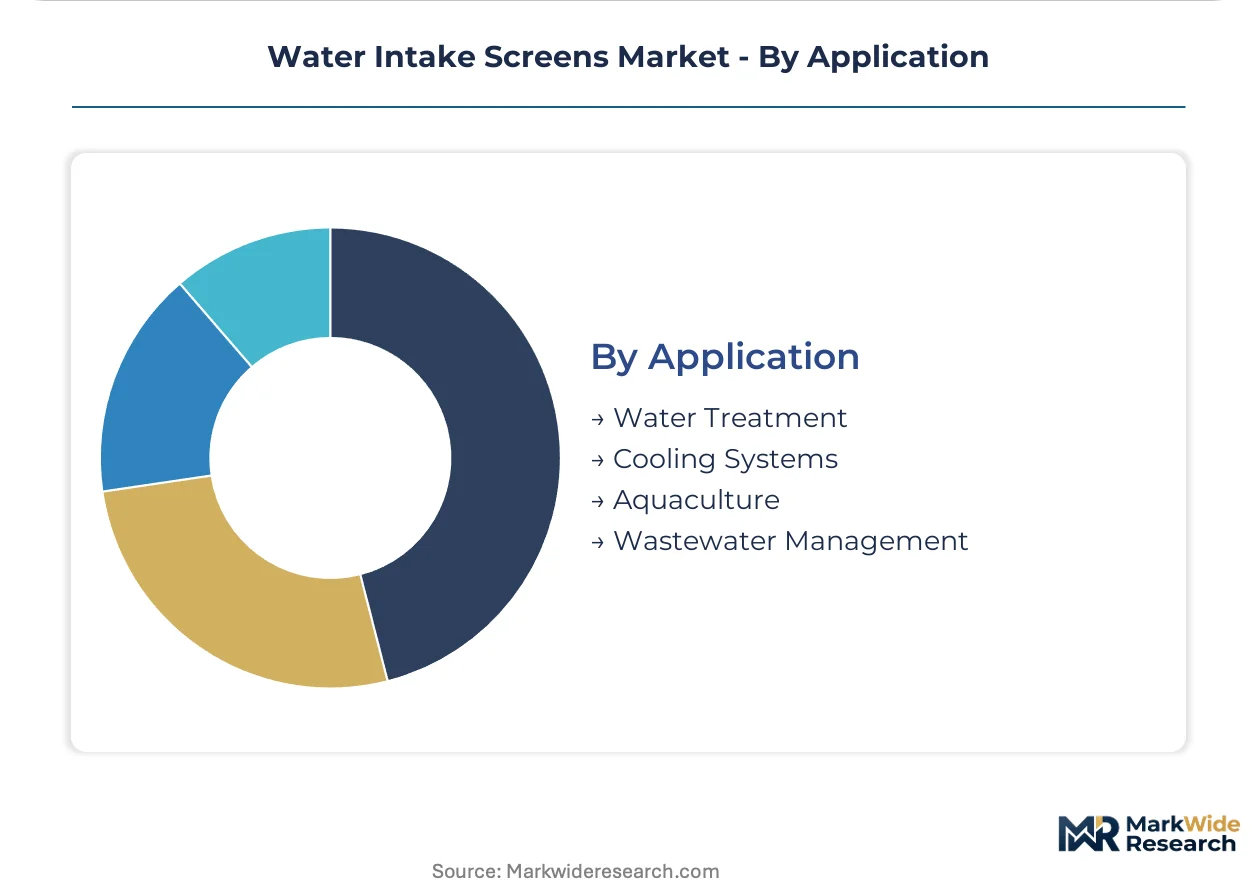
Application:
Functional context dictates aperture sizing and material selection, with cooling system applications dominating stainless steel wedge-wire consumption.
- Cooling Systems:Once-through and closed-cycle thermal plant configurations require high-throughput screens with approach velocity below 0.5 feet per second. US nuclear operators at Columbia River and Chesapeake Bay facilities pilot topology-optimized wedge-wire arrays from additive manufacturing.
- Water Treatment:Potable water extraction points demand debris exclusion without hydraulic head loss. Brazilian municipal utilities specify stainless steel screens for raw water intakes from the Paraná and Tietê river systems.
- Aquaculture:Sensitive ecosystem withdrawals require fine-slot protection of larval fish and invertebrates. Norwegian fjord salmon farming operators specify titanium-clad screens for deep-water intake structures.
- Wastewater Management:Headworks screening at treatment plant inlets tolerates coarser aperture sizing with higher debris throughput. South Korean metropolitan utilities deploy mechanically cleaned bar screens for combined sewer overflow points.
Cooling Systems dominate stainless steel consumption. Aquaculture commands the highest material specification intensity per unit.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping procurement geography as utilities migrate screen sourcing toward jurisdictions with harmonized environmental standards and established stainless-steel fabrication infrastructure. Compliance cost differentials between EPA-mandated US retrofits and greenfield Asian installations are redirecting capital flows.
United States
EPA Section 316(b) deadlines are compressing procurement timelines across Ohio River and Great Lakes basin thermal plants. FERC licensing reviews now incorporate impingement mortality studies as standard practice. Columbia River nuclear facilities and Chesapeake Bay power clusters are piloting topology-optimized wedge-wire arrays from additive manufacturing suppliers.
China
Provincial energy commissions in Guangdong and Shandong are approving combined-cycle gas turbine complexes with redundant screen specifications. MEE discharge permits for Jiangsu and Zhejiang plants mandate aquatic impact assessments before construction approval. Yangtze River Delta thermal developers are specifying dual-flow intake configurations with fine-slot entrainment protection.
Germany
Municipal utility associations are unbundling screen supply from installation contracts, fragmenting traditional vendor relationships. EU Green Deal cooling standards are mandating closed-cycle retrofits at coastal refineries requiring fine-mesh protection. Rhine and Danube basin thermal operators are sourcing wedge-wire elements directly from specialized fabricators.
Norway
Salmon farming operators in deep fjord installations are specifying titanium-clad intake screens for biofouling resistance. National aquaculture regulators are tightening entrainment protection standards for sensitive ecosystem withdrawals. Western fjord clusters are driving premium material specifications that justify cost premiums over standard stainless steel.
India
State-level irrigation departments are deploying hydraulic self-cleaning screens for canal headworks where electrical infrastructure remains unreliable. CEA thermal plant guidelines are incorporating debris exclusion standards previously absent from national codes. Maharashtra and Gujarat water utilities are balancing capital constraints against maintainable mechanical designs for raw water extraction.
Water Intake Screens Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with premium automated systems consolidating around established fabricators while commoditized coarse screens fragment among regional metalworkers. The vendor base organizes into three tiers: wedge-wire engineering specialists with hydraulic performance guarantees, stainless-steel fabricators serving municipal specifications, and diversified water treatment conglomerates bundling screens within broader equipment portfolios. Capacity expansion and strategic partnerships dominate competitive moves as suppliers position for 316(b) compliance-driven replacement cycles.
Among established engineering specialists, Johnson Screens and Aqseptence Group occupy positions defined by manufacturing depth and regional anchoring respectively. Evoqua Water Technologies exemplifies the diversified conglomerate archetype with aftermarket service networks. Atlas Manufacturing and Hendrick Screen Company represent North American fabrication capabilities serving utility procurement channels.
| Leading Market Players |
|---|
| Atlas Manufacturing |
| Evoqua Water Technologies |
| Johnson Screens |
| Aquatech |
| Veolia |
| Aqseptence Group |
| Hendrick Screen Company |
| Culligan |
| Hydrolox |
| Others |
Value Network & Pricing Analysis
316L stainless steel feedstock costs cascade through three pricing tiers before reaching utility procurement desks, with nickel price volatility on the London Metal Exchange compressing margins at the wedge-wire fabrication stage while EPA 316(b) compliance mandates sustain premium positioning for automated self-cleaning systems.
Pricing Analysis
Distributor markups of 12-18% separate specialized fabricators from municipal utility end-users, with three-tier pricing stratification across premium automated systems, standard electro-mechanical configurations, and economy-grade passive screens. Price differentiation hinges on slot tolerance certification below 50 microns and bundled aftermarket service contracts. Cost compression in the mechanical screen tier is intensifying as Chinese fabricators expand export capacity. Municipal water districts in the US Midwest exhibit the highest price sensitivity, while nuclear operators facing FERC licensing deadlines accept minimal negotiation on fish-protection-compliant specifications.
Supply Chain Analysis
Domestic-content mandates in China's MEE discharge permit process are reshaping sourcing patterns for Yangtze River Delta thermal projects, favoring local stainless-steel foundries over European wedge-wire specialists. Manufacturing concentrates in China, Germany, and the United States, with raw material dependencies on Indonesian nickel ore, Brazilian iron ore, and South African chromium. Single-source vulnerability in 316L stainless steel coil supply creates exposure to commodity price spikes. Distribution runs through specialized water treatment equipment distributors and direct OEM procurement channels for large utility accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as EPA 316(b) deadlines and China's GB 50050 standards displace commodity coarse screens with specification-intensive fine-slot wedge-wire systems.
For Market Incumbents: Extend hydraulic performance guarantee capabilities to capture 316(b) biological demonstration timelines that freeze capital deployment at competitor accounts. Additive manufacturing partnerships for topology-optimized slot geometries defend against emerging CFD-IoT integrators. Backward integration into 316L stainless steel coil supply hedges nickel price volatility exposure on fixed-price utility contracts.
For New Entrants and Emerging Players: EPA Section 316(b) in the United States opens a window for specialized biological engineering consultancies to bundle impingement mortality study execution with screen specification design. White-space targets include Norwegian aquaculture titanium-clad screen installations and Indian hydraulic self-cleaning canal headworks. A go-to-market angle anchored in computational fluid dynamics modeling services differentiates against legacy fabricators lacking simulation capabilities.
For Investors and Strategic Acquirers: Consolidation pressure builds where municipal utility procurement unbundling fragments vendor relationships and erodes aftermarket service attach rates. Long-term viability favors suppliers with captive wedge-wire manufacturing and SCADA integration software stacks. Acquisition target archetype: regional stainless-steel fabricators with EPA 316(b) compliance project experience but limited geographic reach. The signal to watch is FERC licensing review velocity as a lead indicator of replacement cycle acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into 316L Stainless Steel Supply | Captive coil sourcing insulates margin pressure from London Metal Exchange nickel volatility. |
| Computational Fluid Dynamics Service Bundling | CFD modeling contracts with Columbia River nuclear operators create recurring software revenue streams. |
| Titanium-Clad Product Line Expansion | Norwegian fjord aquaculture specifications justify material premiums over standard stainless steel. |
| SCADA Integration Partnership | PLC-controlled backwash systems with IoT pressure sensors enable predictive maintenance scheduling. |
| Regional Fabrication Capacity Addition | Guangdong province presence captures MEE-mandated local content requirements for thermal plant construction. |
Research Methodology
Coverage spans the United States, China, Germany, Norway, and India, with primary inputs from each region combining structured interviews with utility procurement managers, wedge-wire fabrication plant engineers, EPA compliance consultants, and aquaculture facility operators with secondary validation. Secondary sources include FERC licensing databases, MEE discharge permit filings, EU Green Deal industrial emissions directive texts, and stainless-steel trade flow customs records. Bottom-up project pipeline tracking triangulates against top-down utility capital expenditure forecasts.
Rate-of-change decomposition separates volume growth from price-mix effects across the projection horizon. Segmentation dimensions modeled include product type, technology tier, end-user vertical, and application context, with regulatory compliance intensity as an additional industry-specific dimension. CAGRs derive from utility retrofit cycle analysis and greenfield thermal plant approval trajectories. Forecast inputs incorporate nickel price scenario modeling and EPA 316(b) enforcement timeline assumptions.
Forecast precision tightens around the base case; tail outcomes carry wider variance under nickel price spike conditions or extended FERC biological study timelines. Forecasts reflect documented assumptions regarding MEE permit velocity and EU Green Deal implementation pace. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pumps and Control Devices
Global Commercial Pumps Market
Pumps and Control Devices
North America Submersible Pumps Market
Pumps and Control Devices
Global Positive Displacement (PD) Pumps Market
Pumps and Control Devices
Axial and Mixed Flow Pumps Market
Pumps and Control Devices
Twin Screw Pumps Market
Pumps and Control Devices
Paint Pump Market
Pumps and Control Devices
Circulators Market
Pumps and Control Devices
Centrifugal Pump Market
Pumps and Control Devices
Global Variable Displacement Pumps Market
Pumps and Control Devices
Water Desalination Pumps Market
Pumps and Control Devices
Positive Displacement (PD) Sanitary Pumps Market
Pumps and Control Devices
Global Hydraulic Metering Pump Market
Pumps and Control Devices
Industrial ASME B73.1 Centrifugal Pumps Market
Pumps and Control Devices
Global Leak Detection Solutions Market
Pumps and Control Devices
Fine Bubble Diffusers Market
Pumps and Control Devices
Drum Pump Market