
 North America Submersible Pumps Market | 2026-2036
North America Submersible Pumps Market Size, Share, and Industry Trends Forecast 2026-2036
North America Submersible Pumps Market Analytics
Aftermarket service revenue is reconfiguring margin pools across the North America Submersible Pumps Market, pulling value from equipment sales toward lifecycle contracts and predictive maintenance programs. Grundfos Holding A/S leverages its digital service platform to capture recurring revenue from municipal water utilities. Flowserve Corp anchors its position through extensive refurbishment networks serving oilfield operators in Texas and Oklahoma. Sulzer AG competes by specializing in slurry-handling aftermarket solutions for mining and industrial end users.
Submersible pumps are hermetically sealed centrifugal units designed to operate fully immersed in fluid, typically constructed from cast iron or stainless steel housings with multistage impeller assemblies capable of generating heads exceeding 1,000 feet for deep-well extraction. Electric submersible systems dominate municipal and agricultural installations due to their compatibility with grid infrastructure and variable frequency drive integration. Intelligent pumping technology represents the fastest-expanding segment, as utilities deploy sensor-embedded units to reduce energy consumption and unplanned downtime. Smart monitoring capabilities are shifting margin pools toward data-analytics providers and system integrators.
EPA efficiency regulations under the Clean Water Act and DOE pump energy conservation standards are mandating minimum performance thresholds for municipal and industrial installations, effectively disqualifying legacy equipment from public procurement cycles. NHTSA and OSHA workplace safety frameworks influence submersible pump deployment protocols in construction dewatering and confined-space applications. Stakeholders must weigh capital allocation between intelligent system upgrades and conventional replacement cycles as regulatory compliance windows narrow and utility procurement specifications evolve.
Market Dynamics
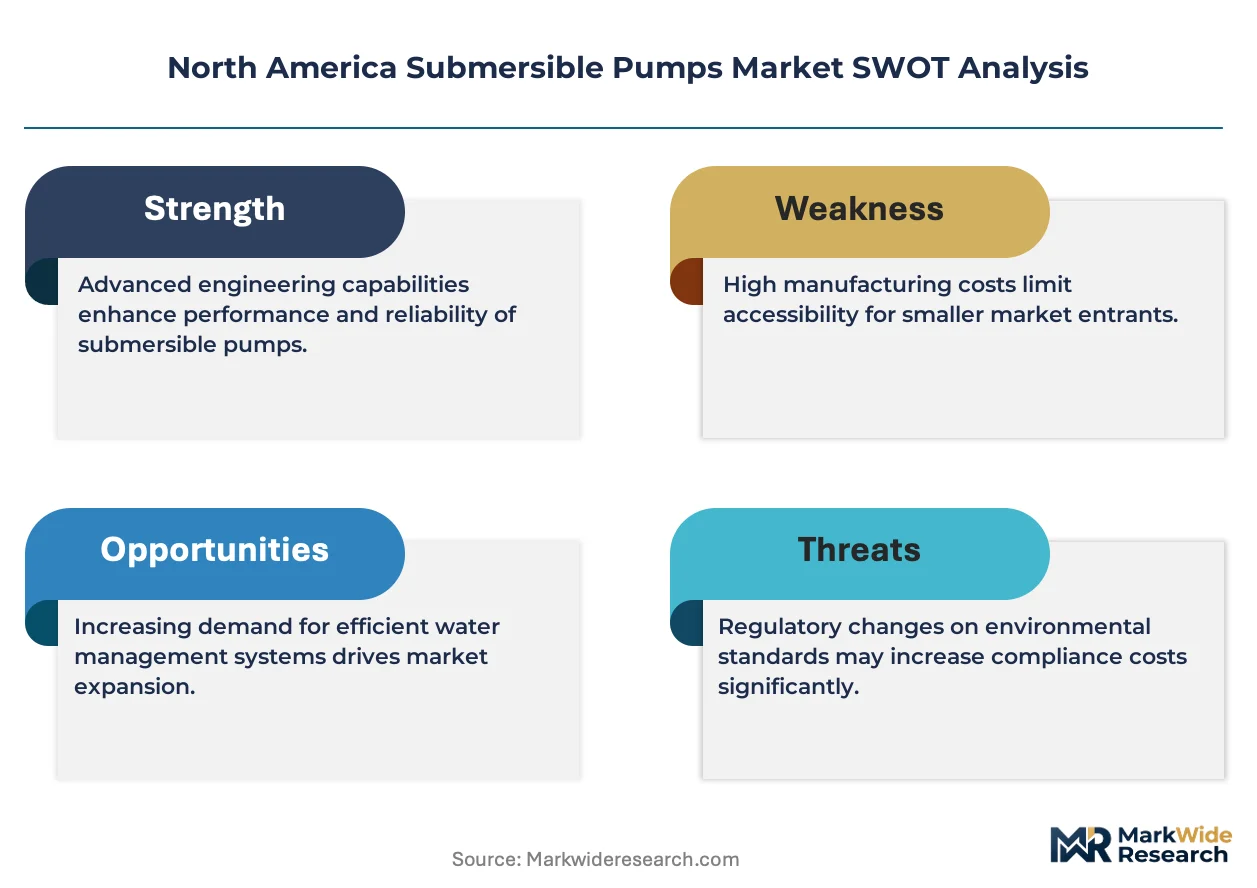
EPA motor efficiency mandates under the DOE Pump Energy Conservation Standards are compressing replacement cycles across municipal water infrastructure, forcing utilities to retire legacy submersible systems ahead of scheduled maintenance intervals and redirect capital toward intelligent pumping architectures.
Growth Catalysts
- Permian Basin artificial lift intensity:Oilfield operators in West Texas and southeastern New Mexico are deploying high-reliability electric submersible pumps for sustained hydrocarbon extraction from unconventional reservoirs.
- Clean Water Act infrastructure mandates:EPA effluent discharge standards are compelling wastewater treatment facilities to upgrade aging lift stations with compliant motor systems.
- Variable frequency drive integration:Grid-compatible pump controls are enabling precision flow management across agricultural irrigation networks in California's Central Valley.
Market Restraints
- Cast iron and stainless steel input volatility:Raw material price swings for pump housings and impeller assemblies are compressing OEM margins and destabilizing project bidding.
- Supply concentration in Texas manufacturing clusters:Heavy reliance on Houston-area foundries and motor winding facilities creates geographic vulnerability to Gulf Coast weather disruptions.
- Technical ceiling on deep-well head pressure:Conventional multistage impeller designs face physical limits exceeding 1,000 feet of lift without exotic material costs.
Strategic Opportunities
- Canadian oil sands thermal extraction:Steam-assisted gravity drainage operations in Alberta require specialized high-temperature submersible systems with substantial aftermarket service potential.
- IRA clean energy manufacturing incentives:Domestic content bonuses for grid-connected industrial equipment are attracting pump assembly investment to US-based production facilities.
- Predictive maintenance platform convergence:Sensor-embedded pumps combined with cloud analytics are creating recurring revenue streams independent of equipment sales cycles.
Industry Challenges
- Certification bottlenecks for NSF/ANSI 61 potable water compliance:Extended laboratory testing timelines for wetted components are delaying municipal procurement awards.
- Integration friction with SCADA legacy architectures:Intelligent pump deployments require costly middleware development to communicate with decades-old utility control systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Submersible Pumps Market |
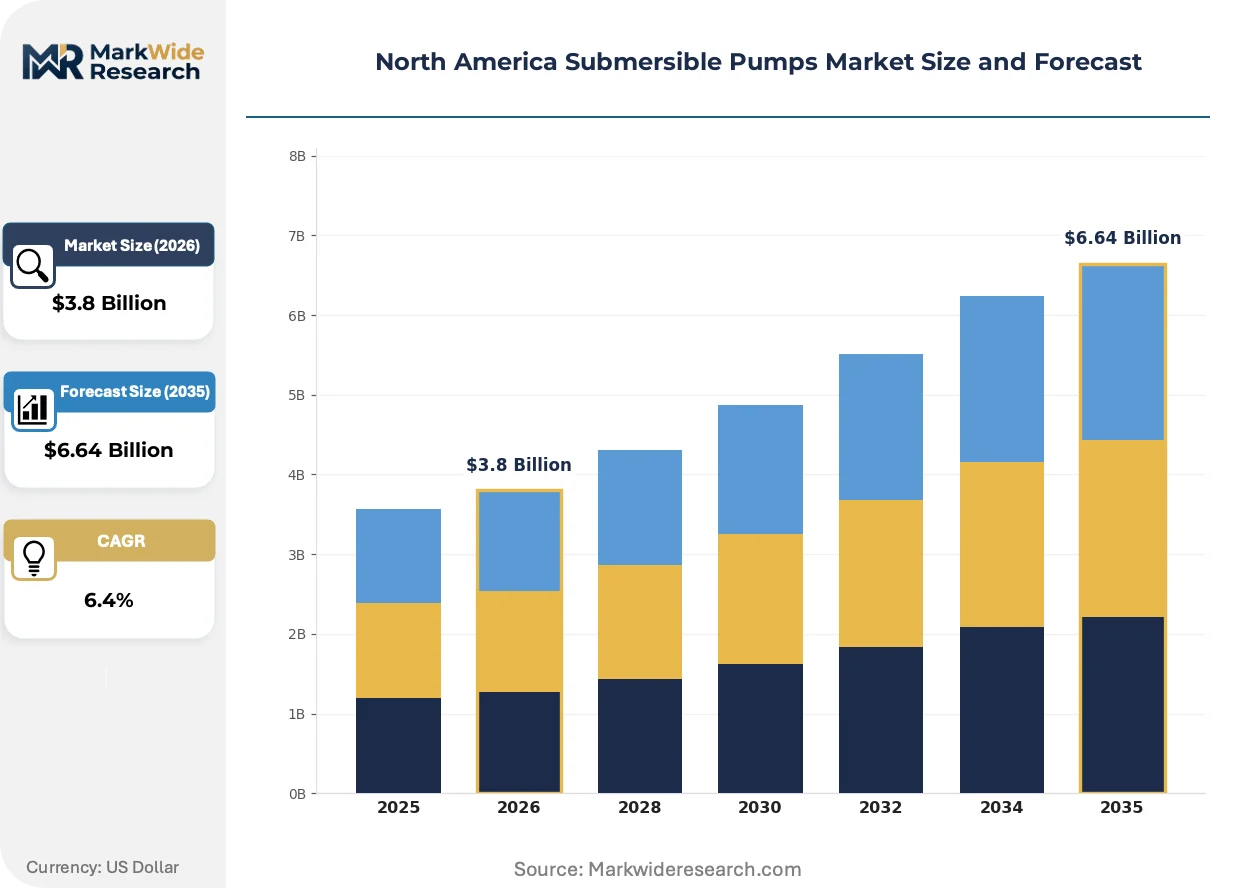
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Submersible, Hydraulic Submersible, Solar Submersible, Pneumatic Submersible Application: Agriculture, Sewage Management, Flood Control, Industrial Processes End User: Municipalities, Construction Firms, Agriculture Sector, Oil & Gas Technology: Intelligent Pumping, Variable Frequency Drive, Multistage Pumps, Smart Monitoring |
| Companies Covered | Grundfos Holding A/S, Flowserve Corp, Sulzer AG, EBARA CORPORATION, Schlumberger Limited, Gorman-Rupp Co, ITT Goulds Pumps Inc, Borets International Ltd, Atlas Copco AB, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Submersible Pumps Market Evolving Landscape
Digitalization is collapsing traditional boundaries between equipment manufacturing and lifecycle service provision, with sensor-embedded submersible pumps generating operational data that reshapes how utilities contract for reliability and energy performance.
Permanent magnet synchronous motor technology is collapsing efficiency gaps between premium and standard pump tiers across North American municipal installations. Water utilities in Arizona and Nevada are adopting these systems for deep-well groundwater extraction where energy costs dominate total ownership economics. The technology is collapsing capital allocation tradeoffs that previously favored cheaper induction motor replacements.
OSHA confined-space entry protocols are tightening deployment requirements for construction dewatering applications across the United States. Contractors must now document atmospheric monitoring and retrieval equipment compatibility before submersible pump installation in excavations and manholes. The policy shift is elevating specification priority for quick-disconnect couplings and intrinsically safe control panels.
Lifecycle contracting is displacing transactional equipment procurement across Canadian provincial water authorities. Ontario and British Columbia municipalities are bundling pump supply with ten-year energy performance guarantees and predictive maintenance subscriptions. The model concentrates vendor selection criteria on total cost of ownership rather than upfront capital expenditure.
North America Submersible Pumps Market Segmentation
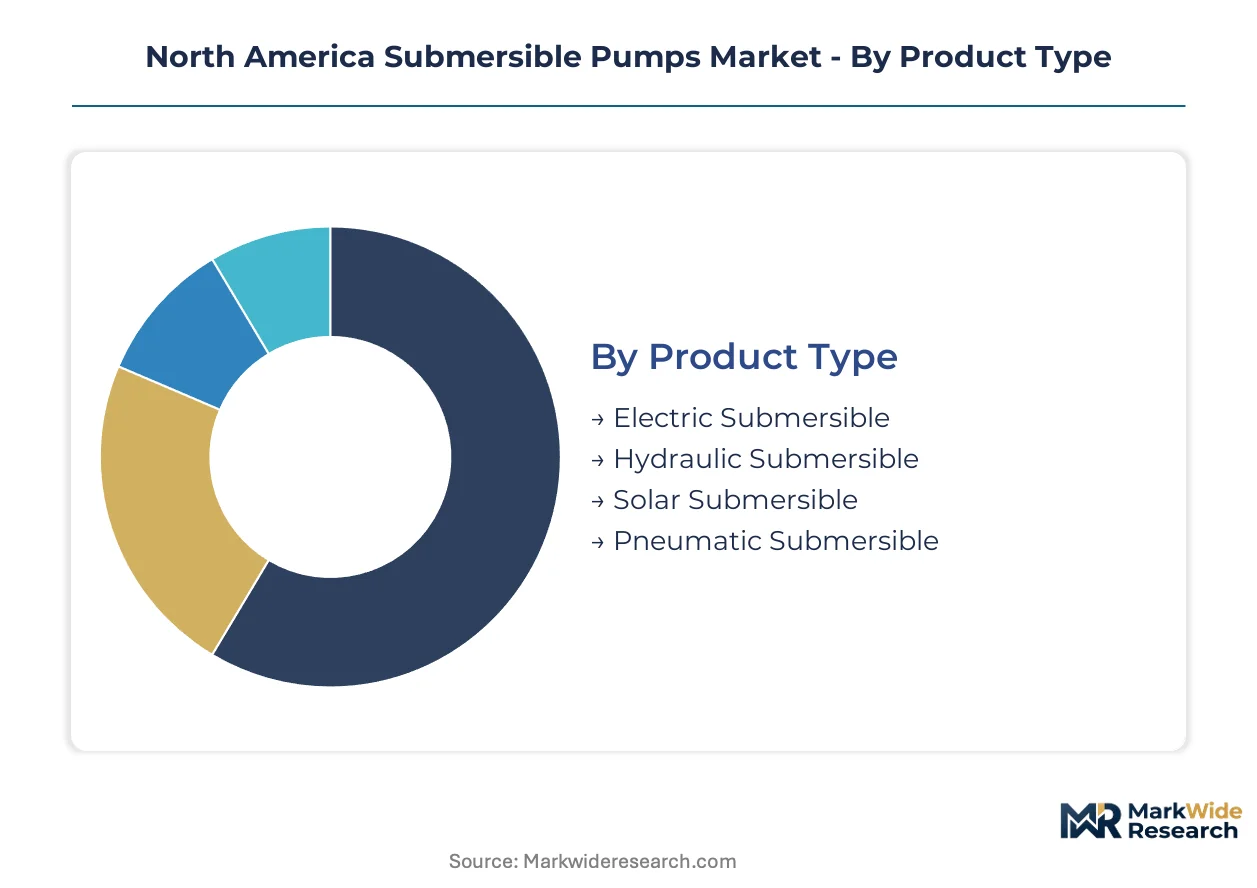
Segmentation in the North America Submersible Pumps Market reveals divergent replacement cycles and margin structures. Electric submersible systems turn over every 12-15 years in municipal installations, while intelligent technology retrofits refresh every 5-7 years. Understanding these temporal patterns guides capital allocation and aftermarket service positioning.
Product Type:
Replacement velocity varies dramatically across pump power sources, with electric systems cycling on infrastructure depreciation schedules and solar units refreshing on panel degradation timelines.
- Electric Submersible:Grid-connected multistage centrifugal units with cast iron or stainless steel housings dominate deep-well extraction. Municipal water utilities in Arizona and Nevada concentrate procurement here, driven by DOE motor efficiency mandates that disqualify legacy induction systems from federal funding eligibility.
- Hydraulic Submersible:Fluid-powered units deploy where electrical ignition hazards prohibit standard equipment. Oilfield operators in the Permian Basin specify these for volatile hydrocarbon environments, though hydraulic power unit maintenance burdens constrain expansion beyond specialty applications.
- Solar Submersible:Photovoltaic-powered DC motor systems serve off-grid agricultural irrigation in California's Central Valley, where NEM 3.0 tariff restructuring accelerates solar-plus-storage adoption.
- Pneumatic Submersible:Compressed-air-driven diaphragm pumps handle abrasive slurry transfer in mining dewatering across Nevada and Arizona, limited by compressor infrastructure requirements.
Electric submersible systems dominate installed base. Solar submersible configurations are where expansion concentrates.
Application:
Cost tier differentiation separates mission-critical continuous-duty applications from intermittent emergency deployments, with sewage management commanding premium pricing and flood control operating on municipal contingency budgets.
- Agriculture:Center-pivot and drip irrigation systems in the Central Valley and High Plains deploy high-volume submersible borehole pumps. Variable frequency drive integration is climbing fastest here as groundwater sustainability regulations tighten drawdown permits.
- Sewage Management:Wastewater lift stations and treatment plant influent pumping require NSF/ANSI 61 certified components. EPA effluent discharge standards are compressing replacement cycles as utilities face Clean Water Act compliance deadlines.
- Flood Control:Mobile dewatering pumps for hurricane response and stormwater management operate on intermittent deployment schedules. FEMA procurement specifications emphasize rapid deployment capability over energy efficiency.
- Industrial Processes:Cooling water circulation and chemical transfer applications in Texas and Louisiana petrochemical corridors specify corrosion-resistant alloys. Process uptime requirements justify premium intelligent pumping architectures.
Sewage management commands the highest per-unit pricing. Agriculture represents the steepest expansion trajectory.
End User:
Customer type determines contract structure, with municipalities favoring lifecycle performance guarantees and oilfield operators prioritizing equipment availability over capital expenditure optimization.
- Municipalities:City and county water authorities bundle pump supply with decade-long service contracts. Ontario and British Columbia provincial frameworks are displacing transactional procurement with outcome-based reliability agreements.
- Construction Firms:Dewatering contractors face OSHA confined-space entry protocol compliance costs that elevate quick-disconnect specification priority. Project-based purchasing cycles concentrate demand in spring construction seasons.
- Agriculture Sector:Farm cooperatives and large-scale irrigation districts negotiate volume pricing for standardized borehole configurations. Groundwater sustainability districts in Texas and California are restricting new well permits.
- Oil & Gas:Artificial lift operations in West Texas and southeastern New Mexico require 99.5% runtime reliability. Aftermarket service contracts generate recurring revenue independent of new equipment sales.
Municipalities anchor long-term service revenue. Oil and gas is where technology premium capture concentrates.
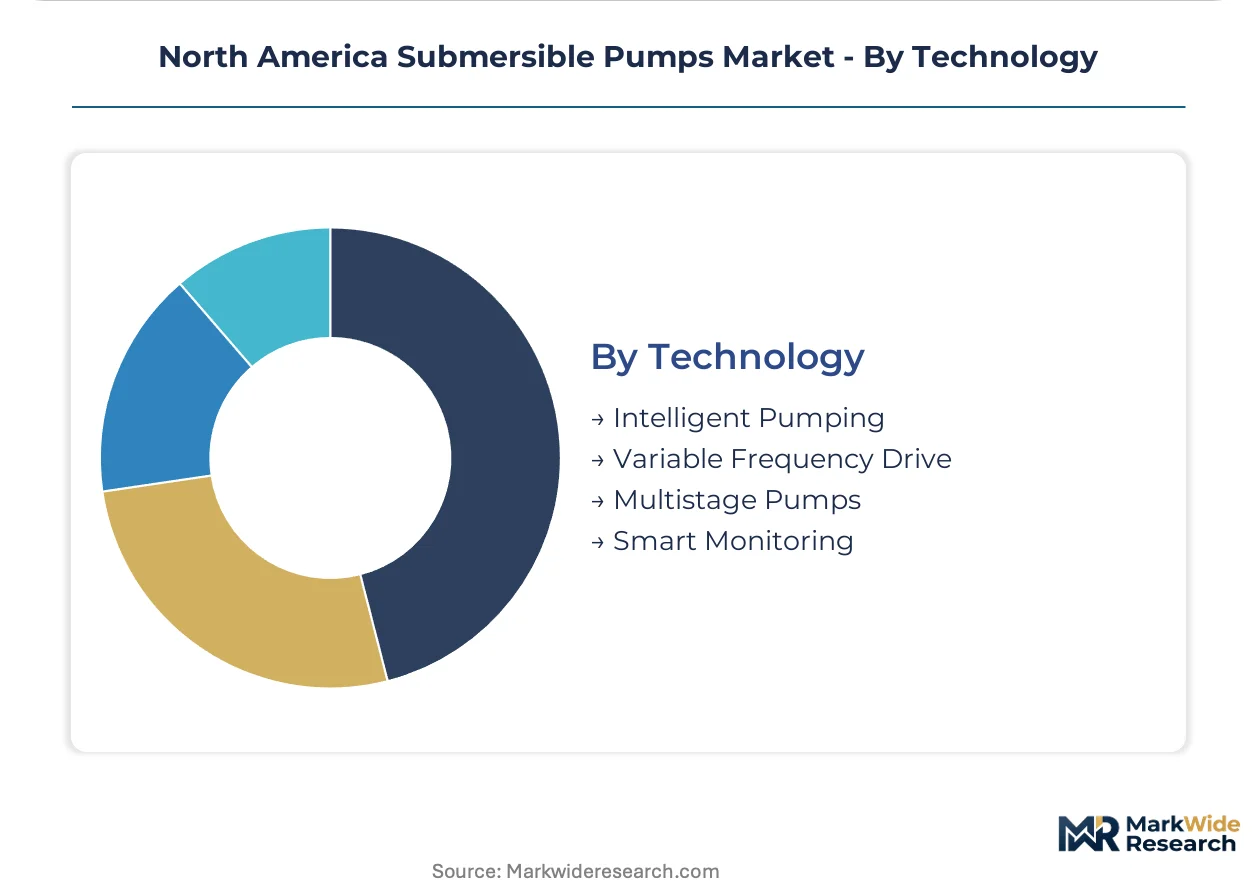
Technology:
Maturity gradients separate established electromechanical platforms from digitally native architectures, with smart monitoring systems commanding software-like margins against hardware-commoditized conventional pumps.
- Intelligent Pumping:Sensor-embedded units with embedded edge computing enable autonomous flow optimization. Water utilities in Nevada are adopting permanent magnet synchronous motor variants for deep-well extraction where energy costs dominate total ownership economics.
- Variable Frequency Drive:Grid-compatible motor controls enable precision flow matching to demand curves. California agricultural districts specify VFD-compatible pumps to comply with groundwater pumping restrictions.
- Multistage Pumps:Concentric impeller assemblies generate heads exceeding 1,000 feet for deep aquifer access. Physical limits on cast iron pressure ratings constrain further specification expansion without exotic material cost escalation.
- Smart Monitoring:Cloud-connected vibration and temperature analytics enable predictive maintenance. SCADA legacy architecture integration friction delays deployment in older municipal control systems.
Multistage pumps dominate installed base. Intelligent pumping is where margin expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity diverges sharply across North America. Canadian oil sands operators prioritize lifecycle reliability over upfront cost, while Mexican agricultural buyers face acute capital constraints that compress specification tiers.
United States
Permian Basin artificial lift intensity drives premium pump procurement in West Texas and southeastern New Mexico. EPA motor efficiency mandates under DOE Pump Energy Conservation Standards disqualify legacy induction systems from federal infrastructure funding eligibility. Houston-area foundries and motor winding facilities anchor domestic manufacturing capacity, though Gulf Coast weather exposure creates supply vulnerability.
Canada
Alberta steam-assisted gravity drainage operations require specialized high-temperature submersible systems for thermal bitumen extraction. Provincial water authorities in Ontario and British Columbia are displacing transactional procurement with decade-long lifecycle performance guarantees. Toronto and Calgary serve as aftermarket service hubs for mining dewatering and municipal infrastructure verticals.
Mexico
Groundwater-dependent agricultural irrigation in Sonora and Chihuahua states concentrates demand for cost-optimized borehole configurations. CONAGUA water concession regulations are tightening extraction permits for aquifer sustainability. Monterrey industrial corridor demand centers on automotive and aerospace cooling water circulation applications.
North America Submersible Pumps Market Competitive Landscape
Full-line manufacturers and specialized aftermarket service providers split the market along capital intensity versus lifecycle revenue vectors. The vendor base exhibits moderate concentration, with European-headquartered multinationals holding installed base advantages in municipal water verticals while North American specialists dominate oilfield artificial lift. Three archetypes define competitive positioning: integrated pump-and-service platforms, component-focused refurbishment specialists, and regional fabrication houses serving price-sensitive agricultural segments. Capacity expansion and predictive maintenance platform development constitute the dominant competitive moves across tiers.
Within the integrated platform tier, Grundfos Holding A/S and Flowserve Corp exemplify divergent geographic anchoring strategies. Grundfos represents the European-headquartered archetype with digital service platform capabilities, while Flowserve occupies a position among North American specialists with extensive refurbishment network infrastructure. Sulzer AG sits within the slurry-handling specialization vector, anchoring aftermarket solutions for mining and industrial end users.
| Leading Market Players |
|---|
| Grundfos Holding A/S |
| Flowserve Corp |
| Sulzer AG |
| EBARA CORPORATION |
| Schlumberger Limited |
| Gorman-Rupp Co |
| ITT Goulds Pumps Inc |
| Borets International Ltd |
| Atlas Copco AB |
| Others |
Value Network & Pricing Analysis
Texas manufacturing clusters for cast iron foundries and motor winding facilities concentrate upstream supply, anchoring margin capture in aftermarket service tiers rather than original equipment transactions. This geographic concentration feeds directly into how vendors structure lifetime value contracts with municipal utilities and oilfield operators.
Pricing Analysis
Aftermarket service contracts and predictive maintenance subscriptions generate the dominant lifetime value streams, displacing transactional equipment sales as the primary revenue anchor. Three-tier pricing structure across premium intelligent systems, standard electric submersibles, and economy agricultural configurations reflects certification grade and after-sales bundling intensity. Cost compression in standard electric tiers is intensifying because raw material volatility for stainless steel housings destabilizes project bidding. Agricultural cooperatives in California and Texas exhibit the highest price sensitivity, while Canadian oil sands operators prioritize lifecycle reliability over upfront capital expenditure.
Supply Chain Analysis
Extended payment terms from Houston-area foundries and supply-chain finance facilities for motor component distributors are stabilizing working capital across the supplier tier. Manufacturing draws from the United States, Mexico, and Canada, with cast iron foundries, permanent magnet motors, and multistage impeller assemblies as critical inputs. Single-source vulnerability around Gulf Coast weather exposure creates geographic risk concentration. Distribution runs through direct OEM channels for municipal utilities and oilfield operators, with regional fabrication houses serving price-sensitive agricultural segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity persists across intelligent pumping retrofits and Canadian thermal extraction verticals, as EPA compliance windows and provincial procurement shifts create niche entry points for specialized service providers.
For Market Incumbents: Harden aftermarket platform moats through predictive maintenance software integration and captive refurbishment network expansion in Alberta and Texas. Capacity addition in Monterrey industrial corridor addresses tariff exposure on cross-border component flows. Certification investment in NSF/ANSI 61 potable water compliance defends against emerging entrants targeting municipal procurement bottlenecks. For New Entrants and Emerging Players: Mid-market solar submersible configurations for California agricultural districts represent the most penetrable entry point, given NEM 3.0 tariff restructuring and groundwater sustainability enforcement gaps. Canadian provincial water authorities in Ontario and British Columbia offer second-tier opportunity through lifecycle contracting displacement of incumbent service relationships. Go-to-market execution should anchor on energy performance guarantee structures rather than equipment-centric value propositions. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across intelligent pumping technology stacks as sensor commoditization and cloud analytics platform consolidation reduce hardware-dependent scaling requirements. Acquisition targets should concentrate on software-native predictive maintenance providers with embedded utility customer relationships. The signal to watch is municipal procurement specification evolution toward outcome-based reliability metrics rather than capital expenditure thresholds.| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Maintenance Platform Development | Recurring revenue capture from Nevada and Arizona water utilities reduces equipment sales cyclicality. |
| Permanent Magnet Motor Manufacturing Scale-Up | DOE efficiency compliance positions vendors for federal infrastructure funding eligibility. |
| Canadian Oil Sands Thermal System Specialization | High-temperature submersible expertise anchors decade-long service contracts in Alberta. |
| SCADA Integration Middleware Investment | Legacy utility control system compatibility unlocks intelligent pump retrofit opportunities. |
| Domestic Content Assembly Expansion | IRA manufacturing incentives attract pump production investment to US-based facilities. |
Research Methodology
Cross-validation between primary interviews with municipal water utility procurement directors, oilfield artificial lift engineers, and aftermarket service heads anchors the qualitative findings against secondary validation. Plant managers at Texas and California foundries, OEM procurement teams, and maintenance directors at Nevada mining operations provided operational perspective. Secondary sources include EPA enforcement databases, DOE pump efficiency standard filings, FEMA procurement specifications, and provincial water authority contract disclosures. Bottom-up unit economics and top-down infrastructure spending trajectories were triangulated to bound estimation error.
Calibration against historical replacement cycle data and regulatory compliance window timelines informed the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, application vertical, end user archetype, and technology maturity tier, with regional regulatory cluster as an additional industry-specific dimension. CAGRs were derived from installed base turnover rates and capital expenditure pipeline analysis. Forecast inputs incorporated groundwater sustainability permit restrictions and Clean Water Act enforcement intensity variations.
Practitioners should monitor EPA motor efficiency mandate expansion and provincial procurement specification evolution for early signals of demand inflection. Forecasts reflect assumptions regarding regulatory compliance timeline adherence and raw material price stabilization. Macroeconomic deviation, regulatory enforcement acceleration, or permanent magnet motor technology disruption would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pumps and Control Devices
Wind Powered Water Pumps Market
Pumps and Control Devices
Regenerative Turbine Pump Market
Pumps and Control Devices
Global Submersible Pumps Market
Pumps and Control Devices
Global Vacuum Pump Market
Pumps and Control Devices
Global Lubrication Pumps Market
Pumps and Control Devices
Split Casing Pump Market
Pumps and Control Devices
High Power Air Pump Market
Pumps and Control Devices
Multistage Pump Market
Pumps and Control Devices
Radial Piston Pumps Market
Pumps and Control Devices
Seawater Pump Market
Pumps and Control Devices
Canned Motor Pumps Market
Pumps and Control Devices
North America Positive Displacement Pumps Market
Pumps and Control Devices
Global Smart Pumps Market
Pumps and Control Devices
Horizontal Pumping Systems (HPS) Market
Pumps and Control Devices
Pumps and Trigger Spray Market
Pumps and Control Devices
Latin America Pumps Market