
 Volute Pump Market | 2026-2036
Volute Pump Market Size, Share, and Industry Trends Forecast 2026-2036
Volute Pump Market Analysis
Project finance for municipal water infrastructure is reshaping competitive access in the volute pump sector, allowing asset-light operators to bid against capital-intensive incumbents. Grundfos leverages its integrated manufacturing footprint across Europe and Asia to sustain cost discipline on large municipal contracts. KSB SE & Co. KGaA anchors its position through deep specialization in engineered metallurgy for corrosive fluid handling. Xylem Inc. differentiates via digital monitoring overlays that extend service revenue streams beyond hardware sales.
A volute pump channels fluid through a spiral-shaped casing that converts kinetic energy into pressure via a continuously expanding flow cross-section, typically achieving efficiencies of 70-85 percent at best-efficiency point depending on specific speed and impeller geometry. The primary industrial purpose spans water distribution, wastewater transfer, and process fluid circulation where stable head-capacity curves matter. Centrifugal designs dominate installed base value owing to decades of standardization and broad interchangeability of components. Submersible configurations represent the fastest-expanding product category as wet-pit installations eliminate suction piping complexity in flood-prone treatment facilities. Electric-drive technology leads absolute unit shipments, though hydraulic power recovery turbines capture margin pools in high-head oil and gas applications.
The EPA enforces Clean Water Act effluent standards that mandate redundant pumping capacity at municipal treatment plants, directly expanding replacement demand cycles. Ecodesign regulations from the EU commission set minimum efficiency index thresholds for motors above 0.75 kW, pushing OEMs toward permanent-magnet synchronous designs and variable-frequency drives. China's MEE administers discharge permits that tighten total nitrogen limits, forcing upgrades to higher-head multistage volute configurations in nutrient-removal trains. Stakeholders must monitor how tightening carbon-border adjustments affect foundry energy costs and whether captive casting capacity becomes a decisive competitive variable.
Market Dynamics
EU Ecodesign minimum efficiency index thresholds for motors above 0.75 kW are forcing OEMs toward permanent-magnet synchronous designs and variable-frequency drives, compressing margins for legacy induction-motor suppliers.
Growth Catalysts
- EPA Clean Water Act effluent standards:The EPA mandates redundant pumping capacity at municipal treatment plants, directly expanding replacement demand cycles for volute pump installations.
- Submersible wet-pit configurations:Flood-prone treatment facilities in coastal zones are eliminating suction piping complexity through submersible volute pump adoption.
- China municipal wastewater infrastructure:Urbanization intensifies procurement of electric-drive centrifugal units as water supply utilities scale buildouts.
Market Restraints
- Foundry energy cost volatility:Carbon-border adjustments tighten input costs for cast-iron and stainless-steel volute casings, squeezing mid-tier OEM margins.
- Captive casting capacity concentration:Supply-side consolidation among specialized foundries in Germany and Japan creates bottleneck risk for precision-machined volute components.
- Hydraulic power recovery turbine substitution:High-head oil and gas applications increasingly deploy energy-recovery devices that bypass traditional volute pump trains.
Strategic Opportunities
- Digital monitoring overlay convergence:Vibration sensing and cloud-based predictive analytics are merging with volute pump hardware to generate recurring service revenue streams.
- India municipal water project finance:Asset-light operators can bid against capital-intensive incumbents as state-level utilities issue performance-linked procurement tenders.
- EU Green Deal circularity mandates:Remanufacturing obligations for industrial equipment create aftermarket revenue pools for volute pump refurbishment specialists.
Industry Challenges
- Permanent-magnet motor engineering talent scarcity:OEMs face recruitment gaps for synchronous motor design expertise as efficiency regulations tighten.
- Legacy SCADA integration complexity:Digital-native monitoring systems encounter protocol friction when retrofitting decades-old municipal pump stations.
- CE marking timeline compression:Accelerated Ecodesign compliance deadlines strain certification bandwidth for smaller European pump manufacturers.
Report Scope
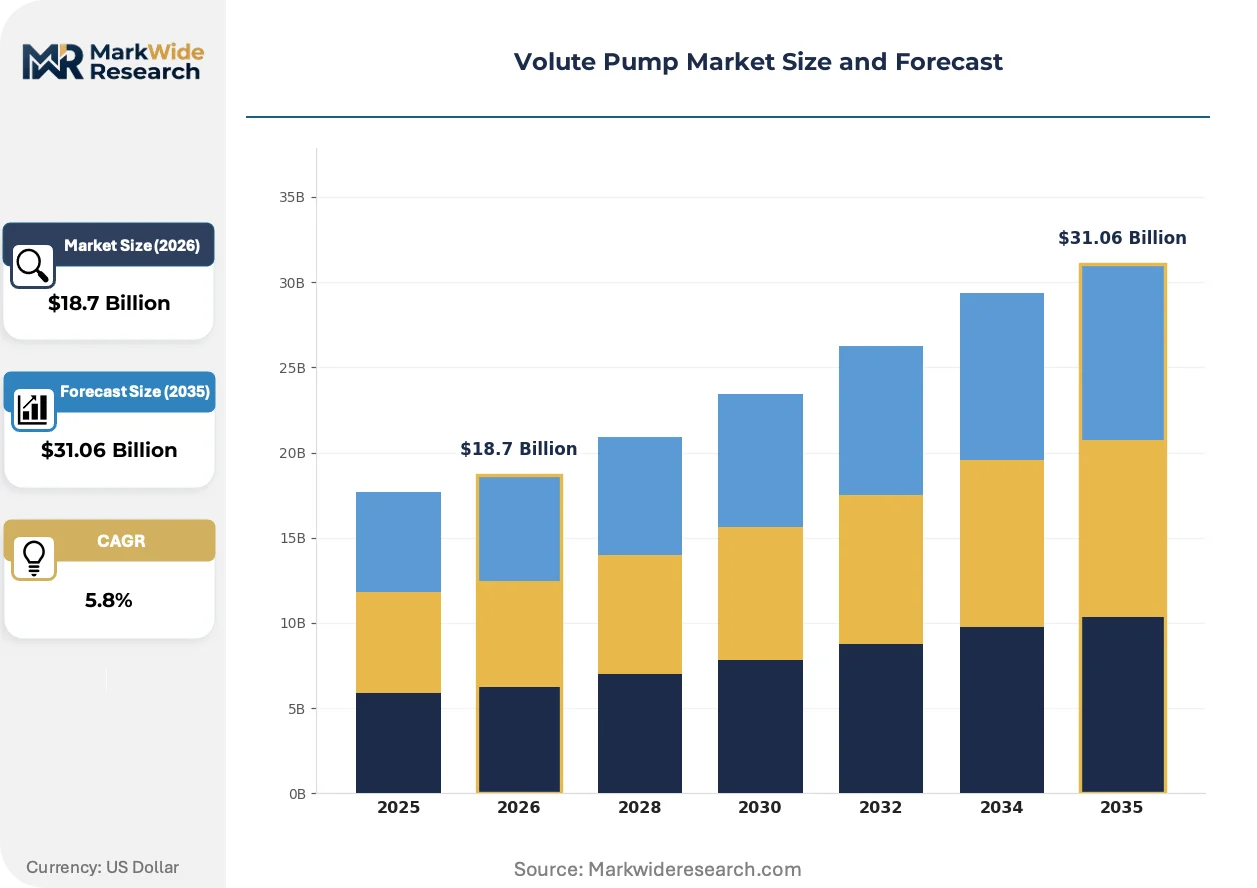
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Volute Pump Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Centrifugal, Submersible, Self-Priming, Vertical End User: Industrial, Agriculture, Municipal, Construction Technology: Electric, Hydraulic, Pneumatic, Mechanical Application: Water Supply, Wastewater Management, Irrigation, Fire Protection |
| Companies Covered | Grundfos, Wilo SE, KSB SE & Co. KGaA, Xylem Inc., Flowserve Corporation, Sulzer Ltd, Pentair plc, Weir Group plc, Ebara Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Volute Pump Market Emerging Trajectories
Three distinct vectors are reshaping volute pump technology and commercialization: embedded intelligence in hardware, tightening efficiency mandates, and evolving procurement modalities in municipal infrastructure.
Condition-based monitoring systems are digitizing field operations across water utilities. These sensor-embedded volute pumps transmit vibration, temperature, and flow data to centralized dashboards. Municipal operators in Denmark and Singapore are deploying them at scale. The technology is digitizing maintenance scheduling, compressing unplanned downtime and shifting vendor revenue toward subscription-based service contracts.
REACH restrictions on hexavalent chromium coatings are forcing metallurgical redesigns for corrosive fluid handling. The regulation bans traditional surface treatments for pump components exposed to wastewater and chemical process streams. European OEMs are accelerating engineered polymer and duplex stainless-steel adoption. High-head multistage configurations for nutrient-removal trains face the steepest compliance cost escalation.
Performance-based contracting is displacing traditional equipment-only sales in municipal procurement. Water utilities in Australia and the Netherlands now specify guaranteed uptime and energy consumption thresholds rather than capital expenditure limits. Channel intermediaries lose relevance as manufacturers establish direct service arms. This shift concentrates in large urban treatment facilities with sufficient scale to underwrite outcome-based risk allocation.
Volute Pump Market Segmentation
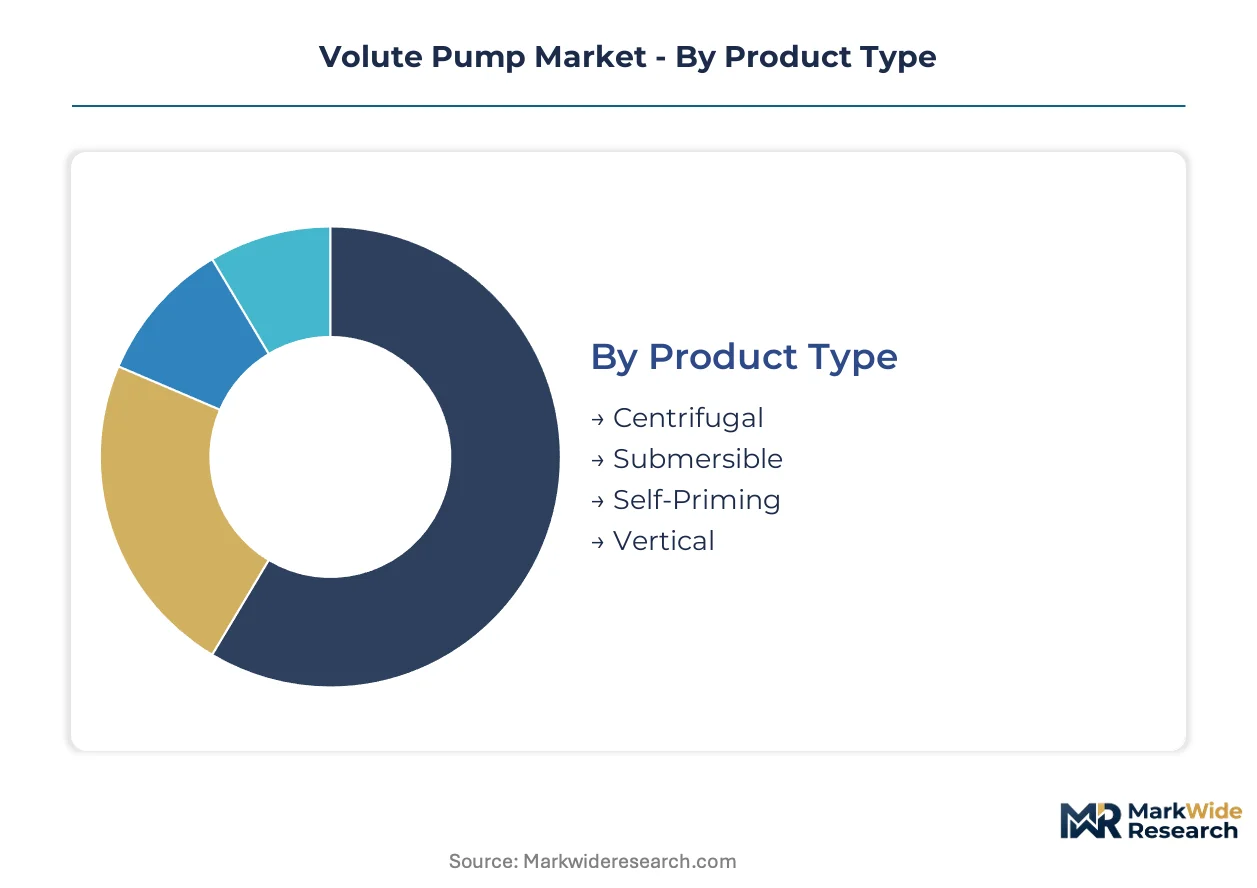
Segmentation in the volute pump market reveals divergent replacement cycles and margin structures across configurations. Product type and application drive fundamentally different procurement rhythms, while technology choice determines regulatory exposure and aftermarket revenue potential.
Product Type:
Centrifugal units turn over slowest due to decades of standardization and rebuild economics, while submersible configurations cycle fastest as coastal utilities accelerate wet-pit retrofits.
- Centrifugal:Spiral-casing designs convert kinetic energy to pressure through expanding flow cross-sections, achieving 70-85 percent efficiency at best-efficiency point. Municipal water distribution networks in China and India absorb the largest procurement volumes as urbanization strains legacy infrastructure. These units dominate installed base value owing to component interchangeability and established service ecosystems.
- Submersible:Wet-pit configurations eliminate suction piping and flood-risk exposure in below-grade installations. Coastal treatment facilities from Florida to Bangladesh are specifying these for climate-resilient pump stations. Submersible volute pumps are where expansion concentrates as operators prioritize operational continuity over capital minimization.
- Self-Priming:Suction-lift capability suits intermittent-duty dewatering and mobile construction applications where permanent installation is uneconomical.
- Vertical:Space-constrained installations in high-rise buildings and compact treatment plants favor column-suspended designs with motor mounting above flood level.
Centrifugal designs dominate installed base. Submersible configurations are where expansion concentrates.
End User:
Cost tier stratification separates premium-specified municipal contracts from price-sensitive agricultural procurement, with industrial buyers occupying a middle ground on total lifecycle valuation.
- Industrial:Process fluid circulation in chemical, pharmaceutical, and food processing demands corrosion-resistant metallurgy and tight head-capacity stability. REACH restrictions on hexavalent chromium coatings are forcing metallurgical redesigns across European process industries, compressing margins for legacy suppliers while creating openings for duplex stainless-steel specialists.
- Municipal:Water utilities specify redundant capacity under EPA Clean Water Act mandates, with procurement increasingly shifting to performance-based contracting. Danish and Singaporean operators now embed condition-monitoring sensors as standard, digitizing maintenance scheduling and compressing unplanned downtime. Municipal represents the fastest-growing trajectory as urban infrastructure buildouts accelerate across developing economies.
- Agriculture:Irrigation districts prioritize capital minimization over efficiency optimization, creating a price-commoditized segment vulnerable to foundry cost volatility.
- Construction:Temporary dewatering and site water management drive rental-fleet demand with rapid asset turnover and minimal service attachment.
Industrial applications command premium pricing through specification intensity. Municipal procurement is climbing the fastest as project finance reshapes competitive access.
Technology:
Volume concentration in electric-drive units contrasts with margin concentration in hydraulic power recovery, where energy-recovery turbines capture value in high-head oil and gas applications.
- Electric:Permanent-magnet synchronous motors paired with variable-frequency drives are displacing induction designs as EU Ecodesign minimum efficiency index thresholds tighten above 0.75 kW. OEMs face engineering talent scarcity in synchronous motor design, compressing certification bandwidth for smaller manufacturers.
- Hydraulic:Power recovery turbines in offshore and downstream oil and gas bypass traditional pump trains, capturing margin pools where energy economics justify capital intensity.
- Pneumatic:Explosion-risk environments and remote installations without reliable grid access specify air-driven units for intrinsic safety and operational independence.
- Mechanical:Direct-drive configurations persist in specialized low-speed, high-torque applications where electronic complexity introduces unacceptable failure modes.
Electric technology anchors absolute unit shipments. Hydraulic configurations concentrate margin capture in energy-intensive process loops.
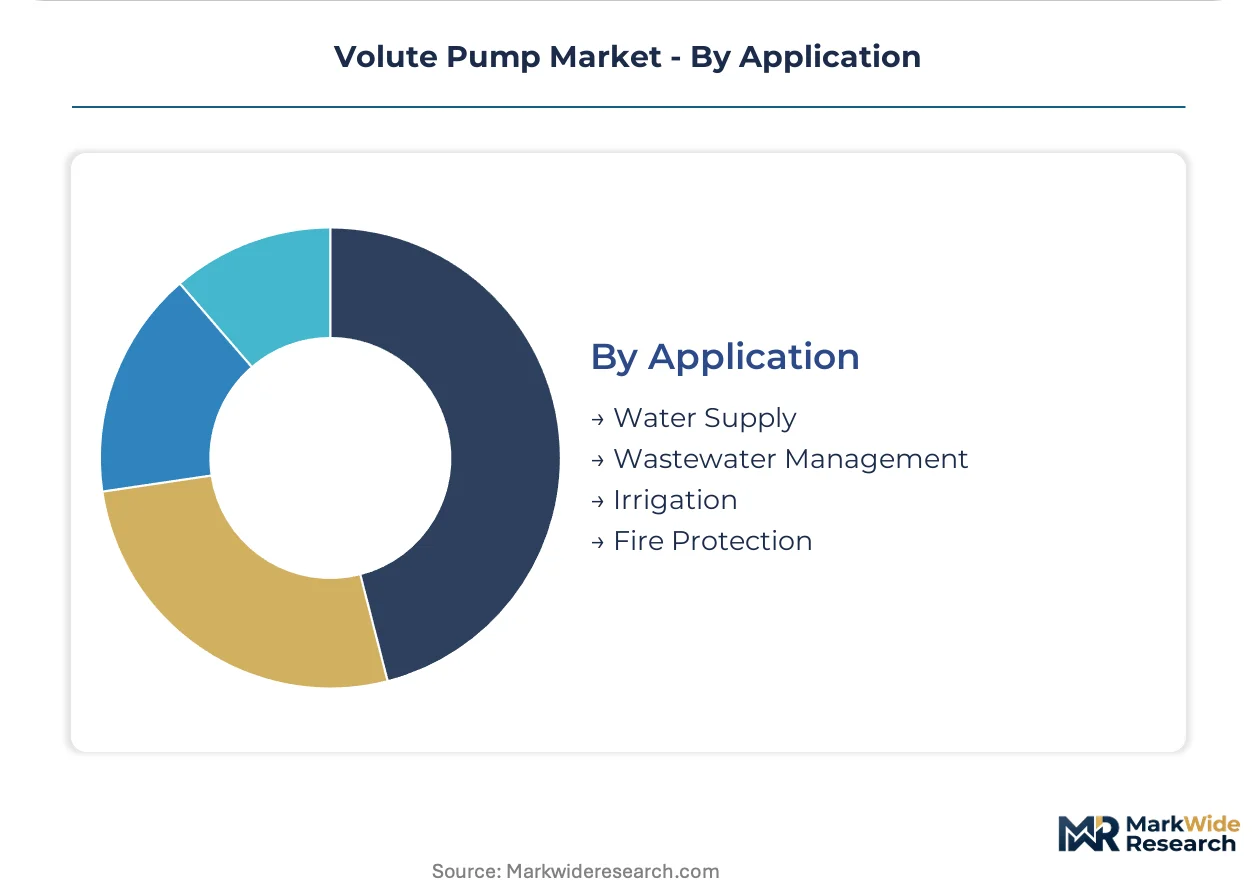
Application:
Geography determines application priority, with water-stressed regions emphasizing supply security while nutrient-loading regulations in developed markets drive wastewater upgrade cycles.
- Water Supply:Raw water intake, treatment, and distribution infrastructure commands the largest absolute investment flows. China's MEE discharge permits are tightening total nitrogen limits, forcing upgrades to higher-head multistage volute configurations in nutrient-removal trains.
- Wastewater Management:Effluent standards mandate redundant pumping capacity, directly expanding replacement demand cycles. Australia's performance-linked procurement tenders now specify guaranteed uptime rather than capital expenditure limits, concentrating channel power with manufacturers establishing direct service arms.
- Irrigation:Surface and pressurized systems in water-stressed agricultural regions face efficiency mandates that favor electric-drive centrifugal units over traditional diesel alternatives.
- Fire Protection:Code-mandated standby capacity in commercial and industrial facilities creates stable replacement demand with limited technology disruption.
Water supply applications dominate installed base value. Wastewater management is gaining share fastest as regulatory tightening accelerates upgrade cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import balances in precision-machined volute casings are tightening as carbon-border adjustments reshape foundry economics. Germany and Japan maintain casting capacity surpluses, while China and India absorb growing import volumes for municipal infrastructure buildouts. Currency volatility and energy cost differentials are redirecting procurement flows across three continents.
China
Urban wastewater infrastructure expansion drives procurement of electric-drive centrifugal units across the Yangtze River Delta. The MEE tightens total nitrogen discharge limits, forcing upgrades to higher-head multistage volute configurations. Shanghai's municipal water authorities are embedding condition-monitoring sensors in new treatment plant installations.
Germany
Engineered metallurgy for corrosive fluid handling anchors demand from chemical process industries along the Rhine corridor. EU Ecodesign minimum efficiency index thresholds push OEMs toward permanent-magnet synchronous motor redesigns. Bavarian pump manufacturers are consolidating captive casting capacity to defend margin positions against energy cost volatility.
United States
EPA Clean Water Act mandates for redundant pumping capacity expand replacement cycles at municipal treatment facilities. Coastal utilities from Florida to Louisiana specify submersible wet-pit configurations for climate-resilient installations. Houston's energy sector deploys hydraulic power recovery turbines in high-head downstream applications.
India
State-level utilities issue performance-linked procurement tenders, allowing asset-light operators to challenge capital-intensive incumbents. The CEA promotes efficiency standards for motors above 0.75 kW, accelerating variable-frequency drive adoption. Gujarat's industrial corridors are scaling process fluid circulation infrastructure for pharmaceutical manufacturing clusters.
Japan
Precision-machined volute component exports sustain foundry specialization against regional cost competition. METI efficiency directives align with EU Ecodesign thresholds, compressing certification timelines for smaller manufacturers. Osaka-Kobe industrial zones concentrate submersible pump fabrication for flood-prone Asian coastal markets.
Volute Pump Market Vendor Landscape
On the supply side, the industry is consolidating around integrated manufacturing footprints and specialized metallurgy capabilities. Tiered competition separates premium-efficiency specialists from mid-tier standard-product suppliers. Two strategic archetypes dominate: diversified fluid-handling conglomerates with digital service overlays, and focused pump engineering houses with captive casting capacity. Competitive moves concentrate on backward integration into precision foundry operations and geographic expansion through project finance partnerships in developing economies.
Within the diversified conglomerate tier, Grundfos and Xylem Inc. exemplify integrated global manufacturing with digital monitoring capabilities. KSB SE & Co. KGaA anchors the specialized engineering archetype through deep metallurgical expertise. These three entities occupy distinct competitive positions: the Danish-German integrated manufacturer, the US-based digital-native service platform, and the German family-controlled engineering specialist with foundry-linked cost discipline.
| Leading Market Players |
|---|
| Grundfos |
| Wilo SE |
| KSB SE & Co. KGaA |
| Xylem Inc. |
| Flowserve Corporation |
| Sulzer Ltd |
| Pentair plc |
| Weir Group plc |
| Ebara Corporation |
| Others |
Supply Flow & Price Mechanics
Foundry undercapacity in Germany and Japan is compressing casting lead times and amplifying pricing power for precision-machined volute component suppliers, forcing OEMs to accept premium terms or absorb margin erosion. This utilization squeeze cascades through the value chain, with municipal buyers facing extended procurement cycles and industrial accounts confronting tiered price escalation based on metallurgical specification intensity.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels, with differentiation driven by duplex stainless-steel grade and CE marking tier. Municipal procurement offices exhibit lowest price sensitivity due to performance-based contracting mandates, while agricultural irrigation districts face acute cost compression amid foundry energy volatility. Pricing pressure stems from carbon-border adjustments tightening input costs for cast-iron casings.
Supply Chain Analysis
Tariff exposure between China and the European Union dominates supply chain risk planning for volute pump OEMs sourcing precision-machined components. Manufacturing concentrates in Germany, Japan, and China, with raw material dependencies on nickel-alloy steel, cast iron, and engineered polymers. Single-source vulnerability persists for permanent-magnet synchronous motor stators. Distribution runs through direct service arms and specialized fluid-handling distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Municipal water utility consolidation across developing economies is shifting procurement leverage toward fewer, larger buyers with performance-linked tender requirements. This buyer-power concentration demands strategic repositioning across three stakeholder archetypes.
For Market Incumbents: Build captive foundry capacity as a cost-discipline moat against mid-tier competitors exposed to carbon-border energy cost spikes. Secure backward integration into precision casting operations in Bavaria or Osaka-Kobe industrial zones. Deepen digital monitoring overlay penetration to convert hardware sales into recurring service revenue streams, insulating against price commoditization in standard centrifugal configurations. For New Entrants and Emerging Players: Establish a beachhead in India's state-level municipal water project finance tenders, where asset-light operators can challenge capital-intensive incumbents on performance-linked risk allocation. Target submersible wet-pit configurations for flood-prone coastal treatment facilities in Bangladesh and Vietnam. Lead with vibration-sensing hardware bundled into subscription maintenance contracts rather than transactional equipment sales. For Investors and Strategic Acquirers: Capital is best deployed toward specialized foundry-linked pump engineering houses with permanent-magnet synchronous motor design capabilities, given engineering talent scarcity and tightening EU Ecodesign efficiency thresholds. Long-term viability favors entities with demonstrated certification bandwidth and direct municipal service arms. Watch for inflection in carbon-border adjustment stringency affecting foundry input costs.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precision Foundry Operations | Captive casting capacity in Germany defends margin positions against energy cost volatility from EU carbon-border mechanisms. |
| Digital Monitoring Overlay Deployment | Condition-based maintenance contracts with Danish and Singaporean utilities shift revenue from hardware to recurring service streams. |
| Permanent-Magnet Synchronous Motor Certification | EU Ecodesign compliance above 0.75 kW thresholds opens municipal procurement access while squeezing legacy induction-motor suppliers. |
| Performance-Based Contracting Capability | Guaranteed uptime tenders in Australia and the Netherlands displace channel intermediaries and concentrate manufacturer-direct relationships. |
| Submersible Wet-Pit Configuration Expansion | Climate-resilient installations from Florida to Bangladesh eliminate suction piping complexity and accelerate replacement cycles. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with municipal procurement directors, plant engineers at chemical process facilities, aftermarket service heads, and foundry operations managers; and secondary validation through customs trade data, SEC filings of listed pump manufacturers, EPA Clean Water Act enforcement records, and EU Ecodesign compliance databases. Bottom-up unit shipment estimates were triangulated against top-down infrastructure investment flows across the analysis window.
Forecast inputs incorporated product type segmentation by centrifugal, submersible, self-priming, and vertical configurations; end-user stratification across municipal, industrial, agricultural, and construction demand pools; and technology differentiation between electric-drive and hydraulic power recovery systems. CAGRs were derived from regression modeling of historical procurement cycles against regulatory compliance deadlines and urbanization-driven infrastructure buildouts. Permanent-magnet motor adoption curves and carbon-border adjustment impact scenarios were integrated as industry-specific variables.
Stress conditions across foundry energy cost volatility, currency fluctuation in precision-machined component trade, and municipal project finance availability were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory timeline adherence and infrastructure investment continuity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pumps and Control Devices
Europe Asia Submerged Pump Market
Pumps and Control Devices
Axial Piston Pumps Market
Pumps and Control Devices
Centrifugal Water Pump Market
Pumps and Control Devices
Global Piston Pumps Market
Pumps and Control Devices
Chopper Pumps Market
Pumps and Control Devices
Rental Industrial Pump Market
Pumps and Control Devices
Canned Motor Pumps Market
Pumps and Control Devices
Radial Piston Pumps Market
Pumps and Control Devices
North America Positive Displacement Pumps Market
Pumps and Control Devices
Industrial Oil Filter Machine Market
Pumps and Control Devices
Global Diaphragm Pump Market
Pumps and Control Devices
Progressing Cavity Pump Market
Pumps and Control Devices
Global Pumps Market
Pumps and Control Devices
Electrostatic Spraying System Market
Pumps and Control Devices
Metering Pump Market
Pumps and Control Devices
Radial Flow Pump Market