
 Global Seed Treatment Chemicals Market | 2026-2036
Global Seed Treatment Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Global Seed Treatment Chemicals Market Intelligence
The traditional separation between chemical formulation expertise and microbial science talent is collapsing under the pressure to develop integrated seed treatment solutions. Bayer AG leverages its dual expertise in both crop science and biologicals to develop synergistic products. BASF SE specializes in advanced chemical formulations that enhance the efficacy of both synthetic and biological active ingredients. Corteva Agriscience differentiates through its focus on genetic traits and complementary seed-applied technologies.
Seed treatment chemicals are formulations applied directly to seeds to protect them from pathogens and pests during early growth stages. These substances, delivered via methods like film coating or pelleting, create a protective zone around the seed to ensure successful germination and plant establishment. Insecticides and fungicides constitute the largest product type categories, protecting high-value cereal crops and oilseeds from disease and insect pressure. The biostimulants segment, however, represents the fastest-growing category as seed companies seek to enhance nutrient uptake and overall stress tolerance.
Regulatory frameworks from the US Environmental Protection Agency (EPA) and the European Chemicals Agency (ECHA) under REACH govern the registration and market access of active ingredients. These strict regulations directly influence product portfolios, forcing the phase-out of certain legacy chemistries and promoting lower-risk biological alternatives. Stakeholder success now depends on navigating divergent international regulatory timelines and investing in multi-functional products that combine pest control with plant health benefits.
Market Dynamics
The convergence of chemical formulation and microbial science is the central force shaping the seed treatment market. Pressure to create integrated solutions that combine pest protection with plant health benefits is breaking down traditional silos, compelling investment in multi-disciplinary research and development to meet new regulatory and agronomic demands.
Growth Catalysts
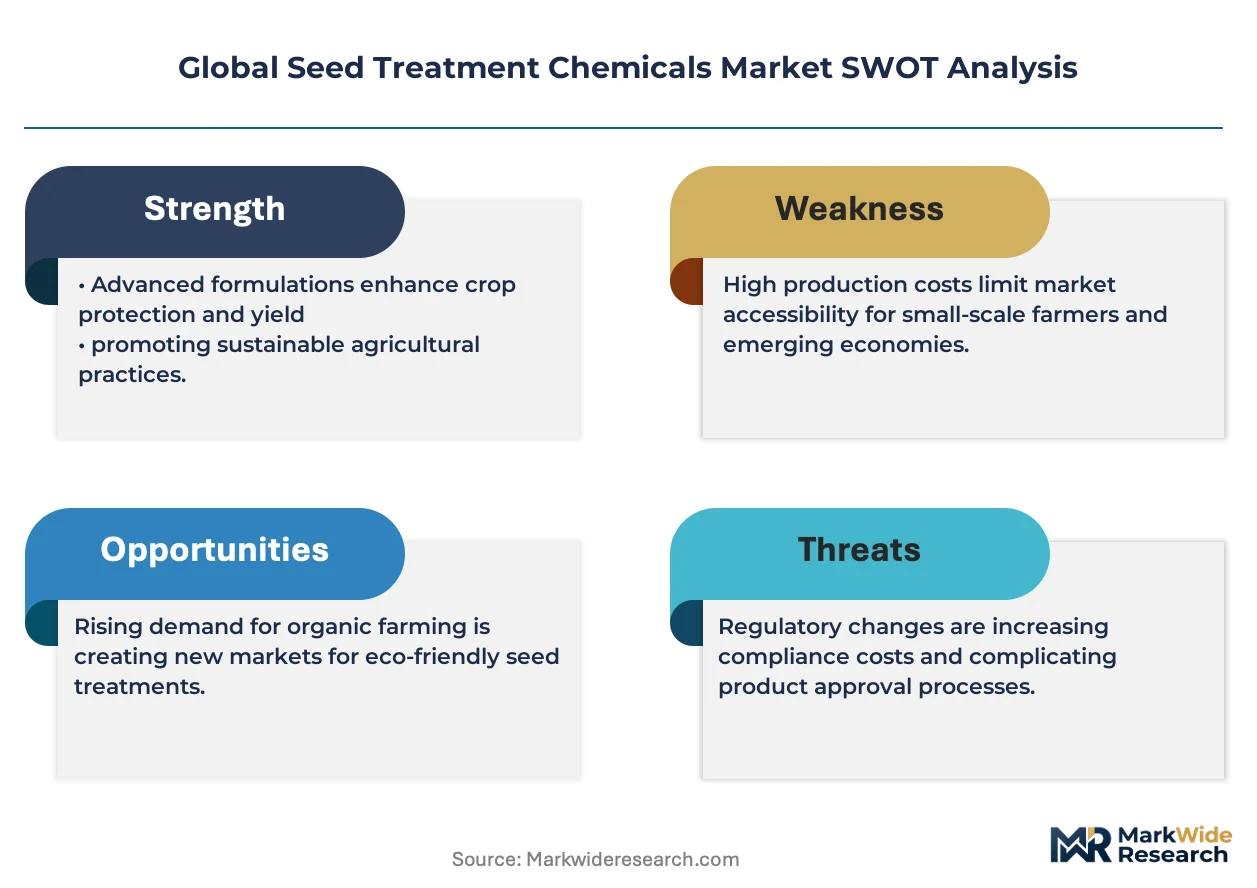
- Regulatory Shift to Biologicals:Policy frameworks like the EU Green Deal incentivize the substitution of synthetic pesticides with biological alternatives, creating a direct pull for biostimulant and microbial-based seed treatments to gain market access.
- Intensive Cereal Crop Farming:Demand for higher yields in staple crops such as corn and wheat, particularly in large-scale agricultural systems, drives the adoption of advanced seed treatments to protect genetic investment and ensure plant establishment.
- Advanced Application Technologies:Innovations in film coating and pelleting allow for the precise application of multiple active ingredients, enabling the development of sophisticated, multi-functional products that combine insecticides, fungicides, and biostimulants.
Market Restraints
- Divergent Regulatory Hurdles:The lengthy and costly approval processes governed by agencies like the US EPA and ECHA, coupled with differing standards between countries, create significant barriers to market entry and slow the international rollout of new active ingredients.
- High Research and Development Costs:Discovering, testing, and registering new active ingredients, whether chemical or biological, requires substantial long-term investment, limiting the number of new products that can be brought to market.
- Genetic Trait Substitution:The development of genetically modified seeds with inherent pest and disease resistance can reduce or eliminate the need for certain chemical seed treatments, posing a direct substitution threat to specific product categories.
Strategic Opportunities
- Emerging Agricultural Economies:Large agricultural producers in regions like Southeast Asia and Latin America represent significant growth opportunities for advanced seed treatments as their farming practices modernize and intensify.
- Nitrogen-Fixing Biologicals:Beyond general stress tolerance, there is a substantial opportunity in developing and marketing microbial treatments specifically for nitrogen fixation, addressing a critical nutrient need and reducing reliance on synthetic fertilizers.
- Precision Agriculture Integration:Combining seed treatment prescriptions with data from digital farming platforms, such as soil sensors and drone imagery, allows for customized, site-specific applications that optimize efficacy and return on investment.
Industry Challenges
- Cross-Disciplinary Talent Scarcity:A significant operational challenge is recruiting and retaining scientists with expertise in both microbial science and advanced chemical formulation, a skill set essential for developing integrated products.
- Intellectual Property Complexity:Protecting intellectual property for living organisms (microbes) and complex biological formulations is more challenging than for single-molecule chemistries, creating legal and commercialization risks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Seed Treatment Chemicals Market |
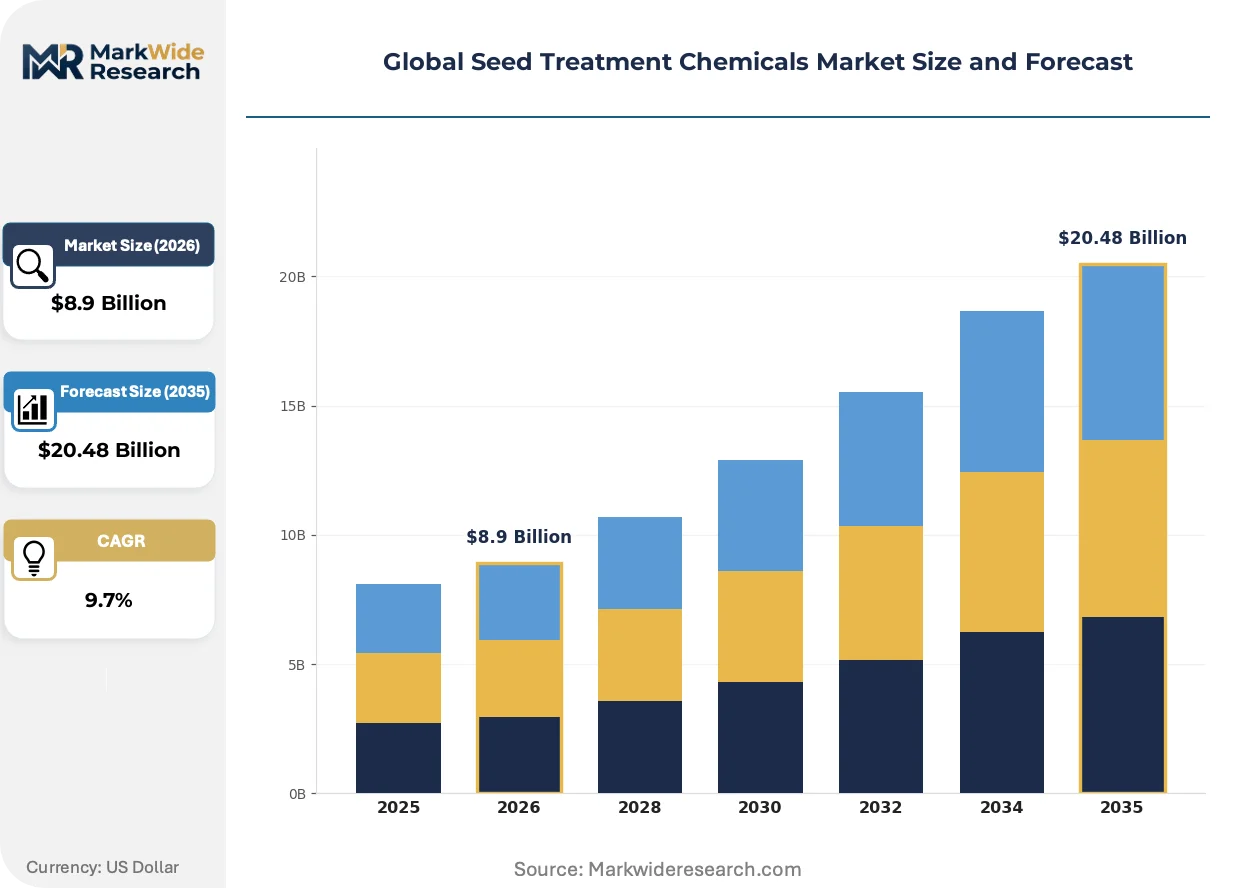
| Market Size in 2026 | $8.9 Billion |
| Market Size in 2035 | $20.48 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fungicides, Insecticides, Biostimulants, Nematicides, Adjuvants Formulation: Liquid, Powder, Granules, Emulsifiable Concentrate, Water Dispersible Granules Application: Cereal Crops, Oilseeds, Pulses, Horticultural Crops, Fiber Crops End Use Industry: Seed Companies, Agricultural Cooperatives, Independent Farmers, Contract Growers, Genomic Research Labs |
| Companies Covered | Syngenta Group, Bayer AG, BASF SE, Corteva Agriscience, FMC Corporation, UPL Limited, Nufarm, Sumitomo Chemical, Adama Agricultural Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Seed Treatment Chemicals Market Strategic Shifts & Innovations
The market's evolution is defined by a pivot from singular-function products toward multi-functional seed enhancements. This movement is a direct response to regulatory pressures demanding lower environmental impact and agronomic needs for comprehensive early-season plant health management, pushing innovation beyond simple protection.
Micro-encapsulation technology allows for the controlled release of multiple active ingredients from a single seed coating. This method is being adopted by developers for high-value crops to deliver both synthetic and biological agents at optimal times during germination and early growth. The use of these advanced delivery systems is fragmenting the traditional, uniform approach to seed treatment, enabling highly customized, crop-specific formulations that improve performance and reduce environmental load.
Regulatory frameworks, particularly the EU's REACH legislation administered by ECHA, are actively reshaping product portfolios. The regulation's mandate for stringent safety assessments on all chemical substances is accelerating the phase-out of some older, legacy chemistries used in seed treatments. The insecticide and fungicide segments are most affected, forcing formulators targeting the European market to prioritize investment in developing lower-risk synthetic compounds and biological alternatives that can meet REACH compliance.
A notable shift in purchasing behavior sees farmers acquiring seed treatments within integrated agronomic service packages. This trend disrupts the traditional product-centric sales model, empowering agricultural technology platforms and large farm cooperatives that offer holistic solutions. This change is most pronounced in the large-scale farming sectors of North America and Brazil, where data-driven decision-making favors bundled offerings that promise optimized yield outcomes across the entire crop cycle.
Global Seed Treatment Chemicals Market Segmentation
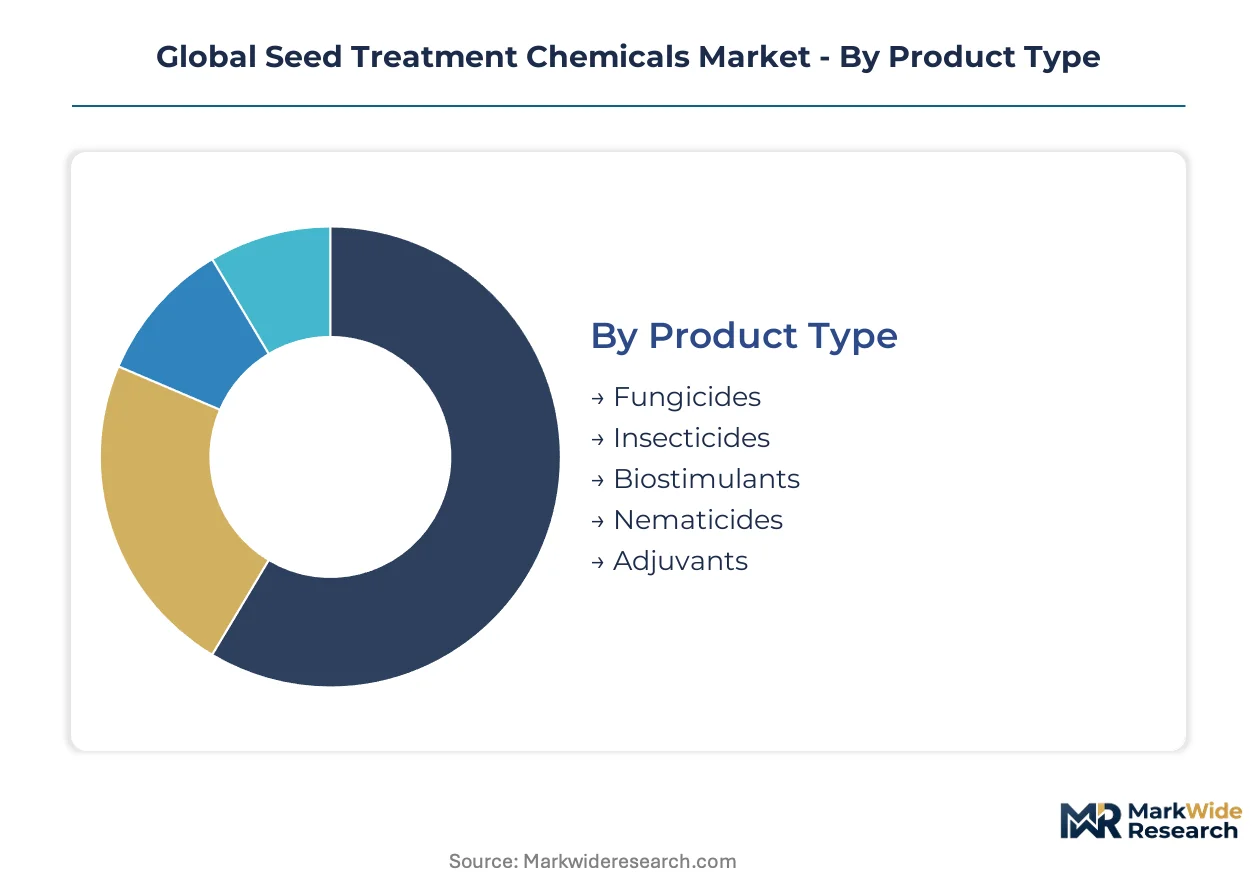
Segmentation provides a granular view of the Global Seed Treatment Chemicals Market, highlighting critical distinctions in product composition, delivery mechanisms, crop targets, and end-user requirements. Understanding these segments enables stakeholders to tailor product development, refine market entry strategies, and allocate resources effectively across diverse agricultural landscapes.
Product Type:
The regulatory landscape significantly differentiates product types, influencing development priorities and market access across global regions.
- Fungicides:These chemical or biological agents protect seeds and seedlings from fungal diseases during germination and early growth stages. Demand concentrates heavily in cereal crops across Europe and North America, driven by persistent disease pressure and the need to protect genetic investments.
- Insecticides:Applied to seeds, these compounds shield young plants from insect pests, preventing early-season damage. High demand from corn and wheat cultivation in Brazil and the United States underpins this segment, ensuring successful stand establishment against prevalent insect threats.
- Biostimulants:These substances enhance natural plant processes, improving nutrient uptake efficiency, stress tolerance, and overall crop quality.
- Nematicides:Formulations specifically designed to control nematodes, which are microscopic roundworms that can damage plant roots.
- Adjuvants:These compounds improve the performance of seed treatment formulations, enhancing coverage, adhesion, and active ingredient stability.
Fungicides handle the majority of throughput; Biostimulants are the fastest mover on share.
Formulation:
Formulation choices directly impact application methods and the precise delivery of active ingredients to the seed surface.
- Liquid:These formulations, often aqueous or oil-based solutions, are applied as coatings to seeds before planting. Large-scale commercial operations in North America and Brazil favor liquid treatments due to their ease of uniform application and compatibility with automated seed treatment equipment.
- Powder:Dry, finely ground formulations that adhere to the seed surface, typically requiring a binding agent. Smaller farms and specific crop types in regions like India and Southeast Asia often utilize powder treatments due to their cost-effectiveness and simpler application requirements.
- Granules:These formulations offer controlled release of active ingredients, providing extended protection and reduced dust exposure during handling.
- Emulsifiable Concentrate:Oil-based formulations that form stable emulsions when mixed with water, often used for active ingredients with low water solubility.
- Water Dispersible Granules:Dry, concentrated formulations that disperse readily in water, combining the advantages of solid and liquid forms for convenient application.
Liquid formulations dominate in volume due to ease of application, while advanced granule types gain traction for their controlled-release properties.
Application:
Application segments are primarily driven by the sheer volume of cultivated acreage and the economic value of the harvest.
- Cereal Crops:This segment includes staples like corn, wheat, and rice, which require robust seed protection to ensure high yields and food security. North America, Brazil, and the European Union represent significant demand centers, driven by intensive farming practices and the need to protect high-value genetic traits.
- Oilseeds:Crops such as soybeans, canola, and sunflowers are critical for edible oils and animal feed, necessitating effective seed treatments for early vigor and disease resistance. Brazil, the United States, and Canada are major producers where these treatments are widely adopted to maximize crop establishment.
- Pulses:Crops like peas, lentils, and chickpeas often benefit from treatments that enhance nitrogen fixation and protect against soil-borne pathogens.
- Horticultural Crops:This high-value segment encompasses fruits and vegetables, where specific seed treatments address unique pest and disease challenges for optimal quality and yield.
- Fiber Crops:Cotton and flax seeds are treated to ensure strong stand establishment and protection against early-season pests and diseases.
Cereal crops represent the largest application area, while horticultural crops demonstrate significant value per acre.
End Use Industry:
The diverse customer types within the end-use industry dictate varying procurement strategies and demand for integrated solutions.
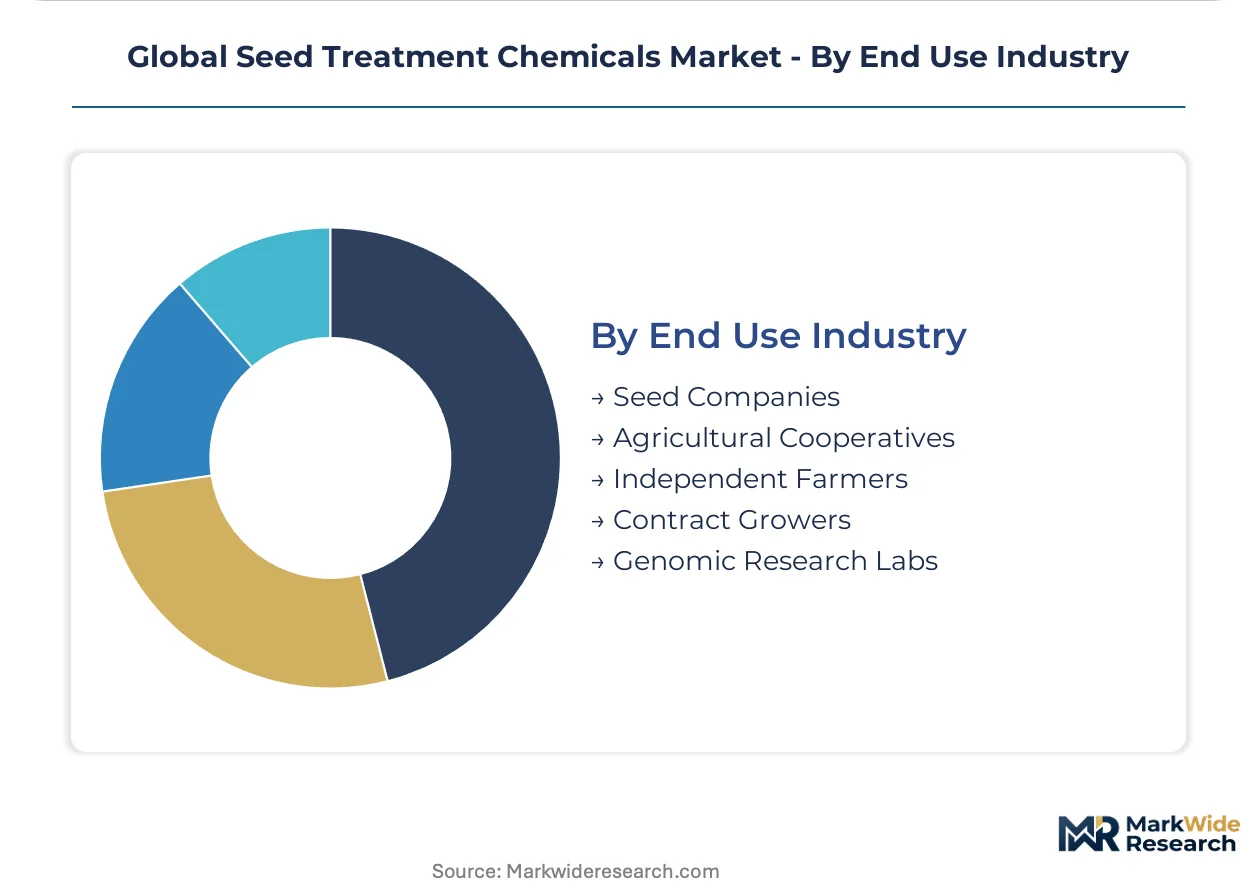
- Seed Companies:These entities develop, produce, and market seeds, integrating seed treatments as a core component of their product offerings. Global agricultural giants and regional specialists prioritize treatments that enhance seed quality, ensure germination, and protect their proprietary genetic material.
- Agricultural Cooperatives:Farmer-owned organizations that provide various services, including bulk purchasing of seeds and treatments, to their members. Cooperatives in Europe and North America leverage collective purchasing power to access advanced seed treatment solutions and agronomic advice.
- Independent Farmers:Individual farm operators who purchase treated seeds directly or apply treatments themselves, seeking accessible and effective solutions for their specific crop needs.
- Contract Growers:Farmers who produce crops under specific agreements for processors or distributors, often adhering to strict protocols for seed treatment application.
- Genomic Research Labs:These facilities focus on developing new genetic traits and complementary seed-applied technologies, driving innovation in the seed treatment sector.
Seed Companies drive innovation and integration of seed treatments, while independent farmers represent the broadest base of end-users.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US Environmental Protection Agency (EPA) anchors regulatory frameworks, significantly influencing the global seed treatment chemicals market. These regulations dictate permissible active ingredients and drive innovation towards safer alternatives. This dynamic shapes product portfolios and market access across major agricultural regions worldwide.
United States
The United States exhibits strong demand, particularly for intensive cereal crop farming like corn and wheat. The US Environmental Protection Agency (EPA) governs active ingredient registration, ensuring product safety. The Midwest agricultural belt, including states like Iowa, adopts advanced seed treatments for optimizing yields.
Brazil
Brazil, a major agricultural producer, drives substantial demand for seed protection in its extensive corn and oilseed cultivation. ANVISA oversees the registration of agricultural chemicals and seed treatments. Mato Grosso, a leading soybean and corn producer, actively implements advanced seed protection technologies.
Germany
Germany's market is influenced by significant cereal crop cultivation and stringent environmental standards. The European Chemicals Agency (ECHA) under REACH shapes product portfolios, favoring lower-risk biological and synthetic alternatives. The Rhineland region, a hub for chemical industries, focuses on developing compliant formulation technologies.
India
India presents a growing market, driven by the need for enhanced food security and modernizing farming practices. The Central Insecticides Board & Registration Committee (CIB&RC) regulates the registration of pesticides and seed treatments. Punjab, a key agricultural state, increasingly utilizes seed treatments to protect high-yielding crop varieties.
China
China's vast agricultural sector generates significant demand, focusing on improving yield and crop quality. The Ministry of Agriculture and Rural Affairs (MARA) regulates agricultural inputs, including seed treatment products. Northeast China, a primary grain-producing region, adopts seed treatments to safeguard crops against prevalent pests.
Global Seed Treatment Chemicals Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, defining the competitive landscape. This market structure features global crop science conglomerates and specialized chemical formulators, alongside emerging biological solution providers. Strategic archetypes include companies offering integrated pest management solutions and those focused on advanced application technologies. Competitors often engage in significant research and development investments and strategic partnerships to expand their product portfolios and geographic reach.
Integrated crop science companies like Syngenta Group and Bayer AG exemplify the market's premium-tier vector, offering broad portfolios combining chemical and biological expertise. BASF SE, another prominent entity, represents advanced chemical formulation capabilities, enhancing both synthetic and biological active ingredients. These global players anchor comprehensive seed treatment offerings, often leveraging extensive research and development capabilities and global distribution networks. Their strategies often involve developing synergistic products that address complex agronomic challenges across diverse crop types.
| Leading Market Players |
|---|
| Syngenta Group |
| Bayer AG |
| BASF SE |
| Corteva Agriscience |
| FMC Corporation |
| UPL Limited |
| Nufarm |
| Sumitomo Chemical |
| Adama Agricultural Solutions |
Cost & Logistics Intelligence
Ninety-day inventory buffers for key active ingredients shape seed treatment pricing power, reflecting concentrated upstream chemical production and specialized formulation expertise. This dynamic influences both cost structures and market accessibility for advanced seed protection solutions.
Pricing Analysis
Significant price spreads exist between advanced seed treatment formulations in Europe and commodity offerings in Southeast Asia. The dominant pricing model is contract-based long-term offtake between seed companies and formulators. Price differentiation stems from formulation complexity and regulatory compliance costs. Pricing softness reflects intense competition for high-volume cereal crop applications. Independent farmers exhibit higher price sensitivity compared to large seed companies.
Supply Chain Analysis
China and India anchor the production of many active ingredients for seed treatment chemicals. The supply chain for seed treatments draws from raw material dependencies on specialized chemical precursors and biological strains. Single-source vulnerability for certain novel biological agents presents a structural risk. Distribution runs through a fragmented network of agricultural distributors and directly to large seed companies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Developing integrated seed treatment solutions faces a critical capability gap, as talent scarcity in cross-disciplinary microbial science and chemical formulation limits product innovation. This constraint impacts the pace of new product development and market penetration.
For Market Incumbents:Compound existing R&D investments in multi-functional biologicals to counter the threat of genetic trait substitution. Secure long-term supply agreements for novel active ingredients to defend market share against emerging specialists. Pursue strategic partnerships with biostimulant developers to expand product portfolios. Deepen channel control through exclusive distribution deals with large agricultural cooperatives.
For New Entrants and Emerging Players:Unmet demand for localized, sustainable seed treatment solutions in emerging agricultural economies offers a significant white-space target. Focus on developing cost-effective, biological alternatives for smallholder farmers in India and Southeast Asia. A go-to-market angle could involve direct farmer education and bundled service packages through regional distributors. Target niche horticultural crops with specific pest and disease challenges where incumbents lack tailored offerings.
For Investors and Strategic Acquirers:Long-term, this sits as a specialty chemicals and biologicals integration play because regulatory shifts favor lower-risk alternatives and demand for plant health benefits grows. Acquisition targets include agile biostimulant startups with validated microbial strains and advanced micro-encapsulation technology providers. The signal to watch is the accelerated phase-out of legacy chemistries by the European Chemicals Agency.
| Strategic Initiative | Industry Significance |
|---|---|
| R&D Investment in Biologics | This drives innovation in sustainable plant protection, meeting EU Green Deal requirements. |
| Strategic Partnerships for Formulation | These collaborations accelerate the development of advanced, multi-functional seed treatment products. |
| Geographic Expansion in Emerging Markets | This captures new demand from modernizing farming practices in Southeast Asia. |
| Digital Agriculture Platform Integration | This enables customized seed treatment prescriptions based on precision farming data. |
| Capacity Expansion for Active Ingredients | This secures supply chain stability for critical chemical and biological components. |
Research Approach
Desk research of regulatory filings, agricultural statistics, and corporate reports preceded structured interviews with crop science executives, seed company procurement leads, and independent agronomists. This approach combined primary insights with secondary validation, ensuring a robust data foundation. Bottom-up market sizing from regional demand was triangulated with top-down analysis of global production capacities.
Variance decomposition isolated the impact of regulatory changes, crop acreage fluctuations, and technology adoption on market growth. The analytical framework modeled segmentation dimensions by product type, formulation, application, and end-use industry across the analysis window. Compound Annual Growth Rates were derived from historical trends and projected shifts in agricultural practices. Key forecast inputs included regional crop yield data and pesticide use restrictions.
Underlying assumptions cover stable agricultural policies and consistent crop prices, with deviation risk concentrated in unforeseen climate events or rapid shifts in consumer preferences. Forecasts reflect these documented assumptions. Recalibration cycles align with material shifts in regulatory frameworks or major technological breakthroughs.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Crop Protection
Larvicides Market
Crop Protection
IPM Pheromones Market
Crop Protection
Australia Crop Protection Chemicals (Pesticides) Market
Crop Protection
Iprodione Market
Crop Protection
China Fungicide Market
Crop Protection
Grain Fumigants Market
Crop Protection
Spain Crop Protection Chemicals Market
Crop Protection
Canada Nematicides Market
Crop Protection
Trapping and Mating Disruption Systems Market
Crop Protection
South America Nematicides Market
Crop Protection
Asia Pacific Insecticide Market
Crop Protection
Europe Chemical Seed Treatment Market
Crop Protection
Vietnam Crop Protection Chemicals Market
Crop Protection
US Insecticide Market
Crop Protection
Acetochlor Herbicide Market
Crop Protection
Global Acaricides Market