
 Boron Fertilizers Market | 2026-2036
Boron Fertilizers Market Size, Share, and Industry Trends Forecast 2026-2036
Boron Fertilizers Market Intelligence
Asset-light distribution models, which reduce capital expenditure for regional players, are reshaping competitive positioning in the market. Global producer Eti Maden leverages its extensive mining operations to control primary boron supply chains. The Mosaic Company integrates boron products into its broader portfolio of crop nutrition solutions for large-scale agriculture. In contrast, Valagro S.P.A. differentiates through its focus on biostimulants and specialty nutrient formulations for horticulture.
Boron fertilizers are specialized micronutrient products designed to correct boron deficiencies in soil and plants. These formulations deliver boron, an essential element for cell wall formation and reproductive growth, in plant-available forms like boric acid or borax. Among product types, soluble forms like boric acid and Solubor lead in high-value horticulture due to their ease of application in fertigation systems. The oilseed crops application segment represents the fastest-growing area, driven by the crop's high sensitivity to boron deficiency.
Product composition and labeling are governed by regulations like the European Union's REACH framework. In the United States, the EPA sets limits on heavy metal content, influencing raw material sourcing and quality control. Agricultural standards from organizations like the OECD guide best practices for nutrient application globally. Future market access will depend on developing formulations that align with evolving soil health and sustainable agriculture initiatives.
Market Dynamics
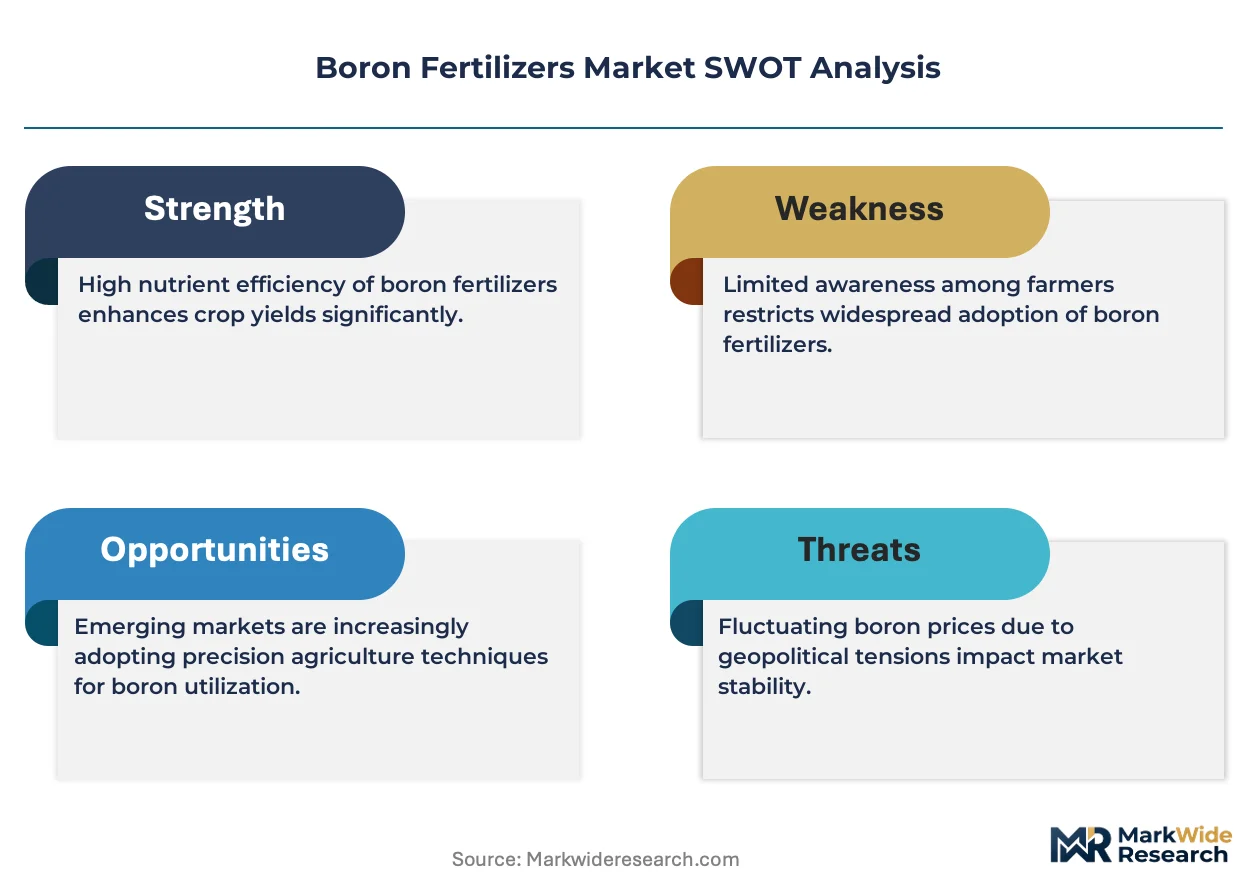
The central tension in the boron fertilizers market is the push for sustainable, high-efficiency formulations driven by regulations in developed economies against the need for cost-effective, bulk nutrient management in large, developing agricultural nations like India and Brazil.
Growth Catalysts
- Precision Agriculture Adoption:Demand for soluble boron products is rising with the adoption of fertigation and foliar spray systems, which require highly soluble and pure nutrient sources for precise application in high-value crops.
- Sustainable Farming Mandates:The European Union's Farm to Fork strategy incentivizes the use of targeted micronutrient fertilizers to improve nutrient use efficiency and reduce the environmental footprint of agriculture, benefiting specialized boron formulations.
- Soil Health Initiatives:National-level programs in countries like Brazil and India that focus on mapping and correcting widespread soil micronutrient deficiencies are creating sustained demand for boron as a critical component of balanced fertilization.
Market Restraints
- Supply Chain Concentration:The global supply of primary boron minerals is heavily concentrated, with entities like Eti Maden in Turkey controlling a significant portion of production, creating price volatility and supply risks for downstream formulators.
- Phytotoxicity Risk:Boron has a narrow range between deficiency and toxicity in plants. The risk of crop damage from improper application acts as a barrier to adoption for farmers lacking access to soil testing and precision application equipment.
- Regulatory Compliance Costs:Adhering to substance registration frameworks like the EU's REACH and heavy metal limits set by the US EPA increases formulation costs and administrative burdens, particularly for smaller manufacturers.
Strategic Opportunities
- Biostimulant Integration:Formulating boron fertilizers with biostimulants offers a synergistic effect, enhancing nutrient uptake and plant resilience. This creates a value-added product category for the specialty horticulture and organic farming sectors.
- Oilseed Crop Focus:The high sensitivity of oilseed crops like canola and sunflower to boron deficiency presents an opportunity for developing crop-specific formulations and marketing campaigns targeted at major oilseed-producing regions.
- Digital Agronomy Platforms:Integrating boron application recommendations into digital farming platforms that use soil data and satellite imagery can help overcome the challenge of precise application, opening markets with less sophisticated agronomic support.
Industry Challenges
- Farmer Education Gap:A significant challenge is educating a fragmented global base of farmers on the specific symptoms of boron deficiency and the correct methods for application, which slows adoption rates in less developed agricultural areas.
- Formulation Stability:Developing stable, multi-nutrient liquid fertilizer formulations that include boron alongside other macro and micronutrients is technically challenging due to chemical incompatibilities, limiting product shelf life and application flexibility.
- Lack of Harmonized Standards:The absence of globally harmonized standards for soil testing protocols and boron application recommendations, with guidance from bodies like the OECD being non-binding, creates confusion and inconsistent practices across regions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Boron Fertilizers Market |
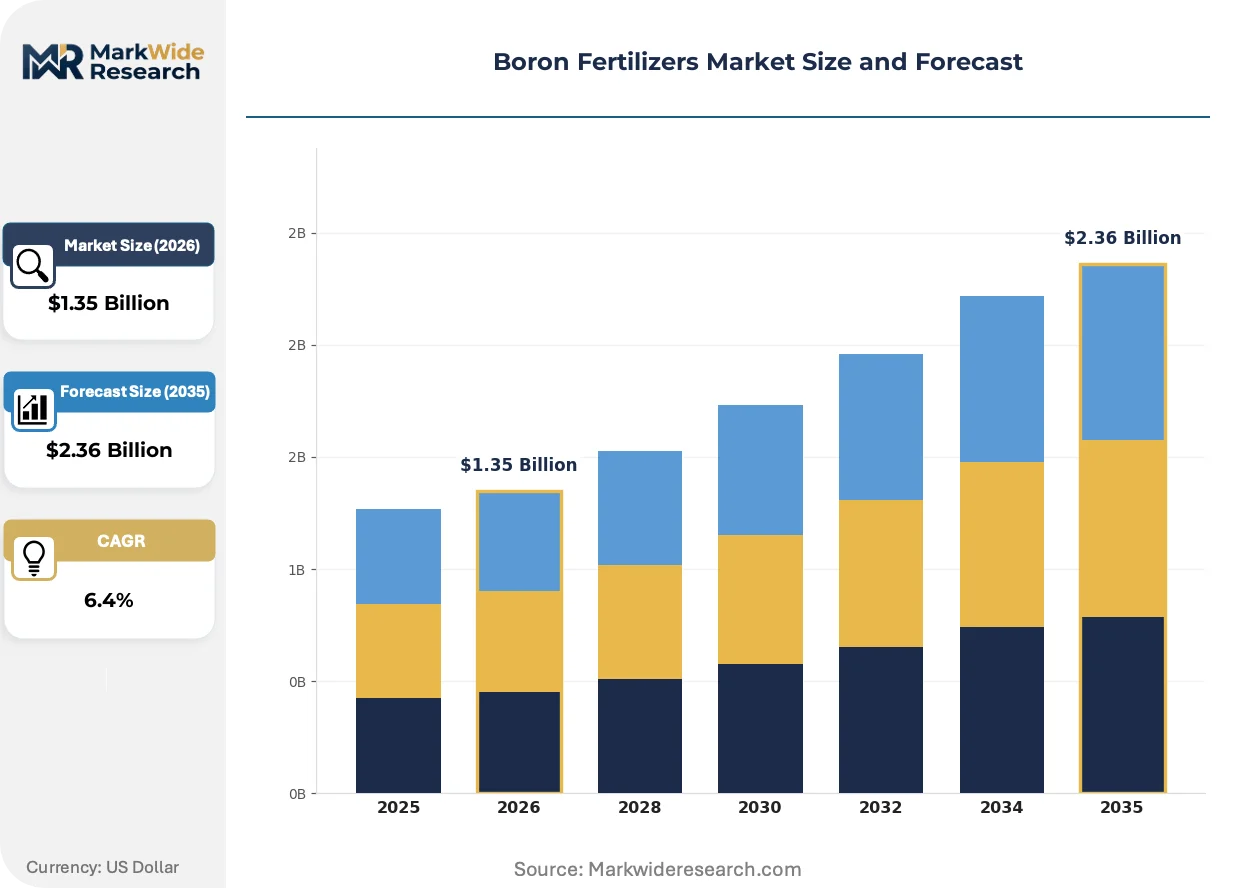
| Market Size in 2026 | $1.35 Billion |
| Market Size in 2035 | $2.36 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Boric Acid, Borax Pentahydrate, Solubor, Colemanite, Ulexite Application: Fruit Crops, Oilseed Crops, Cereals & Grains, Vegetables, Pulses & Nuts End Use Industry: Agricultural Cooperatives, Independent Growers, Government Farms, Organic Farms, Agrochemical Companies Packaging Type: Bag, Bulk Bags, Drums, Sachets, Jumbo Bags |
| Companies Covered | Eti Maden, Quiborax, Minera Santa Rita S.R.L., Inkabor, Searles Valley Minerals, Russian Bor Concern OJSC, The Mosaic Company, Valagro S.P.A., ORO AGRI Europe, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Boron Fertilizers Market Strategic Shifts & Innovations
Product innovation is accelerating, driven by the dual pressures of regulatory mandates for environmental safety and agronomic demands for greater nutrient efficiency. This is leading to the development of sophisticated formulations that go beyond simple nutrient delivery.
Specialty formulations are integrating boron with biostimulants and other micronutrients to enhance plant uptake and stress resilience. High-value horticulture and organic farming segments are rapidly adopting these advanced products. This trend is hybridizing traditional micronutrient fertilizers with biological inputs, creating a new class of high-performance crop nutrition solutions that offer multiple benefits in a single application.
The European Union's Green Deal, via its Farm to Fork strategy, mandates significant reductions in overall fertilizer use and nutrient loss to the environment. This policy is forcing manufacturers to innovate more efficient, targeted formulations that minimize runoff. Consequently, soluble and chelated boron products designed for precise fertigation and foliar feeding are gaining market share in the EU.
A shift toward asset-light distribution models is enabling regional and specialized players to compete more effectively. This approach bypasses capital-intensive warehousing by leveraging third-party logistics (3PL) and direct-to-farm channels. This change in distribution is most evident in large agricultural economies like Brazil and India, where it lowers barriers to entry and improves market access for innovative formulations.
Boron Fertilizers Market Segmentation
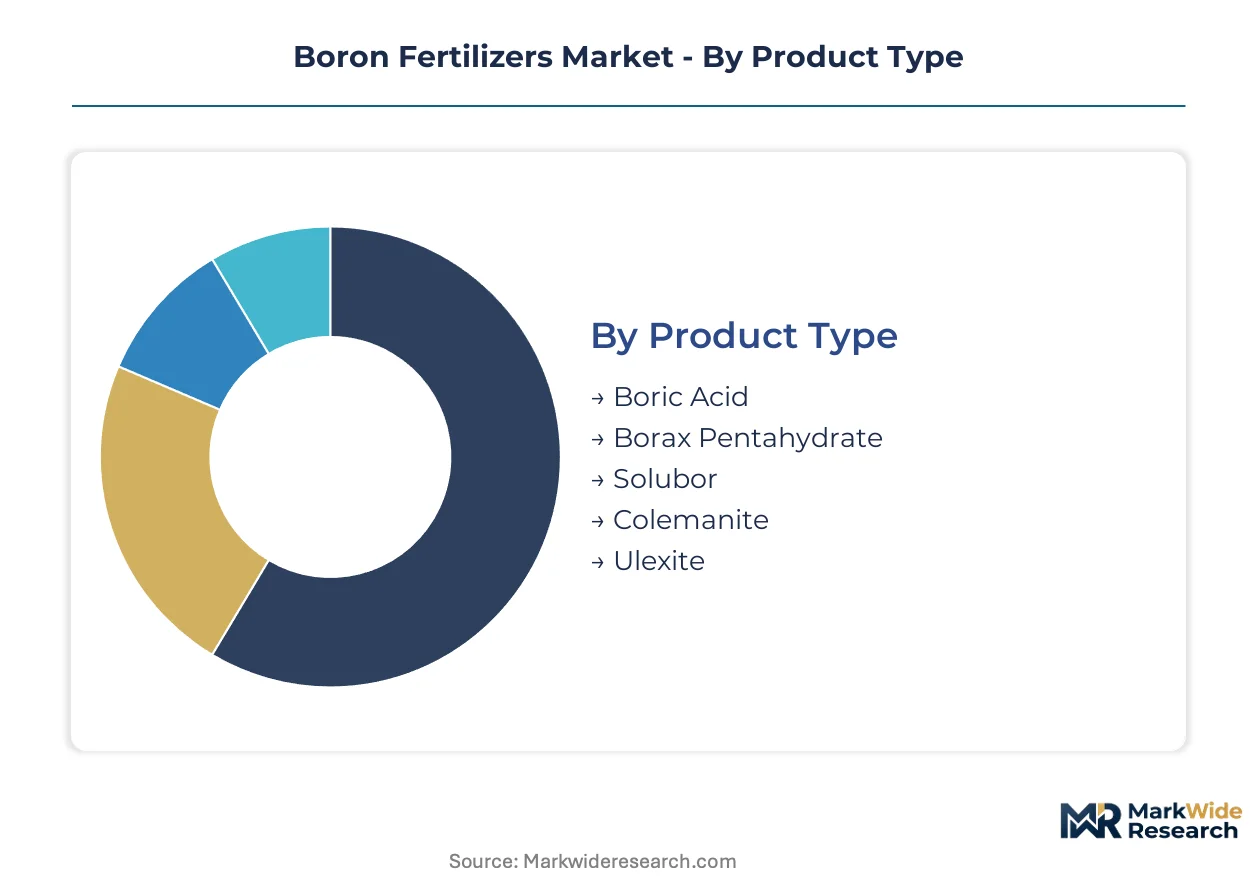
The boron fertilizers market differentiates across several key dimensions, reflecting varied agricultural practices and specific crop nutritional needs. Understanding these distinct segments allows manufacturers to tailor product offerings and distribution strategies effectively. This granular view highlights areas of concentrated demand and emerging opportunities for specialized formulations across diverse farming environments.
Product Type:
The intensity of after-sales service and technical support often varies significantly across boron fertilizer product types, influencing farmer adoption and product positioning. Soluble forms require more detailed application guidance for precision agriculture, while bulk commodities demand less specialized support. Manufacturers must align their service models with the complexity of each product's use case.
- Boric Acid:This highly soluble form delivers boron in a readily available state for plant uptake, commonly used in fertigation and foliar sprays. Demand concentrates in high-value horticulture across Europe, where precise nutrient management is mandated by the EU Green Deal.
- Solubor:A refined sodium borate, Solubor offers excellent solubility and is specifically designed for foliar and soil application in diverse crops. Its ease of integration into existing spray programs drives significant demand in fruit crops and specialty vegetables in Brazil.
- Borax Pentahydrate:This crystalline borate is a common soil-applied boron source, providing a steady release of the micronutrient over time.
- Colemanite:A naturally occurring calcium borate mineral, Colemanite offers a slower-release form of boron, suitable for long-term soil enrichment in various agricultural settings.
- Ulexite:Another natural borate mineral, Ulexite contains both sodium and calcium, offering a balanced slow-release boron option for broadacre crops.
Boric Acid holds the largest share; momentum sits with Solubor.
Application:
The cost tier of boron fertilizer products often correlates directly with their intended application, with high-value crops justifying premium formulations and more precise delivery systems. Bulk applications for staple crops typically utilize more economical, standard-grade products. This differentiation impacts procurement decisions for agricultural enterprises globally.
- Oilseed Crops:These crops, including canola and sunflower, exhibit high sensitivity to boron deficiency, making targeted application crucial for yield optimization. Major oilseed-producing regions like India are driving demand for specialized formulations to address this vulnerability.
- Fruit Crops:Boron is critical for fruit set, quality, and yield in crops such as grapes and citrus, requiring precise foliar or fertigation applications. European Union regulations encourage efficient micronutrient use in these high-value sectors, boosting demand for advanced products.
- Cereals & Grains:While less sensitive than other crops, boron application in cereals and grains can improve nutrient uptake and stress tolerance, particularly in regions with known soil deficiencies.
- Vegetables:Boron supports cell wall integrity and reproductive growth in various vegetable crops, with specialized formulations enhancing quality and marketability.
- Pulses & Nuts:Essential for flowering and pod development, boron fertilizers improve yields in pulse crops and nut trees, especially in areas with imbalanced soil nutrient profiles.
Oilseed Crops represent the most dynamic segment, showing rapid expansion in demand. Fruit Crops also require significant boron input.
End Use Industry:
The application patterns for boron fertilizers vary considerably across different end-use industries, driven by scale, crop diversity, and agronomic sophistication. Large agricultural cooperatives often seek bulk solutions, while independent growers may prioritize ease of use and tailored advice. Organic farms require certified products compliant with specific standards.
- Agricultural Cooperatives:These large entities centralize procurement for numerous farmers, driving demand for cost-effective, bulk quantities of boron fertilizers. Their focus is often on consistent supply and standardized application across diverse regional farmlands in countries like India.
- Independent Growers:Individual farmers often require more accessible product formats and direct technical guidance for precise application on their specific crops and soil conditions. This segment drives demand for specialized formulations and local distribution networks.
- Government Farms:State-managed agricultural operations implement large-scale fertilization programs, often prioritizing national food security and research-driven application protocols.
- Organic Farms:This segment demands boron fertilizers approved for organic certification, emphasizing natural sources and sustainable production methods.
- Agrochemical Companies:These companies integrate boron products into broader nutrient solutions or resell them, serving as key distributors and formulators for the wider agricultural market.
Agricultural Cooperatives and Independent Growers collectively form the largest user base for boron fertilizers, with Organic Farms exhibiting specialized requirements.
Packaging Type:
The volume requirements of different agricultural operations significantly dictate the preferred packaging type for boron fertilizers, impacting logistics and storage efficiency. Large-scale commercial farms favor bulk options for cost-effectiveness, while smaller growers or specialty applications opt for more manageable unit sizes. This influences the entire supply chain from production to final delivery.
- Bulk Bags:These large, industrial-sized containers are designed for high-volume transport and storage, preferred by large agricultural cooperatives and distributors. Their use optimizes logistics for extensive farming operations in major agricultural economies like Brazil.
- Bag:Standard bags, typically 25kg or 50kg, are widely used for general agricultural applications, balancing ease of handling with sufficient quantity for mid-sized farms. This format supports diverse distribution channels and various crop types.
- Drums:Drums offer robust packaging for liquid or granular boron formulations, providing enhanced protection during transport and storage, particularly for specialty products.
- Sachets:Small sachets cater to precise, small-scale applications or home gardening, offering convenience and minimizing waste for individual users.
- Jumbo Bags:Larger than standard bulk bags, jumbo bags facilitate the transport of very high volumes of granular or powdered boron fertilizers, reducing handling costs for industrial-scale buyers.
Bulk Bags and standard Bags dominate the market due to their practicality for agricultural operations, while specialized packaging serves niche demands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regional pricing-power asymmetry between developed economies and large agricultural nations shapes boron fertilizer market dynamics. Developed regions prioritize high-efficiency formulations to meet stringent environmental regulations. Conversely, developing agricultural nations like India and Brazil require cost-effective, bulk nutrient management solutions for widespread soil deficiencies.
Brazil
Brazilian agriculture drives demand for boron fertilizers, especially for fruit crops and oilseeds. National soil health initiatives, such as those from Embrapa, emphasize correcting widespread micronutrient deficiencies. The Mato Grosso region, a major soybean and corn producer, sees significant investment in precise nutrient application technologies.
India
India's expansive agricultural sector generates substantial demand for boron, particularly for oilseed crops and pulses. The country's Ministry of Agriculture and Farmers Welfare promotes balanced fertilization programs to enhance crop productivity. Karnataka and Maharashtra, key agricultural states, are implementing schemes for soil testing and micronutrient application.
France
French horticulture and high-value fruit crops demand specialized boron formulations to comply with European Union directives. The EU's Farm to Fork strategy encourages precise micronutrient application to reduce environmental impact. The Loire Valley, known for its vineyards and fruit production, actively adopts fertigation systems for targeted nutrient delivery.
United States
United States agricultural practices require boron for a range of crops, with EPA regulations governing heavy metal content in fertilizers. The USDA supports soil health programs that include micronutrient management for sustainable farming. California's Central Valley, a hub for specialty crops, utilizes advanced boron products for yield and quality enhancement.
Turkey
Turkey plays a critical role in global boron supply due to extensive mining operations controlled by Eti Maden. The country's agricultural sector also uses boron for various crops, aligning with national agricultural policies for yield improvement. The Eskişehir region, home to significant borate reserves, anchors the upstream supply chain for international markets.
Boron Fertilizers Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream, supplying foundational materials. The boron fertilizers market exhibits a tiered structure, with primary producers, broad-portfolio crop nutrition providers, and specialty formulators. Strategic partnerships and portfolio diversification are common competitive moves among participants. Geographic expansion allows companies to address varied agricultural needs globally.
Within the primary supply tier, Eti Maden leverages its extensive mining operations to control upstream boron availability. The Mosaic Company integrates boron products into its broader portfolio, serving large-scale agricultural enterprises with comprehensive crop nutrition solutions. Valagro S.P.A. differentiates through its focus on biostimulants and specialty nutrient formulations, targeting high-value horticulture and organic farming segments.
| Leading Market Players |
|---|
| Eti Maden |
| Quiborax |
| Minera Santa Rita S.R.L. |
| Inkabor |
| Searles Valley Minerals |
| Russian Bor Concern OJSC |
| The Mosaic Company |
| Valagro S.P.A. |
| ORO AGRI Europe |
| Others |
Cost & Logistics Intelligence
Global freight routes face cost fluctuations, directly impacting boron fertilizer pricing power for downstream formulators. This dynamic reflects upstream supply concentration and influences price differentiation across agricultural markets.
Pricing Analysis
Configured-to-order pricing for specialty boron formulations contrasts with standard bulk commodity rates. The market uses a hybrid contract-based and spot market pricing model. Purity and customization level drive significant price differentiation. Upstream supply concentration creates price volatility, particularly for standard-grade products, making agricultural cooperatives highly price-sensitive for bulk purchases. High-value horticulture segments prioritize specialized formulations.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities support the movement of boron minerals from primary producers. Global boron supply concentrates in Turkey, Chile, and Argentina, with the market depending heavily on raw minerals like colemanite and ulexite. Single-source vulnerability from entities like Eti Maden creates a significant structural risk. Distribution runs through asset-light models, leveraging third-party logistics and direct-to-farm channels in key agricultural economies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The boron fertilizers market requires a substitution defense as incumbents navigate the threat of reduced overall fertilizer use mandated by policies like the EU Green Deal. This shift prioritizes nutrient use efficiency, impacting traditional boron demand.
For Market Incumbents:
Pre-empt regulatory mandates for environmental safety by investing in R&D for advanced, high-efficiency formulations. Develop integrated solutions combining boron with biostimulants to enhance plant resilience and nutrient uptake. Pursue organic certifications for specialized products to capture growth in niche segments. Control primary boron supply chains through strategic long-term off-take agreements to mitigate price volatility risks.
For New Entrants and Emerging Players:
Build out specialized formulations targeting oilseed crops in India, a dynamic segment with high boron sensitivity. Penetrate markets with less sophisticated agronomic support by integrating application recommendations into digital farming platforms. Leverage asset-light distribution models to bypass capital-intensive warehousing. Focus on crop-specific solutions that align with evolving soil health initiatives.
For Investors and Strategic Acquirers:
Carve-out targets emerge from large agricultural conglomerates seeking to divest non-core micronutrient divisions. The market demonstrates long-term viability, driven by stable demand for essential micronutrients over the next decade. Acquire specialty formulators possessing strong R&D in biostimulant integration or regional players with established asset-light distribution networks. Watch for increased adoption rates of digital agronomy platforms as a key inflection indicator for market access.
| Strategic Initiative | Industry Significance |
|---|---|
| Develop Biostimulant-Integrated Boron Formulations | Enhances nutrient uptake and plant resilience for high-value horticulture, aligning with sustainable agriculture initiatives. |
| Expand Asset-Light Distribution Networks | Lowers capital expenditure for regional players, improving market access in large agricultural economies like Brazil. |
| Invest in Digital Agronomy Platform Integration | Overcomes precise application challenges, opening markets in regions with less sophisticated agronomic support. |
| Secure Long-Term Boron Mineral Offtake Agreements | Mitigates price volatility and supply risks stemming from concentrated primary boron production by Eti Maden. |
| Obtain Organic Certifications for Specialty Products | Captures demand from the growing organic farming sector, meeting specific production method standards. |
Research Approach
A spread of perspectives from agronomists, fertilizer manufacturers, large farm cooperative managers, and regulatory body representatives converged on the working assumptions. This study combined primary interviews with extensive secondary validation. Data sources included OECD guidelines, EPA regulations, EU Farm to Fork strategy documents, and national agricultural ministry reports. Bottom-up market sizing and top-down validation ensured robust data triangulation.
The demand-supply balance determined market projections across the analysis window, integrating insights from both historical trends and forward-looking indicators. Segmentation dimensions modeled included Product Type, Application, End Use Industry, Packaging Type, and regional agricultural policies. Compound annual growth rates (CAGRs) were derived using regression analysis. Key inputs included crop sensitivity to boron and national soil micronutrient deficiency rates.
Stress conditions across commodity price volatility, unexpected regulatory shifts, and extreme weather events were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions regarding agricultural policy stability and technological adoption. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fertilizers
Middle East and Africa Fertilizers Market
Fertilizers
Russia Fertilizers Market
Fertilizers
South America Micronutrient Fertilizer Market
Fertilizers
South America Fertilizers Market
Fertilizers
Global Foliar Fertilizer Market
Fertilizers
Middle East and Africa Specialty Fertilizer Market
Fertilizers
China Micronutrient Fertilizer Market
Fertilizers
India Fertilizers Market
Fertilizers
Biological Organic Fertilizers Market
Fertilizers
Brazil Fertilizers Market
Fertilizers
Brazil Organic Fertilizer Market
Fertilizers
Nitrogen Fertilizer Additives Market
Fertilizers
Global Specialty Fertilizer Market
Fertilizers
GCC Fertilizer Market
Fertilizers
Global Liquid Fertilizer Market
Fertilizers
Global Starter Fertilizers Market