
 North America Seed Treatment Market | 2026-2036
North America Seed Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
North America Seed Treatment Market Analytics
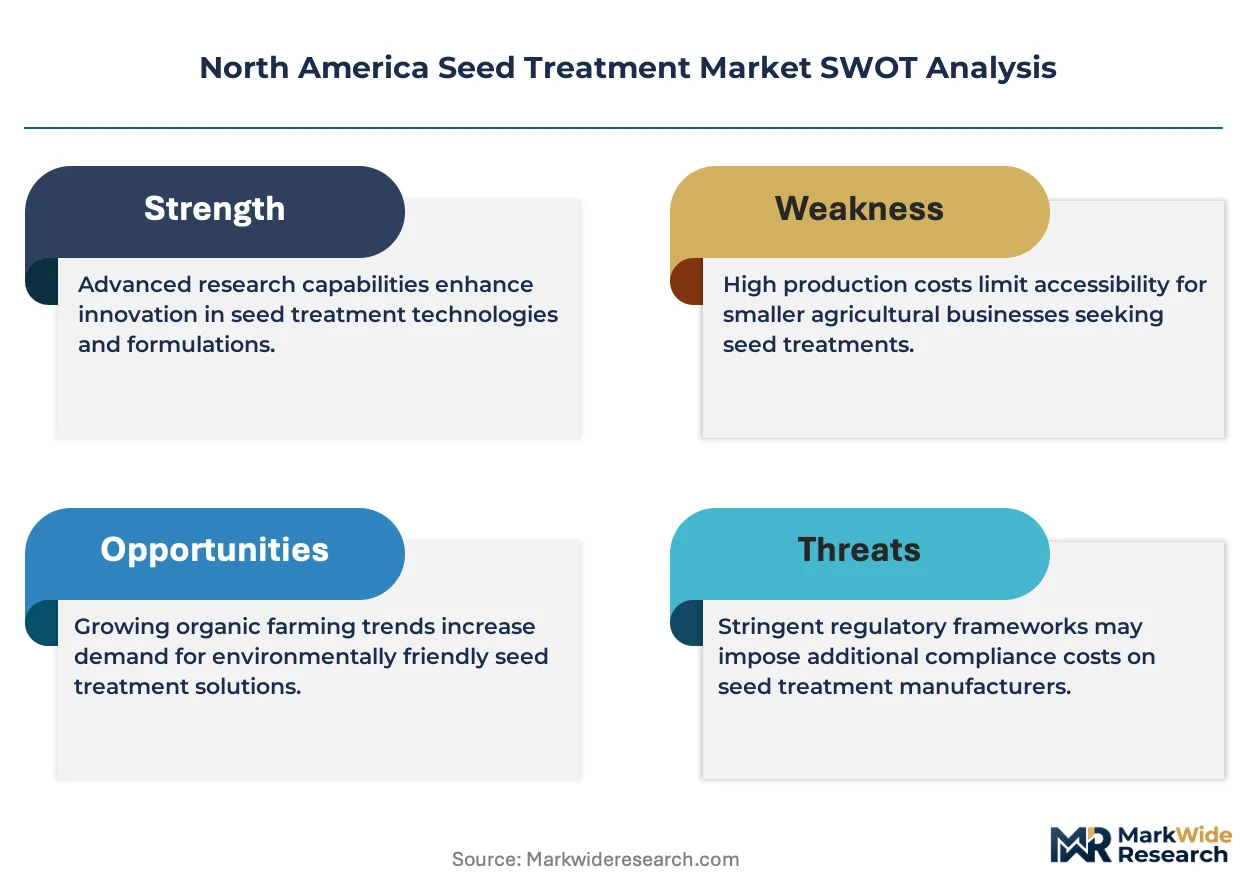
EPA re-registration deadlines for neonicotinoid-coated seeds is realigning the cost-of-entry calculus for new biological entrants. Bayer AG leverages its integrated crop science pipeline to sustain leadership in fungicidal seed treatments across the Great Plains. Corteva Agriscience anchors its position through proprietary polymer coating technologies that improve active ingredient adhesion. Syngenta Group competes by extending its biologicals portfolio into nematode-control seed applications.
Seed treatment encompasses the application of chemical or biological agents to seeds prior to planting, typically involving film coatings of 1-5 microns thickness that encase active ingredients in polymer binders to protect against soil-borne pathogens and early-season insects. The primary commercial purpose centers on reducing plant mortality during germination and establishment phases, thereby improving stand uniformity and yield potential per acre. Biologicals within the product type dimension represent the fastest-expanding margin pool as farmer willingness to pay for non-synthetic alternatives rises. Among applications, cereal crops occupy the largest volume position while oilseeds command premium pricing due to higher per-unit seed costs and greater pest pressure sensitivity.
The EPA governs active ingredient registration under FIFRA while state departments of agriculture enforce treated seed labeling and handling protocols, creating a dual-layer compliance burden that favors established formulators with regulatory affairs infrastructure. USDA conservation programs increasingly incentivize integrated pest management practices that incorporate biological seed treatments, redirecting procurement criteria toward reduced-risk product categories. Stakeholders must monitor pending EPA ecological risk assessments for pollinator-exposed chemistries, as these determinations will force portfolio restructuring decisions before the next planting cycle.
Market Dynamics
The EPA's phased re-registration requirements for neonicotinoid seed coatings are forcing formulators to rebuild active ingredient portfolios around biological alternatives and reduced-risk chemistries before the 2027 planting cycle deadline.
Growth Catalysts
- USDA Conservation Stewardship Program:Financial incentives for integrated pest management practices accelerate farmer willingness to pay for biological seed treatments across the Corn Belt.
- Polymer adhesion advances:Proprietary coating technologies improve active ingredient retention on seed surfaces, reducing off-target dust exposure during planting operations.
- Midwest soybean acreage expansion:Oilseed planting intensity in Iowa, Illinois, and Indiana concentrates demand for premium nematode-control applications.
Market Restraints
- Active ingredient supply concentration:Three chemical manufacturers control over 70% of synthetic fungicide technical supply for seed treatment formulations.
- Biological formulation stability:Living organism viability degrades rapidly in warm storage conditions, limiting distribution radius from production facilities.
- State-level label fragmentation:Individual state departments of agriculture impose supplemental data requirements beyond EPA FIFRA registration, extending time-to-market for new products.
Strategic Opportunities
- Canadian prairie provinces:Saskatchewan and Manitoba canola growers remain underpenetrated for biological seed treatment relative to US Midwest adoption rates.
- Carbon credit stacking:USDA Climate-Smart Commodities grants create incremental revenue streams for farmers documenting biological input use.
- Drone-based micro-coating:Aerial application systems enable on-farm seed treatment customization, bypassing centralized conditioning infrastructure.
Industry Challenges
- Microbiologist talent scarcity:Formulation science programs produce insufficient graduates with dual expertise in entomology and fermentation scale-up.
- Cross-border seed movement compliance:Treated seed shipments between US and Canada require dual notification systems under separate phytosanitary protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Seed Treatment Market |
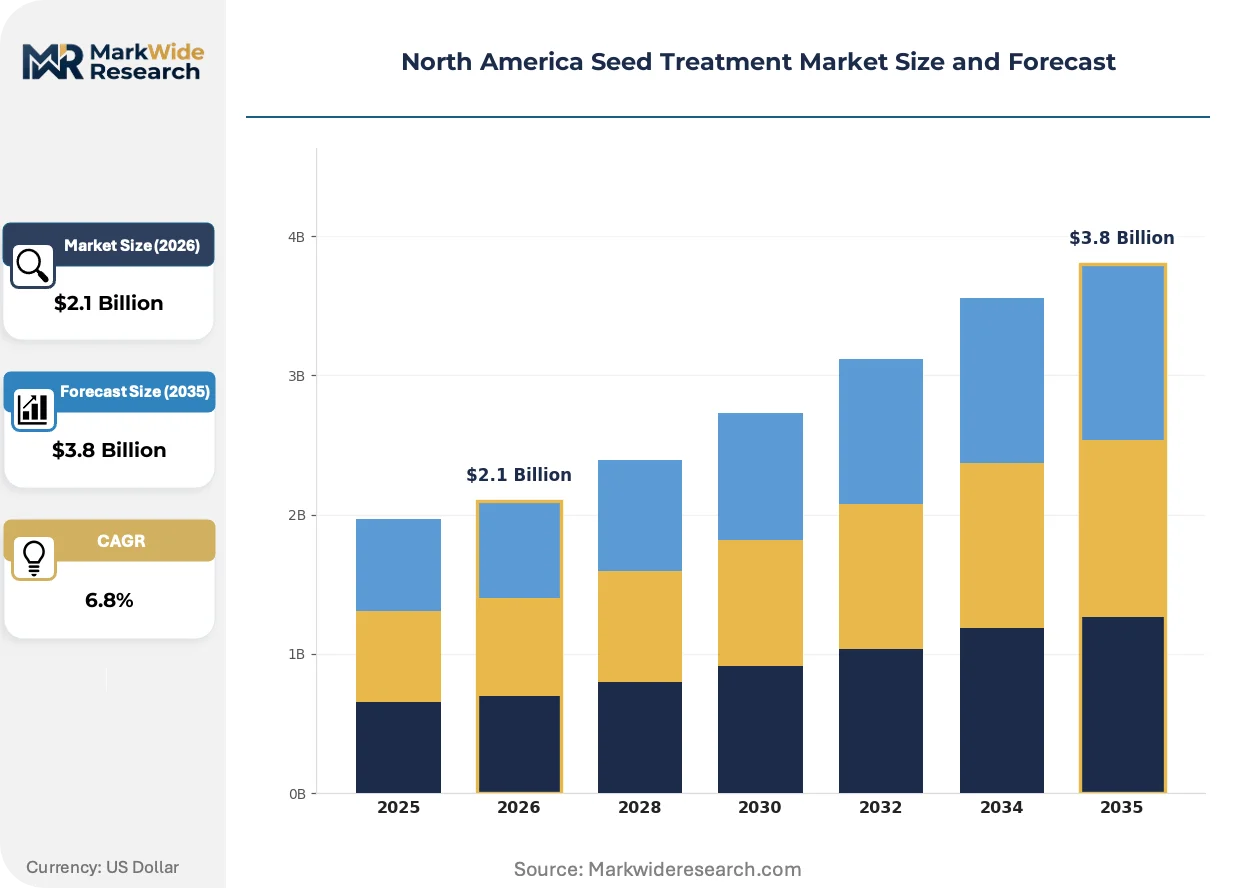
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.8 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Insecticides, Fungicides, Seed Coatings, Biologicals Application: Cereal Crops, Oilseeds, Pulses, Vegetables Distribution Channel: Online Retail, Specialty Stores, Wholesale, Direct Sales End Use Industry: Agriculture, Horticulture, Turf Management, Others |
| Companies Covered | BASF SE, Bayer AG, Corteva Agriscience, Syngenta Group, Nufarm Ltd, UPL Limited, Albaugh LLC, FMC Corporation, Valent U.S.A. LLC, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Seed Treatment Market Evolving Landscape
Biological active ingredients are capturing formulation pipeline investment as registrants anticipate pollinator risk determinations that will restrict conventional chemistry use on major row crops.
RNA interference seed treatments are consolidating research and development resources at major crop science divisions. These nucleic acid-based molecules trigger pest-specific gene silencing without broad-spectrum toxicity. Corn and cotton seed channels show fastest uptake as growers seek alternatives to neonicotinoid prophylaxis. The technology is consolidating competitive positioning around firms with in-house double-stranded RNA manufacturing capacity.
EPA ecological risk assessments for pollinator-exposed chemistries are compressing product lifecycles for conventional insecticidal seed treatments. The agency's 2024 guidance documents require expanded field residue data for clothianidin and thiamethoxam. Soybean and canola seed channels face the most immediate reformulation pressure as these crops coincide with honey bee foraging periods.
Farmer procurement of seed treatment services is unbundling from bundled seed-chemistry packages. Large-scale corn operations in Nebraska and Kansas now negotiate coating services separately from genetic trait licenses. Independent treatment facilities in the Red River Valley report volume gains as growers seek pricing transparency on input components.
North America Seed Treatment Market Segmentation
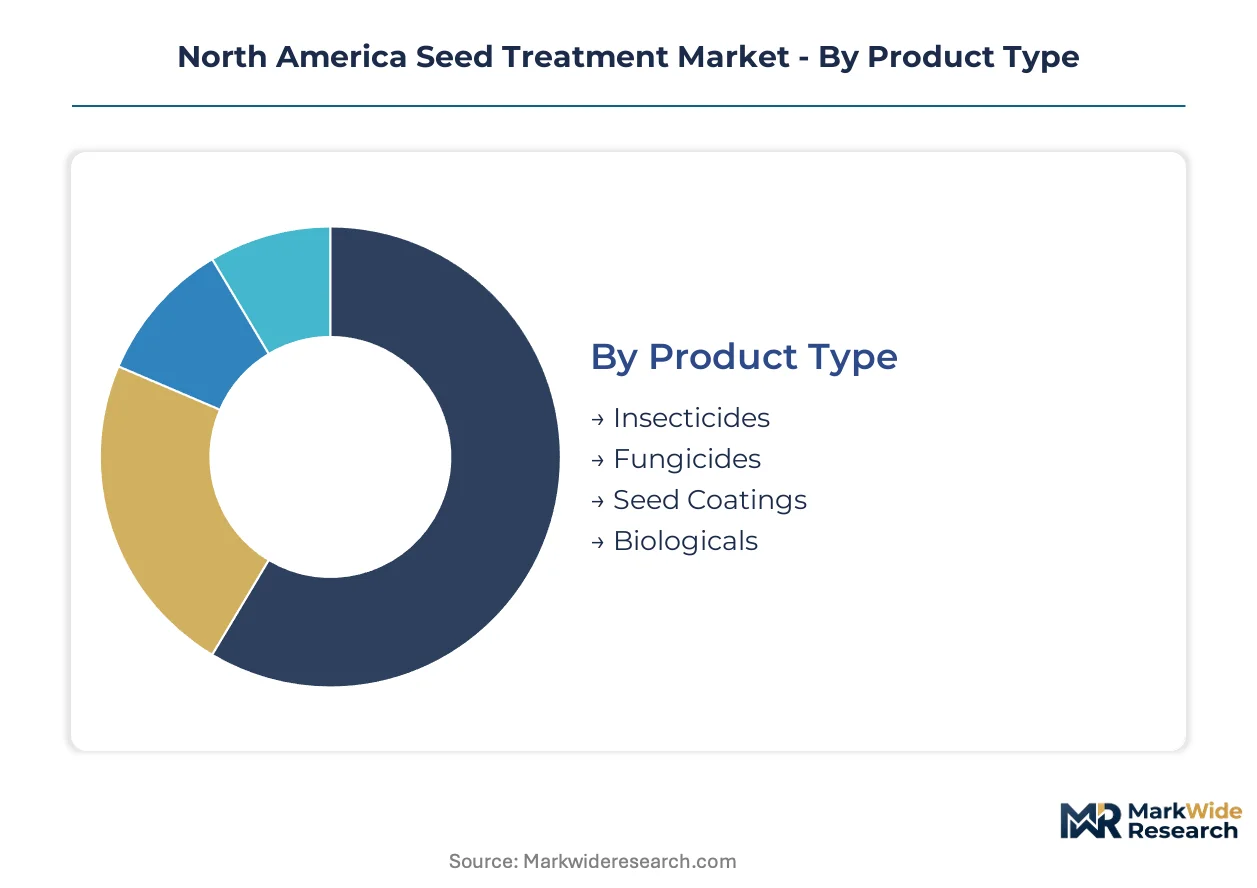
Seed treatment purchasing decisions in North America diverge sharply across product chemistry, crop application, and supply channel. Farmers weigh regulatory compliance timelines against per-acre treatment costs when selecting formulations, while distributors compete on application speed and technical support depth.
Product Type:
Cost tier determines adoption sequence as growers navigate EPA re-registration uncertainty.
- Insecticides:Neonicotinoid-based coatings historically dominated Corn Belt plantings for early-season aphid and wireworm suppression. Iowa and Illinois soybean operations now face forced reformulation as EPA ecological risk assessments restrict clothianidin and thiamethoxam use ahead of pollinator foraging windows.
- Biologicals:Microbial inoculants and biofungicides incorporate living organisms such as Trichoderma species and Bacillus subtilis strains. Midwestern row crop producers expanding integrated pest management practices under USDA Conservation Stewardship Program incentives drive fastest uptake in this category.
- Fungicides:Synthetic azole and strobilurin chemistries protect against Fusarium and Pythium soil-borne pathogens. Great Plains wheat growers rely on these treatments for stand establishment in high-residue no-till systems.
- Seed Coatings:Polymer-based film formulations without biological or chemical actives improve seed flowability and planting precision. Canola producers in Canadian prairie provinces use colorant-only coatings to meet identity preservation protocols.
Volume sits with insecticides; growth tilts toward biologicals.
Application:
Per-unit seed value and pest pressure sensitivity separate premium from commodity treatment tiers.
- Cereal Crops:Wheat, corn, and barley plantings consume the largest treatment volumes by acreage. Nebraska and Kansas corn operations apply dual-mode insecticide-fungicide combinations to protect high-value hybrid seed investments.
- Oilseeds:Soybean and canola seeds command premium coating expenditures due to higher genetic trait licensing costs and nematode susceptibility. Indiana and Manitoba growers prioritize Heterodera glycines control in continuous soybean rotations.
- Pulses:Lentil and dry bean producers in North Dakota and Saskatchewan apply rhizobial inoculants for nitrogen fixation enhancement. Smaller seeded crops require precise coating uniformity to avoid planting equipment clogging.
- Vegetables:High-value hybrid tomato, pepper, and onion seeds receive intensive fungicidal protection in transplant production systems. California Central Valley and Florida vegetable operations specify zero-tolerance seedling mortality rates.
Cereal crops anchor volume; oilseeds capture margin expansion.
Distribution Channel:
Application equipment ownership and planting timeline urgency shape channel selection.
- Direct Sales:Major crop science companies supply treated seed through captive conditioning facilities co-located with genetic trait production. Corn Belt growers purchasing stacked-trait hybrids receive pre-treated seed with bundled chemistry packages.
- Wholesale:Independent seed dealers and cooperatives operate regional treaters serving smaller acreage operations. Red River Valley facilities report volume gains as growers unbundle coating services from genetic licenses.
- Specialty Stores:Agricultural supply retailers stock biological inoculants and small-package treatments for horticultural and specialty crop producers. Urban fringe operations near Minneapolis and Toronto source organic-compliant coatings through this channel.
- Online Retail:E-commerce platforms serve hobby farmers and small-scale vegetable producers with limited local dealer access. Cold-chain shipping constraints restrict biological product availability through this channel.
Direct sales concentrate volume; wholesale gains share fastest.
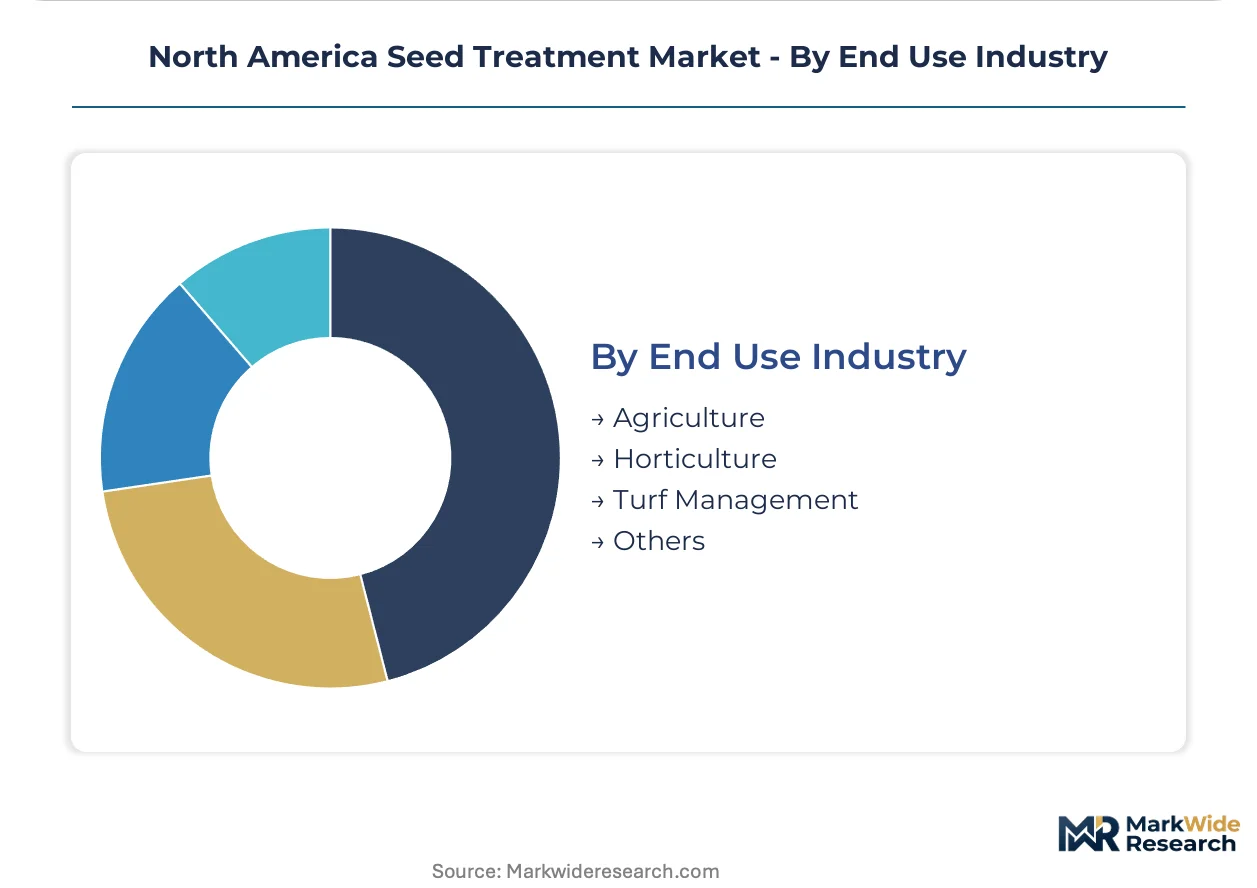
End Use Industry:
Yield risk tolerance and output price volatility determine treatment intensity per acre.
- Agriculture:Commercial row crop and small grain operations represent the dominant demand base. Corn-soybean rotation systems in the Midwest apply treatment to virtually every planted acre.
- Horticulture:Nursery stock, greenhouse transplants, and protected vegetable production require pathogen-free germination. Michigan and Ohio greenhouse complexes specify certified disease-free coated seed for ornamental production.
- Turf Management:Golf course superintendents and sports field managers apply fungicidal treatments to cool-season grass seed for establishment reliability. Kentucky bluegrass and perennial ryegrass coatings dominate this segment.
- Others:Forage grass and cover crop seed treatments support soil health and erosion control programs. USDA Environmental Quality Incentives Program participants in the Dakotas treat Cereal rye for fall biomass production.
Agriculture commands volume; horticulture shows steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US-Mexico-Canada Agreement's agricultural provisions and USDA Climate-Smart Commodities grants are concentrating seed treatment investment corridors across the Great Plains and Canadian prairies. Federal conservation incentives in the United States and provincial sustainability programs in Canada are redirecting procurement toward biological alternatives.
United States
EPA FIFRA re-registration deadlines for neonicotinoid-coated seeds are forcing Corn Belt formulators to rebuild portfolios before the 2027 planting cycle. USDA Conservation Stewardship Program incentives accelerate biological adoption across Iowa, Illinois, and Indiana soybean operations. Nebraska and Kansas corn producers now negotiate seed coating services separately from genetic trait licenses.
Canada
Health Canada PMRA parallel review requirements for pollinator-exposed chemistries compress product lifecycles for conventional insecticidal treatments. Saskatchewan and Manitoba canola growers remain underpenetrated for biological seed treatment relative to US Midwest adoption rates. Prairie province identity preservation protocols drive demand for colorant-only polymer coatings.
Mexico
SADER phytosanitary protocols for cross-border seed movement create compliance complexity for US-treated corn shipments entering Bajío region operations. Northern border state vegetable producers specify zero-tolerance seedling mortality rates for high-value hybrid tomato and pepper transplants. Jalisco and Sinaloa greenhouse complexes source certified disease-free coated seed through specialty agricultural supply channels.
North America Seed Treatment Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across formulation, coating technology, and distribution vectors. The vendor base clusters around three strategic archetypes: integrated crop science majors with captive seed conditioning infrastructure, independent formulators supplying wholesale treaters, and biological specialists targeting USDA conservation incentive programs. Dominant competitive moves include backward integration into polymer binder manufacturing and technology licensing partnerships with drone-based micro-coating system developers.
Among Germany-based integrated agriscience conglomerates, Bayer SE and BASF SE exemplify the diversified major archetype through their combined genetic trait and chemistry pipelines. Corteva Agriscience, structured as a US-incorporated agriscience pure-play, occupies a distinct position emphasizing proprietary coating adhesion technologies. Syngenta Group, with Swiss-Chinese ownership structure, anchors the biologicals expansion vector through nematode-control seed applications.
| Leading Market Players |
|---|
| BASF SE |
| Bayer AG |
| Corteva Agriscience |
| Syngenta Group |
| Nufarm Ltd |
| UPL Limited |
| Albaugh LLC |
| FMC Corporation |
| Valent U.S.A. LLC |
| Others |
Value Network & Pricing Analysis
Large-scale corn operations in Nebraska and Kansas negotiate coating services separately from genetic trait licenses, driving a shift toward unbundled transactional pricing. This buyer concentration in the Corn Belt anchors regional price benchmarks while smaller acreage operations in the Red River Valley face premium markups for independent treatment facility access.
Pricing Analysis
Short lead-time requests during compressed planting windows command 15-25% premiums over standard-schedule coating services. Three-tier pricing structure across premium biological formulations, standard synthetic chemistries, and economy polymer-only coatings stratifies the market. Cost compression in synthetic fungicide tiers stems from active ingredient supply concentration among three chemical manufacturers. Wholesale treaters serving smaller operations exhibit highest price sensitivity, while captive conditioning facilities at major crop science companies absorb margin pressure through bundled seed-chemistry packages.
Supply Chain Analysis
EPA FIFRA registration and Health Canada PMRA parallel review requirements gate market entry for new active ingredients, extending time-to-market for biological formulations. Manufacturing concentrates in the United States, Germany, and China for polymer binder production and fermentation capacity. Supply chains draw from concentrated synthetic fungicide technical supply, live microbial culture production, and specialty colorant manufacturing. Single-source vulnerability in double-stranded RNA manufacturing capacity for RNA interference treatments creates bottleneck risk. Distribution runs through captive conditioning facilities co-located with genetic trait production, independent regional treaters, and agricultural supply retailers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America seed treatment market is becoming a vertical-integration race as players pursue backward integration into polymer binder manufacturing to secure coating adhesion performance and reduce formulation cost exposure.
For Market Incumbents: Acquire fermentation scale-up capacity to secure biological active ingredient supply as EPA neonicotinoid restrictions force portfolio restructuring. Defend market position by locking exclusive distribution through captive seed conditioning infrastructure before independent treaters gain wholesale share. The threat of biological formulation instability limiting distribution radius favors players with distributed production footprints. For New Entrants and Emerging Players: Begin with underpenetrated Canadian prairie provinces where Saskatchewan and Manitoba canola growers lag US Midwest biological adoption rates. Target drone-based micro-coating technology partnerships to bypass centralized conditioning infrastructure and serve large-scale operations seeking planting customization. Carbon credit stacking through USDA Climate-Smart Commodities grants offers a differentiated go-to-market angle for biological input documentation. For Investors and Strategic Acquirers: The window for entry favors biological specialists with nematode-control seed applications and proprietary polymer adhesion technologies. Long-term viability hinges on portfolio positioning ahead of EPA pollinator risk determinations that will compress conventional chemistry product lifecycles. Watch for EPA ecological risk assessment publication timelines as the signal for accelerated incumbent restructuring and acquisition activity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Manufacturing | Corteva's proprietary coating technologies demonstrate how captive binder production secures formulation performance differentiation. |
| Biological Portfolio Expansion | Syngenta's nematode-control applications show how living organism pipelines capture USDA conservation incentive flows. |
| Drone-Based Micro-Coating Development | Aerial application systems enable on-farm seed treatment customization, bypassing centralized Red River Valley conditioning infrastructure. |
| Canadian Prairie Market Entry | Saskatchewan and Manitoba canola operations remain underpenetrated relative to US biological adoption benchmarks. |
| Carbon Credit Stacking Programs | USDA Climate-Smart Commodities grants create incremental revenue streams for farmers documenting biological input use. |
Research Methodology
Document review covered EPA FIFRA registration databases, USDA conservation program guidelines, and Health Canada PMRA submission records, complemented by interviews with seed treatment formulators, crop science R&D directors, and agricultural cooperative procurement managers. Secondary validation drew from SEC filings of diversified agriscience conglomerates, customs trade data on polymer binder imports, and state department of agriculture treated seed regulatory updates. Bottom-up acreage treatment rates and top-down manufacturer revenue triangulation anchored market sizing.
Cross-referencing historical adoption curves against industry panel input shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product chemistry tier, crop application category, distribution channel structure, and regulatory compliance cluster. CAGRs were derived through logistic diffusion modeling of biological adoption rates and price elasticity analysis of unbundled coating services. Industry-specific forecast inputs incorporated EPA re-registration timeline probabilities and USDA Conservation Stewardship Program enrollment trajectories.
Underlying measurement precision varies by segment; biological seed treatment volumes carry wider confidence intervals than synthetic fungicide benchmarks due to formulation stability variability and farmer reporting inconsistencies. Forecasts reflect assumptions about EPA pollinator risk assessment outcomes and Canadian provincial sustainability program funding continuity. A model refresh is warranted upon material change in EPA clothianidin and thiamethoxam registration status.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seed Processing Innovations
Oilseed Processing Market
Seed Processing Innovations
Fenugreek Seed Extract Market
Seed Processing Innovations
Alfalfa Seed Extract Market
Seed Processing Innovations
Maize Seed Treatment Market
Seed Processing Innovations
United States Seed Treatment Market
Seed Processing Innovations
Asia-Pacific Seed Treatment Market
Seed Processing Innovations
Rice Seed Treatment Market
Seed Processing Innovations
Argentina Seed Treatment Market
Seed Processing Innovations
Seed Sorting Machine Market
Seed Processing Innovations
India Seed and Grain Cleaning and Grading Machine Market
Seed Processing Innovations
Soybean Seed Treatment Market
Seed Processing Innovations
Australia Seed Treatment Market
Seed Processing Innovations
Sprouted Durum Wheat for Pasta Applications Market
Seed Processing Innovations
North America Soybean Seed Treatment Market
Seed Processing Innovations
South America Seed Treatment Market
Seed Processing Innovations
Italy Seed Treatment Market