
 Trapping and Mating Disruption Systems Market | 2026-2036
Trapping and Mating Disruption Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Trapping and Mating Disruption Systems Market Analytics
Performance-grade pheromone formulations is collapsing the cost gap with synthetic pesticide programs across high-value orchards and vineyards. Suterra LLC leverages backward integration into pheromone synthesis to sustain margin control across North American tree nut markets. Shin-Etsu Chemical Co., Ltd. anchors Asian supply through captive production of silkworm-derived pheromone precursors.
Trapping and mating disruption systems deploy species-specific semiochemical lures—typically microencapsulated pheromones or kairomones at 0.1–10 mg release rates—to interfere with insect reproduction or concentrate pests for removal. These systems serve commercial agriculture, stored goods facilities, and vector control programs seeking targeted intervention without broad ecological toxicity. Pheromone traps currently dominate installed base value due to established efficacy in Lepidoptera management, while solar powered systems represent the fastest-expanding technology tier as off-grid vineyard and plantation deployments multiply. The behavioral disruption devices segment occupies concentrated margin pools where multi-species matrix formulations command premium positioning against single-pest alternatives.
The EPA registers all pheromone and kairomone products under FIFRA, with biopesticide classification accelerating review timelines relative to conventional chemistries. The EU's Farm to Fork strategy, enforced through EFSA residue protocols and member state sustainable use directives, restricts neonicotinoid and pyrethroid applications in pollinator-exposed zones. California's Department of Pesticide Regulation mandates agricultural use reporting that tracks mating disruption acres separately, creating transparent demand signals for program expansion. Stakeholders must monitor how pollinator protection buffer zones reshape permissible application geometries against pheromone dispenser placement economics.
Market Dynamics
Performance-grade pheromone synthesis is collapsing cost structures against synthetic pesticide programs, while regulatory mandates across multiple jurisdictions accelerate displacement of broad-spectrum chemistries in pollinator-exposed zones.
Growth Catalysts
- EU Sustainable Use of Pesticides Regulation:Mandatory reduction targets for chemical inputs are forcing orchard and vineyard operators toward species-specific behavioral interventions.
- Integrated pest management mandates:California's Department of Pesticide Regulation now tracks mating disruption acres separately, creating transparent demand signals for program expansion across tree nut and stone fruit operations.
- Solar-powered dispenser technology:Off-grid vineyard and plantation deployments are multiplying across Australia's Margaret River and Chile's Central Valley, eliminating electrical infrastructure barriers.
Market Restraints
- Pheromone precursor supply concentration:Silkworm-derived synthesis routes depend on captive Asian production, exposing formulators to input volatility and trade friction.
- Species-specific formulation limitations:Single-pest dispensers require precise pest identification and timing, complicating adoption in multi-pest orchard systems without matrix formulations.
- FIFRA registration timelines:EPA biopesticide classification accelerates review relative to conventional chemistries, yet novel kairomone blends still face 18-24 month evaluation windows.
Strategic Opportunities
- Brazilian citrus and soybean expansion:ANVISA's residue monitoring protocols are tightening, creating entry points for mating disruption systems in South America's largest agricultural economy.
- Stored goods facilities:Warehouse and grain elevator operators seek targeted intervention without fumigation downtime, opening volume channels beyond traditional crop applications.
- Multi-species matrix formulations:Premium positioning against single-pest alternatives commands concentrated margin pools where behavioral disruption devices integrate Lepidoptera, Coleoptera, and Diptera management.
Industry Challenges
- Semiochemical formulation expertise:Microencapsulation and controlled-release engineering require specialized talent scarce outside established pheromone synthesis clusters.
- Legacy dispenser retrieval logistics:Seasonal vineyard and orchard operations face labor bottlenecks removing spent polyethylene tubes, complicating residue compliance and environmental claims.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Trapping and Mating Disruption Systems Market |
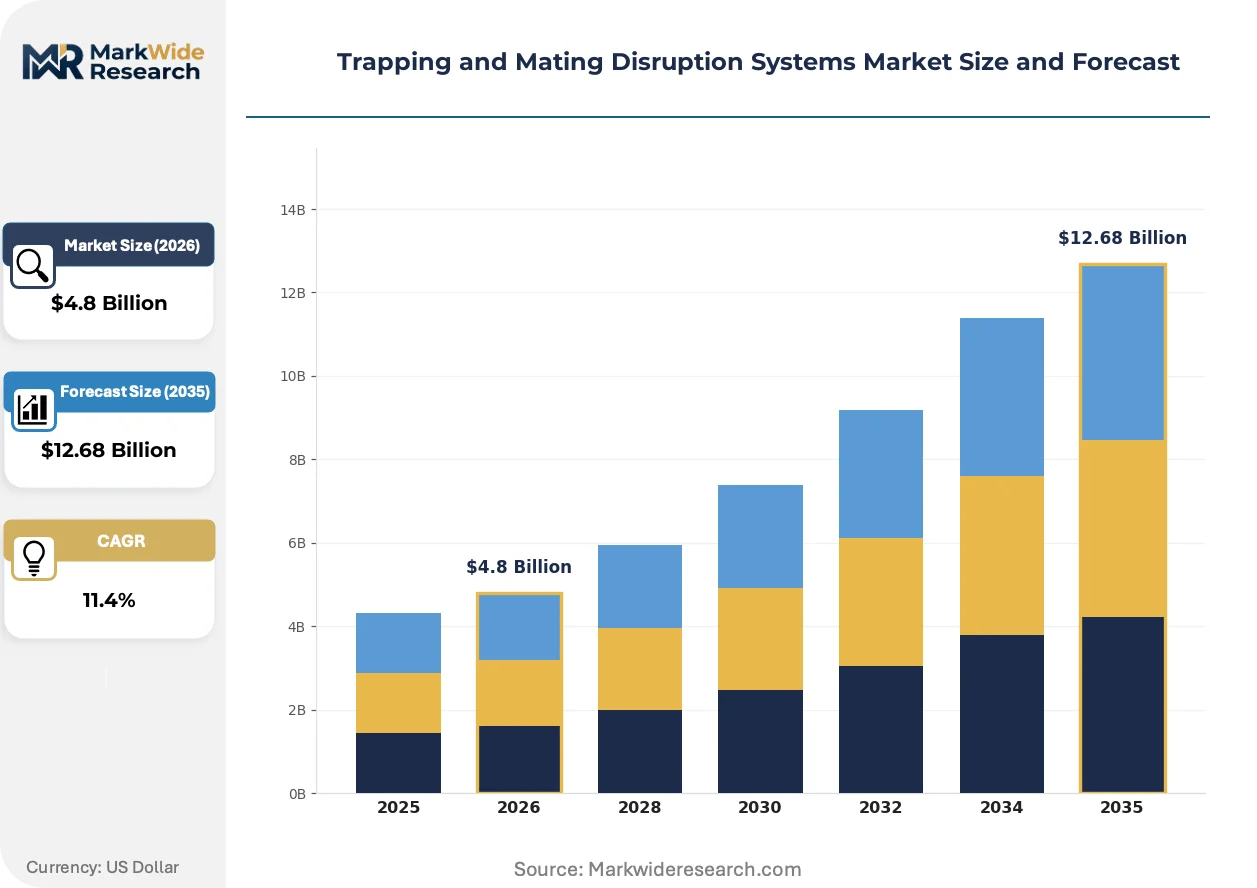
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.68 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mass Traps, Pheromone Traps, Behavioral Disruption Devices, Chemical Disruption Systems Application: Agricultural Pest Control, Residential Pest Management, Public Health, Stored Product Protection Technology: Solar Powered Systems, Electronic Traps, Biochemical Traps, Mechanical Traps End User: Farmers, Pest Control Companies, Government Agencies, Food Processors |
| Companies Covered | Suterra LLC, ISCA Technologies, Shin-Etsu Chemical Co., Ltd., Koppert Biological Systems, BASF SE, Trécé, Inc., Russell IPM Ltd, Provivi, Inc., Pherobank B.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Trapping and Mating Disruption Systems Market Evolving Landscape
Active reshaping of this market centers on three vectors: hardware miniaturization enabling precision placement, regulatory chemistry reclassification accelerating competitive displacement, and procurement model evolution favoring integrated service provision over component sales.
Microencapsulated pheromone formulations with 0.1–10 mg controlled release rates now dominate Lepidoptera management, with specialty crop growers in California's Central Valley and France's Champagne region adopting at accelerated pace. The technology is bifurcating the installed base between premium matrix systems commanding service-contract positioning and commodity single-pest traps facing margin compression.
EFSA residue protocols under the EU Farm to Fork strategy restrict neonicotinoid and pyrethroid applications in pollinator buffer zones, directly constraining permissible application geometries. Orchard operators in Spain's Ebro Valley and Italy's Emilia-Romagna are reconfiguring spray programs around pheromone dispenser placement economics, with member state sustainable use directives creating uneven compliance landscapes.
Integrated pest management service contracts are displacing standalone product sales across high-value vineyard operations, with buyers demanding outcome-based performance guarantees rather than component procurement. This shift concentrates most visibly in Australia's premium wine regions, where contracted pest suppression aligns with sustainability certification requirements for export market access.
Trapping and Mating Disruption Systems Market Segmentation
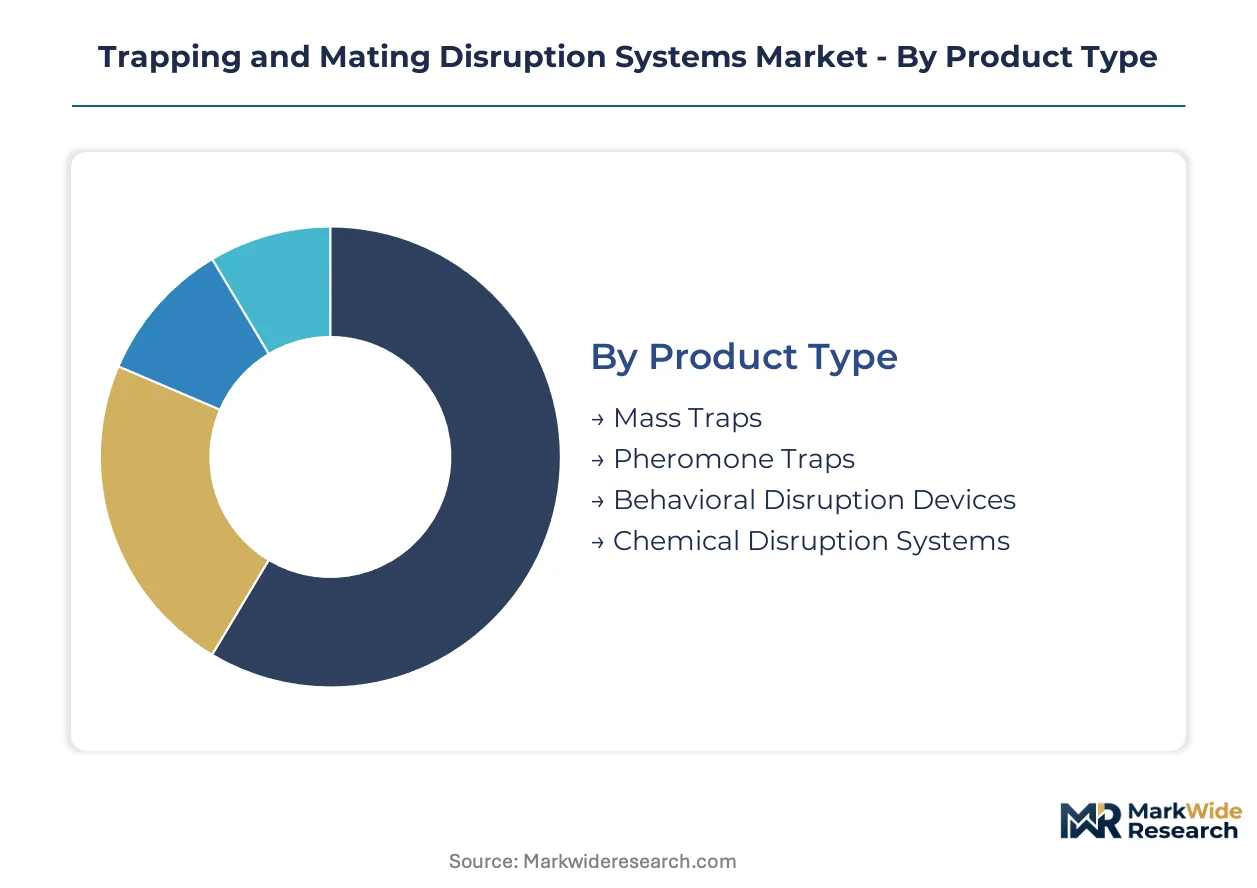
Segmentation in trapping and mating disruption systems reveals how margin pools concentrate around technology sophistication and regulatory compliance tiers. Product architecture and power source decisions determine whether vendors capture service-contract premiums or compete on hardware commodity margins.
Product Type:
Margin concentration sits with systems that integrate controlled-release engineering and multi-species formulation capability.
- Behavioral Disruption Devices:Multi-species matrix formulations command premium positioning through integrated Lepidoptera, Coleoptera, and Diptera management. California's Department of Pesticide Regulation tracks mating disruption acres separately, creating transparent demand signals for program expansion in tree nut and stone fruit operations.
- Pheromone Traps:Microencapsulated semiochemical lures at 0.1–10 mg release rates dominate installed base value through established efficacy in vineyard and orchard Lepidoptera management. Australia's Margaret River and France's Champagne region growers adopt at accelerated pace as residue protocols tighten.
- Mass Traps:High-volume capture systems serve warehouse and grain elevator operators seeking targeted intervention without fumigation downtime.
- Chemical Disruption Systems:Synthetic kairomone blends face 18-24 month EPA evaluation windows under biopesticide classification.
Behavioral disruption devices hold installed capacity. Pheromone traps are rotating up the share rankings.
Application:
Volume concentration follows regulatory mandate intensity across pollinator-exposed agricultural zones.
- Agricultural Pest Control:Specialty crop growers in California's Central Valley and Spain's Ebro Valley reconfigure spray programs around dispenser placement economics as pyrethroid restrictions bite. EU Sustainable Use of Pesticides Regulation mandatory reduction targets force orchard operators toward species-specific behavioral interventions.
- Stored Product Protection:Warehouse and grain elevator operators eliminate fumigation downtime through targeted semiochemical intervention, opening volume channels beyond traditional crop applications. ANVISA's residue monitoring protocols in Brazil create entry points for mating disruption systems in South America's largest agricultural economy.
- Public Health:Vector control programs deploy species-specific lures for mosquito and fly management in urban corridors.
- Residential Pest Management:Consumer-grade pheromone traps serve suburban households with limited technical deployment support.
Agricultural pest control anchors current revenue. Stored product protection is climbing the fastest.
Technology:
Power infrastructure requirements segment adoption between grid-dependent and off-grid deployment economics.
- Solar Powered Systems:Photovoltaic dispenser units eliminate electrical infrastructure barriers across Australia's Margaret River and Chile's Central Valley vineyard corridors. Off-grid plantation deployments multiply as solar miniaturization enables precision placement without trenching or generator dependency.
- Electronic Traps:Sensor-integrated capture systems with remote monitoring capability command service-contract premiums in high-value wine regions.
- Biochemical Traps:Passive semiochemical diffusion systems compete on lowest hardware cost for broad-acre commodity crops.
- Mechanical Traps:Legacy polyethylene tube dispensers face labor bottlenecks in seasonal retrieval logistics.
Electronic traps dominate premium tier positioning. Solar powered systems are gaining share fastest.
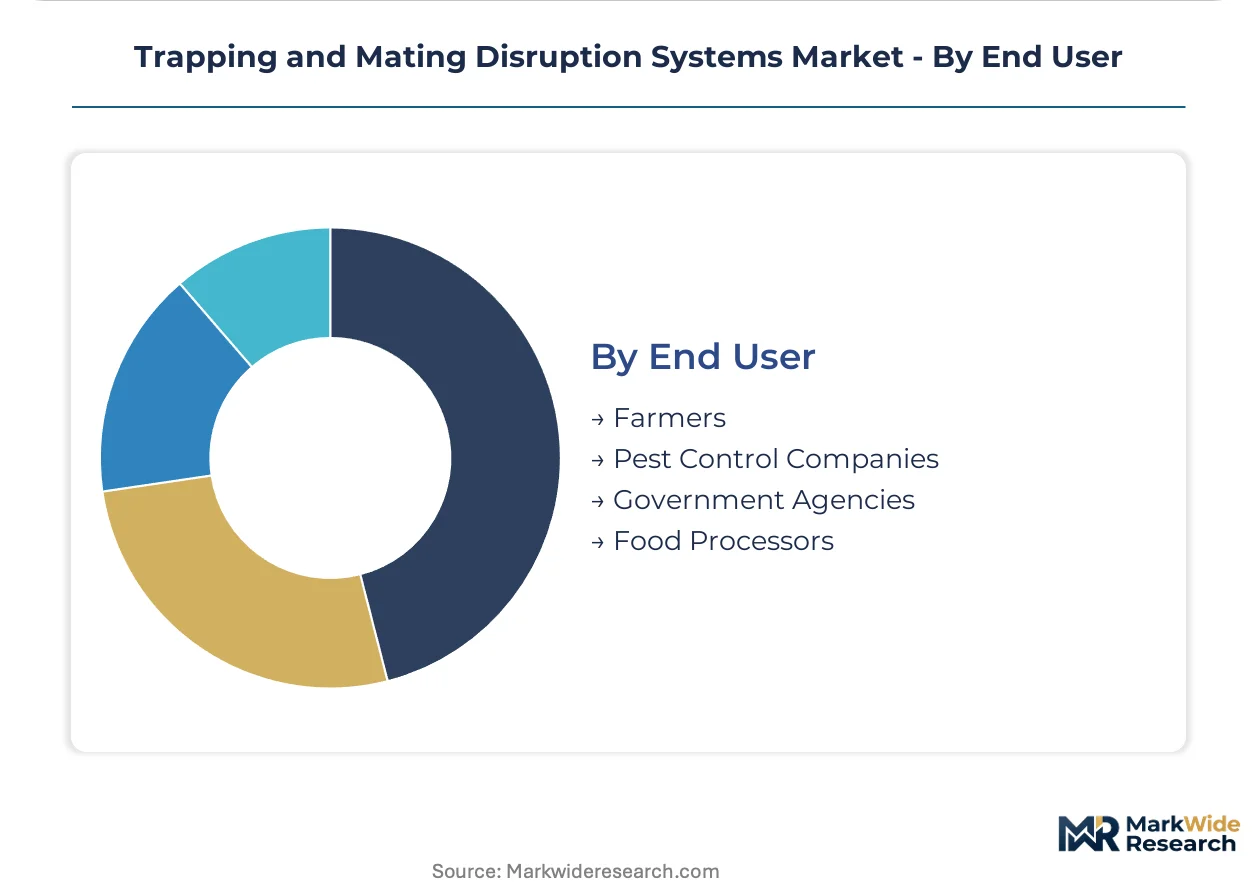
End User:
Procurement sophistication separates integrated service buyers from component purchasers.
- Farmers:California tree nut and stone fruit operators adopt outcome-based performance guarantees rather than component procurement, concentrating demand in Australia's premium wine regions where contracted pest suppression aligns with sustainability certification requirements.
- Pest Control Companies:Service integrators bundle dispenser deployment with monitoring and seasonal maintenance across multi-pest orchard systems.
- Government Agencies:Vector control programs in public health corridors specify species-specific lures for regulatory compliance documentation.
- Food Processors:Grain elevator and warehouse operators prioritize residue-free intervention timelines for export market access.
Farmers represent the largest addressable base. Pest control companies are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-driven agricultural economies generate concentrated demand for residue-compliant pest management, while import-dependent food markets prioritize border biosecurity applications. Trade corridor positioning shapes technology deployment intensity across major producing regions.
United States
California's Central Valley tree nut and stone fruit operations drive North American adoption as the state's Department of Pesticide Regulation tracks mating disruption acres separately. EPA biopesticide classification under FIFRA accelerates registration timelines for novel semiochemical formulations. Vineyard corridors in Napa and Sonoma counties expand solar-powered dispenser deployments to meet sustainability certification requirements for export market access.
Brazil
ANVISA's tightening residue monitoring protocols create entry points for mating disruption systems across citrus and soybean expansion zones. The national agricultural regulator enforces maximum residue limits that constrain synthetic pyrethroid applications in pollinator-exposed areas. São Paulo state's citrus belt operators reconfigure spray programs around behavioral intervention economics as export compliance intensifies.
Spain
Ebro Valley orchard operators face EU Sustainable Use of Pesticides Regulation mandatory reduction targets that force species-specific behavioral interventions. EFSA residue protocols restrict neonicotinoid geometries in pollinator buffer zones. Catalonia's stone fruit and almond producers accelerate pheromone dispenser adoption to maintain access to Northern European retail channels.
Australia
Margaret River and Barossa Valley vineyard operators deploy solar-powered systems to eliminate electrical infrastructure barriers across off-grid plantation zones. The national agricultural regulator enforces export residue protocols that favor non-chemical intervention timelines. Premium wine regions adopt outcome-based service contracts aligning pest suppression with sustainability certification requirements.
Chile
Central Valley fruit exporters confront EU and US residue protocols that restrict conventional chemistry in stone fruit and table grape shipments. The national agricultural service mandates integrated pest management compliance for export registration. Maule and O'Higgins region operators expand solar dispenser networks across vineyard and cherry orchard corridors to secure market access.
Trapping and Mating Disruption Systems Market Competitive Landscape
Listed leaders compete with private specialists across formulation sophistication and geographic coverage dimensions. The vendor base stratifies between consolidated chemical conglomerates with biopesticide divisions and focused semiochemical specialists with captive synthesis capabilities. Three archetypes dominate: backward-integrated pheromone manufacturers, service-integrating pest management providers, and research-driven formulation innovators. Competitive moves concentrate on strategic partnerships for geographic expansion and technology licensing for multi-species matrix development.
Among North American specialists, Suterra LLC and ISCA Technologies exemplify the integrated formulation archetype, while Japan-based Shin-Etsu Chemical Co., Ltd. anchors Asian supply through captive production positioning. These three occupy distinct competitive terrain—Suterra LLC leverages tree nut market concentration, ISCA Technologies represents research-driven innovation capacity, and Shin-Etsu Chemical Co., Ltd. exemplifies upstream chemical integration into agricultural applications.
| Leading Market Players |
|---|
| Suterra LLC |
| ISCA Technologies |
| Shin-Etsu Chemical Co., Ltd. |
| Koppert Biological Systems |
| BASF SE |
| Trécé, Inc. |
| Russell IPM Ltd |
| Provivi, Inc. |
| Pherobank B.V. |
| Others |
Value Network & Pricing Analysis
Long-term offtake contracts between pheromone formulators and California tree nut growers lock in supply access and price visibility across multi-season deployment cycles. These arrangements transfer input volatility risk from specialty crop operators to manufacturers with captive synthesis capabilities, while ANVISA's tightening residue protocols in Brazil create parallel contract structures for citrus belt operators seeking export compliance.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels in the trapping and mating disruption systems market. Price differentiation stems from certification grade—EPA biopesticide registration tier versus state-level exemption status—and volume scale across thousand-acre vineyard contracts versus smallholder orchard programs. Cost compression in commodity single-pest traps is intensifying because microencapsulation technology licensing fees are spreading across larger production runs. Smallholder farmers in pollinator-exposed zones exhibit highest price sensitivity, while premium wine region operators in Australia's Margaret River demonstrate lowest sensitivity due to sustainability certification requirements.
Supply Chain Analysis
Japan and China anchor pheromone precursor production through captive silkworm-derived synthesis routes and fermentation-based alternative chemistry. Formulation inputs draw from specialty polymer microencapsulation resins sourced from German chemical manufacturers and photovoltaic components for solar-powered dispensers concentrated in Taiwanese electronics assembly. Single-source vulnerability persists around silkworm pupae extract supply, which feeds from seasonal sericulture cycles concentrated in Zhejiang province. Distribution runs through agricultural input distributors with technical service capabilities, bypassing commodity chemical wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunities are expanding as procurement model evolution splinters demand between integrated service contracts and component sales, creating distinct competitive arenas for specialists with formulation depth versus hardware commoditizers.
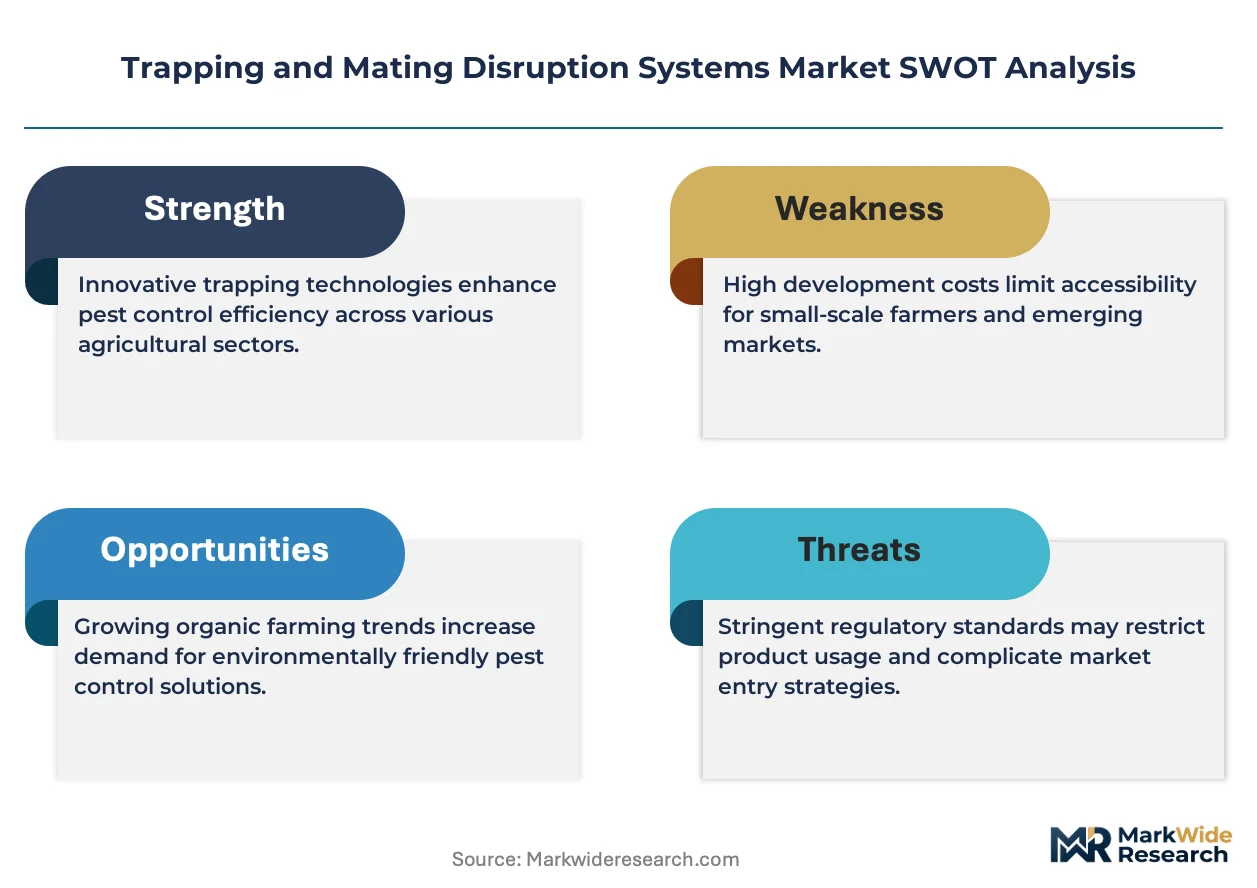
For Market Incumbents: Compound defensive positioning through backward integration into pheromone synthesis and capacity reservation agreements with sericulture cooperatives in Asia. The threat of solar-powered dispenser commoditization by electronics assemblers entering agricultural hardware demands preemptive certification investment in multi-species matrix formulations. Channel control through exclusive technical service partnerships with California pest control companies represents the critical lever for margin defense. For New Entrants and Emerging Players: Lead with stored product protection applications in Brazilian grain elevators and Southeast Asian warehouse corridors, where residue monitoring protocols are tightening fastest. The most penetrable segment sits with mid-scale vineyard operators in Chile's Central Valley seeking solar-powered alternatives to grid-dependent systems. A go-to-market angle anchored in outcome-based performance guarantees—pest suppression metrics rather than hardware delivery—aligns with procurement shifts in premium wine regions. For Investors and Strategic Acquirers: Capital is best deployed toward semiochemical specialists with captive synthesis capabilities and established EPA biopesticide registration portfolios, positioned for long-term viability as conventional chemistry displacement accelerates across pollinator-exposed agricultural zones. Acquisition targets should demonstrate multi-species formulation expertise and service-contract revenue concentration. The signal to watch is California Department of Pesticide Regulation tracking expansion—separate mating disruption acreage reporting to additional states would indicate inflection toward mandated adoption.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pheromone Synthesis | Suterra LLC's captive production of tree nut-targeted lures insulates margin control against Asian precursor volatility. |
| Multi-Species Matrix Formulation Development | Integrated Lepidoptera-Coleoptera-Diptera systems command service-contract premiums in California stone fruit operations. |
| Solar-Powered Dispenser Miniaturization | Photovoltaic unit deployment eliminates electrical infrastructure barriers across Australia's off-grid vineyard corridors. |
| Outcome-Based Service Contract Expansion | Pest suppression guarantees align with sustainability certification requirements for export market access in premium wine regions. |
| Regulatory Registration Acceleration | EPA biopesticide classification under FIFRA compresses novel kairomone blend evaluation timelines relative to conventional chemistries. |
Research Methodology
Desk research of EPA registration databases, EU EFSA residue protocols, and ANVISA monitoring disclosures preceded structured interviews with pheromone synthesis chemists, integrated pest management service directors at California agricultural cooperatives, and procurement leads at Australian wine export consortiums. Secondary validation drew from California Department of Pesticide Regulation use reporting, customs data on semiochemical precursor trade flows, and SEC filings of disclosed biopesticide revenue segments. Bottom-up acreage deployment estimates triangulated against top-down manufacturer capacity disclosures.
Variance decomposition across the projection horizon isolates regulatory mandate intensity, pheromone synthesis cost curves, and solar component price erosion as primary uncertainty sources. Segmentation dimensions modeled include product architecture tier, power source dependency, application sector, and regional regulatory compliance cluster. CAGRs were derived from slope consensus across installed base growth rates and average revenue per acre trajectories. Industry-specific inputs incorporated pollinator buffer zone expansion timelines and export residue protocol harmonization patterns.
Forecasts assume regulatory continuity in EPA biopesticide classification and EU Sustainable Use of Pesticides Regulation enforcement; material policy shifts in either regime would require re-modeling adoption elasticity. Specific risks include trade friction disrupting Asian precursor supply and accelerated neonicotinoid reauthorization altering competitive displacement timelines. Recalibration cycles align with material shifts in state-level integrated pest management mandate expansion and solar photovoltaic cost curves.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Crop Protection
Indonesia Crop Protection Chemicals Market
Crop Protection
Asia-Pacific Crop Protection Chemicals Market
Crop Protection
India Crop Protection Chemicals Market
Crop Protection
Synthetic Pesticide Market
Crop Protection
Latin America Crop Protection Chemicals Market
Crop Protection
Tembotrione Market
Crop Protection
South America Molluscicides Market
Crop Protection
Crop Bactericides Market
Crop Protection
North America Insecticide Market
Crop Protection
France Crop Protection Chemicals Market
Crop Protection
Global SDHI Fungicide Market
Crop Protection
North America Crop Protection Chemicals Market
Crop Protection
Microbial Pesticides Market
Crop Protection
Fumigation Service Market
Crop Protection
Asia-Pacific Nematicides Market
Crop Protection
Indonesia Insecticide Market