
 Global Seed Treatment Fungicides Market | 2026-2036
Global Seed Treatment Fungicides Market Size, Share, and Industry Trends Forecast 2026-2036
Global Seed Treatment Fungicides Market Outlook
Agronomic advisory channels are reshaping how seed treatment fungicides reach row-crop growers, with digital farm-management platforms displacing traditional dealer networks. BASF SE leverages its vertical integration from active ingredient synthesis to on-seed application services to sustain pricing power across major grain markets. Syngenta AG anchors its position through biological-systemic hybrid portfolios, while Bayer AG competes via proprietary coating technologies that extend product adhesion during planting operations.
Seed treatment fungicides comprise chemical or biological agents applied to seeds prior to sowing to suppress soilborne and seedborne fungal pathogens such as Pythium, Fusarium, and Rhizoctonia, typically formulated as liquids, powders, or flowable concentrates containing active ingredients ranging from triazoles to Bacillus subtilis strains. Systemic fungicides penetrate seed tissues to provide internal protection during germination, whereas biological fungicides using microbial antagonists represent the fastest-expanding category as residue-conscious buyers shift procurement toward low-chemistry alternatives. Liquid formulations dominate volume throughput due to compatibility with high-speed commercial treaters, while oilseed applications generate premium margins given the higher per-acre treatment rates for soybeans versus cereal grains.
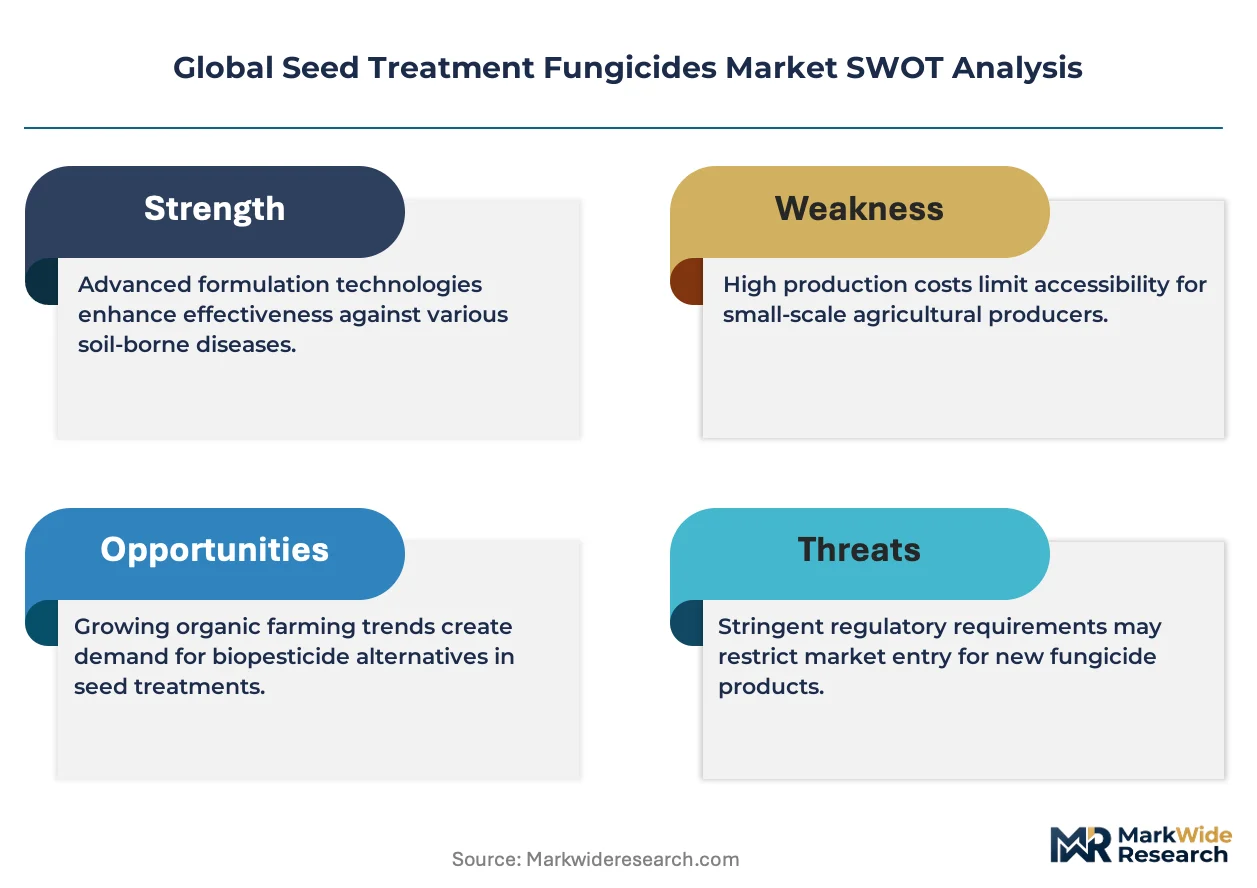
The EPA governs seed treatment registration under the Federal Insecticide, Fungicide, and Rodenticide Act, requiring acute toxicity and environmental fate data that lengthens product development cycles, while the EU Green Deal's pesticide reduction targets are forcing reformulation toward biological actives to maintain market access. India's Central Insecticides Board mandates local efficacy trials before import approvals, creating region-specific registration portfolios that fragment competitive positioning. Stakeholders must monitor evolving residue tolerances in import-dependent grain markets and calibrate R&D pipelines toward biological-systemic combinations that satisfy divergent regulatory thresholds without sacrificing field performance consistency.
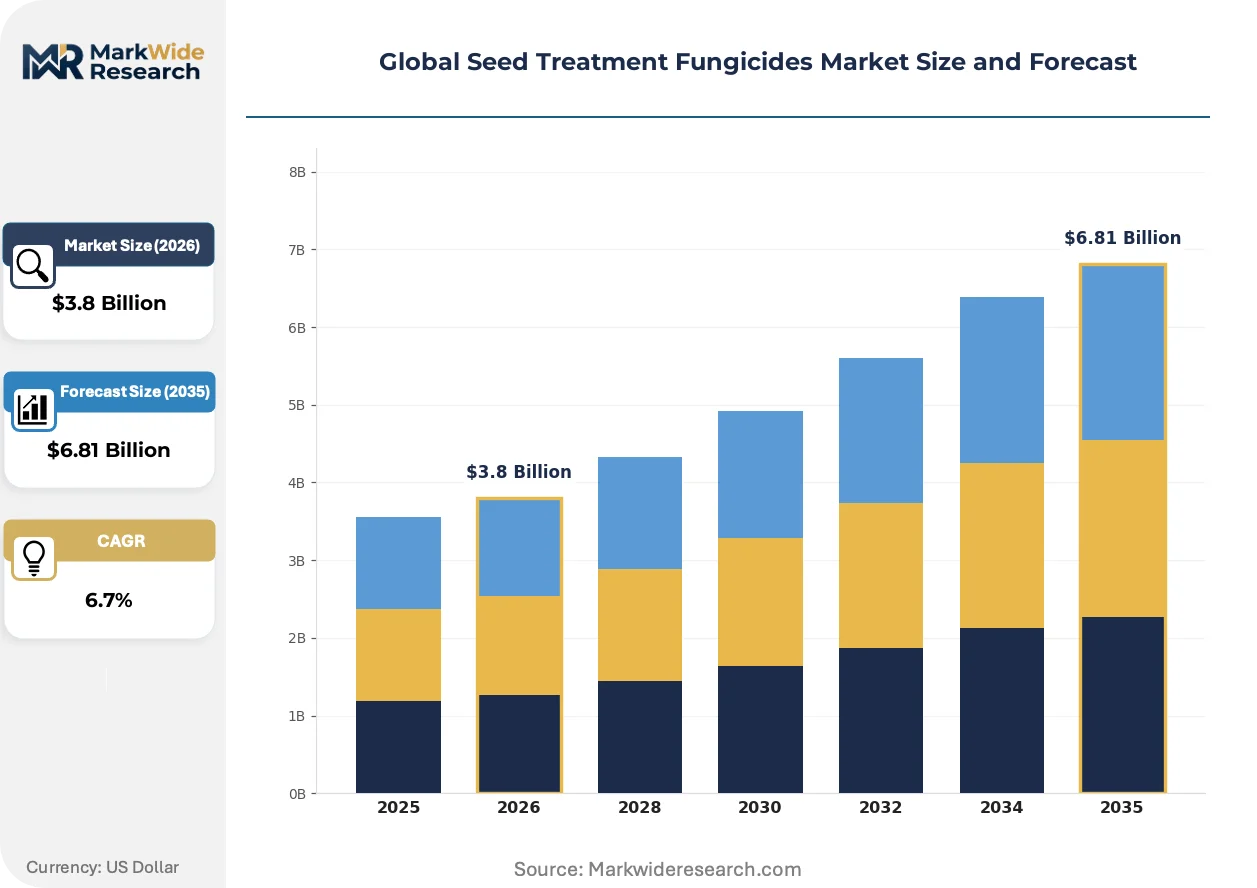
Market Dynamics
Biological-systemic hybrid formulations are compressing traditional chemical-only product cycles as residue thresholds tighten across import-dependent grain corridors.
Growth Catalysts
- EU Green Deal pesticide reduction mandates:The Farm to Fork strategy's 50% chemical reduction target accelerates biological active ingredient substitution in soybean and corn seed treatments.
- Soilborne pathogen pressure in Brazilian Cerrado:Fusarium and Rhizoctonia incidence in double-crop systems drives per-acre treatment rate expansion among specialty crop growers.
- Flowable concentrate technology:Liquid formulation compatibility with high-speed commercial treaters reduces application downtime and labor costs across North American grain elevators.
Market Restraints
- Active ingredient supply concentration:Triazole and strobilurin precursor manufacturing clusters in eastern China create input vulnerability during trade flow disruptions.
- EPA registration timelines:Federal Insecticide, Fungicide, and Rodenticide Act data requirements extend product development cycles, delaying field entry for novel biological actives.
- Seed-applied neonicotinoid substitution limits:Partial chemical fungicide bans in France and Germany restrict combination product portfolios without equivalent standalone biological efficacy.
Strategic Opportunities
- Indian import substitution:Central Insecticides Board local efficacy trial mandates create first-mover advantage for domestic biological formulation partnerships.
- Carbon credit monetization:Biological seed treatment verification protocols under developing soil carbon standards open premium pricing channels for climate-certified growers.
- Digital agronomy platform integration:Farm-management software vendors are embedding treatment recommendation engines that bypass traditional dealer advisory networks.
Industry Challenges
- Biological formulation stability:Bacillus subtilis strain viability during extended storage and temperature fluctuation requires cold-chain infrastructure investment.
- Cross-jurisdiction residue harmonization:Divergent maximum residue limits between EPA, EFSA, and Codex Alimentarius standards complicate export-oriented grain treatment decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Seed Treatment Fungicides Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Contact Fungicides, Systemic Fungicides, Biological Fungicides, Seed Coating Products Crops: Cereal Grains, Oilseeds, Fruits, Vegetables Application Method: Drenching, Coating, Granular Application, Seed Treatment Formulation Type: Liquid Formulations, Solid Formulations, Emulsifiable Concentrates, Wettable Powders |
| Companies Covered | BASF SE, Syngenta AG, Bayer AG, Nufarm, FMC Corporation, ADAMA, Corteva Agriscience, DuPont, UPL Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Seed Treatment Fungicides Market Strategic Shifts
Formulation chemistry and application hardware are converging to reduce chemical load per seed while maintaining pathogen suppression thresholds across variable soil conditions.
Microencapsulation delivery systems for biological actives are rendering obsolete conventional powder-based inoculant formulations that suffer from desiccation and uneven seed coverage. Large-scale corn processors in Iowa and Illinois are adopting encapsulated Trichoderma products at commercial treater throughput rates exceeding 500 bushels per hour. The technology is rendering obsolete legacy dust formulations that required separate hydration steps and extended seed curing periods.
REACH authorization requirements for triazole active ingredients are forcing reformulation toward reduced-risk alternatives across EU member state registration portfolios. ECHA substance evaluation dossiers for prothioconazole and tebuconazole have triggered downstream user notification obligations that lengthen supply chain compliance documentation. Biological-systemic combination products are capturing accelerated regulatory review pathways under EU sustainable use directive implementation.
Direct-to-farm input procurement platforms are compressing traditional three-tier distribution hierarchies spanning manufacturer, regional distributor, and local retailer. Row-crop growers in Brazil's Mato Grosso and Goiás states are purchasing seed treatment services through integrated planting-operation contractors rather than independent input suppliers. This channel consolidation concentrates volume purchasing power among fewer decision-makers and pressures standalone product margins.
Global Seed Treatment Fungicides Market Segmentation
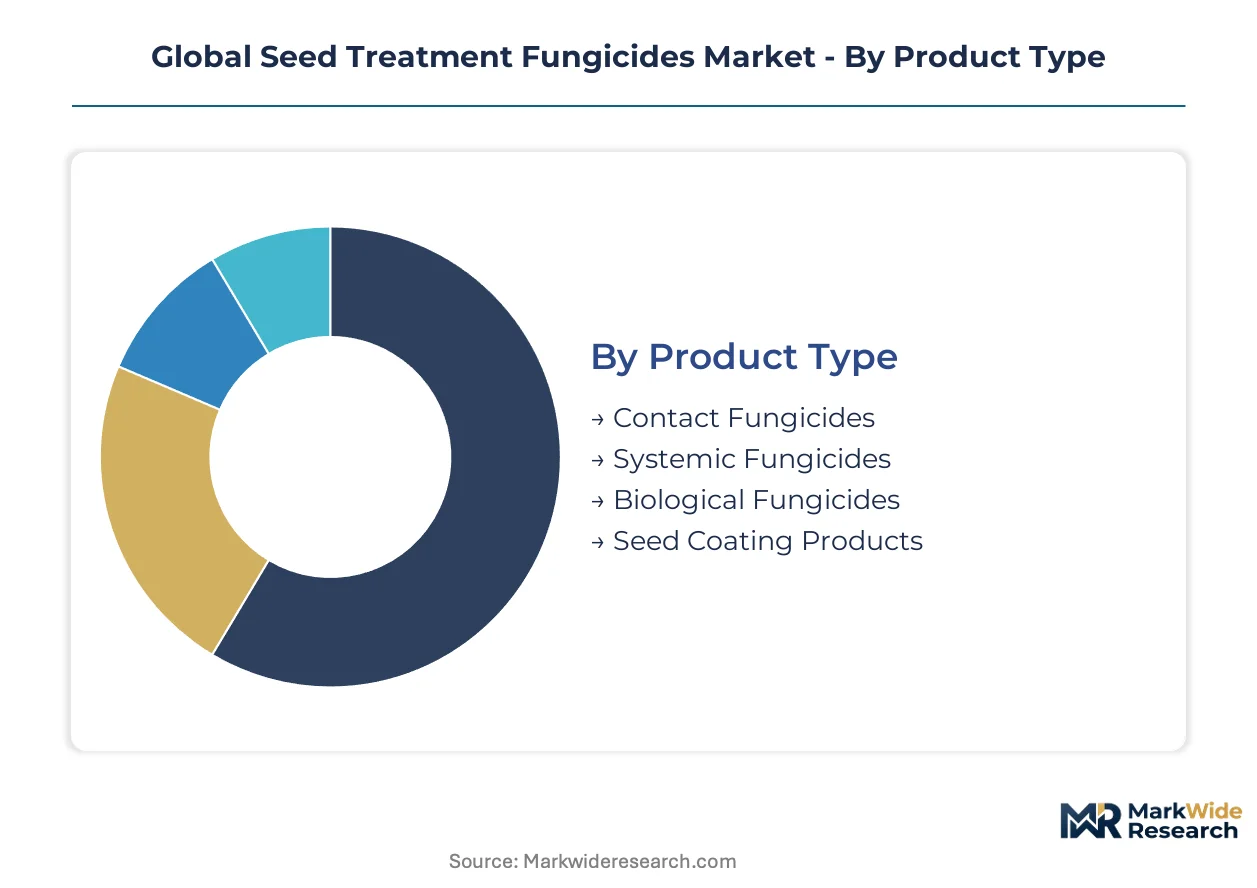
Segmentation in seed treatment fungicides reveals divergent growth trajectories across chemical maturity levels, with biological alternatives compressing traditional product cycles while systemic formulations defend revenue concentration in row-crop belts.
Product Type:
Mature chemistry segments face biological substitution pressure, while emerging actives capture regulatory tailwinds across residue-sensitive import corridors.
- Contact Fungicides:Surface-acting compounds form protective barriers against seedborne pathogens without tissue penetration. Demand concentrates in European cereal operations where Fusarium suppression requirements meet strict pre-harvest interval regulations under EFSA residue protocols.
- Systemic Fungicides:Triazole and strobilurin-based formulations penetrate seed tissues to deliver internal protection during germination. Brazilian soybean growers in Mato Grosso drive per-acre treatment rate expansion as double-crop intensity elevates Rhizoctonia pressure in Cerrado soils.
- Biological Fungicides:Microbial antagonists using Bacillus subtilis and Trichoderma strains gain share fastest where EU Green Deal pesticide reduction mandates reshape procurement specifications.
- Seed Coating Products:Polymer-based carriers integrate fungicide actives with colorants and polymers for visual identification and flowability enhancement.
Systemic fungicides retain volume leadership; biological fungicides hold the steepest expansion curve.
Crops:
Application intensity varies sharply by crop value and disease pressure, with high-acreage commodities commanding formulation scale and specialty crops driving premium pricing.
- Cereal Grains:Wheat and barley treatments emphasize Fusarium head blight suppression through triazole-based coatings. North American spring wheat operations in North Dakota and Saskatchewan prioritize flowable concentrate compatibility with high-speed commercial treaters.
- Oilseeds:Soybean seed treatments command the highest per-acre chemical load among major crops. Brazilian farmers apply combined fungicide-insecticide coatings at rates exceeding cereal grains by 40-60% to address Phytophthora and SDS complex.
- Fruits:High-value perennial crops drive biological fungicide adoption where export residue tolerances to Japan and South Korea restrict synthetic chemistry options.
- Vegetables:Small-seeded crops require precision application equipment and generate premium margins through specialized coating services.
Oilseeds capture the highest treatment value per acre; fruits are climbing the fastest on biological substitution.
Application Method:
Equipment compatibility and labor efficiency determine method selection, with commercial treater throughput requirements favoring continuous-flow systems over batch processes.
- Drenching:Immersion-based application saturates seed surfaces for complete coverage in vegetable and flower seed operations where batch sizes remain manageable.
- Coating:Rotary drum and fluidized bed systems dominate commercial grain elevators across Iowa and Illinois, processing over 500 bushels hourly with uniform active ingredient distribution.
- Granular Application:Boxer-type applicators meter fungicide granules into seed furrows during planting, common in reduced-tillage corn systems where seed treatment coverage is incomplete.
- Seed Treatment:On-site application services at seed company processing facilities integrate fungicide loading with quality testing and packaging.
Coating commands commercial throughput leadership; seed treatment services are gaining share fastest through vertical integration.
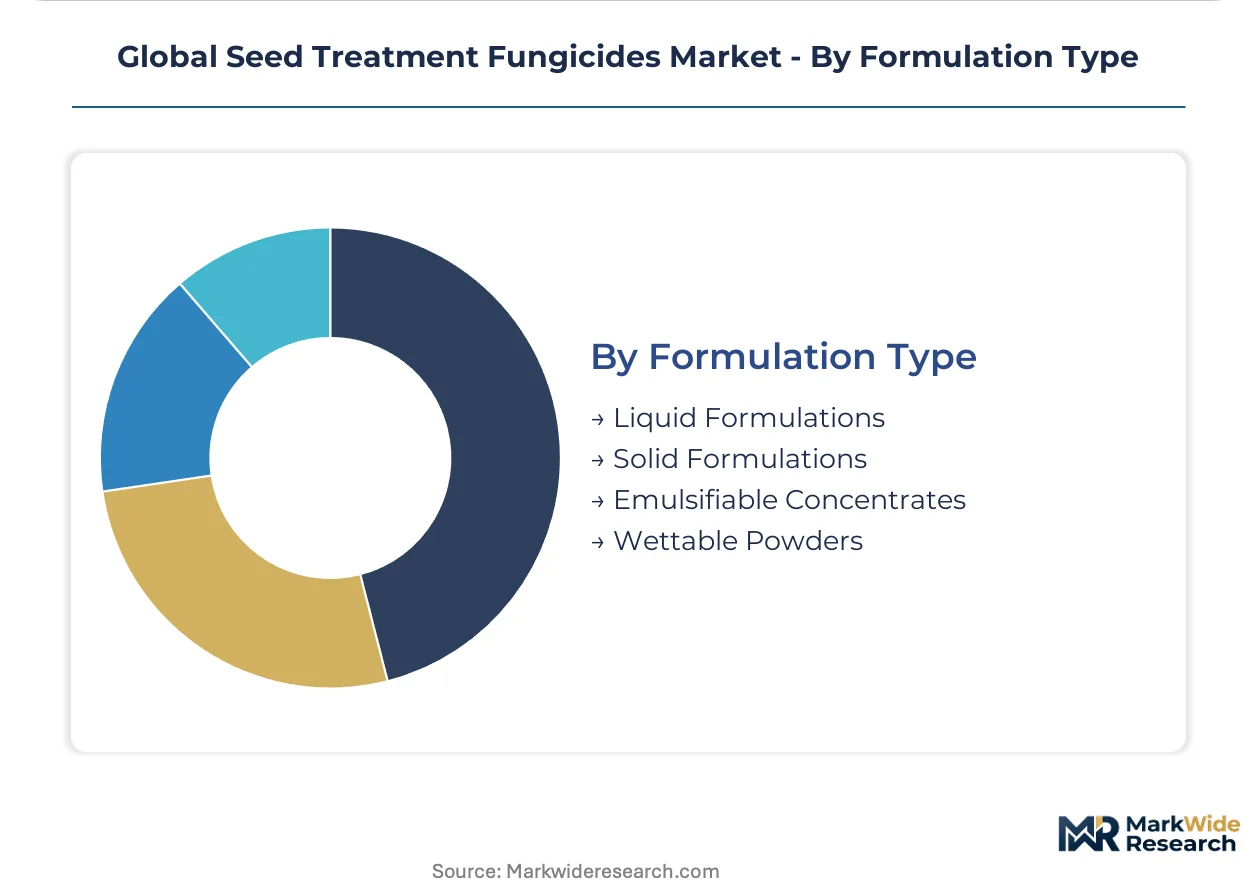
Formulation Type:
Physical state determines storage stability, application equipment compatibility, and active ingredient bioavailability across variable climate conditions.
- Liquid Formulations:Flowable suspensions and solutions dominate high-volume operations through compatibility with automated treater systems. Brazilian commercial elevators prefer liquid triazoles for rapid line turnover and minimal cleanup between batches.
- Solid Formulations:Dusts and granules persist in small-scale vegetable seed operations and regions with limited cold-chain infrastructure for biological storage.
- Emulsifiable Concentrates:Oil-based carriers enhance penetration into waxy seed coats for improved systemic uptake in soybean and cotton applications.
- Wettable Powders:Dry flowables reconstitute at point of use, offering freight cost advantages for remote grain belts in Kazakhstan and Ukraine.
Liquid formulations retain volume leadership; emulsifiable concentrates are expanding most quickly in oilseed-intensive geographies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA registration protocols under FIFRA anchor the dominant geography, shaping product development cycles and field entry timelines for novel biological actives across the North American grain belt.
United States
Iowa and Illinois corn processors drive commercial treater throughput exceeding 500 bushels hourly, demanding flowable concentrate compatibility. EPA FIFRA data requirements extend development cycles for biological-systemic hybrids. The Corn Belt cluster concentrates formulation R&D investment around Des Moines and Chicago agribusiness corridors.
Brazil
Mato Grosso and Goiás soybean growers apply combined fungicide-insecticide coatings at rates 40-60% above cereal grains, addressing Phytophthora and SDS complex. ANVISA import approval pathways fragment registration portfolios versus EPA benchmarks. The Cerrado grain belt anchors double-crop intensity elevating Rhizoctonia pressure and per-acre treatment expansion.
Germany
EFSA residue protocols and REACH authorization requirements for triazole actives force reformulation toward reduced-risk alternatives. ECHA substance evaluation dossiers for prothioconazole trigger downstream user notification obligations. The Rhine-Ruhr industrial corridor concentrates precursor manufacturing for strobilurin and triazole active ingredients.
India
The Central Insecticides Board mandates local efficacy trials before import approvals, creating first-mover advantage for domestic biological formulation partnerships. FSSAI residue tolerances in export-oriented grain markets complicate treatment decisions for basmati rice and wheat consignments. The Punjab-Haryana wheat belt drives flowable concentrate adoption among commercial seed processors.
China
Triazole and strobilurin precursor manufacturing clusters in eastern provinces create input supply concentration for global formulation networks. MEE environmental compliance standards tighten effluent controls on active ingredient synthesis facilities. The Yangtze River Delta agrochemical complex anchors captive supply relationships with multinational seed treatment marketers.
Global Seed Treatment Fungicides Market Competitive Environment
Vertically integrated multinationals and biological-specialist independents split the market into distinct capability tiers. The vendor base concentrates around three strategic archetypes: integrated agrochemical-seed conglomerates with captive formulation capacity, biological-technology specialists leveraging microbial platform IP, and regional toll manufacturers serving import-substitution markets. Competitive moves center on backward integration into active ingredient synthesis and strategic partnerships with digital farm-management platforms.
Within the integrated-agrochemical tier, BASF SE and Syngenta AG exemplify archetypes combining proprietary coating technologies with biological-systemic hybrid portfolios. Bayer AG occupies a position emphasizing seed-adhesion formulations and on-seed application services. These three entities anchor competitive intensity around regulatory compliance speed and commercial treater throughput optimization.
| Leading Market Players |
|---|
| BASF SE |
| Syngenta AG |
| Bayer AG |
| Nufarm |
| FMC Corporation |
| ADAMA |
| Corteva Agriscience |
| DuPont |
| UPL Limited |
| Others |
Value Chain & Pricing Dynamics
Tariff exposure on Chinese-sourced triazole precursors widens pricing spreads between standard flowable concentrates and configured-to-order biological-systemic hybrids while compressing mid-tier chemical-only formulations. Input cost volatility forces Brazilian and North American grain elevators toward long-term offtake contracts with captive synthesis operations, reshaping procurement from spot-market purchasing to integrated supply relationships.
Pricing Analysis
The customization-premium spread separates commodity-grade triazole coatings from engineered biological-systemic combinations that command 15-30% uplifts based on cold-chain certification and strain-specific efficacy guarantees. Price differentiation hinges on formulation complexity and regulatory compliance tier—REACH-authorized actives carry premiums over standard EPA-registered equivalents. Pricing pressure stems from Brazilian direct-to-farm platform consolidation that aggregates volume purchasing power among fewer decision-makers. Small-scale vegetable seed operators exhibit highest price sensitivity, while Iowa and Illinois corn processors prioritize throughput compatibility over per-unit cost.
Supply Chain Analysis
Upstream feedstock concentration in eastern Chinese provinces for strobilurin and triazole precursors creates single-source vulnerability that multinational formulators hedge through captive Indian synthesis partnerships. Active ingredient supply draws from China, India, and Germany, with polymer coating carriers sourced from Rhine-Ruhr petrochemical complexes. Distribution runs through vertically integrated seed company processing facilities and commercial grain elevator networks, bypassing traditional three-tier dealer hierarchies in Brazil's Mato Grosso and Goiás states.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The global seed treatment fungicides market sits in a cyclical recovery phase driven by EU Green Deal pesticide reduction mandates that force biological substitution and refresh product portfolios. Incumbents and entrants must calibrate positioning around regulatory compliance speed and cold-chain infrastructure investment.
For Market Incumbents: Entrench biological-systemic hybrid capabilities through backward integration into Bacillus subtilis strain development and cold-chain logistics networks. Prioritize EPA registration pipeline acceleration to offset FIFRA data requirement delays that disadvantage novel biological entrants. Defend against Brazilian platform consolidation by embedding treatment recommendation engines within digital farm-management software partnerships.
For New Entrants and Emerging Players: Build out domestic biological formulation capacity in India to exploit Central Insecticides Board local efficacy trial mandates that create first-mover advantage before import approval pathways mature. Target carbon credit monetization protocols under developing soil carbon standards as a premium pricing channel for climate-certified grower segments. Pursue toll manufacturing partnerships with regional seed processors to bypass capital-intensive captive synthesis requirements.
For Investors and Strategic Acquirers: The market sits at a substitution-acceleration phase that favors biological-technology specialists with validated microbial platform IP and cold-chain operational capabilities. Long-term viability over the next decade rests on regulatory tailwinds for reduced-risk alternatives rather than chemical-only incumbency. Watch for ANVISA import approval streamlining in Brazil as an inflection signal that would compress competitive moats for domestic formulation partnerships.
| Strategic Initiative | Industry Significance |
|---|---|
| Biological Active Ingredient Scale-Up | Cold-chain infrastructure investment secures Bacillus subtilis viability for commercial treater throughput rates exceeding 500 bushels hourly. |
| Regulatory Fast-Track Partnership | EU sustainable use directive implementation accelerates review pathways for biological-systemic combination products versus chemical-only portfolios. |
| Digital Platform Integration | Farm-management software embedding bypasses traditional dealer networks in Brazil's Mato Grosso and Goiás soybean belts. |
| Carbon Credit Verification Protocol | Soil carbon standard certification opens premium pricing channels for climate-certified growers in residue-sensitive export corridors. |
| Regional Toll Manufacturing | Indian domestic formulation partnerships exploit Central Insecticides Board mandates before import approval pathways mature. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with seed company formulation directors, commercial grain elevator operations managers, Brazilian integrated planting contractors, EPA regulatory affairs specialists, and EU sustainable agriculture policy officers. Secondary validation drew from EPA FIFRA registration databases, ECHA substance evaluation dossiers, ANVISA import approval records, Indian Central Insecticides Board trial protocols, and customs trade data on triazole precursor flows. Bottom-up treatment rate modeling across soybean, corn, and cereal grain segments was cross-checked against top-down agrochemical manufacturer revenue disclosures.
Calibration against historical biological adoption curves in EU member states under Farm to Fork implementation anchored growth assumptions across the analysis window. Segmentation dimensions included product type, crop category, application method, and formulation chemistry maturity, with regional regulatory cluster intensity applied as a cross-cutting modifier. CAGRs were derived from trend-line extrapolation of per-acre treatment rate expansion in Brazilian Cerrado double-crop systems and North American Corn Belt commercial treater throughput data, validated against import-substitution pipeline visibility in India and China.
Practitioners should monitor EFSA residue tolerance revisions and EPA biological active ingredient registration timeline compression for early signals of competitive repositioning. Forecasts reflect assumptions around EU Green Deal implementation pace and Brazilian platform consolidation velocity. Cross-checking against IHS Markit agrochemical trade flow data and seed industry processing capacity announcements is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Crop Protection
Japan Crop Protection Chemicals Market
Crop Protection
Global Chlorpyrifos Market
Crop Protection
Isoxaflutole Market
Crop Protection
Pest Control Market
Crop Protection
South America Crop Protection Chemicals Market
Crop Protection
India Insecticide Market
Crop Protection
United States Nematicides Market
Crop Protection
Soil Sterilizers Market
Crop Protection
Specialty Pesticides Market
Crop Protection
Global Seed Treatment Chemicals Market
Crop Protection
Trapping and Mating Disruption Systems Market
Crop Protection
Asia-Pacific Crop Protection Chemicals Market
Crop Protection
Soybean Fungicide Seed Treatment Market
Crop Protection
Europe Nematicide Market
Crop Protection
Corn Preemergence Herbicide Market
Crop Protection
Canada Nematicides Market