
 Global Acaricides Market | 2026-2036
Global Acaricides Market Size, Share, and Industry Trends Forecast 2026-2036
Global Acaricides Market Foresight
Agronomic expertise in integrated pest management is reorganizing how acaricide portfolios reach commercial growers. Syngenta AG leverages its biologicals pipeline to anchor premium positioning in resistance-prone mite segments. Bayer AG competes through digital farming platforms that pair acaricide prescriptions with real-time field monitoring. UPL Limited extends its generic manufacturing scale across Latin America and Africa, sustaining cost leadership in emulsifiable concentrate formulations.
Acaricides are biocidal compounds formulated specifically to kill or suppress mites and ticks, typically incorporating active ingredients such as abamectin, bifenazate, or etoxazole at concentrations between 1.8% and 15% by weight, delivered through foliar spray or soil drench application to protect crop yields and ornamental plant health. Pyrethroids retain dominant volume share in broad-acre field crops where cost-per-hectare drives procurement decisions, while botanical extracts represent the fastest-expanding category as organic certification requirements tighten across European retail supply chains. Liquid formulations command the largest revenue pool due to ease of tank-mixing and application precision, though wettable powders persist in developing markets where cold-chain logistics for biological actives remain underdeveloped.
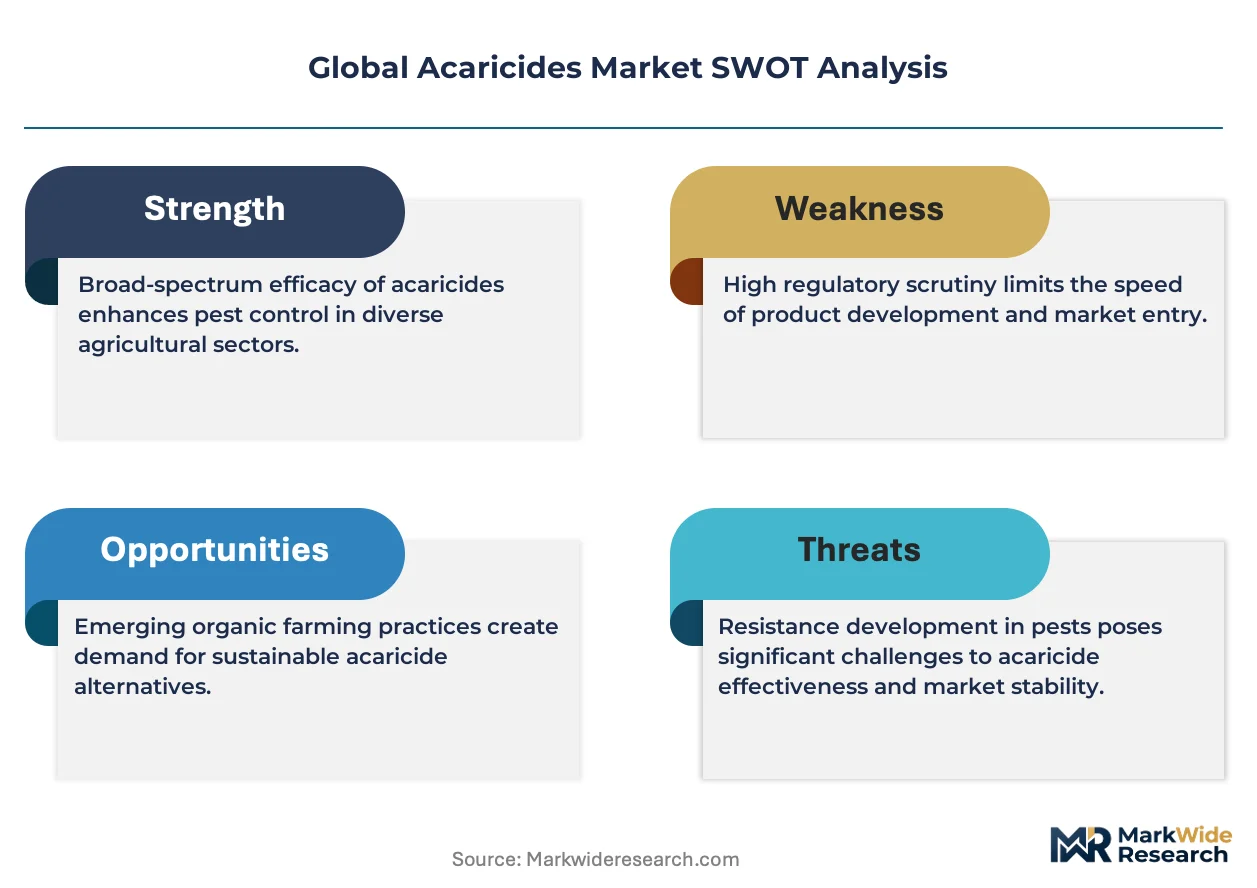
The EPA in the United States maintains residue tolerance databases that directly determine which acaricide actives qualify for export-oriented fruit and vegetable programs, while the EU Green Deal pesticide reduction mandates are forcing reformulation investments away from synthetic organophosphates. India's Central Insecticides Board registration delays for new molecular entities create bottlenecks that favor incumbent chemistries with established maximum residue limits. Stakeholders must monitor evolving pollinator risk assessments from EFSA and EPA, as these will likely restrict application windows and buffer zones before any new chemistry reaches commercial scale.
Market Dynamics
Mite resistance proliferation across Brazil's citrus belt and India's cotton corridor is forcing rapid portfolio turnover, with farmers cycling through chemistries faster than registration timelines permit.
Growth Catalysts
- EU Green Deal pesticide reduction mandates:The Farm-to-Fork strategy's 50% synthetic pesticide reduction target by 2030 is accelerating botanical extract R&D pipelines and premium positioning for bio-based formulations.
- Commercial citrus expansion in Brazil:Sao Paulo state's intensified orchard density creates recurring mite pressure cycles that demand scheduled acaricide applications across extended growing seasons.
- RNA interference delivery systems:Emerging sprayable dsRNA platforms target specific mite gene sequences without broad-spectrum ecological damage, opening resistance-free application windows.
Market Restraints
- Active ingredient cost volatility:Abamectin fermentation feedstock prices fluctuate with corn syrup and soybean meal commodity cycles, compressing margin stability for emulsifiable concentrate manufacturers.
- Registration concentration risk:India's Central Insecticides Board maintains multi-year review queues for new molecular entities, entrenching incumbent chemistries with grandfathered maximum residue limits.
- Biological storage infrastructure gaps:Cold-chain deficiencies across sub-Saharan Africa and Southeast Asia limit shelf-life viability for temperature-sensitive microbial acaricide formulations.
Strategic Opportunities
- Untapped West African cocoa belt:Ghana and Cote d'Ivoire's expanding commercial orchard sectors lack established acaricide distribution networks, presenting first-mover channel construction potential.
- Drone-based precision application:Unmanned aerial systems equipped with variable-rate nozzles enable micro-dose acaricide delivery to orchard canopies, reducing water volumes and labor costs.
- India's PLI scheme for agrochemical manufacturing:Production-linked incentives for domestic active ingredient synthesis attract contract manufacturing investments serving export markets.
Industry Challenges
- Resistance monitoring technician scarcity:Field bioassay expertise for tracking mite population susceptibility shifts remains concentrated in university extension programs, limiting grower access to real-time guidance.
- Pollinator risk assessment compliance:EFSA and EPA buffer zone calculations for bee-toxic acaricides require field-specific spray drift modeling that stretches agronomic advisory capacity.
- Tank-mix compatibility verification:Co-formulation stability testing across proliferating biological-synthetic combinations demands expanded analytical laboratory throughput.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Acaricides Market |
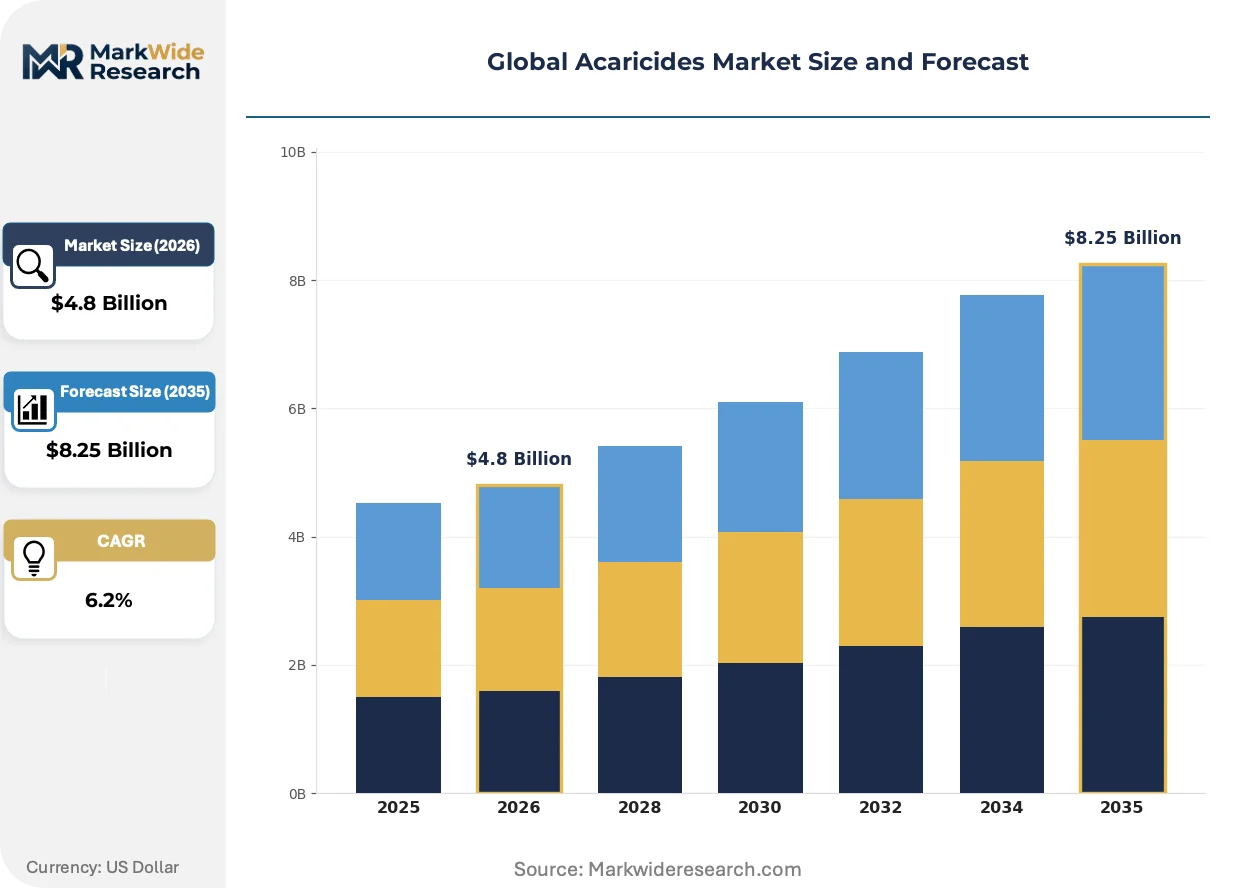
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.25 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Organophosphates, Carbamates, Pyrethroids, Botanical Extracts, Inorganic Compounds Form: Liquid, Wettable Powder, Emulsifiable Concentrate, Granules, Dust Application: Cotton, Citrus Crops, Vegetables, Ornamentals, Coffee Plants End User: Plantation Farmers, Horticulture Experts, Organic Crop Producers, Commercial Growers, Research Institutions |
| Companies Covered | BASF SE, Bayer AG, Corteva Agriscience, FMC Corporation, Nissan Chemical Industries Ltd, Syngenta AG, Sumitomo Chemical Ltd, UPL Limited, Nufarm, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Acaricides Market Shifts & Advancements
Formulation chemistry and application hardware are converging to address resistance management and residue compliance simultaneously, reshaping how acaricide value reaches commercial growers.
Microencapsulated release technology is decomposing traditional spray schedules into extended-protection windows. Brazilian citrus cooperatives now deploy abamectin-loaded polymer spheres that degrade across 21-day intervals, reducing application frequency by half. This chemistry is decomposing the cost-per-hectare procurement calculus that previously favored bulk pyrethroid purchases.
REACH authorization timelines for organophosphate actives are compressing available chemistries in European specialty crop protection. The EU Green Deal's hazard-based cut-off criteria are disqualifying several established acaricides from renewal, forcing reformulation investments toward botanical extracts and microbial fermentation products. German and Dutch glasshouse vegetable producers are responding by consolidating procurement through grower cooperatives with dedicated regulatory affairs staff.
Certification-driven procurement is fragmenting buyer segments across organic, residue-compliant, and conventional tiers. European retail chains now specify maximum residue limits below statutory tolerances, requiring dedicated supply chain segregation. This specification cascade is most visible in Spain's Almeria greenhouse cluster, where export-oriented pepper and tomato growers maintain parallel acaricide inventories for different customer channels.
Global Acaricides Market Segmentation
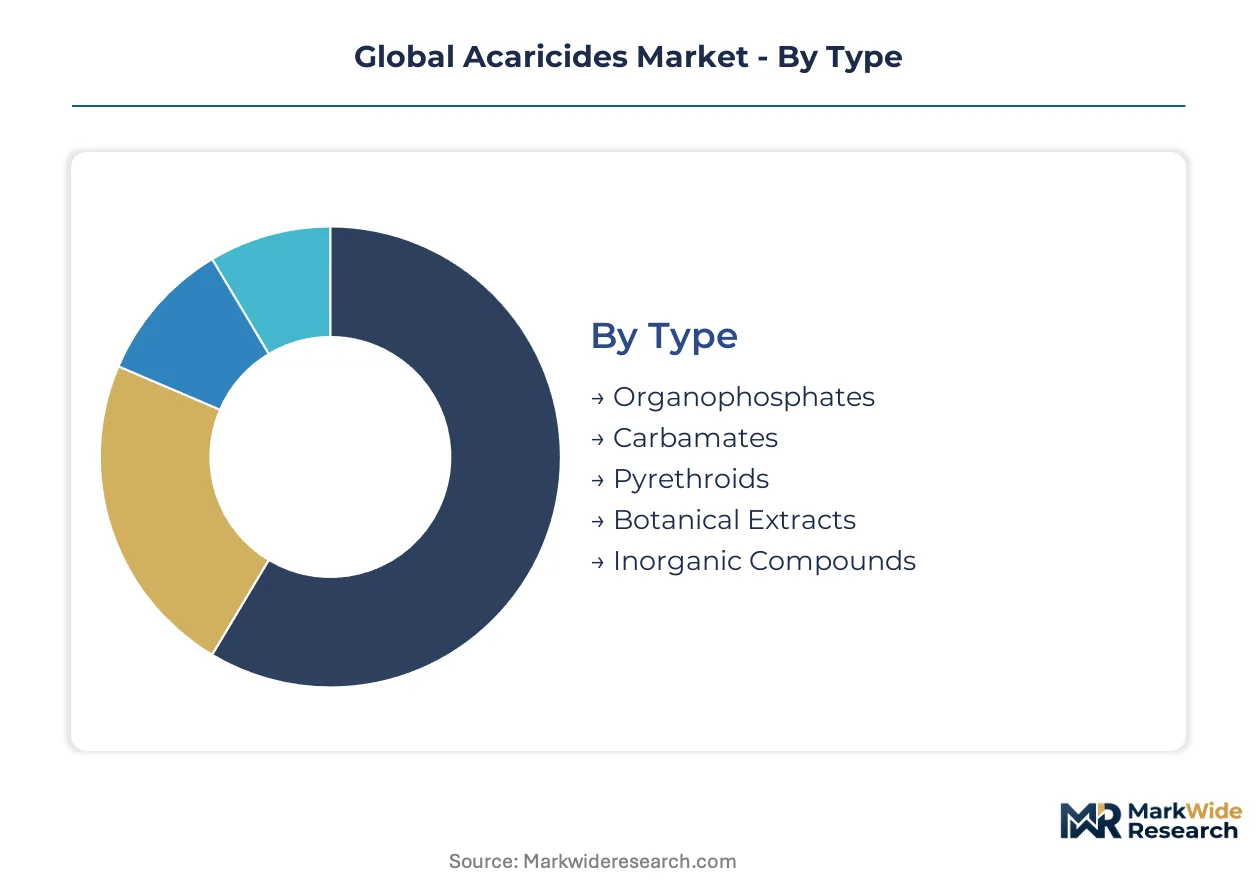
Acaricide procurement patterns diverge sharply across chemical families, formulation physics, and crop-specific residue requirements. Understanding these splits reveals where formulation R&D investments concentrate and which distribution channels capture margin.
Type:
Pyrethroids and organophosphates dominate domestic consumption in Brazil and India, while botanical extracts command premium export pricing into EU retail supply chains.
- Pyrethroids:Synthetic esters derived from chrysanthemum acid analogs deliver rapid knockdown at low application rates. Demand concentrates in Maharashtra and Gujarat cotton belts where cost-per-hectare procurement governs selection, though resistance cycling now compresses effective windows.
- Botanical Extracts:Azadirachtin and pyrethrin-based formulations carry organic certification eligibility. Spanish Almeria greenhouse exporters and German glasshouse operators absorb volume fastest as EU Green Deal hazard-based cut-off criteria disqualify synthetics from renewal.
- Organophosphates:Cholinesterase-inhibiting chemistries face REACH authorization compression across European specialty crops.
- Carbamates:N-methyl carbamate actives retain niche positioning in Latin American banana plantations with established maximum residue limits.
- Inorganic Compounds:Sulfur and lime-sulfur formulations serve organic citrus in Sao Paulo state where synthetic restrictions tighten.
Pyrethroids holds the largest share; momentum sits with botanical extracts.
Form:
Liquid formulations capture the widest geographic distribution, while wettable powders persist where cold-chain infrastructure for biological actives remains undeveloped.
- Liquid:Ready-to-use and soluble concentrate formats enable precise tank-mixing with fungicides and micronutrients. Brazilian citrus cooperatives and Indian cotton procurement officers favor these for application speed and labor reduction.
- Emulsifiable Concentrate:Oil-in-water systems suspend lipophilic actives for foliar penetration. UPL Limited and generic manufacturers across Latin America and Africa sustain cost leadership here, though abamectin feedstock volatility squeezes margins.
- Wettable Powder:Dry flowable granules reconstitute in field tanks. Sub-Saharan African distribution networks rely on these where temperature-controlled storage for microbial formulations is unavailable.
- Granules:Slow-release matrices suit soil-drench applications in orchard systems with drip irrigation.
- Dust:Powdered sulfur and inert carriers serve smallholder vegetable plots with backpack sprayer limitations.
Liquid formulations generate the highest revenue pool; wettable powders retain strongest presence in developing markets.
Application:
Citrus and cotton anchor volume demand, while ornamentals and coffee command formulation premiums tied to residue sensitivity and export certification.
- Cotton:Spider mite complexes in India's Deccan Plateau and Brazil's Cerrado drive scheduled spray programs. Resistance monitoring shortages force faster chemistry cycling than registration timelines permit.
- Citrus Crops:Sao Paulo state's intensified orchard density creates recurring pressure cycles demanding extended-protection formulations. Microencapsulated abamectin now reduces application frequency by half in cooperative-managed blocks.
- Vegetables:Greenhouse tomatoes and peppers in Almeria and Dutch glasshouse clusters require parallel inventory segregation for different retail channel specifications.
- Ornamentals:Nursery stock and cut flower producers in Colombia and Kenya face EU phytosanitary entry requirements.
- Coffee Plants:Arabica plantations in Vietnam and Indonesia confront leaf rust co-infection pressures.
Cotton absorbs the greatest acaricide tonnage; citrus shows the steepest expansion trajectory.
End User:
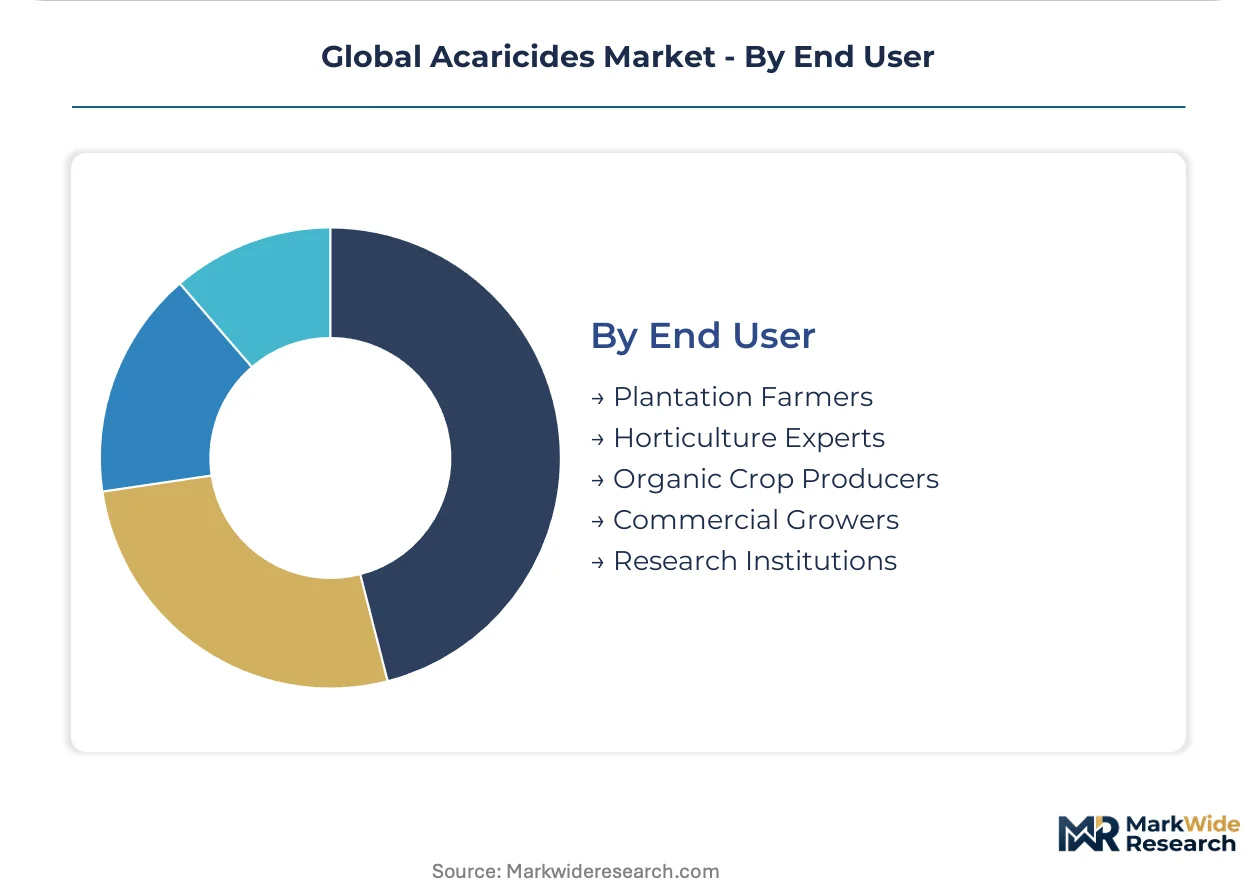
Commercial growers and plantation farmers drive synthetic chemistry volume, while organic crop producers and horticulture experts pull bio-based formulation development.
- Commercial Growers:Large-scale citrus and vegetable operations in Brazil and Spain consolidate procurement through cooperatives with dedicated regulatory affairs staff. These entities negotiate directly with Syngenta AG and Bayer AG for resistance-management program bundles.
- Plantation Farmers:Cocoa operators in Ghana and Cote d'Ivoire lack established distribution networks, presenting first-mover channel construction potential for generic manufacturers.
- Organic Crop Producers:Certification-driven procurement fragments buyer segments across residue-compliant tiers. German and Dutch producers respond to EU Green Deal mandates by consolidating through specialized buying groups.
- Horticulture Experts:Glasshouse technical managers in the Netherlands and Belgium specify maximum residue limits below statutory tolerances.
- Research Institutions:Indian agricultural universities and EFSA-funded consortia conduct pollinator risk assessments that prefigure buffer zone restrictions.
Commercial growers represent the dominant demand base; organic crop producers are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil deploys acaricides for citrus belt intensification while India targets cotton spider mites, whereas European procurement pivots toward botanical extracts under hazard-based regulatory cut-offs.
Brazil
São Paulo state's densified citrus orchards generate recurring mite pressure cycles demanding scheduled applications across extended growing seasons. ANVISA maintains residue tolerance databases that determine export qualification for fruit shipments. Microencapsulated abamectin formulations now dominate cooperative-managed blocks, halving spray frequency.
India
Maharashtra and Gujarat cotton corridors absorb the greatest acaricide tonnage as spider mite complexes force rapid chemistry cycling. The Central Insecticides Board's multi-year review queues for new molecular entities entrench incumbent chemistries with grandfathered maximum residue limits. Field bioassay expertise for resistance monitoring remains concentrated in university extension programs.
United States
California's Central Valley specialty crop producers face pollinator risk assessments that prefigure buffer zone restrictions before new chemistries reach commercial scale. EPA residue tolerance databases directly determine which actives qualify for export-oriented fruit and vegetable programs. Drone-based precision application systems equipped with variable-rate nozzles enable micro-dose delivery to orchard canopies.
Germany
Glasshouse vegetable producers in the Lower Saxony and North Rhine-Westphalia clusters consolidate procurement through grower cooperatives with dedicated regulatory affairs staff. REACH authorization timelines for organophosphate actives compress available chemistries, forcing reformulation investments toward microbial fermentation products. Certification-driven procurement fragments buyer segments across organic, residue-compliant, and conventional tiers.
Spain
Almeria's greenhouse pepper and tomato exporters maintain parallel acaricide inventories for different retail channel specifications as European retail chains mandate maximum residue limits below statutory tolerances. The EU Green Deal's Farm-to-Fork strategy accelerates botanical extract demand. Dutch technical managers specify hazard-based cut-off criteria that disqualify several established synthetics from renewal.
Global Acaricides Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with the upper tier commanding formulation R&D pipelines and the lower tier competing on generic manufacturing scale. Market structure reflects consolidation around resistance-management program bundles and digital farming platforms. Two archetypes dominate: integrated agrochemical conglomerates with biologicals pipelines, and generic manufacturers extending cost leadership across emerging markets. Competitive moves concentrate on portfolio diversification into bio-based formulations and geographic expansion through contract manufacturing investments.
Within the integrated conglomerate tier, Syngenta AG and Bayer AG exemplify divergent strategic positioning—one leveraging biologicals pipelines for premium resistance-prone segments, the other competing through digital farming platforms pairing prescriptions with real-time monitoring. UPL Limited occupies a position at the scale-driven end, extending generic manufacturing across Latin America and Africa to sustain cost leadership in emulsifiable concentrate formulations. These three anchors illustrate how formulation physics and distribution reach determine competitive boundaries.
| Leading Market Players |
|---|
| BASF SE |
| Bayer AG |
| Corteva Agriscience |
| FMC Corporation |
| Nissan Chemical Industries Ltd |
| Syngenta AG |
| Sumitomo Chemical Ltd |
| UPL Limited |
| Nufarm |
| Others |
Supply & Pricing Matrix
Long-term offtake agreements between Brazilian citrus cooperatives and fermentation-based active ingredient manufacturers lock in both abamectin supply access and price visibility across multi-season cycles, insulating buyers from corn syrup and soybean meal commodity volatility that otherwise compresses emulsifiable concentrate margins.
Pricing Analysis
Contract-based long-term offtake structures dominate procurement for commercial citrus and cotton operations, with price differentiation resting on certification grade and volume scale. Three-tier pricing structure across organic-certified botanical extracts, residue-compliant synthetics, and conventional generics separates premium positioning from economy tiers. Cost compression in pyrethroid formulations is intensifying because of resistance-driven chemistry cycling and shorter effective windows. Smallholder cotton growers in India's Deccan Plateau exhibit highest price sensitivity, while EU greenhouse exporters absorb premium botanical pricing for retail channel compliance.
Supply Chain Analysis
China and India anchor active ingredient synthesis for pyrethroid and organophosphate chemistries, while Germany and Switzerland concentrate formulation R&D and microbial fermentation capacity. The supply chain draws from corn syrup and soybean meal feedstocks for abamectin fermentation, petroleum-derived intermediates for synthetic esters, and neem biomass for azadirachtin extraction. Single-source vulnerability concentrates in India's Central Insecticides Board registration bottlenecks, which entrench incumbent chemistries. Distribution runs through grower cooperatives with dedicated regulatory affairs staff in Brazil and Spain, and through generic manufacturer networks across sub-Saharan Africa.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Field bioassay expertise for mite resistance monitoring remains concentrated in university extension programs, creating a persistent capability gap that limits grower access to real-time susceptibility guidance and stretches agronomic advisory capacity.
For Market Incumbents: Shield premium positioning in resistance-prone segments by accelerating botanical extract R&D pipelines ahead of EU Green Deal hazard-based cut-off deadlines. Deepen backward integration into microbial fermentation capacity to capture margin from temperature-sensitive biological formulations. Lock in grower cooperative relationships through bundled resistance-management programs that embed digital monitoring platforms. For New Entrants and Emerging Players: Cold-chain logistics for biological actives in sub-Saharan Africa represents the most penetrable service-layer gap, where incumbent distribution networks under-serve temperature-sensitive microbial formulations. Target Ghana and Cote d'Ivoire's expanding cocoa belt with generic emulsifiable concentrate offerings and first-mover channel construction. Lead with drone-based precision application partnerships to differentiate from established spray-service providers. For Investors and Strategic Acquirers: Regional formulation specialists with captive regulatory affairs capabilities and established maximum residue limit databases represent the priority acquisition archetype. Long-term viability hinges on portfolio exposure to bio-based actives outpacing synthetic chemistry compression over the next decade. Monitor EFSA pollinator risk assessment publications as the inflection signal for buffer zone restrictions that will reshape application economics.| Strategic Initiative | Industry Significance |
|---|---|
| Botanical Extract R&D Pipeline Expansion | EU Green Deal hazard-based cut-off criteria disqualify synthetics from renewal, accelerating demand for azadirachtin and pyrethrin formulations. |
| Microencapsulated Release Technology Deployment | Brazilian citrus cooperatives halve spray frequency through polymer sphere formulations, decomposing cost-per-hectare procurement calculus. |
| Drone-Based Precision Application Partnership | Unmanned aerial systems with variable-rate nozzles enable micro-dose delivery to orchard canopies, reducing water volumes and labor costs. |
| Backward Integration into Fermentation Capacity | Captive abamectin production insulates margin from corn syrup and soybean meal commodity cycles compressing generic manufacturers. |
| Grower Cooperative Regulatory Affairs Embedding | Dedicated compliance staff within Brazilian and Spanish procurement consortia secure export qualification through ANVISA and EU tolerance database navigation. |
Research Methodology
Cross-validation between primary interviews with crop protection R&D directors, regulatory affairs leads at agrochemical registrants, Brazilian citrus cooperative procurement officers, and Indian cotton extension specialists anchors the qualitative findings. Secondary validation draws from EPA residue tolerance databases, EFSA pollinator risk assessments, ANVISA registration filings, and Central Insecticides Board approval queues. Bottom-up volume estimates from crop-specific application rates triangulate against top-down market sizing from active ingredient trade flows.
Sensitivity analysis around EU Green Deal implementation timelines, mite resistance proliferation rates, and abamectin feedstock commodity cycles stress-tests projection robustness across the analysis window. Segmentation dimensions span chemical family, formulation physics, crop application, and end-user procurement archetype. CAGRs derive from regression against historical resistance-driven chemistry cycling patterns and registration pipeline velocity.
Underlying assumptions cover sustained EU Farm-to-Fork pesticide reduction enforcement, with deviation risk concentrated in India's registration timeline acceleration and pollinator buffer zone restriction timing. Recalibration cycles align with material shifts in EFSA hazard-based cut-off criteria publications and ANVISA tolerance database revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Crop Protection
Poland Crop Protection Chemicals Market
Crop Protection
Global Crop Growth Regulators Market
Crop Protection
Hungary Crop Protection Chemicals Market
Crop Protection
Global Acephate Market
Crop Protection
Europe Agricultural Pheromones Market
Crop Protection
Europe Fungicide Market
Crop Protection
Canada Crop Protection Chemicals Market
Crop Protection
North America Molluscicides Market
Crop Protection
Crop Protection Chemicals Market
Crop Protection
Glufosinate Ammonium Market
Crop Protection
Nematicides Market
Crop Protection
United States Crop Protection Chemicals Market
Crop Protection
Global Chlorpyrifos Market
Crop Protection
North America Crop Protection Chemicals Market
Crop Protection
Europe Seed Treatment Market
Crop Protection
Global SDHI Fungicide Market