
 Australia Crop Protection Chemicals (Pesticides) Market | 2026-2036
Australia Crop Protection Chemicals (Pesticides) Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Crop Protection Chemicals (Pesticides) Market Outlook
Domestic formulator investment in Western Australian manufacturing corridors is realigning supply chains toward regional blending capacity. Nufarm Limited leverages its Geraldton formulation plant to anchor herbicide supply for wheatbelt cooperatives. BASF Australia Ltd sustains R&D intensity in fungicide chemistry targeting barley net blotch complexes. Bayer CropScience Pty Ltd competes through seed treatment bundling with canola trait platforms.
Crop protection chemicals encompass synthetic and biological agents formulated to suppress agricultural pests, weeds, and pathogens through neurotoxic, metabolic, or growth-disruptive modes of action, typically applied at rates measured in grams of active ingredient per hectare. These compounds serve to safeguard yield potential and grain quality across Australia's export-oriented farming systems. Herbicides command the largest product type position due to zero-tillage adoption across the wheat-sheep zone, while fungicides represent the fastest-expanding category as wetter sowing windows elevate Septoria and rust pressure in cereals. Seed treatment formulations are capturing margin pools as farmers seek insurance against soil-borne establishment risks in variable seasons.
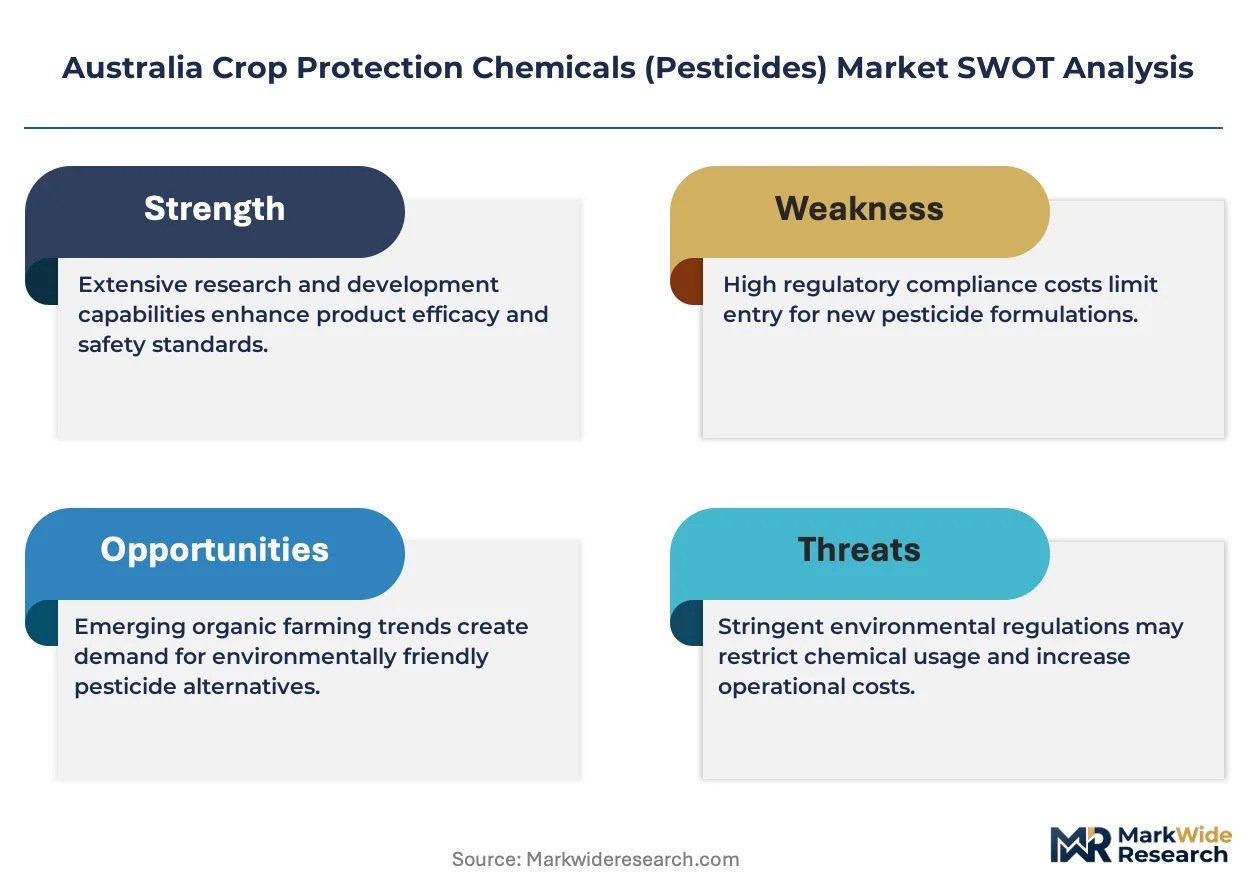
The Australian Pesticides and Veterinary Medicines Authority (APVMA) governs active ingredient registration and residue limits, with its 2022 legislative reforms extending data protection periods and tightening environmental hazard thresholds. Food Standards Australia New Zealand (FSANZ) enforces maximum residue limits that shape export market access for meat and grain shipments. Stakeholders must monitor APVMA review timelines for older chemistries and align product pipelines with the trajectory of biological alternatives gaining regulatory preference.
Market Dynamics
Glyphosate resistance across the wheatbelt is forcing broadacre grain growers into multi-mode herbicide rotations, compressing product lifecycles and accelerating formulator R&D pipelines toward novel modes of action.
Growth Catalysts
- Zero-tillage expansion:Conservation farming adoption across the wheat-sheep zone sustains pre-emergent herbicide volumes as farmers minimize soil disturbance.
- APVMA re-registration reforms:Tighter environmental hazard thresholds accelerate industry consolidation toward lower-risk chemistry portfolios.
- Murray-Darling Basin intensification:Irrigated horticulture and row-cropping sustain year-round application demand independent of seasonal grain cycles.
Market Restraints
- Active ingredient supply concentration:China dominates technical-grade manufacturing, exposing Australian formulators to freight cost volatility and currency fluctuation.
- APVMA timeline extension:Extended data protection periods and review backlogs delay new product market entry by 18-36 months.
- Biological substitution threat:Microbial inoculants and RNA interference technologies capture specialty crop segments previously served by synthetic chemistry.
Strategic Opportunities
- Western Australian manufacturing corridors:Domestic blending capacity expansion reduces import dependency for wheatbelt cooperatives.
- Seed treatment bundling:Trait-platform integration creates premium pricing pools as farmers seek establishment risk insurance.
- Biological alternatives preference:APVMA regulatory trajectory favors lower-toxicity registrations, opening pipeline slots for biopesticide entrants.
Industry Challenges
- Resistance management expertise gap:Agronomist workforce shortages limit grower access to rotation planning advice across remote wheatbelt regions.
- Residue compliance complexity:FSANZ maximum residue limit alignment with export destination markets requires continuous analytical certification investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Crop Protection Chemicals (Pesticides) Market |
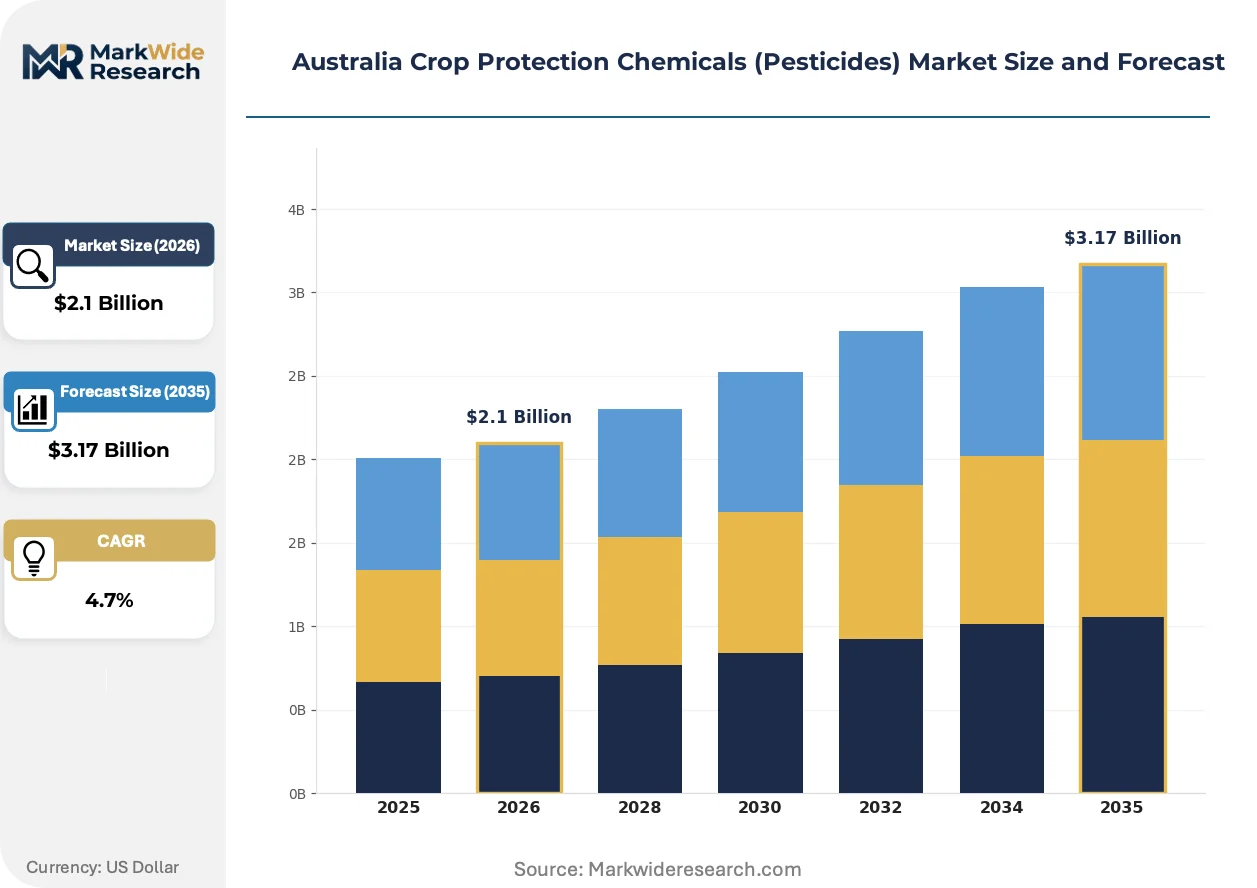
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.17 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Herbicides, Insecticides, Fungicides, Rodenticides Formulation: Liquid, Granular, Powder, Emulsifiable Concentrate Application Method: Foliar, Soil Treatment, Seed Treatment, Aerial Spraying Crop Type: Cereals, Fruits, Vegetables, Oilseeds |
| Companies Covered | Syngenta Australia Pty Ltd, Bayer CropScience Pty Ltd, BASF Australia Ltd, Corteva Agriscience (Australia), Nufarm Limited, FMC Australasia Pty Ltd, Adama Australia Pty Ltd, Sumitomo Chemical Australia Pty Ltd, UPL Australia Pty Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Crop Protection Chemicals (Pesticides) Market Strategic Shifts
Formulation chemistry and application technology are converging to address resistance pressure while meeting tightening environmental thresholds set by national regulators.
RNA interference (RNAi) biopesticides are consolidating research investment across public-private partnerships. CSIRO and agricultural biotechnology firms co-develop double-stranded RNA formulations targeting specific pest genomes without broad-spectrum toxicity. Cotton and horticulture sectors trial these products under permit, compressing the addressable market for conventional neurotoxic insecticides.
APVMA legislative reforms enacted in 2022 extend proprietary data protection periods while elevating ecotoxicological assessment standards. Formulators now face higher registration costs for novel active ingredients, pushing mid-tier players toward off-patent molecule repositioning. Older chemistries undergoing scheduled review face accelerated phase-out timelines, forcing portfolio restructuring.
Farmer buying collectives are displacing traditional retail agronomy channels in grain-growing regions. Wheatbelt cooperatives aggregate procurement volumes to negotiate direct supply contracts with formulators, compressing distributor margins. This concentration is most pronounced in South Australia and Western Australia where grower groups control substantial hectarage blocks.
Australia Crop Protection Chemicals (Pesticides) Market Segmentation
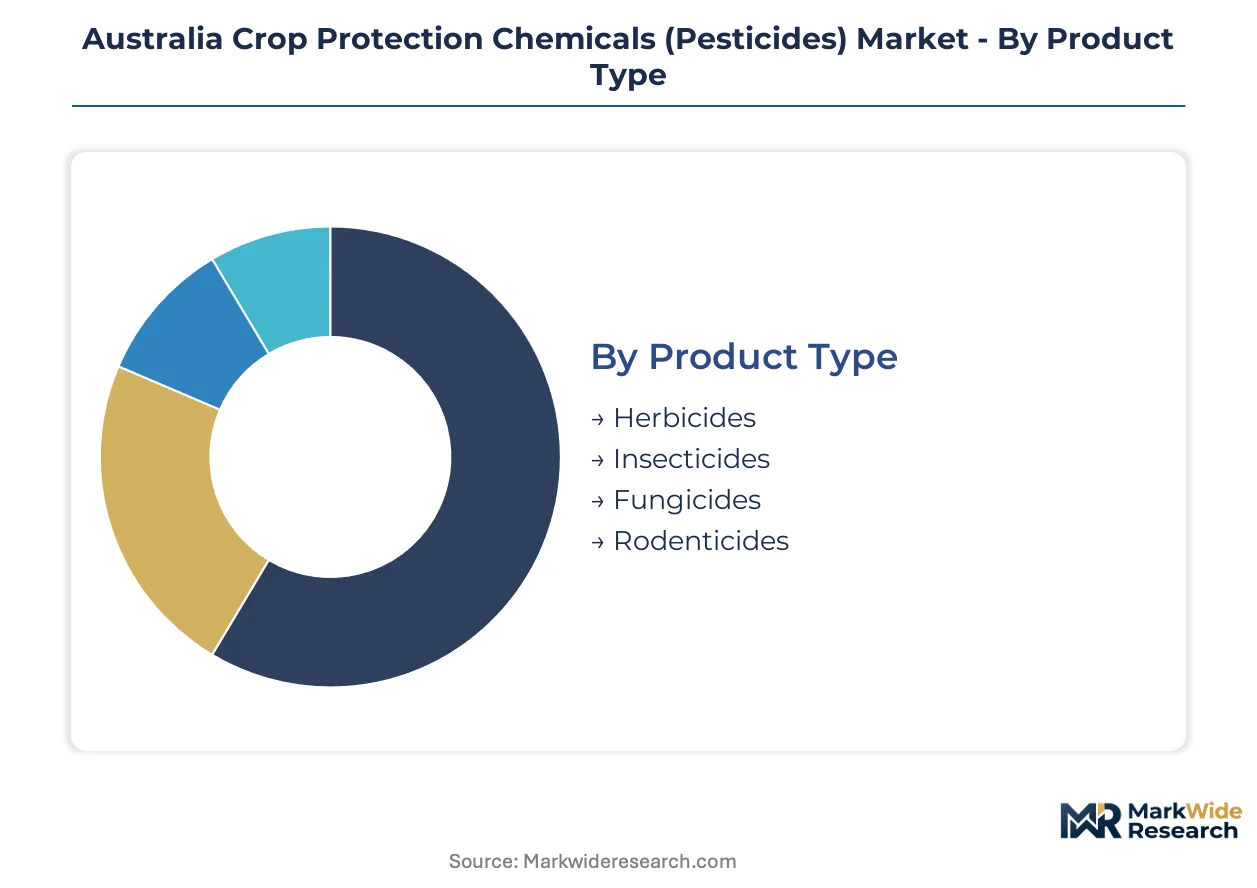
Segmentation in the Australian crop protection market reveals how application constraints, crop economics, and regulatory pressure fragment demand across distinct product configurations. Each dimension carries implications for formulation investment, distribution logistics, and grower advisory services.
Product Type:
Buyers differentiate primarily by the pest complex threatening their rotation, which dictates chemistry selection and resistance management protocols.
- Herbicides:These formulations suppress weed competition through metabolic disruption or growth regulation, with pre-emergent and post-emergent variants tailored to zero-tillage systems. Demand concentrates in the Western Australian wheatbelt, where glyphosate resistance has forced growers into multi-mode rotations combining trifluralin, clethodim, and paraquat alternatives.
- Fungicides:Systemic and contact actives protect yield potential against Septoria, net blotch, and rust pathogens in cereals. Victoria's high-rainfall cropping zones drive the steepest expansion trajectory as wetter sowing windows extend disease pressure windows.
- Insecticides:Neurotoxic and growth-regulating compounds target aphid, mite, and caterpillar infestations in broadacre and horticultural systems. Cotton growers in Queensland's Darling Downs represent the most intensive user cohort.
- Rodenticides:Anticoagulant and acute toxic baits protect stored grain and establishment-phase crops from mouse and rat damage. South Australia's Mallee region sees concentrated application during plague cycles.
Volume sits with herbicides; growth tilts toward fungicides.
Formulation:
Application equipment compatibility and environmental fate characteristics determine formulation preference across Australia's varied farming scales.
- Liquid:Suspension concentrates and soluble liquids enable precise dose calibration through modern sprayer systems. Large-scale broadacre operators in New South Wales favor liquid herbicides for compatibility with GPS-guided application rigs.
- Emulsifiable Concentrate:Oil-based carriers enhance cuticular penetration for systemic uptake in waxy-leaf crops. Horticultural producers in the Murray-Darling Basin specify EC formulations for stone fruit and citrus protection.
- Granular:Controlled-release matrices reduce operator exposure and environmental drift in high-wind conditions. Western Australian lupin growers deploy granular insecticides at sowing for early-season establishment insurance.
- Powder:Wettable powders and water-dispersible granules suit backpack and handheld equipment in smallholder vegetable operations. Queensland's Lockyer Valley salad green producers maintain powder stocks for targeted spot treatments.
Scale advantages accrue to liquid formulations; specialty crop margins sustain powder demand.
Application Method:
Equipment capital intensity and labor availability shape how growers deploy chemistry across Australia's vast and unevenly populated agricultural zones.
- Foliar:Broadcast or directed spraying delivers contact or systemic actives to plant surfaces for immediate pest suppression. South Australian broadacre cooperatives operate self-propelled sprayer fleets covering 15,000+ hectares per machine annually.
- Seed Treatment:Film coatings and pelleting technologies embed fungicides and insecticides directly on germplasm. Canola growers across the Eyre Peninsula pay premiums for bundled trait-plus-treatment packages against blackleg and aphid establishment risks.
- Soil Treatment:Incorporation or injection places chemistry in the root zone for nematode, fungal, and early-season insect control. Tasmanian potato producers apply soil fumigants pre-planting to manage powdery scab and wireworm complexes.
- Aerial Spraying:Fixed-wing and rotary aircraft access waterlogged or remote terrain beyond ground rig reach. Queensland sugarcane operations contract aerial applicators for ratoon crop protection across the Burdekin and Wet Tropics districts.
Ground-based foliar dominates hectarage; seed treatment commands the fastest margin expansion.
Crop Type:
Export market orientation and residue compliance stringency create divergent chemistry requirements across Australia's major production systems.
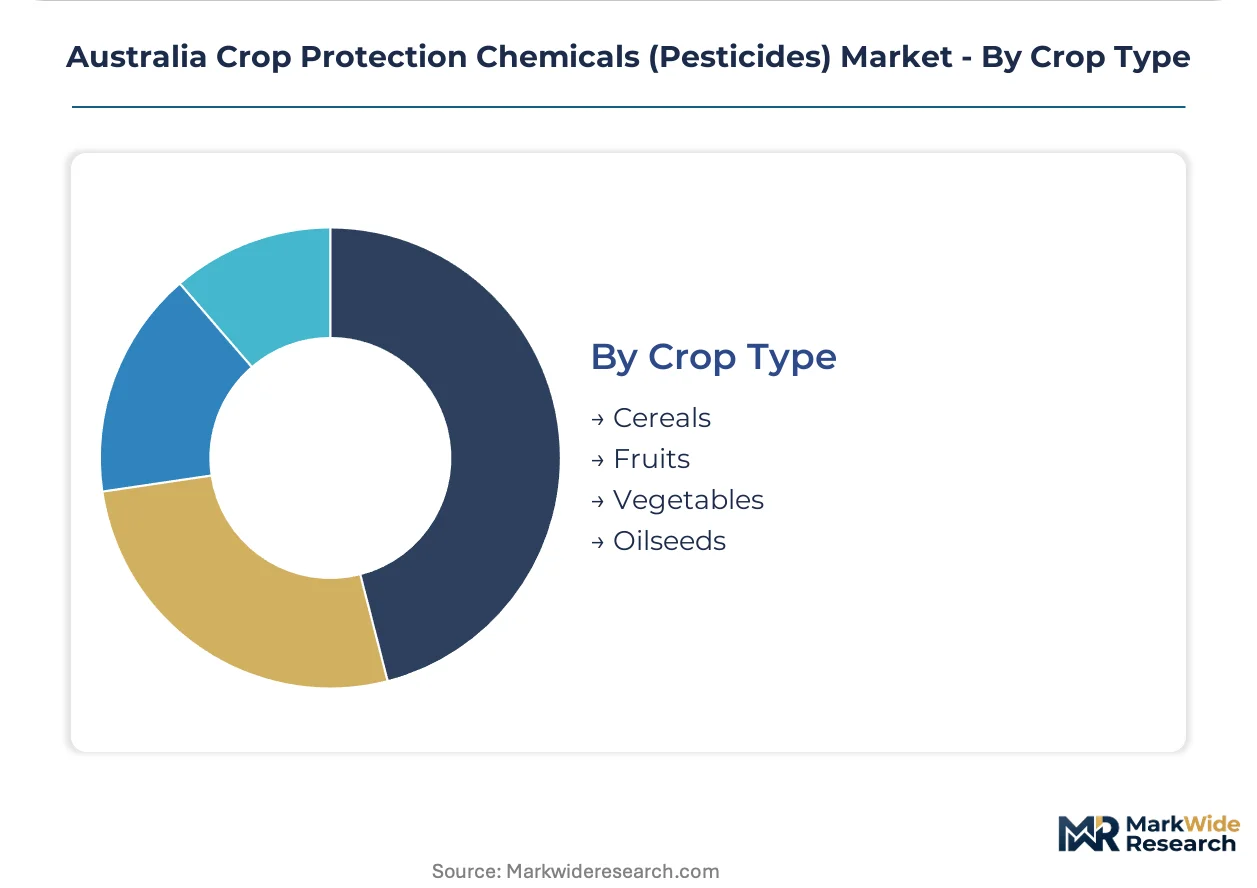
- Cereals:Wheat, barley, and oat protection programs emphasize herbicide rotations and foliar fungicide timing for grain quality preservation. The Western Australian wheat-sheep zone accounts for the largest absolute chemical volume.
- Oilseeds:Canola and sunflower production demands integrated weed management and sclerotinia control aligned with food-grade and industrial oil specifications. Victorian Wimmera growers prioritize blackleg-resistant varieties with reduced fungicide dependency.
- Fruits:Pome, stone, and citrus operations face maximum residue limit scrutiny from Asian export markets, favoring softer chemistry and biological alternatives. Riverina and Goulburn Valley packers maintain FSANZ-compliant spray diaries for traceability.
- Vegetables:Leafy greens, brassicas, and alliums require rapid pre-harvest interval management and resistance-aware insecticide rotation. Queensland's Bundaberg tomato and capsicum producers coordinate area-wide resistance monitoring programs.
Cereals anchor tonnage; horticultural segments drive premium formulation development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Western Australia's wheat-sheep zone anchors national herbicide consumption through zero-tillage grain systems. The Murray-Darling Basin sustains year-round chemical demand through irrigated horticulture and intensive row-cropping corridors.
New South Wales
The Liverpool Plains and Riverina irrigation districts drive fungicide and herbicide procurement for wheat, cotton, and rice rotations. The state's Environmental Protection Authority enforces spray drift buffer zones under the Pesticides Act 1999, tightening application protocols near waterways. Sydney-based formulator headquarters coordinate distribution networks reaching Griffith and Moree cooperatives.
Victoria
The Wimmera and Mallee regions generate concentrated demand for cereal fungicides as wetter sowing windows extend disease pressure. Agriculture Victoria administers the ChemClear program for obsolete chemical collection, shaping farm-level inventory management. Melbourne's port infrastructure handles bulk technical-grade imports for Geelong formulation plants.
Queensland
The Darling Downs cotton belt and Burdekin sugarcane districts sustain insecticide and herbicide volumes through summer-dominant cropping. Biosecurity Queensland regulates aerial application permits under the Biosecurity Act 2014, governing spray contractor operations. Brisbane logistics hubs channel products north to Mackay and Townsville supply depots.
Western Australia
The wheatbelt corridor from Geraldton to Esperance consumes pre-emergent herbicides for dryland cereal production. The Department of Primary Industries and Regional Development monitors glyphosate resistance through the Australian Herbicide Resistance Initiative. Geraldton hosts Nufarm's regional formulation facility supplying wheatbelt cooperatives directly.
South Australia
The Mallee and Eyre Peninsula concentrate rodenticide demand during mouse plague cycles and canola seed treatment procurement. Primary Industries and Regions SA enforces mandatory spray record-keeping under the Agricultural and Veterinary Chemicals Act 1994. Adelaide-based analytical laboratories certify residue compliance for export grain shipments.
Australia Crop Protection Chemicals (Pesticides) Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue biological alternatives and precision application services. The market consolidates around multinational agricultural chemistry portfolios with Australian formulation and distribution subsidiaries. Three archetypes dominate: integrated global suppliers with captive active ingredient pipelines, regional formulators with wheatbelt cooperative relationships, and specialist biological entrants exploiting APVMA regulatory preference for lower-toxicity registrations. Competitive intensity centers on seed treatment bundling and resistance management advisory services rather than price alone.
Among integrated global suppliers, Syngenta Australia Pty Ltd, Bayer CropScience Pty Ltd, and BASF Australia Ltd exemplify the archetype of multinational agricultural chemistry houses operating through Australian subsidiaries. These entities anchor the premium formulation tier through established registration portfolios and technical advisory networks. Their positioning reflects the structural advantage of global R&D pipelines feeding into APVMA registration processes.
| Leading Market Players |
|---|
| Syngenta Australia Pty Ltd |
| Bayer CropScience Pty Ltd |
| BASF Australia Ltd |
| Corteva Agriscience (Australia) |
| Nufarm Limited |
| FMC Australasia Pty Ltd |
| Adama Australia Pty Ltd |
| Sumitomo Chemical Australia Pty Ltd |
| UPL Australia Pty Ltd |
| Others |
Value Chain & Pricing Dynamics
Wheatbelt cooperative procurement concentration drives contract-based long-term offtake pricing for herbicide volumes, with advisory service bundling separating premium formulator relationships from transactional spot purchases. The APVMA registration timeline extension compresses margin pools for novel active ingredients, pushing price differentiation toward resistance management expertise rather than molecule novelty alone.
Pricing Analysis
Warranty and resistance-management advisory bundling distinguishes premium formulator contracts from unbundled commodity chemistry transactions. Three-tier pricing structure across premium, standard, and economy levels segments the market: premium tiers incorporate agronomist rotation planning and residue compliance certification, standard tiers cover proven off-patent molecules with basic label support, and economy tiers supply generic active ingredients through cooperative direct sourcing. Price differentiation hinges on APVMA registration exclusivity and geographic delivery cost to remote wheatbelt depots. Cost compression in the standard tier is intensifying because Chinese technical-grade import volatility exposes formulators to currency fluctuation. Cooperative buyers exhibit highest price sensitivity for commodity herbicides, while horticultural exporters in the Murray-Darling Basin prioritize residue compliance over unit cost.
Supply Chain Analysis
Direct-to-cooperative channels handle wheatbelt bulk procurement, bypassing traditional distributor networks that once aggregated grower demand. Geographic supply concentration centers on China for technical-grade active ingredients, India for intermediate chemical synthesis, and Australia for regional formulation and blending. Raw material dependencies include glyphosate technical acid, fungicide azole intermediates, and neonicotinoid insecticide precursors. Single-source vulnerability from Chinese manufacturing concentration exposes Australian formulators to freight cost spikes and geopolitical trade friction. Distribution runs through Geraldton and Geelong formulation plants supplying wheatbelt cooperatives directly, with Melbourne and Brisbane logistics hubs handling import consolidation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Australia crop protection market is becoming a vertical-integration race, with formulators pursuing backward integration into regional blending capacity to secure supply chain autonomy against import volatility.
For Market Incumbents: Deepen captive supply relationships with Western Australian wheatbelt cooperatives through Geraldton corridor capacity expansion, insulating against Chinese technical-grade concentration risk. Prioritize APVMA registration pipeline investment in RNA interference biopesticides before regulatory preference for lower-toxicity chemistry hardens into mandatory substitution timelines. Consolidate resistance management advisory services as a margin pool defense against biological substitute technologies capturing specialty crop segments. For New Entrants and Emerging Players: Capture the biological alternatives registration pipeline slot opened by APVMA legislative reforms, exploiting accelerated review timelines for microbial inoculants and biofungicides relative to synthetic chemistry. Target Victorian high-rainfall cereal zones where wetter sowing windows extend disease pressure and growers seek sclerotinia control alternatives with reduced residue risk. Pursue seed treatment bundling partnerships with canola trait platforms as the primary go-to-market angle, leveraging establishment risk insurance demand. For Investors and Strategic Acquirers: The window for entry favors regional formulators with wheatbelt cooperative relationships and captive blending infrastructure. Long-term viability hinges on APVMA registration portfolio depth rather than molecule pipeline novelty, as data protection period extensions entrench incumbent positions. Monitor biological substitution penetration rates in horticultural export segments as the inflection indicator for synthetic chemistry demand erosion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Regional Blending | Geraldton corridor capacity reduces import dependency for wheatbelt cooperatives against Chinese supply volatility. |
| Biological Alternative Registration Pipeline | APVMA regulatory preference accelerates review timelines for microbial inoculants capturing specialty crop segments. |
| Seed Treatment Bundling Partnership | Trait-platform integration creates premium pricing pools for canola establishment risk insurance across Eyre Peninsula. |
| Resistance Management Advisory Services | Agronomist expertise differentiation defends margin pools against biological substitutes and generic competition. |
| Long-term Cooperative Supply Agreements | Direct procurement contracts with South Australian and Western Australian grower groups compress distributor intermediation. |
Study Parameters
Multi-period observation of APVMA registration timelines, glyphosate resistance frequency indices, and wheatbelt cooperative procurement volumes anchored the trend analysis, supplemented by interviews with formulator technical directors, wheatbelt cooperative procurement managers, APVMA regulatory affairs specialists, and horticultural export compliance officers. Secondary validation drew from APVMA public registration databases, Australian Bureau of Agricultural and Resource Economics trade statistics, Food Standards Australia New Zealand residue limit gazettes, and CSIRO crop protection research publications. Bottom-up triangulation across product-type demand curves and top-down reconciliation against national agricultural chemical import values ensured forecast consistency.
Segment-weighting across product type, formulation, application method, and crop type dimensions calibrated value distribution within the analytical framework. CAGRs were derived through exponential smoothing of historical volume trends adjusted for regulatory phase-out schedules and biological substitution elasticities. Modeled inputs included APVMA review pipeline backlogs, glyphosate resistance allele frequency trajectories, and Murray-Darling Basin irrigation allocation forecasts. The projection horizon spans the analysis window with annual granularity for near-term resistance management transitions and biennial steps for long-term chemistry substitution scenarios.
The model holds under stable APVMA regulatory trajectory and continued Chinese technical-grade supply access; deviation in bilateral trade friction intensity or accelerated biological efficacy validation would shift volume projections. Forecasts reflect documented assumptions regarding resistance evolution rates and cooperative procurement consolidation pace. Periodic stress-testing of base assumptions against APVMA legislative amendment proposals and CSIRO biopesticide trial outcomes is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Crop Protection
IPM Pheromones Market
Crop Protection
Vietnam Insecticide Market
Crop Protection
North America Crop Protection Chemicals Market
Crop Protection
India Herbicide Market
Crop Protection
Middle East and Africa Turf and Ornamental Grass Protection Market
Crop Protection
Seed Treatment Materials Market
Crop Protection
Europe Molluscicides Market
Crop Protection
Tebuconazole Epoxide Market
Crop Protection
Global Seed Treatment Chemicals Market
Crop Protection
India Crop Protection Chemicals Market
Crop Protection
Miticides Market
Crop Protection
South America Nematicides Market
Crop Protection
Global Seed Treatment Fungicides Market
Crop Protection
Europe Nematicide Market
Crop Protection
Global Integrated Pest Management (IPM) Pheromones Market
Crop Protection
South America Fungicide Market