
 Iprodione Market | 2026-2036
Iprodione Market Size, Share, and Industry Trends Forecast 2026-2036
Iprodione Market Outlook
China is narrowing its technical-grade production gap for dicarboximide fungicides through state-backed agrochemical park expansions in Jiangsu and Shandong provinces. Bayer CropScience leverages its integrated active ingredient synthesis network across European and Asian manufacturing sites. Syngenta sustains broad label registrations across high-value vegetable segments, while BASF competes through specialized seed-treatment compatibility programs.
Iprodione is a contact fungicide from the dicarboximide class, formulated as wettable powders, liquid suspensions, or soluble concentrates for foliar application against Botrytis cinerea and Sclerotinia sclerotiorum in protected and field crops. The compound inhibits septum formation in fungal hyphae through interference with tubulin assembly, delivering protective and early curative activity at application rates typically ranging from 500 to 1000 grams active ingredient per hectare. Wettable powder formulations dominate procurement among agricultural producers due to lower unit costs and established tank-mix compatibility, while liquid concentrates capture preference among horticulturists seeking precision dosing in greenhouse operations. Field crops represent the most mature application segment with slowing label expansion, whereas ornamentals generate concentrated margin pools through specialized distributor networks serving landscape professionals.
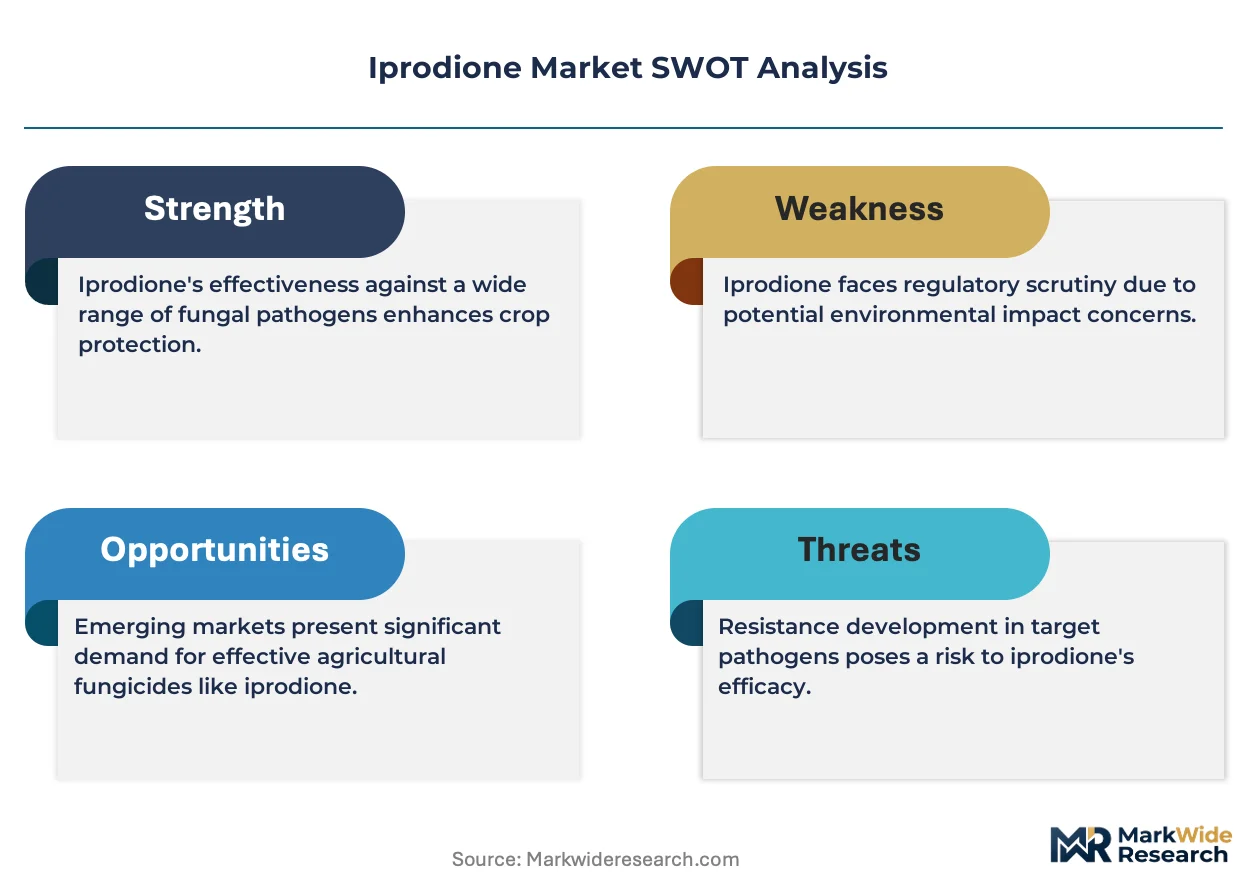
EPA residue tolerance assessments and REACH authorization requirements in Europe constrain formulation chemistry options and re-entry interval labeling, directly shaping product development priorities and geographic registration strategies. China's NMPA and MEE enforce increasingly stringent environmental release standards for fungicide manufacturing facilities, raising compliance capital requirements for domestic and imported active ingredient suppliers. Stakeholders must monitor evolving maximum residue limit harmonization between import markets and production-origin jurisdictions to anticipate registration renewal risks and reposition supply commitments accordingly.
Market Dynamics
China's tightening GB standards on pesticide residues are compressing formulation windows for dicarboximide fungicides, forcing suppliers to accelerate residue metabolism studies and reposition wettable powder grades toward lower-dose liquid concentrate alternatives.
Growth Catalysts
- Vegetable Protected Cultivation Expansion:China's greenhouse acreage for high-value solanaceous crops is expanding, creating sustained demand for Botrytis-specific chemistries with established MRL compliance pathways.
- REACH Authorization Pathways:ECHA's streamlined renewal procedures for existing active ingredients are enabling label retention across European horticultural markets, preserving revenue bases for compliant suppliers.
- Micro-encapsulation Advances:Controlled-release formulation technologies are extending spray intervals and reducing application frequency in labor-constrained Japanese protected vegetable operations.
Market Restraints
- Active Ingredient Cost Volatility:Chlorination reagent and glycine derivative feedstock prices fluctuate with Chinese petrochemical capacity utilization, compressing margin predictability for wettable powder manufacturers.
- Regulatory Substitution Pressure:EFSA's ongoing cumulative risk assessments for dicarboximide fungicides are elevating registration maintenance costs and accelerating grower migration to SDHI alternatives in French and Italian viticulture.
- Technical Limitation in Systemic Efficacy:Iprodione's purely contact mode of action restricts curative windows compared to translaminar competitors, limiting penetration in markets favoring single-spray disease management protocols.
Strategic Opportunities
- Seed Treatment Compatibility Programs:Formulation innovations enabling tank-mix stability with neonicotinoid and biological seed treatments are opening access to Brazilian soybean and Indian groundnut pre-sowing markets.
- Ornamental Distributor Network Consolidation:Specialized procurement cooperatives serving Dutch and Colombian floriculture clusters present concentrated volume contracts with premium pricing tolerance for residue-certified supplies.
- China's Dual Carbon Manufacturing Incentives:MEE credit systems for waste-heat recovery and solvent recycling in agrochemical synthesis are lowering effective compliance costs for Jiangsu-based technical-grade producers.
Industry Challenges
- Residue Analytical Talent Scarcity:LC-MS/MS method development for complex matrix quantification requires specialized chromatography expertise that outpaces training pipeline output in emerging manufacturing jurisdictions.
- Label Harmonization Complexity:Divergent re-entry interval calculations between EPA worker exposure models and EU AOEL derivations force dual-label maintenance for suppliers serving transatlantic vegetable export chains.
- Legacy Formulation Integration:Wettable powder production lines require capital-intensive dust-control retrofitting to meet OSHA and MEE particulate emission standards, stranding mid-tier manufacturing assets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Iprodione Market |
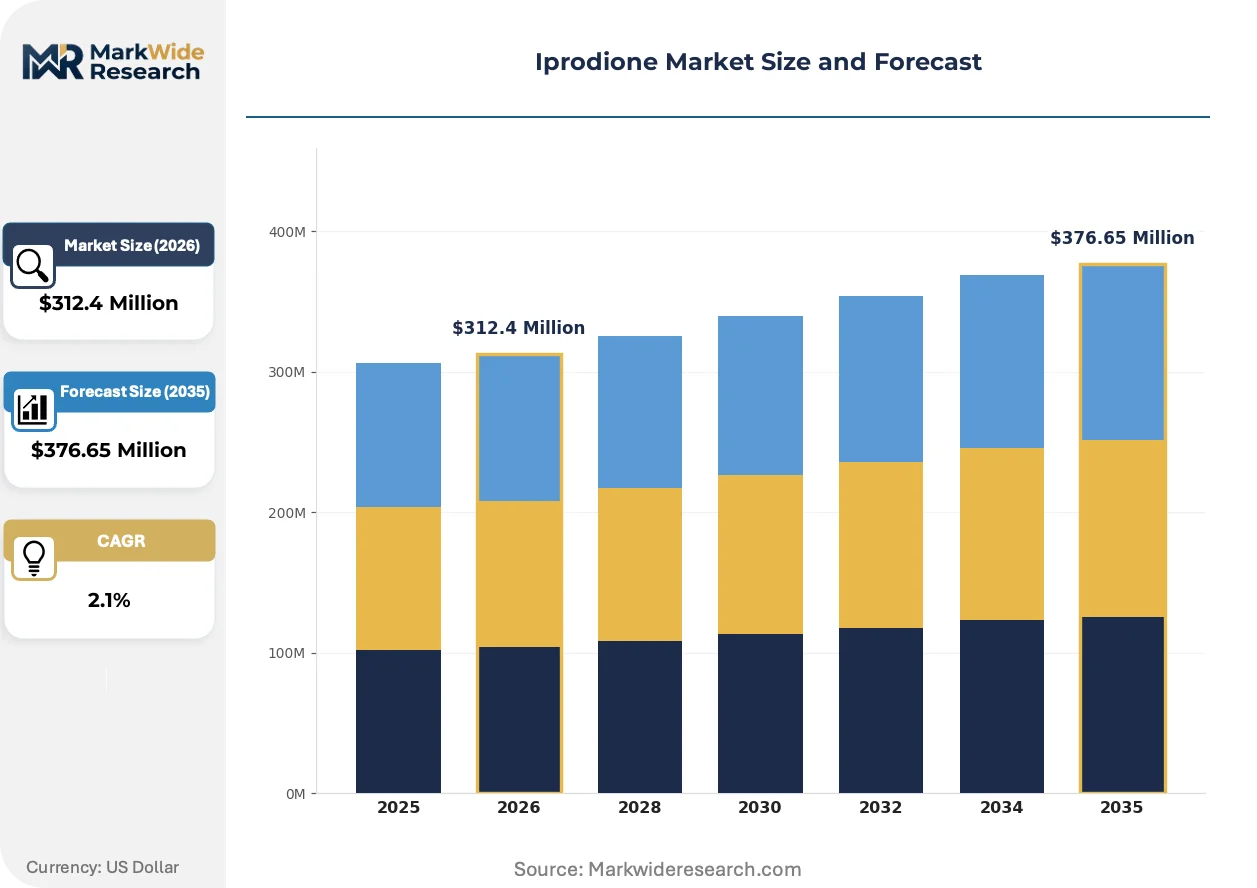
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $376.65 Million |
| CAGR (2026 – 2036) | 2.1% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granules, Liquid, Soluble Concentrate, Wettable Powder Application: Fruits, Vegetables, Ornamentals, Field Crops End User: Agricultural Producers, Horticulturists, Landscape Professionals, Crop Consultants Distribution Channel: Online Retail, Agricultural Supply Stores, Wholesale Distributors, Direct Sales |
| Companies Covered | Bayer CropScience, Syngenta, FMC, BASF, UPL, MilliporeSigma, MedChemExpress, Biosynth, Pharmaffiliates, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Iprodione Market Strategic Shifts
Suspension concentrate formulations with improved rainfastness are displacing conventional wettable powders in high-value horticulture, while regulatory data requirements for endocrine disruption screening are reshaping registration investment priorities across major fungicide classes.
Solvent-free micro-emulsion technologies are rendering obsolete conventional emulsifiable concentrate formulations in European greenhouse operations. Dutch and Belgian tomato propagators are adopting these water-based systems at accelerated replacement cycles to satisfy supermarket chain residue audit protocols. The shift is compressing demand for aromatic solvent carriers and elevating formulation R&D spending toward colloidal stability optimization.
EPA's revised ecological risk assessment methodologies for non-target aquatic organisms are extending data submission timelines for dicarboximide renewals. The agency's refined runoff modeling requirements are forcing label amendments that restrict application timing near vulnerable watersheds. Vegetable growers in Florida and California are responding by adopting vegetative buffer zones and precision application technologies to preserve chemical access.
Certification-driven procurement is consolidating buyer power among export-oriented vegetable cooperatives in Shandong and Hebei provinces. These grower associations are displacing traditional distributor networks with direct technical service relationships, demanding batch-specific residue certificates and accelerated analytical turnaround. The pattern is most visible in garlic and ginger supply chains serving Japanese and South Korean import inspection regimes.
Iprodione Market Segmentation
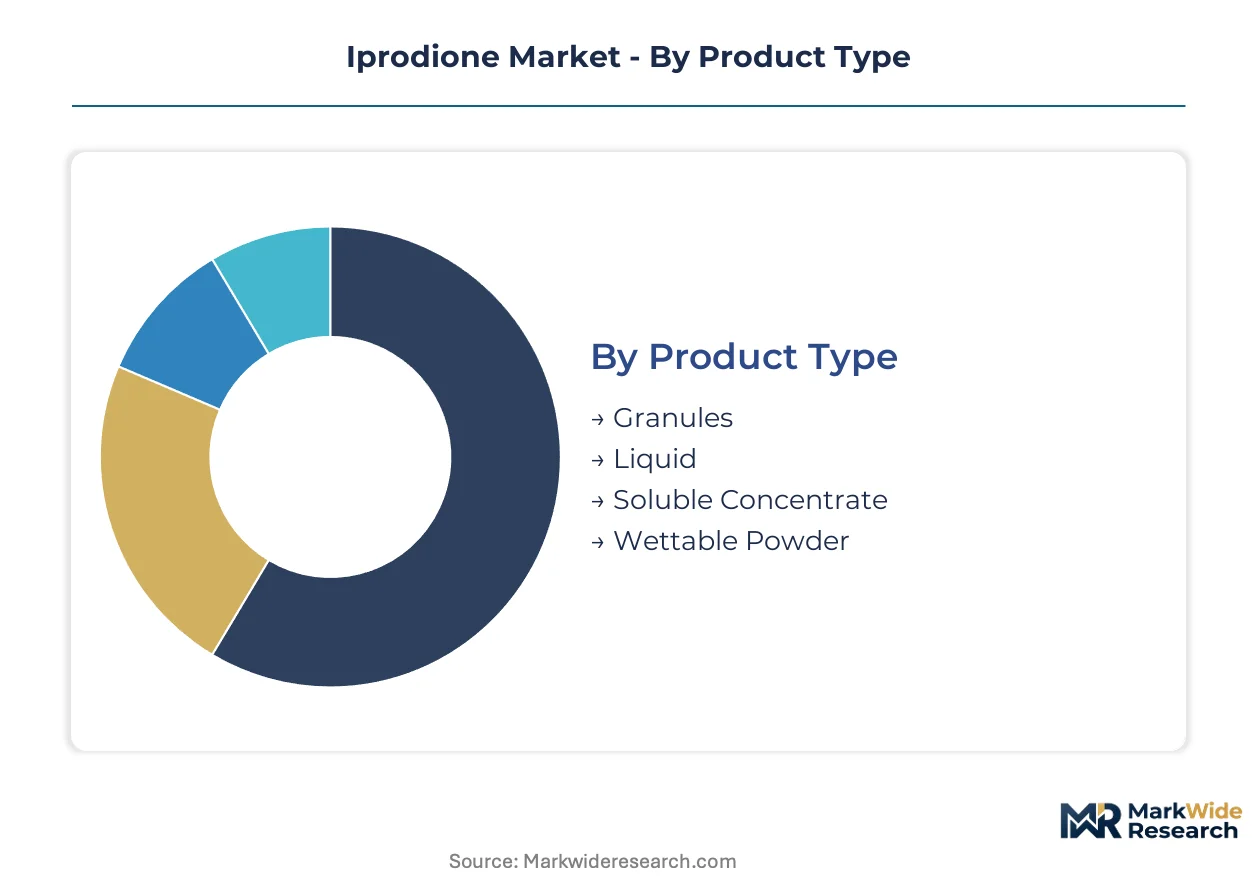
Iprodione procurement patterns diverge sharply across formulation chemistry, crop system, and buyer sophistication. Segment-level dynamics determine margin capture, registration investment priorities, and distribution channel economics for active ingredient suppliers.
Product Type:
Wettable powders turn inventory slowest due to established tank-mix habits, while liquid concentrates cycle faster as greenhouse operators prioritize precision dosing.
- Wettable Powder:Dry flowable formulation containing dispersible granules that reconstitute in spray tanks. Agricultural producers in China's Shandong vegetable belt specify this grade for cost-sensitive bulk procurement against Botrytis pressure in field tomatoes.
- Liquid:Pre-dissolved suspension concentrate enabling direct metered injection. Dutch tomato propagators in Westland cluster demand this format to satisfy supermarket chain residue audit protocols with reduced handling variability.
- Soluble Concentrate:Water-miscible solution requiring minimal agitation. Japanese protected vegetable operations favor this grade for automated dosing systems in labor-constrained greenhouse environments.
- Granules:Dry broadcast-ready formulation for soil incorporation. Limited adoption concentrates in Brazilian soybean seed treatment compatibility trials.
Wettable powder dominates installed base. Liquid is where expansion concentrates.
Application:
Margin structure inverts across these segments: field crops run on volume economics while ornamentals sustain premium pricing through specialized distributor networks.
- Vegetables:Protected and open-field solanaceous crops drive the steepest expansion trajectory as China's greenhouse acreage widens and GB residue standards tighten formulation requirements.
- Ornamentals:Floriculture and nursery stock applications command concentrated margin pools. Colombian rose exporters and Dutch bulb propagators pay certified-residue premiums through specialized procurement cooperatives.
- Fruits:Grape and berry applications face accelerating substitution pressure from SDHI fungicides in French and Italian viticulture as EFSA cumulative risk assessments advance.
- Field Crops:Soybean and groundnut pre-sowing applications represent mature demand with slowing label expansion, though Brazilian seed treatment compatibility programs open incremental access.
Field crops anchor volume base. Vegetables capture fastest share gains.
End User:
Technical service intensity separates these buyers, with crop consultants cycling recommendations fastest and agricultural producers slowest to alter established spray programs.
- Agricultural Producers:Broadacre and vegetable farm operators representing the deepest installed base. China's Shandong and Hebei grower cooperatives displace traditional distributors with direct technical service relationships demanding batch-specific residue certificates.
- Horticulturists:Greenhouse and nursery specialists with precision dosing requirements. Belgian tomato propagators adopt solvent-free micro-emulsion systems at accelerated replacement cycles to satisfy retail audit protocols.
- Landscape Professionals:Turf and ornamental maintenance contractors with seasonal demand concentration. Limited iprodione access due to re-entry interval restrictions near residential zones.
- Crop Consultants:Independent agronomic advisors influencing fungicide selection across client portfolios. Florida and California consultants drive adoption of vegetative buffer zones to preserve chemical access under EPA watershed restrictions.
Agricultural producers dominate procurement volume. Horticulturists command premium tier pricing.
Distribution Channel:
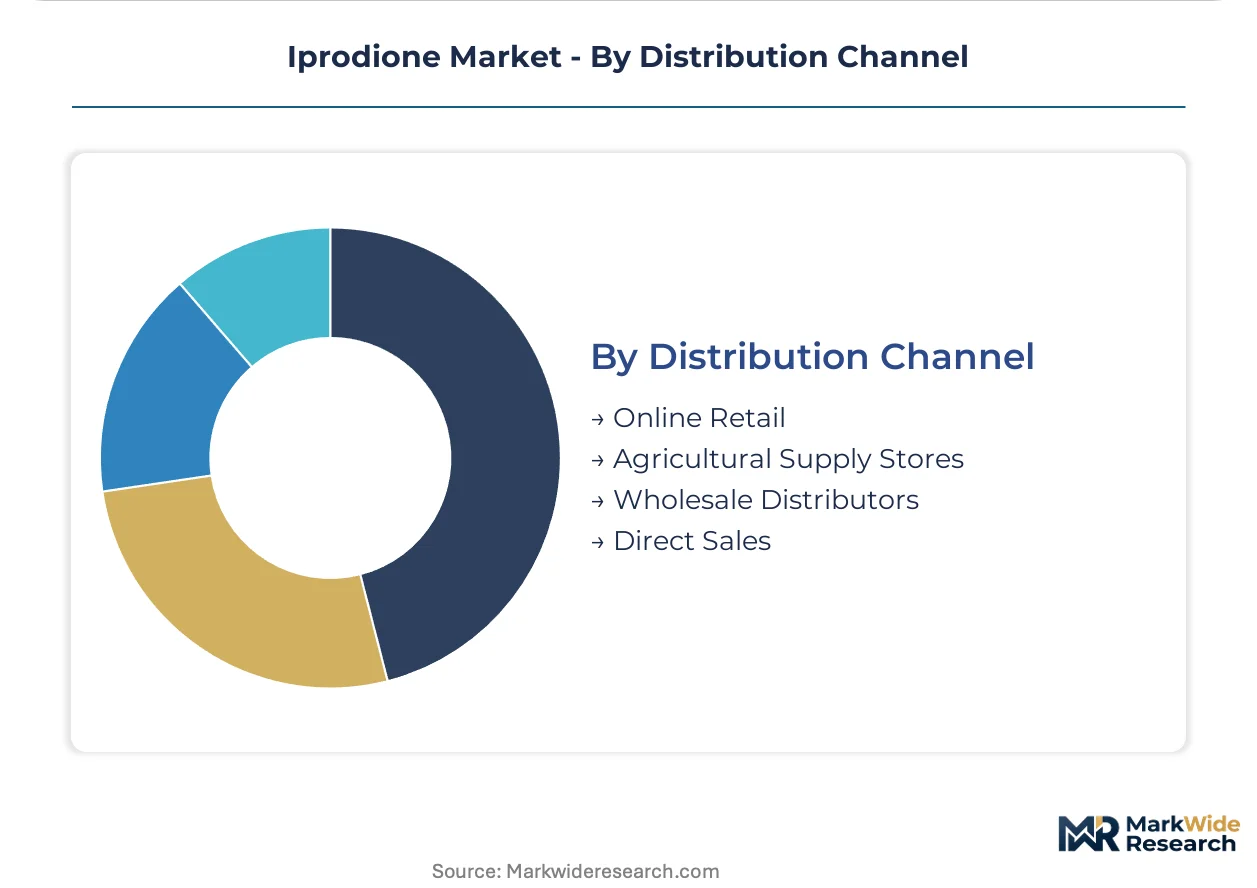
Channel economics reflect buyer scale and certification burden, with wholesale distributors handling slowest-turn inventory and online retail cycling fastest among smallholder vegetable growers.
- Wholesale Distributors:Regional agrochemical wholesalers maintaining inventory depth and technical support infrastructure. Traditional dominance erodes as Chinese export-oriented cooperatives consolidate procurement.
- Agricultural Supply Stores:Local retail points serving mid-scale producers with immediate availability. Japanese agricultural cooperatives (JA) channel substantial volume through this tier.
- Direct Sales:Manufacturer-to-grower relationships bypassing distributor margins. Certification-driven procurement in Shandong garlic and ginger supply chains accelerates this shift.
- Online Retail:E-commerce platforms capturing smallholder demand with transparent pricing. Limited penetration due to hazardous material shipping restrictions and residue certificate requirements.
Wholesale distributors retain largest share. Direct sales is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Yangtze River Delta's agrochemical logistics corridor underwrites China's dominance in technical-grade iprodione synthesis, while Rotterdam's port infrastructure anchors European formulation distribution for horticultural supply chains.
China
Greenhouse expansion in Shandong and Hebei provinces drives sustained demand for Botrytis-specific chemistries. NMPA and MEE enforce tightening environmental release standards at Jiangsu-based manufacturing facilities. The Yangtze River Delta agrochemical parks concentrate technical-grade production capacity expansion.
Netherlands
Westland cluster tomato propagators require residue-certified supplies for supermarket audit compliance. ECHA's streamlined REACH renewal procedures preserve label access across European horticultural markets. Rotterdam's bulk chemical terminals handle formulation imports serving Belgian and German greenhouse operations.
United States
Florida and California vegetable growers adopt precision application technologies to satisfy EPA watershed runoff restrictions. The agency's revised ecological risk assessment methodologies extend dicarboximide renewal timelines. Central Valley processing tomato operations maintain established spray programs against Sclerotinia pressure.
Brazil
Soybean seed treatment compatibility programs open incremental access to pre-sowing fungicide applications. ANVISA registration requirements shape formulation chemistry options for domestic manufacturers. The Mato Grosso agricultural frontier sustains volume demand through broadacre cultivation expansion.
Japan
Protected vegetable operations favor automated dosing systems for labor-constrained greenhouse environments. METI oversees maximum residue limit harmonization with import market requirements. Chubu region horticultural clusters adopt micro-encapsulation advances to extend spray intervals.
Iprodione Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in active ingredient supply. The vendor base stratifies between multinational agrochemical platforms with integrated synthesis networks and regional formulators serving procurement cooperatives. Three archetypes dominate: integrated life-science conglomerates with global registration portfolios, technical-grade producers leveraging Chinese agrochemical park infrastructure, and specialized distributors serving ornamental certification chains. Competitive moves concentrate on seed-treatment compatibility partnerships and residue-analytical service bundling.
Among integrated life-science platforms, Bayer CropScience and Syngenta occupy positions exemplifying the registration-intensive system tier, while BASF represents the specialized formulation compatibility vector. Chinese technical-grade supply is anchored by UPL's manufacturing footprint. These players illustrate how geographic synthesis advantages and regulatory compliance capabilities separate market tiers.
| Leading Market Players |
|---|
| Bayer CropScience |
| Syngenta |
| FMC |
| BASF |
| UPL |
| MilliporeSigma |
| MedChemExpress |
| Biosynth |
| Pharmaffiliates |
| Others |
Value Chain & Pricing Dynamics
Jiangsu province's agrochemical park expansions concentrate technical-grade synthesis capacity, translating directly into pricing leverage for wettable powder manufacturers serving Shandong vegetable cooperatives. Chlorination reagent and glycine derivative feedstock volatility from Chinese petrochemical utilization swings compress margin predictability across formulation tiers.
Pricing Analysis
REACH authorization dictates the pricing tier structure across European horticultural markets, separating residue-certified premium grades from standard wettable powder economy tiers. Certification level and volume scale drive price differentiation, with Dutch ornamental cooperatives paying premiums for batch-specific analytical certificates. Cost compression in liquid concentrate alternatives is intensifying because Chinese GB standard tightening accelerates grower migration from wettable powders. Agricultural producers in China's Hebei province remain most price-sensitive, while Belgian greenhouse operators show least sensitivity due to supermarket audit compliance requirements.
Supply Chain Analysis
Chlorination reagents and glycine derivatives anchor upstream feedstock dependencies for dicarboximide fungicide synthesis. Geographic supply concentration centers on China, India, and Germany for technical-grade production and formulation finishing. Single-source vulnerability runs through Jiangsu-based environmental compliance equipment suppliers facing MEE emission standard retrofits. Distribution runs through Rotterdam's bulk chemical terminals serving Belgian and Dutch greenhouse clusters, with direct sales channels gaining share among Chinese export-oriented vegetable cooperatives.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Residue-analytical service bundling expands faster than active ingredient hardware, creating attach-rate opportunities for technical-grade suppliers serving certification-driven procurement cooperatives.
For Market Incumbents: Pre-empt SDHI substitution pressure in French and Italian viticulture by accelerating seed-treatment compatibility programs for Brazilian soybean applications. Backward integration into Jiangsu-based technical-grade capacity insulates margin structures from chlorination reagent volatility. Prioritize MEE-compliant waste-heat recovery investments to capture dual carbon manufacturing credits. For New Entrants and Emerging Players: Colombian rose export supply chains present geographic underpenetration with concentrated volume contracts and premium pricing tolerance for residue-certified supplies. Ornamental distributor network consolidation in Dutch floriculture clusters offers the most penetrable segment. Lead with micro-encapsulation formulation partnerships to differentiate against established wettable powder incumbents. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compliance play because REACH authorization pathways and EPA residue tolerance assessments create durable moats for incumbent registration portfolios. Target specialized distributors with integrated analytical laboratories serving ornamental certification chains. Watch EFSA cumulative risk assessment progress as the signal indicating accelerated substitution timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Seed Treatment Compatibility Program | Opens Brazilian soybean and Indian groundnut pre-sowing markets through neonicotinoid tank-mix stability. |
| Micro-encapsulation Formulation Launch | Extends spray intervals in Japanese labor-constrained protected vegetable operations. |
| Residue-Analytical Service Bundling | Captures Shandong garlic and ginger cooperative procurement shifting from traditional distributors. |
| Backward Integration into Technical-Grade Synthesis | Secures Jiangsu agrochemical park capacity against chlorination reagent feedstock volatility. |
| Ornamental Distributor Network Acquisition | Consolidates access to Dutch and Colombian floriculture premium pricing pools. |
Study Parameters
A standing panel of agrochemical plant managers, procurement leads at vegetable cooperatives, distribution channel partners, and technical R&D directors provided ongoing calibration. Primary interview insights combined with customs and trade data, SEC 10-K filings, and NMPA registration databases enabled bottom-up and top-down triangulation across the analysis window.
Scenario-bracketing around regulatory authorization timelines and feedstock volatility bands anchored the analytical framework. Segmentation dimensions modeled include formulation chemistry, crop system, buyer sophistication, and regional regulatory cluster. CAGRs derived from historical volume trajectories adjusted for REACH renewal probabilities and Chinese greenhouse acreage expansion rates.
The forecast holds incumbent behavior within observed patterns; aggressive capacity additions by Jiangsu-based technical-grade producers or accelerated EFSA substitution rulings would shift outcomes. Cross-checking against ECHA authorization renewal schedules and Chinese GB standard implementation timelines is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Crop Protection
US Herbicide Market
Crop Protection
Azoxystrobin Market
Crop Protection
Global Insect Growth Regulators Market
Crop Protection
Europe Crop Protection Chemicals Market
Crop Protection
US Pest Control Market
Crop Protection
North America Insecticide Market
Crop Protection
Global Insecticide Seed Treatment Market
Crop Protection
Pest Control Products Market
Crop Protection
Latin America Crop Protection Chemicals Market
Crop Protection
Generic Crop Protection Chemicals Market
Crop Protection
Fosthiazate Market
Crop Protection
Fruit and Vegetable Crop Protection Market
Crop Protection
Sustainable Crop Protection Chemicals Market
Crop Protection
Vietnam Herbicide Market
Crop Protection
South America Nematicides Market
Crop Protection
Global Termite Control Market