
 Spain Crop Protection Chemicals Market | 2026-2036
Spain Crop Protection Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Spain Crop Protection Chemicals Market Analytics
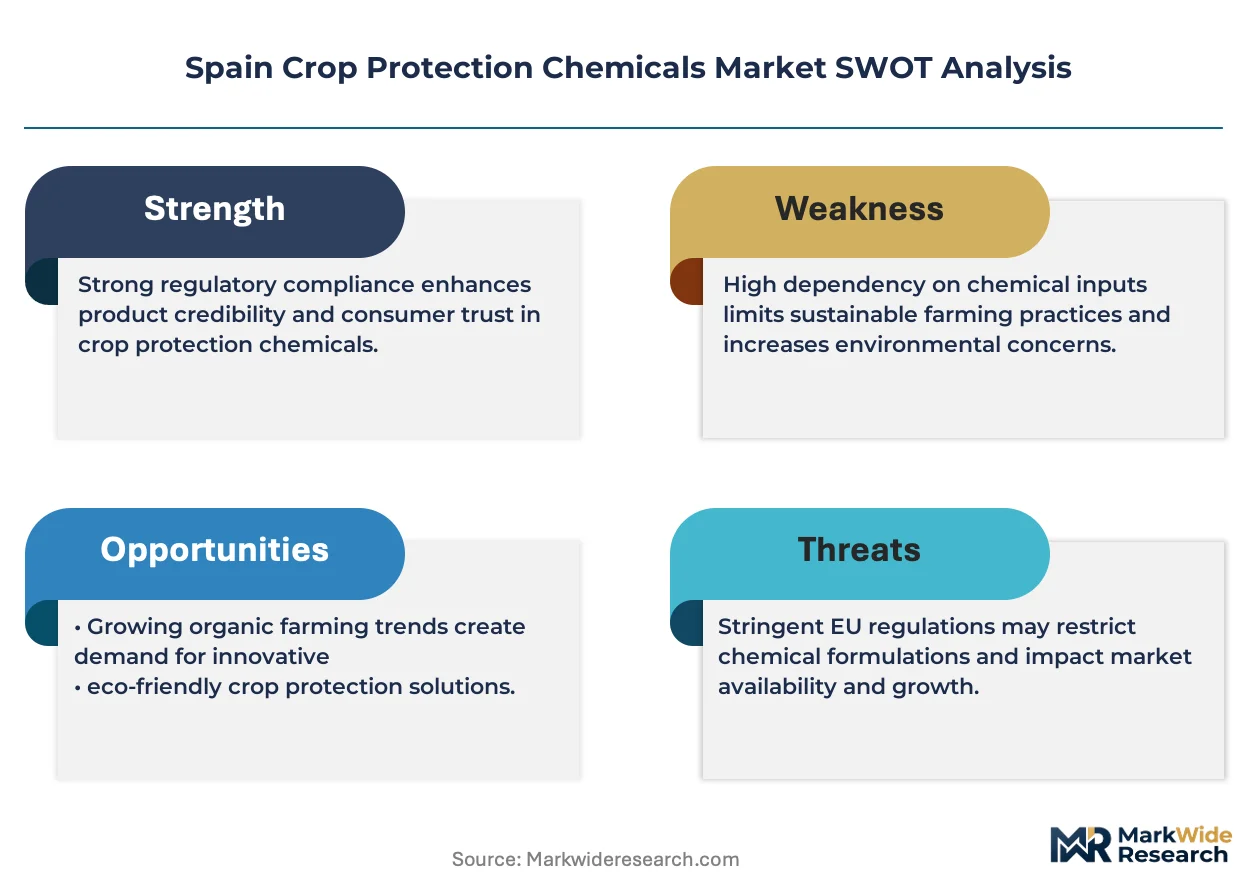
A capital-intensity divergence between multinational R&D platforms and regional formulators is reorganizing competitive hierarchy in Spain. Bayer CropScience AG leverages its integrated discovery pipeline to sustain patent-protected chemistry access. BASF SE anchors its position through backward integration into active ingredient manufacturing. UPL Limited competes on generic herbicide portfolios optimized for Mediterranean weed spectrums.
Crop protection chemicals comprise synthetic and biological formulations designed to manage weeds, pests, and pathogens through active ingredients typically applied at grams per hectare rates, with emulsifiable concentrates and suspension concentrates dominating Spanish distribution channels due to compatibility with existing spray equipment. Herbicides command the largest product type share, reflecting Spain's extensive cereal and oilseed monocultures where grass weed resistance pressures demand rotational chemistry. Foliar sprays represent the leading application method, though soil treatments gain traction in drip-irrigated vegetable systems across Murcia and Almería where water scarcity constrains aerial options.
Spain's Ministry of Agriculture, Fisheries and Food enforces EU REACH and Sustainable Use of Pesticides Directive compliance, while EFSA evaluations determine maximum residue limits for export-oriented citrus and stone fruit producers. The national integrated pest management certification scheme shapes procurement criteria for cooperative buyers supplying Mercadona and Carrefour Spain. Stakeholders must monitor regulatory divergence between EU hazard-based cut-off criteria and third-country import tolerances affecting almond and table grape export competitiveness.
Market Dynamics
The EU Farm to Fork strategy pesticide reduction mandate is compressing product registration timelines and forcing formulators to accelerate biological pipeline development ahead of synthetic chemistry phase-outs.
Growth Catalysts
- Precision Application Technology:Drone-mounted variable-rate sprayers enable olive and vineyard operators to reduce active ingredient volumes by targeting individual canopies rather than blanket coverage.
- Integrated Pest Management Certification:Mercadona and Carrefour Spain procurement criteria now require IPM-verified suppliers, pulling cooperative buyers toward certified product portfolios.
- Andalusia Horticulture Intensification:Drip-irrigated vegetable systems in Almería and Murcia expand soil treatment demand as water scarcity eliminates aerial application options.
Market Restraints
- Active Ingredient Import Concentration:Generic herbicide formulators depend on Chinese and Indian active ingredient suppliers, exposing margins to freight volatility and currency fluctuation.
- EFSA Hazard-Based Cut-Off Criteria:Endocrine disruptor and candidate substitution substance classifications remove chemistries from Spanish registration eligibility before patent expiration.
- Resistance Management Complexity:Grass weed resistance in Extremadura cereal monocultures demands rotational chemistry protocols that raise technical advisory costs for distributors.
Strategic Opportunities
- Biological Formulation White Space:Bacterial and fungal biocontrol agents for citrus psyllid management in Valencia lack registered alternatives to neonicotinoid restrictions.
- Export Market Divergence:Almond and table grape producers require dual-registration chemistries satisfying both EU MRLs and third-country import tolerances for US and Middle Eastern buyers.
- Digital Agronomy Convergence:Sensor networks combined with predictive disease models enable prescriptive fungicide timing in Castile-La Mancha vineyards.
Industry Challenges
- Residue Monitoring Infrastructure:Cooperative laboratories face capacity constraints validating compliance with supermarket chain maximum residue limit protocols.
- Formulation Rework Costs:REACH substance restriction updates force reformulation of emulsifiable concentrate portfolios without guaranteed re-registration timelines.
- Spray Drift Liability Exposure:Buffer zone requirements for aquatic organism protection limit application windows in Ebro Valley rice cultivation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spain Crop Protection Chemicals Market |
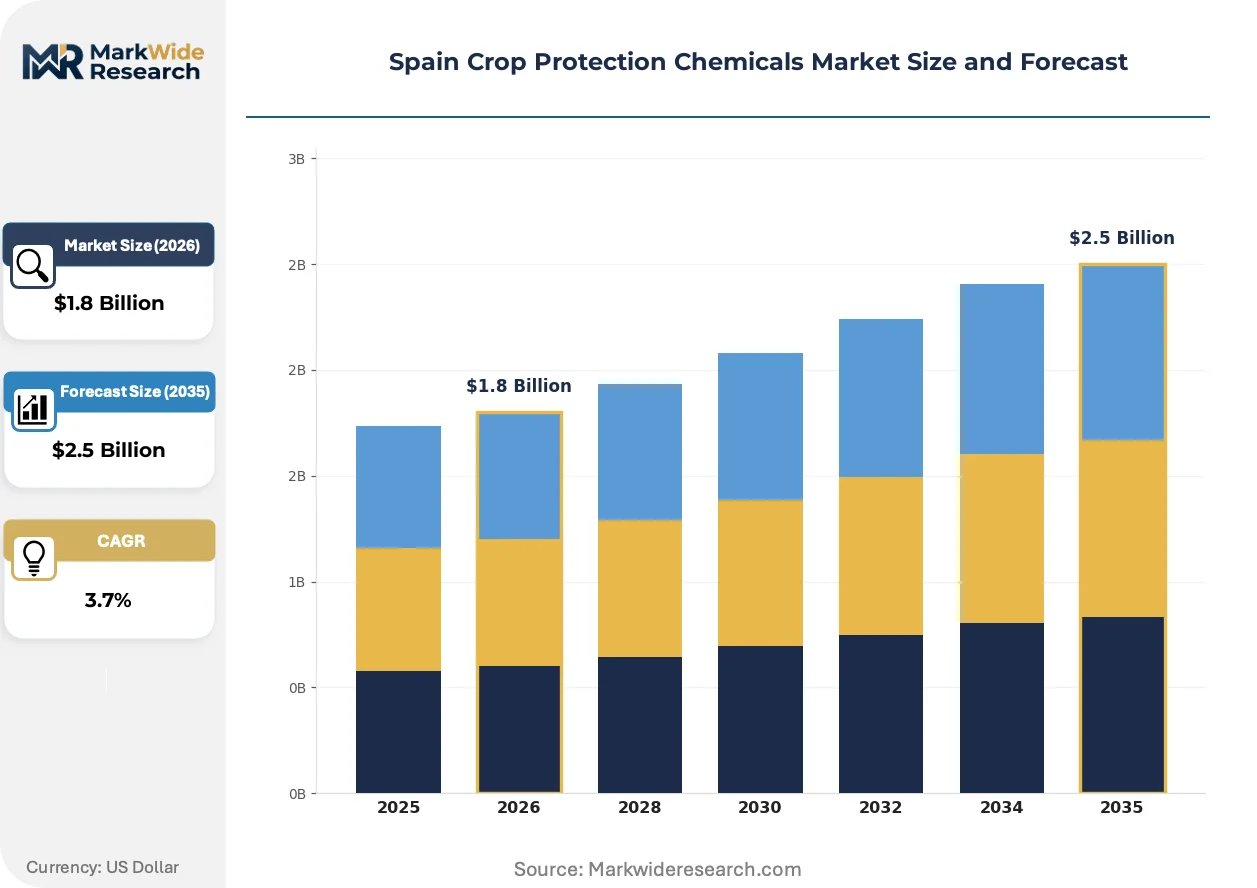
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.5 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Herbicides, Insecticides, Fungicides, Seed Treatments Formulation: Granules, Liquids, Emulsifiable Concentrates, Suspensions Application Method: Foliar Sprays, Soil Treatments, Seed Coatings, Aerial Application Crop Type: Cereals, Fruits, Vegetables, Oilseeds |
| Companies Covered | FMC Corporation, ADAMA Agricultural Solutions Ltd, Bayer CropScience AG, Nufarm Limited, Corteva Agriscience, BASF SE, Sumitomo Corporation, UPL Limited, Syngenta International AG, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spain Crop Protection Chemicals Market Evolving Landscape
Biological active ingredients and digital application systems are converging to displace conventional synthetic chemistry in Spanish specialty crop segments, with regulatory pressure accelerating formulation pipeline redirection.
RNA interference-based biopesticides targeting specific lepidopteran pests in greenhouse vegetable systems is supplanting broad-spectrum pyrethroid applications. Almería cooperative technicians pilot foliar sprays containing double-stranded RNA molecules that silence essential insect genes. This selectivity eliminates beneficial predator mortality and compresses resistance development timelines compared to neurotoxic chemistries.
EFSA's 2023 guidance on cumulative risk assessment for pesticide residues is restructuring Spanish citrus export protocols. Maximum residue limit calculations now aggregate exposure across multiple active ingredients with shared toxicological profiles. Valencia orange packers are consolidating supplier bases to chemistries with distinct modes of action to maintain US and Japanese market access.
Cooperative procurement committees in Castile and León now mandate third-party resistance monitoring data before herbicide volume commitments. Technical service providers supply DNA-based rapid diagnostic kits documenting target-site mutations in black-grass populations. This verification requirement shifts distributor margins toward advisory services rather than product volume incentives.
Spain Crop Protection Chemicals Market Segmentation
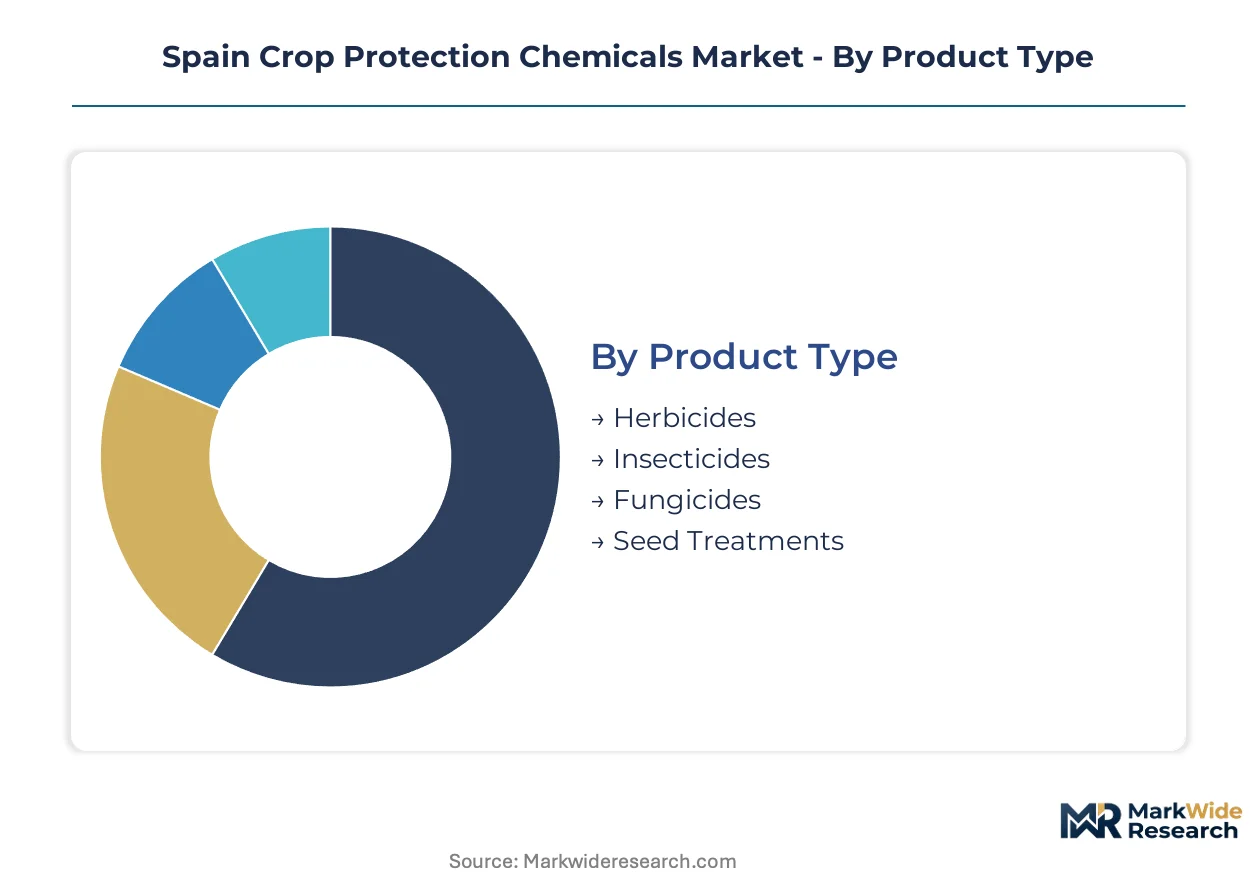
Spain's crop protection chemicals market fragments across four dimensions that reflect divergent agronomic requirements and regulatory pressures. Understanding these segment boundaries enables suppliers to align formulation investments with specific crop-system economics and application infrastructure constraints.
Product Type:
Domestic consumption concentrates in herbicides for Extremadura cereal monocultures, while export-oriented citrus and stone fruit operations drive fungicide demand for residue-sensitive Northern European markets.
- Herbicides:Synthetic auxins and ALS inhibitors dominate cereal and oilseed systems across Castile and León, where black-grass resistance pressures demand rotational chemistry protocols. Extremadura cooperative procurement committees now mandate DNA-based resistance monitoring before volume commitments.
- Fungicides:Triazoles and strobilurins protect Valencia citrus and Castile-La Mancha vineyards against downy mildew and botrytis bunch rot. EFSA cumulative risk assessments force packers toward chemistries with distinct toxicological profiles to maintain Japanese market access.
- Insecticides:Neonicotinoid restrictions in Murcia greenhouse vegetables accelerate pyrethroid and biological alternatives for whitefly and thrips management.
- Seed Treatments:Systemic fungicide-insecticide combinations protect Andalusia maize and sunflower establishment against soil-borne pathogens and early-season pests.
Herbicides hold the largest share; momentum sits with seed treatments as farmers front-load protection against tightening aerial application windows.
Formulation:
Cost-to-efficacy ratios and equipment compatibility determine formulation selection across Spain's divergent farm scales and irrigation infrastructures.
- Emulsifiable Concentrates:Oil-based carriers penetrate waxy cuticles of Mediterranean olive and citrus foliage, with established compatibility across Andalusia's aging tractor-mounted sprayer fleet.
- Suspensions:Aqueous dispersions of insoluble active ingredients suit high-volume vegetable applications in Almería's drip-irrigated greenhouses where water-miscibility reduces nozzle clogging.
- Liquids:Ready-to-use solutions command premium positioning for precision vineyard applications in Rioja and Ribera del Duero.
- Granules:Controlled-release formulations target soil-dwelling pests in Murcia protected cultivation where foliar spray drift risks neighbor complaints.
Emulsifiable concentrates dominate current volumes; suspensions are climbing the fastest as greenhouse intensification accelerates.
Application Method:
Water scarcity and buffer zone constraints are restructuring application method economics across Spain's major agricultural zones.
- Foliar Sprays:Tractor-mounted boom sprayers remain standard for Extremadura cereals and Castile-La Mancha vineyards, though drone-mounted variable-rate systems gain traction in olive orchards for canopy-specific targeting.
- Soil Treatments:Pre-plant incorporation and drip-line injection expand in Almería and Murcia vegetables where water scarcity eliminates aerial options and surface water buffer zones restrict foliar timing.
- Seed Coatings:Film coatings applied by cooperative seed processors reduce field-level handling and enable precise dose control for Castile and León cereals.
- Aerial Application:Fixed-wing and helicopter spraying contracts concentrate in Ebro Valley rice cultivation where ground equipment cannot access flooded paddies.
Foliar sprays retain the largest installed base; soil treatments are gaining share fastest as drip irrigation expands.
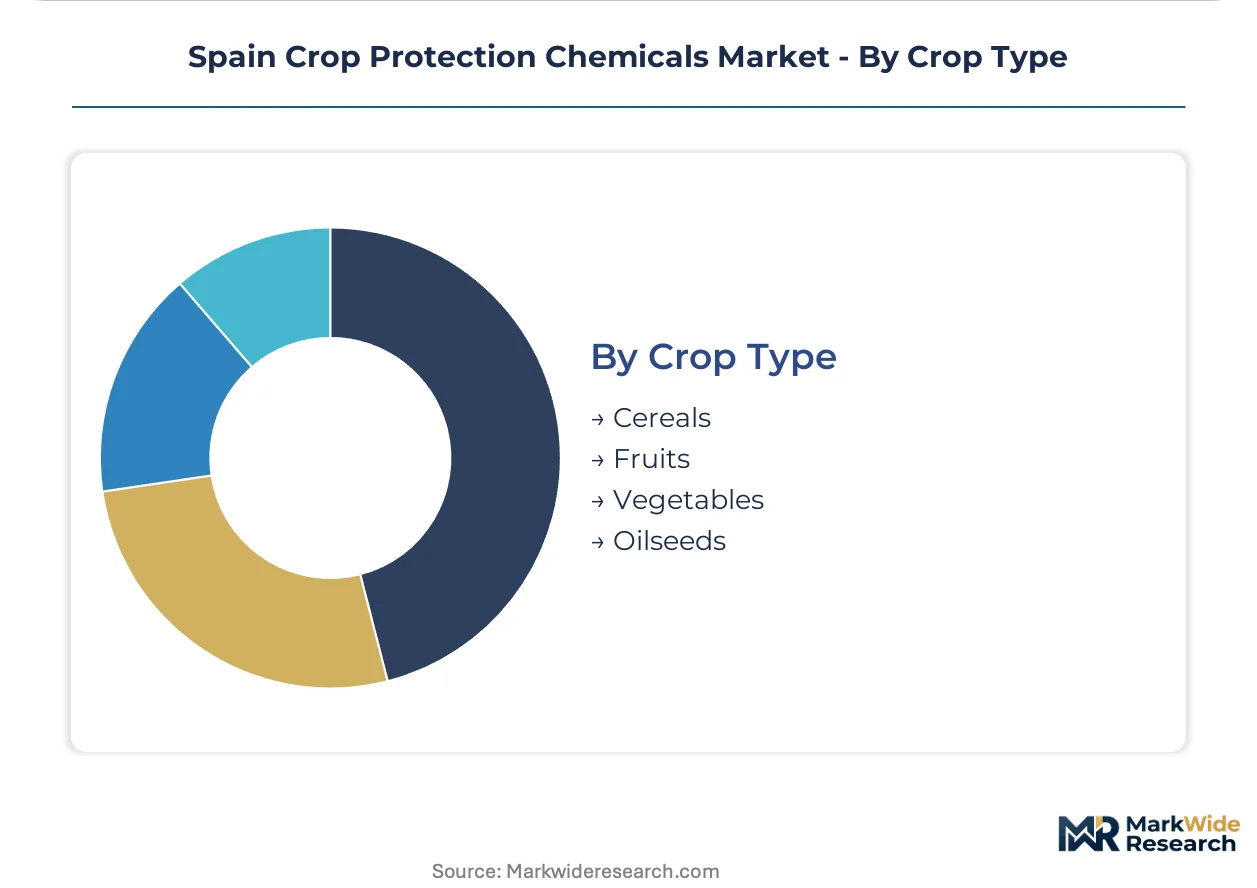
Crop Type:
Export market access requirements and domestic food security priorities create divergent procurement patterns across Spain's major crop categories.
- Fruits:Citrus in Valencia and stone fruit in Aragón face dual-registration demands for EU MRL compliance and third-country tolerances for US and Middle Eastern buyers.
- Vegetables:Protected cultivation in Almería and Murcia generates intensive protection chemical demand with strict supermarket chain residue protocols from Mercadona and Carrefour Spain.
- Cereals:Extensive rain-fed wheat and barley in Castile and León drive herbicide volume through cooperative purchasing pools.
- Oilseeds:Sunflower and rapeseed in Andalusia and Castile-La Mancha require distinct weed control spectrums from cereal monocultures.
Cereals command the greatest volume; fruits are expanding most quickly as export-oriented specialty production intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Andalusia commands pricing leverage over Castile-La Mancha through its export-oriented horticulture concentration, while Extremadura's cereal monocultures face compressed margins from cooperative purchasing power.
Andalusia
Intensive greenhouse vegetable production in Almería and Huelva drives soil treatment demand for drip-irrigated pepper and tomato systems. EFSA Sustainable Use of Pesticides Directive compliance shapes cooperative procurement through Mercadona supply chain requirements. The Poniente Almeriense corridor concentrates biological formulation trials as neonicotinoid restrictions tighten.
Castile and León
Extensive rain-fed wheat and barley monocultures generate herbicide volume through cooperative purchasing pools. REACH substance restriction updates force reformulation of emulsifiable concentrate portfolios without guaranteed re-registration timelines. The Tierra de Campos plateau anchors black-grass resistance monitoring programs using DNA-based rapid diagnostic protocols.
Valencia
Citrus psyllid management in orange groves accelerates biological active ingredient demand following neonicotinoid phase-outs. EFSA cumulative risk assessment guidance restructures export protocols for US and Japanese market access. The Ribera Alta comarca concentrates dual-registration chemistry procurement satisfying both EU MRLs and third-country import tolerances.
Catalonia
Stone fruit orchards in Lleida and Huesca face residue-sensitive Northern European supermarket chain requirements. The national integrated pest management certification scheme shapes procurement criteria for cooperative buyers supplying Carrefour Spain. The Segrià county cluster pilots sensor networks combined with predictive disease models for prescriptive fungicide timing.
Castile-La Mancha
Vineyard operators in La Rioja and Ribera del Duero adopt drone-mounted variable-rate sprayers for canopy-specific targeting. Buffer zone requirements for aquatic organism protection limit application windows in Guadiana River watershed cultivation. The Valdepeñas sub-region concentrates precision application technology adoption among olive and vineyard operators.
Spain Crop Protection Chemicals Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with patent-protected discovery pipelines diverging from generic formulation optimization. The market structure consolidates around multinational R&D platforms and regional formulators serving Mediterranean crop spectrums. Three archetypes dominate: integrated discovery pipelines, backward-integrated active ingredient manufacturers, and generic herbicide portfolio specialists. Competitive moves center on biological pipeline acceleration and precision application technology partnerships.
Within the multinational tier, Bayer CropScience AG and BASF SE anchor positions through distinct strategic foundations, while UPL Limited exemplifies the generic specialist archetype optimized for regional weed spectrums. Bayer CropScience AG represents integrated discovery pipeline capabilities. BASF SE occupies a position anchored in backward integration into active ingredient manufacturing. UPL Limited sits within the cost-optimized formulation tier competing on generic herbicide portfolios.
| Leading Market Players |
|---|
| FMC Corporation |
| ADAMA Agricultural Solutions Ltd |
| Bayer CropScience AG |
| Nufarm Limited |
| Corteva Agriscience |
| BASF SE |
| Sumitomo Corporation |
| UPL Limited |
| Syngenta International AG |
| Others |
Value Network & Pricing Analysis
Active ingredient manufacturing scale economies in China and India compress price floors for Spanish generic formulators while concentrating supply risk in distant production hubs. This dual concentration—of manufacturing capacity and price-setting power—forces regional distributors to absorb freight volatility and currency fluctuation without passing full costs to cooperative buyers locked into annual procurement contracts.
Pricing Analysis
The customization-premium spread separates standard emulsifiable concentrate formulations from precision-application-ready suspensions tailored for Almería drip-irrigation systems. Pricing stratifies across premium, standard, and economy tiers driven by certification grade (EU Farm to Fork IPM compliance) and volume scale through cooperative purchasing pools. Pricing pressure stems from EFSA hazard-based cut-off criteria forcing premature chemistry phase-outs before patent expiration. Cooperative buyers in Extremadura exhibit highest price sensitivity due to cereal monoculture margin compression, while export-oriented Valencia citrus packers prioritize residue compliance over unit cost.
Supply Chain Analysis
Inbound logistics costs through Barcelona and Valencia ports fluctuate with container availability on Asia-Mediterranean trade lanes, amplifying working capital requirements for inventory-heavy formulation distributors. Active ingredient supply concentrates in China and India, with formulation packaging and distribution anchored in Spanish regional cooperatives. The supply chain draws from pyrethroid and triazole technical materials, petroleum-derived solvent carriers, and precision-spray nozzle components. Single-source vulnerability persists for neonicotinoid-replacement biological actives. Distribution runs through cooperative procurement committees supplying Mercadona and Carrefour Spain retail networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution defense imperatives as RNA interference biopesticides displace synthetic chemistries in Almería greenhouse vegetables. Biological pipeline acceleration represents the critical pivot for maintaining shelf space amid EU Farm to Fork pesticide reduction mandates.
For Market Incumbents: Compound biological formulation capabilities through partnerships with specialized microbial discovery platforms before neonicotinoid restrictions eliminate conventional revenue streams in Murcia protected cultivation. Prioritize backward integration into active ingredient manufacturing for proprietary biocontrol strains to defend margin position against generic herbicide price erosion from Chinese and Indian competitors. Accelerate precision application technology bundling with cooperative buyers to shift distributor economics toward advisory services.
For New Entrants and Emerging Players: Lead with bacterial and fungal biocontrol agents for citrus psyllid management in Valencia, where neonicotinoid phase-outs have created immediate registration white space without incumbent biological alternatives. Target the biological formulation segment serving export-oriented stone fruit producers in Aragón facing dual EU and third-country MRL compliance pressures. Pursue cooperative pilot programs demonstrating RNA interference efficacy against lepidopteran pests as the primary go-to-market pathway.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors backward-integrated active ingredient manufacturers with captive biological pipeline access over pure-play generic formulators exposed to Chinese technical material price volatility. Long-term viability across the projection horizon rests on regulatory arbitrage capabilities navigating EU hazard-based cut-off criteria while maintaining third-country export market access. Acquisition targets should demonstrate dual-registration chemistry portfolios and precision application technology partnerships. The signal to watch is EFSA cumulative risk assessment guidance expansion beyond citrus into vegetable categories, which would accelerate biological displacement timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| Biological Pipeline Acceleration | RNA interference and microbial biocontrol development addresses neonicotinoid restriction gaps in Valencia citrus and Murcia vegetables. |
| Precision Application Technology Partnership | Drone-mounted variable-rate sprayer integration with cooperative buyers shifts distributor margins toward canopy-specific advisory services. |
| Dual-Registration Chemistry Investment | Active ingredients satisfying both EU MRLs and US EPA tolerances protect almond and table grape export competitiveness against regulatory divergence. |
| Backward Integration into Active Ingredient Manufacturing | Captive production of proprietary biological actives reduces dependency on Chinese and Indian technical material suppliers. |
| Cooperative Procurement Committee Engagement | Direct relationships with Mercadona and Carrefour Spain supply chain gatekeepers secure shelf space amid IPM certification requirements. |
Research Methodology
Desk research of EU regulatory filings, EFSA guidance documents, and cooperative procurement committee records preceded structured interviews with formulation R&D directors, cooperative technical service managers, and distribution channel partners. Primary fieldwork encompassed plant managers at Almería greenhouse operations, regulatory affairs leads navigating REACH compliance, and procurement officers at major retail supply chains. Secondary validation drew from Spanish Ministry of Agriculture enforcement data, customs import records for active ingredients, and SEC filings of multinational crop protection companies. Bottom-up volume estimates from crop-specific application rates triangulated against top-down market size assessments.
Variance decomposition across product type, formulation, application method, and crop type segmentation dimensions structured the analytical framework over the projection horizon. CAGRs derived from trend extrapolation of precision technology adoption curves, biological formulation registration timelines, and EU Farm to Fork implementation pace. Industry-specific forecast inputs included EFSA cumulative risk assessment guidance evolution and cooperative purchasing pool consolidation patterns.
The analysis sits within stated boundaries; outcomes outside sustained EU pesticide reduction policy enforcement and stable Asia-Mediterranean shipping lanes would require recalibration. Forecasts reflect assumptions regarding biological formulation efficacy validation timelines and third-country MRL harmonization progress. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Crop Protection
South America Molluscicides Market
Crop Protection
US Insecticide Market
Crop Protection
Global Algaecides Market
Crop Protection
Europe Chemical Seed Treatment Market
Crop Protection
Australia Crop Protection Chemicals (Pesticides) Market
Crop Protection
Sustainable Crop Protection Chemicals Market
Crop Protection
China Fungicide Market
Crop Protection
Global Crop Growth Regulators Market
Crop Protection
Pest Control Market
Crop Protection
IPM Pheromones Market
Crop Protection
Global Home and Garden Pesticides Market
Crop Protection
North America Crop Protection Chemicals Market
Crop Protection
Fruit and Vegetable Crop Protection Market
Crop Protection
Argentina Crop Protection Chemicals Market
Crop Protection
Europe Fungicide Market
Crop Protection
Global Turf Protection Market