
 Vietnam Crop Protection Chemicals Market | 2026-2036
Vietnam Crop Protection Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Vietnam Crop Protection Chemicals Market Analytics
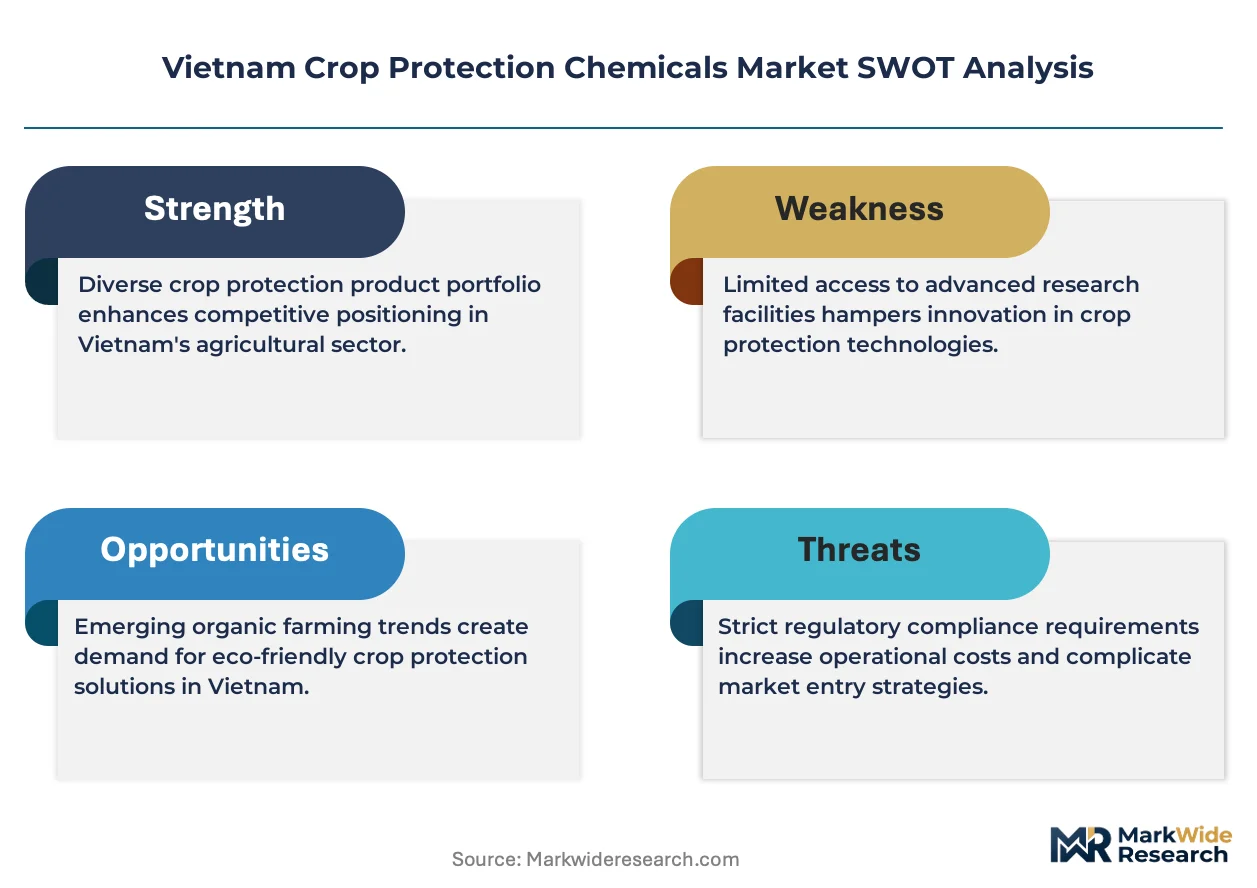
Domestic formulator capacity in the Red River Delta is rebalancing toward higher-margin technical-grade imports. Bayer AG leverages its herbicide portfolio to anchor distribution networks across northern provinces. Syngenta Group competes through integrated seed-chemistry bundles targeting rice and vegetable growers. BASF SE sustains R&D intensity in fungicide formulations suited to Vietnam's tropical humidity cycles.
Crop protection chemicals comprise synthetic and biological active ingredients formulated to control weeds, insects, and plant pathogens, typically applied at rates measured in grams of active ingredient per hectare to preserve yield quality and volume in commercial agriculture. Herbicides dominate product-type revenue due to labor scarcity in rice transplanting, while biopesticides represent the fastest-expanding category as MEE residue thresholds tighten export compliance for fruits and vegetables. Emulsifiable concentrate formulations retain share among smallholder cooperatives despite a gradual shift to liquid and granule formats that reduce handler exposure and simplify aerial application.
Vietnam's Ministry of Agriculture and Rural Development (MARD) and the Ministry of Natural Resources and Environment (MONRE) jointly administer pesticide registration, residue limits, and environmental release permits that determine which molecules gain market access. The country's national standards body issues bioefficacy and safety protocols that foreign suppliers must satisfy before commercialization. Stakeholders must monitor pending MARD revisions to the positive list of approved active ingredients, as delisting events would force rapid portfolio restructuring across distributor and grower channels.
Market Dynamics
Vietnam's tightening MEE pesticide residue standards are forcing rapid portfolio restructuring across distributor and grower channels, compressing synthetic molecule margins while elevating biopesticide technical grades.
Growth Catalysts
- MEE Residue Thresholds:The Ministry of Natural Resources and Environment's stricter maximum residue limits for export-bound fruits and vegetables are compelling formulators to accelerate biopesticide registration timelines.
- Mekong Delta Intensification:Commercial rice and vegetable cooperatives in this southern region are expanding hectarage under intensive cropping systems that require systematic herbicide and fungicide programs.
- Labor Scarcity in Transplanting:Rural workforce shortages are driving mechanical direct-seeding adoption, which elevates pre-emergence herbicide demand as manual weeding becomes uneconomical.
Market Restraints
- Active Ingredient Import Dependence:Domestic formulators rely on technical-grade imports from China and India, exposing margin structures to currency volatility and shipping cost swings.
- Registration Timeline Friction:MARD's bioefficacy review protocols and field trial requirements extend commercialization cycles to 24-36 months for novel molecules.
- Smallholder Fragmentation:The majority of Vietnamese farms operate below two hectares, diluting purchasing power and complicating precision application technology deployment.
Strategic Opportunities
- Red River Delta Formulator Capacity:Northern provinces harbor underutilized technical blending infrastructure that can pivot toward high-margin biological formulations.
- Aerial Application Services:Drone spraying cooperatives are emerging as a direct-to-farmer channel that bypasses traditional distributor markups in the Mekong Delta.
- Integrated Pest Management Mandates:MARD's extension programs incentivize biocontrol agent adoption alongside reduced-risk synthetics in export vegetable zones.
Industry Challenges
- Residue Testing Infrastructure Gap:Provincial laboratories lack ISO-certified equipment to verify compliance with evolving MEE standards, creating certification bottlenecks for exporters.
- Handler Training Deficits:Smallholder cooperatives show inconsistent adherence to personal protective equipment protocols, elevating liability exposure for distributors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vietnam Crop Protection Chemicals Market |
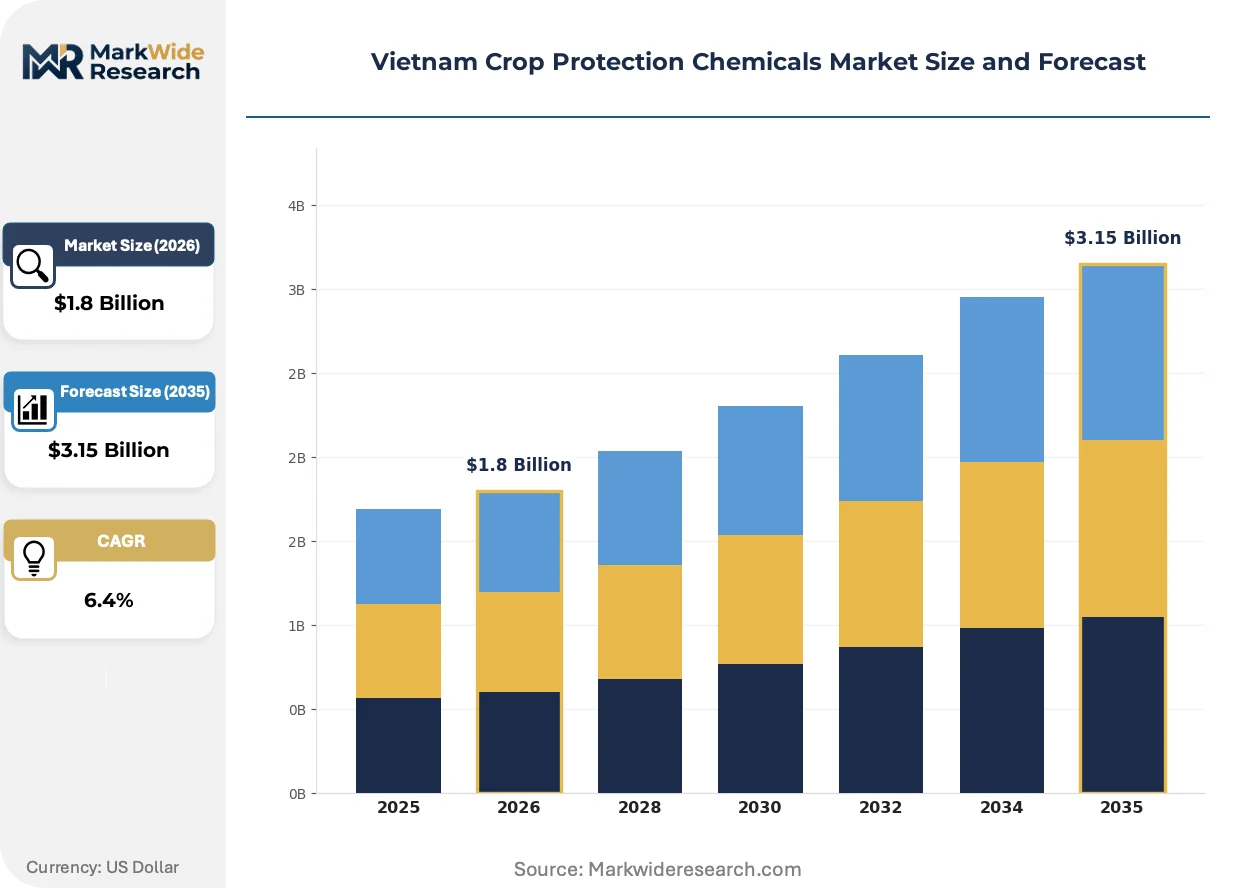
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Herbicides, Insecticides, Fungicides, Biopesticides Application: Cereals, Fruits, Vegetables, Oilseeds Formulation: Liquid, Granule, Powder, Emulsifiable Concentrate End User: Agricultural Producers, Commercial Growers, Cooperatives, Retailers |
| Companies Covered | Bayer AG, BASF SE, Syngenta Group, FMC Corporation, UPL Limited, Corteva Agriscience, Sumitomo Chemical Co., Ltd., Nufarm Limited, Adama Agricultural Solutions, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vietnam Crop Protection Chemicals Market Evolving Landscape
Formulation chemistry and application technology are converging to reduce handler exposure while maintaining efficacy under Vietnam's tropical humidity cycles. These shifts are compressing legacy emulsifiable concentrate positions.
Water-dispersible granule formulations are overtaking emulsifiable concentrates in rice and vegetable segments. Mekong Delta cooperatives are adopting these solid formats to eliminate solvent exposure during tank mixing. The structural consequence is margin compression for legacy solvent-based supply chains as granule production scales in Hai Phong technical facilities.
MONRE's circular economy directives now mandate biodegradable surfactant content in new registrations. This policy is accelerating rhamnolipid and alkyl polyglucoside substitution for petroleum-based spreader-stickers. Vegetable exporters targeting EU retail channels are reformulating first, given EFSA-equivalent residue scrutiny in German and Dutch procurement specifications.
Drone service providers are unbundling application from product sales, charging per-hectare fees rather than markup on chemical volume. This model disrupts traditional distributor financing relationships in An Giang and Can Tho provinces. Rice mechanization cooperatives represent the fastest adopters, having already invested in GPS-guided seeders that integrate with spray fleet management platforms.
Vietnam Crop Protection Chemicals Market Segmentation
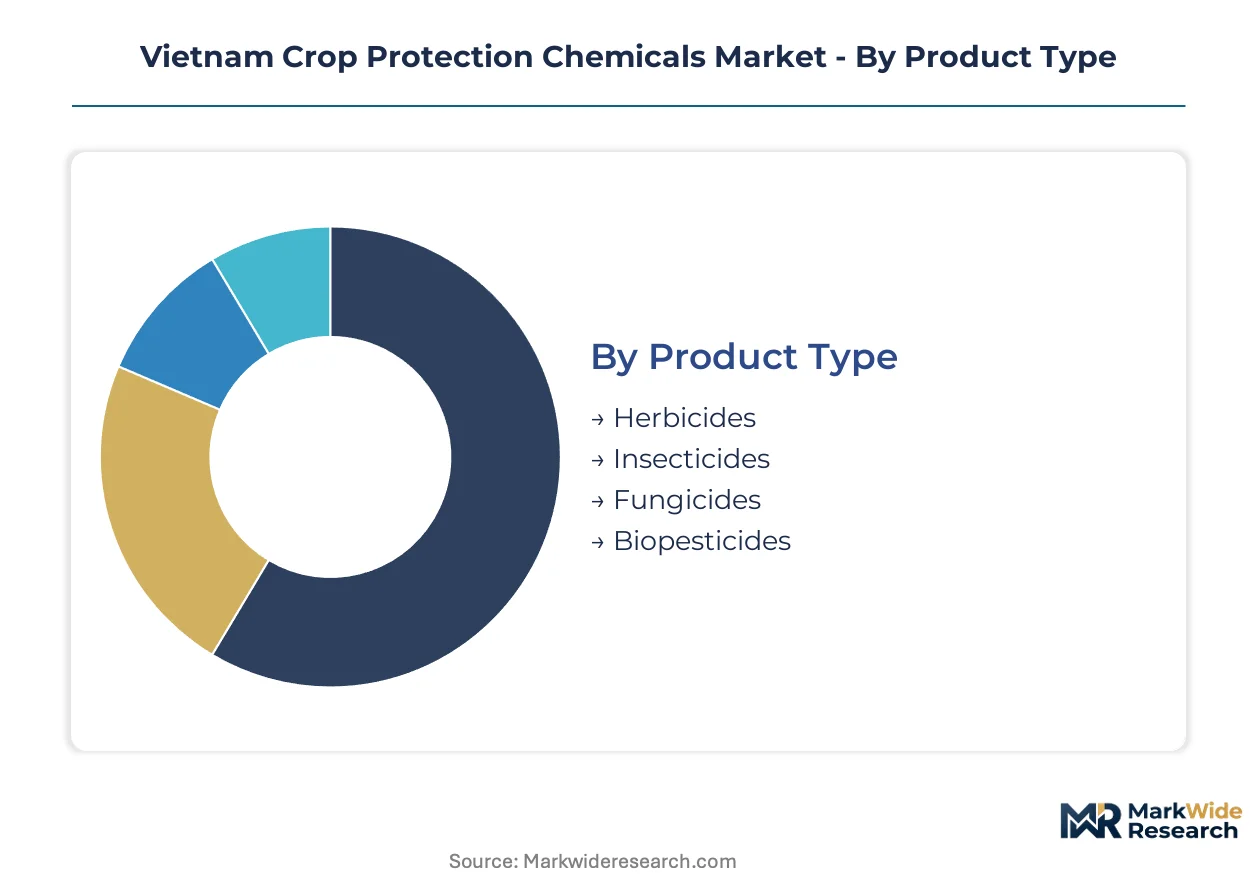
Vietnam's crop protection market segments reflect divergent regulatory burdens across MARD registration pathways. MEE residue enforcement intensity varies sharply by crop destination and formulation chemistry, forcing suppliers to maintain parallel compliance portfolios.
Product Type:
Certification burden concentrates in synthetic molecules facing MARD bioefficacy review and MONRE environmental release permits, while biopesticides navigate accelerated biological registration tracks.
- Herbicides:Pre-emergence and post-emergence formulations dominate rice mechanization corridors. Mekong Delta direct-seeding operations absorb paraquat alternatives and glufosinate-ammonium blends as labor scarcity eliminates manual weeding economics.
- Insecticides:Neonicotinoid and pyrethroid chemistries face tightening MEE aquatic toxicity thresholds. Vegetable export zones near Ho Chi Minh City drive demand for molecules meeting German EFSA-equivalent residue specifications.
- Fungicides:Triazole and strobilurin formulations combat rice blast and vegetable downy mildew under tropical humidity cycles.
- Biopesticides:Bacillus thuringiensis and Trichoderma-based products climb fastest as MEE delistings force portfolio restructuring.
Leading the category by volume: Herbicides. Growing fastest: Biopesticides.
Application:
Cost tier stratification separates intensive commercial cropping from subsistence production, with residue-sensitive export crops commanding premium formulation grades.
- Cereals:Rice dominates hectarage and chemical spend across the Mekong Delta and Red River Delta. Triple-cropping intensity demands systematic herbicide-fungicide programs with MARD-mandated resistance management protocols.
- Fruits:Dragon fruit, mango, and longan operations face EU and China-bound residue scrutiny. Biopesticide penetration runs highest here as MEE maximum residue limits tighten ahead of other crop categories.
- Vegetables:Intensive peri-urban production around Hanoi and Ho Chi Minh City supplies domestic supermarkets and export channels.
- Oilseets:Soybean and peanut cultivation in Central Highlands provinces absorbs selective herbicide programs.
Volume concentration: Cereals. Steepest expansion trajectory: Fruits.
Formulation:
Handler exposure reduction and aerial application compatibility are displacing legacy solvent-based formats across customer segments.
- Liquid:Suspension concentrates and micro-emulsions simplify tank-mixing for drone service providers. An Giang cooperatives prefer these formats for compatibility with GPS-guided spray fleet management platforms.
- Granule:Water-dispersible granules eliminate solvent exposure during mixing. Hai Phong technical facilities are scaling granule production to supply Mekong Delta vegetable cooperatives.
- Powder:Wettable powders retain share in smallholder manual application segments.
- Emulsifiable Concentrate:Petroleum-based solvents face MONRE biodegradable surfactant mandates.
Share leader: Liquid. Gaining share fastest: Granule.
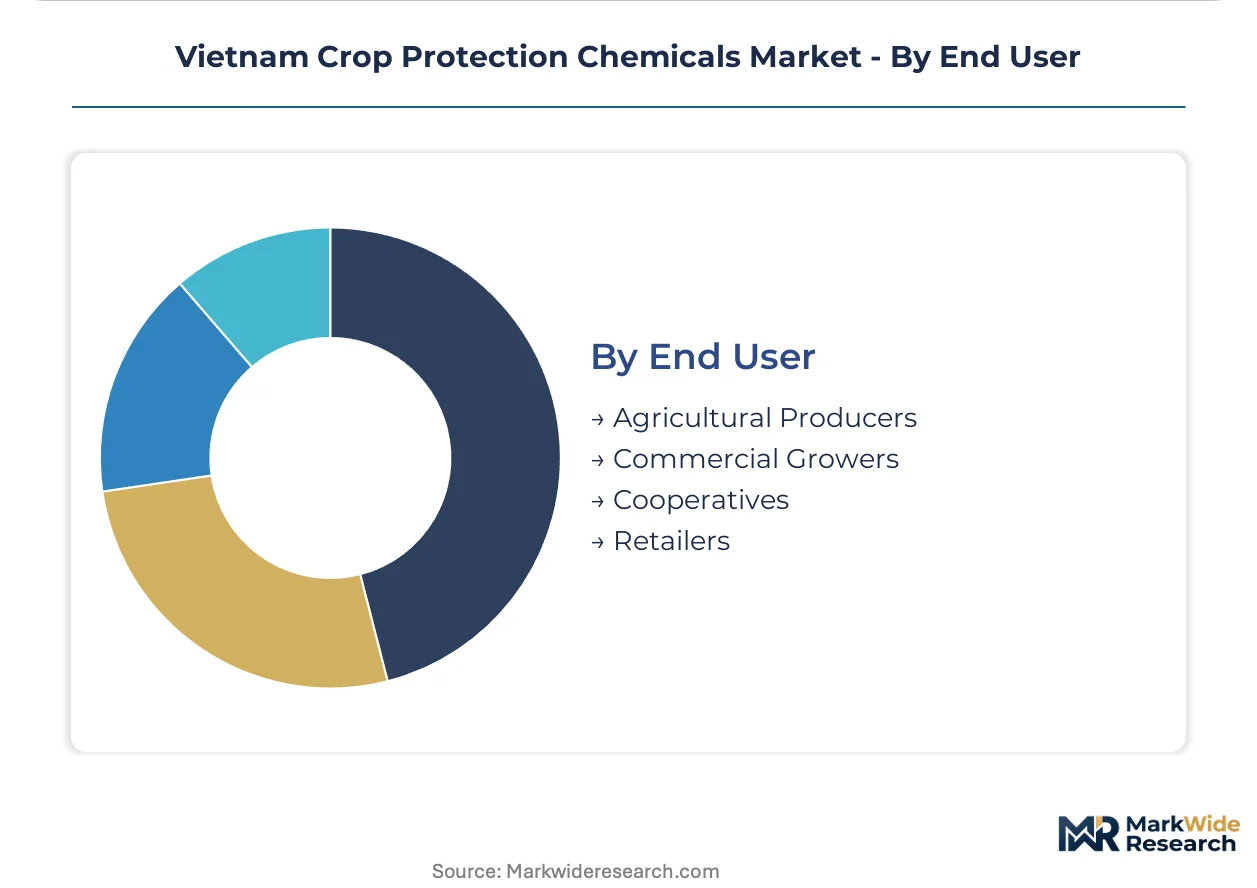
End User:
Customer scale determines procurement channel access, with cooperatives and commercial growers bypassing traditional distributor markups through direct manufacturer relationships.
- Agricultural Producers:Smallholders below two hectares rely on provincial extension networks for MARD-approved product lists. Fragmented purchasing power limits precision application technology deployment.
- Commercial Growers:Large-scale operations in Long An and Tien Giang provinces negotiate direct supply contracts. These entities drive adoption of water-dispersible granules and drone application services.
- Cooperatives:Rice mechanization cooperatives represent the fastest adopters of integrated seed-chemistry bundles and aerial spray fleets.
- Retailers:Provincial agro-input shops face margin compression as drone cooperatives unbundle application from product sales.
Volume concentration: Agricultural Producers. Procurement sophistication climbing fastest: Commercial Growers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Technical-grade active ingredient imports from China and India supply Vietnam's formulator network across the Red River Delta and Mekong Delta corridors. MARD registration protocols and MONRE environmental permits shape commercialization timelines for molecules entering these processing zones.
Mekong Delta
Intensive triple-cropping rice operations in An Giang and Can Tho provinces absorb systematic herbicide-fungicide programs. MEE residue standards for export-bound fruits and vegetables compel rapid biopesticide adoption among dragon fruit and mango cooperatives. Drone spraying services in Long An and Tien Giang are unbundling application from traditional distributor channels.
Red River Delta
Hai Phong technical facilities are scaling water-dispersible granule production to serve vegetable export zones. MARD-mandated resistance management protocols govern fungicide rotation in triple-cropping systems across Hung Yen and Thai Binh provinces. Domestic formulators here are rebalancing toward higher-margin biological formulations as synthetic margins compress.
Central Highlands
Soybean and peanut cultivation in Dak Lak and Lam Dong provinces drives selective herbicide demand for mechanized row cropping. MONRE's biodegradable surfactant mandates are accelerating formulation reformulation among local blending operations. Peri-urban vegetable production around Da Lat supplies domestic supermarkets with residue-sensitive produce.
Southeast Region
Ho Chi Minh City anchors procurement sophistication for vegetable exporters targeting German and Dutch retail channels. EFSA-equivalent residue scrutiny in these markets elevates demand for biopesticide technical grades. Binh Duong and Dong Nai provinces host integrated pest management extension programs incentivizing biocontrol agent adoption.
North Central Coast
Thanh Hoa and Nghe An provinces balance rice production with emerging fruit cultivation for China-bound export. MARD's pending revisions to the positive list of approved active ingredients create portfolio uncertainty for distributors serving these transitional cropping systems. Provincial laboratories here face ISO certification gaps for residue testing infrastructure.
Vietnam Crop Protection Chemicals Market Competitive Landscape
Global majors compete with regional champions across formulation chemistry and distribution reach in Vietnam's crop protection sector. The market structure concentrates around multinational agrochemical conglomerates with established MARD registration portfolios, while Indian and Chinese technical-grade suppliers feed domestic blending capacity. Three archetypes dominate: integrated seed-chemistry bundlers, standalone agrochemical formulators, and biological specialty developers. Competitive moves center on biopesticide registration acceleration and drone application service partnerships.
Within the multinational tier, Bayer AG and BASF SE exemplify integrated players with anchored distribution networks across northern and southern provinces. Syngenta Group occupies a position representing seed-chemistry bundling strategies targeting rice mechanization cooperatives. These three entities sit within the premium registration tier where MARD bioefficacy protocols and MONRE environmental permits create sustained competitive moats against late entrants.
| Leading Market Players |
|---|
| Bayer AG |
| BASF SE |
| Syngenta Group |
| FMC Corporation |
| UPL Limited |
| Corteva Agriscience |
| Sumitomo Chemical Co., Ltd. |
| Nufarm Limited |
| Adama Agricultural Solutions |
| Others |
Value Network & Pricing Analysis
Technical-grade active ingredient imports from China and India cascade through Vietnam's formulator network into three distinct pricing tiers shaped by MARD registration status and MONRE environmental compliance. Currency volatility against the yuan and rupee transmits directly to Red River Delta blending margins, while Mekong Delta cooperatives absorb cost swings through volume-commitment contracts with drone service providers.
Pricing Analysis
Service unbundling separates chemical procurement from aerial application fees, disrupting traditional distributor markups in An Giang and Can Tho provinces. Three-tier pricing structure across premium, standard, and economy levels stratifies by MEE residue certification tier and biopesticide registration completeness. Pricing pressure stems from MONRE's biodegradable surfactant mandates forcing reformulation investments. Smallholder cooperatives below two hectares exhibit highest price sensitivity, while export-oriented commercial growers in Long An prioritize residue compliance over unit cost.
Supply Chain Analysis
Workforce availability constraints in Hai Phong technical facilities and Chinese Jiangsu province manufacturing clusters limit granule production scaling. Geographic supply concentration centers on China and India for technical-grade inputs, with Vietnamese domestic formulators providing downstream blending. Raw material dependencies include paraquat alternatives, glufosinate-ammonium, and rhamnolipid surfactants. Single-source vulnerability from Indian technical-grade suppliers exposes margin structures to shipping cost swings. Distribution runs through provincial agro-input shops facing compression from drone cooperatives unbundling application services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vietnam's crop protection sector has become a vertical-integration race where control over MARD registration timelines and biopesticide technical-grade sourcing determines margin capture. Players are pursuing backward integration into biological active ingredient production to escape import dependency on Chinese and Indian suppliers.
For Market Incumbents: Anchor distribution networks through exclusive drone service partnerships in Mekong Delta rice mechanization corridors. Accelerate biopesticide registration pipelines to preempt MEE delisting events. Defend against emerging Indian technical-grade suppliers by locking multi-year offtake agreements with Red River Delta formulators pivoting to biological formulations.
For New Entrants and Emerging Players: The gap between premium EFSA-equivalent certified products and economy-tier generic synthetics offers entry space for mid-tier biopesticide specialists. Target dragon fruit and mango cooperatives in Tien Giang province facing acute MEE residue compliance pressure. Deploy direct-to-farmer digital platforms bypassing fragmented provincial retailer networks.
For Investors and Strategic Acquirers: MONRE's pending circular economy directives on biodegradable surfactants are the leading indicator that formulation chemistry capabilities will command acquisition premiums. Long-term viability rests on portfolios balanced between synthetic molecules with MARD resistance management protocols and biological registrations with accelerated approval tracks. Target domestic Vietnamese formulators with underutilized Hai Phong technical facilities and established MONRE environmental permits. Watch for MARD positive list revisions as portfolio restructuring triggers.
| Strategic Initiative | Industry Significance |
|---|---|
| Biopesticide Registration Acceleration | MEE residue threshold tightening compresses synthetic molecule commercialization windows against biological alternatives. |
| Backward Integration into Technical-Grade Production | Captive supply of Bacillus thuringiensis and Trichoderma strains reduces exposure to Chinese and Indian import volatility. |
| Drone Application Service Partnerships | An Giang cooperatives adopting GPS-guided spray fleets create direct-to-farmer channels displacing provincial distributor markups. |
| Water-Dispersible Granule Capacity Expansion | Hai Phong technical facilities scaling solid formulation production capture MONRE biodegradable surfactant mandate premiums. |
| Integrated Seed-Chemistry Bundling | Rice mechanization cooperatives demand systematic herbicide-fungicide programs aligned with MARD resistance management protocols. |
Research Methodology
Document review covered MARD registration databases, MONRE environmental release permits, and Vietnam customs trade records, complemented by interviews with formulation plant managers, procurement leads at Mekong Delta cooperatives, distribution channel partners in Red River Delta provinces, and technical R&D directors at biological specialty developers. Secondary validation drew from ASEAN agrochemical trade statistics, FAO pesticide use surveys, and ISO-certified laboratory accreditation records. Bottom-up hectarage and application-rate modeling triangulated against top-down value-chain estimates.
Cross-referencing historical MARD approval timelines with industry panel input on bioefficacy review friction shaped the projection framework across the analysis window. Segmentation dimensions modeled include product type, application crop, formulation chemistry, and end-user scale tier. CAGRs were derived from intensity-of-use coefficients applied to MARD crop hectarage projections, with biopesticide adoption curves calibrated against MEE enforcement trajectory assumptions.
Inputs from provincial extension networks and drone service provider cooperatives were available through the study window; gaps in ISO-certified residue testing infrastructure deployment introduce uncertainty bands around export compliance timing forecasts. Material deviation in MARD positive list revision schedules or MONRE surfactant mandate implementation timelines warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Crop Protection
Vietnam Herbicide Market
Crop Protection
Global Integrated Pest Management (IPM) Pheromones Market
Crop Protection
Sustainable Crop Protection Chemicals Market
Crop Protection
Captan Fungicide Market
Crop Protection
South Korea Crop Protection Chemicals Market
Crop Protection
Spain Crop Protection Chemicals Market
Crop Protection
France Crop Protection Chemicals Market
Crop Protection
North America Crop Protection Chemicals Market
Crop Protection
Europe Fungicide Market
Crop Protection
Pre-Emergent Herbicide Market
Crop Protection
Fumigation Service Market
Crop Protection
Avicides Market
Crop Protection
Acetochlor Herbicide Market
Crop Protection
Global Insecticide Seed Treatment Market
Crop Protection
Metamifop Market
Crop Protection
Brazil Crop Protection Chemical Market