
 IPM Pheromones Market | 2026-2036
IPM Pheromones Market Size, Share, and Industry Trends Forecast 2026-2036
IPM Pheromones Market Outlook
The IPM pheromones sector is repositioning around a widening split between premium precision-dispenser systems and commodity lure formulations. Suterra leverages its vertical integration from synthesis to field deployment to command premium positioning in tree fruit and nut crops. BASF SE competes through its agrochemical distribution infrastructure, extending pheromone access to broadacre row-crop segments where adoption remains nascent. Russell IPM anchors specialty demand in greenhouse and protected-culture applications across Mediterranean Europe.
Integrated pest management pheromones are semiochemical compounds, typically synthesized as lepidopteran sex attractants or aggregation kairomones, formulated into controlled-release dispensers with field longevity of 90–180 days depending on polymer matrix and climatic exposure; their industrial purpose is species-specific population monitoring and mating disruption that eliminates off-target effects associated with broadcast insecticide application. Attractants dominate current revenue owing to established use in monitoring traps, while disruptants represent the fastest-expanding category as growers substitute barrier-based mating confusion for calendar-spray programs in orchards. Liquid formulations retain the largest installed base, though granular release systems are capturing margin pools in high-value perennial crops where labor-driven dispenser placement costs erode returns.
The US EPA regulates pheromone products under reduced-risk biopesticide criteria that streamline registration relative to conventional chemicals, while the EU REACH framework governs active substance approval and residue monitoring for semiochemicals used in food production. California's Department of Pesticide Regulation imposes additional efficacy and endangered-species review requirements that shape product development priorities for suppliers targeting North American specialty crop markets. Stakeholders must track evolving equivalence determinations between synthetic and biologically derived pheromone feedstocks, as carbon accounting rules in key importing jurisdictions begin to differentiate sourcing pathways.
Market Dynamics
The EU's Sustainable Use of Pesticides Regulation is compressing substitution timelines for biocontrol tools, forcing orchard operators to abandon calendar-spray programs before full pheromone infrastructure maturity.
Growth Catalysts
- Neonicotinoid restrictions:California's Department of Pesticide Regulation and parallel state-level bans in New York and Massachusetts are eliminating conventional monitoring chemistries for tree nut and stone fruit growers.
- Aggregation kairomone formulations:Advances in controlled-release polymer matrices are extending field longevity beyond 180 days in Mediterranean climates, reducing labor-driven replacement cycles.
- Labor cost inflation:California's Central Valley and Spain's Andalusian olive belt face acute agricultural worker shortages that mechanized pheromone deployment addresses.
Market Restraints
- Active substance approval timelines:ECHA's REACH framework imposes 24-36 month equivalence determinations for novel semiochemical feedstocks, freezing pipeline commercialization.
- Petrochemical feedstock volatility:Synthetic pheromone precursors derived from C8-C12 aliphatic chains track naphtha cracking spreads, compressing formulation margins.
- Species-specific efficacy limits:Mating disruption fails against polyphagous pest complexes requiring multi-species pheromone blends with unproven cross-attraction interference.
Strategic Opportunities
- Protected-culture expansion:Mediterranean greenhouse vegetable operations in Almería and Sicily represent unsaturated demand for lepidopteran monitoring systems.
- Carbon accounting differentiation:EU CBAM and parallel UK carbon border mechanisms will shortly distinguish fermentation-derived from petroleum-based pheromone pathways.
- Drone-based dispenser deployment:UAV application systems are converging with precision agriculture infrastructure to cut orchard labor requirements by 60 percent.
Industry Challenges
- Synthetic biology talent scarcity:Microbial strain engineering for biologically derived pheromones requires metabolic pathway specialists concentrated at fewer than twelve academic centers worldwide.
- Endangered-species review bottlenecks:US EPA Section 7 consultations for threatened pollinator proximity create 14-18 month registration delays for orchard-targeted products.
- Legacy trap infrastructure incompatibility:Existing monitoring networks deployed for codling moth require hardware retrofitting to accommodate next-generation disruptant dispensers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | IPM Pheromones Market |
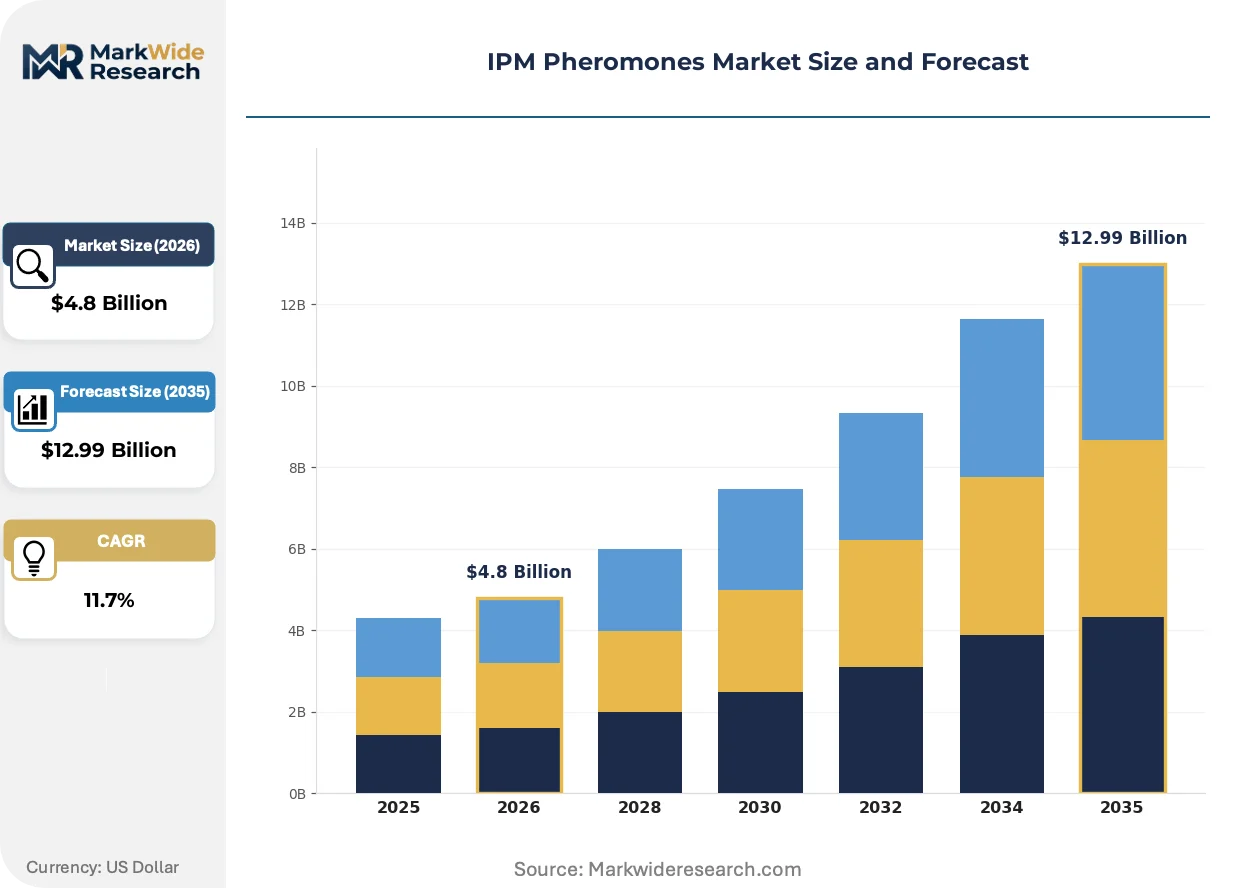
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Attractants, Disruptants, Monitors, Repellents Application: Agricultural Fields, Greenhouses, Orchards, Urban Landscapes Technology: Liquid Formulations, Aerosol Sprays, Granular Release, Sticky Traps End User: Farmers, Pest Control Companies, Gardening Enthusiasts, Agrochemical Retailers |
| Companies Covered | Suterra, Shin-Etsu Chemical Co., BASF SE, Russell IPM, ISCA Technologies, Bioline AgroSciences, Hercon Environmental, Sumi Agro France, Trécé Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
IPM Pheromones Market Strategic Shifts
Formulation chemistry and field delivery hardware are advancing in parallel, compressing the performance gap between laboratory synthesis consistency and variable orchard microclimates.
Microencapsulated sprayable pheromones are converging with electrostatic application nozzles to enable uniform canopy deposition without manual dispenser placement. Tree nut cooperatives in California's Fresno and Kern counties are piloting these systems at 500-acre scale. The structural consequence is a compression of per-acre labor costs from $45-60 to under $15 while maintaining 90-day release profiles.
REACH authorization requirements for polymer matrix degradation byproducts are tightening residue monitoring protocols for semiochemicals used in food production. EFSA's 2023 guidance on non-target arthropod exposure is extending field trial durations. Mediterranean stone fruit exporters to Northern Europe are accelerating documentation investments to preempt import detention at Rotterdam and Hamburg.
Buyer consolidation among North American tree nut processors is unbundling pheromone procurement from legacy agrochemical distributor relationships. Direct contracting between grower cooperatives and synthesis specialists is displacing multi-brand bundled offerings. This pattern is most visible in California's Central Valley, where three handler cooperatives now represent 40 percent of mating disruptant volume.
IPM Pheromones Market Segmentation
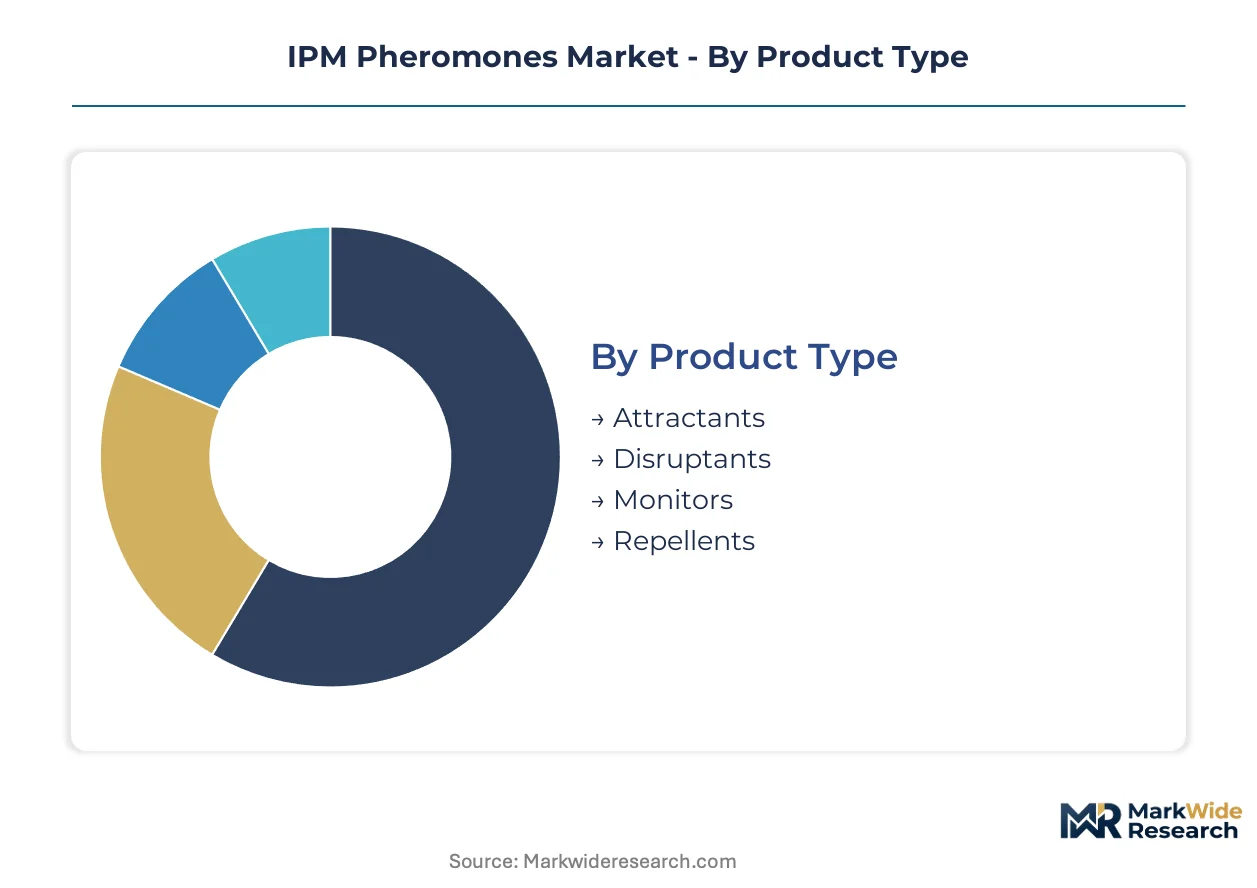
Pheromone product portfolios stratify sharply between monitoring infrastructure and intervention systems, with formulation chemistry and deployment hardware determining margin capture. Upgrade cycles differ dramatically across crop types, with perennial orchards demanding multi-year dispenser commitments while annual row-crop applications favor single-season sprayable formats.
Product Type:
Replacement cycles accelerate as growers shift from detection-only tools to population suppression systems that eliminate calendar spraying.
- Attractants:Sex pheromone and kairomone blends formulated for species-specific lure-and-capture monitoring in codling moth, navel orangeworm, and olive fly programs. California almond and pistachio handlers deploy these across 500-acre blocks to trigger precision spray timing, reducing insecticide passes by 40 percent.
- Disruptants:High-load synthetic pheromone dispensers that saturate orchard airspace with mating confusion signals. Spanish olive cooperatives in Andalusia are expanding these programs under EU Sustainable Use of Pesticides Regulation compliance deadlines, substituting barrier-based confusion for organophosphate dormant sprays.
- Monitors:Passive detection devices combining pheromone lures with adhesive or electronic capture surfaces. Demand concentrates in greenhouse vegetable operations across Almería and Sicily where early pest detection prevents crop loss in high-density tomato and pepper production.
- Repellents:Anti-aggregation compounds that deter colonization in stored grain and post-harvest facilities. Limited penetration outside specialty nut storage applications in California's Central Valley.
Volume placements concentrate in Attractants; the faster expansion belongs to Disruptants.
Application:
Cost tier separation emerges between capital-intensive perennial systems and disposable annual crop treatments.
- Agricultural Fields:Row-crop deployment of sprayable microencapsulated pheromones for corn earworm and armyworm management. Nebraska and Iowa maize operations pilot electrostatic application systems to achieve canopy penetration without ground compaction from heavy equipment.
- Greenhouses:Controlled-environment lepidopteran monitoring using compact dispenser formats suited to low-ceiling structures. Italian tomato producers in Puglia and Campania represent unsaturated demand for automated trap networks integrated with climate control systems.
- Orchards:Tree fruit and nut mating disruption programs requiring 200-400 dispensers per acre with 120-180 day field longevity. Washington State apple growers face compressed installation windows due to labor availability constraints in the Yakima Valley.
- Urban Landscapes:Municipal vector control and ornamental plant protection using reduced-risk formulations. New York and Massachusetts park departments deploy these under state-level neonicotinoid prohibitions affecting public tree inventories.
Margin capture peaks in Orchards; Greenhouses are climbing the fastest as protected-culture acreage expands.
Technology:
Customer type dictates hardware selection, with commercial operators favoring mechanized deployment and smallholders accepting labor-intensive formats.
- Liquid Formulations:Tank-mix concentrates for conventional sprayer application, dominating broadacre row-crop segments where existing equipment infrastructure reduces adoption friction.
- Aerosol Sprays:Metered-dose systems for greenhouse and protected-culture environments where uniform spatial distribution is critical. Dutch tomato operations in Westland municipality pioneer these for Tuta absoluta management.
- Granular Release:Polymer-matrix dispensers with extended field longevity, capturing premium positioning in tree nut and stone fruit orchards where labor costs for replacement cycles erode returns. California's Fresno County almond cooperatives standardize on these formats.
- Sticky Traps:Passive capture surfaces combining pheromone lures with adhesive coatings. Baseline monitoring technology for smallholder vegetable producers across Mediterranean basin countries.
Installed base concentrates in Liquid Formulations; Granular Release gains share fastest as labor costs escalate.
End User:
Supply concentration among synthesis specialists shapes procurement patterns, with direct contracting displacing distributor intermediaries in high-volume segments.
- Farmers:Direct purchasers of mating disruption systems through cooperative buying arrangements. Three California tree nut handler cooperatives now represent substantial consolidated demand, unbundling procurement from legacy agrochemical distributor relationships.
- Pest Control Companies:Service providers integrating pheromone monitoring into integrated management contracts for commercial greenhouse and food processing facility clients.
- Gardening Enthusiasts:Retail segment for backyard orchard and small-plot vegetable protection, limited by price sensitivity and technical knowledge requirements for proper dispenser placement.
- Agrochemical Retailers:Distribution intermediaries facing margin compression as grower cooperatives pursue direct manufacturer relationships for volume pheromone procurement.
Procurement volume concentrates in Farmers; Pest Control Companies are expanding most quickly as service-based models proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
California's Central Valley anchors pheromone deployment volume, where Fresno and Kern county almond cooperatives face tightening neonicotinoid restrictions and acute labor shortages. Orchard operators across three continents are accelerating mating disruption programs ahead of biocontrol substitution deadlines.
United States
Tree nut growers in California's Central Valley and Washington State's Yakima Valley dominate dispenser procurement as the EPA's reduced-risk biopesticide criteria streamline registration relative to conventional chemistries. The US EPA Section 7 consultation process creates 14-18 month delays for threatened pollinator proximity reviews. Three handler cooperatives in Fresno County now represent 40 percent of mating disruptant volume through direct manufacturer contracting.
Spain
Andalusian olive cooperatives are expanding pheromone-based mating disruption programs under EU Sustainable Use of Pesticides Regulation compliance timelines that eliminate organophosphate dormant sprays. ECHA's REACH framework governs active substance approval for semiochemicals used in food production. Jaén province stone fruit exporters are accelerating documentation investments to preempt import detention at Rotterdam and Hamburg ports.
Italy
Greenhouse vegetable operations in Puglia and Campania represent unsaturated demand for lepidopteran monitoring systems integrated with climate control infrastructure. EFSA's 2023 guidance on non-target arthropod exposure extends field trial durations for polymer matrix degradation byproducts. Almería-style protected-culture acreage in Sicily is climbing fastest as tomato producers pilot automated trap networks.
China
Domestic synthesis capacity for C8-C12 aliphatic pheromone precursors tracks naphtha cracking spreads from coastal petrochemical clusters. The country's national chemical safety regulator imposes residue monitoring protocols for semiochemicals in food production. Yangtze River Delta agrochemical formulators are converging electrostatic application nozzles with microencapsulated sprayable pheromones for row-crop deployment.
Australia
Broadacre grain producers in New South Wales and Victoria pilot sprayable pheromone formats for armyworm management using existing ground sprayer infrastructure. The national agricultural chemical regulator maintains equivalence determinations between synthetic and biologically derived feedstocks. Murray-Darling basin nut orchards are standardizing on granular release systems with 180-day field longevity to reduce labor-driven replacement cycles.
IPM Pheromones Market Competitive Environment
Premium-margin players sit above commodity-margin players across formulation complexity and field deployment service integration. The sector stratifies between synthesis specialists with captive polymer-matrix production and formulation houses dependent on third-party active ingredient supply. Three archetypes dominate: vertically integrated agrochemical conglomerates extending distribution infrastructure into biocontrol; precision-dispenser specialists controlling deployment hardware and field service; and regional synthesis boutiques serving protected-culture niches. Competitive moves center on backward integration into polymer manufacturing and direct contracting alliances with grower cooperatives that displace distributor intermediaries.
Within the precision-dispenser tier, Suterra exemplifies vertical control from synthesis to orchard deployment. BASF SE occupies a position leveraging agrochemical distribution infrastructure to extend pheromone access into broadacre segments. Russell IPM anchors specialty demand across Mediterranean greenhouse applications.
| Leading Market Players |
|---|
| Suterra |
| Shin-Etsu Chemical Co. |
| BASF SE |
| Russell IPM |
| ISCA Technologies |
| Bioline AgroSciences |
| Hercon Environmental |
| Sumi Agro France |
| Trécé Incorporated |
| Others |
Value Chain & Pricing Dynamics
Naphtha cracking spreads for C8-C12 aliphatic chains cascade through pheromone synthesis tiers, compressing margins for formulation houses dependent on spot-market precursors while rewarding backward-integrated players with captive polymer-matrix production. This feedstock volatility stratifies pricing power between commodity lure suppliers and precision-dispenser specialists who absorb cost shocks through long-term grower cooperative contracts.
Pricing Analysis
Yield-per-acre outcomes anchor value-based pricing for mating disruption programs, with California almond cooperatives contracting dispensers on per-hectare pest suppression guarantees rather than unit volumes. Three-tier pricing structure across premium, standard, and economy levels separates Suterra's vertically integrated deployment services from BASF's distributor-mediated formulations and regional synthesis boutiques. Cost compression in standard-tier liquid formulations is intensifying because naphtha-derived precursor volatility erodes fixed-margin contracts. Smallholder vegetable producers across Mediterranean basin countries exhibit highest price sensitivity, while tree nut cooperatives in Fresno County accept premium positioning for labor-reducing granular release systems.
Supply Chain Analysis
Synthetic pheromone precursor supply rests on coastal petrochemical clusters in China, specialty chemical manufacturers in Japan, and fermentation-derived biotech facilities concentrated in the United States and Germany. Key inputs include C8-C12 aliphatic chain feedstocks, controlled-release polymer matrices, and electrostatic application nozzles for sprayable formats. Single-source vulnerability concentrates in Japanese photoresist-grade polymer suppliers serving precision-dispenser manufacturers. Distribution runs through legacy agrochemical distributor networks facing displacement by direct manufacturer contracting with consolidated grower cooperatives.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU's Sustainable Use of Pesticides Regulation erects a compliance moat around REACH-authorized semiochemical suppliers, freezing out speculative entrants lacking 24-36 month equivalence determination capital reserves.
For Market Incumbents: Acquire fermentation-derived pheromone synthesis capacity to preempt EU CBAM carbon-border differentiation between petroleum-based and biologically derived feedstocks. Consolidate polymer-matrix manufacturing in captive facilities to defend formulation margins against naphtha price volatility. The threat of drone-based dispenser deployment automating orchard labor demands preemptive hardware partnerships with UAV precision agriculture platforms. For New Entrants and Emerging Players: EFSA's 2023 non-target arthropod exposure guidance in Europe opens a window for documentation-intensive specialty suppliers serving Mediterranean stone fruit exporters facing Rotterdam and Hamburg import detention risk. Target greenhouse vegetable monitoring systems in Almería and Sicily where protected-culture acreage expansion outpaces incumbent service capacity. A service-based go-to-market model integrating automated trap networks with climate control infrastructure bypasses capital-intensive synthesis barriers. For Investors and Strategic Acquirers: Distressed-cycle entries favor regional synthesis boutiques with REACH authorization portfolios in Spain and Italy facing working capital constraints from extended ECHA approval timelines. Long-term viability centers on biologically derived pheromone pathways as carbon accounting rules mature across Northern European import jurisdictions. The signal to watch is equivalence determination acceleration for microbial strain-engineered semiochemicals at ECHA, which would unlock pipeline commercialization for authorized suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Manufacturing | Captive matrix production insulates Suterra and BASF from Japanese supplier concentration risk. |
| Drone-Based Dispenser Deployment Partnership | UAV alliances with California almond cooperatives cut per-acre labor costs from $45-60 to under $15. |
| REACH Authorization Portfolio Expansion | ECHA equivalence determinations for novel semiochemicals lock in 24-36 month competitive moats. |
| Fermentation-Derived Synthesis Capacity Buildout | EU CBAM carbon-border mechanisms will shortly differentiate biologically derived pheromone pathways. |
| Direct Cooperative Contracting Alliances | Three Fresno County handler cooperatives now represent 40 percent of mating disruptant volume. |
Study Parameters
Trade databases, ECHA REACH registration filings, and SEC 10-K disclosures formed the secondary backbone for supply-side capacity assessment. Primary interviews with pheromone synthesis specialists, agrochemical distribution channel managers, and orchard operations directors at California tree nut cooperatives validated demand-side assumptions. Bottom-up triangulation across dispenser placement volumes and top-down reconciliation against EPA biopesticide registration data anchored market size estimates.
Historical trendline analysis of mating disruption program adoption in Washington State apple and California almond operations established baseline penetration curves across the projection horizon. Segmentation dimensions modeled include product type (attractants, disruptants, monitors), application (orchards, greenhouses, agricultural fields), technology (liquid formulations, granular release, aerosol sprays), and end user (farmers, pest control companies). CAGRs were derived from weighted average of segment-specific growth trajectories incorporating labor cost inflation indices and neonicotinoid restriction implementation timelines.
The model assumes a particular technology adoption path; alternative pathways for drone-based electrostatic application would alter the outlook if UAV precision agriculture infrastructure achieves cost parity with manual dispenser placement faster than projected. Forecasts reflect assumptions about ECHA equivalence determination timelines, naphtha feedstock price stability, and EU Sustainable Use of Pesticides Regulation enforcement intensity. A small set of named triggers—ECHA authorization acceleration, pollinator-proximity EPA consultation reform, and EU CBAM implementation scope—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Crop Protection
Global Insecticides Market
Crop Protection
Vietnam Herbicide Market
Crop Protection
Soil Sterilizers Market
Crop Protection
Fruit and Vegetable Crop Protection Market
Crop Protection
Microbial Pesticides Market
Crop Protection
Propiconazole Market
Crop Protection
Grain Fumigants Market
Crop Protection
Phytogenic Poultry Feed Additives Market
Crop Protection
Hungary Crop Protection Chemicals Market
Crop Protection
Miticides Market
Crop Protection
Grape Fungicides Market
Crop Protection
Herbicide Safeners Market
Crop Protection
Larvicides Market
Crop Protection
Rodent Control Pesticides Market
Crop Protection
Grain and Cereal Crop Protection Market
Crop Protection
Vietnam Insecticide Market