
 China Fungicide Market | 2026-2036
China Fungicide Market Size, Share, and Industry Trends Forecast 2026-2036
China Fungicide Market Insights
Specialty vegetable cooperatives is rotating toward higher-efficacy systemic products as grain-focused state farms cede procurement share. Syngenta Group leverages its Jiangsu manufacturing base to sustain domestic triazole supply. Bayer AG anchors its position through biological fungicide R&D partnerships with Chinese agricultural institutes. Jiangsu Yangnong Chemical Co Ltd dominates chloronitrile production capacity in the Yangtze River Delta.
China fungicides comprise synthetic or biological active ingredients formulated to inhibit fungal spore germination, mycelial growth, or sporulation through modes such as ergosterol biosynthesis inhibition or mitochondrial respiration disruption; these compounds protect yield quantity and quality in food and feed crops. Triazoles and strobilurins command the largest volume pools among product types due to their established efficacy against powdery mildew and rust pathogens in wheat and rice. Emulsifiable concentrate formulations retain cost advantages in direct sales channels serving large provincial distributors, though liquid suspension concentrates gain share among precision-spraying adopters.
China's Ministry of Agriculture and Rural Affairs enforces GB 2763 maximum residue limits that determine which fungicide actives gain crop registration approval, while the Ministry of Ecology and Environment monitors manufacturing discharge under dual carbon compliance timelines. SAMR oversees product quality certification that gates market access for imported and domestic formulations alike. Stakeholders must weigh regulatory registration timelines against the accelerating substitution pressure from microbial antagonist products.
Market Dynamics
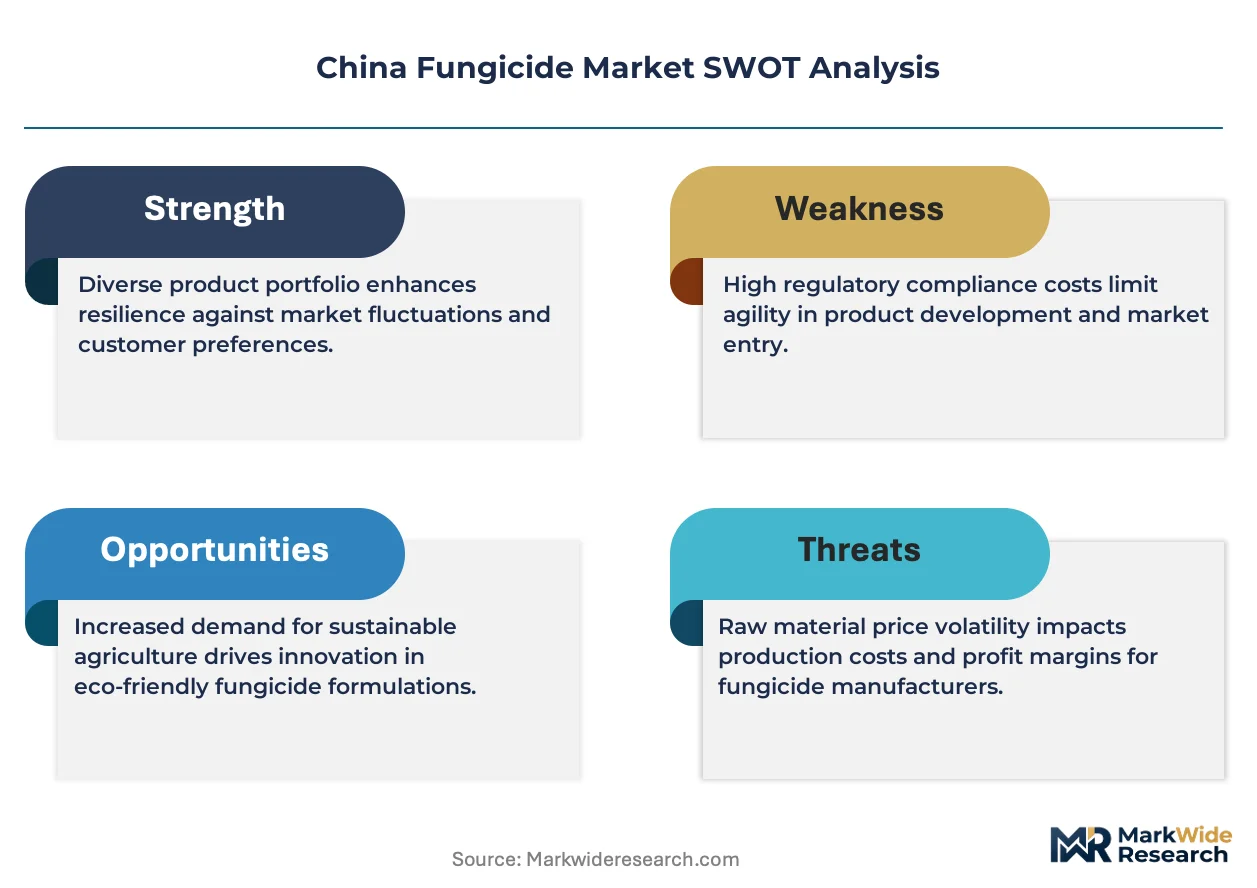
China's fungicide sector is pivoting around tightening GB 2763 residue limits that force active ingredient substitution faster than registration timelines permit, compressing product lifecycles while specialty crop growers absorb compliance costs.
Growth Catalysts
- Dual carbon compliance timelines:MEE discharge mandates accelerate closure of antiquated synthesis facilities, concentrating viable supply among compliant producers and tightening effective capacity.
- Biological antagonist R&D partnerships:Agricultural institutes in Jiangsu and Shandong are co-developing microbial formulations that bypass synthetic residue concerns entirely.
- Precision-spraying hardware penetration:Drone applicator fleets in Hebei and Henan provinces favor liquid suspension concentrate formulations over legacy emulsifiable concentrates.
Market Restraints
- Active ingredient import dependency:Technical-grade triazole intermediates concentrate among Yangtze River Delta suppliers, exposing formulators to single-source risk.
- Registration timeline friction:SAMR crop-specific approval cycles extend 18-24 months, lagging pathogen resistance evolution in wheat and rice belts.
- Biological substitute efficacy gaps:Microbial antagonists lack consistent performance against Fusarium head blight in humid southern provinces.
Strategic Opportunities
- Northwest specialty vegetable expansion:Gansu and Xinjiang greenhouse clusters seek residue-compliant fungicides for export-oriented tomato and pepper production.
- Carbon credit monetization:MEE low-carbon manufacturing certification unlocks preferential financing for biological production facilities.
- Direct cooperative procurement platforms:Digital tender systems connect Jiangsu formulators with county-level grower cooperatives, bypassing provincial distributor markups.
Industry Challenges
- Formulation chemist scarcity:Yangtze River Delta employers compete for talent capable of stabilizing biological actives in aqueous suspensions.
- Legacy EC inventory stranding:Distributor warehouses in Shandong hold emulsifiable concentrate stocks that precision-spraying adopters reject.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Fungicide Market |
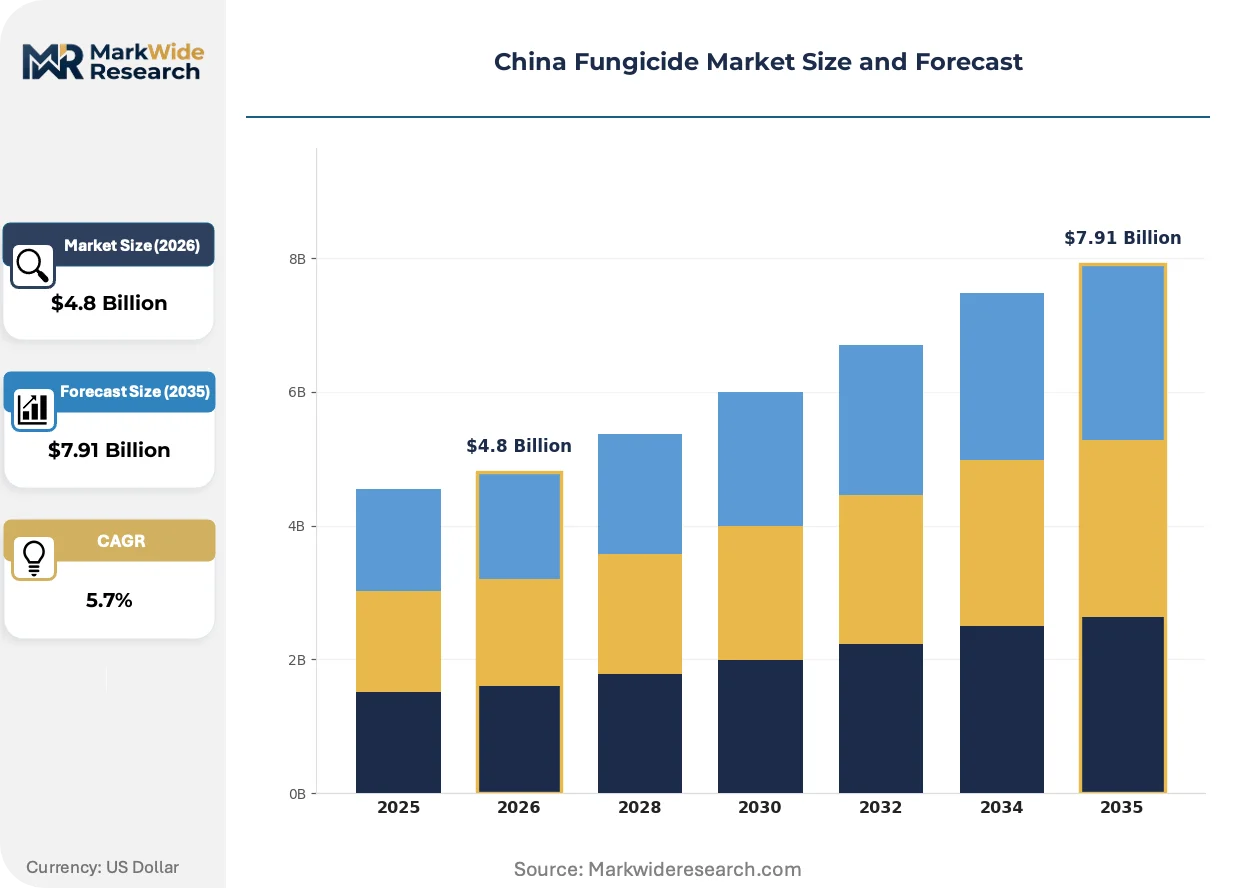
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Triazoles, Azoles, Strobilurins, Chloronitriles Application: Crops, Turf, Ornamentals, Seed Treatment Formulation Type: Liquid, Powder, Granules, Emulsifiable Concentrate Distribution Channel: Direct Sales, Retail, Online, Wholesalers |
| Companies Covered | Syngenta Group, Bayer AG, BASF SE, Nutrichem Co Ltd, Rainbow Agro, Jiangsu Yangnong Chemical Co Ltd, Wynca Group, UPL Limited, FMC Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Fungicide Market Trends and Innovations
Formulation chemistry and application hardware are converging to redefine efficacy benchmarks, while regulatory stringency compresses permissible active ingredient portfolios faster than biological alternatives can scale.
Nano-dispersion suspension concentrate technology is displacing conventional emulsifiable concentrates in high-value vegetable production. Greenhouse operators in Shandong province are adopting these formulations to prevent nozzle clogging in automated misting systems. The shift is compressing profit pools for legacy EC manufacturers unable to retrofit synthesis lines.
GB 2763-2021 maximum residue limit revisions have eliminated several organophosphate fungicides from wheat registration eligibility. MEE enforcement of these standards through provincial agricultural bureaus is forcing rapid label amendments. Northern grain belt distributors are clearing non-compliant inventory through distressed channel sales ahead of planting seasons.
County-level grower cooperatives are consolidating procurement authority previously dispersed among individual township distributors. This concentration enables direct technical service relationships with Jiangsu-based formulators. The pattern is most pronounced in vegetable-producing counties surrounding Weifang, where cooperative membership exceeds ten thousand hectares under integrated pest management protocols.
China Fungicide Market Segmentation
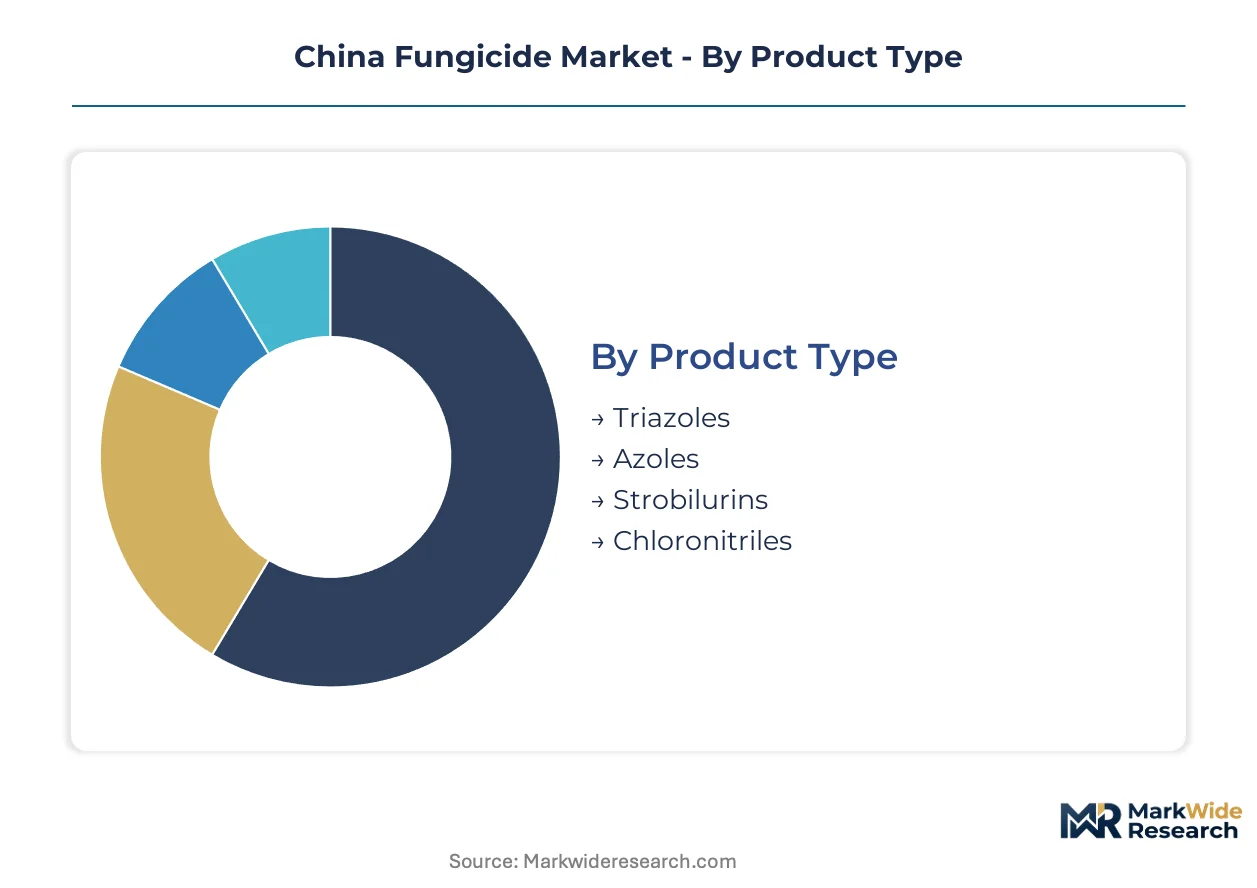
China's fungicide market segments reflect divergent pressure points across the regulatory-compliance axis and application-technology frontier. Distinct procurement patterns emerge between grain-belt state farms and export-oriented specialty vegetable operations.
Product Type:
Domestic formulation demand concentrates in Jiangsu and Shandong provinces, while export-oriented technical-grade output flows through Yangtze River Delta port infrastructure.
- Triazoles:Systemic ergosterol biosynthesis inhibitors deliver curative and protective action against powdery mildew and rust pathogens. Jiangsu Yangnong Chemical Co Ltd anchors domestic production capacity, though technical-grade intermediates concentrate among single-source suppliers exposing formulators to disruption risk.
- Strobilurins:Mitochondrial respiration disruptors command premium positioning in high-value vegetable protection. Greenhouse operators in Shandong province favor these actives for automated misting system compatibility, driving suspension concentrate formulation demand.
- Azoles:Broad-spectrum demethylation inhibitors serve wheat and rice belt applications under tightening GB 2763 residue surveillance.
- Chloronitriles:Contact-action protectants retain cost advantages in direct sales channels serving large provincial distributors.
Triazoles hold the largest share; momentum sits with strobilurins.
Application:
Cost-tier stratification separates residue-sensitive export operations from price-driven domestic grain production.
- Crops:Wheat, rice, and specialty vegetable applications dominate volume consumption. County-level grower cooperatives in Weifang-surrounding counties consolidate procurement authority exceeding ten thousand hectares under integrated pest management protocols, enabling direct technical service relationships with Jiangsu formulators.
- Seed Treatment:Pre-plant fungal protection commands premium pricing in hybrid seed production zones. Gansu and Xinjiang greenhouse clusters seek residue-compliant formulations for export-oriented tomato and pepper production, absorbing compliance cost premiums.
- Turf:Golf course and sports field maintenance drives concentrated demand in coastal municipality clusters.
- Ornamentals:Nursery and floriculture operations in peri-urban zones favor biological antagonist alternatives to bypass synthetic residue concerns.
Crops command absolute volume; seed treatment is climbing the fastest.
Formulation Type:
Application-hardware penetration reshapes formulation preferences across precision-spraying adopters versus legacy equipment bases.
- Liquid:Suspension concentrate formulations prevent nozzle clogging in drone applicator fleets across Hebei and Henan provinces. Nano-dispersion technology displaces conventional alternatives in high-value vegetable production, compressing profit pools for manufacturers unable to retrofit synthesis lines.
- Emulsifiable Concentrate:Legacy formulations retain cost advantages in direct sales channels though precision-spraying adopters reject distributor warehouse stocks in Shandong.
- Powder:Dry flowable formats serve manual application in smallholder rice production zones.
- Granules:Soil-incorporated delivery systems address root-rot complexes in protected vegetable cultivation.
Liquid formulations hold the largest share; momentum sits with suspension concentrate variants.
Distribution Channel:
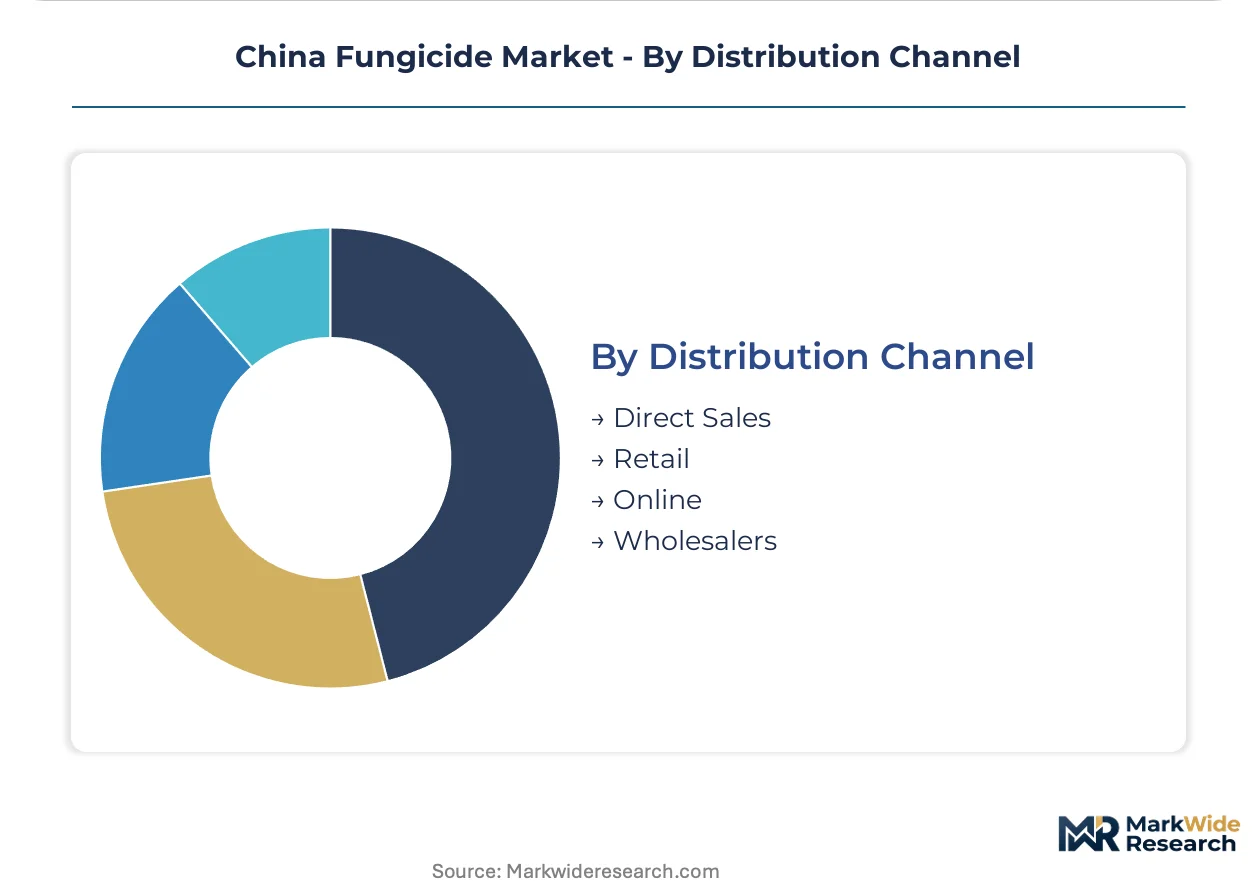
Customer-type concentration drives channel bifurcation between consolidated cooperative procurement and fragmented retail access.
- Direct Sales:Jiangsu formulators bypass provincial distributor markups through digital tender systems connecting with county-level grower cooperatives. This channel captures volume concentration from specialty vegetable operations consolidating previously dispersed township procurement.
- Wholesalers:Provincial distributors in northern grain belts clear non-compliant inventory through distressed channel sales ahead of planting seasons following GB 2763-2021 revisions.
- Retail:Township-level agrochemical shops serve smallholder fragmentation in rice and wheat belts.
- Online:E-commerce platforms gain traction among precision-spraying hardware adopters seeking technical specifications and bulk pricing transparency.
Direct sales hold the largest share; online channels are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Yangtze River Delta port infrastructure anchors fungicide formulation distribution across eastern China, channeling technical-grade actives from Jiangsu synthesis clusters into domestic and export markets.
Jiangsu Province
Precision-spraying hardware adoption drives suspension concentrate demand among greenhouse operators in the Yangtze River Delta. MEE discharge mandates under dual carbon timelines accelerate antiquated facility closures, concentrating viable production among compliant chloronitrile and triazole manufacturers. Nanjing and Changzhou host formulation R&D partnerships between agricultural institutes and biological antagonist developers.
Shandong Province
County-level grower cooperatives surrounding Weifang consolidate procurement authority exceeding ten thousand hectares under integrated pest management protocols. GB 2763-2021 residue limit revisions force rapid label amendments for wheat belt distributors clearing non-compliant inventory. Qingdao port infrastructure supports export-oriented technical-grade shipments to Southeast Asian markets.
Hebei Province
Drone applicator fleets across the North China Plain favor liquid suspension concentrate formulations over legacy emulsifiable concentrates. SAMR crop-specific registration timelines lag pathogen resistance evolution in winter wheat production zones. Baoding and Shijiazhuang agrochemical distributors pivot toward direct cooperative procurement platforms.
Gansu Province
Northwest specialty vegetable greenhouse clusters seek residue-compliant fungicides for export-oriented tomato and pepper production. Dual carbon compliance certification unlocks preferential financing for biological production facilities in the Lanzhou-Xining economic zone. Hexi Corridor irrigation infrastructure supports high-value protected cultivation expansion.
Xinjiang Uygur Autonomous Region
Export-oriented greenhouse agriculture in the Tarim Basin absorbs compliance cost premiums for GB 2763-compliant formulations. Urumqi and Kashgar logistics hubs connect Central Asian markets with Chinese technical-grade supply. Cotton and tomato seed treatment demand drives pre-plant fungal protection procurement in oasis agricultural zones.
China Fungicide Market Competitive Landscape
Concentration sits with domestic chemical conglomerates and multinational agrochemical divisions operating Jiangsu-based manufacturing assets. The sector exhibits tiered structure: Yangtze River Delta formulators with captive technical-grade supply, multinational R&D partnerships leveraging biological platforms, and provincial distributors consolidating cooperative procurement relationships. Two dominant competitive moves define positioning: backward integration into chloronitrile intermediate production, and digital tender systems bypassing traditional wholesale markups.
Among multinational agrochemical divisions, Syngenta Group, Bayer AG, and BASF SE exemplify the R&D partnership archetype, anchoring biological fungicide development through Chinese agricultural institute collaborations. Jiangsu Yangnong Chemical Co Ltd represents domestic manufacturing concentration, occupying a position within the technical-grade intermediate supply tier that exposes downstream formulators to single-source risk. These three entities collectively illustrate the competitive tension between global biological platform investment and regional synthesis capacity consolidation under tightening MEE discharge enforcement.
| Leading Market Players |
|---|
| Syngenta Group |
| Bayer AG |
| BASF SE |
| Nutrichem Co Ltd |
| Rainbow Agro |
| Jiangsu Yangnong Chemical Co Ltd |
| Wynca Group |
| UPL Limited |
| FMC Corporation |
| Others |
Pricing and Supply Chain Analysis
Technical-grade triazole intermediate production in the Yangtze River Delta generates scale economies that compress unit costs for compliant manufacturers while stranding antiquated synthesis facilities under MEE discharge enforcement. This capacity consolidation simultaneously elevates price floors for downstream formulators exposed to single-source supply risk and tightens margin structures across the chloronitrile value chain.
Pricing Analysis
Volume-discount tiering separates provincial distributor contracts from direct cooperative procurement platforms, with county-level grower cooperatives in Shandong absorbing compliance cost premiums for residue-compliant formulations. Three-tier pricing structure across premium suspension concentrates, standard emulsifiable concentrates, and economy-grade chloronitriles reflects certification grade and after-sales technical service bundling. Cost compression in legacy EC tiers is intensifying because precision-spraying adopters reject distributor warehouse stocks, while biological formulation buyers exhibit lowest price sensitivity due to export-market residue requirements.
Supply Chain Analysis
Strategic stockpiling of technical-grade intermediates prevails among Jiangsu formulators seeking to buffer single-source vulnerability in Yangtze River Delta chloronitrile supply. Domestic production draws from aniline and chlorine feedstocks concentrated in Shandong and Jiangsu petrochemical clusters, with formulation chemistry talent scarcity in the Yangtze River Delta constituting the primary structural risk. Distribution runs through provincial agricultural bureaus monitoring GB 2763 compliance alongside direct digital tender systems connecting manufacturers with consolidated cooperative procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's fungicide sector operates as a regulatory-entrenchment defensive moat, where SAMR registration timelines and MEE discharge compliance create switching costs that protect incumbent positions while constraining new entrant velocity.
For Market Incumbents: Consolidate backward integration into chloronitrile intermediate production to neutralize single-source exposure in Yangtze River Delta technical-grade supply. Capture channel control through digital tender platforms that bypass provincial distributor markups, while expanding biological R&D partnerships with Jiangsu agricultural institutes to preempt microbial antagonist substitution threats. For New Entrants and Emerging Players: Lead with residue-compliant biological formulations targeting Gansu and Xinjiang export-oriented greenhouse clusters where compliance cost absorption is highest. The northwest specialty vegetable expansion corridor offers the most penetrable geographic white space, with carbon credit monetization through MEE low-carbon certification providing a differentiated go-to-market angle against synthetic incumbents. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among Jiangsu-based formulators with captive technical-grade supply and direct cooperative procurement relationships. Long-term viability centers on acquisition targets possessing dual carbon compliance certification and suspension concentrate formulation capabilities, with the inflection signal to monitor being SAMR acceleration of biological product registration timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Chloronitrile Intermediates | Captive supply of technical-grade actives neutralizes Yangtze River Delta single-source concentration risk. |
| Biological Antagonist R&D Partnership | Collaborations with Jiangsu agricultural institutes bypass GB 2763 residue concerns entirely. |
| Suspension Concentrate Capacity Expansion | Nano-dispersion retrofitting captures precision-spraying adoption in Hebei and Henan drone fleets. |
| Direct Cooperative Procurement Platform | Digital tender systems connect Jiangsu formulators with Weifang-surrounding county cooperatives. |
| MEE Low-Carbon Certification Program | Carbon credit monetization unlocks preferential financing for biological production facilities. |
Research Methodology
The analysis maps triazole, strobilurin, azole, and chloronitrile product categories, each validated through plant managers at Jiangsu formulation facilities, procurement leads at Shandong grower cooperatives, distribution channel partners in Hebei, and technical R&D directors at agricultural institutes. Primary interview findings triangulate against customs and trade data, Ministry of Agriculture registration databases, MEE discharge compliance records, and SAMR quality certification filings. Bottom-up volume estimates from county-level cooperative procurement consolidate with top-down sectoral spending patterns.
Consistency checks validate volume and value outputs against Yangtze River Delta production capacity disclosures and provincial agricultural bureau procurement records across the analysis window. Segmentation dimensions include product type, application crop, formulation technology, and distribution channel structure. CAGRs derive from regression analysis of historical registration approval timelines correlated with adoption curve penetration in precision-spraying hardware and biological formulation substitution rates.
Forecasts assume regulatory continuity in SAMR crop-specific approval cycles and MEE dual carbon enforcement timelines; material policy shifts would require re-modeling. Specific risks include GB 2763 maximum residue limit revisions eliminating additional synthetic actives and biological antagonist efficacy breakthroughs accelerating substitution beyond modeled adoption curves. Revision becomes warranted when biological product registration approval velocity crosses thresholds that compress synthetic product lifecycles faster than historical patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Crop Protection
Europe Herbicide Market
Crop Protection
Corn Preemergence Herbicide Market
Crop Protection
Fruit and Vegetable Crop Protection Market
Crop Protection
China Insecticide Market
Crop Protection
Europe Agricultural Pheromones Market
Crop Protection
Thailand Crop Protection Chemicals Market
Crop Protection
Global Organophosphate Pesticide Market
Crop Protection
Metamitron Herbicides Market
Crop Protection
Canada Nematicides Market
Crop Protection
Tebuconazole Market
Crop Protection
Indonesia Insecticide Market
Crop Protection
Global Insect Pest Control Market
Crop Protection
Pest Control Services Market
Crop Protection
Dicamba Market
Crop Protection
Middle East and Africa Algaecides Market
Crop Protection
South America Insecticide Market