
 Canada Compound Feed Market | 2026-2036
Canada Compound Feed Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Compound Feed Market Outlook
Asset-light leasing arrangements for feed milling equipment is tilting competitive dynamics toward mid-sized regional entrants. Cargill Inc. leverages its integrated grain origination network across Saskatchewan and Manitoba to secure cost-advantaged ingredient positions. Nutreco Canada Inc. sustains premium positioning through specialized aquafeed formulations serving British Columbia salmon operations. Paragon Feeds Corp. anchors its presence in Ontario through direct-to-farm distribution channels that bypass traditional distributor markups.
Compound feed consists of blended formulations containing cereals, protein meals, minerals, and additives, manufactured through pelleting or mash processes to deliver standardized metabolizable energy and crude protein levels for livestock performance. Ruminant feed occupies the largest volume share, reflecting the scale of Canadian beef and dairy herds, while aquafeed represents the fastest-expanding category as land-based recirculating aquaculture systems multiply in Atlantic Canada. Ingredient type segmentation shows corn and soybean meal commanding dominant positions, though wheat inclusion rates fluctuate with Prairie crop rotation patterns and domestic milling competition.
Health Canada and the Canadian Food Inspection Agency enforce the Feeds Act and Regulations, mandating ingredient approval, label accuracy, and contaminant limits that directly shape formulation costs and product registration timelines. The Canadian Grain Commission's grading standards for feed-quality wheat and corn influence regional sourcing economics and blender procurement decisions. Provincial environmental regulations in Alberta and Manitoba governing manure nutrient management are tightening nutrient density specifications in swine and dairy rations. Stakeholders must monitor how carbon pricing mechanisms and feed transportation cost structures reshape the geographic viability of decentralized versus centralized milling operations.
Market Dynamics
Alberta's dairy herd expansion and Health Canada's Feeds Act traceability mandates are compressing formulation timelines while concentrating procurement among Prairie feed mills capable of real-time ingredient tracking.
Growth Catalysts
- Precision nutrition protocols:Dairy operations in Quebec and Alberta are adopting ration optimization software that demands higher-frequency feed analysis and customized additive inclusion rates.
- Recirculating aquaculture systems:Atlantic Canada salmon and trout producers are scaling land-based facilities that require specialized high-protein aquafeed formulations with exact amino acid profiles.
- Manure nutrient regulations:Provincial environmental rules in Manitoba and Alberta are mandating lower phosphorus excretion, driving demand for phytase-enhanced swine and dairy rations.
Market Restraints
- Feed-quality grain supply concentration:Prairie corn and wheat origination tilts toward Saskatchewan and Manitoba elevator networks, creating regional procurement bottlenecks during harvest compression periods.
- Regulatory registration friction:Health Canada's novel feed ingredient approval process extends product launch timelines by months, particularly for enzyme and probiotic additives.
- Protein meal import dependency:Soybean meal supply chains remain exposed to US Midwest crush capacity and rail export logistics, amplifying cost volatility during peak demand windows.
Strategic Opportunities
- Direct-to-farm distribution channels:Ontario and Quebec livestock operations are bypassing traditional distributor networks, creating margin capture potential for regional mills with captive delivery fleets.
- Carbon credit integration:Federal greenhouse gas offset protocols may reward methane-reducing feed additives, opening premium pricing tiers for ruminant formulations with verified enteric fermentation suppression.
- Atlantic Canada aquafeed localization:British Columbia salmon expertise is transferring to Nova Scotia and New Brunswick land-based facilities, creating demand for domestically manufactured marine protein alternatives.
Industry Challenges
- Formulation chemist scarcity:Prairie feed mills face recruitment gaps for specialists capable of balancing metabolizable energy calculations with real-time ingredient variability.
- Legacy mill equipment retrofit costs:Pelleting lines installed in the 1990s require capital-intensive upgrades to achieve Health Canada's mandated lot traceability and cross-contamination controls.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Compound Feed Market |
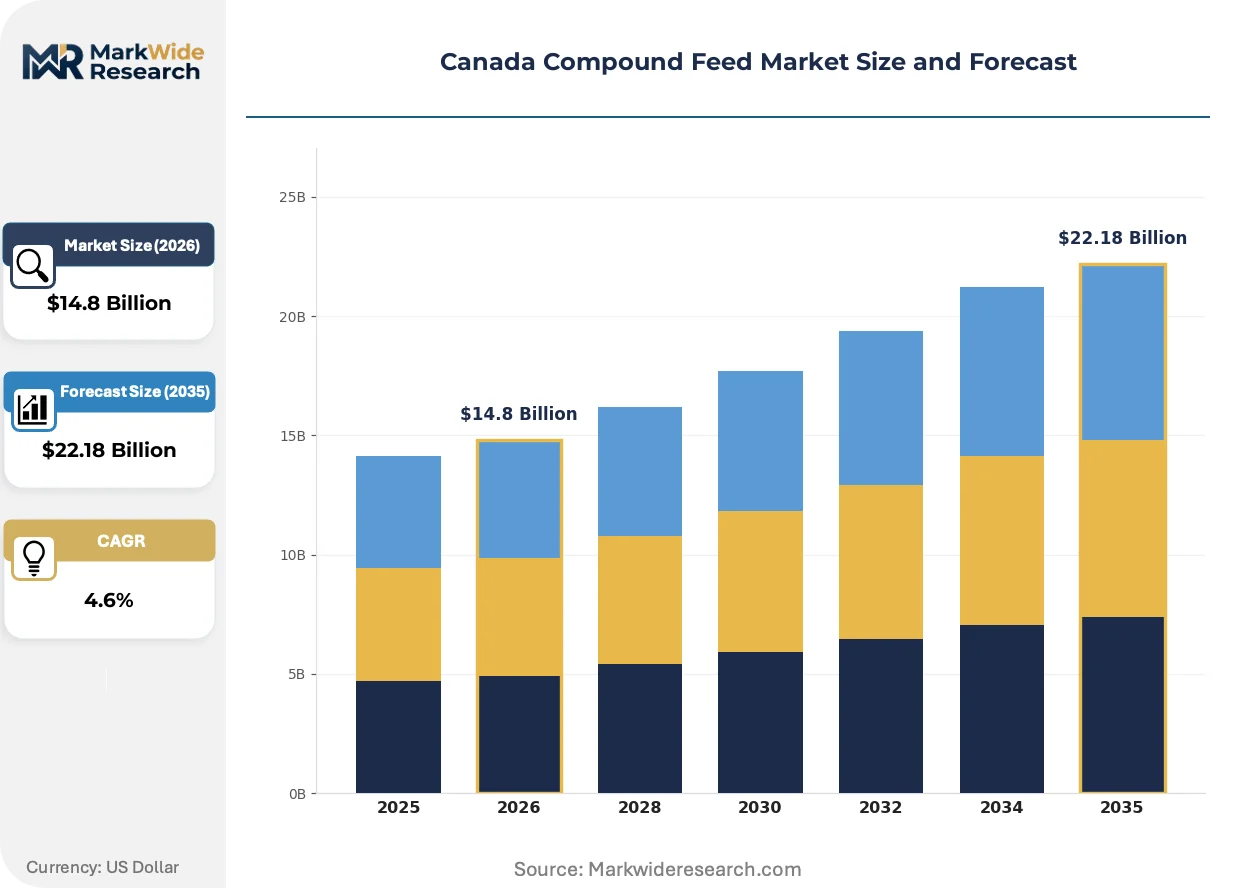
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $22.18 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Poultry Feed, Swine Feed, Ruminant Feed, Aquafeed End User: Farmers, Feed Manufacturers, Livestock Growers, Aquaculture Operators Distribution Channel: Direct Sales, Retail Stores, E-commerce, Distributors Ingredient Type: Corn, Soybean Meal, Wheat, Others |
| Companies Covered | Cargill Inc., Alltech Inc., Novus International, Archer Daniels Midland, Land O Lakes Purina, Neovia Group, Paragon Feeds Corp., Canadian Organic Feeds Limited, Nutreco Canada Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Compound Feed Market Strategic Shifts
Near-infrared spectroscopy and blockchain ingredient tracking are compressing quality assurance cycles while enabling premium pricing for verified-sustainable feed certifications.
Near-infrared reflectance spectroscopy is collapsing the lag between ingredient delivery and nutritional verification. Prairie feed mills are deploying inline NIR sensors at receiving bays to adjust formulation matrices within hours rather than days. This compression is eliminating buffer inventory requirements and enabling just-in-time sourcing contracts with Alberta and Saskatchewan grain elevators.
Health Canada's updated Feeds Act traceability provisions are mandating lot-level ingredient documentation from origin to farm delivery. Manufacturers must now maintain chain-of-custody records for all vitamins, minerals, and medicated additives. British Columbia aquafeed producers are responding fastest, leveraging existing seafood export documentation systems to achieve compliance ahead of Prairie cattle feed operations.
Consolidated procurement by Alberta and Manitoba hog integrators is displacing spot-market purchasing with annual volume contracts tied to performance guarantees. Feed mills must now absorb ingredient cost volatility within fixed-price arrangements. This concentration is most visible in the Red River Valley, where two large-scale operations account for dominant share of regional swine feed demand.
Canada Compound Feed Market Segmentation
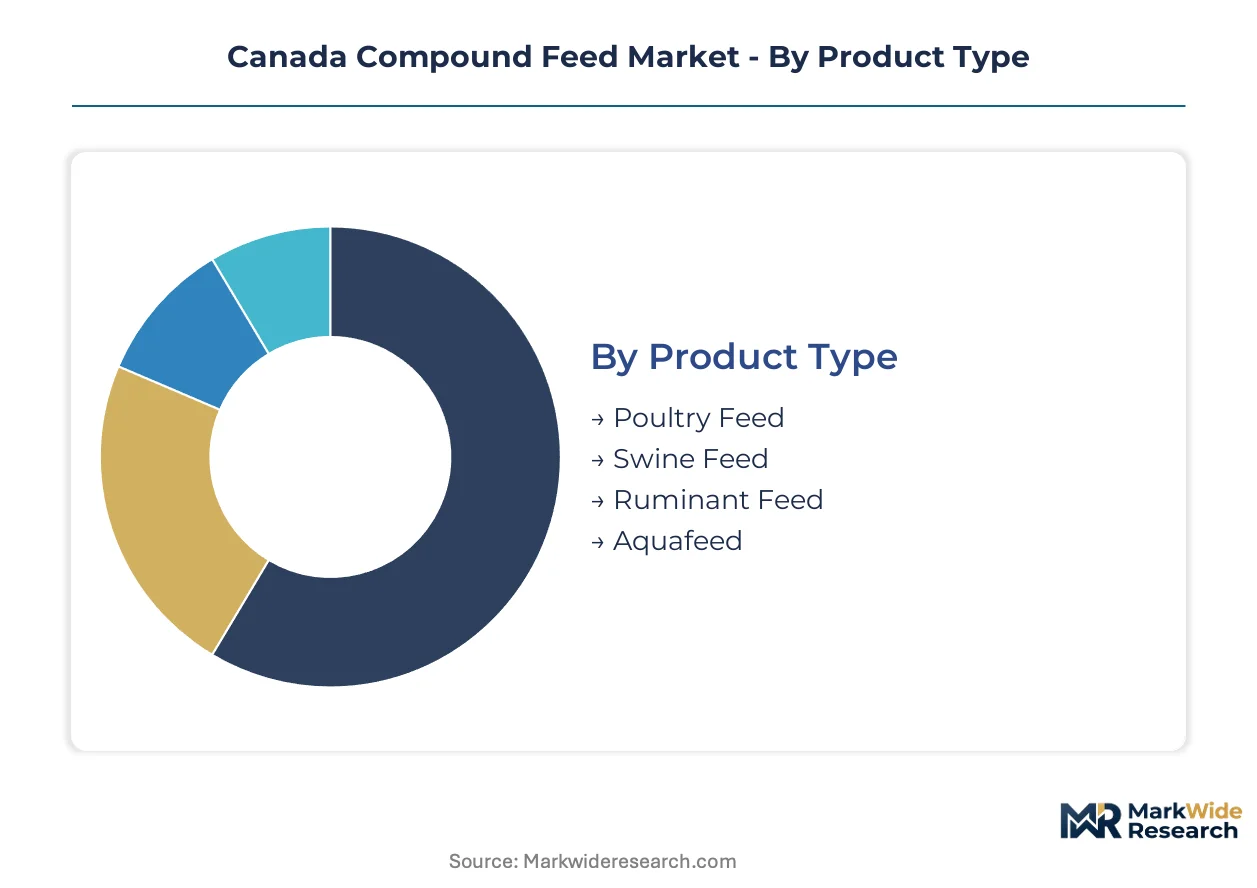
Segmentation in Canada's compound feed market reveals how formulation complexity, procurement scale, and regulatory exposure fragment demand across distinct operational profiles. Understanding these divides enables suppliers to align milling capacity, ingredient sourcing, and distribution infrastructure with the specific performance and compliance requirements of each buyer category.
Product Type:
Ruminant feed formulations span the widest metabolizable energy range, from high-fiber beef cattle rations to precision-balanced dairy concentrates, while aquafeed commands the tightest amino acid specifications and highest additive inclusion rates.
- Ruminant Feed:Blended formulations deliver standardized crude protein and energy density for beef and dairy herds, with Prairie feed mills optimizing for regional corn and barley availability. Demand concentrates in Alberta and Quebec, where expanding dairy operations require nutritionally precise rations that comply with provincial manure nutrient regulations.
- Aquafeed:High-protein extruded pellets with exact amino acid profiles serve Atlantic Canada salmon and trout operations in land-based recirculating aquaculture systems. British Columbia producers are transferring technical expertise to Nova Scotia and New Brunswick facilities, accelerating domestic manufacturing requirements for marine protein alternatives.
- Poultry Feed:Mash and pelleted formulations balance energy density with feed conversion efficiency for layer and broiler operations across Ontario and Quebec.
- Swine Feed:Phytase-enhanced rations reduce phosphorus excretion to meet Manitoba and Alberta environmental standards for manure nutrient management.
The dominant share belongs to ruminant feed, while aquafeed is closing the gap fastest.
End User:
Procurement scale separates spot-market purchasers from integrators demanding annual volume contracts with embedded performance guarantees.
- Farmers:Small-to-midscale livestock operators purchase through distributor networks or direct-to-farm channels, with Ontario and Quebec producers increasingly bypassing traditional markups. Feed mills with captive delivery fleets capture margin by eliminating intermediary layers.
- Feed Manufacturers:Regional mills blend base formulations for private-label distribution, requiring real-time ingredient tracking to satisfy Health Canada Feeds Act traceability mandates.
- Livestock Growers:Large-scale cattle and hog operations in the Prairie provinces dominate procurement volumes and dictate formulation specifications.
- Aquaculture Operators:Atlantic Canada salmon producers source specialized high-protein formulations with verified chain-of-custody documentation for export compliance.
Livestock growers command the largest procurement volumes, though aquaculture operators are expanding their share most rapidly.
Distribution Channel:
Channel selection reflects buyer scale, urgency tolerance, and the need for formulation customization versus standard product availability.
- Direct Sales:Feed mills with dedicated logistics fleets deliver customized rations to large integrators, absorbing ingredient cost volatility within fixed-price annual contracts. Red River Valley hog operations exemplify this concentration.
- Distributors:Traditional networks serve smaller farmers with standard formulations, though their share erodes as regional mills build direct relationships.
- Retail Stores:Farm supply cooperatives and agricultural retailers stock bagged feed for hobby farmers and small-scale poultry operations.
- E-commerce:Digital ordering platforms gain traction among mid-scale producers seeking price transparency and scheduled delivery flexibility.
Direct sales generate the highest revenue concentration, while e-commerce is gaining adoption fastest among younger farm operators.
Ingredient Type:
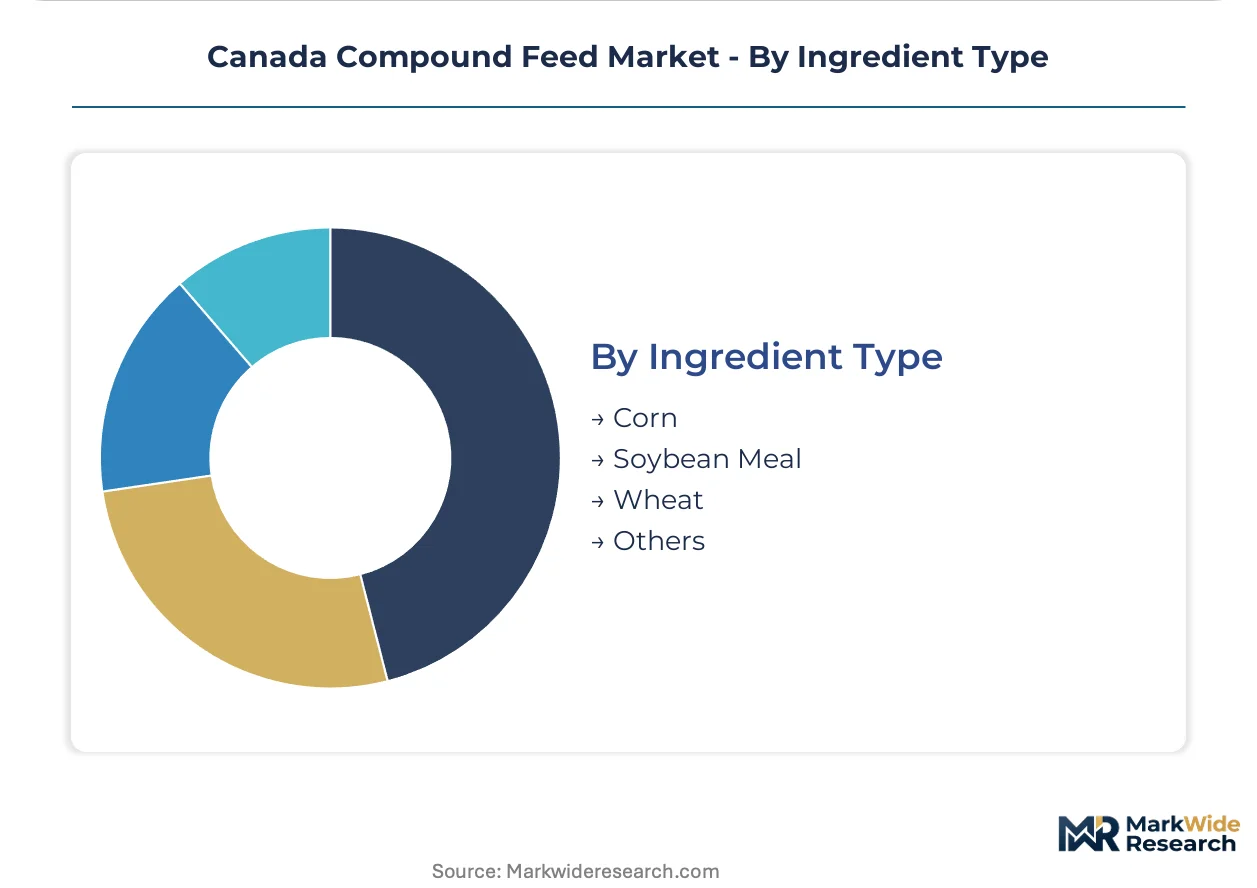
Regional crop patterns and import logistics determine cost structures, with Prairie origination creating sourcing advantages for mills near Saskatchewan and Manitoba elevator networks.
- Corn:The dominant energy source in Canadian feed formulations, with Prairie corn origination tilting toward Saskatchewan and Manitoba elevator networks. Harvest compression periods create regional procurement bottlenecks that mills manage through just-in-time sourcing contracts.
- Soybean Meal:The primary protein component remains exposed to US Midwest crush capacity and rail export logistics, amplifying cost volatility during peak demand windows.
- Wheat:Inclusion rates fluctuate with Prairie crop rotation patterns and domestic milling competition for feed-quality grain.
- Others:Barley, canola meal, and synthetic amino acids fill formulation gaps when primary ingredients face price spikes or supply constraints.
Corn maintains the largest formulation share, though canola meal and regional protein alternatives are expanding their inclusion fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Alberta feed mills command pricing premiums through captive grain origination, while Atlantic Canada operations absorb protein meal import premiums that compress margins on aquafeed formulations.
Ontario
Dairy herd expansion in Eastern Ontario drives demand for precision-formulated rations with real-time nutrient verification. Health Canada's Feeds Act traceability mandates force mills to upgrade lot-tracking systems ahead of Prairie competitors. The Guelph-Waterloo corridor concentrates feed technology providers serving direct-to-farm distribution channels that bypass traditional distributor markups.
Quebec
Ration optimization software adoption accelerates among dairy operations requiring higher-frequency feed analysis and customized additive inclusion rates. Provincial environmental regulations governing manure nutrient management tighten phosphorus density specifications in swine and dairy rations. The Saint-Hyacinthe agricultural hub anchors specialized formulation capacity serving expanding dairy herds in the Montérégie region.
Alberta
Large-scale cattle and hog operations dominate procurement volumes and dictate formulation specifications to regional mills. Carbon pricing mechanisms reshape the geographic viability of decentralized versus centralized milling operations across the province. The Red Deer-Lethbridge corridor concentrates feed milling capacity adjacent to expanding beef feedlot operations and dairy herd growth zones.
British Columbia
Salmon aquaculture operations drive demand for specialized high-protein formulations with exact amino acid profiles and verified chain-of-custody documentation. Existing seafood export documentation systems enable faster compliance with Health Canada Feeds Act traceability provisions than Prairie cattle feed operations. The Vancouver Island and Sunshine Coast clusters transfer technical expertise to Atlantic Canada land-based recirculating aquaculture facilities.
Atlantic Canada
Land-based recirculating aquaculture systems for salmon and trout multiply across Nova Scotia and New Brunswick, creating demand for domestically manufactured marine protein alternatives. Federal greenhouse gas offset protocols may reward methane-reducing feed additives, opening premium pricing tiers for verified sustainable certifications. The St. Andrews and Digby sub-regions concentrate emerging aquafeed manufacturing capacity serving export-oriented salmon producers.
Canada Compound Feed Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream, supplying base formulations and additive premixes to regional blenders. The Canada compound feed market structures around three tiers: multinational grain traders with captive origination networks, specialized aquafeed formulators with marine protein expertise, and regional mills with direct-to-farm distribution fleets. Strategic moves concentrate on backward integration into grain origination and asset-light leasing arrangements for pelleting equipment that lower barriers for mid-sized entrants.
Among multinational agribusiness operators, Cargill Inc. and Archer Daniels Midland exemplify the integrated grain-origination archetype, leveraging Prairie elevator networks to secure cost-advantaged corn and wheat positions. Nutreco Canada Inc. occupies the specialized aquafeed tier, while Paragon Feeds Corp. anchors the regional direct-distribution model in Ontario. These three patterns—origination-integrated, species-specialized, and channel-captive—define competitive positioning across provincial markets.
| Leading Market Players |
|---|
| Cargill Inc. |
| Alltech Inc. |
| Novus International |
| Archer Daniels Midland |
| Land O Lakes Purina |
| Neovia Group |
| Paragon Feeds Corp. |
| Canadian Organic Feeds Limited |
| Nutreco Canada Inc. |
| Others |
Value Chain & Pricing Dynamics
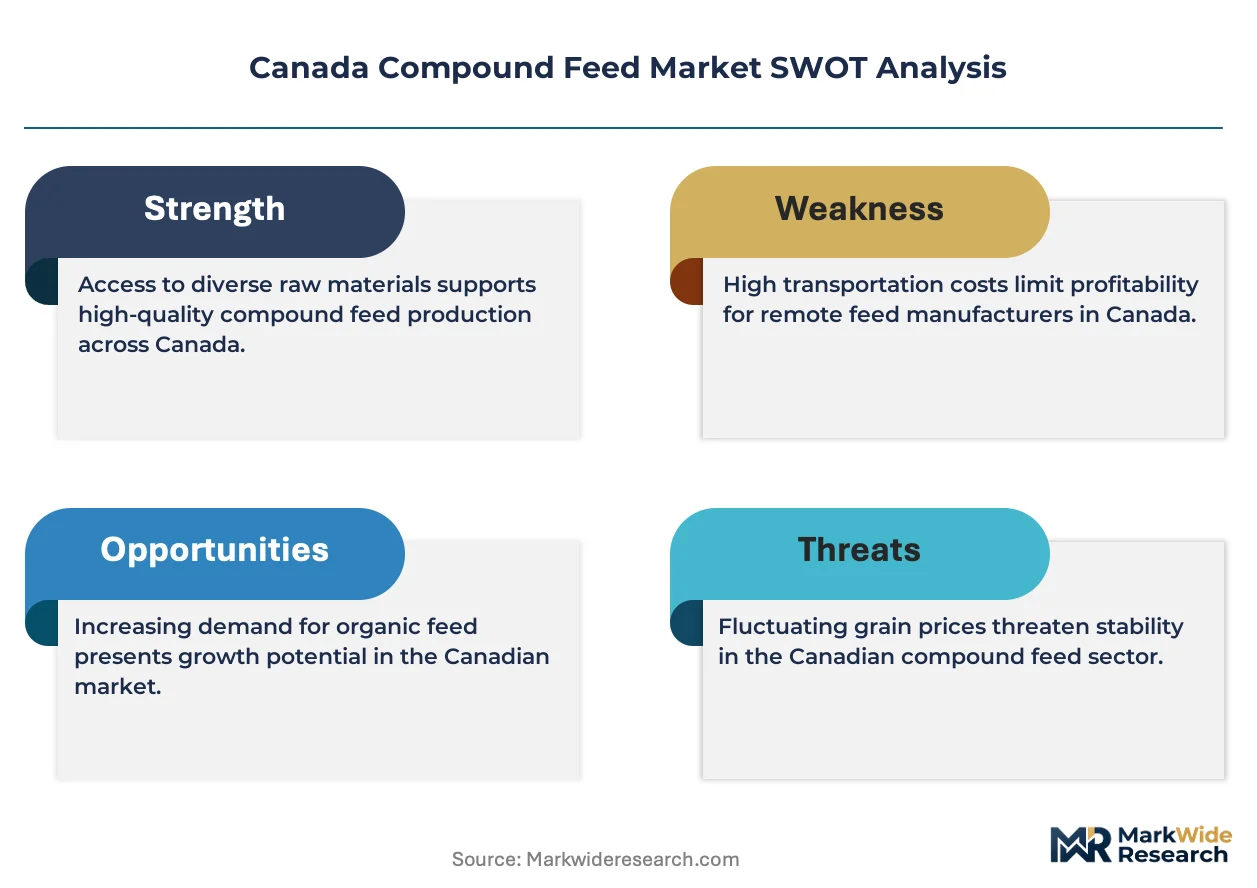
Soybean meal import dependency from US Midwest crush facilities compresses margin structures across Prairie feed mills while simultaneously forcing pricing tier spreads that separate origin-integrated multinationals from regional blenders absorbing rail logistics volatility.
Pricing Analysis
Livestock grower integrators anchor contract-based long-term offtake pricing that absorbs ingredient cost swings within fixed annual arrangements. Three-tier pricing structure across premium, standard, and economy levels separates traceability-certified aquafeed from commodity ruminant formulations and residual feed-quality grain products. Pricing pressure stems from consolidated procurement by Red River Valley hog operations demanding performance guarantees. Small-to-midscale farmers exhibit highest price sensitivity, while Atlantic Canada aquaculture operators accept premiums for verified chain-of-custody documentation.
Supply Chain Analysis
Cargill's Prairie elevator networks and Nutreco's British Columbia aquafeed facilities concentrate domestic manufacturing capacity, with ingredient sourcing drawing from Saskatchewan corn origination, Manitoba wheat grading pools, and US Midwest soybean meal crush operations. Corn, soybean meal, and feed-quality wheat constitute the core formulation inputs. Single-source vulnerability runs through rail-dependent protein meal imports during peak autumn harvest compression. Distribution runs through direct-to-farm captive fleets for large integrators and traditional distributor networks for smaller operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Canada's compound feed market represents an early-cycle expansion story as land-based recirculating aquaculture systems in Atlantic Canada drive specialized formulation demand that domestic manufacturing capacity has yet to fully match.
For Market Incumbents: Build captive grain origination moats through Saskatchewan and Manitoba elevator network expansion to defend against mid-sized regional entrants leasing pelleting equipment. Secure backward integration into feed-quality corn and barley origination. Invest in real-time NIR spectroscopy and blockchain traceability systems ahead of Health Canada Feeds Act enforcement timelines to maintain premium positioning.
For New Entrants and Emerging Players: Atlantic Canada aquafeed manufacturing capacity gaps present white-space entry points for specialized marine protein alternative formulations serving Nova Scotia and New Brunswick salmon operations. Target direct-to-farm distribution channels in Ontario and Quebec dairy corridors where traditional distributor markups create margin capture opportunities. Lead with precision nutrition software integration as the go-to-market differentiator.
For Investors and Strategic Acquirers: Regional mills with direct-to-farm captive delivery fleets and Health Canada compliance infrastructure represent the priority acquisition archetype for platform consolidation plays. Long-term viability hinges on carbon credit integration potential for methane-reducing feed additives and aquafeed localization trends. Monitor federal greenhouse gas offset protocol finalization as the key inflection signal for premium pricing tier expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Grain Origination | Cargill's Saskatchewan elevator network secures cost-advantaged corn positions against regional competitors. |
| Direct-to-Farm Distribution Expansion | Paragon Feeds' Ontario captive fleet eliminates distributor markups and captures margin from dairy operations. |
| Aquafeed Manufacturing Localization | Atlantic Canada land-based salmon facilities demand domestic marine protein alternatives reducing import dependency. |
| Traceability Technology Deployment | Inline NIR sensors at Prairie receiving bays compress quality assurance cycles and enable just-in-time sourcing. |
| Carbon Credit Integration | Federal offset protocols reward methane-reducing additives opening premium ruminant formulation tiers. |
Study Parameters
Operator-level perspectives from feed mill plant managers, livestock grower procurement leads, aquaculture operations directors, and Health Canada regulatory affairs specialists anchored the qualitative base. Primary interviews triangulated against Canadian Grain Commission grading standards, CFIA enforcement bulletins, provincial environmental regulation filings, and Prairie grain elevator network capacity data. Bottom-up volume modeling across ingredient type, product formulation, and end-user segments converged with top-down market sizing from agribusiness financial disclosures.
Scenario-bracketing framed the analytical approach across the analysis window, with segmentation dimensions spanning ruminant versus aquafeed versus poultry versus swine formulations, direct sales versus distributor versus retail channels, and Prairie versus Ontario-Quebec versus Atlantic Canada regional clusters. CAGRs derived from historical volume trajectories, herd expansion projections, and regulatory compliance cost absorption curves. Feed conversion efficiency trends and manure nutrient regulation stringency indices served as industry-specific forecast inputs.
Practitioners should monitor US Midwest rail export logistics disruptions, Prairie harvest compression severity, and Health Canada novel ingredient approval timelines for early signals requiring forecast revision. Quarterly review of carbon offset protocol developments, aquaculture facility commissioning announcements, and regional mill equipment upgrade capex cycles is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
Asia-Pacific Animal Protein Market
Agriculture and Agri Products
Forage Feed Market
Agriculture and Agri Products
Spain Compound Feed Market
Agriculture and Agri Products
Mushroom Cultivation Market
Agriculture and Agri Products
Alfalfa Market
Agriculture and Agri Products
Live Goods Market
Agriculture and Agri Products
Inulin Market
Agriculture and Agri Products
Rape Seed Meal Market
Agriculture and Agri Products
China Animal Protein Market
Agriculture and Agri Products
Seaweed Algae Market
Agriculture and Agri Products
Global Medicated Feed Market
Agriculture and Agri Products
Post-Harvest Treatment Market
Agriculture and Agri Products
Europe Compound Feed Market
Agriculture and Agri Products
Floriculture Market
Agriculture and Agri Products
Sorghum by-Products Market
Agriculture and Agri Products
Tissue Cultured Date Palm Market