
 Acetochlor Herbicide Market | 2026-2036
Acetochlor Herbicide Market Size, Share, and Industry Trends Forecast 2026-2036
Acetochlor Herbicide Market Insights
Agronomic expertise in chloroacetanilide stewardship is collapsing across the US Corn Belt and Brazil's frontier zones, constraining safe expansion of acetochlor hectares. Bayer AG leverages its seed-and-chemistry bundling infrastructure to sustain grower loyalty in North American corn systems. Syngenta AG anchors its position through proprietary safener technology that reduces crop phytotoxicity at higher application rates. Corteva Agriscience competes via geographic dominance in Latin American soybean rotations where acetochlor pre-emergent programs dominate weed resistance management.
Acetochlor is a chloroacetanilide herbicide selective for grass and broadleaf weed control in row crops, typically formulated as emulsifiable concentrate or suspension concentrate with active ingredient loads ranging from 50% to 90% and requiring incorporation or rainfall activation within specific time windows to prevent volatility losses. Its primary commercial purpose centers on pre-emergent residual control in corn and soybean systems where glyphosate-tolerant weed biotypes have proliferated. Liquid formulations occupy the largest volume share due to ease of tank-mix compatibility with atrazine and mesotrione partners in standard programs. Emulsifiable concentrate variants retain margin strength in developing markets where application infrastructure favors simpler mixing protocols. The suspension concentrate segment captures fastest growth in precision agriculture zones where drift reduction and lower-use-rate efficacy align with stewardship mandates.
The US EPA governs acetochlor registration under FIFRA with mandatory safener requirements and annual use reporting, while the EU operates under REACH and the Sustainable Use Directive with member-state-specific buffer zone enforcement that restricts application windows near water bodies. China's MEE imposes production capacity caps and discharge standards on chloroacetanilide intermediates that reshape supply geography. Stakeholders must monitor evolving safener patent expiries and regulatory tolerance harmonization between import-dependent markets to anticipate formulation switching costs and re-registration investment requirements.
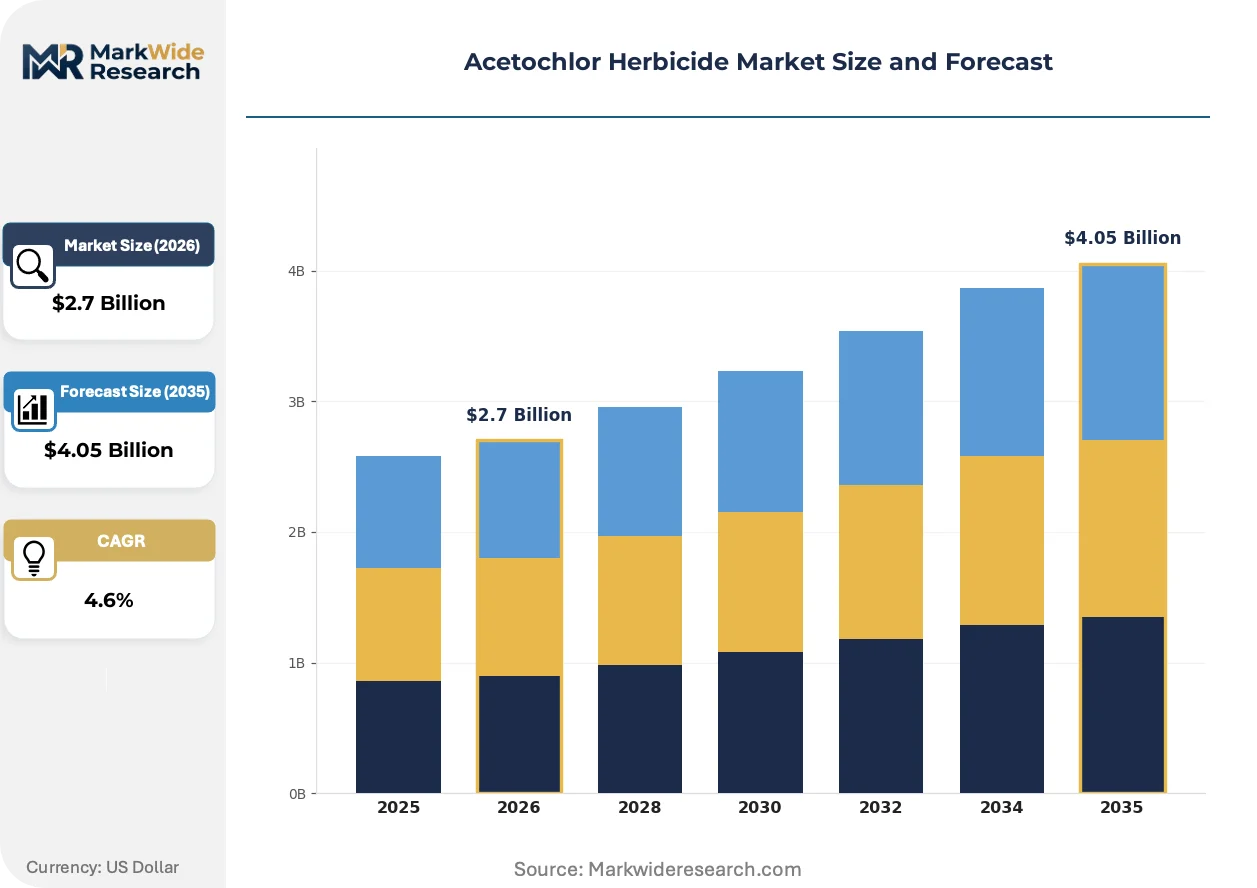
Market Dynamics
Glyphosate resistance proliferation across US Midwest corn and Brazil Cerrado soybean systems is compressing grower tolerance for single-mode chemistry programs, forcing accelerated rotation toward chloroacetanilide residual layers with mandatory safener co-formulations.
Growth Catalysts
- EPA FIFRA Safener Mandates:Regulatory requirements for crop protection co-formulations are institutionalizing premium product tiers and locking in formulation switching costs that favor established registrants with patent-protected safener libraries.
- Brazil Cerrado Mechanization:No-till soybean expansion across Mato Grosso and Goiás is concentrating demand for pre-emergent residual programs where acetochlor tank-mixes with atrazine command preferred distributor positioning.
- Drone Application Systems:Aerial spraying infrastructure in Heilongjiang and Shandong provinces is enabling ultra-low-volume suspension concentrate delivery that reduces labor costs and drift liability in Chinese corn systems.
Market Restraints
- Chloroacetyl Chloride Feedstock Volatility:Chinese MEE discharge standards on intermediate production are constraining supply elasticity and amplifying cost pass-through to formulated product pricing.
- EU Green Deal Restriction Cascade:Member-state buffer zone enforcement under the Sustainable Use Directive is compressing application windows near water bodies and redirecting investment toward reduced-risk variant development.
- Glufosinate Substitution Pressure:LibertyLink soybean system expansion in Argentina and Paraguay is displacing acetochlor hectares in rotation sequences where stacked trait packages simplify weed resistance management.
Strategic Opportunities
- India Rabi Corn Belt:Underpenetrated pre-emergent herbicide adoption in Madhya Pradesh and Karnataka offers expansion potential as FCI procurement price floors stabilize grower input investment confidence.
- Precision Agriculture Convergence:Integration of soil moisture sensors with variable-rate application equipment is enabling site-specific acetochlor deposition that reduces total active ingredient load per hectare.
- PLI Scheme Manufacturing Incentives:India's production-linked incentive framework for agrochemical technicals is attracting formulation capacity that can serve ASEAN export demand with tariff advantages.
Industry Challenges
- Safener Stewardship Expertise Collapse:Agronomic training gaps across US extension services and Brazilian frontier zones are constraining safe expansion of higher-rate acetochlor programs without crop phytotoxicity incidents.
- Re-registration Timeline Compression:REACH dossier updates and EPA endocrine screening requirements are demanding simultaneous multi-jurisdiction data generation that strains regulatory affairs bandwidth at mid-scale registrants.
- Legacy Tank-Mix Infrastructure:Existing spray equipment calibration protocols in developing markets favor emulsifiable concentrate rheology, slowing suspension concentrate adoption despite drift reduction benefits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Acetochlor Herbicide Market |
| Market Size in 2026 | $2.7 Billion |
| Market Size in 2035 | $4.05 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granular, Liquid, Emulsifiable Concentrate, Suspension Concentrate Formulation: SL, EC, SC, WDG Application Method: Soil Application, Pre-emergent, Post-emergent, Banding Crops: Corn, Soybeans, Wheat, Rice |
| Companies Covered | BASF SE, Bayer AG, Syngenta AG, Corteva Agriscience, FMC Corporation, UPL Limited, Nufarm Limited, Sumitomo Chemical, ADAMA Agricultural Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Acetochlor Herbicide Market Trends and Innovations
Formulation chemistry advances and application precision technologies are restructuring competitive advantage away from commodity active ingredient supply toward integrated stewardship service bundles that lock in grower loyalty through resistance management protocols.
Micro-encapsulated acetochlor delivery systems are extending soil residual persistence through controlled-release polymer matrices that reduce volatility losses under high-temperature conditions. Large-scale corn operations in Iowa and Illinois are adopting these formulations at accelerating rates to compress re-application labor costs. This technology is displacing conventional emulsifiable concentrate volumes in premium market tiers where per-hectare application efficiency determines procurement decisions.
EU REACH authorization timelines for chloroacetanilide metabolites are forcing registrants to submit extended environmental fate dossiers that delay formulation renewals. The industrial consequence is a bifurcation between legacy products facing sunset clauses and next-generation reduced-risk variants with expedited review pathways. Suspension concentrate segments in German and French cereal systems are most affected, with distributors building inventory buffers against potential supply interruptions.
Channel consolidation among North American agricultural retailers is compressing manufacturer negotiation leverage and shifting margin capture toward co-op buying groups with private-label formulation capabilities. Independent agronomy advisors in Nebraska and Kansas are being absorbed into vertically integrated input suppliers that bundle seed, chemistry, and digital prescription services. This pattern is most visible in the US Corn Belt where dealer network density has fallen by a third over the past decade.
Acetochlor Herbicide Market Segmentation
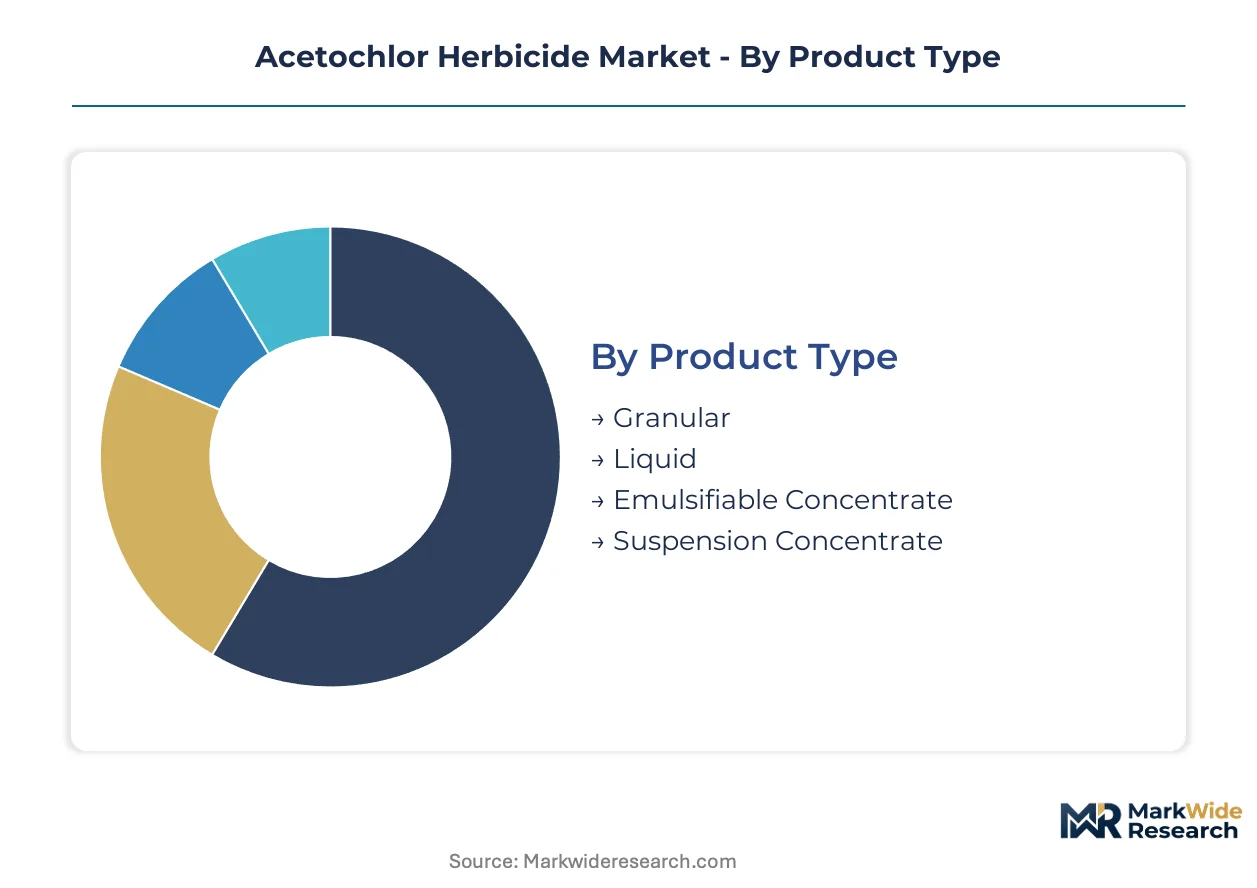
Acetochlor herbicide procurement channels vary sharply by physical form and formulation complexity. Distributor stocking decisions, farmer mixing protocols, and regulatory handling requirements all hinge on which segment combination a grower selects.
Product Type:
Liquid and suspension concentrate formulations dominate commercial channel throughput, while granular products flow through specialized turf and small-farm retail networks.
- Liquid:Standard emulsifiable and suspension concentrates supplied in bulk tanker or drum formats. Corn operations across Iowa, Illinois, and Mato Grosso rely on liquid acetochlor for seamless tank-mix compatibility with atrazine and mesotrione partners in pre-emergent programs.
- Suspension Concentrate:Finely milled active ingredient suspended in aqueous carrier with superior drift reduction properties. Adoption concentrates in precision agriculture zones where aerial application via Heilongjiang drone fleets and Nebraska variable-rate equipment demands lower-use-rate efficacy.
- Granular:Clay or polymer-based carrier particles for direct soil incorporation without spray equipment. Demand persists in Japanese rice paddy systems and Southeast Asian smallholder contexts where mechanized spraying infrastructure remains limited.
- Emulsifiable Concentrate:Oil-in-water systems with surfactant packages aiding leaf and soil penetration. Brazilian Cerrado distributors favor EC rheology for compatibility with existing spray tank calibration protocols.
By volume, Liquid leads. By growth pace, Suspension Concentrate is ahead.
Formulation:
Cost tiers separate commodity technical buyers from premium formulation adopters seeking safener integration and application precision.
- SL (Soluble Liquid):True solution formulations with complete water miscibility. Premium positioning in German and French cereal systems subject to EU Sustainable Use Directive buffer zone restrictions favors SL variants for reduced environmental fate complexity.
- EC (Emulsifiable Concentrate):Oil-based systems requiring mechanical agitation before application. Developing market penetration in India's Madhya Pradesh and Karnataka corn belts relies on EC familiarity among extension-trained agronomists.
- SC (Suspension Concentrate):Solid active ingredient particles suspended in aqueous phase with polymer stabilizers. Chinese MEE discharge standards on chloroacetyl chloride intermediates are compressing SC production costs relative to EC alternatives.
- WDG (Water-Dispersible Granules):Dry granular products dispersing upon water contact for drift-minimized application. Argentina's LibertyLink soybean expansion zones show WDG uptake where glufosinate tank-mix compatibility simplifies resistance management.
By margin contribution, SC formulations command premium positioning. By adoption velocity, WDG is climbing fastest.
Application Method:
Customer type and farm scale dictate method selection, with commercial row-crop operations separating from specialty and smallholder systems.
- Pre-emergent:Soil-surface application before crop emergence forming residual chemical barrier. US Midwest corn systems facing glyphosate-resistant waterhemp and Palmer amaranth biotypes anchor pre-emergent acetochlor demand with mandatory safener co-formulations.
- Soil Application:Mechanical incorporation or rainfall-activated surface deposition. Brazil's no-till soybean expansion across Goiás and Mato Grosso depends on soil-applied acetochlor for early-season grass control without tillage disturbance.
- Post-emergent:Foliar-directed application after crop establishment with specialized nozzle configurations. Limited acetochlor use due to crop phytotoxicity constraints, confined to directed banding in tolerant corn growth stages.
- Banding:Concentrated application in crop row zone reducing total hectare load. Kansas and Nebraska large-scale operations adopt banding for cost efficiency where weed pressure concentrates in planting furrows.
By hectare coverage, Pre-emergent dominates. By stewardship-driven substitution, Soil Application is expanding most quickly.
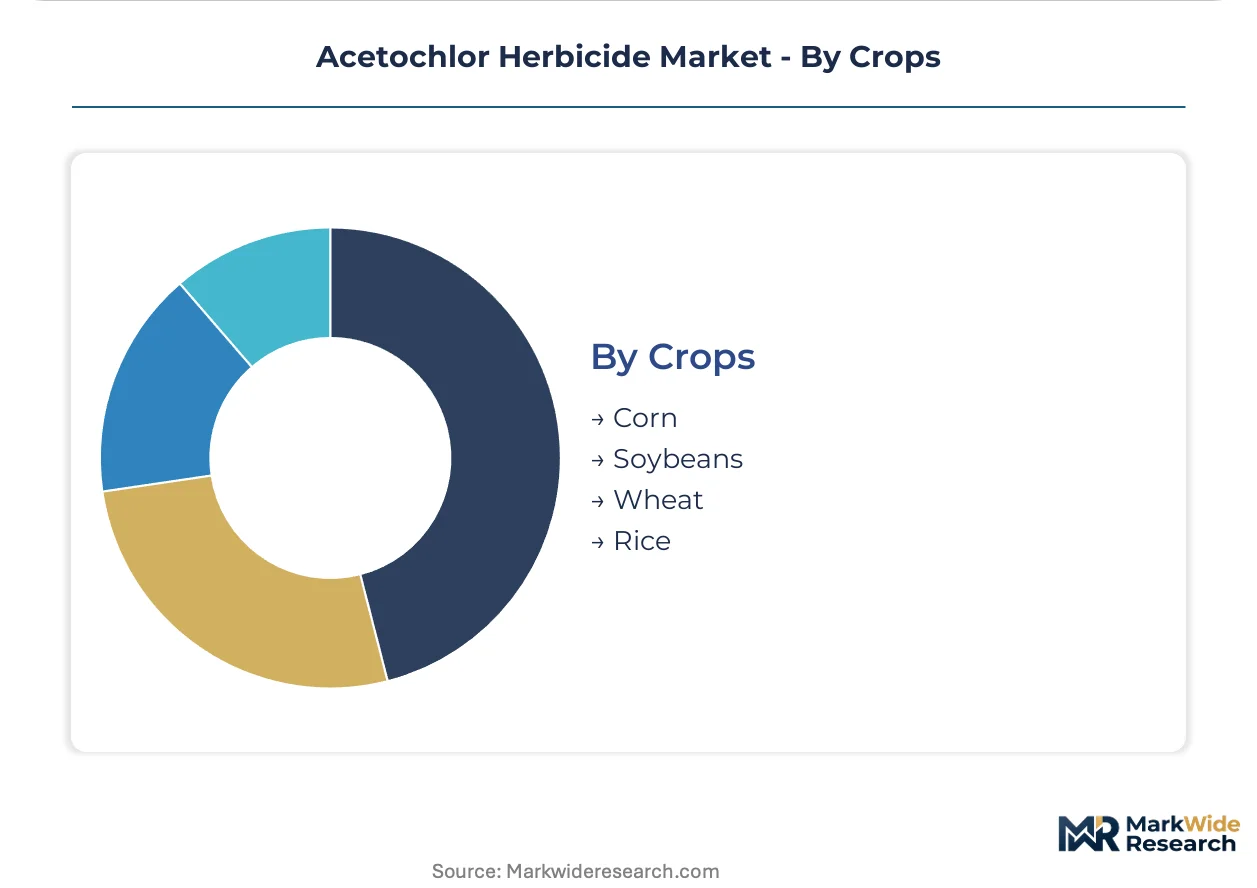
Crops:
Geographic concentration of each crop type shapes regional formulation preferences and channel density.
- Corn:Primary acetochlor market with pre-emergent residual programs standard in US Midwest, China, and EU maize systems. EPA FIFRA safener mandates institutionalize premium product tiers for corn applications.
- Soybeans:Brazil Cerrado no-till expansion drives demand where acetochlor tank-mixes with atrazine command preferred distributor positioning ahead of planting.
- Wheat:Minor acetochlor use in EU and Australian cereal rotations where chloroacetanilide alternatives face metabolite scrutiny under REACH authorization timelines.
- Rice:Paddy-specific granular and liquid applications in Japan, South Korea, and Southeast Asian delta systems with distinct water management protocols.
By revenue concentration, Corn leads. By frontier expansion potential, Soybeans is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in Brazilian Cerrado soybean systems exceeds US Midwest corn belts by 15-20% due to no-till premium positioning and limited generic penetration. Regulatory divergence between EPA FIFRA mandates and EU Green Deal restrictions is fragmenting formulation standards across major demand centers.
United States
Glyphosate-resistant waterhemp and Palmer amaranth biotypes across Iowa and Illinois corn systems drive residual herbicide layering with mandatory safener co-formulations. EPA FIFRA registration requires annual use reporting and buffer zone compliance near water bodies. Large-scale operations in Nebraska and Kansas concentrate demand for banding application equipment that reduces per-hectare active ingredient loads.
Brazil
No-till soybean expansion across Mato Grosso and Goiás commands premium positioning for pre-emergent acetochlor tank-mixes with atrazine ahead of planting. ANVISA pesticide re-registration timelines are compressing product renewal windows and favoring established registrants with regulatory affairs bandwidth. Distributor networks in the Cerrado mechanization belt are consolidating around vertically integrated input suppliers bundling seed and chemistry.
China
Drone application infrastructure in Heilongjiang and Shandong provinces enables ultra-low-volume suspension concentrate delivery in corn systems. MEE discharge standards on chloroacetyl chloride intermediates constrain supply elasticity and amplify cost pass-through to formulated product pricing. Yangtze River Delta formulation clusters are pivoting toward export-oriented production under dual carbon compliance mandates.
Germany
EU REACH authorization timelines for chloroacetanilide metabolites delay formulation renewals and bifurcate legacy products from reduced-risk variants. ECHA buffer zone enforcement under the Sustainable Use Directive compresses application windows near water bodies in cereal-growing regions. Rhineland distributors are building inventory buffers against potential supply interruptions for suspension concentrate segments.
India
Underpenetrated pre-emergent herbicide adoption in Madhya Pradesh and Karnataka corn belts offers expansion potential as FCI procurement price floors stabilize grower input investment confidence. DGFT agrochemical import regulations and PLI scheme manufacturing incentives attract formulation capacity serving ASEAN export demand. Deccan Plateau extension services favor emulsifiable concentrate familiarity among trained agronomists.
Acetochlor Herbicide Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with safener patent portfolios separating premium registrants from commodity technical suppliers. The vendor base concentrates around integrated agrochemical conglomerates with seed-chemistry bundling infrastructure and mid-scale regional formulators with private-label capabilities. Three archetypes dominate: patent-protected safener technology holders, geographic specialists in Latin American soybean rotations, and cost-optimized technical manufacturers serving developing markets. M&A activity targets distribution network density, while strategic partnerships focus on drone application system integration.
Within the integrated conglomerate tier, Bayer AG and Syngenta AG exemplify technology leadership through proprietary safener libraries and seed-chemistry bundling infrastructure. Corteva Agriscience anchors geographic specialization in North American corn systems. BASF SE occupies a position spanning both premium formulation development and technical manufacturing scale. These three entities represent the competitive archetypes that structure procurement negotiations with consolidated agricultural retailers.
| Leading Market Players |
|---|
| BASF SE |
| Bayer AG |
| Syngenta AG |
| Corteva Agriscience |
| FMC Corporation |
| UPL Limited |
| Nufarm Limited |
| Sumitomo Chemical |
| ADAMA Agricultural Solutions |
| Others |
Pricing and Supply Chain Analysis
Glufosinate substitution in Argentina and Paraguay soybean systems simultaneously redraws supply geography toward stacked-trait seed bundlers and compresses acetochlor pricing power in residual herbicide tiers. This displacement dynamic feeds back into formulation investment patterns, redirecting capital toward safener-integrated premium tiers where patent protection sustains margin capture against commodity technical erosion.
Pricing Analysis
Brazilian Cerrado no-till premiums exceed US Midwest corn belt benchmarks by a substantial spread due to limited generic penetration and distributor consolidation. Three-tier pricing structure across premium safener-integrated, standard emulsifiable concentrate, and economy technical tiers separates Bayer and Syngenta patent holders from Indian and Chinese commodity suppliers. Pricing pressure stems from Chinese MEE discharge standards on chloroacetyl chloride intermediates that amplify cost pass-through. Smallholder segments in Southeast Asia and India's Deccan Plateau exhibit highest price sensitivity, while large-scale Brazilian soybean operations show lowest elasticity due to resistance management lock-in.
Supply Chain Analysis
Strategic stockpiling of suspension concentrate formulations dominates EU and North American procurement patterns ahead of REACH re-registration deadlines, while just-in-time liquid delivery persists in Brazilian distributor networks. Manufacturing gravity centers on China's Yangtze River Delta formulation clusters, India's PLI-incentivized technical plants, and Germany's Rhineland safener synthesis facilities. Chloroacetyl chloride, atrazine technical, and proprietary safener molecules constitute critical input dependencies. Single-source vulnerability concentrates in Chinese intermediate production subject to MEE capacity caps. Distribution runs through vertically integrated agricultural retailers consolidating across the US Corn Belt and Brazilian Cerrado.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Drone-enabled precision application and micro-encapsulation chemistry constitute dual technological inflections reshaping competitive advantage in residual herbicide systems. EPA FIFRA safener mandates and EU Green Deal metabolite restrictions simultaneously accelerate premium tier consolidation and compress mid-scale registrant viability.
For Market Incumbents: Shield patent-protected safener portfolios through accelerated Indian and Brazilian formulation capacity expansion ahead of PLI scheme saturation. Deepen backward integration into chloroacetyl chloride intermediates to offset Chinese MEE supply constraints. Channel control through seed-chemistry bundling in North American corn systems remains the critical defensive lever against glufosinate displacement.
For New Entrants and Emerging Players: Lead with drone-compatible suspension concentrate formulations targeting Heilongjiang and Shandong corn provinces where aerial application infrastructure outpaces established distributor relationships. India's Madhya Pradesh and Karnataka rabi corn belts offer the most penetrable geography given underdeveloped pre-emergent adoption and FCI price floor stabilization. Go-to-market execution should anchor on agronomic training partnerships that address safener stewardship expertise gaps constraining incumbent expansion.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed Indian technical manufacturers and Brazilian regional formulators lacking regulatory affairs bandwidth for simultaneous EPA and ANVISA re-registration. Five-to-ten year viability hinges on safener patent cliff timing and metabolite authorization outcomes under REACH. The signal to watch is EU member-state buffer zone enforcement stringency that would accelerate reduced-risk variant switching costs and stranded legacy inventory risk.
| Strategic Initiative | Industry Significance |
|---|---|
| Safener Patent Extension Investment | Prolongs exclusivity windows for Bayer and Syngenta in North American corn systems facing glyphosate resistance proliferation. |
| Drone Application System Partnership | Enables ultra-low-volume suspension concentrate penetration in Heilongjiang corn provinces with limited ground spray infrastructure. |
| Backward Integration into Chloroacetyl Chloride | Reduces exposure to Chinese MEE discharge standards constraining intermediate supply elasticity and cost pass-through. |
| India PLI Manufacturing Scale-Up | Captures tariff-advantaged ASEAN export positioning while serving underpenetrated Deccan Plateau corn belt demand. |
| Micro-Encapsulation Technology Licensing | Extends soil residual persistence in Iowa and Illinois high-temperature conditions, compressing re-application labor costs. |
Research Methodology
Cross-validation between regulatory filing databases and distributor procurement records anchors the qualitative findings in documented compliance patterns. Primary interviews with EPA registration specialists, ANVISA regulatory affairs directors, Bayer and Syngenta field agronomists, and Coop buying group procurement managers combined with secondary validation from FIFRA registration documents, REACH dossier submissions, Chinese MEE discharge permits, and Indian DGFT import records. Bottom-up hectare adoption estimates and top-down formulation production volumes triangulate market sizing across the analysis window.
Sensitivity analysis on Chinese intermediate supply constraints and Brazilian re-registration timeline compression frames the forecast confidence intervals. Segmentation dimensions span formulation type, crop system, application method, and regional regulatory cluster. CAGRs derive from weighted average of historical adoption velocity and projected resistance management protocol shifts. Key inputs include drone fleet deployment rates in Chinese corn provinces and EU member-state buffer zone enforcement variance.
The analysis sits within stated boundaries; outcomes outside sustained glyphosate resistance proliferation or abrupt Chinese environmental regulatory tightening would require recalibration. Forecasts assume continued no-till expansion in Brazil and stable FCI procurement floors in India. Revision becomes warranted when glufosinate trait penetration in South American soybean systems crosses thresholds that structurally displace chloroacetanilide residual programs.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Crop Protection
Propiconazole Market
Crop Protection
Australia Crop Protection Chemicals (Pesticides) Market
Crop Protection
Hungary Crop Protection Chemicals Market
Crop Protection
North America Nematicides Market
Crop Protection
Metamitron Herbicides Market
Crop Protection
Thailand Crop Protection Chemicals Market
Crop Protection
Europe Crop Protection Chemicals Market
Crop Protection
US Turf and Ornamental Protection Market
Crop Protection
US Pest Control Market
Crop Protection
Indonesia Insecticide Market
Crop Protection
Europe Fungicide Market
Crop Protection
Global Aquatic Herbicides Market
Crop Protection
India Crop Protection Chemicals Market
Crop Protection
Chile Crop Protection Chemicals Market
Crop Protection
Japan Crop Protection Chemicals Market
Crop Protection
Avicides Market