
 Agricultural Surfactants Market | 2026-2036
Agricultural Surfactants Market Size, Share, and Industry Trends Forecast 2026-2036
Agricultural Surfactants Market Intelligence
The U.S. Environmental Protection Agency's (EPA) inert ingredient approval process is reorganizing market access for new surfactant formulations. This framework mandates rigorous toxicological and environmental impact data before a substance can be used in pesticide products. BASF SE leverages its extensive chemical synthesis capabilities to develop compliant, high-performance nonionic surfactants. Corteva Agriscience differentiates through its integrated seed and crop protection portfolio, creating tailored adjuvant systems, while Croda International Plc specializes in bio-based surfactants derived from renewable sources.
Agricultural surfactants are adjuvants that reduce the surface tension of water, improving the spread, adhesion, and penetration of agrochemicals on plant surfaces. These compounds, often based on ethoxylated alcohols or alkyl polyglucosides, ensure uniform coverage and enhance the efficacy of active ingredients. Nonionic surfactants dominate the product landscape due to their compatibility with a wide range of active ingredients and low phytotoxicity. In application segments, demand for surfactants in herbicide formulations is expanding to address challenges in weed management for cereals and grains.
Regulations from bodies like Europe's ECHA under REACH and Health Canada's PMRA are setting stricter limits on nonylphenol ethoxylates (NPEs), driving a shift toward safer, biodegradable alternatives. These standards directly influence formulation chemistry and market access for global manufacturers. Navigating the divergent regulatory requirements for tank-mix versus in-can adjuvants across key agricultural markets remains a critical strategic decision for suppliers.
Market Dynamics
The agricultural surfactants market is defined by regulatory pressure on chemical safety, particularly from frameworks like the EU's REACH. This force compels innovation in formulation chemistry, steering development toward biodegradable and lower-toxicity alternatives to meet new compliance standards.
Growth Catalysts
- Precision Farming Adoption:The expansion of precision agriculture techniques, especially in large farming economies like Brazil, requires highly efficient agrochemical applications, boosting demand for surfactants that ensure uniform spray coverage and active ingredient uptake.
- Weed Resistance Management:Proliferating herbicide-resistant weeds in cereal and grain cultivation necessitate more advanced herbicide formulations, creating a direct need for high-performance adjuvants that can overcome biological barriers and enhance efficacy.
- Bio-based Product Demand:Government policies and consumer preferences favoring sustainability are promoting the use of surfactants derived from renewable feedstocks, opening new avenues for bio-based chemistries like alkyl polyglucosides.
Market Restraints
- Regulatory Divergence:Conflicting standards for tank-mix versus in-can adjuvants between agencies like the U.S. EPA and Europe's ECHA create significant compliance burdens and market access hurdles for manufacturers operating across regions.
- Feedstock Price Volatility:The market's reliance on petrochemical derivatives, such as for ethoxylated alcohols, exposes surfactant producers to price fluctuations in crude oil and natural gas, impacting production costs and margin stability.
- Genetic Crop Advances:The development of new herbicide-tolerant crop varieties can alter agrochemical usage patterns, in some cases reducing the volume or changing the type of surfactants required for effective weed control.
Strategic Opportunities
- Biopesticide Formulations:The growing biopesticide segment presents a significant opportunity for developing specialized, often bio-based, surfactants that can stabilize delicate biological active ingredients and improve their performance in the field.
- Emerging Agricultural Economies:Agricultural modernization in regions like Southeast Asia and parts of Africa offers untapped markets for surfactant suppliers as farmers adopt more intensive and efficient crop protection practices.
- Controlled-Release Technologies:Advanced surfactants are integral to developing microencapsulation systems for agrochemicals, enabling controlled-release formulations that offer extended efficacy, improved safety, and reduced environmental impact.
Industry Challenges
- Compliance and Approval Delays:Navigating the rigorous data requirements and lengthy review processes of bodies like the U.S. EPA for new inert ingredient approvals creates significant operational delays and costs for introducing innovative surfactants.
- End-User Education Gap:The technical complexity of matching the optimal surfactant to specific crop-pesticide-water combinations remains a barrier, requiring extensive education to ensure proper use and prevent misapplication by growers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Agricultural Surfactants Market |
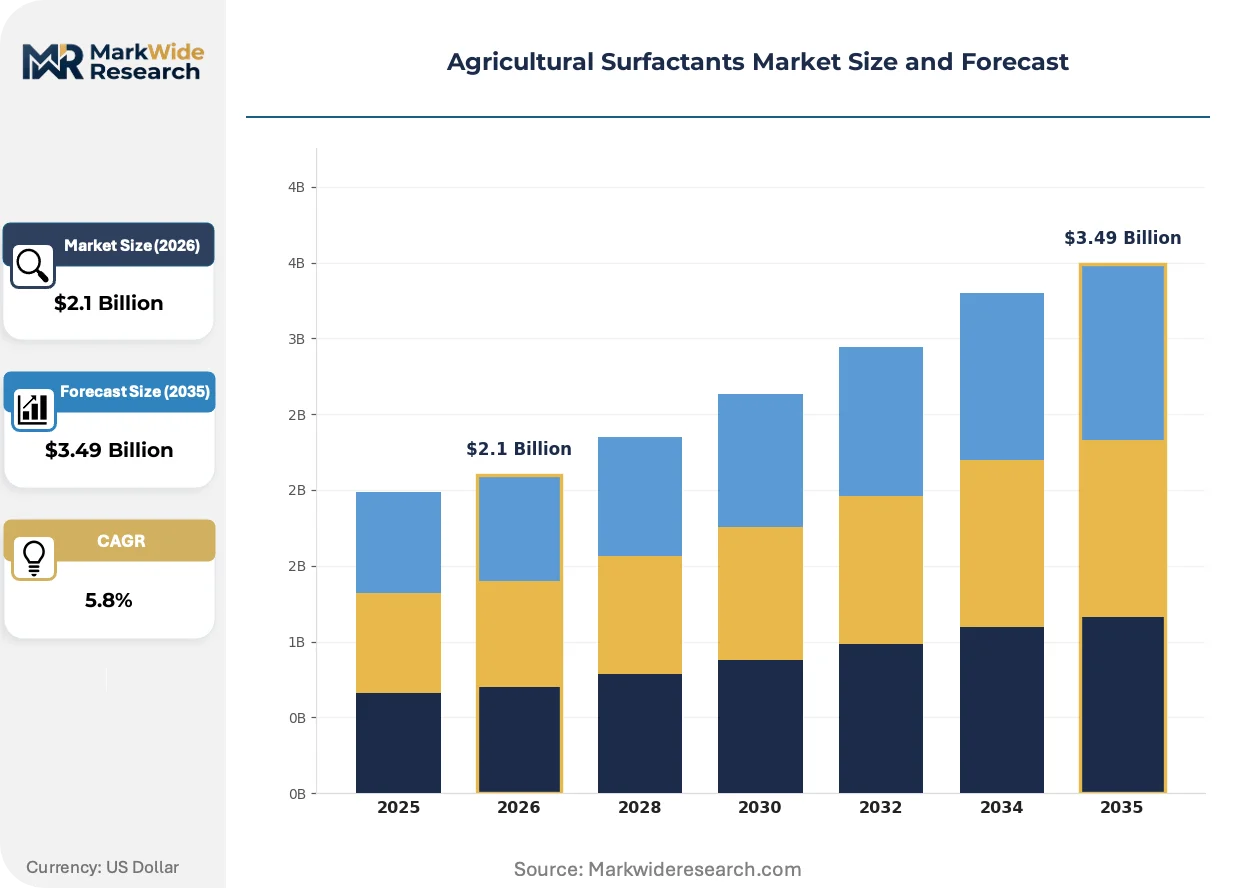
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.49 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Anionic, Nonionic, Cationic, Amphoteric, Silicone-based Application: Pesticides, Herbicides, Fungicides, Insecticides, Soil Conditioners Crop Type: Cereals & Grains, Fruits & Vegetables, Oilseeds & Pulses, Fibers, Plantation Crops Formulation Method: Emulsifiable Concentrates, Wettable Powders, Water Dispersible Granules, Suspension Concentrates, Liquid Solutions |
| Companies Covered | Solvay, Clariant, BASF SE, Croda International Plc, Nufarm, Corteva Agriscience, Helena Agri-Enterprises, Wilbur-Ellis Holdings, Evonik Industries AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Agricultural Surfactants Market Strategic Shifts & Innovations
The intersection of environmental stewardship and agricultural productivity is pushing formulation science toward greater specificity. This evolution prioritizes surfactants that not only enhance agrochemical performance but also meet stringent regulatory criteria for safety and biodegradability across different global markets.
Alkyl polyglucosides (APGs) are bio-based surfactants derived from sugars and fatty alcohols, offering excellent wetting properties and low toxicity. Formulators targeting sustainable product lines are rapidly adopting APGs to replace traditional chemistries. The expansion of these specialty bio-surfactants is fragmenting the conventional market, creating distinct segments based on environmental profiles rather than just performance.
Regulatory actions from Europe's ECHA under REACH and Health Canada's PMRA are severely restricting the use of nonylphenol ethoxylates (NPEs) due to environmental concerns. This is forcing a large-scale reformulation of many established pesticide products sold in those jurisdictions. Herbicide and insecticide manufacturers are most affected, now prioritizing safer alcohol ethoxylates and APGs to ensure continued market access.
Demand is shifting from standalone purchases of commodity adjuvants toward integrated crop management programs. This model disrupts traditional distributors by bundling customized surfactant packages with specific seeds and chemicals. This trend is most prominent in North American and Brazilian markets where large-scale, data-driven farming operations seek system-level performance guarantees.
Agricultural Surfactants Market Segmentation
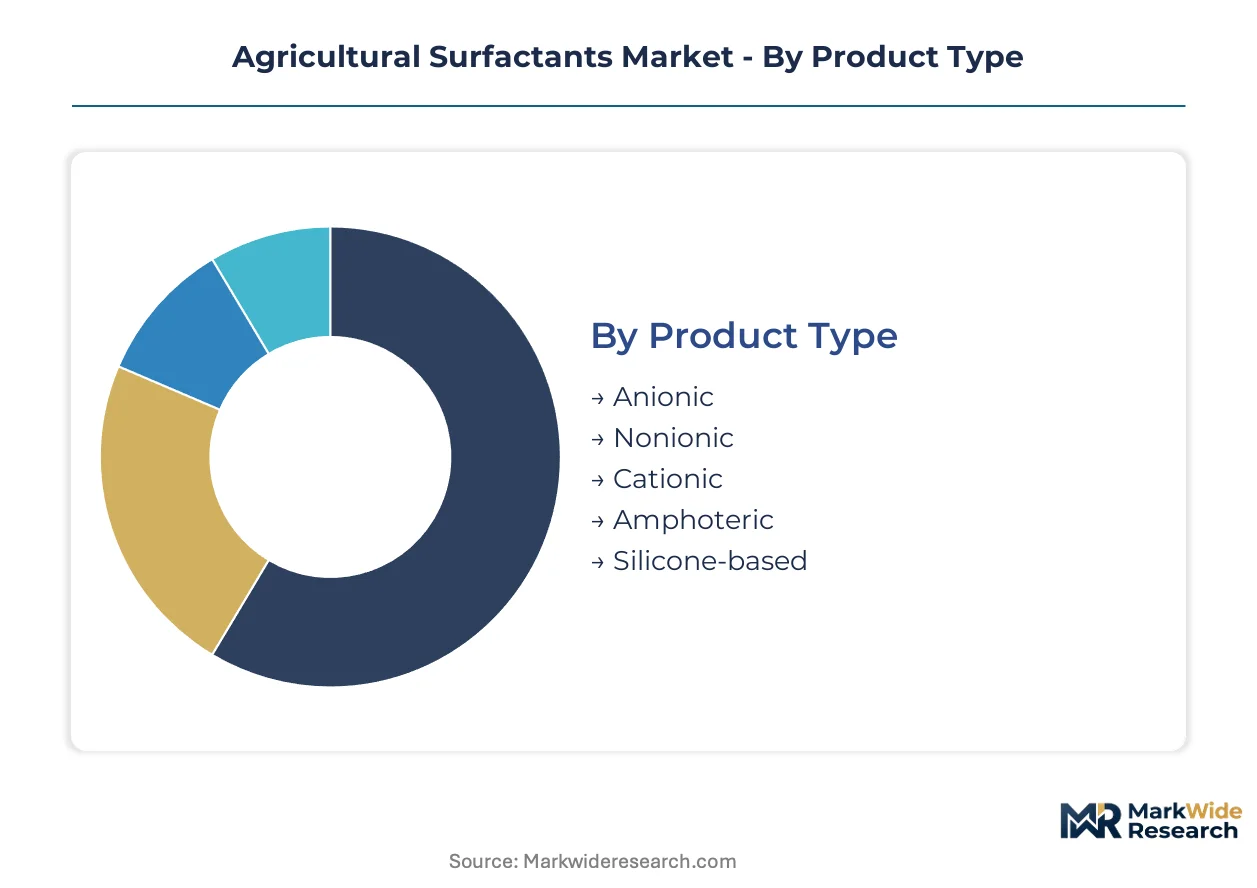
Understanding the market segmentation of agricultural surfactants is crucial for identifying specific demand drivers and regulatory influences across diverse product types and applications. This granular analysis highlights where innovation is most impactful and where market access challenges or opportunities exist for manufacturers.
Product Type:
Regulatory frameworks significantly influence the development and marketability of different surfactant product types, driving innovation toward compliant chemistries.
- Nonionic:These surfactants, often based on ethoxylated alcohols or alkyl polyglucosides, lack an electrical charge, ensuring broad compatibility with diverse agrochemicals and minimizing plant damage. Demand concentrates in advanced herbicide formulations, where they improve spreading and penetration to combat weed resistance.
- Anionic:Characterized by a negative charge in aqueous solutions, these surfactants offer excellent wetting and dispersing properties, commonly used in pesticide formulations requiring strong emulsification or suspension. Their use is influenced by specific regulatory approvals and environmental impact assessments.
- Cationic:These carry a positive charge, often used for their fungicidal properties or as conditioning agents in specific agrochemical applications.
- Amphoteric:Featuring both positive and negative charges, amphoteric surfactants offer versatility in pH conditions and are valued for mildness and foaming properties.
- Silicone-based:Known for their super-spreading capabilities, these surfactants significantly reduce surface tension, enhancing coverage for systemic agrochemicals.
Established volume favors Nonionic surfactants; emerging adoption favors newer, more environmentally compliant nonionic chemistries.
Application:
Specific agricultural application needs dictate the precise surfactant properties required to optimize the performance of active ingredients.
- Herbicides:Surfactants are critical in herbicide formulations, ensuring uniform spread and enhanced penetration of active ingredients into target weeds, particularly vital for managing resistant weed populations in cereals and grains. Demand is concentrated in large-scale farming economies like Brazil, where precision application is crucial.
- Pesticides:This broad category, including insecticides and fungicides, relies on surfactants to improve spray retention, droplet adhesion, and uptake efficiency on plant surfaces. The U.S. EPA's inert ingredient approval process influences market access for new surfactant formulations in this segment.
- Fungicides:Surfactants enhance the protective and systemic action of fungicides by improving their contact and absorption on crop foliage.
- Insecticides:These formulations benefit from surfactants that ensure effective coverage on insect pests and plant surfaces, improving active ingredient delivery.
- Soil Conditioners:Surfactants aid in the uniform distribution and penetration of soil conditioning agents, improving soil structure and nutrient availability.
Market expansion is primarily driven by Herbicides, while Pesticides represent a consistent, foundational demand.
Crop Type:
The diverse physiological characteristics and cultivation practices of various crop types influence the volume and specific types of surfactants deployed.
- Cereals & Grains:Surfactants are extensively used in these crops, primarily with herbicides and fungicides, to manage widespread weed resistance and disease pressure across vast acreages. Large agricultural economies, particularly in North America and Europe, exhibit high demand for effective surfactant systems.
- Fruits & Vegetables:These crops demand surfactants that provide excellent coverage and penetration without causing phytotoxicity, crucial for maintaining fruit quality and marketability. Precision farming techniques in regions like California and Spain drive demand for tailored adjuvant systems.
- Oilseeds & Pulses:Surfactants improve the efficacy of crop protection products for these valuable crops, supporting yield optimization and quality.
- Fibers:Crops like cotton utilize surfactants to ensure even distribution of defoliants and pest control agents, optimizing harvest efficiency.
- Plantation Crops:Surfactants are vital for efficient application of agrochemicals in crops such as coffee, tea, and rubber, often in challenging environmental conditions.
The largest consumption occurs in Cereals & Grains, with specialized requirements emerging from Fruits & Vegetables.
Formulation Method:
Different agrochemical formulation methods require specific surfactant chemistries to ensure stability, dispersibility, and optimal performance in the field.
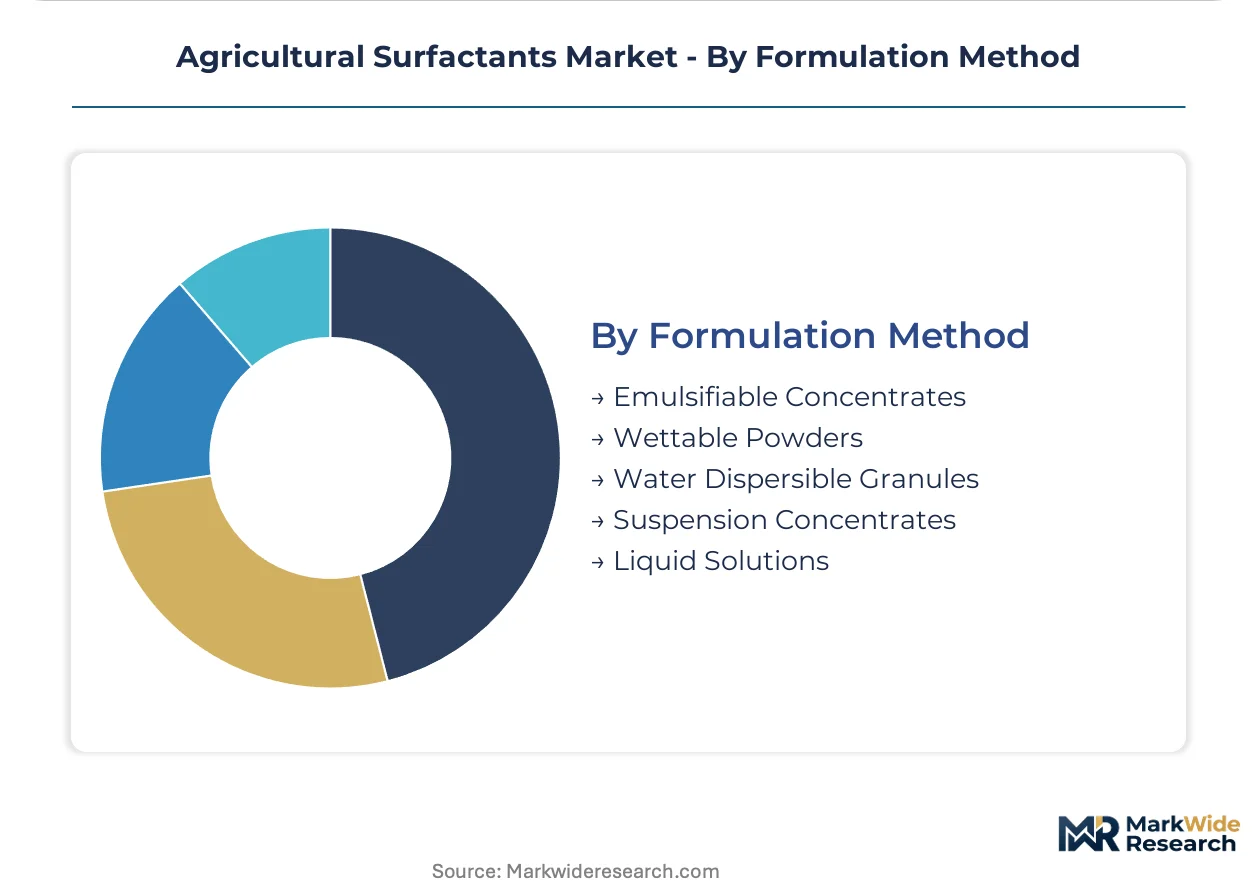
- Emulsifiable Concentrates:These oil-based formulations require surfactants, typically nonionic or anionic, to create stable emulsions when diluted in water, ensuring uniform application of lipophilic active ingredients. This method is widely used for many herbicides and insecticides globally.
- Suspension Concentrates:Surfactants in these formulations prevent active ingredient particles from settling, maintaining a stable suspension for effective dilution and spray application. They are increasingly favored for their reduced solvent content and improved safety profiles.
- Wettable Powders:Surfactants in these solid formulations ensure rapid and complete dispersion of the powder in water, preventing clogging and improving spray coverage.
- Water Dispersible Granules:These formulations use surfactants to facilitate the breakdown and dispersion of granules into a stable suspension upon contact with water.
- Liquid Solutions:While often simpler, surfactants can still enhance the wetting and spreading properties of active ingredients in true liquid solution formulations.
Demand is strongest for formulations requiring complex emulsification, while dry formulations like Wettable Powders and Water Dispersible Granules represent a growing segment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Government policies and incentives across major agricultural economies are shaping demand for agricultural surfactants. These frameworks push for sustainable formulations and efficient agrochemical applications. Regional dynamics reflect varied crop types and regulatory landscapes influencing adoption rates.
United States
United States demand for agricultural surfactants is driven by extensive corn and soybean cultivation. The U.S. EPA's inert ingredient approval process rigorously vets new surfactant formulations. California's Central Valley, a major agricultural hub, sees high adoption of advanced adjuvants for specialty crops.
Brazil
Brazil's expanding soybean and sugarcane production creates significant demand for high-performance surfactants. ANVISA regulations influence the registration and use of agrochemical adjuvants. The Mato Grosso region, a key agricultural frontier, actively integrates precision farming techniques requiring efficient spray additives.
Germany
German agriculture requires specialized surfactants for cereals and rapeseed cultivation. Europe's ECHA under REACH standards mandates stringent environmental profiles for chemical substances. The Rhine-Main region, a chemical industry cluster, develops biodegradable surfactant alternatives.
India
India's diverse crop portfolio, including rice and wheat, drives surfactant usage for enhanced pesticide efficacy. The country's national pesticide regulatory body influences agrochemical formulation approvals. Punjab, a major grain-producing state, sees increasing adoption of modern spray technologies.
China
China's vast agricultural output, particularly in grains and vegetables, necessitates efficient agrochemical delivery. The Ministry of Ecology and Environment (MEE) sets environmental standards for agricultural chemicals. Shandong province, a key agricultural and chemical manufacturing center, innovates in green surfactant technologies.
Agricultural Surfactants Market Key Industry Players
Player mix skews toward large, diversified chemical manufacturers and specialized adjuvant producers. The market structure exhibits both consolidation among global giants and fragmentation among regional specialists. Strategic archetypes include integrated crop solution providers and bio-based chemistry innovators. Dominant competitive moves involve portfolio diversification and strategic partnerships to navigate regulatory shifts.
Within the specialized chemical sector, BASF SE exemplifies a global leader leveraging extensive chemical synthesis capabilities for high-performance nonionic surfactants. Corteva Agriscience represents an integrated seed and crop protection portfolio, creating tailored adjuvant systems that optimize efficacy across its product lines. Croda International Plc anchors the bio-based surfactant segment, specializing in renewable-sourced chemistries like alkyl polyglucosides to meet sustainability demands. These companies collectively demonstrate varied approaches to product development, regulatory compliance, and market access within the agricultural surfactants industry, from broad chemical expertise to specialized bio-solutions.
| Leading Market Players |
|---|
| Solvay |
| Clariant |
| BASF SE |
| Croda International Plc |
| Nufarm |
| Corteva Agriscience |
| Helena Agri-Enterprises |
| Wilbur-Ellis Holdings |
| Evonik Industries AG |
| Others |
Cost & Logistics Intelligence
Europe's ECHA under REACH standards gates supply qualification and enables price differentiation for compliant agricultural surfactants. This regulatory scrutiny influences both market access and premium pricing for advanced formulations.
Pricing Analysis
Regulatory compliance certifications create the primary price spread in agricultural surfactants. Commodity ethoxylated alcohols often trade on a spot basis, while specialized bio-based alkyl polyglucosides command premium contract pricing. Bio-based origin and enhanced performance efficacy drive price differentiation. Pricing softness in basic nonionics stems from feedstock price volatility, yet specialty growers exhibit lower price sensitivity for high-performance formulations.
Supply Chain Analysis
Extended lead times for specialty surfactants often reflect complex synthesis and rigorous regulatory approval processes. Supply concentration for petrochemical-derived surfactants centers in China and the USA, with Germany leading in bio-based chemistries. The sector relies heavily on petrochemical derivatives and vegetable oils, facing commodity price volatility for crude oil and natural gas. Distribution runs through direct channels to large formulators and specialized agricultural distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The agricultural surfactants market presents a significant service-attach opportunity. Tailored adjuvant systems, bundled with crop protection programs, are expanding faster than standalone commodity product sales, creating recurring revenue streams.
For Market Incumbents:
Shield core market share by accelerating investment in compliant, bio-based surfactant R&D, particularly alkyl polyglucosides. Acquire specialized bio-surfactant producers to quickly integrate sustainable chemistries and mitigate threats from evolving environmental regulations. Strengthen relationships with large agrochemical formulators through co-development of tailored adjuvant systems. Prioritize certification investment for new inert ingredients.
For New Entrants and Emerging Players:
Anchor in niche segments by developing specialized surfactants for biopesticide formulations, offering performance guarantees for delicate biological active ingredients. Target emerging agricultural economies like Southeast Asia, where modernization drives demand for efficient crop protection. A go-to-market strategy emphasizing superior environmental profiles and application-specific efficacy can differentiate offerings.
For Investors and Strategic Acquirers:
Capital-intensity ratios are inflecting upwards across the bio-based surfactant sub-segment due to complex R&D and specialized production. The market offers long-term viability for companies with strong intellectual property in compliant, high-performance solutions. Target specialized bio-surfactant manufacturers or adjuvant system developers for strategic acquisitions. Watch for new inert ingredient approvals by the U.S. EPA as a key inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Bio-based Formulation R&D | Develops novel alkyl polyglucosides, securing market access under stricter ECHA regulations. |
| Integrated Adjuvant System Development | Optimizes agrochemical efficacy across Corteva Agriscience's seed and crop protection portfolio. |
| Regulatory Compliance Investment | Ensures continuous market access by meeting U.S. EPA inert ingredient approval requirements. |
| Geographic Expansion into Emerging Markets | Captures demand from precision farming adoption in large agricultural economies like Brazil. |
| Controlled-Release Technology Partnership | Enhances active ingredient delivery, reducing environmental impact and improving safety for growers. |
Research Approach
Cross-validation between primary interviews and secondary data sources anchors the qualitative findings. This study involved discussions with R&D directors, procurement leads at agrochemical firms, distribution channel partners, and agricultural researchers. Secondary validation utilized ECHA chemical registration databases, U.S. EPA inert ingredient lists, customs trade data, and agricultural census reports. A bottom-up and top-down triangulation approach ensured data accuracy.
Sensitivity analysis informed the robustness of market projections across the analysis window. A quantitative model segmented the market by product type, application, crop type, and formulation method, alongside regional regulatory clusters. Compound annual growth rates were derived from historical trends and future projections of key variables. Agrochemical consumption volumes and regulatory approval timelines for new chemistries served as primary forecast inputs.
Decision-makers should treat outputs as directional under current regulatory frameworks and agrochemical usage patterns; material deviation would warrant model refresh. Unforeseen changes in environmental regulations or major shifts in crop genetics represent key risk factors. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Chemicals
Global Dinotefuran Market
Agricultural Chemicals
Philippines Feed Additives Market
Agricultural Chemicals
Middle East and Africa Agricultural Pheromones Market
Agricultural Chemicals
Neem Pesticides Market
Agricultural Chemicals
North America Feed Phytogenics Market
Agricultural Chemicals
North America Feed Acidifiers Market
Agricultural Chemicals
Asia-Pacific Feed Mycotoxin Detoxifiers Market
Agricultural Chemicals
India Fungicide Market
Agricultural Chemicals
Agricultural Grade Zinc Chemicals Market
Agricultural Chemicals
Mexico Feed Additives Market
Agricultural Chemicals
North America Agricultural Disinfectants Market
Agricultural Chemicals
North America Fungicide Market
Agricultural Chemicals
Pesticide Adjuvant Market
Agricultural Chemicals
Stored Grain Insecticides Market
Agricultural Chemicals
Plant Activator Market
Agricultural Chemicals
North America Soil Treatment Market