
 US Insecticide Market | 2026-2036
US Insecticide Market Size, Share, and Industry Trends Forecast 2026-2036
US Insecticide Market Insights
FIFRA re-registration deadlines are broadening the cost-of-entry calculus for synthetic active ingredient manufacturers. BASF SE leverages its Ludwigshafen-based R&D pipeline to sustain novel mode-of-action discovery for resistance-prone pest complexes. Bayer AG anchors its position through digital farming platforms that bundle prescription insecticide applications with seed genetics. FMC Corporation differentiates via selective chemistry portfolios targeting lepidopteran pests in high-value vegetable systems.
US insecticides comprise formulated chemical or biological agents designed to disrupt arthropod nervous systems, growth regulation, or feeding behavior, typically applied at rates measured in ounces or pounds per acre depending on pest pressure and crop stage. These products serve primarily to protect yield and quality in agricultural production systems, alongside public health and structural pest suppression. Agricultural applications lead volume consumption, reflecting the scale of row-crop and specialty production, while liquid formulations capture the dominant share of value owing to precision application compatibility with aerial and ground equipment. The residential segment competes through ready-to-use formats and perimeter defense positioning, though margin pools concentrate in professional channels serving commercial and industrial accounts.
EPA, under FIFRA authority, governs active ingredient registration and label restrictions, while state departments of agriculture in Iowa, Illinois, and Texas enforce applicator certification and buffer zone compliance that directly shape field-level product selection. USDA coordinates resistance monitoring networks that inform regulatory mitigation measures and product stewardship requirements. FDA residue tolerance settings for food commodities intersect with EPA registration decisions, creating a dual compliance threshold for agricultural insecticide use. Stakeholders must monitor the trajectory of biological product efficacy standards as EPA develops parallel registration pathways that could restructure competitive positioning between conventional and microbial alternatives.
Market Dynamics
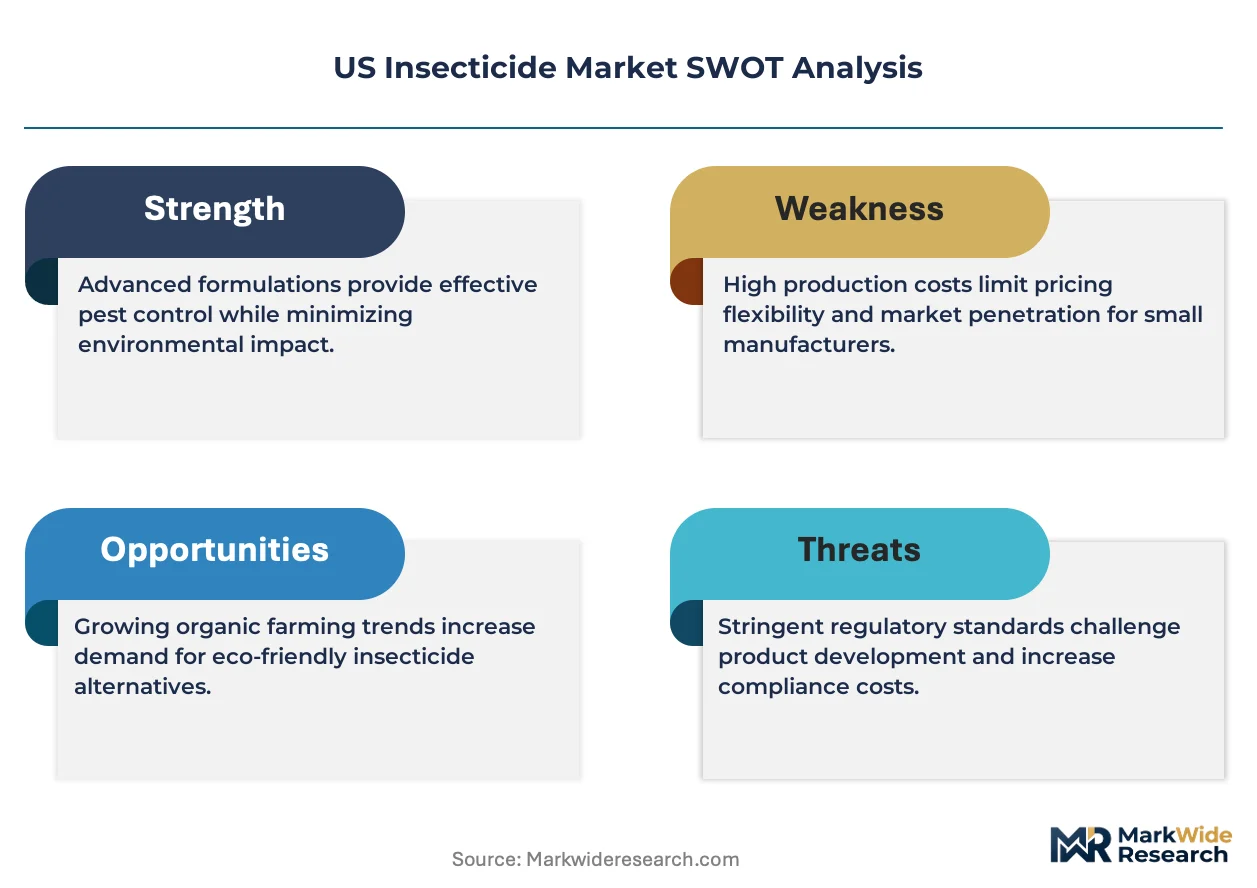
EPA's FIFRA re-registration deadlines for neonicotinoid compounds are compressing synthetic active ingredient pipelines while accelerating biological formulation investment across the agricultural value chain.
Growth Catalysts
- Biological registration pathways:EPA's parallel review frameworks for microbial and biochemical insecticides are shortening time-to-market for novel active ingredients derived from Bacillus thuringiensis and spinosad fermentation.
- Resistance management protocols:Corn Belt state extension services mandate rotation of chemistries with distinct modes of action, sustaining demand for novel synthetic and biological alternatives in Iowa and Illinois soybean systems.
- Precision application infrastructure:Variable-rate spray technology adoption in California specialty crops is concentrating value in liquid formulations compatible with drone and ground-based sensor systems.
Market Restraints
- Active ingredient cost volatility:Pyrethroid and organophosphate precursor supply concentrates in Chinese chemical manufacturing clusters, exposing formulators to input price swings and tariff exposure.
- Ecological buffer requirements:EPA-mandated setback distances from water bodies and pollinator habitat restrict application windows in the Mississippi River watershed, compressing effective demand per acre.
- Biological efficacy variability:Temperature-dependent performance of entomopathogenic fungi and nematodes limits reliable pest suppression in the northern Corn Belt compared to synthetic alternatives.
Strategic Opportunities
- Texas High Plains cotton systems:Bollworm resistance to Bt traits is expanding foliar insecticide demand in a geography previously dominated by seed-delivered protection.
- RNA interference platforms:Convergence of nucleic acid delivery systems with precision spray technology is opening species-specific pest suppression without off-target arthropod impacts.
- Professional channel consolidation:Structural pest management operators are consolidating purchasing power, creating direct manufacturer-to-applicator distribution bypassing traditional retail channels.
Industry Challenges
- Entomological expertise scarcity:University extension programs face declining enrollment in agricultural pest management specializations, constraining field-level resistance monitoring and stewardship implementation.
- Formulation facility capex:Biological production requires segregated fermentation and downstream processing infrastructure distinct from synthetic chemical manufacturing, demanding capital deployment without established depreciation schedules.
- Residue testing compliance:FDA tolerance enforcement for specialty crop exports requires third-party certified laboratory capacity that lags behind biological product adoption rates in organic production systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Insecticide Market |
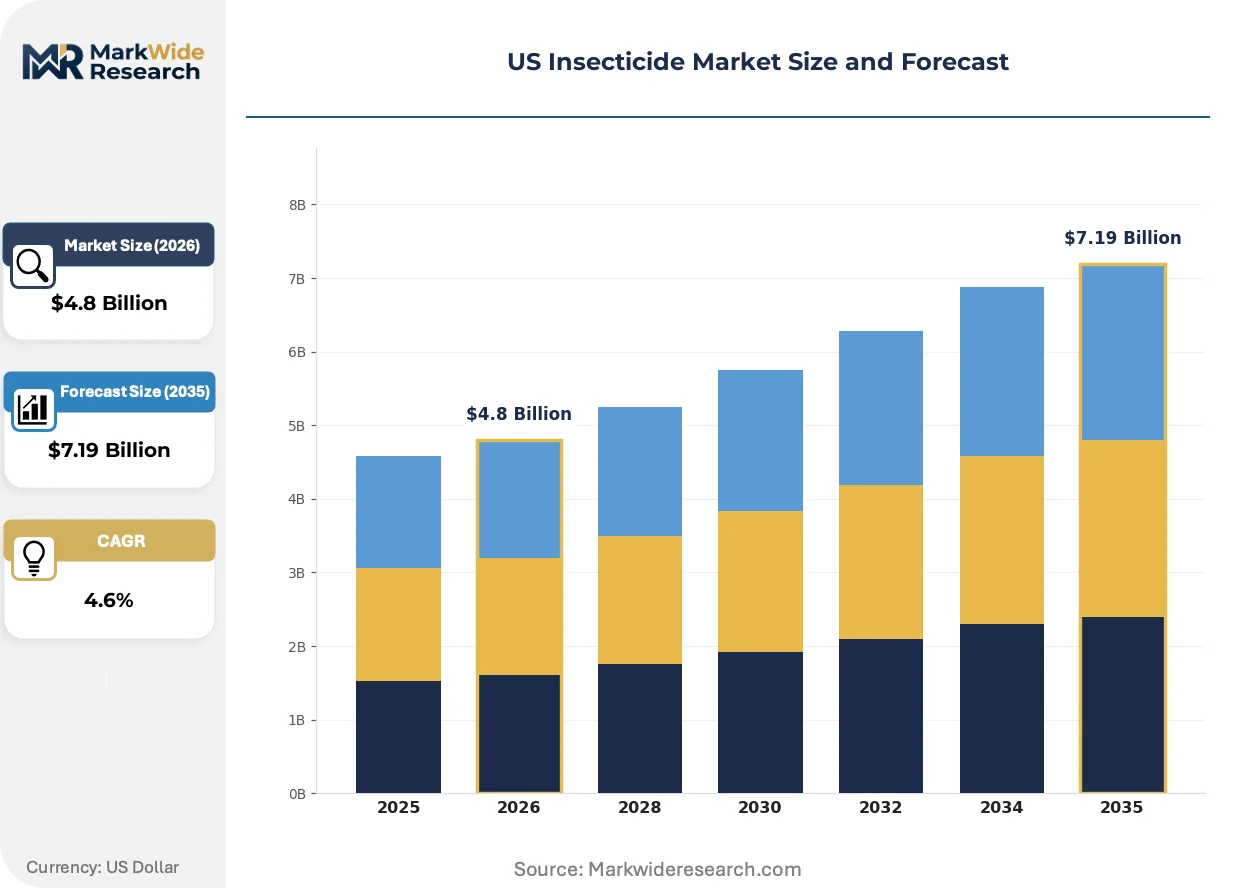
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application Type: Agricultural, Residential, Commercial, Industrial Product Form: Liquid, Granular, Aerosol, Bait Target Pest: Insects, Mites, Nematodes, Weeds Distribution Channel: Online, Retail, Wholesale, Direct Sales |
| Companies Covered | BASF SE, Bayer AG, Corteva Agriscience, FMC Corporation, Syngenta Group, Nufarm Ltd, UPL Limited, Sumitomo Chemical Co. Ltd, ADAMA Agricultural Solutions Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Insecticide Market Trends and Innovations
Digital farming platforms are restructuring how insecticide prescriptions are generated, delivered, and validated, compressing the traditional agronomist-retailer-applicator value chain into integrated decision systems.
Drone-mounted electrostatic sprayers are automating variable-rate application in California almond and grape vineyards. Large specialty crop operations in Fresno and Kern counties deploy fleets that adjust droplet size and release timing based on real-time pest density maps. This hardware convergence is automating the translation of satellite imagery into precise chemical deposition, reducing per-acre labor requirements while improving coverage uniformity in complex canopy architectures.
EPA's endangered species biological opinions for organophosphate and carbamate insecticides are forcing label amendments that restrict application timing and geography. The industrial consequence is a phased withdrawal of broad-spectrum chemistries from watersheds supporting salmon and steelhead populations. Pacific Northwest apple and potato growers are responding by accelerating adoption of mating disruption pheromones and selective lepidopteran-targeting materials that avoid aquatic toxicity triggers.
Prescription bundling through seed genetics platforms is displacing standalone insecticide procurement in row-crop systems. Corn and soybean growers in the I-states increasingly purchase trait packages with embedded insect protection, reducing separate chemical purchase decisions. This channel consolidation is most visible in Iowa and Illinois, where dealer agronomists now specify foliar rescue treatments only when trait failure thresholds are documented through scouting apps rather than calendar schedules.
US Insecticide Market Segmentation
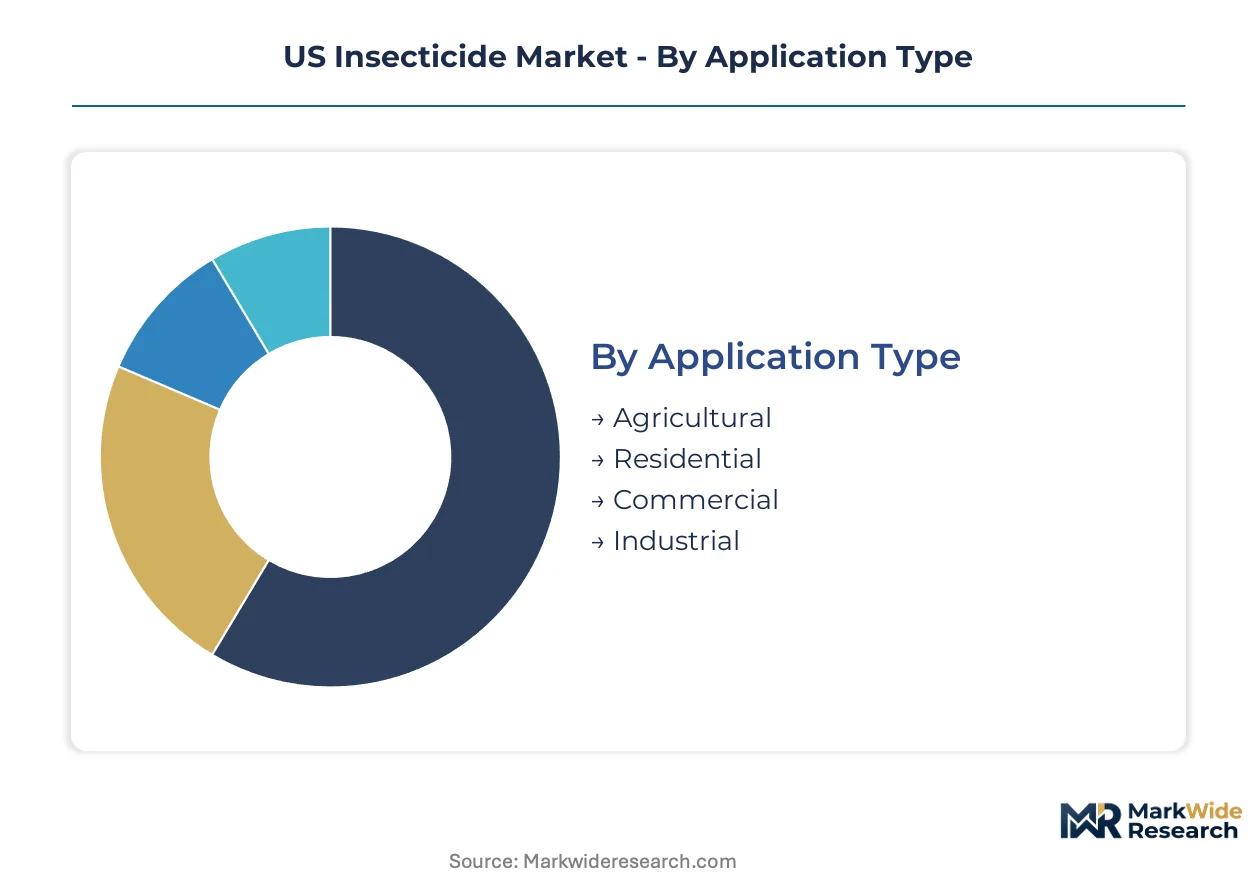
US insecticide demand fragments across application contexts, formulation technologies, and procurement channels that each impose distinct performance specifications and regulatory compliance burdens. Understanding these segment boundaries clarifies where margin pools concentrate versus where volume commoditization pressures dominate.
Application Type:
Upgrade cycles in agricultural equipment and residential application tools reshape replacement demand across each use context, with precision technology adoption accelerating obsolescence of legacy chemistries.
- Agricultural:Formulated products for row-crop and specialty production systems, applied via ground rigs, aerial equipment, or irrigation systems at rates calibrated to pest pressure thresholds. Demand concentrates in Iowa, Illinois, and Texas corn-soy-cotton rotations where resistance management protocols mandate chemistry rotation; EPA buffer zone restrictions compress effective application windows in watershed states.
- Residential:Ready-to-use formulations and perimeter defense systems targeting structural and ornamental pests in single-family and multi-unit housing. California and Florida metropolitan areas drive volume through year-round pest pressure; consumer preference shifts toward low-odor, pet-safe formulations favor biological and botanical actives over synthetic pyrethroids.
- Commercial:Professional-grade materials deployed by licensed applicators serving food service, hospitality, and healthcare facilities. Texas and Georgia commercial corridors sustain demand through mandatory integrated pest management contracts; third-party audit requirements for organic certification compatibility constrain product selection.
- Industrial:Heavy-duty formulations for manufacturing facilities, warehouses, and transportation infrastructure. Gulf Coast petrochemical complexes and Midwest distribution hubs anchor procurement volume; OSHA worker protection standards mandate restricted-entry intervals that favor residual chemistries with shorter re-entry periods.
Volume placements concentrate in Agricultural; the faster expansion belongs to Residential.
Product Form:
Cost tier differentiation separates premium precision-compatible formulations from economy bulk materials, with application infrastructure investments determining which form factors capture value.
- Liquid:Emulsifiable concentrates, suspension concentrates, and microencapsulated formulations compatible with variable-rate spray technology. Dominates California specialty crop systems where drone and ground-based sensor platforms require flowable, non-clogging chemistries; precision agriculture adoption sustains premium pricing over dry alternatives.
- Granular:Clay or corn-cob carrier matrices delivering soil-active chemistries for pre-plant or at-planting pest suppression. Corn Belt row-crop systems in Nebraska and Kansas favor broadcast application compatibility; equipment capital requirements for precision placement limit adoption in smaller operations.
- Aerosol:Pressurized formulations for crack-and-crevice, spot, and fogging applications in structural pest management. Professional channels in urban Florida and Arizona metropolitan areas sustain demand; propellant regulatory shifts under EPA SNAP program accelerate transition to lower-GWP alternatives.
- Bait:Palatable matrices containing slow-acting toxicants for social insect colony elimination. Subterranean termite pressure in Southeastern states and invasive ant species in Hawaii drive specialty demand; formulation stability requirements in tropical climates favor synthetic over biological actives.
Volume placements concentrate in Liquid; the steepest expansion trajectory belongs to Bait.
Target Pest:
Application specificity varies sharply across arthropod classes, with biological and behavioral differences dictating formulation chemistry and delivery mechanism requirements.
- Insects:Lepidopteran, coleopteran, hemipteran, and dipteran species across agricultural and structural contexts. Bollworm resistance to Bt traits in Texas High Plains cotton expands foliar insecticide demand; lepidopteran-targeting materials command premium positioning in high-value vegetable systems.
- Mites:Arachnid pests in specialty crops requiring specific miticidal modes of action distinct from general insecticides. California Central Valley almond and grape vineyards sustain demand for selective chemistry; resistance to abamectin and bifenazate drives rotation to novel chemical classes.
- Nematodes:Soil-dwelling roundworms suppressing crop roots and tubers. Southeastern potato and vegetable systems in Florida and Georgia anchor fumigant and non-fumigant demand; EPA buffer requirements for soil fumigants compress effective treated acreage.
- Weeds:Herbicide-resistant weed complexes requiring tank-mix partners or rotation sequences. Mississippi River watershed soybean systems drive demand for residual chemistry; dicamba and 2,4-D volatility concerns restrict application timing in sensitive crop geographies.
Volume placements concentrate in Insects; the fastest share gains belong to Nematodes.
Distribution Channel:
Customer type and procurement scale determine channel selection, with professional consolidation and direct manufacturer relationships reshaping traditional retail dominance.
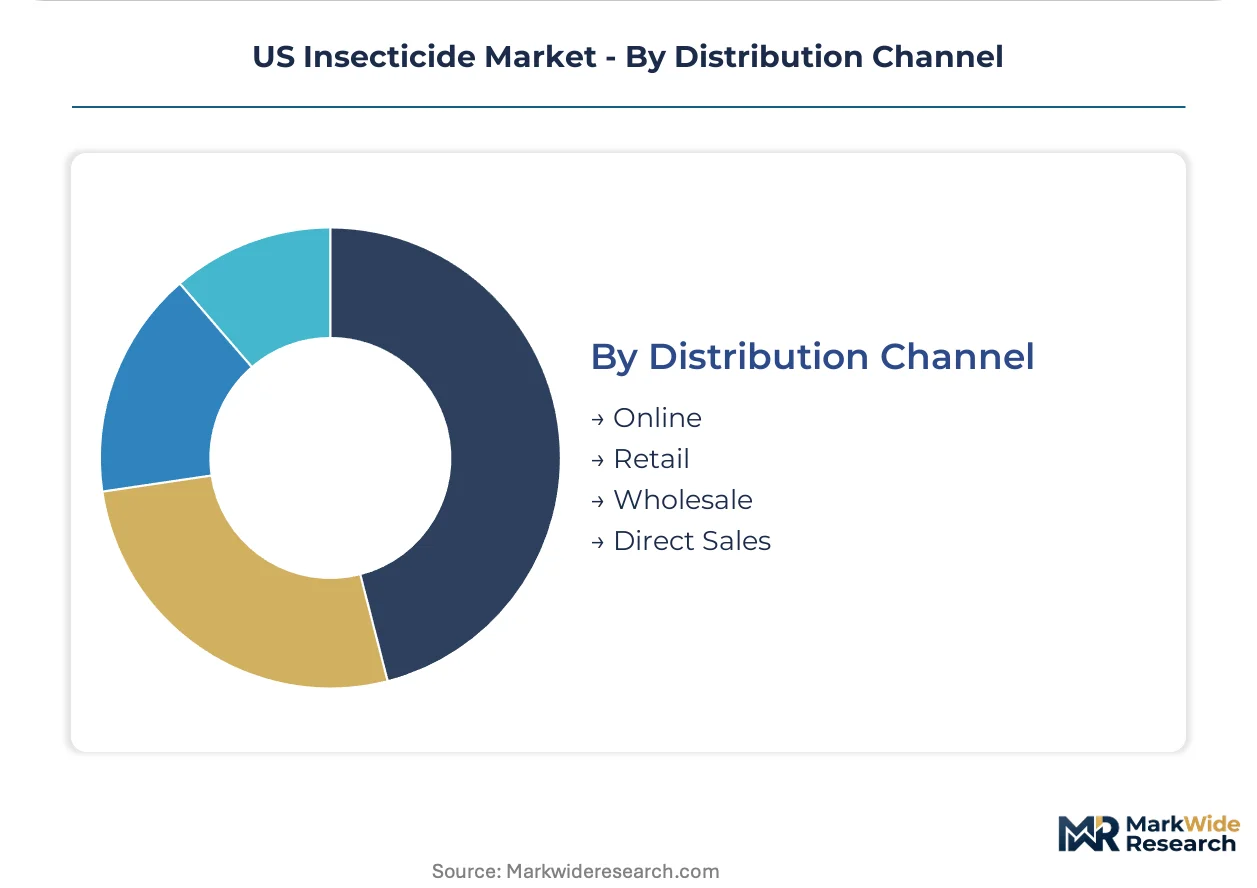
- Online:E-commerce platforms serving residential consumers and small commercial accounts. Amazon and specialty agricultural marketplaces capture share in remote geographies lacking physical distribution infrastructure; subscription models for seasonal perimeter defense sustain recurring revenue.
- Retail:Big-box home improvement and farm supply stores with seasonal merchandising programs. Midwest and Southern states with dense agricultural populations sustain co-op and farm store networks; private-label penetration pressures branded manufacturer margins.
- Wholesale:Distributor intermediaries serving professional pest management and agricultural retailer channels. Consolidation among national distributors concentrates purchasing leverage; inventory financing and technical support services differentiate surviving intermediaries.
- Direct Sales:Manufacturer-to-applicator relationships bypassing traditional distribution tiers. Large specialty crop operations in California and consolidated structural pest management chains negotiate volume contracts; prescription bundling with seed genetics platforms accelerates direct channel displacement of standalone chemical procurement.
Volume placements concentrate in Wholesale; the channel climbing fastest belongs to Direct Sales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Foreign Trade Zones in Texas and Louisiana concentrate import-dependent formulation facilities, drawing active ingredient throughput from Gulf Coast petrochemical corridors. These zones anchor regional supply chains while EPA regional offices in Dallas and Atlanta enforce divergent compliance calendars.
Texas High Plains
Bollworm resistance to Bt cotton traits has resurrected foliar insecticide demand across Lubbock, Plainview, and Amarillo growing districts. Texas Department of Agriculture applicator certification requirements now mandate resistance management documentation for pyrethroid applications. Multi-county cooperative extension networks coordinate regional pest monitoring that triggers coordinated spray windows across contiguous cotton acreage.
California Central Valley
Almond, grape, and vegetable systems in Fresno, Kern, and Tulare counties sustain premium pricing for selective lepidopteran materials and mating disruption pheromones. California Department of Pesticide Regulation's stricter neonicotinoid restrictions than federal baselines accelerate biological product registration. Drone application fleets operating from Visalia and Bakersfield service contracts now cover over 200,000 acres of specialty crop canopy.
Iowa-Illinois Corn Belt
Rootworm and corn borer pressure in Des Moines, Cedar Rapids, and Champaign-Urbana rotations sustains soil-applied and seed-treatment chemistries. Iowa State University and University of Illinois extension services enforce mode-of-action rotation protocols through certified crop adviser continuing education requirements. Dealer agronomists in the I-states now bundle trait packages with rescue treatment prescriptions rather than standalone chemical sales.
Pacific Northwest
Apple and potato growers in Yakima Valley and Columbia Basin confront EPA biological opinions restricting organophosphate use near salmon-bearing watersheds. Washington State Department of Ecology enforces buffer setbacks exceeding federal minimums for aquatic habitat protection. Mating disruption and selective materials now dominate tree fruit pest management from Wenatchee to Hood River.
Southeastern States
Subterranean termite pressure across Georgia, Florida, and Alabama sustains fumigant and bait demand in structural pest management channels. Florida Department of Agriculture's strict pyrethroid application windows for pollinator protection compress treatment seasons in citrus and ornamental systems. Professional pest management operators in Atlanta and Orlando metro areas consolidate purchasing through direct manufacturer contracts bypassing wholesale distribution.
US Insecticide Market Competitive Landscape
German producers anchor one tier; Japanese specialists hold differentiated positions in selective chemistry portfolios. The US insecticide market structures around three concentration layers: integrated agrichemical conglomerates with seed-genetics platforms, mid-scale formulation specialists serving regional crop systems, and biological technology developers racing EPA parallel registration pathways. Consolidation pressure intensifies as prescription bundling displaces standalone chemical procurement, while capacity expansion in biological fermentation facilities accelerates across the agricultural value chain.
Within the integrated conglomerate tier, BASF SE, Bayer AG, and FMC Corporation represent divergent strategic postures. BASF SE exemplifies Ludwigshafen-anchored R&D investment in novel mode-of-action discovery. Bayer AG occupies a position bundling digital farming platforms with seed-delivered protection. FMC Corporation sits within the selective chemistry specialist archetype targeting high-value vegetable systems. These three entities collectively illustrate how European-headquartered agrichemical operations navigate US regulatory complexity through regional formulation infrastructure and direct channel relationships with consolidated agricultural retailers.
| Leading Market Players |
|---|
| BASF SE |
| Bayer AG |
| Corteva Agriscience |
| FMC Corporation |
| Syngenta Group |
| Nufarm Ltd |
| UPL Limited |
| Sumitomo Chemical Co. Ltd |
| ADAMA Agricultural Solutions Ltd. |
| Others |
Pricing and Supply Chain Analysis
Certification-grade divergence between EPA-registered biological formulations and legacy synthetic chemistries manifests in both pricing premiums and segregated manufacturing infrastructure. Biological production facilities command facility-specific capital deployment without established depreciation schedules, while synthetic active ingredient pipelines face compressed margins from Chinese precursor cost volatility and tariff exposure.
Pricing Analysis
Expedited EPA registration timelines for microbial insecticides command premium positioning against spot-market synthetic pyrethroids facing inventory gluts. Three-tier pricing structure across precision-compatible liquids, standard emulsifiable concentrates, and economy granular carriers segments buyer archetypes. Cost compression in pyrethroid formulations is intensifying because Chinese manufacturing cluster concentration exposes formulators to input price swings. Professional pest management operators demonstrate lowest price sensitivity through direct manufacturer contracts, while residential consumers via big-box retail show highest elasticity to per-unit sticker prices.
Supply Chain Analysis
Reverse-logistics flows for pesticide container recycling and unused product returns are mandated by EPA container handling regulations, adding compliance cost layers to distributor operations. Active ingredient supply concentrates in China, India, and Germany, with pyrethroid and organophosphate precursors sourcing from Chinese chemical manufacturing clusters. Formulation depends on fermentation-derived biological actives from specialized facilities in California and North Carolina. Single-source vulnerability in Chinese precursor supply creates tariff exposure and logistics chokepoint risk. Distribution runs through consolidated national wholesalers serving professional applicator channels, with direct manufacturer-to-retailer bypass accelerating in row-crop seed genetics bundling.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Biological fermentation capacity scarcity props pricing premiums across the US insecticide market, constraining supply expansion despite accelerating EPA registration demand. This bottleneck sustains margin pools for incumbent operators with captive production infrastructure.
For Market Incumbents: Lock in exclusive supply agreements with California and North Carolina biological fermentation facilities before capacity expansion cycles complete. Secure backward integration into Bacillus thuringiensis strain development to defend against microbial startup entrants racing EPA parallel registration pathways. Prioritize channel control through direct contracts with consolidating structural pest management operators in Atlanta and Orlando metro corridors. For New Entrants and Emerging Players: The mid-tier price-point gap between premium California specialty crop biologicals and economy Corn Belt synthetics offers white-space targeting. Focus initial penetration on Texas High Plains cotton systems where bollworm resistance to Bt traits has resurrected foliar insecticide demand previously served by seed-delivered protection. Pursue go-to-market partnerships with drone application fleet operators in Fresno and Kern counties to bypass established wholesale distribution. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by integrated agrichemical conglomerates seeking biological technology capabilities. Long-term viability in the US insecticide market hinges on navigating EPA FIFRA re-registration complexity and securing fermentation capacity access. Target acquisition archetypes include mid-scale formulation specialists with established California Department of Pesticide Regulation compliance track records. Monitor EPA endangered species biological opinion enforcement intensity as early signal for accelerated synthetic chemistry withdrawal timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Biological Fermentation Capacity Expansion | Segregated infrastructure investment captures EPA registration queue advantages before competitor facility commissioning. |
| Direct Channel Bypass of Wholesale Tiers | Manufacturer-to-applicator contracts with consolidated pest management operators displace traditional retail margin extraction. |
| RNA Interference Platform Development | Species-specific nucleic acid delivery converges with precision spray technology to open premium positioning without off-target liability. |
| Resistance Management Stewardship Integration | Mode-of-action rotation protocols embedded in digital farming platforms lock in recurring prescription bundling revenue. |
| Endangered Species Compliance Pre-Positioning | Early withdrawal from salmon-bearing watersheds ahead of EPA biological opinions preserves market access in Pacific Northwest specialty crops. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with EPA registration specialists, agricultural extension entomologists, formulation plant managers, and professional pest management operators. Secondary validation drew from USDA resistance monitoring network reports, EPA FIFRA registration databases, state department of agriculture applicator certification records, and FDA residue tolerance enforcement disclosures. Bottom-up acreage and application rate modeling triangulated against top-down manufacturer revenue segmentation.
Granularity-level modeling operated at state-crop-pest complex intersections across the projection horizon, with specific attention to Iowa-Illinois corn-soy rotations, California Central Valley specialty crops, and Texas High Plains cotton systems. Segmentation dimensions included application type, formulation technology, target pest class, and procurement channel structure. CAGRs were derived from regression analysis of historical acreage trends and resistance-driven chemistry rotation patterns, incorporating EPA regulatory timeline assumptions and biological product adoption curve inputs.
Inputs from EPA registration databases and USDA extension networks were available through the study window; gaps in proprietary manufacturer pricing data introduce uncertainty bands around tier-level margin estimates. Forecasts reflect documented assumptions regarding FIFRA re-registration timelines and biological efficacy standard development trajectories. Practitioners should monitor EPA endangered species biological opinion rollout schedules and Chinese precursor export permit volatility for early signals of supply constraint or regulatory acceleration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Crop Protection
United States Nematicides Market
Crop Protection
Thailand Crop Protection Chemicals Market
Crop Protection
Grain Fumigants Market
Crop Protection
Grain Protectant Market
Crop Protection
Argentina Crop Protection Chemicals Market
Crop Protection
Indonesia Insecticide Market
Crop Protection
Low-Odor, Enclosed-Greenhouse Foliar Protection Market
Crop Protection
Europe Herbicide Market
Crop Protection
Miticides Market
Crop Protection
Vietnam Herbicide Market
Crop Protection
North America Acaricides Market
Crop Protection
Vietnam Insecticide Market
Crop Protection
Dicamba Market
Crop Protection
Japan Crop Protection Chemicals Market
Crop Protection
Global Insecticide Seed Treatment Market
Crop Protection
Pre-Emergent Herbicide Market