
 Asia Pacific Insecticide Market | 2026-2036
Asia Pacific Insecticide Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Insecticide Market Insights
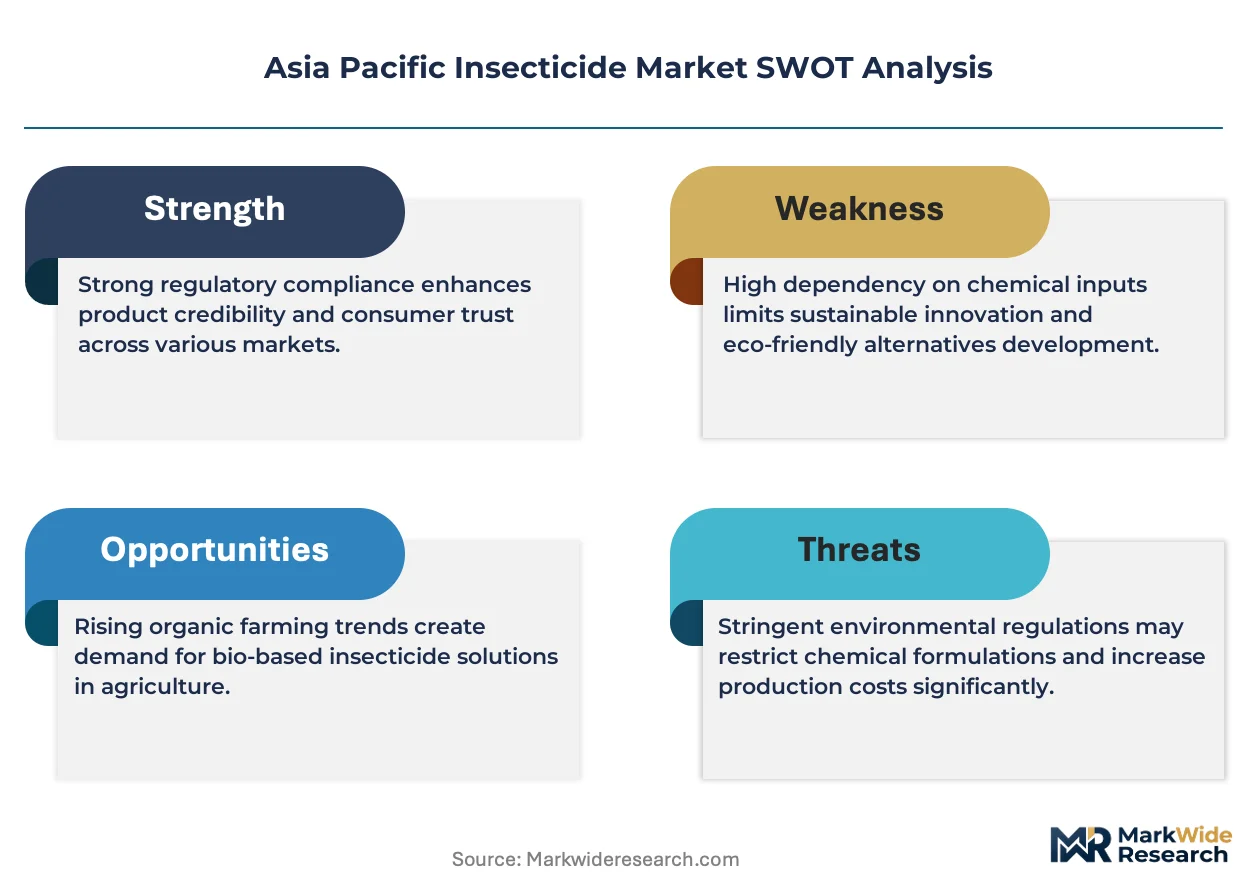
Agronomic extension officer availability is collapsing across Indonesia and Vietnam, forcing growers toward simplified, broad-spectrum chemical solutions. Syngenta Group leverages its granular distribution network to sustain channel dominance in tier-three Chinese counties. UPL Limited anchors its position through backward integration into active ingredient synthesis in India. BASF SE differentiates via biological insecticide co-development with regional research institutes.
Asia Pacific insecticides comprise synthetic and naturally derived compounds formulated to disrupt arthropod nervous systems, growth cycles, or feeding behaviors, with active ingredients typically concentrated between 10-50% for agricultural emulsifiable concentrates. These agents protect cereal, oilseed, and horticultural crops from yield-limiting pest pressure across tropical and subtropical growing conditions. Chemical insecticides retain the largest revenue pool, though biological insecticides are expanding fastest as residue thresholds tighten in Japanese and South Korean export-oriented agriculture. Emulsifiable concentrates dominate formulation demand in large-scale mechanized farming, while granules sustain penetration in flooded rice systems across Thailand and Myanmar.
China's MEE enforces wastewater discharge limits on organophosphate manufacturers, raising compliance costs for domestic producers. India's CEA and CDSCO jointly regulate insecticide registration and residue limits, with the PLI scheme incentivizing local technical-grade production. Japan's PMDA and Food Sanitation Act impose strict maximum residue limits on imported produce, redirecting exporter formulation choices. Stakeholders must monitor how ASEAN harmonization of MRL standards reshapes product registration priorities and manufacturing location decisions.
Market Dynamics
China's MEE wastewater discharge mandates on organophosphate manufacturers are compressing domestic technical-grade capacity, forcing formulators to relocate synthesis operations or absorb compliance premiums that reshape regional supply economics.
Growth Catalysts
- India's PLI scheme:The production-linked incentive program for agrochemical manufacturing draws technical-grade synthesis investment into Gujarat and Maharashtra industrial corridors.
- Rice pest pressure:Brown planthopper and stem borer infestations across Southeast Asian deltas sustain insecticide demand among smallholder farming collectives.
- Japan's residue thresholds:Maximum residue limits under the Food Sanitation Act redirect exporter formulation strategies toward lower-toxicity chemistries.
Market Restraints
- Active ingredient concentration:China's environmental compliance costs for organophosphate technical-grade production have risen substantially under MEE discharge limits.
- Extension officer collapse:Agronomic advisory capacity in Indonesia and Vietnam has contracted, limiting grower access to integrated pest management guidance.
- Biological substitution:Bacillus thuringiensis and entomopathogenic nematodes gain traction in Japanese protected cultivation as residue-compliant alternatives.
Strategic Opportunities
- Myanmar's delta expansion:Flooded rice systems in Ayeyarwady and Bago regions remain underserved by granular formulation distribution networks.
- Drone application convergence:Unmanned aerial vehicle spraying platforms merge with micro-encapsulated chemistries to penetrate terrain-inaccessible holdings.
- ASEAN MRL harmonization:Coordinated maximum residue limit standards under negotiation create pathway for single-registration multi-market access.
Industry Challenges
- Formulation chemist scarcity:Technical expertise for emulsifiable concentrate and suspension concentrate development concentrates in legacy manufacturing clusters.
- CDSCO registration timelines:India's insecticide approval process extends commercialization cycles for novel active ingredients.
- Channel inventory fragmentation:Tier-three county distributors in China maintain opaque stock positions that distort demand signaling to manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Insecticide Market |
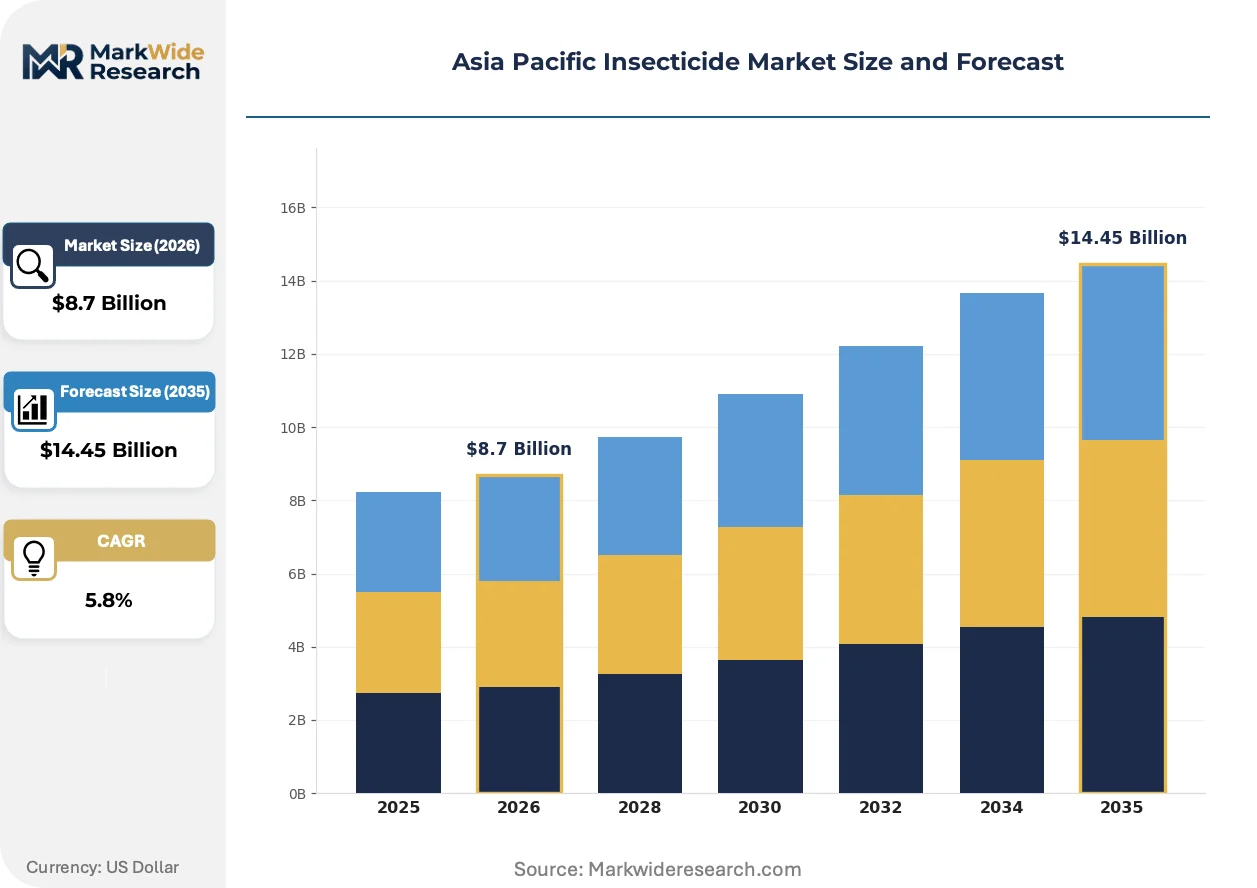
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chemical Insecticides, Biological Insecticides, Insect Growth Regulators, Neem-Based Insecticides Application: Agriculture, Public Health, Residential, Commercial Formulation: Granules, Emulsifiable Concentrates, Liquid, Aerosols Sales Channel: Online, Distributors, Retail, Direct Sales |
| Companies Covered | Syngenta Group, Corteva Agriscience, FMC Corporation, UPL Limited, ADAMA Agricultural Solutions Ltd, BASF SE, Bayer AG, Nufarm Ltd, Sumitomo Chemical Co., Ltd., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Insecticide Market Trends and Innovations
Formulation chemistry and application methodology are diverging sharply between export-oriented horticulture and domestic staple crop systems across the region.
Micro-encapsulated delivery systems are bifurcating the application equipment market. Japanese greenhouse operators and Vietnamese dragonfruit exporters adopt precision drone-mounted spraying platforms that demand compatible chemistries. This technology is bifurcating equipment procurement patterns between large-scale mechanized holdings and manual backpack sprayer dependence among smallholders.
China's MEE dual carbon goals enforce energy intensity caps on technical-grade synthesis facilities. Domestic producers face capacity rationing or carbon credit purchase obligations. Jiangsu and Shandong province formulators respond by relocating active ingredient production to western industrial zones with lower grid carbon intensity.
Cooperative procurement collectives are consolidating input purchasing across Indian cotton-belt states. Maharashtra and Gujarat grower groups negotiate volume-based pricing directly with technical-grade suppliers, compressing traditional distributor margins. This consolidation is most visible in Telangana's chili and cotton districts where farmer producer organizations now aggregate insecticide demand for 40,000-plus hectare blocks.
Asia Pacific Insecticide Market Segmentation
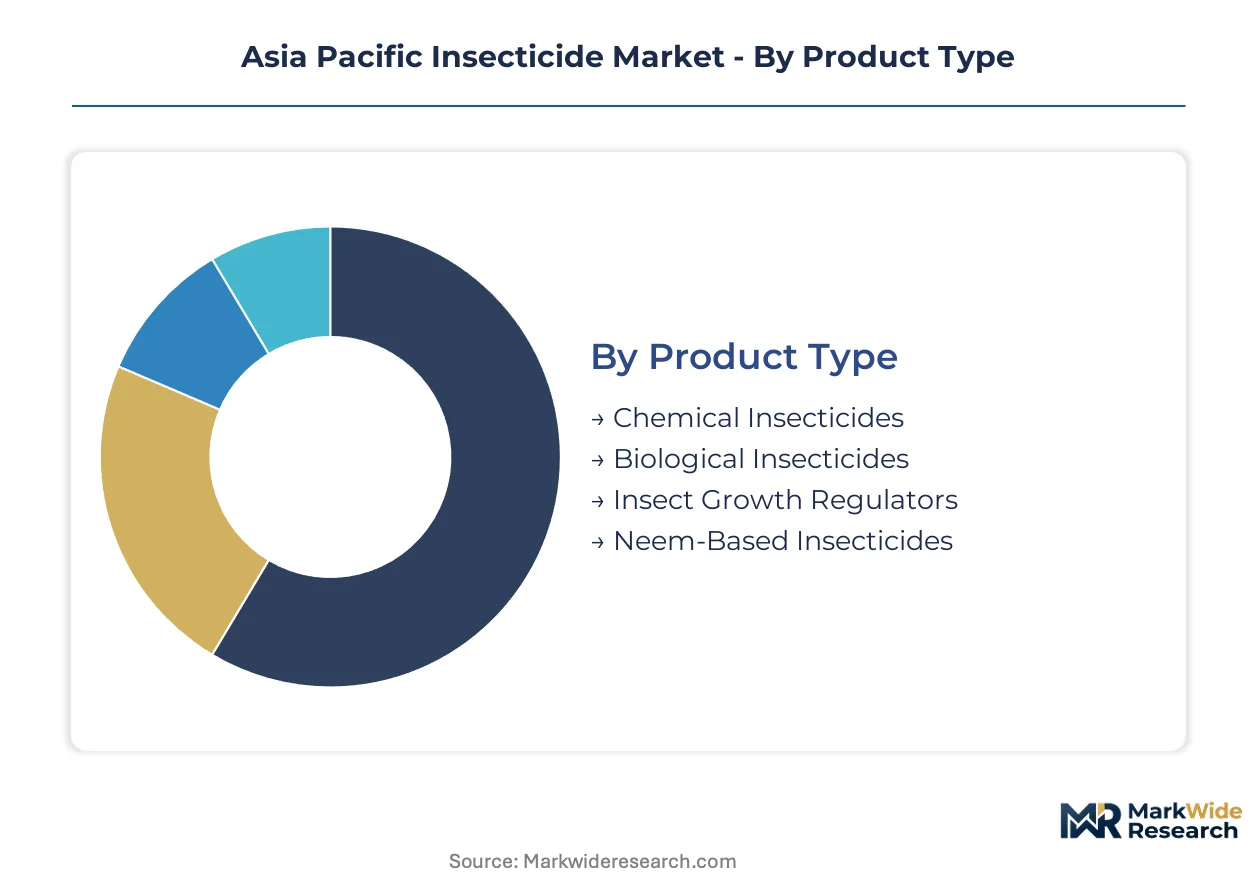
Segmentation reveals divergent growth trajectories between domestic staple crop protection and export-oriented horticulture systems across the Asia Pacific region. Product type and formulation choices bifurcate sharply based on residue compliance requirements and mechanization levels.
Product Type:
Domestic consumption concentrates in broad-spectrum chemistries for rice and cotton belts, while export agriculture drives biological adoption under Japanese and South Korean residue thresholds.
- Chemical Insecticides:Synthetic compounds disrupting arthropod nervous systems dominate volume across Indian cotton-belt states and Chinese central grain provinces. Organophosphate and pyrethroid formulations sustain penetration where extension officer collapse pushes growers toward simplified solutions.
- Biological Insecticides:Bacillus thuringiensis and entomopathogenic nematodes gain share fastest in Japanese protected cultivation and Vietnamese dragonfruit export zones. PMDA residue limits under the Food Sanitation Act redirect formulation strategies toward microbial and botanical alternatives.
- Insect Growth Regulators:Juvenile hormone mimics and chitin synthesis inhibitors target specific life stages in integrated pest management programs.
- Neem-Based Insecticides:Azadirachtin formulations serve organic certification requirements across Kerala and Karnataka spice-growing districts.
Chemical insecticides command the established base. The steepest expansion runs through biological insecticides.
Application:
Cost-tier differentiation separates high-input commercial operations from subsistence smallholder systems with limited mechanization access.
- Agriculture:Rice pest pressure from brown planthopper and stem borer infestations sustains demand across Southeast Asian deltas. India's PLI scheme draws technical-grade synthesis investment into Gujarat and Maharashtra corridors serving cotton, chili, and oilseed protection.
- Public Health:Malaria and dengue vector control programs in Myanmar and Cambodia deploy indoor residual spraying and larvicidal applications.
- Residential:Urban household demand concentrates in aerosol and coil formats across tier-one Chinese cities and Indian metros.
- Commercial:Food processing facilities and warehousing operations in Thailand and Vietnam adopt fumigation and surface treatment protocols.
Agriculture commands the established base. The steepest expansion runs through public health vector control programs.
Formulation:
Application methodology diverges between flooded rice systems requiring granular delivery and mechanized farming adopting emulsifiable concentrates.
- Granules:Slow-release formulations penetrate flooded rice systems across Thailand's Central Plains and Myanmar's Ayeyarwady delta. Water-compatible delivery avoids drift losses in paddy cultivation.
- Emulsifiable Concentrates:Oil-in-water formulations dominate large-scale mechanized farming in Punjab and Haryana wheat-rice rotations. Concentrated active ingredients between 10-50% suit tractor-mounted boom sprayers.
- Liquid:Ready-to-use solutions serve smallholder backpack sprayer operations with limited mixing infrastructure.
- Aerosols:Pressurized delivery systems target household and commercial indoor applications across urban Southeast Asia.
Emulsifiable concentrates command the established base. The steepest expansion runs through granules in underserved delta regions.
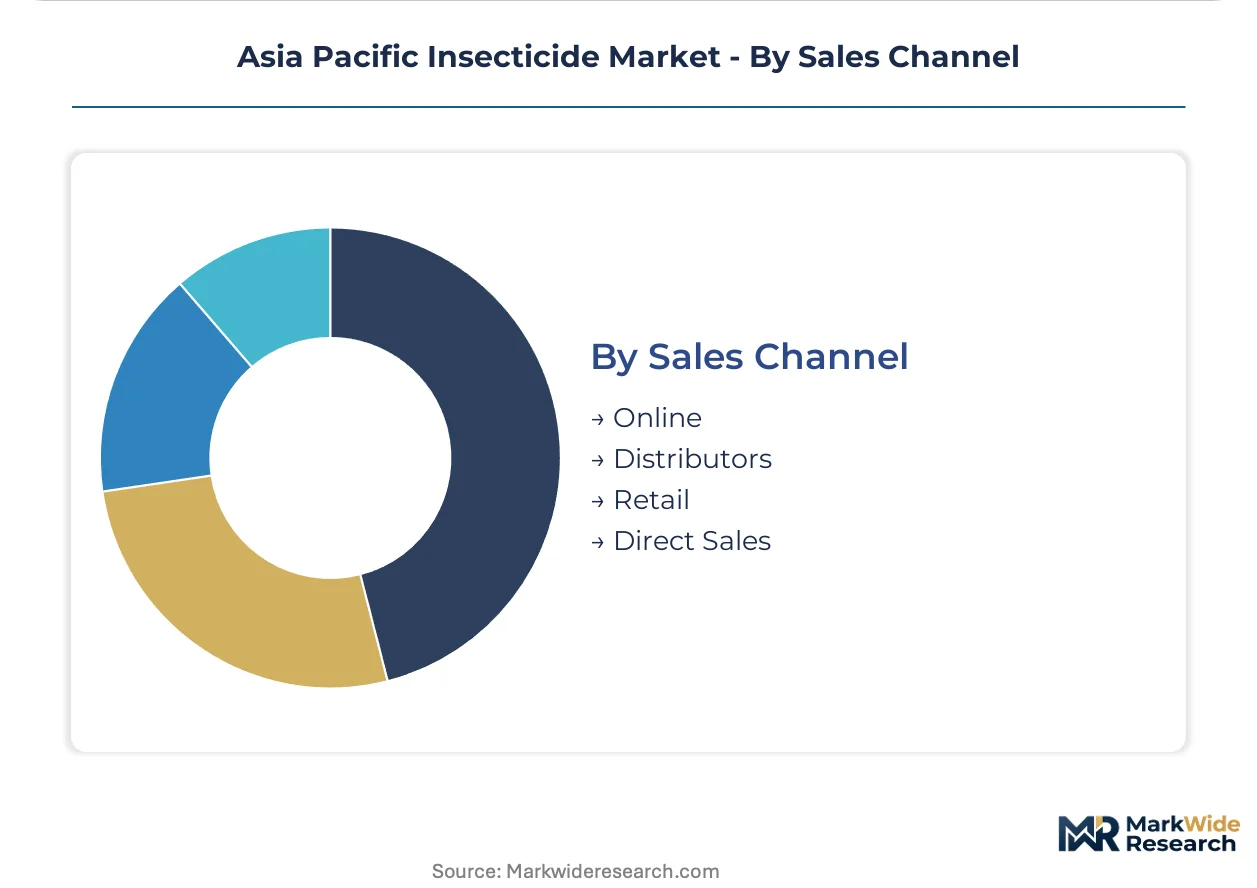
Sales Channel:
Customer-type fragmentation separates organized procurement collectives from traditional distributor-dependent smallholders.
- Distributors:Granular distribution networks sustain channel dominance in tier-three Chinese counties and Indonesian regencies. Opaque inventory positions distort demand signaling to manufacturers.
- Retail:Mom-and-pop agro-dealer networks serve fragmented smallholder bases across Vietnam's Mekong Delta and Philippines rice terraces.
- Direct Sales:Cooperative procurement collectives in Maharashtra and Gujarat negotiate volume-based pricing directly with technical-grade suppliers, compressing traditional margins.
- Online:E-commerce platforms aggregate input purchasing for farmer producer organizations covering 40,000-plus hectare blocks in Telangana.
Distributors command the established base. The steepest expansion runs through direct sales via cooperative consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China and India consume insecticides at radically different intensity profiles—China for mechanized grain protection, India for labor-intensive cotton and chili cultivation—while Southeast Asian deltas prioritize water-compatible granular formulations for flooded rice systems.
China
Central grain provinces in Henan and Shandong deploy emulsifiable concentrates for wheat and corn protection at scale. MEE wastewater discharge mandates on organophosphate manufacturers have compressed technical-grade capacity in Jiangsu, forcing formulators to relocate synthesis to western zones with lower grid carbon intensity. Yangtze River Delta formulators now ration active ingredient production under dual carbon goals.
India
Maharashtra and Gujarat cotton-belt states drive pyrethroid and neonicotinoid consumption among smallholder collectives. CDSCO registration timelines extend commercialization cycles, while the PLI scheme draws technical-grade synthesis investment into industrial corridors near Mumbai and Ahmedabad. Telangana farmer producer organizations now aggregate insecticide demand for 40,000-plus hectare blocks through cooperative procurement.
Japan
Protected cultivation in Chubu and Kyushu regions favors biological insecticides under PMDA residue limits. The Food Sanitation Act imposes strict maximum residue limits on domestic and imported produce, redirecting formulation strategies toward Bacillus thuringiensis and entomopathogenic nematodes. Kanto greenhouse operators lead drone-mounted precision spraying adoption.
Vietnam
Mekong Delta rice systems sustain granular demand for brown planthopper and stem borer control. Agronomic extension officer collapse has contracted integrated pest management guidance, pushing growers toward simplified broad-spectrum solutions. Dragonfruit export zones in Lam Dong province adopt lower-toxicity chemistries to meet Japanese residue thresholds.
Thailand
Central Plains flooded rice cultivation maintains penetration for slow-release granular formulations. Water-compatible delivery avoids drift losses in paddy systems where mechanized boom spraying is impractical. Ayutthaya and Suphan Buri provinces concentrate distribution network development for smallholder access.
Asia Pacific Insecticide Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with multinational agrochemical conglomerates controlling technical-grade synthesis and formulation chemistry while regional distributors retain last-mile penetration in fragmented smallholder markets. The competitive terrain splits between backward-integrated technical producers and formulation-focused service providers. Three archetypes dominate: synthesis-integrated multinationals with captive active ingredient supply, distribution-heavy regional platforms with granular network density, and biological specialists co-developing microbial alternatives with research institutes. Capacity relocation and channel consolidation represent the dominant competitive moves as environmental compliance reshapes manufacturing geography.
Among synthesis-integrated multinationals, Syngenta Group exemplifies the archetype through its granular distribution network density in tier-three Chinese counties, while UPL Limited anchors the backward-integrated position through technical-grade production in India. BASF SE occupies the biological innovation tier via co-development partnerships with regional research institutes. These three entities represent the strategic poles—distribution control, upstream integration, and biological differentiation—around which competitive positioning organizes in this market.
| Leading Market Players |
|---|
| Syngenta Group |
| Corteva Agriscience |
| FMC Corporation |
| UPL Limited |
| ADAMA Agricultural Solutions Ltd |
| BASF SE |
| Bayer AG |
| Nufarm Ltd |
| Sumitomo Chemical Co., Ltd. |
| Others |
Pricing and Supply Chain Analysis
Technical-grade synthesis scale economies in China's Jiangsu and Shandong provinces concentrate active ingredient production among integrated formulators, compressing unit costs for organophosphate and pyrethroid chemistries while elevating price floors for smaller players absorbing MEE compliance premiums.
Pricing Analysis
Contract-based long-term offtake agreements dominate procurement between Indian cotton-belt cooperatives and technical-grade suppliers, though spot purchases persist for seasonal pest pressure spikes. Price differentiation stems from volume scale and CDSCO registration tier, with fully-registered chemistries commanding premiums over provisional approvals. Pricing pressure stems from cooperative consolidation in Maharashtra and Gujarat, where farmer producer organizations bypass traditional distributor markups. Smallholder collectives exhibit highest price sensitivity, while Japanese greenhouse operators prioritize residue compliance over cost.
Supply Chain Analysis
China and India anchor technical-grade synthesis capacity, with Jiangsu province formulators rationing output under MEE dual carbon goals while Gujarat industrial corridors expand pyrethroid production under PLI incentives. Active ingredient production draws from organophosphate intermediates, neonicotinoid precursors, and microbial fermentation feedstocks. Single-source vulnerability concentrates in Jiangsu's organophosphate technical-grade base, where wastewater discharge mandates threaten supply continuity. Distribution runs through granular networks in tier-three Chinese counties and cooperative procurement platforms in Indian cotton belts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward cooperative procurement collectives across Indian cotton-belt states, fragmenting traditional distributor control as Maharashtra and Gujarat farmer producer organizations aggregate demand across 40,000-plus hectare blocks.
For Market Incumbents: Fortify backward integration into active ingredient synthesis to offset MEE compliance cost inflation in Chinese technical-grade production. Prioritize CDSCO registration pipeline acceleration to defend market access against PLI-scheme entrants capturing local synthesis incentives. Channel control in tier-three Chinese counties remains defensible through granular distribution density, though cooperative bypass in India threatens margin capture. For New Entrants and Emerging Players: Drone-compatible micro-encapsulated formulation gaps in Vietnamese dragonfruit export zones and Myanmar's underserved Ayeyarwady delta present white-space entry points. Target granular distribution networks in flooded rice systems where mechanized spraying is impractical. Go-to-market leverage rests on co-development partnerships with regional research institutes for biological insecticide registration under Japanese PMDA residue limits. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors biological formulation specialists with PMDA-compliant pipelines over legacy organophosphate manufacturers facing MEE capacity rationing. Long-term viability hinges on residue threshold trajectory in Japanese and South Korean import markets. Watch ASEAN MRL harmonization negotiations as inflection signal for single-registration multi-market access economics.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Technical-Grade Synthesis | Captures PLI scheme incentives in Gujarat and Maharashtra industrial corridors. |
| Biological Insecticide Co-Development Partnership | Accelerates PMDA registration pathways for Japanese greenhouse residue compliance. |
| Granular Distribution Network Expansion | Penetrates tier-three Chinese counties and Myanmar's underserved delta regions. |
| Drone-Compatible Micro-Encapsulation R&D | Aligns formulation chemistry with Vietnamese and Japanese precision spraying adoption. |
| Cooperative Procurement Platform Integration | Bypasses traditional distributor margins in Telangana and Maharashtra cotton belts. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of CDSCO registration databases, MEE discharge compliance filings, and ASEAN trade flow records through structured interviews with agrochemical plant managers, agronomic extension officers, cooperative procurement leads, and distribution channel partners across India, China, and Vietnam. Bottom-up demand modeling triangulates against top-down technical-grade production capacity assessments.
Segmentation dimensions modeled span chemical versus biological product type, emulsifiable concentrate versus granular versus liquid formulation, agriculture versus public health application, and distributor versus direct sales channel across the projection horizon. CAGRs derive from regression analysis of historical pest pressure indices, PLI scheme incentive uptake trajectories, and residue limit tightening schedules. Industry-specific inputs include brown planthopper infestation cycle data and MEE carbon intensity cap implementation timelines.
Underlying assumptions cover sustained rice pest pressure across Southeast Asian deltas, PLI scheme continuity for Indian technical-grade investment, and ASEAN MRL harmonization progression, with deviation risk concentrated in MEE enforcement intensity and CDSCO registration timeline variability. Recalibration cycles align with material shifts in residue limit negotiations, environmental compliance mandate revisions, and cooperative procurement platform consolidation milestones.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Crop Protection
Global Crop Growth Regulators Market
Crop Protection
Europe Agricultural Pheromones Market
Crop Protection
Global Aquatic Herbicides Market
Crop Protection
US Herbicide Market
Crop Protection
Crop Bactericides Market
Crop Protection
Soybean Fungicide Seed Treatment Market
Crop Protection
Tebuconazole Market
Crop Protection
Seed Treatment Materials Market
Crop Protection
United Kingdom Crop Protection Chemicals Market
Crop Protection
Metamifop Market
Crop Protection
Glufosinate Ammonium Market
Crop Protection
Vietnam Crop Protection Chemicals Market
Crop Protection
Tebufenozide Market
Crop Protection
Europe Herbicide Market
Crop Protection
Grain Protectant Market
Crop Protection
Spain Crop Protection Chemicals Market